
 Spirodiclofen Market | 2026-2036
Spirodiclofen Market Size, Share, and Industry Trends Forecast 2026-2036
Spirodiclofen Market Analytics
High-purity suspension concentrate grades are rotating toward center stage as growers prioritize tank-mix compatibility and reduced phytotoxicity risk in integrated programs. Bayer CropScience leverages its established acaricide portfolio to sustain channel presence across European pome fruit regions. Syngenta Crop Protection anchors its position through proprietary formulation science that extends residual control in hot-climate citrus operations. ADAMA competes on cost-optimized emulsifiable concentrate supply to Southeast Asian vegetable cooperatives.
Spirodiclofen functions as a tetronic acid derivative acaricide and insecticide that inhibits lipid biosynthesis in mites and whiteflies, with a molecular structure conferring translaminar movement and ovicidal properties against spider mite eggs. Suspension concentrate formulations occupy the dominant volume position due to superior user safety profiles and ease of handling in mechanized spray systems, while wettable powder demand contracts in regulated markets where dust exposure faces occupational health scrutiny. The pest type dimension reveals spider mite applications generating the deepest margin pools, particularly in greenhouse tomato and ornamental rose production where resistance management protocols mandate rotation partners.
EPA residue tolerance schedules and EU MRL harmonization under EFSA oversight shape product registration timelines and export-access viability for treated commodities. China's NMPA and Ministry of Agriculture impose domestic manufacturing license requirements that filter market entry for imported technical-grade material. Brazil's ANVISA re-evaluation framework for existing acaricides introduces uncertainty windows that stakeholders must monitor for label restriction risks.
Market Dynamics
EU MRL harmonization under EFSA oversight is compressing formulation innovation cycles and forcing manufacturers to accelerate residue mitigation chemistry ahead of re-registration deadlines.
Growth Catalysts
- Specialty crop protection programs:California's Central Valley drives adoption momentum through integrated pest management mandates that prioritize acaricides with favorable resistance profiles.
- REACH compliance frameworks:European formulators invest in suspension concentrate upgrades to meet occupational exposure limits and secure export-access viability for treated pome fruit.
- Asian citrus psyllid pressure:Brazil's citrus belt sustains procurement volumes as growers rotate away from organophosphates toward lipid biosynthesis inhibitors.
Market Restraints
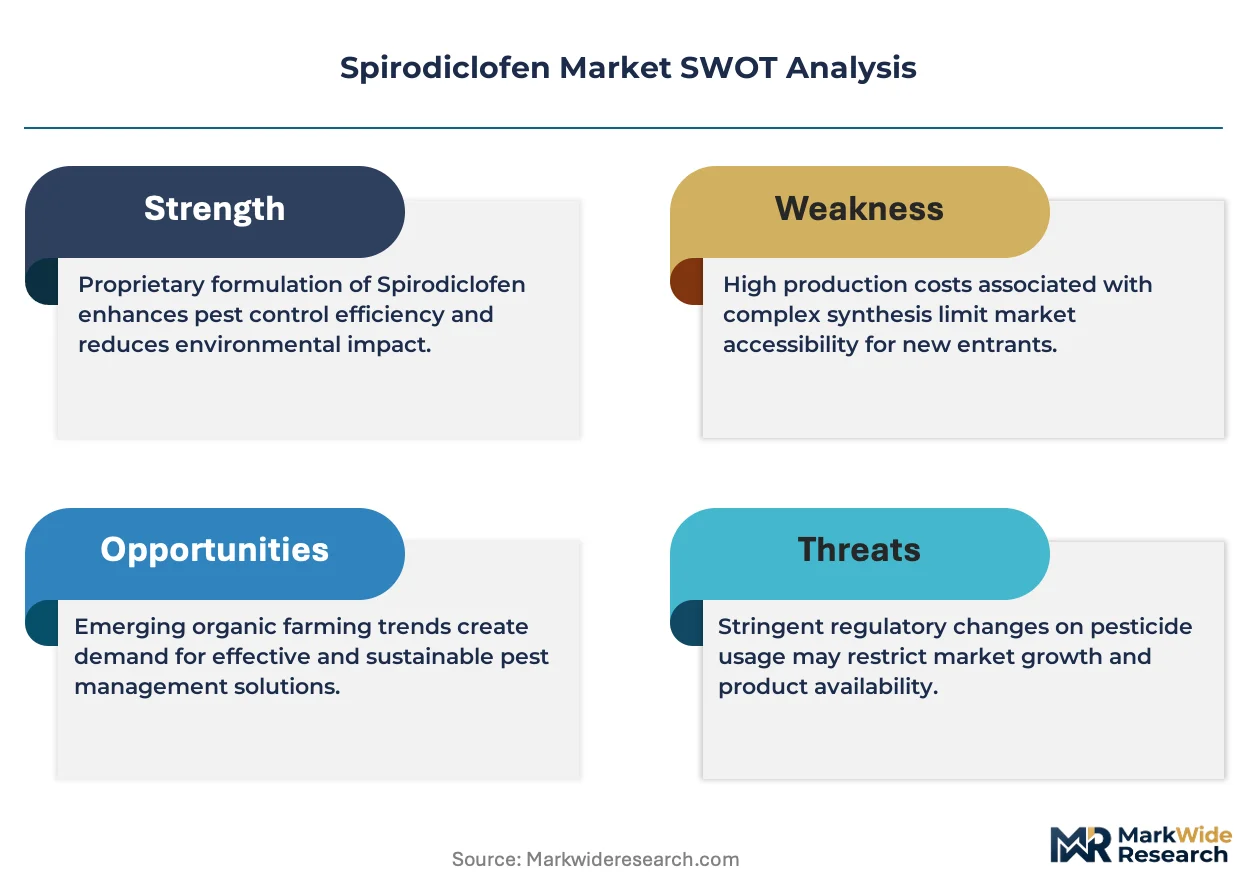
- Active ingredient cost volatility:Tetronic acid derivative synthesis depends on petrochemical feedstocks vulnerable to energy price swings.
- Supply concentration risk:Technical-grade material production clusters in China's Jiangsu and Shandong provinces, exposing buyers to domestic manufacturing license delays.
- Substitution threat from predatory mites:Biological control programs in Dutch greenhouse tomato operations displace chemical acaricides in high-value segments.
Strategic Opportunities
- Underpenetrated Southeast Asian vegetable cooperatives:Cost-optimized emulsifiable concentrate formats address price-sensitive chili and tomato growers in Vietnam and Thailand.
- Regulatory tailwind from EU Green Deal:Farm-to-Fork pesticide reduction targets accelerate demand for precision application technologies that extend residual control per unit applied.
- Drone spray system convergence:Low-volume aerial application platforms integrate with suspension concentrate rheology to penetrate dense citrus canopies.
Industry Challenges
- Formulation chemist talent scarcity:Expertise in translaminar delivery systems and ovicidal stability concentrates among a shrinking pool of crop protection specialists.
- Re-registration dossier complexity:Brazil's ANVISA re-evaluation framework demands multi-year toxicology studies that strain R&D timelines and working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spirodiclofen Market |
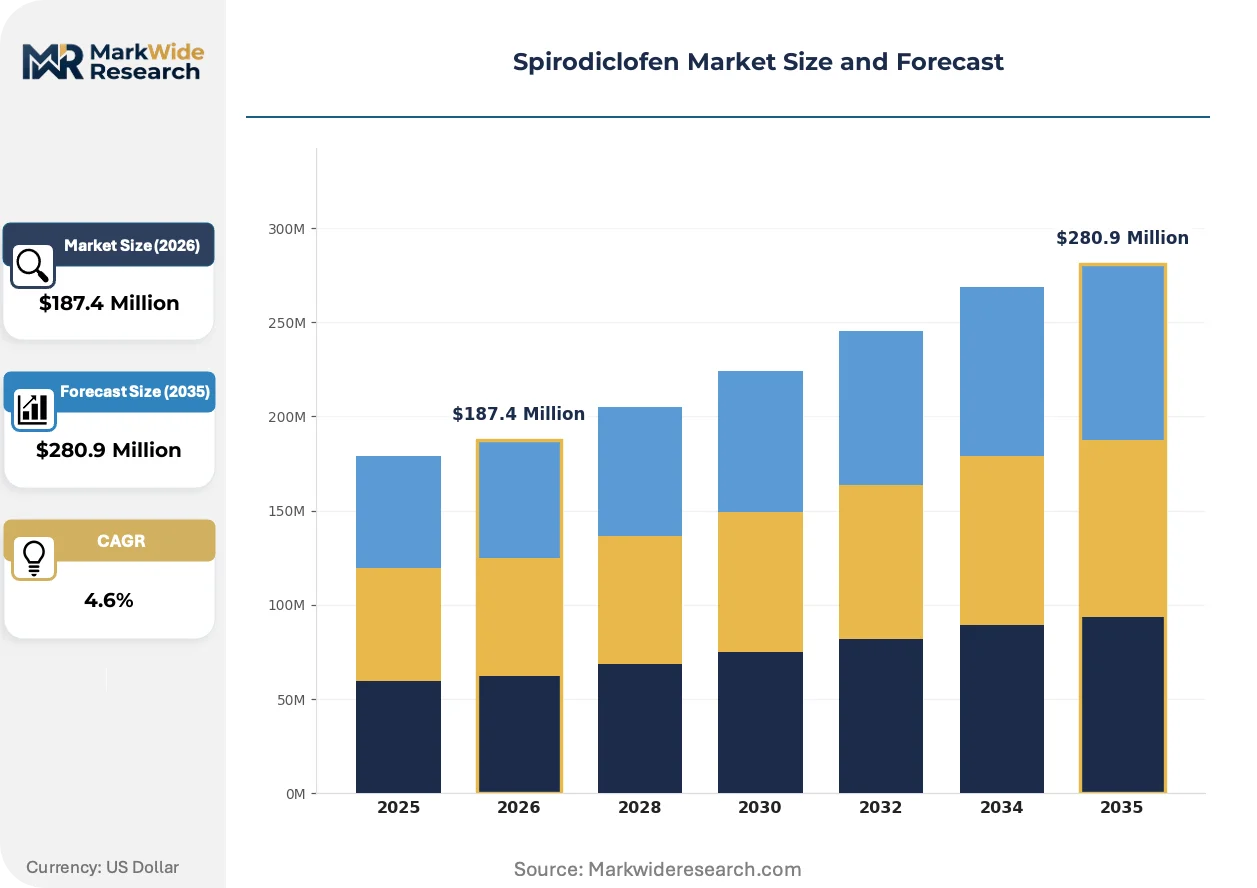
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Emulsifiable Concentrate, Granules, Wettable Powder, Suspension Concentrate Application: Fruit Crops, Vegetable Crops, Ornamental Plants, Transgenic Crops Pest Type: Spider Mites, Whiteflies, Aphids, Thrips Distribution Channel: Online Sales, Wholesale, Retail, Direct Sales |
| Companies Covered | Bayer CropScience, Shijiazhuang Xingbai Bioengineering, Syngenta Crop Protection, BASF, UPL, Corteva Agriscience, FMC Corporation, Sumitomo Chemical, ADAMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spirodiclofen Market Evolving Landscape
Formulation science is pivoting toward user safety and application precision as regulatory thresholds tighten and labor costs rise in mechanized agriculture.
Microencapsulation technology is fragmenting the residual control landscape by enabling pulse-release of active ingredients that align with mite generation cycles. Greenhouse rose producers in Colombia and Kenya adopt these formats to reduce re-entry intervals and comply with supermarket chain residue protocols. The structural consequence is compressing demand for conventional suspension concentrates in high-value ornamental segments.
EFSA's updated guidance on endocrine disruption assessment is forcing registrants to generate new mammalian toxicology data ahead of EU active substance renewal deadlines. This regulatory burden disproportionately affects small and mid-sized formulators lacking in-house regulatory affairs capacity. Pome fruit regions in northern Italy and Poland witness delayed product launches as dossier preparation extends beyond historical timelines.
Cooperative procurement pooling is consolidating buyer power among Brazilian citrus growers who negotiate volume contracts directly with technical-grade suppliers. Traditional distribution channels face margin compression as large farming operations internalize formulation blending capabilities. This behavioral shift concentrates most visibly in São Paulo state's citrus belt where processor-owned cooperatives command procurement decisions.
Spirodiclofen Market Segmentation
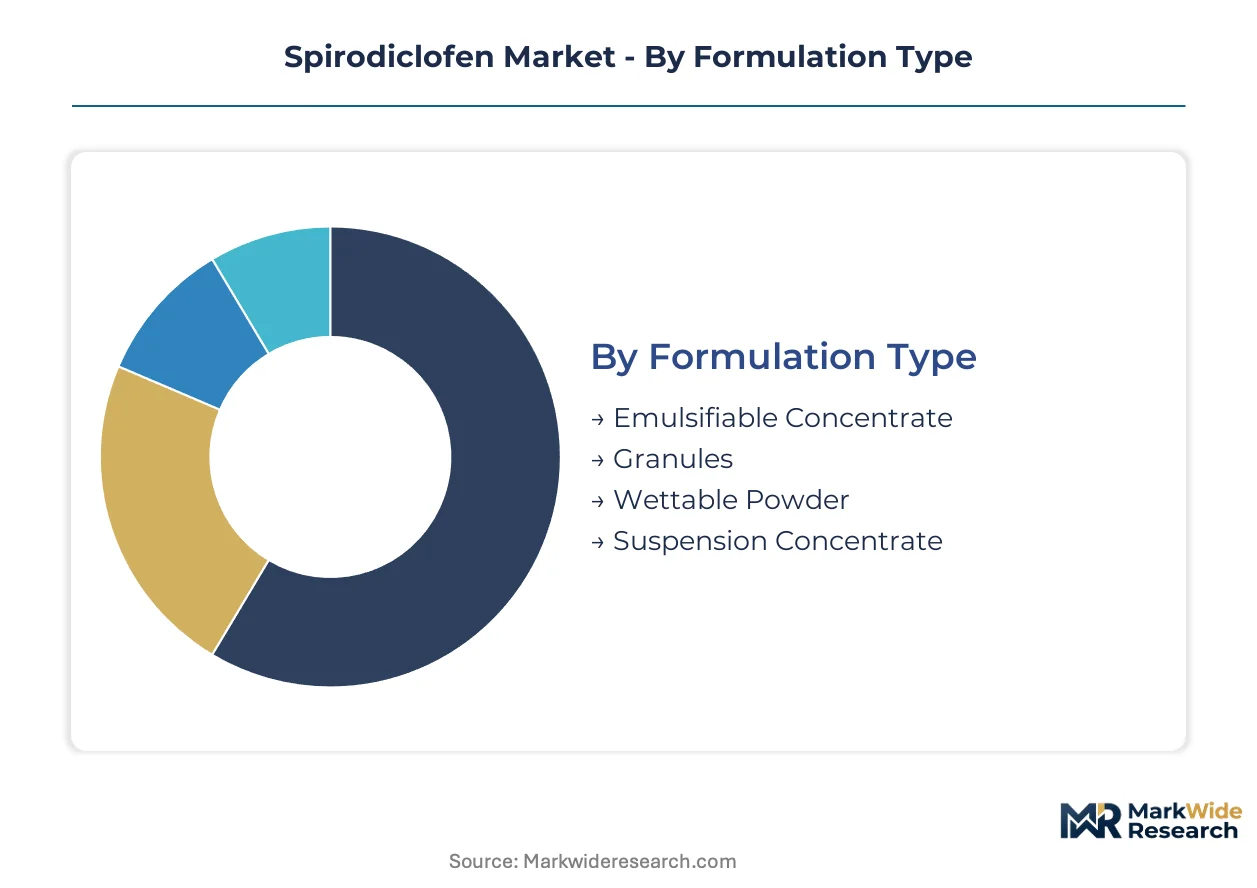
Spirodiclofen's commercial architecture fragments across formulation chemistry, crop specificity, pest target, and channel strategy. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer positioning and grower procurement behavior.
Formulation Type:
Channel mix varies sharply by physical form—suspension concentrates flow through mechanized spray service providers, while emulsifiable concentrates reach smallholder cooperatives via wholesale distributors.
- Suspension Concentrate:Aqueous dispersion systems with superior user safety profiles dominate California Central Valley specialty crop programs. Mechanized spray operations in Brazil's São Paulo citrus belt specify this format for tank-mix compatibility with fungicide partners.
- Emulsifiable Concentrate:Oil-based solutions carrying cost-optimized technical-grade material penetrate Southeast Asian vegetable cooperatives in Vietnam and Thailand. ADAMA and regional generic suppliers anchor volume through this price-accessible format.
- Wettable Powder:Dust-exposure concerns under EU occupational health frameworks are compressing demand in regulated markets; residual use concentrates in legacy orchard operations with existing spray equipment.
- Granules:Soil-incorporation formats serve protected greenhouse structures in Kenya and Colombia where rose producers seek reduced drift and extended residual windows.
Suspension concentrate dominates installed base. Emulsifiable concentrate is where expansion concentrates in price-sensitive emerging markets.
Application:
Margin tiers stratify by crop value intensity—ornamentals command formulation premiums while transgenic acreage faces substitution pressure from trait-embedded pest resistance.
- Fruit Crops:Citrus, pome fruit, and stone fruit applications generate the deepest margin pools; EU MRL harmonization under EFSA oversight shapes registration investment and export-access viability for treated commodities.
- Ornamental Plants:Greenhouse rose production in Colombia and Kenya adopts microencapsulated formats to comply with supermarket chain residue protocols and reduce re-entry intervals.
- Vegetable Crops:Tomato and chili operations in Southeast Asia drive procurement of cost-optimized formulations; integrated pest management mandates in Dutch greenhouses accelerate biological control substitution.
- Transgenic Crops:Bt trait penetration in cotton and maize constrains chemical acaricide attachment rates; spirodiclofen serves rotation windows in resistance management protocols rather than foundation programs.
Fruit crops anchor revenue concentration. Ornamental plants is climbing the fastest on premium formulation uptake.
Pest Type:
Application timing and dose rates diverge by pest biology—ovicidal properties against mite eggs command premium positioning versus adulticidal use patterns.
- Spider Mites:Tetronic acid derivative activity against tetranychid species generates the steepest expansion trajectory; California tomato greenhouses and Brazilian citrus orchards sustain procurement through resistance rotation requirements.
- Whiteflies:Translaminar movement targets Bemisia tabaci nymphs on leaf undersides; Israel and Spain's protected vegetable sectors specify this mode for virus vector suppression.
- Aphids:Secondary label claims support tank-mix positioning though dedicated aphicide chemistry dominates this segment.
- Thrips:Limited efficacy against frankliniella species constrains material allocation; niche use in ornamental propagation facilities.
Spider mites dominate installed base. Whiteflies is where expansion concentrates on virus pressure intensification.
Distribution Channel:
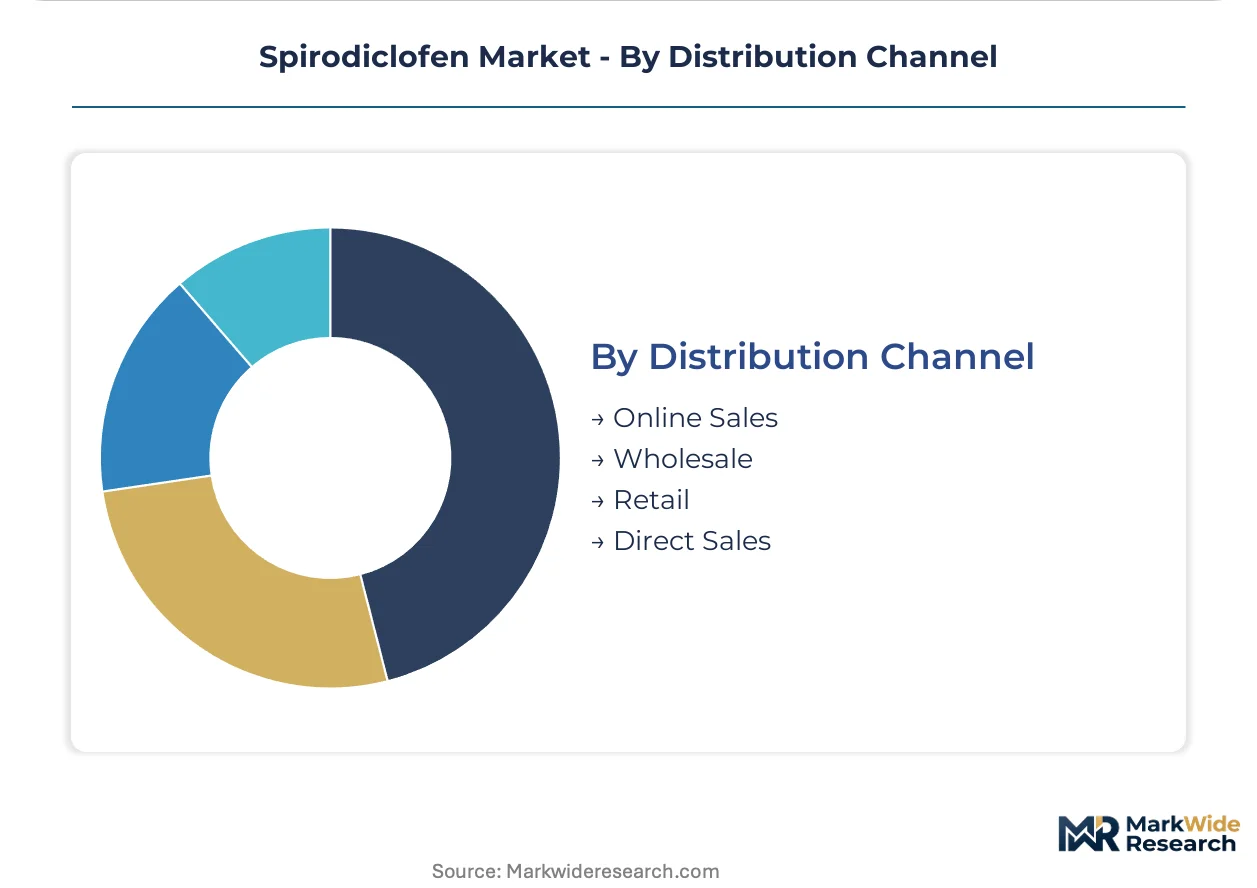
Customer scale and technical service requirements fragment channel selection—direct procurement consolidates among Brazilian cooperatives while retail maintains smallholder reach.
- Wholesale:Regional distributors with formulation blending capabilities serve mid-scale vegetable operations in Mexico's Sinaloa valley and Spain's Almería greenhouse cluster.
- Direct Sales:Processor-owned citrus cooperatives in São Paulo state negotiate volume contracts directly with technical-grade suppliers, bypassing traditional distribution margins.
- Retail:Independent agrochemical retailers maintain smallholder access in India's Maharashtra tomato belt and Thailand's chili-growing regions.
- Online Sales:E-procurement platforms capture emerging share among younger farm managers in Australia's Murray-Darling citrus operations; regulatory compliance documentation limits penetration in EU markets.
Wholesale dominates installed base. Direct sales is where expansion concentrates on cooperative procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports technical-grade spirodiclofen to formulation plants in Brazil and Southeast Asia, creating a trade corridor that shapes regional supply security and procurement timelines for acaricide end-users.
United States
California's Central Valley specialty crop programs drive acaricide procurement through integrated pest management mandates that favor lipid biosynthesis inhibitors. EPA residue tolerance schedules under FIFRA oversight determine label specifications for pome fruit and citrus exports. Fresno County tomato greenhouses and Kern County almond orchards sustain concentrated demand for suspension concentrate formulations.
Brazil
São Paulo state's citrus belt sustains procurement volumes as growers rotate away from organophosphates toward tetronic acid derivatives for Asian citrus psyllid management. ANVISA's re-evaluation framework for existing acaricides introduces registration uncertainty windows that stakeholders monitor closely. Processor-owned cooperatives in the Triângulo Mineiro region negotiate direct volume contracts with technical-grade suppliers, bypassing traditional distribution channels.
China
Jiangsu and Shandong provinces cluster domestic manufacturing of technical-grade material, exposing buyers to NMPA licensing delays and Ministry of Agriculture registration requirements. The country's national pesticide regulator imposes manufacturing license requirements that filter market entry for imported formulations. Export-oriented formulation plants in Nanjing and Qingdao supply Southeast Asian vegetable cooperatives with cost-optimized emulsifiable concentrate formats.
Spain
Almería's protected vegetable sector specifies spirodiclofen for Bemisia tabaci nymph suppression in virus vector management programs. EFSA MRL harmonization under EU Green Deal pesticide reduction targets compresses formulation innovation cycles. Greenhouse clusters in Murcia and Valencia adopt precision application technologies to extend residual control per unit applied.
India
Maharashtra's tomato belt and Gujarat's cotton regions drive procurement through independent agrochemical retailers serving smallholder operations. The Central Insecticides Board regulates registration timelines under the Insecticides Act. Nashik district grape growers and Anand district vegetable cooperatives represent concentrated demand pockets for acaricide rotation partners in resistance management protocols.
Spirodiclofen Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and geographic coverage dimensions. The vendor base stratifies into three tiers: multinational agrochemical conglomerates with integrated R&D pipelines, regional generic suppliers competing on cost-optimized technical material, and specialty formulators focused on microencapsulation delivery systems. Strategic archetypes include patent-protected innovators, backward-integrated manufacturers, and channel-optimized distributors. Dominant competitive moves center on suspension concentrate formulation upgrades and direct procurement relationships with Brazilian citrus cooperatives.
Among diversified agrochemical conglomerates, Bayer CropScience and Syngenta Crop Protection exemplify the patent-protected innovator archetype through established acaricide portfolios. ADAMA occupies a position within the cost-optimized generic tier, serving price-sensitive Southeast Asian vegetable markets through emulsifiable concentrate supply. Shijiazhuang Xingbai Bioengineering represents Chinese private manufacturers concentrated in technical-grade production clusters.
| Leading Market Players |
|---|
| Bayer CropScience |
| Shijiazhuang Xingbai Bioengineering |
| Syngenta Crop Protection |
| BASF |
| UPL |
| Corteva Agriscience |
| FMC Corporation |
| Sumitomo Chemical |
| ADAMA |
| Others |
Value Network & Pricing Analysis
Capacity utilization in China's Jiangsu and Shandong technical-grade clusters shapes both supply concentration and price floors for downstream formulators. Scale economies at these manufacturing hubs compress unit costs for suspension concentrate grades while creating entry barriers for smaller competitors seeking REACH-compliant supply.
Pricing Analysis
Prior-generation wettable powder formats trade at substantial discounts to current suspension concentrate grades, while next-generation microencapsulated variants command formulation premiums. Three-tier pricing structure separates suspension concentrate premiums from emulsifiable concentrate mid-tier positioning and wettable powder economy levels. Price differentiation rests on certification grade under EU MRL harmonization and volume scale in Brazilian cooperative procurement. Cost compression in emulsifiable concentrate tiers is intensifying because of petrochemical feedstock volatility. Southeast Asian vegetable cooperatives exhibit highest price sensitivity; California specialty crop programs show lowest sensitivity due to integrated pest management mandate compliance requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate procurement behavior among Brazilian citrus cooperatives facing ANVISA re-evaluation uncertainty, while just-in-time inventory governs European formulator operations under REACH compliance frameworks. Geographic supply concentrates in China, Brazil, and India for technical-grade material and formulation blending. Raw material dependencies draw from tetronic acid derivative precursors, petrochemical solvents, and suspension agent polymers. Single-source vulnerability in China's Jiangsu province exposes buyers to NMPA licensing delays. Distribution runs through wholesale distributors serving mid-scale operations, direct sales to processor-owned cooperatives, and retail channels reaching smallholder markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spirodiclofen incumbents face substitution defense imperatives as biological control programs in Dutch greenhouse tomato operations displace chemical acaricides in high-value ornamental segments.
For Market Incumbents: Secure suspension concentrate formulation upgrades to maintain tank-mix compatibility advantages against generic emulsifiable concentrate suppliers. Anchor direct procurement relationships with São Paulo citrus cooperatives to bypass margin-compressing distribution channels. Biological control adoption in greenhouse rose production represents the primary substitution threat; vertical integration into microencapsulation technology serves as the critical defensive lever. For New Entrants and Emerging Players: Technical service gaps in precision application technology deployment present white-space opportunities where incumbents under-serve Southeast Asian vegetable cooperatives. Target Vietnam and Thailand chili-growing regions with cost-optimized emulsifiable concentrate supply supported by drone spray system integration services. Penetration concentrates in price-sensitive emerging markets lacking integrated pest management infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty formulators with microencapsulation delivery capabilities over commodity suspension concentrate suppliers. Long-term viability across the projection horizon hinges on regulatory affairs capacity to navigate EFSA endocrine disruption assessment requirements. Acquisition targets should demonstrate in-house toxicology dossier preparation capabilities; signal to watch is ANVISA re-evaluation timeline acceleration for existing acaricide registrations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Technical-Grade Production | Captures margin compression from China's NMPA licensing bottlenecks in Jiangsu supply clusters. |
| Microencapsulation Formulation Development | Addresses EFSA MRL harmonization pressure through pulse-release chemistry extending residual windows. |
| Direct Procurement Channel Establishment | Bypasses wholesale margin layers in São Paulo citrus belt cooperative consolidation trend. |
| Drone Spray System Partnership | Aligns suspension concentrate rheology with low-volume aerial application platforms in Brazilian citrus canopy penetration. |
| Regulatory Affairs Capacity Expansion | Accelerates dossier preparation for Brazil's ANVISA re-evaluation framework toxicology study requirements. |
Research Methodology
Desk research of customs trade data, EPA tolerance schedules, EFSA guidance documents, and ANVISA registration filings preceded structured interviews with formulation R&D directors, Brazilian citrus cooperative procurement managers, European pome fruit grower association technical leads, and Southeast Asian vegetable cooperative agronomists. Primary fieldwork combined with secondary validation across regulatory databases, SEC filings of listed agrochemical conglomerates, and industry association reports. Bottom-up segmentation modeling triangulated against top-down market sizing from technical-grade production capacity estimates.
Variance decomposition across formulation type, crop application, pest target, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization trends in premium suspension concentrate versus economy emulsifiable concentrate tiers. Industry-specific forecast inputs incorporated EPA re-registration timelines and EFSA active substance renewal deadlines.
Forecasts assume regulatory continuity in EPA FIFRA oversight, EU REACH frameworks, and Brazil's ANVISA evaluation procedures; material policy shifts would require re-modeling. Revision becomes warranted when biological control adoption rates in greenhouse ornamental production cross threshold levels displacing chemical acaricide rotation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Pine Chemicals Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Hydrazine Market
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Catechol Market
Chemicals
Piroctone Olamine Market
Chemicals
Bakers Ammonia Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Desalination Chemicals Market
Chemicals
Tin Chemicals Market
Chemicals
Global Glycine Market
Chemicals
Fluorine Derivatives Market
Chemicals
Thiourea Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market