
 Hydrophobing Agents Market | 2026-2036
Hydrophobing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrophobing Agents Market Analysis
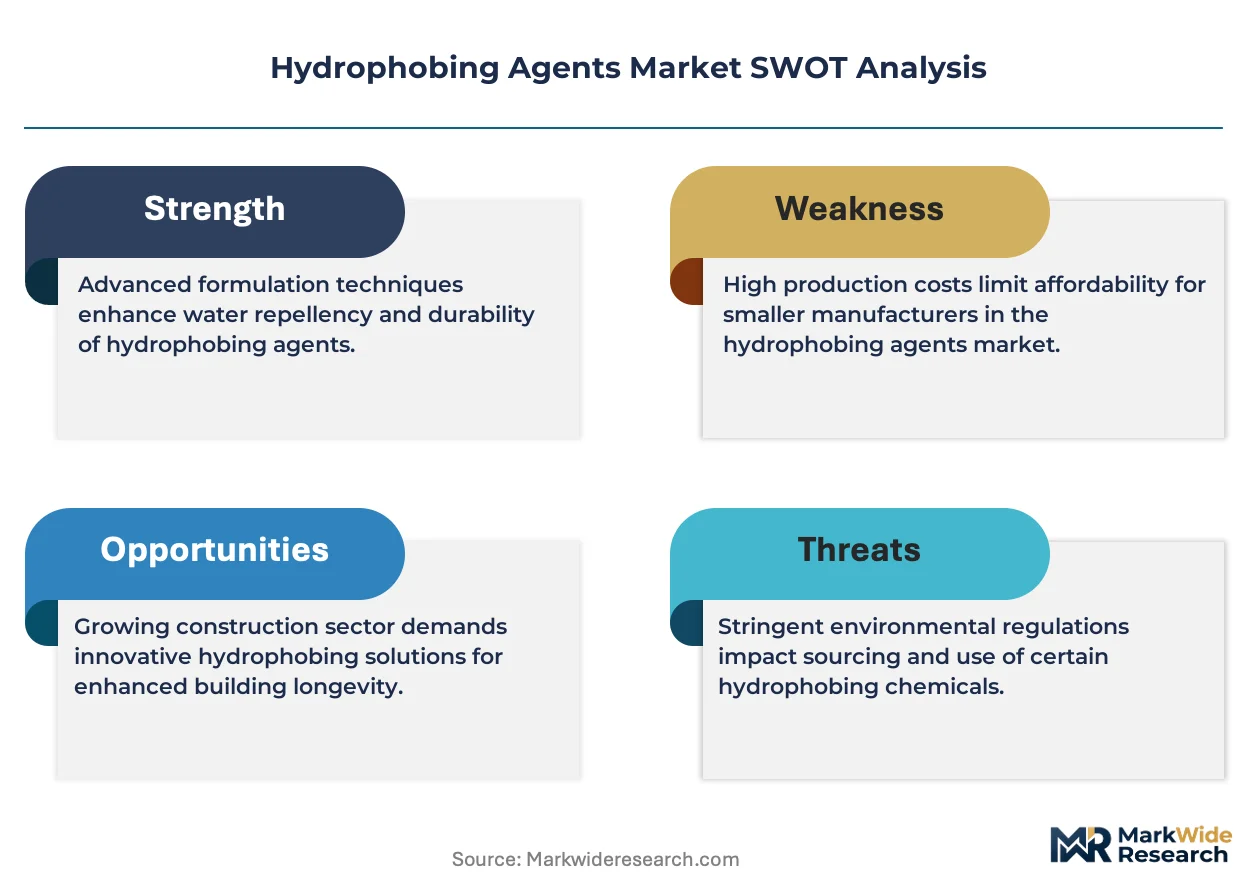
The capital-intensity divergence between integrated silane producers and specialty compounders is unwinding as raw material volatility reshapes margin structures. BASF SE leverages its backward integration into organosilicon precursors to sustain cost discipline across European supply chains. Evonik Industries anchors its position through R&D intensity in hybrid silane-siloxane architectures. Wacker Chemie AG dominates merchant silane supply to Asian coating formulators.
Hydrophobing agents are surface-active compounds—typically organosilanes, fluoropolymers, or polyurethane dispersions—applied at 0.5–5.0 wt% loadings to reduce substrate surface energy below 20 mN/m, primarily to prevent water ingress and chloride ion penetration in porous construction materials. Silane formulations lead the product type matrix due to their covalent bonding with mineral substrates and alkali resistance, while fluoropolymer segments command premium positioning in automotive and aerospace end uses where hydrocarbon repellency is required alongside water resistance. Application in concrete admixtures represents the fastest-expanding structural channel as infrastructure durability specifications extend design-life requirements.
REACH registration requirements in Europe, EPA VOC emission limits in the United States, and China's MEE environmental compliance inspections collectively elevate formulation transparency and restrict solvent-borne hydrophobing systems. The EU Green Deal's embodied carbon benchmarks for construction materials are redirecting specification authority toward environmental product declarations. Stakeholders must monitor regulatory divergence between jurisdictions where chemical hazard classifications are misaligned, as this friction determines which formulation platforms retain multi-region market access.
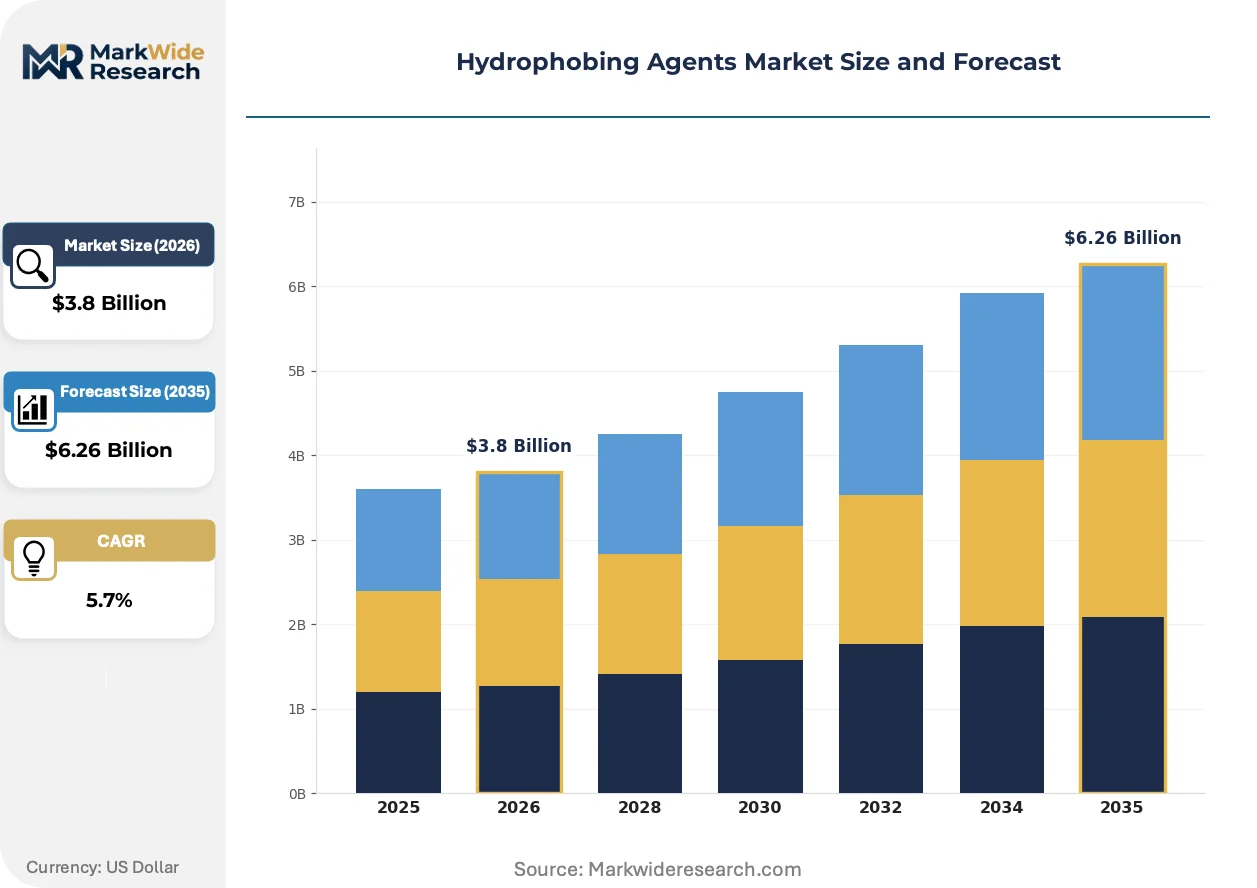
Market Dynamics
Raw material volatility in organosilicon feedstocks is compressing margin structures and forcing specialty compounders toward backward integration or strategic partnerships with merchant silane suppliers.
Growth Catalysts
- REACH compliance deadlines:European formulators are accelerating silane system adoption to meet low-VOC mandates before registration windows close.
- China's coastal infrastructure replacement:Megacity waterproofing specifications in Shanghai, Shenzhen, and Guangzhou are tightening chloride ingress standards for concrete structures.
- Silane-siloxane hybrid architectures:Advanced formulations deliver extended alkali resistance and covalent substrate bonding that fluoropolymers cannot match.
Market Restraints
- Organosilicon feedstock concentration:Merchant silane supply concentrates among German and Chinese producers, exposing compounders to price volatility.
- Fluoropolymer substitution in premium segments:Automotive and aerospace specifications still require hydrocarbon repellency that silanes cannot deliver.
- Regulatory misalignment across jurisdictions:Divergent hazard classifications between EPA VOC limits, REACH registration, and China's MEE inspections fragment multi-region formulation access.
Strategic Opportunities
- India's infrastructure build-out:Smart city initiatives and highway expansion create first-mover positioning for silane admixture suppliers.
- EU Green Deal embodied carbon benchmarks:Environmental product declarations are becoming specification gatekeepers for public construction tenders.
- Hybrid silane-polyurethane convergence:Waterborne systems combining covalent bonding with film-forming properties open wood and masonry coating applications.
Industry Challenges
- Formulation chemist scarcity:Expertise in hybrid organosilicon architectures remains concentrated among legacy European and Japanese technical centers.
- REACH registration capital intensity:Small and mid-size compounders face six-figure dossier costs that favor integrated producers.
- Specification authority fragmentation:Architects, engineers, and asset owners maintain divergent performance testing protocols that complicate standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrophobing Agents Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silane, Siloxane, Polyurethane, Fluoropolymer Application: Building Materials, Textiles, Coatings, Concrete End User: Construction, Textile Manufacturers, Automotive, Aerospace Technology: Spray, Dip Coating, Brush, Roll-on |
| Companies Covered | Tokuyama Corporation, 3M, Evonik Industries, AkzoNobel N.V., PPG Industries, Cabot Corporation, BASF SE, The Sherwin-Williams Company, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrophobing Agents Market Emerging Trajectories
Formulation chemistry is pivoting toward waterborne and low-VOC systems as regulatory pressure intersects with infrastructure durability demands. Three distinct vectors are reshaping competitive positioning.
Hybrid silane-siloxane technology is fragmenting the traditional product matrix by delivering alkali resistance comparable to pure silanes with application flexibility approaching silicones. Concrete admixture formulators in Germany and China are adopting these systems at accelerating rates for bridge deck and tunnel lining specifications. The technology is fragmenting established supplier relationships as compounders bypass pure silane merchants for integrated hybrid suppliers.
REACH registration requirements in Europe are elevating formulation transparency to a competitive differentiator. Substance data sharing and exposure scenario documentation now determine which hydrophobing platforms retain market access. Specialty compounders serving German and French construction markets are consolidating around registrants with complete dossier portfolios.
Asset owner procurement is compressing specification cycles as infrastructure replacement timelines accelerate. Municipal authorities in China's coastal megacities and US state DOTs are unbundling material selection from general contractor discretion. This shift is most visible in Shanghai and California where owner-controlled specifications now mandate silane-based systems for chloride-exposed concrete.
Hydrophobing Agents Market Segmentation
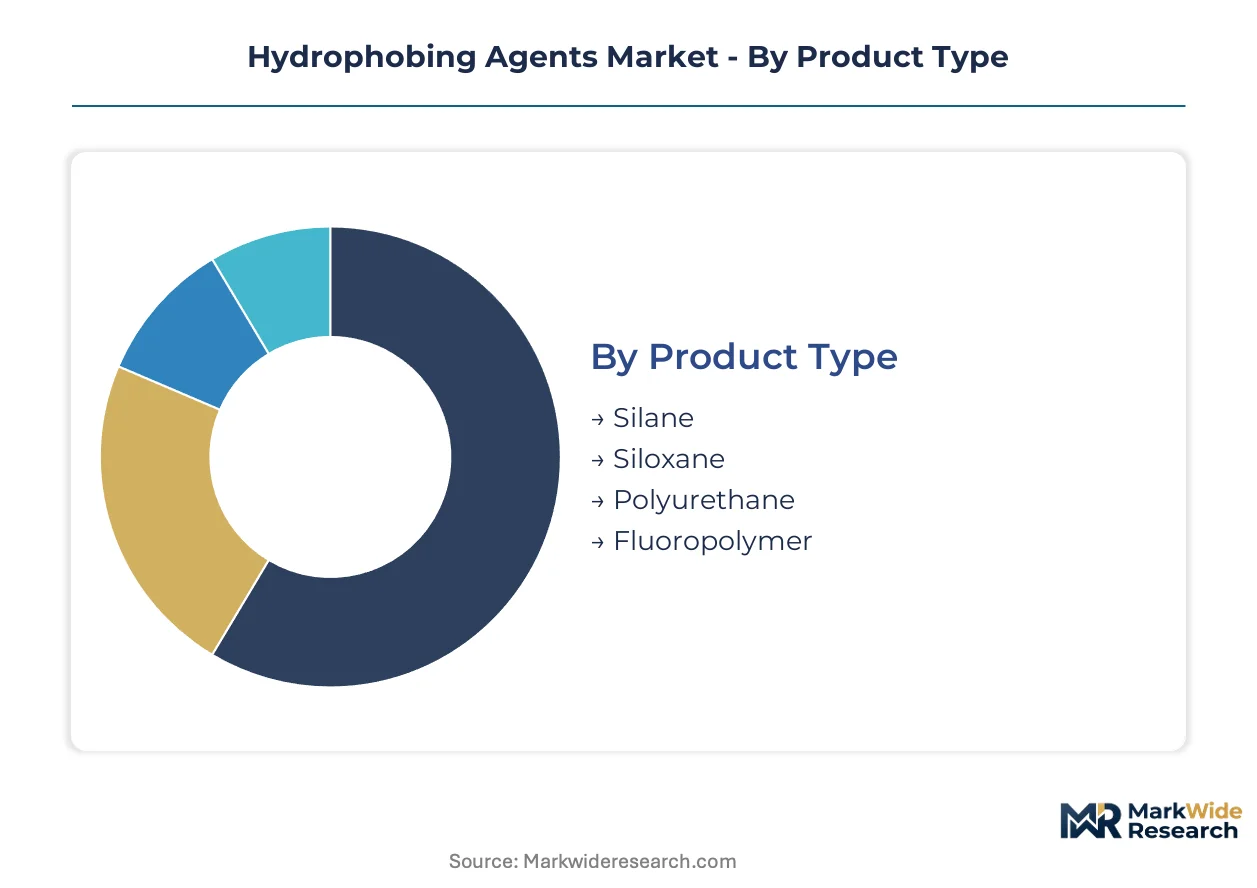
Hydrophobing agent procurement fractures across four distinct category axes, each commanding separate specification authority among architects, coating formulators, and asset owners. Understanding where margin pools concentrate within each dimension determines supplier positioning against tightening durability standards and environmental compliance mandates.
Product Type:
Silane formulations capture the deepest margin pools due to covalent bonding chemistry and REACH registration barriers that limit merchant supply competition.
- Silane:Organosilane monomers and oligomers form permanent Si-O-Si bonds with mineral substrates, delivering alkali resistance above pH 13. Demand concentrates in German bridge deck specifications and China's coastal megacity infrastructure replacement cycles where chloride ingress standards are tightening fastest.
- Siloxane:Polymeric siloxanes provide film-forming hydrophobicity with greater substrate flexibility than silanes. European coating formulators are rotating toward hybrid silane-siloxane architectures to satisfy low-VOC mandates while maintaining concrete penetration depth.
- Polyurethane:Waterborne polyurethane dispersions dominate wood and masonry coating applications where film-forming properties complement covalent bonding. The segment serves premium architectural coatings in North American residential construction.
- Fluoropolymer:Perfluorinated compounds command automotive and aerospace specifications requiring simultaneous hydrocarbon and water repellency. Regulatory pressure from EPA and ECHA on PFAS chemistry is constraining formulation flexibility.
Silane holds installed capacity across European and Chinese merchant supply bases. Siloxane is rotating up the share rankings as hybrid architectures displace pure silane specifications in concrete admixtures.
Application:
Volume concentration tracks infrastructure replacement cycles, with concrete and building materials commanding procurement scale that textile and coating channels cannot match.
- Concrete:Admixture applications represent the steepest expansion trajectory as asset owners unbundle material selection from contractor discretion. Shanghai and California DOT specifications now mandate silane-based systems for chloride-exposed structures.
- Building Materials:Brick, stone, and mortar treatments serve restoration and new construction across European heritage preservation and Middle Eastern luxury residential developments. REACH compliance deadlines are accelerating silane system specification.
- Coatings:Architectural and industrial coatings integrate hydrophobing functionality into multi-layer systems. Waterborne formulation requirements in Germany and China's coastal provinces are redirecting chemistry toward hybrid platforms.
- Textiles:Technical textiles for outdoor apparel and industrial membranes require wash-durable hydrophobicity. Fluoropolymer chemistry retains dominance despite regulatory pressure on perfluorinated compounds.
Concrete applications are gaining share fastest as infrastructure durability specifications extend design-life requirements. Building materials retain the broadest installed specification base across restoration and new construction.
End User:
Customer concentration varies sharply, with construction sector procurement consolidating around municipal and state DOT authorities while automotive and aerospace maintain fragmented OEM specification.
- Construction:Public infrastructure owners in Germany, China, and the United States are tightening waterproofing specifications and mandating environmental product declarations. EU Green Deal embodied carbon benchmarks are becoming specification gatekeepers.
- Automotive:OEM specifications for underbody coatings and interior textiles require hydrocarbon repellency that silane chemistry cannot deliver. Fluoropolymer retention here resists substitution pressure.
- Aerospace:De-icing fluid resistance and fuel tank sealant applications command premium pricing with qualification cycles exceeding five years. Boeing and Airbus specification authority remains concentrated with incumbent fluoropolymer suppliers.
- Textile Manufacturers:Outdoor apparel and industrial membrane producers balance wash durability against regulatory pressure on perfluorinated chemistry. European formulators are accelerating PFAS-free alternative development.
Construction holds the deepest specification authority as asset owners reclaim material selection from general contractors. Aerospace maintains the most defensible margin position through qualification barriers.
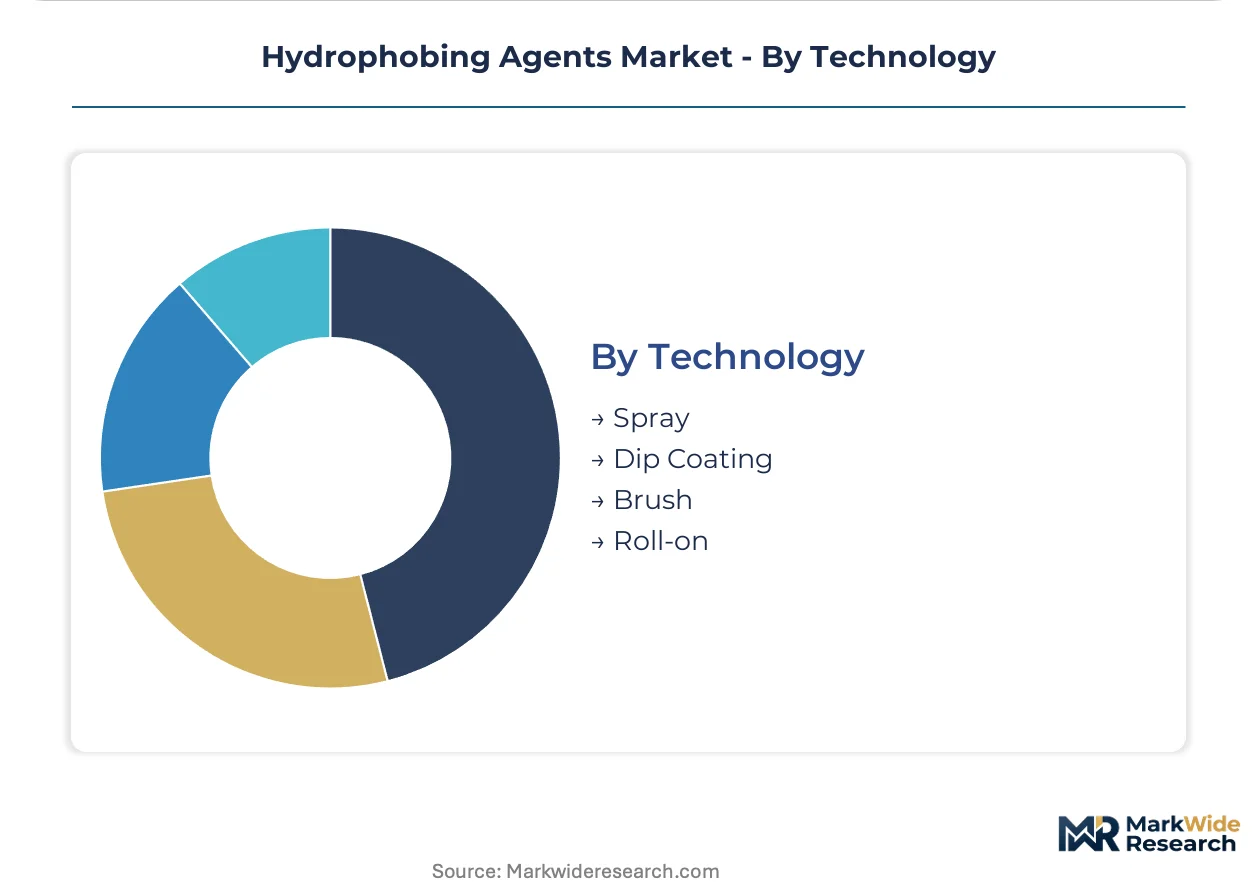
Technology:
Application method selection determines formulation viscosity requirements and labor cost structure, with spray systems commanding industrial scale and brush/roll methods serving restoration niches.
- Spray:Airless and HVLP spray systems dominate industrial concrete and coating applications. German bridge deck contractors specify spray-applied silane systems for penetration depth consistency.
- Dip Coating:Continuous immersion systems serve textile and small-component manufacturing. The technology enables precise loading control for technical textile producers.
- Brush:Manual application persists in heritage restoration and detail work where substrate geometry prevents spray coverage. European masonry restoration specialists maintain specification authority here.
- Roll-on:Roller application serves DIY and light commercial markets with lower skill requirements. The segment tracks residential construction cycles in North American and Australian markets.
Spray technology holds installed capacity across industrial infrastructure channels. Dip coating is climbing the fastest as technical textile production scales in Asia-Pacific manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's coastal megacities exhibit the lowest price elasticity as infrastructure replacement cycles compress procurement timelines, while Indian state highway authorities remain acutely sensitive to unit economics in bulk admixture tenders. European formulators occupy a middle position where REACH compliance costs override pure price competition.
China
Shanghai, Shenzhen, and Guangzhou municipal authorities are unbundling material selection from contractor discretion for bridge deck and tunnel specifications. MEE environmental compliance inspections are redirecting formulation chemistry toward low-VOC silane systems in coastal provinces. The Yangtze River Delta manufacturing cluster is scaling waterborne hybrid production to serve domestic infrastructure replacement demand.
Germany
Federal transport infrastructure budgets are tightening waterproofing specifications for autobahn bridge maintenance and railway tunnel rehabilitation. REACH registration deadlines are accelerating silane system adoption as formulators face six-figure dossier costs. The Rhine-Ruhr industrial corridor concentrates backward-integrated organosilicon production serving European coating compounders.
United States
State DOT authorities in California and New York are mandating silane-based systems for chloride-exposed concrete structures. EPA VOC emission limits are constraining solvent-borne hydrophobing systems in architectural coatings. The Gulf Coast petrochemical corridor maintains merchant silane supply to domestic admixture formulators.
India
Smart city initiatives and National Highway Authority expansion are creating procurement scale for concrete admixture suppliers. BIS certification requirements are elevating quality barriers for imported formulation chemistry. The Delhi-Mumbai Industrial Corridor is concentrating infrastructure investment where waterproofing specifications are tightening fastest.
Japan
Metropolitan Tokyo and Osaka prefectures are extending design-life requirements for underground infrastructure and coastal flood defenses. METI industrial standards are harmonizing with REACH substance data sharing protocols for construction chemical imports. The Kanto region maintains specification authority for high-performance hybrid silane-siloxane systems.
Hydrophobing Agents Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive organosilicon supply and the latter competing on formulation agility. The upper tier leverages backward integration into precursors to sustain margin discipline during raw material volatility. Three archetypes define competitive positioning: integrated chemical conglomerates with merchant silane capacity, specialty compounders focused on hybrid architectures, and regional coating formulators serving localized specification authority. Dominant competitive moves include strategic partnerships between compounders and merchant suppliers to secure feedstock access, and portfolio diversification into waterborne systems to satisfy tightening VOC mandates.
Within the integrated chemical tier, BASF SE and Evonik Industries exemplify divergent strategic postures—BASF anchoring cost discipline through captive precursor supply, Evonik occupying a position defined by R&D intensity in hybrid architectures. Wacker Chemie AG sits within the merchant supply archetype, dominating silane distribution to Asian coating formulators. These three entities collectively represent how European chemical conglomerates have partitioned the value chain between upstream control and downstream formulation specialization.
| Leading Market Players |
|---|
| Tokuyama Corporation |
| 3M |
| Evonik Industries |
| AkzoNobel N.V. |
| PPG Industries |
| Cabot Corporation |
| BASF SE |
| The Sherwin-Williams Company |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Merchant silane capacity utilization above 85% across the Rhine-Ruhr and Yangtze River Delta corridors is anchoring price floors for compounders lacking backward integration. German integrated producers leverage captive organosilicon supply to resist margin compression while specialty formulators absorb feedstock volatility through quarterly contract renegotiations.
Pricing Analysis
After-sales technical service contracts spanning formulation optimization and on-site application training represent the highest lifetime value tier for hydrophobing agent suppliers. Project-based pricing dominates concrete admixture procurement as municipal authorities bundle material supply with performance warranties. Price differentiation hinges on REACH dossier completeness and penetration depth certification under German bridge deck specifications. Cost compression in siloxane hybrid tiers is intensifying as Chinese coastal formulators scale waterborne production. Indian state highway authorities exhibit acute price sensitivity in bulk tenders, while Shanghai municipal buyers prioritize chloride ingress performance over unit economics.
Supply Chain Analysis
Inventory buffers for organosilicon monomers rarely exceed three weeks across European coating compounders, exposing formulators to supply interruptions. Merchant silane production concentrates in Germany, China, and the United States, with the Rhine-Ruhr corridor feeding Western European demand and the Yangtze Delta serving Asia-Pacific coating formulators. Raw material dependencies center on methylchlorosilane precursors, methanol feedstock, and platinum-group catalysts. Single-source vulnerability concentrates in high-purity silane oligomers qualified for aerospace sealant applications. Distribution runs through regional chemical distributors holding technical inventory for concrete admixture contractors and coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure asset owners are consolidating specification authority across Germany, China, and California, compressing contractor discretion and elevating environmental product declarations to procurement gatekeepers.
For Market Incumbents: Compound defensive positioning through REACH registration portfolio completion and captive precursor capacity expansion in the Yangtze River Delta. Silane-siloxane hybrid R&D intensity must accelerate as Chinese formulators displace pure silane specifications. Backward integration into organosilicon feedstocks anchors margin discipline against merchant supply volatility. For New Entrants and Emerging Players: Technical service gaps in Indian smart city concrete admixture deployment create first-mover positioning for hybrid system suppliers with localized application support. India's National Highway Authority expansion represents the most penetrable procurement channel for silane admixture specialists. A go-to-market angle targeting BIS certification assistance alongside material supply differentiates against incumbent distributors. For Investors and Strategic Acquirers: Specialty compounders with complete REACH dossiers and established relationships with German transport infrastructure authorities offer durable cash flow visibility. The acquisition target archetype encompasses regional coating formulators holding municipal specification authority in China's coastal megacities. The signal to watch is accelerating unbundling of material selection from general contractor discretion in US state DOT procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organosilicon Precursors | Captive methylchlorosilane supply insulates BASF and Evonik from merchant price volatility. |
| REACH Dossier Completion | Full substance registration secures market access as European registration windows close. |
| Hybrid Silane-Siloxane R&D Expansion | Advanced architectures displace pure silane specifications in German bridge deck contracts. |
| Waterborne Formulation Scale-Up | Low-VOC production alignment captures MEE compliance demand in China's coastal provinces. |
| Long-term Supply Agreements with Municipal Authorities | Direct procurement relationships with Shanghai and California DOTs compress specification cycles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, Cefic sector reports, SEC 10-K filings, and ECHA registration databases to validate volume and value estimates. Primary interviews engaged technical R&D directors at coating formulators, procurement leads at concrete admixture suppliers, plant managers at merchant silane producers, and specification engineers at German and Chinese transport infrastructure authorities. Bottom-up triangulation across product-grade volume builds and top-down cross-checks against end-use consumption patterns anchor forecast integrity.
Segmentation dimensions modeled span product type chemistry, application channel, end-user industry concentration, and regional regulatory cluster across the projection horizon. CAGRs derive from fitted growth curves against infrastructure replacement cycle timing and environmental compliance deadline phasing. Forecast inputs incorporate REACH registration completion rates, MEE inspection enforcement intensity, and chloride ingress specification tightening trajectories in coastal megacities.
Material uncertainties — feedstock price volatility, regulatory reclassification of organosilicon substances, and infrastructure budget allocation shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding specification authority migration and hybrid technology adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Quaternium-15 Market
Chemicals
Phenylethyl Market
Chemicals
Global Methylene Chloride Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Acrylic Acids and Esters Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Oxybenzone Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Aromatic Polyamine Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market