
 Metal Removal Fluids Market | 2026-2036
Metal Removal Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Removal Fluids Market Analysis
Aerospace manufacturing is realigning metal removal fluid procurement toward high-performance synthetic formulations capable of titanium and nickel-alloy machining. Quaker Houghton leverages its specialty chemical portfolio to dominate aerospace-qualified fluid supply chains. FUCHS anchors European demand through its Stuttgart-based R&D campus focused on biodegradable cutting fluid chemistry. Castrol competes in Asian industrial clusters with metalworking fluid lines engineered for high-speed CNC environments.
Metal removal fluids are lubricating coolants formulated from mineral oils, synthetic esters, or water-dilutable concentrates designed to reduce friction, dissipate heat, and evacuate chips during machining, grinding, and forming operations; their performance is measured by parameters including pH stability, corrosion protection duration, and foam tendency under high-pressure delivery. Synthetic formulations command premium positioning due to extended sump life and superior heat transfer coefficients in demanding applications. Oil-based segments retain entrenched positions in heavy-duty broaching and gear cutting where extreme pressure additives prove essential. Water-soluble concentrates capture volume in general metalworking shops prioritizing cost per gallon and waste treatment simplicity.
EPA regulates metalworking fluid discharges under Clean Water Act effluent guidelines, while OSHA enforces permissible exposure limits for oil mist and biocide components in manufacturing facilities. REACH registration requirements in Europe compel reformulation of chlorinated paraffin and formaldehyde-releasing biocide chemistries, redirecting R&D investment toward boron-free and vegetable-derived base stocks. Stakeholders must monitor evolving biocide restrictions across multiple jurisdictions while assessing whether synthetic fluid premiums justify total cost of ownership reductions in extended-use environments.
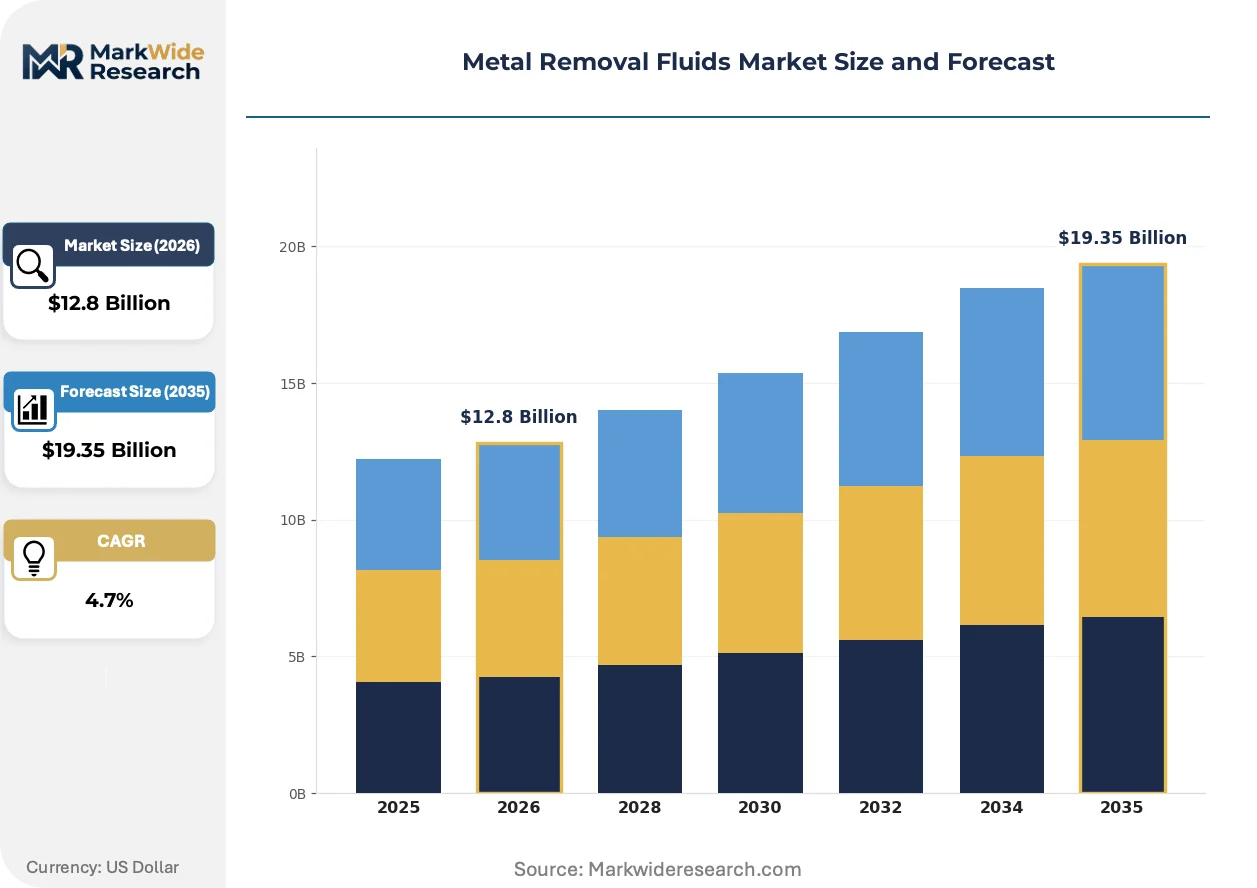
Market Dynamics
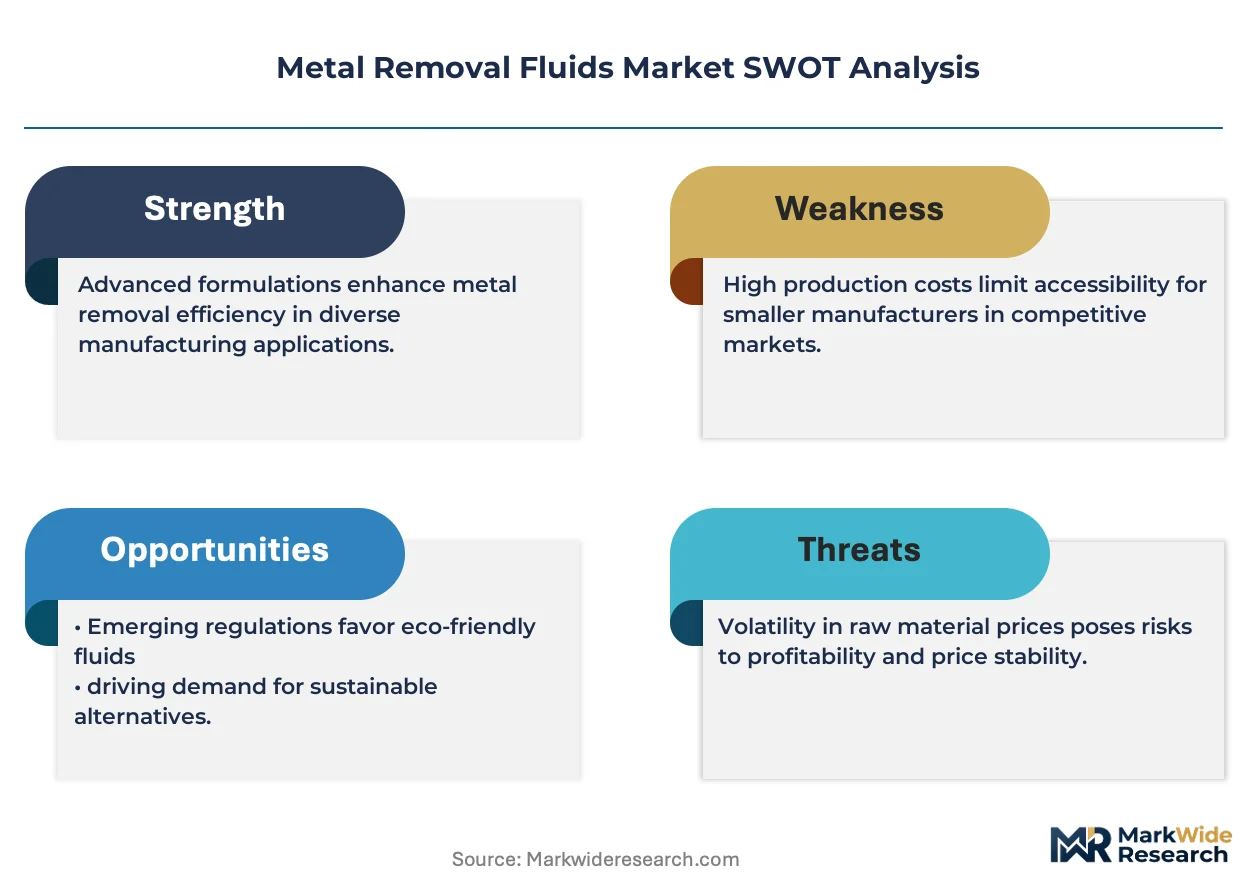
REACH and EU Green Deal mandates are forcing wholesale reformulation of metal removal fluid chemistries, redirecting R&D investment away from chlorinated paraffins and formaldehyde-releasing biocides toward boron-free and vegetable-derived alternatives. This regulatory pressure is compressing legacy product lifecycles while creating first-mover advantages for suppliers with clean-sheet synthetic portfolios.
Growth Catalysts
- Aerospace-qualified synthetic formulations:Titanium and nickel-alloy machining requirements in commercial aviation are pulling demand toward high-performance coolants with superior heat transfer coefficients and extended sump life.
- REACH registration deadlines:European chemical disclosure requirements are accelerating customer migration to pre-registered synthetic ester bases that eliminate compliance uncertainty.
- Germany's precision engineering corridor:Concentrated demand around Stuttgart and Munich is anchoring regional consumption of biodegradable cutting fluids for high-tolerance CNC operations.
Market Restraints
- Base stock supply concentration:Vegetable-derived ester feedstocks depend on limited Southeast Asian oleochemical processing capacity, exposing formulators to agricultural commodity volatility.
- Biocide regulatory fragmentation:Divergent national restrictions on isothiazolinone and triazine chemistries complicate global product standardization and inflate registration costs.
- Legacy oil-based infrastructure:Heavy-duty broaching and gear cutting operations retain entrenched mineral oil systems due to extreme pressure additive performance requirements that synthetics have not fully replicated.
Strategic Opportunities
- Indian manufacturing scale-up:PLI scheme incentives for precision engineering and automotive component production are creating fresh demand for water-soluble concentrates in underpenetrated industrial clusters.
- Closed-loop coolant management:Centralized fluid recycling services represent a channel innovation that captures recurring revenue while locking in formulation supply agreements.
- ISO 14001 certification convergence:Environmental management system mandates are tilting procurement specifications toward suppliers with verified lifecycle assessments and carbon footprint disclosures.
Industry Challenges
- Tribology-chemistry cross-training:Formulation teams require hybrid expertise in friction mechanics and polymer science that traditional lubricant engineering programs rarely produce.
- Multi-jurisdiction biocide compliance:Synchronized regulatory filings across EPA, ECHA, and emerging market agencies strain regulatory affairs bandwidth and extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Removal Fluids Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Soluble, Oil-Based, Semi-Synthetic, Synthetic Application: Metalworking, Automotive Manufacturing, Aerospace, Machinery Maintenance End User: Manufacturers, OEMs, Maintenance Providers, Workshops Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Quaker Houghton, FUCHS, Exxon Mobil Corporation, TotalEnergies, BP p.l.c., Chevron Corporation, Shell plc, Castrol, Idemitsu Kosan Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Removal Fluids Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based and hybrid synthetic platforms that reconcile performance thresholds with tightening chemical safety mandates. This shift is compressing the viable lifecycle of legacy mineral oil formulations while rewarding suppliers with advanced ester and polyalkylene glycol capabilities.
Microemulsion technology is absorbing machining heat more efficiently than conventional soluble oils while maintaining the lubricity required for difficult-to-cut alloys. Aerospace tier suppliers in Germany and Japan are adopting these systems at accelerated pace for titanium structural components. The technology is absorbing market share from semi-synthetics in applications where thermal stability and residue control determine part quality.
ECHA's restriction proposals on medium-chain chlorinated paraffins are forcing reformulation of extreme-pressure additives across European metalworking supply chains. Industrial consequence includes accelerated qualification of sulfur-phosphorus and borate ester alternatives in gear cutting and broaching fluids. Heavy-duty applications in Central European automotive supply chains are most affected, with formulators accelerating alternative additive package validation.
Fluid management service contracts are displacing transactional gallon sales as the dominant commercial model in high-volume manufacturing environments. Tier-one automotive suppliers in the US Midwest and German Mittelstand firms are consolidating vendor relationships around performance-guaranteed coolant programs. This pattern is most visible in precision machining clusters where sump life optimization and waste minimization carry measurable total cost impact.
Metal Removal Fluids Market Segmentation
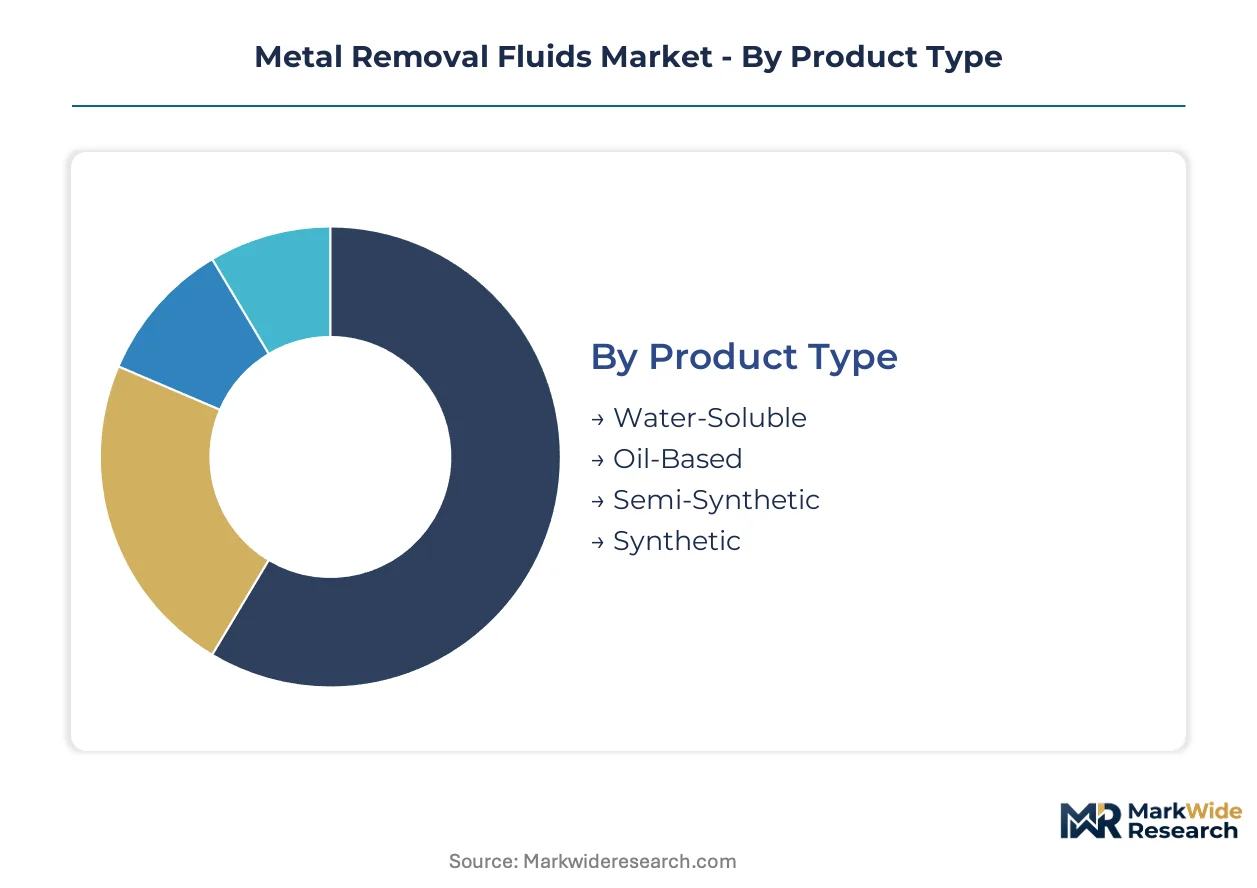
Metal removal fluid procurement splits sharply across certification requirements. Aerospace-qualified synthetics demand REACH pre-registration and Boeing/Airbus process approvals, while general metalworking shops prioritize cost-per-gallon metrics over regulatory documentation.
Product Type:
REACH registration deadlines and Boeing process specifications create tiered certification burdens. Synthetics and semi-synthetics require full ECHA dossier submission; oil-based legacy formulations face MCCP restriction pressures.
- Synthetic:Formulated from polyalkylene glycols and synthetic esters delivering superior heat transfer coefficients and extended sump life. Demand concentrates in Stuttgart and Munich precision engineering corridors where REACH-compliant pre-registered bases eliminate supply uncertainty. Boeing and Airbus tier suppliers mandate these formulations for titanium structural component machining.
- Semi-Synthetic:Hybrid platforms combining mineral oil segments with synthetic performance additives. Japanese aerospace tier suppliers adopt these for nickel-alloy applications where thermal stability requirements sit below full synthetic thresholds but above soluble oil capabilities.
- Oil-Based:Mineral oil formulations with extreme-pressure additive packages dominate heavy-duty broaching operations in legacy automotive supply chains.
- Water-Soluble:Cost-optimized concentrates capturing volume in Indian PLI-scheme precision engineering clusters prioritizing waste treatment simplicity.
Leading the category by volume: Water-Soluble. Growing fastest: Synthetic.
Application:
End-use differentiation tracks thermal load severity and surface finish tolerances. Aerospace and automotive powertrain applications drive premium formulation uptake; maintenance operations favor standardized concentrates.
- Aerospace:Titanium and nickel-alloy machining demands coolants with validated heat transfer performance under high-pressure delivery. German Mittelstand firms and Japanese tier suppliers specify microemulsion synthetics for structural component programs.
- Automotive Manufacturing:Powertrain machining lines in US Midwest and Central European corridors favor semi-synthetics balancing sump life with cost per gallon in high-volume CNC environments.
- Metalworking:General job shops across India's emerging industrial clusters prioritize water-soluble concentrates for multi-metal compatibility.
- Machinery Maintenance:Repair and overhaul operations standardize on legacy soluble oils with minimal qualification overhead.
Volume leadership: Automotive Manufacturing. Steepest expansion trajectory: Aerospace.
End User:
Procurement sophistication varies across organizational scale and technical staffing density. OEMs maintain formulation qualification teams; workshops rely on distributor technical support.
- Manufacturers:Tier-one automotive suppliers in Germany and the US consolidate vendor relationships around performance-guaranteed coolant programs with centralized fluid recycling services.
- OEMs:Boeing, Airbus, and powertrain original equipment manufacturers mandate supplier process approvals and REACH documentation audits.
- Maintenance Providers:Independent repair facilities purchase through wholesale distributors prioritizing inventory breadth over technical specification depth.
- Workshops:Small metalworking shops in India's PLI-scheme corridors represent underpenetrated demand for water-soluble concentrate technical support.
Category margin leader: OEMs. Fastest-growing customer type: Manufacturers.
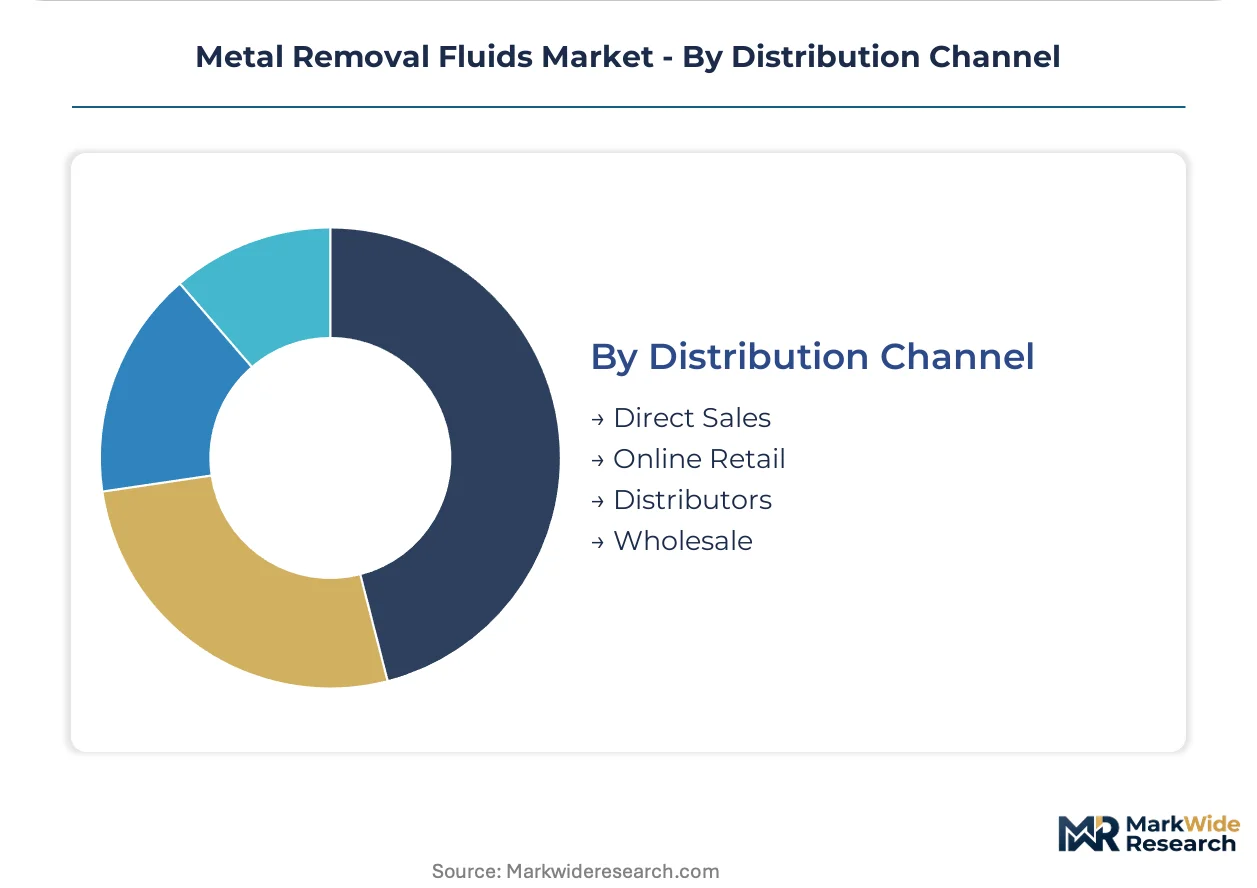
Distribution Channel:
Channel selection reflects order scale and technical service requirements. Direct relationships dominate aerospace-qualified supply; distributors capture fragmented workshop demand.
- Direct Sales:Quaker Houghton and FUCHS maintain technical service engineers co-located with Stuttgart and Munich aerospace manufacturing clusters.
- Distributors:Industrial supply houses capture volume in general metalworking shops across India's emerging precision engineering corridors.
- Wholesale:Bulk concentrate supply to automotive tier suppliers in the US Midwest runs through regional lubricant wholesalers.
- Online Retail:Small-package soluble oil and coolant concentrate sales to independent workshops through industrial e-commerce platforms.
Revenue concentration: Direct Sales. Channel expanding most quickly: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering corridor around Stuttgart and Munich concentrates aerospace-qualified synthetic fluid demand, while India's PLI-scheme industrial zones are scaling water-soluble concentrate consumption for emerging precision manufacturing clusters.
Germany
Baden-Württemberg's aerospace tier suppliers and Bavarian automotive powertrain manufacturers drive synthetic and semi-synthetic formulation demand. REACH registration deadlines and EU Green Deal mandates compel migration toward pre-registered ester bases. Stuttgart-based R&D campuses focus on biodegradable cutting fluid chemistry for high-tolerance CNC operations serving Airbus structural component programs.
United States
Midwest automotive powertrain machining lines and Pacific Northwest aerospace fabrication sustain premium coolant consumption. EPA Clean Water Act effluent guidelines and OSHA oil mist exposure limits shape formulation compliance requirements. Michigan and Ohio industrial clusters consolidate vendor relationships around performance-guaranteed coolant programs with centralized fluid recycling services.
India
Maharashtra and Gujarat precision engineering clusters under the PLI scheme generate fresh demand for water-soluble concentrates in underpenetrated markets. BIS standards and DGFT import regulations influence local formulation sourcing strategies. Tamil Nadu automotive component manufacturing corridors adopt cost-optimized concentrates prioritizing waste treatment simplicity over performance premiums.
Japan
Kanto and Kansai aerospace tier suppliers specify microemulsion synthetics for nickel-alloy structural components. METI industrial standards and JIS certification requirements guide procurement specifications toward thermally stable formulations. Nagoya-area precision machining clusters adopt hybrid semi-synthetic platforms where thermal requirements sit below full synthetic thresholds.
China
Yangtze River Delta and Pearl River Delta manufacturing zones absorb volume in general metalworking applications. MEE environmental regulations and dual carbon goals redirect formulation investment toward lower-emission chemistries. Shandong Peninsula industrial corridors balance cost-optimized soluble oils with emerging synthetic adoption in export-oriented precision component sectors.
Metal Removal Fluids Market Vendor Landscape
Top-tier vendors anchor aerospace-qualified supply chains, while mid-tier specialists capture fragmented general metalworking demand. The vendor base stratifies across three tiers: multinational lubricant conglomerates with integrated R&D campuses, regional formulators with distributor-heavy channel strategies, and niche specialists in biodegradable ester chemistry. M&A activity concentrates on synthetic portfolio expansion and geographic footprint extension into Indian PLI-scheme corridors.
Within the multinational tier, Quaker Houghton and FUCHS exemplify divergent geographic anchoring strategies. Quaker Houghton leverages specialty chemical capabilities to occupy positions in aerospace-qualified fluid supply chains, while FUCHS anchors European demand through Stuttgart-based technical service infrastructure. Castrol represents the Asia-Pacific focused archetype, competing in high-speed CNC industrial clusters with formulation lines engineered for thermal stability requirements. These three entities collectively illustrate how competitive positioning maps to regional manufacturing density and certification complexity.
| Leading Market Players |
|---|
| Quaker Houghton |
| FUCHS |
| Exxon Mobil Corporation |
| TotalEnergies |
| BP p.l.c. |
| Chevron Corporation |
| Shell plc |
| Castrol |
| Idemitsu Kosan Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal chemical disclosure mandates gate qualified supply access and premium-tier pricing power for metal removal fluid formulators. REACH registration deadlines compress viable supplier pools while concentrating margin capture among pre-registered synthetic ester base stock providers serving aerospace-qualified buyers.
Pricing Analysis
Short lead-time premiums for REACH-registered synthetic ester bases command substantial markups over spot vegetable-oil inventories with uncertain compliance documentation. Three-tier pricing structure separates aerospace-certified microemulsions from semi-synthetic powertrain grades and economy water-soluble concentrates. Pricing pressure stems from Southeast Asian oleochemical feedstock volatility squeezing vegetable-derived formulation margins. General metalworking workshops exhibit highest price sensitivity; Boeing and Airbus tier suppliers demonstrate lowest sensitivity due to process approval lock-in costs.
Supply Chain Analysis
Workforce availability constraints in Germany's Stuttgart precision engineering corridor and Maharashtra's PLI-scheme industrial zones concentrate high-skill formulation capacity. Supply draws from Malaysian and Indonesian palm kernel oleochemical processing, German synthetic ester R&D campuses, and Indian water-soluble concentrate blending facilities. Single-source vulnerability runs through Southeast Asian vegetable ester feedstock concentration exposed to agricultural commodity swings. Distribution runs through direct technical service teams for aerospace-qualified accounts and industrial distributors for fragmented workshop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration deadlines construct a cost-of-compliance moat that entrenches pre-registered synthetic suppliers while accelerating customer consolidation around compliant formulators. ECHA's medium-chain chlorinated paraffin restriction proposals deepen this barrier by forcing legacy reformulation investments that mid-tier competitors cannot absorb.
For Market Incumbents: Deploy centralized fluid recycling service contracts to lock in formulation supply agreements with tier-one automotive manufacturers. Capture recurring revenue streams from Michigan and Ohio powertrain machining clusters while defending against emerging Indian formulators with cost-optimized water-soluble concentrate lines. Strengthen Stuttgart-based technical service infrastructure to anchor European aerospace-qualified demand against Castrol's Asian industrial cluster penetration.
For New Entrants and Emerging Players: Industrial e-commerce platforms offer the lowest-friction route to penetrate India's underpenetrated PLI-scheme precision engineering workshops. Target Tamil Nadu and Gujarat metalworking clusters with technical support bundles for water-soluble concentrate first-time adopters. Partner with regional lubricant wholesalers to bypass direct sales infrastructure requirements while building formulation credibility.
For Investors and Strategic Acquirers: Boeing process approval wins for titanium machining synthetics signal the leading indicator that a formulator has crossed the compliance threshold for sustainable aerospace supply chain positioning. Long-term viability favors synthetic ester specialists with verified lifecycle assessments over mineral oil legacy players facing MCCP additive restrictions. Monitor ECHA biocide restriction proposals as the inflection trigger for accelerated market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstocks | Captive Malaysian palm kernel ester supply secures margin against agricultural commodity volatility. |
| REACH Pre-Registration Investment | ECHA dossier submission eliminates customer migration risk ahead of deadline compression. |
| Closed-Loop Coolant Management Service Launch | Performance-guaranteed programs capture recurring revenue from US Midwest automotive tiers. |
| Microemulsion Technology Qualification | Titanium machining approval from Airbus tier suppliers opens aerospace structural component demand. |
| Joint Venture with Indian Distributor Network | Maharashtra and Gujarat channel access accelerates PLI-scheme precision engineering penetration. |
Methodological Framework
Trade association filings from ACC and Cefic, customs export databases, and SEC 10-K lubricant segment disclosures formed the secondary backbone of this analysis. Primary interviews with plant engineers at German automotive powertrain facilities, procurement leads at aerospace tier suppliers, distribution channel partners in Indian industrial corridors, and technical R&D directors at synthetic ester laboratories combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis of synthetic ester adoption rates, semi-synthetic penetration in powertrain machining, and water-soluble concentrate volume shifts informed the projection framework. Segmentation modeling spanned product type, application severity tier, end-user procurement sophistication, and regional regulatory cluster across the analysis window. CAGR derivation incorporated aerospace build rate forecasts, automotive powertrain production indices, and REACH compliance deadline impacts on supplier pool concentration.
The model holds under stable REACH implementation timelines and sustained aerospace production schedules; deviation in ECHA biocide restriction acceleration or Southeast Asian feedstock supply disruption would shift trajectory. Forecasts reflect these base-case assumptions with acknowledged sensitivity to regulatory enforcement intensity and agricultural commodity cycles. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
CDU Heat Exchanger Antifoulants Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Regenerative Thermal Oxidizer Market
Industrial Chemicals
Ferric Chloride As Etchant Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Chemical Process Mixers Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
North America Molecular Sieve Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market