
 Butadiene Derivatives Market | 2026-2036
Butadiene Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Butadiene Derivatives Market Outlook
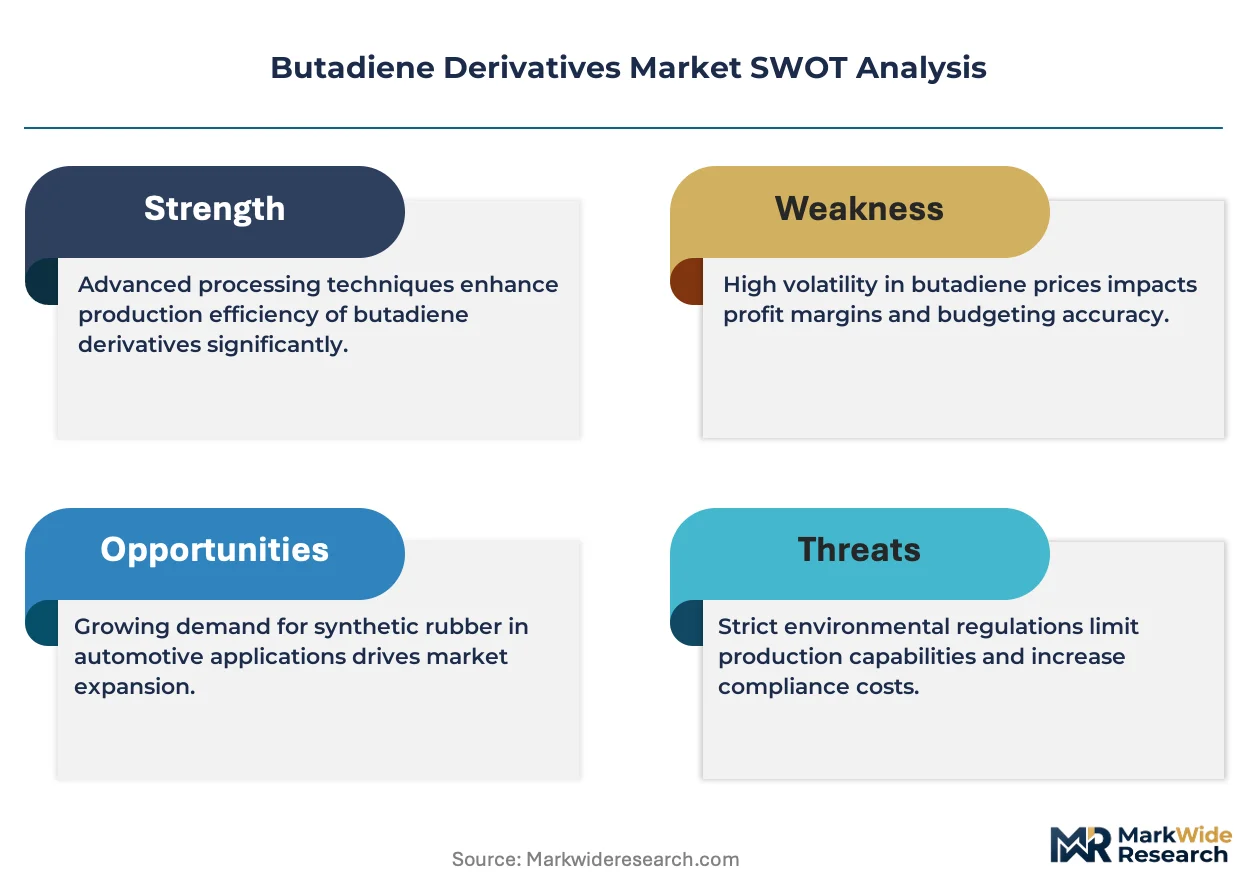
ISO 14001 environmental management certification is redrawing competitive boundaries among butadiene derivative suppliers. LyondellBasell Industries Holdings B.V. leverages its Gulf Coast steam cracker integration to secure feedstock cost advantages. INEOS Group Holdings S.A. anchors European supply through its Cologne-Rhein site, which operates as a critical hub for acrylonitrile butadiene styrene output. China Petrochemical Corporation dominates domestic volume through Sinopec's integrated refining-petrochemical complexes.
Butadiene derivatives comprise synthetic rubbers, engineering thermoplastics, and specialty latexes synthesized via catalytic polymerization of butadiene monomer extracted from C4 hydrocarbon streams. Styrene-butadiene rubber serves as the primary tread compound for passenger and commercial tires, requiring specific Mooney viscosity ranges to balance rolling resistance and wear characteristics. Polybutadiene commands structural priority in high-performance tire formulations where low glass-transition temperature enables enhanced wet grip. Acrylonitrile butadiene styrene concentrates margin pools in electronics housings and automotive interior components demanding Vicat softening points above 100 degrees Celsius.
EPA New Source Performance Standards constrain butadiene fugitive emissions at US production facilities, while REACH Annex XVII restrictions limit residual monomer content in consumer-contact latex applications. China's MEE enforces dual carbon intensity caps that favor derivatives with lower process-energy footprints. Stakeholders must track how evolving tire-labeling regulations in the European Union and emerging GB standards in China redirect formulation specifications across the butadiene derivative value chain.
Market Dynamics
Vehicle electrification is compressing tire-labeling specifications across major automotive supply chains, forcing butadiene derivative producers to recalibrate Mooney viscosity ranges and glass-transition temperature targets for rolling resistance optimization.
Growth Catalysts
- EPA New Source Performance Standards:Fugitive emissions thresholds at US production facilities are accelerating capital deployment toward closed-loop recovery systems and vapor-recapture infrastructure.
- Styrene-butadiene rubber in EV tires:Electric vehicle manufacturers specify lower rolling-resistance compounds, pulling high-viscosity SBR grades into premium tread formulations.
- China's dual carbon intensity caps:MEE enforcement favors derivatives with reduced process-energy footprints, concentrating new capacity in state-backed petrochemical complexes with integrated refining operations.
Market Restraints
- Crude C4 feedstock volatility:Naphtha-cracking economics fluctuate with natural gas liquids pricing, compressing margin visibility for non-integrated butadiene extractors.
- REACH Annex XVII residual monomer limits:Consumer-contact latex applications face restrictive testing protocols that extend qualification timelines for specialty glove and medical-device suppliers.
- Polyurethane foam substitution:Automotive seating and insulation segments are evaluating TPU and microcellular PU alternatives that bypass butadiene-based supply chains entirely.
Strategic Opportunities
- India's PLI scheme for advanced chemistry:Domestic tire manufacturing incentives are attracting butadiene derivative investments to serve ASEAN automotive export corridors.
- Acrylonitrile butadiene styrene in 5G infrastructure:Low-dielectric ABS grades are penetrating base station housing applications as telecom equipment vendors qualify Vicat-softening-point specifications above 105 degrees Celsius.
- EU Green Deal carbon border adjustments:Import tariffs on high-emission chemical feedstocks create first-mover advantages for producers with ISO 14001-certified European assets.
Industry Challenges
- Catalytic polymerization expertise scarcity:Rare-earth neodymium catalyst handling requires specialized process engineering talent that concentrates at legacy Ziegler-Natta research centers.
- REACH SVHC notification timelines:Substance-of-very-high-concern dossier preparation consumes 18-24 months, delaying market entry for novel butadiene copolymer grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butadiene Derivatives Market |
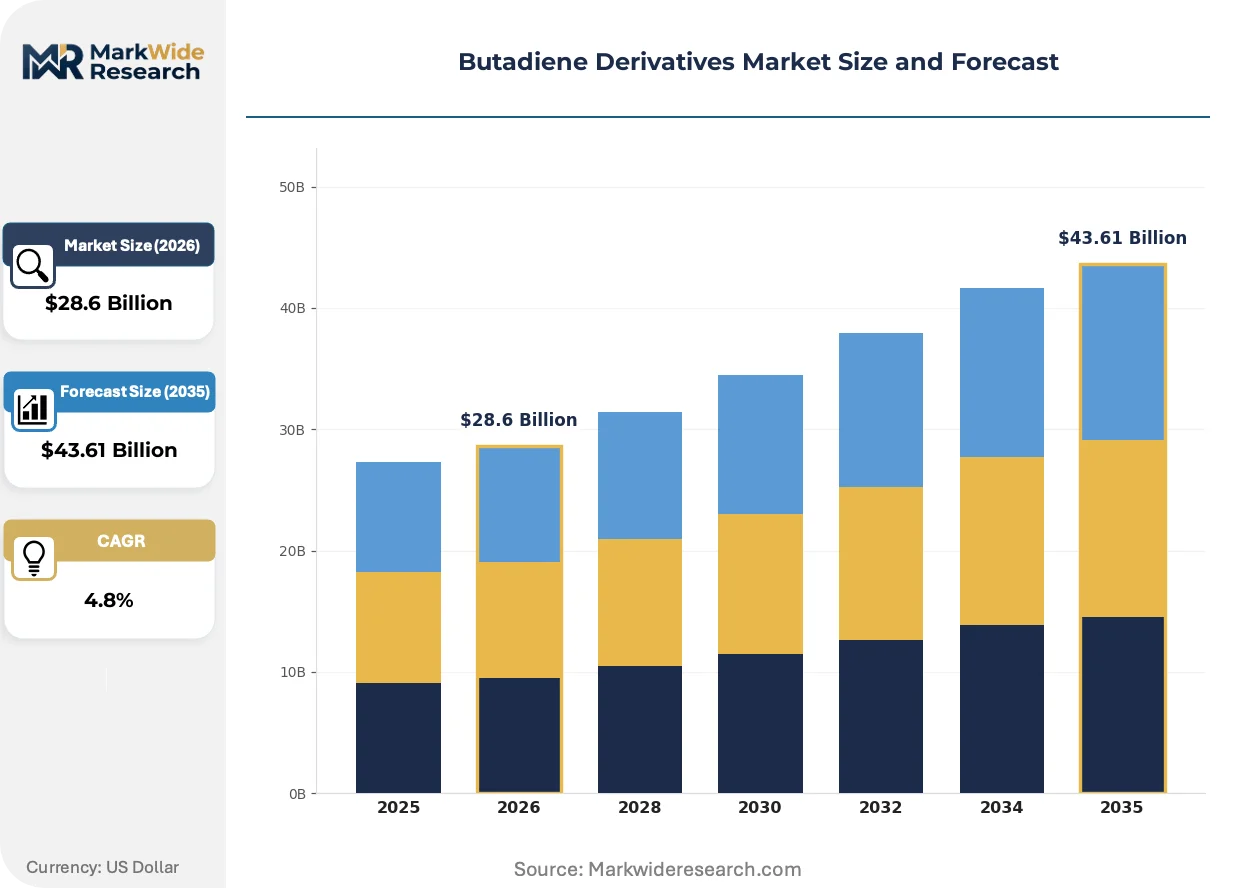
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene-Butadiene Rubber, Acrylonitrile Butadiene Styrene, Polybutadiene, Butadiene Latex Application: Tires, Footwear, Adhesives, Coatings End User: Automotive, Textile, Construction, Electronics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Royal Dutch Shell Plc, LyondellBasell Industries Holdings B.V., INEOS Group Holdings S.A., China Petrochemical Corporation, Exxon Mobil Corporation, BASF SE, TPC Group, Braskem, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butadiene Derivatives Market Strategic Shifts
Bio-based butadiene pathways and advanced catalyst architectures are fragmenting traditional petrochemical process advantages, while regulatory carbon-accounting requirements restructure procurement qualification protocols across tire and electronics supply chains.
Solution polymerization using neodymium-based catalyst systems is decomposing the historical dominance of emulsion SBR in high-performance tire segments. European tire manufacturers are qualifying these grades for original-equipment fitments on premium electric vehicles. The technology is decomposing legacy Ziegler-Natta capacity utilization rates as producers retool for stereospecific polybutadiene with higher cis-1,4 content.
REACH Annex XVII restrictions on residual monomer content in consumer-contact applications are tightening testing burdens for latex-glove and condom manufacturers. Compliance costs are concentrating procurement among integrated producers with in-house polymerization-finish capabilities. Medical-device and personal-care segments are consolidating supplier bases to those with certified low-monomer extraction processes.
Automotive OEMs are unbundling compound formulation specifications from single-source tire-supplier agreements, creating direct qualification relationships with butadiene derivative producers. Tier-1 tire manufacturers face compressed development cycles as vehicle platforms launch with proprietary rolling-resistance targets. This pattern is most pronounced in Germany and South Korea, where OEMs specify Mooney viscosity ranges at the monomer procurement stage.
Butadiene Derivatives Market Segmentation
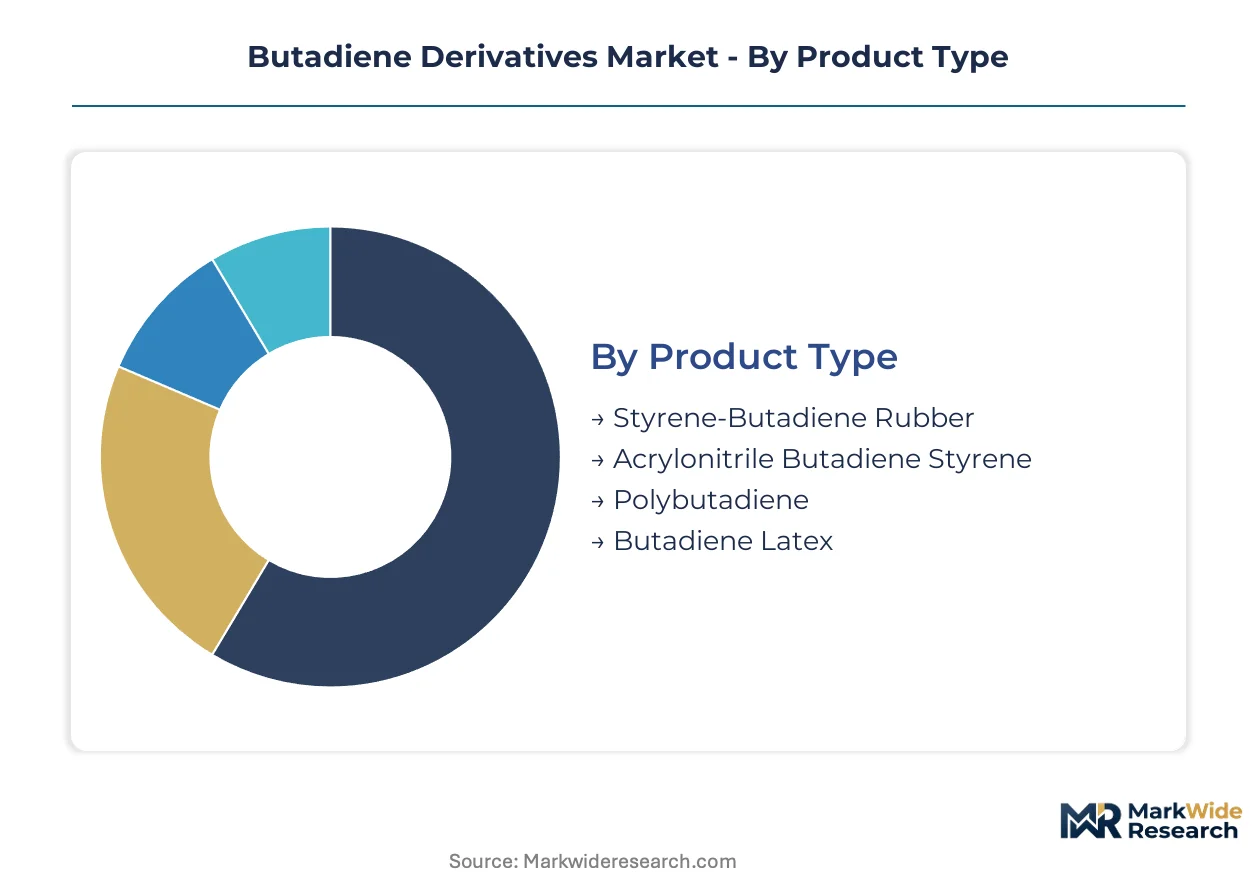
Butadiene derivative specifications fragment across tire-labeling regimes, electronics housing standards, and medical-device biocompatibility protocols. Each segment carries distinct regulatory burdens that reshape procurement qualification timelines and margin structures.
Product Type:
REACH Annex XVII residual monomer thresholds and EPA New Source Performance Standards create divergent compliance cost structures across polymer chemistries.
- Styrene-Butadiene Rubber:Emulsion and solution polymerization grades dominate passenger tire tread formulations. OEMs in Germany and South Korea specify Mooney viscosity ranges at the procurement stage for rolling-resistance optimization in electric vehicle fitments.
- Polybutadiene:High-cis neodymium-catalyzed grades command structural priority in performance tires where low glass-transition temperature enables wet grip. China's state-backed petrochemical complexes are scaling solution-polymerization capacity to serve domestic automotive supply chains.
- Acrylonitrile Butadiene Styrene:Engineering thermoplastic for electronics housings and automotive interior components requiring Vicat softening points above 100 degrees Celsius.
- Butadiene Latex:Specialty grades face REACH testing burdens for residual monomer content in medical gloves and condom applications.
Established volume favors Styrene-Butadiene Rubber; emerging adoption favors Polybutadiene.
Application:
Cost tier differentiation separates commodity compounds from specification-grade formulations qualified for original-equipment supply.
- Tires:Tread, sidewall, and carcass compounds consume the majority of derivative volume. Electric vehicle manufacturers compress development cycles with proprietary rolling-resistance targets that unbundle formulation specifications from single-source supplier agreements.
- Adhesives:Pressure-sensitive and structural formulations for packaging and industrial assembly.
- Footwear:Soling compounds and dipped latex for athletic and industrial boot applications.
- Coatings:Waterborne and solvent-based systems for protective and decorative finishes.
Procurement concentration clusters in Tires; formulation innovation concentrates in Adhesives.
End User:
Customer type determines specification stringency, with automotive OEMs imposing the most aggressive compound qualification protocols.
- Automotive:Tier-1 tire manufacturers and direct OEM relationships drive demand for high-viscosity SBR and stereospecific polybutadiene. Vehicle electrification alters compound specifications across the value chain.
- Electronics:ABS grades with low dielectric constants penetrate 5G base station housing applications as telecom vendors qualify Vicat-softening-point specifications above 105 degrees Celsius.
- Construction:Sealants, membranes, and adhesives for building envelope applications.
- Textile:Carpet backing and fabric coatings utilizing butadiene latex binders.
Volume leadership sits with Automotive; margin expansion concentrates in Electronics.
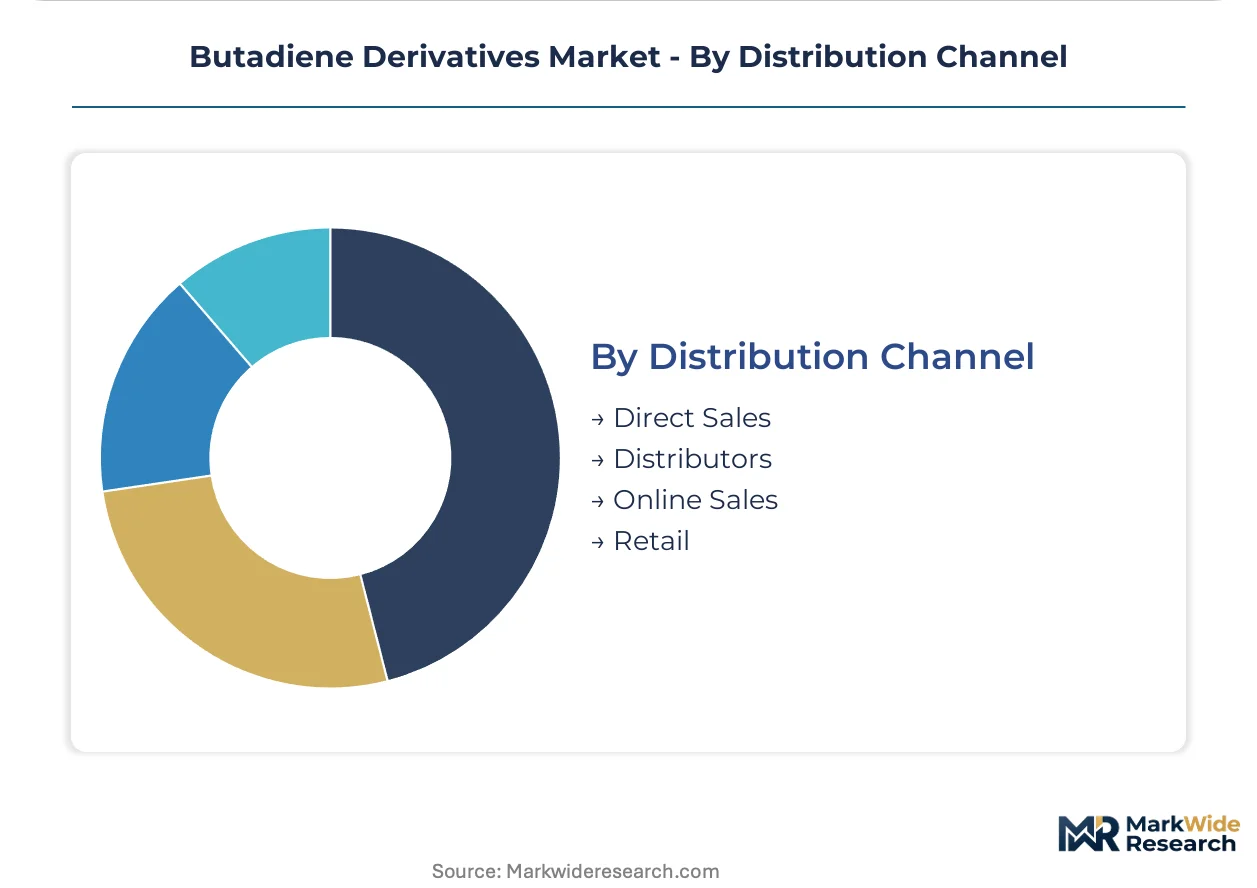
Distribution Channel:
Supply concentration shapes channel selection, with integrated producers favoring direct relationships for specification-grade materials.
- Direct Sales:Long-term contracts with tire manufacturers and automotive OEMs for high-volume SBR and polybutadiene. ISO 14001 certification increasingly filters supplier qualification.
- Distributors:Regional stocking for small-batch specialty latexes and ABS grades serving fragmented end-use segments.
- Online Sales:Emerging channel for standard-grade materials in price-transparent segments.
- Retail:Limited to consumer-facing adhesive and coating products.
Contract value concentrates in Direct Sales; geographic reach expands through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and tire manufacturers concentrate procurement decisions in manufacturing clusters where integrated petrochemical infrastructure meets stringent emissions compliance regimes.
China
Sinopec's refining-petrochemical complexes scale derivative output for domestic EV supply chains. MEE dual carbon intensity caps favor producers with lower process-energy footprints. Ningbo-Zhoushan petrochemical zones attract state-backed capacity expansions serving Southeast Asian automotive export corridors.
United States
Gulf Coast steam cracker integration secures feedstock cost advantages for synthetic rubber producers. EPA New Source Performance Standards constrain fugitive emissions, accelerating capital deployment toward closed-loop recovery systems. Houston Ship Channel infrastructure anchors butadiene extraction and derivative manufacturing.
Germany
Cologne-Rhein chemical parks concentrate acrylonitrile butadiene styrene output for automotive interior and electronics housing applications. REACH Annex XVII residual monomer limits tighten qualification timelines for specialty latex suppliers. KBA tire-labeling enforcement redirects formulation specifications toward lower rolling-resistance compounds.
South Korea
Yeosu and Ulsan industrial complexes host solution-polymerization capacity for high-cis polybutadiene serving premium tire exports. MFDS medical-device regulations extend testing protocols for latex applications. Domestic OEMs specify Mooney viscosity ranges at the monomer procurement stage for EV fitments.
India
PLI scheme incentives for advanced chemistry attract butadiene derivative investments to Gujarat and Maharashtra chemical corridors. BIS standards for automotive components impose Vicat softening point specifications on ABS grades. Dahej and Mundra port infrastructure enables ASEAN market access for tire manufacturing inputs.
Butadiene Derivatives Market Competitive Environment
Player mix skews toward integrated petrochemical conglomerates with captive C4 feedstock supply. Gulf Coast and Yangtze River Delta infrastructure anchors cost-positioned extraction capacity. Three archetypes dominate: state-backed Asian refiners with downstream polymerization assets, European chemical majors with REACH-certified specialty grades, and North American integrated producers with steam cracker economics. Capacity expansion and strategic partnerships represent the dominant competitive vectors as electrification alters compound specifications.
Among European chemical majors, INEOS Group Holdings S.A. and BASF SE exemplify the specialty-grade archetype with certified low-monomer extraction processes. LyondellBasell Industries Holdings B.V. occupies a position among Gulf Coast integrated producers leveraging feedstock cost structures. These three entities represent the competitive spectrum from commodity-scale extraction to specification-grade formulation qualification.
| Leading Market Players |
|---|
| Royal Dutch Shell Plc |
| LyondellBasell Industries Holdings B.V. |
| INEOS Group Holdings S.A. |
| China Petrochemical Corporation |
| Exxon Mobil Corporation |
| BASF SE |
| TPC Group |
| Braskem |
| Dow |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day inventory cycles at Gulf Coast steam crackers translate directly into contract pricing power for integrated butadiene extractors, while non-integrated European processors absorb feedstock volatility through formula-based pass-through mechanisms. This lead-time asymmetry between regions concentrates margin capture among producers with captive C4 supply.
Pricing Analysis
Cost-plus contracts indexed to naphtha-cracker margins dominate long-term offtake agreements between synthetic rubber producers and tire manufacturers. Price differentiation rests on ISO 14001 certification tiers and volume scale commitments, with certified low-monomer grades commanding premiums over standard emulsion SBR. Cost compression in commodity-grade polybutadiene is intensifying because China's state-backed complexes are flooding ASEAN export corridors. Tier-2 tire manufacturers in India exhibit the highest price sensitivity, while German OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Houston Ship Channel throughput constraints periodically disrupt C4 fractionation schedules for Gulf Coast derivative producers. Supply concentrates in the United States, China, and Germany, with feedstock drawn from naphtha crackers, ethylene co-production streams, and dehydrogenation units. The chain rests on crude C4 availability, neodymium catalyst supply, and specialized polymerization-finish equipment. Single-source vulnerability runs through rare-earth catalyst channels from Chinese separation facilities. Distribution runs through direct sales contracts for high-volume tire grades and regional distributors for specialty latex batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story because REACH compliance timelines and OEM qualification protocols create switching costs that entrench incumbent positions for decades.
For Market Incumbents: Secure backward integration into C4 extraction assets to defend against naphtha-margin volatility, while accelerating ISO 14001 certification across European latex finish lines to exploit carbon border adjustment advantages. Polyurethane foam substitution in automotive seating represents the most pressing substitute threat. Capacity addition in India's Gujarat chemical corridor offers geographic diversification against Chinese oversupply. For New Entrants and Emerging Players: Technical service gaps in neodymium-catalyzed polybutadiene qualification support white-space entry, as legacy producers under-serve mid-tier tire manufacturers seeking high-cis grades without minimum volume commitments. India's PLI-attracted tire manufacturing clusters present the most penetrable geography. A co-development partnership with domestic automotive OEMs for EV-specific rolling-resistance compounds offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because emissions compliance and certification burdens continuously raise barriers against commodity entrants. Acquisition targets should display integrated refining-petrochemical assets with established OEM qualification relationships. The signal to watch is KBA tire-labeling enforcement stringency, as tightening rolling-resistance thresholds accelerate formulation turnover and concentrate procurement among specification-capable suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Extraction | Captive feedstock supply insulates margin structures from naphtha-cracking volatility in Gulf Coast operations. |
| Neodymium Catalyst Capacity Expansion | Solution-polymerization scale-up captures premium tire segment migration away from emulsion SBR grades. |
| REACH-Certified Low-Monomer Finish Lines | Annex XVII compliance enables medical-device and personal-care latex procurement consolidation. |
| Joint Venture in India PLI Corridors | Gujarat and Maharashtra positioning serves ASEAN automotive export demand with tariff-advantaged supply. |
| Long-term Supply Agreement with EV OEMs | Direct qualification relationships bypass Tier-1 tire manufacturer formulation control in Germany and South Korea. |
Study Parameters
Initial hypotheses were tested against primary input from petrochemical plant managers, tire manufacturer procurement leads, automotive OEM platform engineers, and specialty latex distribution channel partners, and refined through secondary validation across customs trade data, ACC and Cefic industry reports, EPA emissions filings, and SEC 10-K disclosures from integrated chemical majors. Bottom-up volume builds across polymerization grades were triangulated against top-down demand estimates from tire production databases and automotive platform forecasts.
Variance in projected outcomes was decomposed across the analysis window by modeling volume and value outputs through segmentation dimensions including polymer chemistry grade, end-use industry application, regional production hub configuration, and certification tier. CAGRs were derived from regression-weighted historical trend extrapolation adjusted for regulatory phase-in schedules and OEM platform launch cadences. Forecast inputs incorporated naphtha-cracking economics, electric vehicle penetration curves, and dual carbon intensity enforcement trajectories.
Forecasts assume regulatory continuity in REACH Annex XVII enforcement, EPA New Source Performance Standards, and China's MEE dual carbon caps; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as tire-labeling regime stringency and bio-based butadiene pathway economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Thiochemicals Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Phosphate Chemical Reagents Market