
 Asia-Pacific Silica Sol Market | 2026-2036
Asia-Pacific Silica Sol Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Silica Sol Market Insights
High-purity semiconductor-grade silica sol is rotating toward the center of supplier strategies across the Asia-Pacific. Nissan Chemical Corporation leverages its integrated colloidal silica synthesis platform to dominate electronics polishing applications in Japan and Taiwan. FUSO CHEMICAL Co., Ltd anchors its position through captive control over sodium silicate feedstock and proprietary particle-size modulation technology. Evonik Industries AG competes on functionalized silica variants tailored to adhesives and coatings formulations in South Korea and Southeast Asia.
Silica sol denotes a stable dispersion of amorphous silicon dioxide nanoparticles in aqueous medium, typically ranging from 5 to 100 nanometers in particle diameter and stabilized by surface charge or steric mechanisms; manufacturers produce it via ion-exchange or peptization of alkali silicate solutions for applications spanning surface polishing, binder systems, and catalyst supports. Colloidal silica leads product-type revenue due to its ubiquity in electronics planarization, while functionalized silica captures the fastest expansion as automotive and healthcare end users demand surface-modified particles for enhanced adhesion and biocompatibility. The coatings application segment sits at maturity in Japan and Australia, whereas electronics and ceramics drive incremental volume in China and Vietnam.
China's MIIT enforces GB standards on nanomaterial purity and environmental discharge, tightening market access for imported silica sol with elevated heavy-metal content. Japan's METI and South Korea's MFDS both classify colloidal silica for semiconductor applications under specialized chemical substance frameworks, creating dual compliance burdens for regional suppliers. India's BIS certification requirements for construction-grade binders further fragment product specifications across the region. Stakeholders must monitor divergence between Chinese GB standards and Japanese JIS specifications when configuring regional manufacturing footprints.
Market Dynamics
Water-based colloidal silica systems are displacing solvent-based alternatives across Asia-Pacific manufacturing clusters, driven by Japan's METI circular economy mandates and tightening discharge protocols in China's Jiangsu industrial corridor.
Growth Catalysts
- Semiconductor planarization demand:Electronics manufacturers in Taiwan and South Korea are scaling silica sol consumption for chemical mechanical polishing of advanced node wafers.
- GB standard alignment:China's MIIT nanomaterial purity requirements are consolidating domestic supply chains and accelerating import substitution for high-purity grades.
- Precision casting expansion:Foundries across Shandong province are adopting silica sol binders for turbine blade investment casting to serve aerospace OEMs.
Market Restraints
- Sodium silicate feedstock volatility:Energy-intensive production of alkali silicate precursors exposes margin structures to natural gas price swings in East Asian manufacturing hubs.
- Dual compliance burdens:Suppliers face divergent JIS and GB certification requirements for semiconductor-grade material, fragmenting regional production footprints.
- Alumina sol substitution:Refractory applications in Vietnam are partially migrating to alumina-based binders where thermal shock resistance exceeds silica sol performance.
Strategic Opportunities
- Vietnam electronics assembly:Emerging semiconductor packaging and display manufacturing clusters in Bac Ninh province offer untapped demand for polishing-grade colloidal silica.
- Functionalized silica convergence:Surface-modified particles combining silane coupling with controlled particle size are opening automotive adhesive applications in South Korea.
- India PLI scheme leverage:Production-linked incentives for electronics manufacturing are drawing silica sol suppliers toward Gujarat and Tamil Nadu special economic zones.
Industry Challenges
- Particle size modulation expertise:Narrowing diameter distributions below 10 nanometers for semiconductor applications requires scarce process engineering talent concentrated in Japan and Taiwan.
- Cross-border certification timelines:BIS registration for construction-grade binders in India extends commercialization cycles by 12-18 months relative to domestic competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Silica Sol Market |
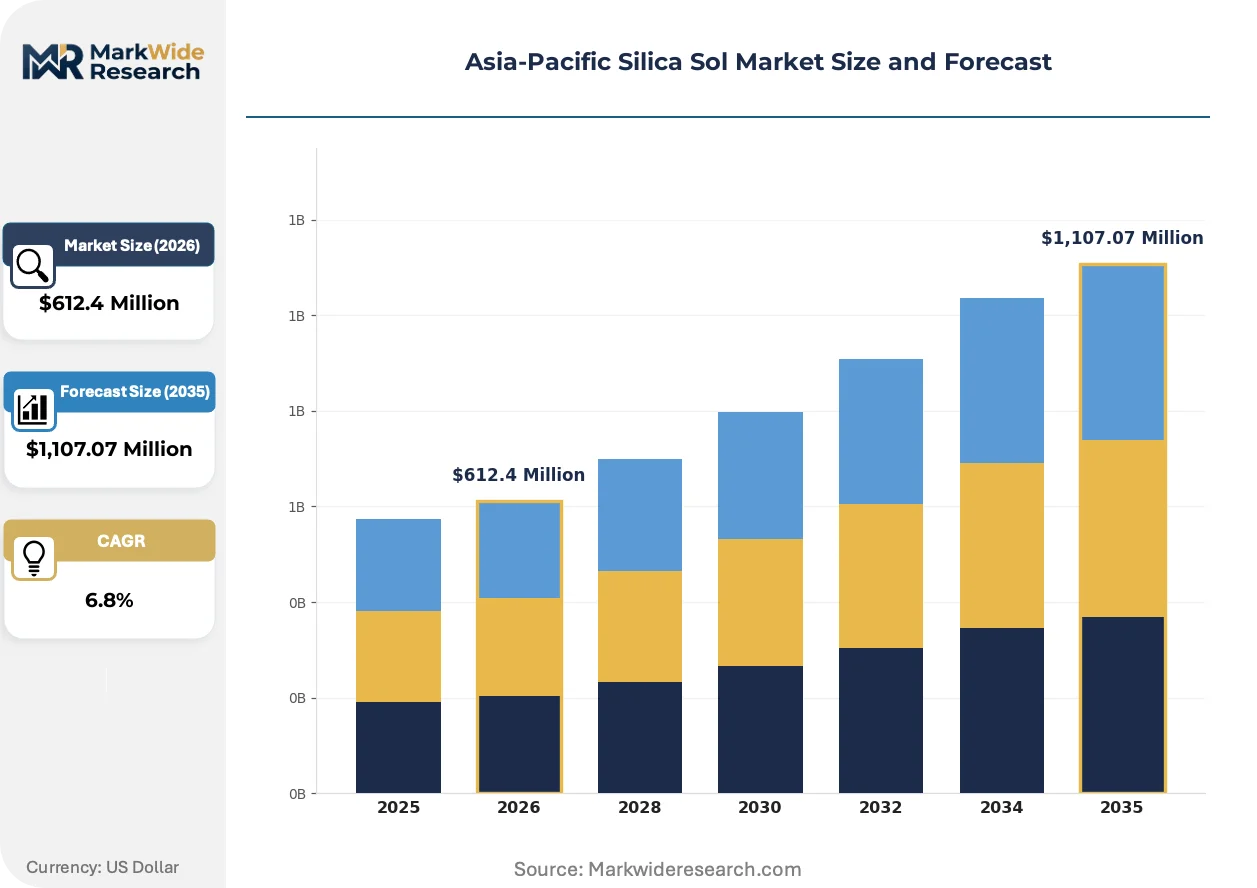
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colloidal Silica, Acid-Modified Silica, Alkali-Modified Silica, Functionalized Silica Application: Coatings, Adhesives, Electronics, Ceramics End User: Automotive, Construction, Healthcare, Consumer Goods Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Nissan Chemical Corporation, W. R. Grace & Co., Evonik Industries AG, Ecolab, Nouryon, FUSO CHEMICAL Co., Ltd, Cabot Corporation, Merck KGaA, Qingdao FSK Foundry Materials CO., LTD., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Silica Sol Market Trends and Innovations
Particle surface engineering and aqueous stabilization chemistry are redefining performance benchmarks across electronics, healthcare, and advanced materials applications in the Asia-Pacific silica sol landscape.
Monodisperse colloidal silica with sub-20 nanometer particle distributions is supplanting polydisperse alternatives in chemical mechanical polishing slurries. Memory and logic chip fabricators in Hsinchu and Pyeongtaek are transitioning to narrow-distribution grades to reduce defect densities on 3nm-class wafers. This shift is compressing margins for suppliers lacking precision ion-exchange synthesis capabilities.
METI's 2024 amendments to chemical substance reporting frameworks are reclassifying functionalized silica for medical device coatings under specialized handling protocols. Manufacturers must now submit particle characterization data beyond standard purity metrics to PMDA-equivalent review bodies. Electronics-grade suppliers in Osaka and Nagoya are responding by segregating semiconductor and healthcare production lines to isolate compliance costs.
Direct procurement contracts between silica sol producers and semiconductor foundries are displacing distributor-mediated supply in South Korea and Taiwan. Samsung and TSMC-affiliated buyers are negotiating multi-year offtake agreements with volume commitments and technical co-development clauses. This channel consolidation is most pronounced in Gyeonggi province, where three foundries now account for the majority of high-purity silica sol consumption.
Asia-Pacific Silica Sol Market Segmentation
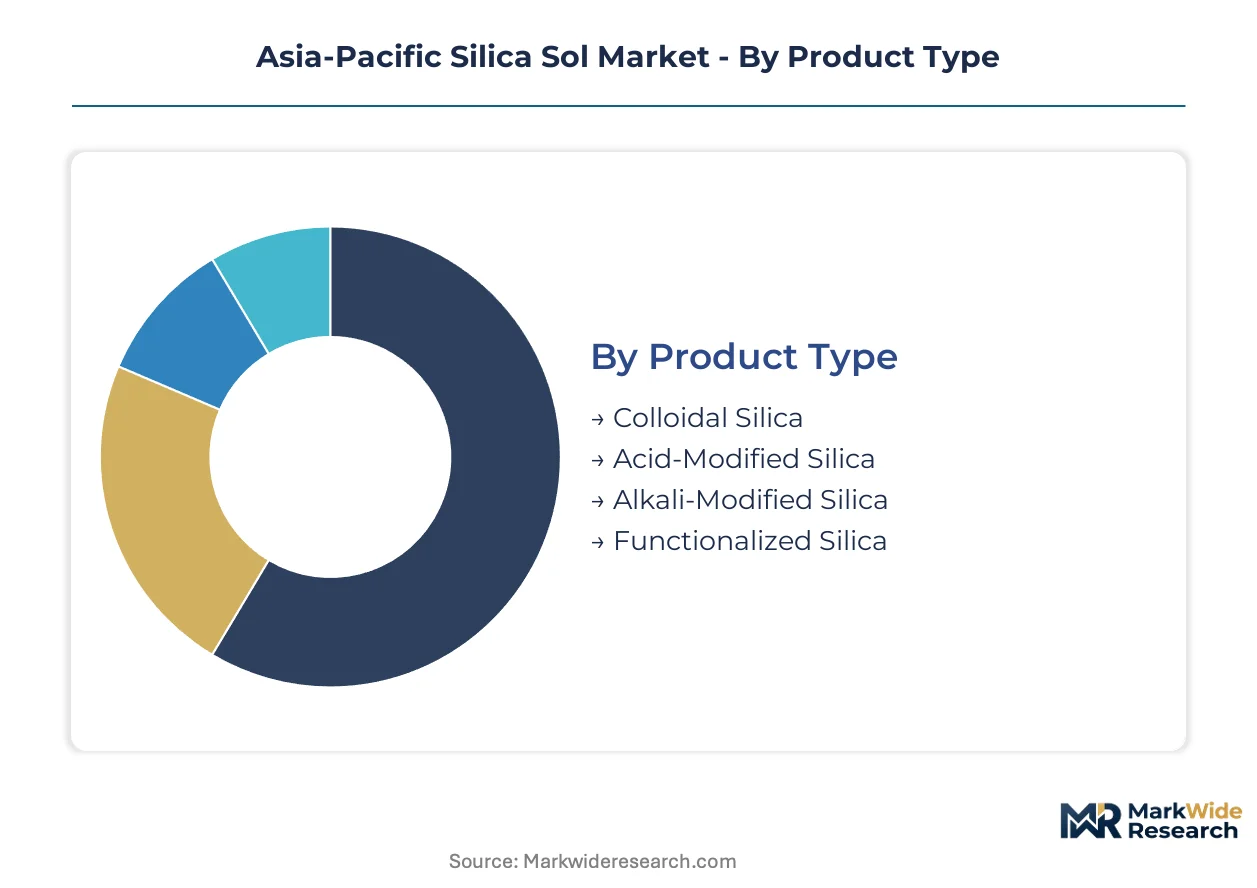
Silica sol suppliers configure product portfolios around purity gradients and surface chemistry specifications that align with distinct compliance burdens across semiconductor, medical, and industrial end uses. Segmentation strategy determines which grades capture premium pricing versus volume turnover in fragmented Asia-Pacific demand clusters.
Product Type:
Acid-modified and alkali-modified variants face the most acute substitution pressure from alumina sol and zirconia-based binders in refractory applications where thermal performance thresholds exceed silica limits.
- Colloidal Silica:Stable aqueous dispersion of amorphous SiO₂ nanoparticles, typically 5-100 nanometers, stabilized by surface charge. Demand concentrates in Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek semiconductor clusters for chemical mechanical polishing of advanced node wafers, driven by foundry scaling for 3nm-class production.
- Functionalized Silica:Surface-modified particles incorporating silane coupling agents or organic functional groups for enhanced adhesion and biocompatibility. Automotive adhesive formulators in South Korea's Gyeonggi province and medical device coaters in Japan's Osaka medical technology corridor are the primary demand anchors, with METI's circular economy mandates accelerating water-based system adoption.
- Acid-Modified Silica:pH-adjusted colloidal dispersion optimized for acidic binder environments. Precision foundries in China's Shandong province specify this grade for turbine blade investment casting.
- Alkali-Modified Silica:Stabilized alkaline formulation for refractory and construction applications. Vietnam's refractory manufacturers are partially migrating to alumina alternatives where thermal shock resistance requirements exceed silica performance.
Colloidal silica anchors the volume base while functionalized silica gains share at the steepest rate.
Application:
Cost tier stratification separates electronics-grade material commanding technical co-development contracts from mature coatings segments where distributor mediation still dominates.
- Electronics:Chemical mechanical polishing slurries for wafer planarization requiring sub-20 nanometer monodisperse particle distributions. Samsung and TSMC-affiliated buyers in South Korea and Taiwan are negotiating multi-year direct procurement contracts with volume commitments, displacing traditional distributor channels.
- Coatings:Surface finishing and protective layer applications spanning industrial and consumer goods. Japan and Australia represent mature demand centers with established supply relationships and limited growth headroom.
- Adhesives:Binder systems for automotive and industrial assembly. South Korean automotive OEMs are specifying surface-modified silica for structural adhesive formulations to meet lightweighting targets.
- Ceramics:Refractory binder and advanced ceramic processing aid. China's Jiangsu and Shandong ceramics clusters source high-purity grades, though Vietnam's refractory sector is testing alumina sol substitution.
Electronics applications command the steepest price premiums while coatings provide the most predictable volume throughput.
End User:
Customer type fragmentation creates divergent certification timelines, with healthcare and automotive segments imposing the longest qualification cycles.
- Automotive:Structural adhesives, sealants, and surface treatment formulations. South Korean and Japanese OEMs are integrating silica sol into lightweight vehicle assembly processes.
- Construction:Cement modification, concrete densification, and refractory binders. India's BIS certification requirements for construction-grade material extend commercialization cycles.
- Healthcare:Medical device coatings and pharmaceutical processing aids. Japan's METI and PMDA-equivalent review bodies now require particle characterization data beyond standard purity metrics for functionalized silica used in implantable devices.
- Consumer Goods:Personal care, food processing, and household product applications. This segment exhibits the lowest technical barriers and highest price sensitivity.
Automotive and healthcare end users impose the most stringent qualification protocols while construction delivers the highest volume absorption.
Distribution Channel:
Supply concentration in East Asian manufacturing hubs shapes channel strategy, with direct engagement favored where technical specification and volume scale align.
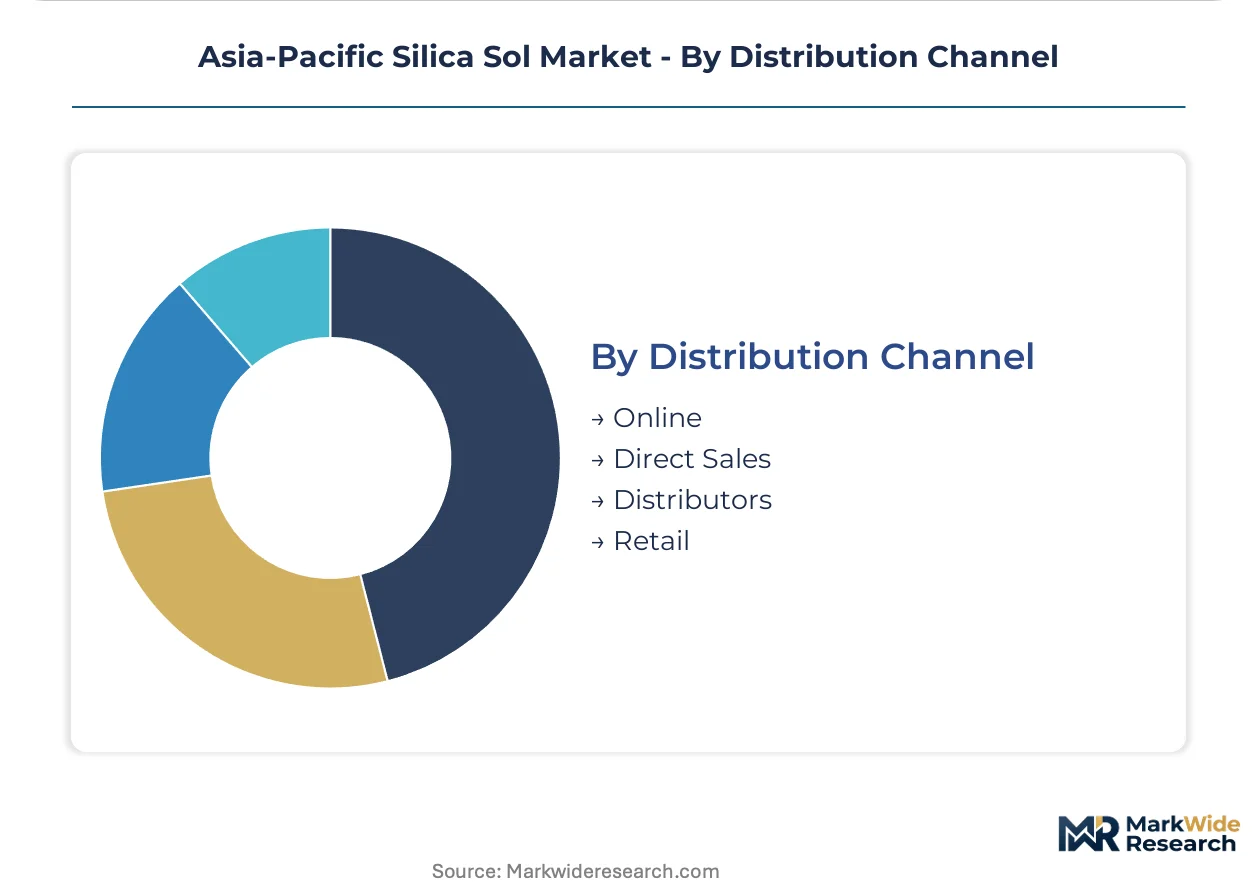
- Direct Sales:Long-term offtake agreements between silica sol producers and semiconductor foundries. This channel dominates high-purity electronics-grade transactions in South Korea and Taiwan.
- Distributors:Regional chemical distributors serving fragmented industrial and coatings demand. Still prevalent in Southeast Asian emerging markets and mature Japanese coatings segments.
- Online:E-procurement platforms for standardized grades and small-volume orders. Growing penetration in India's Gujarat and Tamil Nadu special economic zones.
- Retail:Limited to consumer-grade and small-package industrial formulations. Minimal relevance for bulk industrial silica sol.
Direct sales capture the highest value transactions while distributor networks retain relevance in geographically dispersed demand pockets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific silica sol trade flows reflect a pronounced import dependency for semiconductor-grade material, with high-purity volumes moving from Japan and South Korea toward Chinese foundries while construction-grade product circulates within ASEAN free-trade corridors.
China
Foundries in Shandong and Jiangsu provinces drive silica sol consumption for precision investment casting of turbine blades and medical implants. MIIT enforces GB standards on nanomaterial purity and environmental discharge, tightening market access for imported material with elevated heavy-metal content. The Yangtze River Delta electronics cluster sources high-purity grades for semiconductor polishing applications.
Japan
Electronics polishing applications in Hsinchu and domestic memory chip fabrication anchor colloidal silica demand. METI circular economy mandates push manufacturers toward water-based colloidal silica systems, reclassifying functionalized silica for medical device coatings under specialized handling protocols. Osaka and Nagoya production lines now segregate semiconductor and healthcare grades to isolate compliance costs.
South Korea
Samsung and TSMC-affiliated buyers in Gyeonggi province negotiate multi-year direct procurement contracts with volume commitments and technical co-development clauses. MFDS classifies colloidal silica for semiconductor applications under specialized chemical substance frameworks, creating dual compliance burdens for regional suppliers. Pyeongtaek foundries scale consumption for chemical mechanical polishing of advanced node wafers.
India
Production-linked incentives for electronics manufacturing draw silica sol suppliers toward Gujarat and Tamil Nadu special economic zones. BIS certification requirements for construction-grade binders extend commercialization cycles by 12-18 months relative to domestic competitors. Foundries across the industrial corridor expand silica sol adoption for precision investment casting.
Vietnam
Emerging semiconductor packaging and display manufacturing clusters in Bac Ninh province offer untapped demand for polishing-grade colloidal silica. Refractory applications partially migrate to alumina-based binders where thermal shock resistance exceeds silica sol performance. The northern industrial zone attracts regional suppliers seeking ASEAN market access.
Asia-Pacific Silica Sol Market Competitive Landscape
Concentration sits with integrated chemical conglomerates possessing captive sodium silicate feedstock and proprietary particle-size modulation capabilities. Japanese and German specialists dominate high-purity electronics grades through precision ion-exchange synthesis platforms, while regional Chinese manufacturers capture construction and foundry volume through cost-optimized alkali-modified formulations. Three archetypes define competitive positioning: integrated silicate producers, functionalization specialists, and regional volume fabricators. Capacity expansion and backward integration into sodium silicate precursors represent the dominant competitive moves across East Asian manufacturing hubs.
Within the integrated silicate tier, Nissan Chemical Corporation and FUSO CHEMICAL Co., Ltd exemplify archetypes combining feedstock control with electronics-grade purification capabilities. Evonik Industries AG occupies a position among functionalization specialists serving adhesives and coatings formulations. These three entities represent the spectrum from captive raw material security to surface chemistry differentiation in a market where particle size modulation expertise concentrates in Japan and Taiwan.
| Leading Market Players |
|---|
| Nissan Chemical Corporation |
| W. R. Grace & Co. |
| Evonik Industries AG |
| Ecolab |
| Nouryon |
| FUSO CHEMICAL Co., Ltd |
| Cabot Corporation |
| Merck KGaA |
| Qingdao FSK Foundry Materials CO., LTD. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates above 85% at Japanese and South Korean ion-exchange synthesis facilities create asymmetric pricing power for semiconductor-grade material, compressing margin structures for second-tier suppliers lacking backward integration into sodium silicate feedstock. This concentration dynamic forces buyers in China's Yangtze River Delta to absorb premium differentials or accept extended lead times for GB-certified high-purity grades.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across the Asia-Pacific silica sol landscape. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade monodisperse material from construction-grade alkali-modified formulations. Cost compression in standard-tier electronics applications is intensifying because Samsung and TSMC-affiliated buyers are consolidating procurement through direct multi-year agreements. Construction-grade buyers in India's BIS-regulated market exhibit the highest price sensitivity, while semiconductor foundries in Gyeonggi province accept technical co-development premiums.
Supply Chain Analysis
Strait of Malacca transit routes underpin raw material flows for sodium silicate precursors moving from Chinese alkali silicate producers toward Japanese and South Korean purification facilities. Supply concentration rests on China for feedstock chemicals, Japan for precision ion-exchange synthesis equipment, and South Korea for semiconductor-grade packaging. Single-source vulnerability concentrates in Japanese particle-size modulation technology providers. Distribution runs through direct procurement channels for electronics-grade material and regional chemical distributors for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific silica sol market is experiencing high-growth disruption as Japan's METI circular economy mandates reclassify functionalized silica under specialized handling protocols, creating compliance-driven supplier consolidation.
For Market Incumbents: Compound captive control over sodium silicate precursors with segregated production lines for semiconductor and healthcare grades to isolate METI/PMDA-equivalent compliance costs. Alumina sol substitution in Vietnam refractory applications threatens volume erosion; counter with thermal shock resistance co-development programs for aerospace turbine blade casters in Shandong province. For New Entrants and Emerging Players: BIS certification fast-tracks for construction-grade binders in Gujarat and Tamil Nadu special economic zones unlock 12-18 month commercialization advantages over import-dependent competitors. Target India's PLI-scheme electronics manufacturing corridor with polishing-grade colloidal silica for emerging semiconductor packaging clusters. Lead with e-procurement platform partnerships to bypass entrenched distributor relationships in Southeast Asian emerging markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated silicate producers possessing both feedstock security and sub-20 nanometer particle distribution capabilities. Long-term viability over a 5-10 year window hinges on qualification timelines for healthcare-grade functionalized silica as METI reporting frameworks tighten. Watch for direct procurement contract announcements from Samsung and TSMC-affiliated buyers as inflection indicators for channel consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply buffers margin structures against natural gas price volatility in East Asian manufacturing hubs. |
| Segregated Production Line Investment | Isolated semiconductor and healthcare manufacturing streams reduce cross-contamination risks under METI reclassification protocols. |
| Direct Procurement Contract Negotiation | Multi-year offtake agreements with Samsung and TSMC-affiliated buyers displace distributor-mediated supply in Gyeonggi province. |
| GB Standard Certification Alignment | MIIT nanomaterial purity compliance accelerates import substitution opportunities for domestic Chinese suppliers. |
| Particle Surface Engineering R&D | Silane coupling and controlled particle size convergence opens automotive adhesive applications in South Korea's lightweighting push. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at colloidal silica synthesis facilities, procurement leads at semiconductor foundries, and technical R&D directors at functionalized silica formulators; and secondary validation through customs/trade data, SEC 10-K filings from integrated chemical conglomerates, and MIIT/GB standard documentation. Bottom-up volume modeling across product type, application, and end user segments was triangulated against top-down industry revenue estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including grade tier (semiconductor versus industrial purity), end-use industry (electronics, automotive, healthcare, construction), and regional production hub concentration. CAGRs were derived from weighted average growth contributions across these segments, incorporating foundry capacity expansion schedules in Taiwan and South Korea, and METI regulatory implementation timelines for medical device coating applications.
Decision-makers should treat outputs as directional under base assumptions of sustained semiconductor planarization demand and stable sodium silicate feedstock availability; material deviation in natural gas pricing or foundry capital expenditure cycles would warrant model refresh. Practitioners should keep alternative scenarios live as alumina sol substitution rates in Vietnam refractories and India PLI scheme electronics manufacturing uptake evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Drum Melters Market
Industrial Chemicals
Biobased Degreaser Market