
 Adblue Market | 2026-2036
Adblue Market Size, Share, and Industry Trends Forecast 2026-2036
Adblue Market Intelligence
Margin capture from bulk liquid distribution is narrowing as fleet operators shift to on-site blending and packaged fluid solutions. Yara International ASA leverages its extensive global production and distribution network to maintain scale advantages. BASF SE differentiates through high-purity grades required for sensitive SCR catalysts in newer vehicle models. Meanwhile, Shell plc expands its retail presence at gas stations, targeting light commercial vehicle and passenger car segments.
Adblue is a non-toxic aqueous urea solution, specifically formulated with 32.5% high-purity urea and 67.5% deionized water. It functions as a reducing agent in selective catalytic reduction (SCR) systems to convert harmful nitrogen oxides (NOx) from diesel engine exhaust into nitrogen and water. Heavy-duty trucks represent the largest application segment due to widespread SCR system adoption in commercial transport. Packaged fluid formats show accelerated demand over bulk supply, driven by convenience for smaller fleets and agricultural machinery operators.
Emissions mandates are the primary market driver, with frameworks like the EPA's Clean Air Act in the United States and Euro 6/7 standards in Europe setting strict NOx limits. Similarly, China's VI and India's Bharat Stage VI (BS-VI) regulations compel the use of SCR technology in new diesel vehicles. Future market direction hinges on the enforcement of these standards in off-road applications and the development of next-generation after-treatment systems.
Market Dynamics
The compulsory adoption of selective catalytic reduction (SCR) technology, driven by stringent government emissions mandates, is the central force shaping the Adblue market. Regulations like Europe's Euro 6 and China's VI standards directly create non-discretionary demand for this diesel exhaust fluid.
Growth Catalysts
- Expanding Regulatory Scope:The extension of NOx emission limits to non-road mobile machinery (NRMM) and agricultural equipment under frameworks like the EU's Stage V forces SCR adoption in new vehicle categories, creating incremental demand.
- Heavy-Duty Freight Sector:The global logistics and freight industry's continued reliance on diesel-powered heavy-duty trucks for long-haul transport sustains a large, foundational demand base for Adblue, particularly along major transport corridors.
- New Market Implementation:The enforcement of standards such as Bharat Stage VI (BS-VI) in India has rapidly converted a substantial portion of the country's massive commercial vehicle fleet into a major new consumption market.
Market Restraints
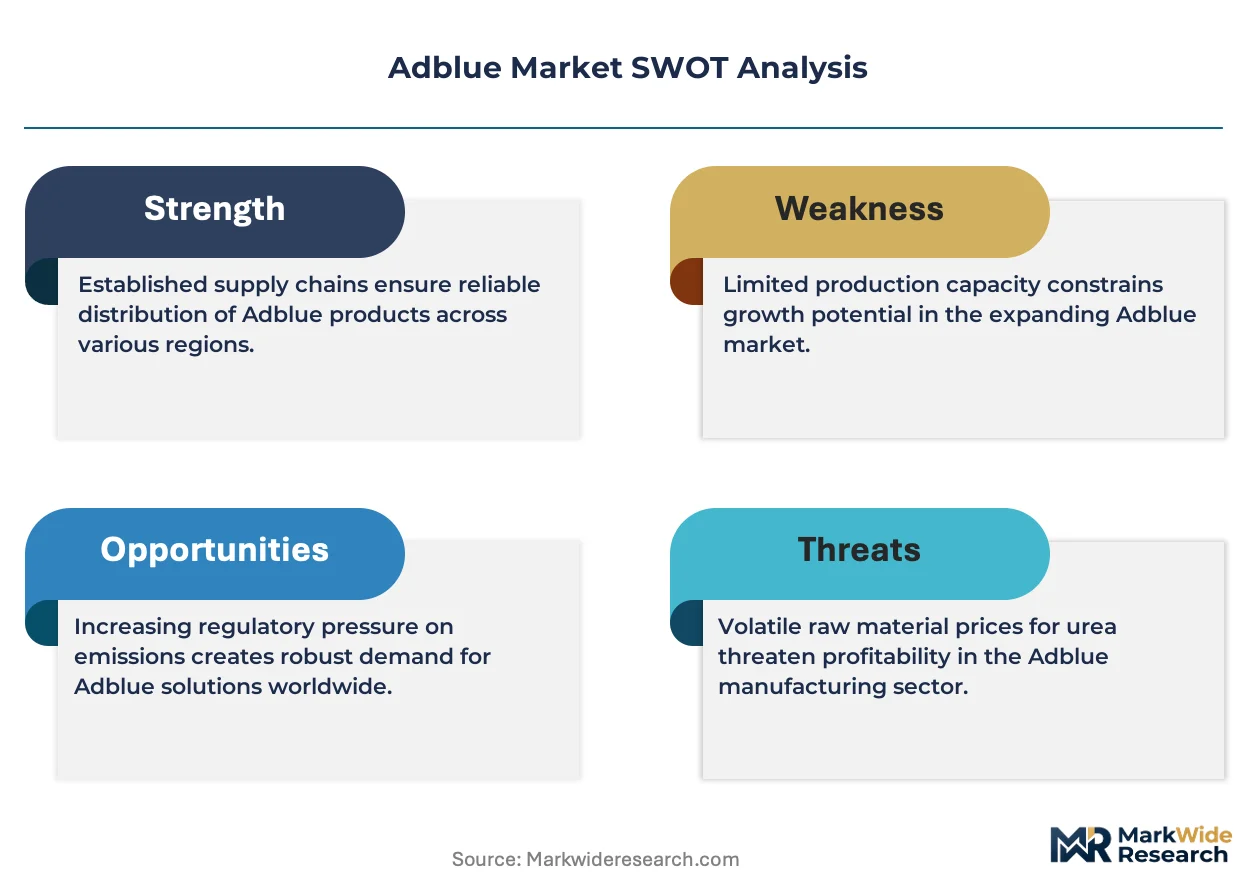
- Urea Price Volatility:As the primary raw material, the price of high-purity urea is subject to fluctuations based on agricultural demand and natural gas costs, creating margin pressure and cost uncertainty for Adblue producers.
- Electrification Threat:The long-term transition to battery-electric and hydrogen fuel-cell commercial vehicles, particularly in last-mile delivery and regional haulage segments, represents a direct substitution threat that will eventually erode the diesel engine fleet.
- Contamination Risks:The effectiveness of SCR systems is highly sensitive to Adblue purity. Contamination with minerals or other impurities can lead to costly catalyst failure, creating a barrier for low-quality or informal producers.
Strategic Opportunities
- Marine Sector Application:Stricter International Maritime Organization (IMO) regulations on NOx emissions from marine diesel engines are creating an emerging opportunity for urea-based solutions in the shipping industry, particularly for vessels operating in Emission Control Areas.
- Smart Dispensing Systems:Developing and deploying integrated telemetry and automated refilling solutions for on-site storage tanks at fleet depots offers a value-added service that enhances customer retention and optimizes logistics.
- South American Market Entry:As countries like Brazil and Argentina progressively adopt stricter, Euro-equivalent emission standards for commercial vehicles, these regions represent significant untapped markets for Adblue production and distribution.
Industry Challenges
- Quality Assurance at Scale:Ensuring the precise 32.5% urea concentration and deionized water purity across millions of liters in a complex supply chain, including on-site blending, presents a significant operational quality control challenge.
- Temperature-Sensitive Logistics:Adblue's freezing point requires specialized, often heated, storage and transport infrastructure, adding cost and complexity to distribution networks, especially in colder climates found in Canada and Northern Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adblue Market |
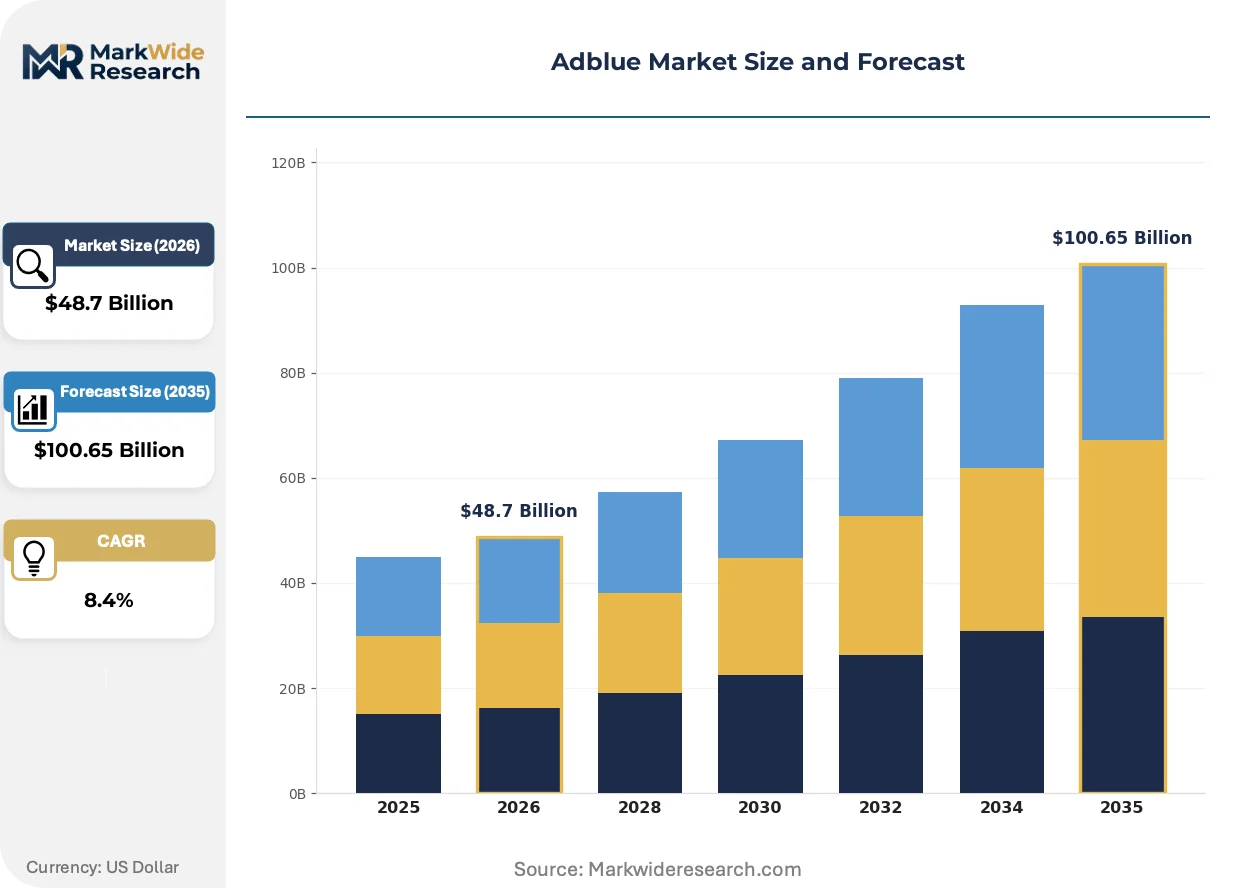
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Solution, Ready-to-Use, Bulk Liquid, Packaged Fluid Application: Heavy-Duty Trucks, Light Commercial Vehicles, Agricultural Machinery, Construction Equipment End User: Fleet Operators, Equipment Rental Companies, Logistics Providers, Agricultural Enterprises Distribution Channel: Direct Sales, Online Retail, Automotive Dealerships, Gas Stations |
| Companies Covered | BASF SE, Yara International ASA, Shell plc, CF Industries Holdings, Inc., TotalEnergies SE, GreenChem Holding B.V., Mitsui Chemicals, Inc., Nissan Chemical Corporation, Sinopec Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adblue Market Strategic Shifts & Innovations
Operational efficiency and service integration are becoming key differentiators as the market matures beyond simple compliance. The focus is shifting toward purity assurance, supply chain optimization, and integrated fluid management to support increasingly sensitive after-treatment hardware.
Automated fluid management systems are gaining traction as a key technological evolution. These systems use sensors in on-site storage tanks to monitor Adblue levels and automatically trigger replenishment orders. Large logistics fleet operators and commercial fueling depots are the primary adopters, seeking to minimize vehicle downtime and reduce manual labor. The market for Adblue supply is migrating from simple bulk delivery contracts to integrated service solutions that provide greater value and customer lock-in.
Upcoming emissions regulations, particularly the proposed Euro 7 standards in Europe, are setting a new bar for after-treatment system performance. These rules will likely require more sophisticated on-board diagnostics (OBD) to monitor reductant quality in real time. The heavy-duty and light-duty diesel vehicle segments are most impacted, compelling manufacturers to design SCR systems that are intolerant of off-spec fluid, thereby reinforcing demand for certified, high-purity Adblue.
A bifurcation in purchasing behavior is segmenting the demand side. While large commercial fleets pursue cost advantages through bulk deliveries or on-site blending, smaller fleet operators, agricultural users, and individual passenger car owners prefer pre-packaged formats. This demand for convenient, sealed containers ensures fluid purity and simplifies handling. This pattern is particularly pronounced in the developed markets of North America and Western Europe, requiring distinct channel strategies for retail and bulk distribution.
Adblue Market Segmentation
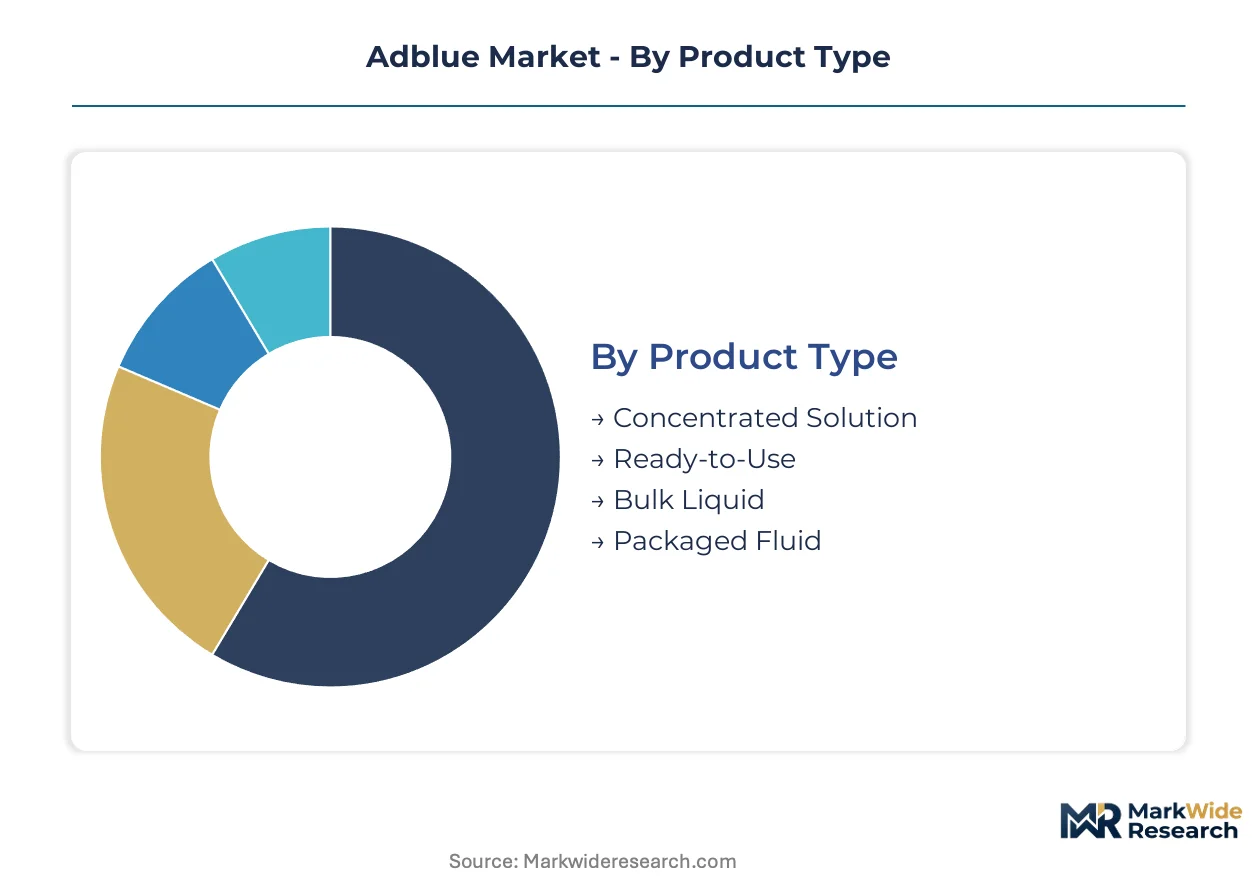
Understanding the Adblue market through segmentation reveals the diverse operational requirements and strategic priorities across its value chain. This granular view helps identify specific demand pockets, distribution challenges, and opportunities for product differentiation based on end-user needs and regulatory compliance frameworks.
Product Type:
The product type segmentation for Adblue highlights varying after-sales service intensities required by different formats.
- Bulk Liquid:This format involves large-volume deliveries, typically in tankers or intermediate bulk containers, designed for high-consumption users. Demand concentrates among heavy-duty truck fleets and major logistics hubs in Germany and China, driven by significant cost efficiencies and reduced handling.
- Packaged Fluid:Available in sealed containers, usually 5-liter, 10-liter, or 20-liter sizes, this format ensures fluid purity and simplifies handling for smaller users. Smaller fleet operators and agricultural machinery users in North America and Western Europe primarily adopt packaged fluid, valuing convenience and contamination prevention.
- Concentrated Solution:This product requires dilution with deionized water before use, primarily serving specialized industrial applications or regions with specific logistical advantages.
- Ready-to-Use:A pre-mixed 32.5% urea solution, this is the standard formulation for direct application in selective catalytic reduction systems.
By volume, Bulk Liquid leads. By growth pace, Packaged Fluid is ahead.
Application:
The application segment illustrates the diverse volume requirements and operational environments for Adblue consumption.
- Heavy-Duty Trucks:These vehicles represent the largest application segment, primarily diesel engines equipped with selective catalytic reduction systems for long-haul transport. Demand sustains in global logistics corridors, particularly across Europe and China, compelled by strict Euro 6 and China VI emissions mandates.
- Light Commercial Vehicles:This segment includes vans and smaller trucks employing SCR technology for urban and regional delivery services. Demand expands within urban centers across Europe and North America, driven by tightening emission regulations and the need for compliance in commercial fleets.
- Agricultural Machinery:Tractors, harvesters, and other off-road equipment utilize Adblue to comply with regulations like the EU's Stage V emission limits for non-road mobile machinery.
- Construction Equipment:Excavators, loaders, and various diesel-powered machinery in infrastructure projects require Adblue to meet environmental standards for off-road applications.
Supply concentration for Adblue aligns with the geographical distribution of heavy-duty truck fleets.
End User:
End user categories reflect distinct purchasing behaviors and service expectations within the Adblue market.
- Fleet Operators:These entities manage extensive vehicle fleets, prioritizing operational uptime, cost efficiency, and reliable supply for their diverse vehicle types. Large commercial fleets in North America and Europe drive demand, seeking integrated solutions and smart dispensing systems.
- Logistics Providers:Companies specializing in freight movement have high Adblue consumption rates and focus on supply chain reliability to ensure continuous operations. Major freight corridors in Germany and India represent significant demand centers, driven by stringent regulatory compliance.
- Equipment Rental Companies:These businesses manage a varied portfolio of machinery, requiring flexible Adblue supply solutions to cater to different client needs and equipment types.
- Agricultural Enterprises:Operators of farm machinery often prefer convenient, pre-packaged Adblue formats due to remote locations and varying consumption patterns.
Margin potential varies, with large fleet operators often securing better bulk pricing.
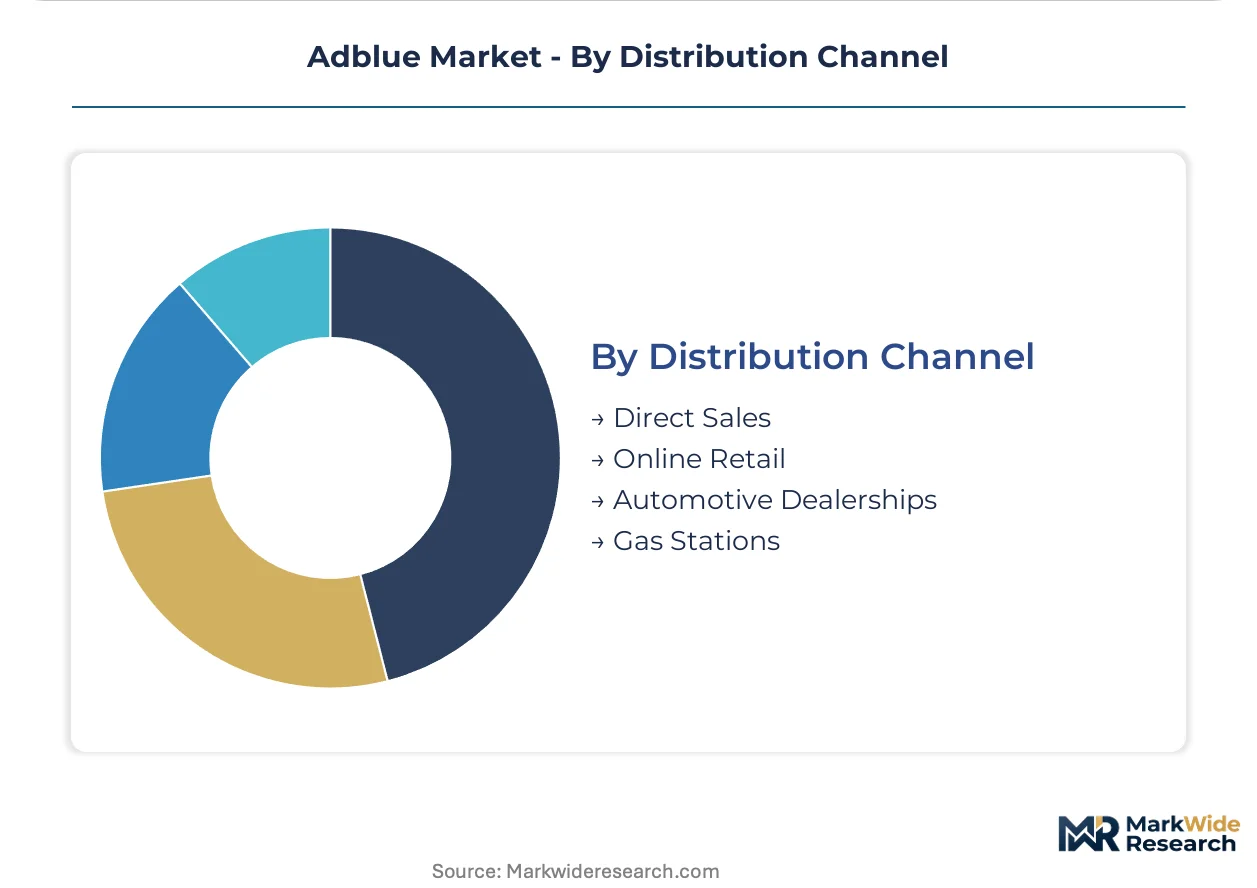
Distribution Channel:
Distribution channels reflect the market's evolving maturity, from traditional bulk supply to consumer-centric retail points.
- Direct Sales:This channel involves direct delivery from suppliers to large commercial fleets, industrial users, or dedicated fueling depots, often in bulk quantities. Large commercial fleets and industrial users in China rely on direct sales for volume discounts and integrated service solutions.
- Gas Stations:Retail sales at gas stations cater to light commercial vehicles and passenger cars, offering convenience through packaged formats or dedicated Adblue pumps. This channel is particularly prevalent in Europe, driven by immediate availability for smaller volume users.
- Online Retail:E-commerce platforms facilitate the sale of packaged Adblue, providing accessibility and convenience for smaller fleet operators and individual consumers.
- Automotive Dealerships:Dealerships offer Adblue as part of their aftermarket services, often bundled with vehicle maintenance or sold as complementary products.
Gas stations are gaining share fastest, while direct sales maintain foundational market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Adblue exhibits varying elasticity across regions. Large commercial fleets in developed markets prioritize supply reliability and bulk cost efficiencies, making them more price-sensitive. Conversely, smaller operators and passenger car owners in diverse geographies value convenience and packaged fluid purity, showing less price sensitivity for smaller volumes.
Germany
Demand for Adblue in Germany stems from its extensive logistics networks and high density of heavy-duty trucks. Euro 6 standards compel widespread SCR system adoption across commercial transport. Major freight corridors around Frankfurt and Hamburg concentrate consumption, requiring reliable bulk liquid supply for continuous operations.
China
China's market requires Adblue for its vast commercial vehicle fleet, driven by the country's stringent China VI emissions regulations. The rapid expansion of logistics and freight movement fuels substantial consumption. Industrial hubs in the Yangtze River Delta and Pearl River Delta drive significant demand for bulk deliveries to support heavy-duty transport.
India
India represents a rapidly growing Adblue market, primarily due to the implementation of Bharat Stage VI (BS-VI) standards for new diesel vehicles. This regulatory framework has converted a substantial portion of the country's commercial vehicle fleet into a new consumption base. Major transport routes connecting Mumbai, Delhi, and Chennai see high demand for both bulk and packaged solutions.
United States
The United States sustains Adblue demand through its large heavy-duty truck sector and federal EPA Clean Air Act regulations. These rules mandate SCR technology in diesel engines, particularly for long-haul freight. Key logistics hubs in Texas and California demonstrate significant consumption, focusing on consistent supply for fleet operators.
Brazil
Brazil offers a strategic opportunity for Adblue, as the country progressively adopts stricter Euro-equivalent emission standards for commercial vehicles. This regulatory shift will compel wider SCR system usage across its substantial truck and bus fleet. Agricultural regions in Mato Grosso and São Paulo will increasingly require packaged Adblue for off-road machinery.
Adblue Market Key Industry Players
Scale-focused commodity suppliers and specialized high-purity solution providers split the Adblue market, reflecting diverse operational requirements. The market exhibits a tiered structure, with large chemical producers supplying raw urea and smaller entities focusing on distribution and blending. Key strategic archetypes include global chemical giants leveraging existing infrastructure for bulk supply and regional distributors emphasizing last-mile delivery for packaged formats. Dominant competitive moves involve capacity expansion to meet regulatory demand and strategic partnerships to optimize complex distribution networks across varied geographies.
Within the global chemical and energy conglomerate archetype, Germany-based BASF SE and Norway-based Yara International ASA exemplify companies leveraging extensive production and distribution networks. BASF SE specifically emphasizes high-purity grades required for sensitive SCR catalysts in newer vehicle models, differentiating its offering. Meanwhile, Shell plc, a UK-Dutch multinational, occupies a strategic position focused on expanding its retail presence at gas stations. This strategy targets light commercial vehicle and passenger car segments, providing convenient access to packaged fluid solutions and expanding its market reach beyond bulk supply.
| Leading Market Players |
|---|
| BASF SE |
| Yara International ASA |
| Shell plc |
| CF Industries Holdings, Inc. |
| TotalEnergies SE |
| GreenChem Holding B.V. |
| Mitsui Chemicals, Inc. |
| Nissan Chemical Corporation |
| Sinopec Group |
| Others |
Cost & Logistics Intelligence
Urea price volatility directly determines Adblue pricing tier spreads and shapes its global supply chain. Fluctuations in agricultural demand and natural gas costs impact raw material expenses for both bulk and packaged fluid solutions.
Pricing Analysis
Integrated service solutions drive lifetime value for Adblue suppliers, bundling fluid supply with automated dispensing systems and telemetry. The dominant pricing model involves contract-based long-term offtake for bulk users and per-unit transactional sales for packaged fluid. Price differentiation stems from high-purity grades required for sensitive SCR catalysts and the significant volume scale of bulk deliveries. Margin capture is narrowing as fleet operators pursue cost efficiencies through on-site blending, making large commercial fleets highly price-sensitive.
Supply Chain Analysis
Large chemical producers like Yara International ASA and BASF SE concentrate raw urea supply for the Adblue market. Geographic supply centers on Germany, China, and India, reflecting major logistics corridors and expanding regulatory enforcement. The supply chain draws from high-purity urea and deionized water, with temperature-sensitive logistics posing a structural risk due to Adblue's freezing point. Distribution runs through direct sales for bulk volumes and gas stations or online retail for packaged formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Adblue market exhibits a platform-economics inflection, moving beyond simple commodity supply to integrated fluid management. This shift is driven by the interoperability of sensors, telemetry, and automated refilling systems within fleet operations.
For Market Incumbents: Harden existing distribution networks by investing in automated fluid management systems for large fleet operators. Expand retail presence at gas stations to capture light commercial vehicle and passenger car segments, countering margin pressure from bulk shifts. Differentiate offerings through high-purity grades to meet upcoming Euro 7 standards, mitigating the long-term electrification threat. Develop strategic partnerships with OEMs to ensure Adblue compatibility with next-generation SCR systems.
For New Entrants and Emerging Players: Establish a beachhead in the marine sector, targeting vessels operating in Emission Control Areas with IMO-compliant urea-based solutions. Focus on South American market entry, particularly Brazil and Argentina, as these regions adopt stricter Euro-equivalent emission standards. Penetrate agricultural enterprises and smaller fleet operators by offering convenient, pre-packaged Adblue formats that ensure fluid purity and simplify handling. Emphasize localized distribution networks and customer service for market differentiation.
For Investors and Strategic Acquirers: Euro 7 standards reshape the acquisition landscape, favoring companies capable of supplying ultra-high purity Adblue for next-generation SCR systems. The market exhibits long-term viability for the next 5-10 years, particularly in heavy-duty transport, before widespread electrification. Target regional distributors with robust last-mile delivery networks or technology firms specializing in smart dispensing and fluid management solutions. The signal to watch is the progressive enforcement of emission standards in off-road applications and marine sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in South America | Meeting new demand from Brazil and Argentina as Euro-equivalent emission standards are adopted. |
| Investment in Automated Fluid Management | Optimizing logistics and enhancing customer retention for large fleet operators in Europe. |
| Development of High-Purity Adblue Grades | Ensuring compliance with stringent upcoming Euro 7 standards for sensitive SCR catalysts. |
| Expansion of Retail Distribution Network | Capturing light commercial vehicle and passenger car segments at gas stations. |
| Strategic Partnerships with Marine OEMs | Securing early market share in the emerging IMO-regulated marine sector. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, industry association reports, and company financial statements. This involved interviews with fleet managers, chemical engineers, logistics directors, and regulatory compliance officers across major markets. The analysis employs a robust bottom-up and top-down triangulation approach to validate market sizing and growth projections. This comprehensive data gathering ensures a holistic perspective on market dynamics.
Forecast inputs considered include diesel vehicle fleet turnover rates, evolving emission standards, and global urea production capacity. The analytical framework models market dynamics across the analysis window, segmenting by product type, application, end user, distribution channel, and regional regulatory enforcement. Compound annual growth rates were derived by assessing historical data and projecting future regulatory impacts. This approach provides a granular view of market evolution.
Stress conditions across geopolitical disruptions and raw material price shocks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions concerning future regulatory enforcement and technological advancements in diesel engine after-treatment. Quarterly review of regulatory updates and raw material indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Tetrafluoroethane (R134A) Refrigerant Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Batch Reactors Market