
 Business Process Re-Engineering Market | 2026-2036
Business Process Re-Engineering Market Size, Share, and Industry Trends Forecast 2026-2036
Business Process Re-Engineering Market Intelligence
Artificial intelligence is hardening the economics of process discovery and redesign, displacing manual workflow mapping with algorithmic pattern recognition. Accenture Operations leverages its embedded consulting-engineering model to sustain multi-year transformation contracts. Genpact anchors its competitive position through domain-specific AI accelerators in finance and supply chain. Bain & Company differentiates by integrating private-equity portfolio expertise with operational restructuring methodology.
Business process re-engineering denotes the fundamental redesign of core workflows to achieve dramatic improvements in cost, quality, speed, or service output, typically employing cross-functional teams, value-chain analysis, and iterative prototyping with measurable KPI baselines. Its primary commercial purpose is to eliminate non-value-adding activities and compress cycle times from customer order to cash receipt. Workflow automation solutions lead current deployment pipelines as enterprises prioritize touchless transaction processing, while cloud-based delivery is expanding fastest by removing infrastructure provisioning delays from implementation timelines. Change management services command premium pricing because behavioral adoption failure remains the dominant source of project value leakage.
FDA guidelines on electronic records and signatures shape validation requirements for re-engineered pharmaceutical quality processes, while the EU AI Act imposes risk-classification obligations on automated decision systems deployed in European banking and telecom operations. HIPAA and SEC record-keeping rules in the US extend compliance scope to healthcare and capital markets transformations. Stakeholders must weigh regulatory divergence against platform standardization when selecting solution architectures for multi-jurisdiction deployments.
Market Dynamics
The EU AI Act's risk-classification framework is forcing financial institutions and telecom operators to rebuild automated decision workflows from the ground up, converting compliance spend into structural transformation budgets.
Growth Catalysts
- Cloud-First Mandates:The EU AI Act and parallel US federal digital modernization directives are accelerating compliance-driven re-engineering spend across banking and healthcare verticals.
- Workflow Automation:Touchless transaction processing is displacing manual handoffs in order-to-cash cycles, compressing cycle times and eliminating non-value-adding activities.
- India Delivery Scale:IT-BPM exporters in India anchor delivery capacity for North American and European clients, concentrating execution expertise in Bangalore and Hyderabad clusters.
Market Restraints
- Behavioral Adoption Failure:Change management services command premium pricing because workforce resistance remains the dominant source of project value leakage.
- Regulatory Divergence:Multi-jurisdiction deployments face friction from conflicting FDA validation requirements for pharmaceutical quality processes and EU AI Act obligations on automated systems.
- Legacy System Entrenchment:Core banking and ERP platforms built on COBOL and early relational architectures resist modular extraction without complete rebuilds.
Strategic Opportunities
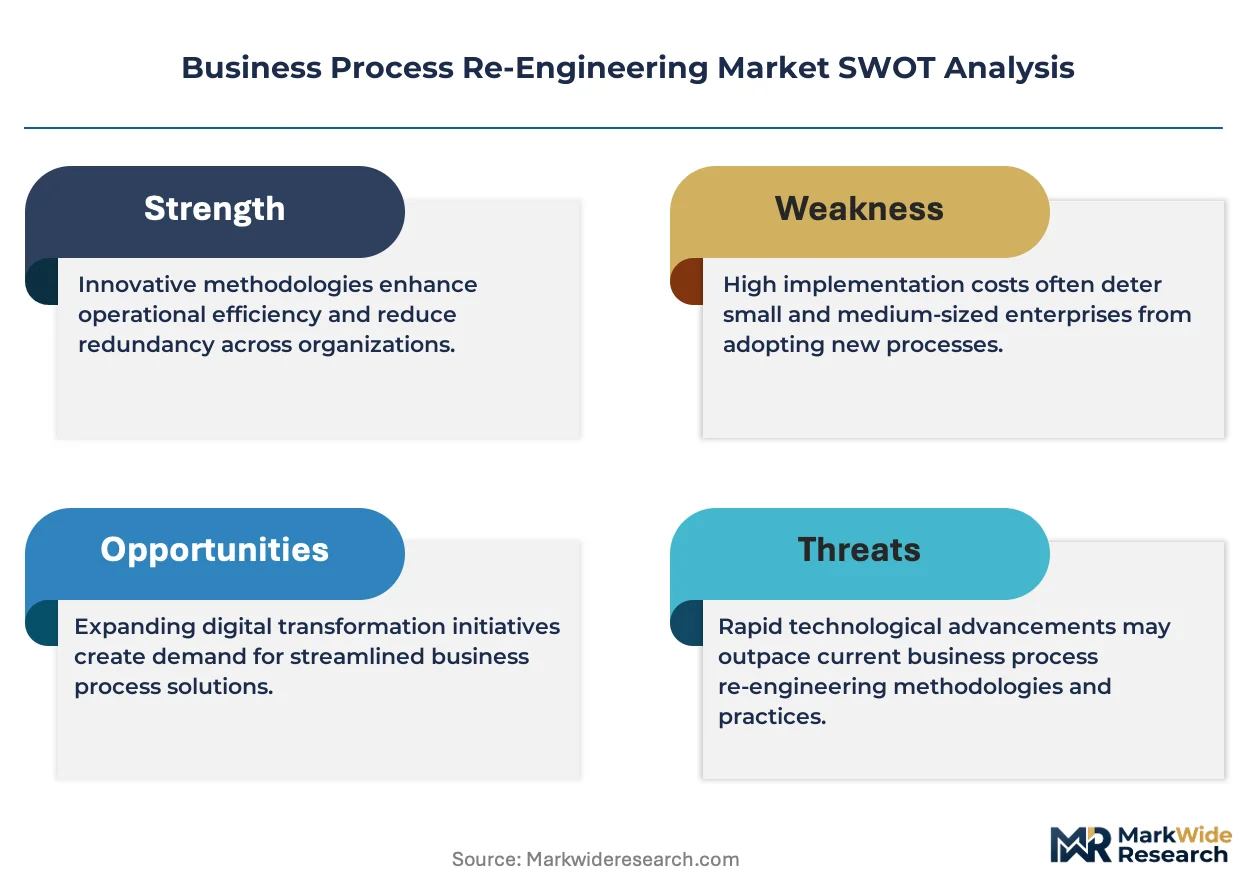
- Process Mining Convergence:Algorithmic pattern recognition combined with robotic process automation is opening white space in supply chain diagnostics for manufacturing verticals.
- Healthcare Digitization:HIPAA-compliant workflow redesign presents untapped potential in US hospital systems seeking touchless patient intake and billing reconciliation.
- Change Management Premiumization:Behavioral science methodologies embedded in transformation contracts capture margin from adoption-risk transfer.
Industry Challenges
- Cross-Functional Talent Scarcity:Professionals combining domain expertise in finance or supply chain with AI implementation skills command compensation premiums that compress project margins.
- Validation Timeline Compression:FDA electronic records guidelines impose 21 CFR Part 11 compliance timelines that extend pharmaceutical re-engineering cycles beyond original forecasts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Process Re-Engineering Market |
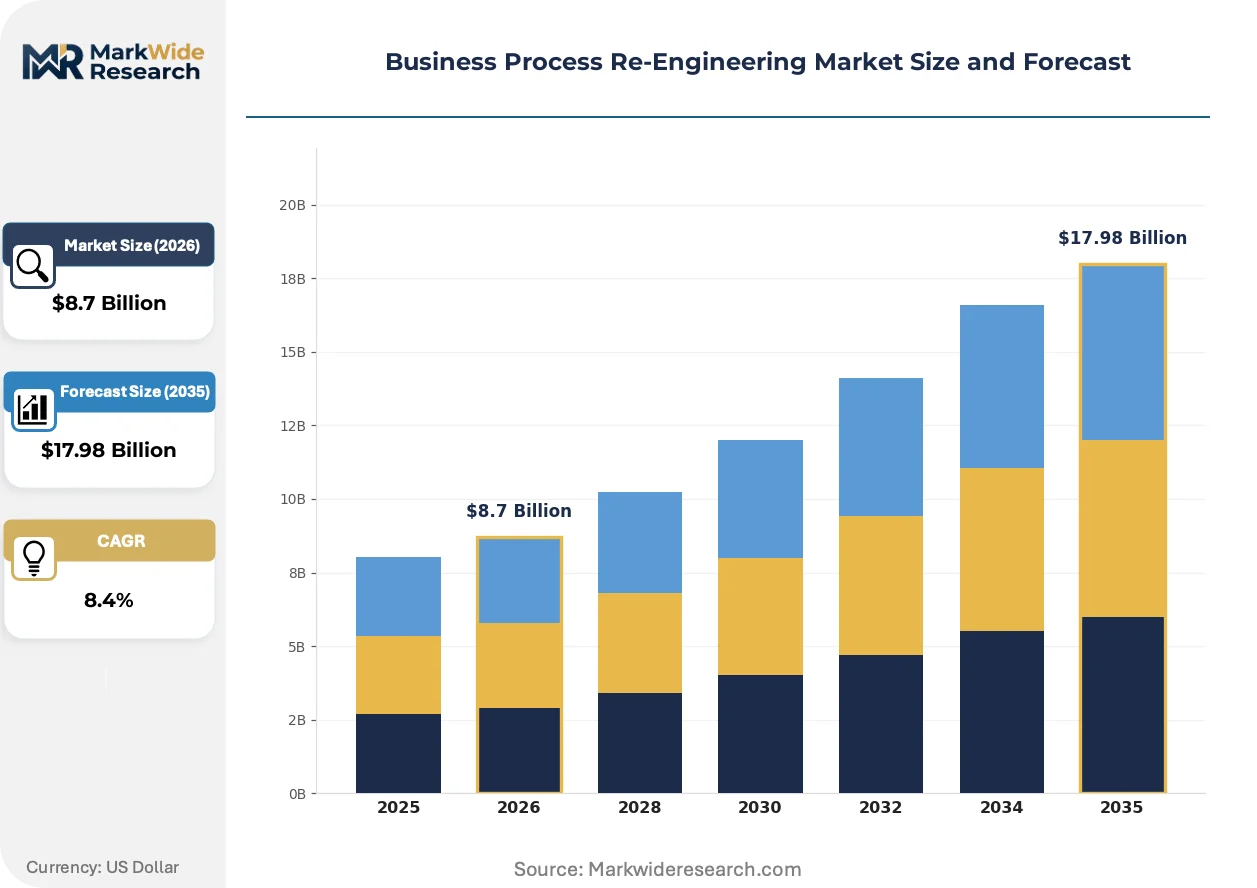
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Workflow Automation, Process Optimization, Change Management, Performance Measurement, Risk Assessment, Compliance Management Deployment Mode: On-Premises, Cloud-Based, Hybrid, Managed Service, SaaS, Hosted End User Type: Financial Services Firms, Manufacturing Plants, Telecom Providers, Government Agencies, Educational Institutions, Energy Companies Industry Application: Customer Service Transformation, Supply Chain Enhancement, Product Development Streamlining, Financial Process Reorganization, Quality Assurance Improvement, Human Resources Optimization |
| Companies Covered | Tallyfy, Panorama Consulting, The Hackett Group, Accenture Operations, Genpact, Bain & Company, Inteq Group, Infosys BPM, Clerestory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Process Re-Engineering Market Strategic Shifts & Innovations
Artificial intelligence is hardening the economics of process discovery, shifting competitive advantage from consulting scale to algorithmic execution speed and domain-specific training data depth.
Process mining software is modularizing the workflow mapping phase, breaking monolithic transformation contracts into discrete diagnostic sprints. Financial services firms in Germany and the Netherlands are deploying these tools to isolate bottlenecks in loan origination pipelines. This modularization is compressing the sales-to-delivery cycle from twelve-month engagements to six-week proof-of-concept structures.
The EU AI Act's automated decision system obligations are reshaping vendor qualification criteria for European banking and telecom procurement teams. Risk-classification tiers now determine validation depth and human-in-the-loop requirements. Institutions in France and Spain are prioritizing re-engineering partners with pre-certified algorithmic governance frameworks.
Enterprise buyers are unbundling transformation contracts into outcome-based milestone payments tied to measurable KPI baselines. This procurement evolution displaces time-and-materials structures in North American healthcare and capital markets verticals. The shift is most visible in US hospital systems where CFOs demand cycle-time reduction guarantees before releasing full project fees.
Business Process Re-Engineering Market Segmentation
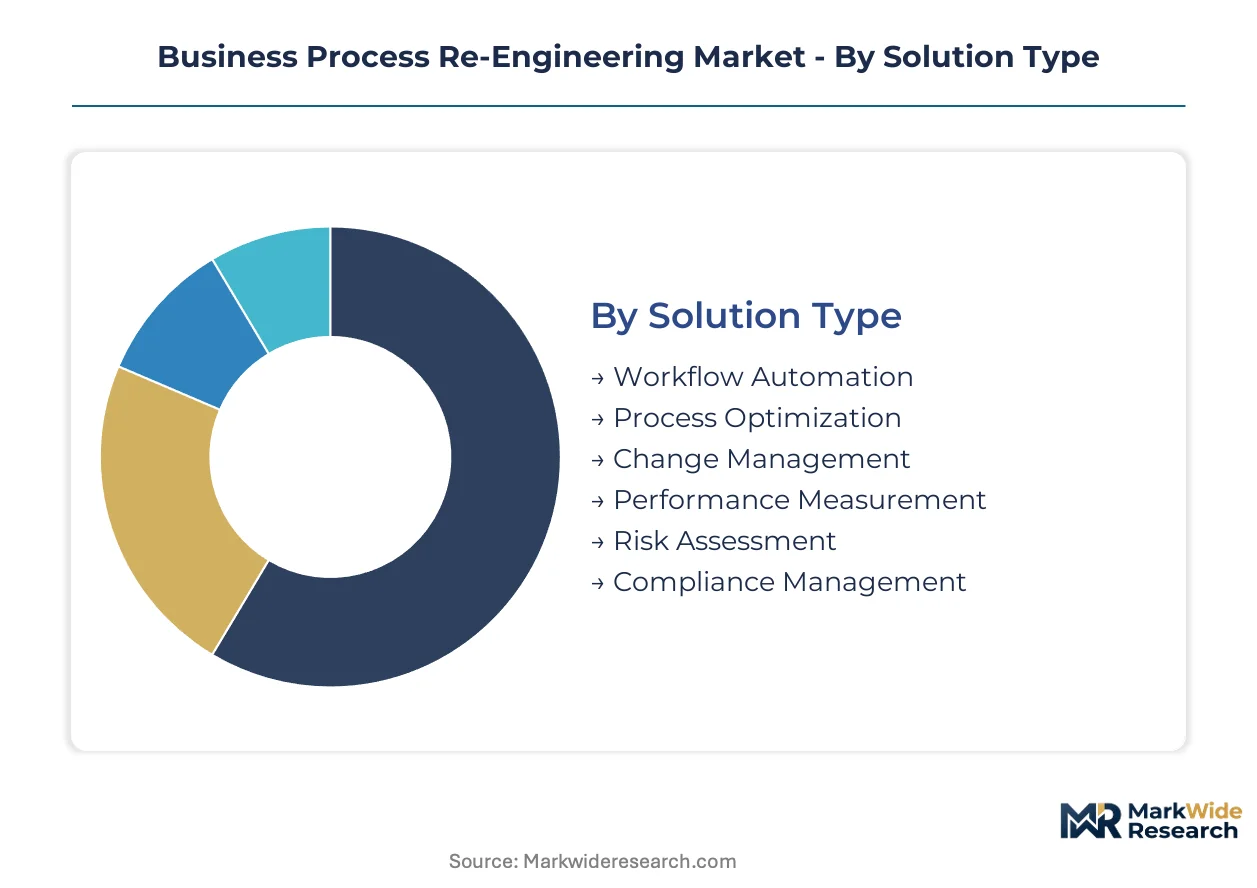
Segmentation in business process re-engineering reveals how solution architectures, delivery models, and vertical specialization determine contract value and margin structure. Buyers prioritize deployment flexibility and industry-specific compliance frameworks when selecting transformation partners.
Solution Type:
Customization intensity spans from standardized automation modules to bespoke behavioral interventions requiring embedded organizational psychologists.
- Workflow Automation:Touchless transaction engines eliminate manual handoffs in order-to-cash cycles. Financial services firms in Germany deploy these tools to compress loan origination timelines under EU AI Act risk-classification mandates.
- Change Management:Behavioral science methodologies address workforce resistance, the dominant source of project value leakage. Premium pricing reflects adoption-risk transfer and embedded organizational psychologists.
- Process Optimization:Value-chain analysis and iterative prototyping target cycle-time compression.
- Performance Measurement:KPI baselines enable outcome-based milestone payments.
- Risk Assessment:Algorithmic governance frameworks satisfy vendor qualification criteria in France and Spain.
- Compliance Management:Validation protocols address FDA 21 CFR Part 11 and HIPAA record-keeping obligations.
Leading the category by volume: Workflow Automation. Expanding most quickly: Change Management.
Deployment Mode:
Cost tier stratification separates capital-intensive infrastructure ownership from variable operational expenditure models.
- Cloud-Based:Removes infrastructure provisioning delays from implementation timelines. EU AI Act cloud-first mandates accelerate banking sector adoption across Frankfurt and Amsterdam clusters.
- SaaS:Subscription pricing democratizes access for mid-market healthcare systems seeking HIPAA-compliant workflow redesign.
- On-Premises:Retains control for pharmaceutical quality processes under strict FDA validation requirements.
- Hybrid:Balances sensitive data residency with cloud scalability.
- Managed Service:Transfers operational burden to IT-BPM exporters in Bangalore and Hyderabad.
- Hosted:Dedicated infrastructure meets telecom operator latency specifications.
Cloud-Based captures the largest revenue share. SaaS climbs the fastest as CFOs demand cycle-time reduction guarantees.
End User Type:
Application complexity varies from standardized transaction processing to heavily regulated decision workflows requiring human-in-the-loop architectures.
- Financial Services Firms:Automated decision systems trigger EU AI Act risk-classification obligations. Institutions in France and Spain prioritize partners with pre-certified algorithmic governance.
- Government Agencies:US federal digital modernization directives accelerate compliance-driven re-engineering spend. Procurement teams unbundle contracts into outcome-based milestone structures.
- Manufacturing Plants:Process mining convergence opens supply chain diagnostics opportunities.
- Telecom Providers:Automated customer workflows face EU AI Act scrutiny.
- Educational Institutions:Administrative efficiency drives student lifecycle management redesign.
- Energy Companies:Asset maintenance workflows integrate predictive analytics.
Financial Services Firms dominate contract value. Government Agencies show steepest expansion trajectory as federal mandates deepen.
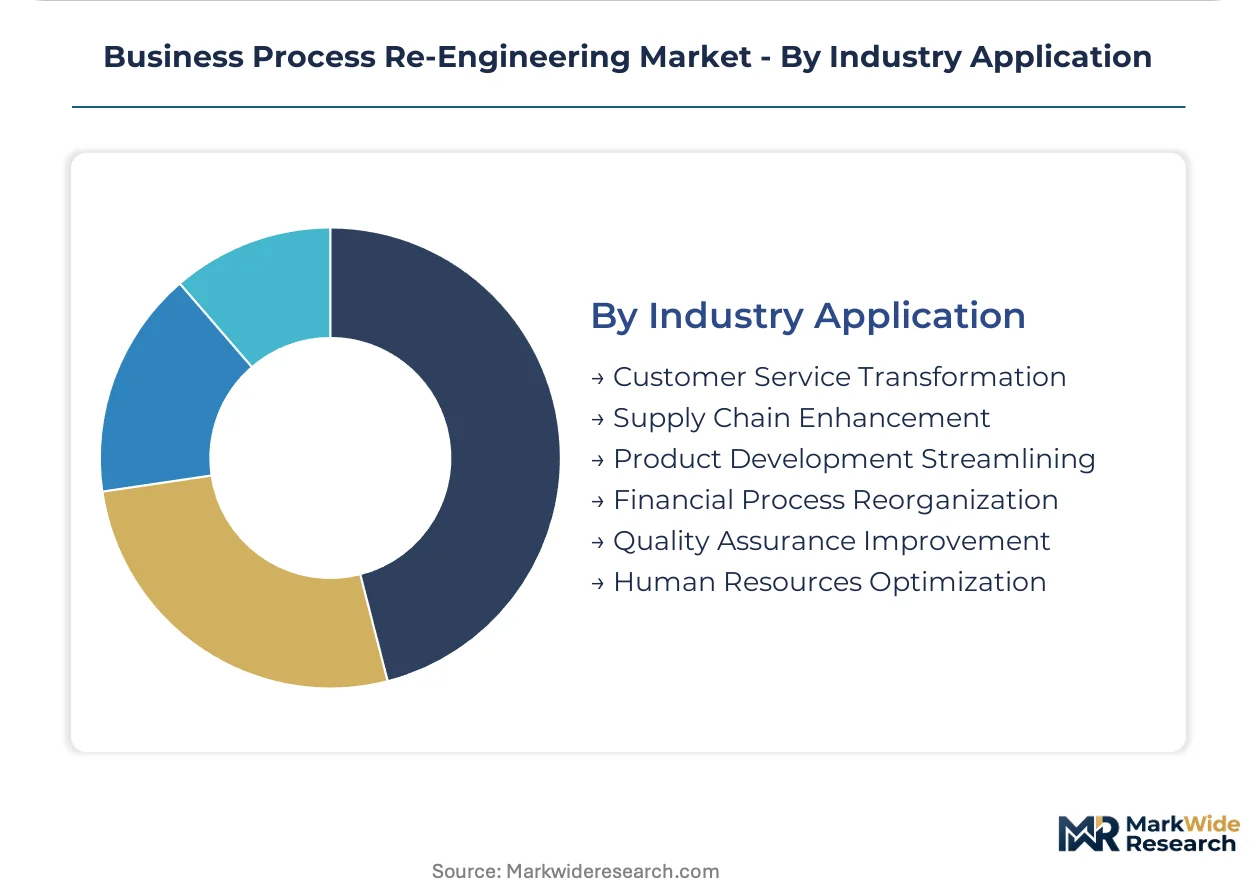
Industry Application:
Margin profiles diverge between high-volume transactional workflows and knowledge-intensive transformation requiring cross-functional expertise.
- Customer Service Transformation:Touchless intake and billing reconciliation target US hospital systems. HIPAA-compliant redesign presents white space as CFOs demand measurable KPI baselines.
- Supply Chain Enhancement:Process mining plus robotic process automation isolates bottlenecks. German and Dutch manufacturers deploy six-week proof-of-concept structures replacing twelve-month engagements.
- Financial Process Reorganization:Order-to-cash compression eliminates non-value-adding activities.
- Product Development Streamlining:Cross-functional teams accelerate time-to-market.
- Quality Assurance Improvement:FDA electronic records guidelines extend pharmaceutical cycles.
- Human Resources Optimization:Behavioral adoption methodologies reduce workforce resistance.
Customer Service Transformation leads by revenue concentration. Supply Chain Enhancement gains share fastest as modular diagnostics proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bangalore and Hyderabad concentrate IT-BPM delivery capacity for North American and European clients. Tax incentives under India's Software Technology Parks of India scheme accelerated cluster formation. These zones now anchor execution scale for cross-border transformation contracts.
United States
Federal digital modernization directives from the Office of Management and Budget accelerate compliance-driven re-engineering spend across healthcare and capital markets. HIPAA and SEC record-keeping rules extend transformation scope to hospital systems and investment banks. New York and Boston clusters host consulting-engineering firms serving Fortune 500 workflow automation mandates.
Germany
EU AI Act risk-classification obligations force financial institutions in Frankfurt to rebuild automated decision workflows from compliance budgets. BaFin supervisory guidance on algorithmic governance shapes vendor qualification criteria. Munich and Stuttgart manufacturing hubs deploy process mining diagnostics to compress supply chain cycle times.
India
IT-BPM exporters anchor delivery scale for North American and European clients seeking touchless transaction processing. RBI guidelines on digital lending infrastructure drive domestic bank re-engineering demand. Bangalore and Hyderabad clusters concentrate cross-functional talent combining domain expertise with AI implementation skills.
France
CNIL oversight on automated decision systems intersects with EU AI Act obligations for Paris-based banking and telecom operators. Institutions prioritize re-engineering partners with pre-certified algorithmic governance frameworks. Île-de-France hosts procurement teams unbundling transformation contracts into outcome-based milestone structures.
United Kingdom
FCA operational resilience requirements pressure London financial services firms to compress order-to-cash cycles through workflow automation. NHS digitization targets create demand for HIPAA-analogous patient intake redesign. The London-Southeast corridor concentrates consulting firms serving private-equity portfolio operational restructuring.
Business Process Re-Engineering Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with advisory-led consultancies capturing premium pricing in change management while IT-BPM exporters dominate execution scale. The vendor base concentrates around three strategic archetypes: embedded consulting-engineering hybrids, domain-specific AI accelerator platforms, and private-equity-integrated operational restructuring specialists. Capacity expansion through Bangalore and Hyderabad delivery clusters represents one dominant competitive move; algorithmic governance framework pre-certification for EU AI Act compliance represents another.
Within the embedded consulting-engineering tier, Accenture Operations and Genpact exemplify contrasting scale models. Accenture Operations occupies a position representing multi-year transformation contract sustainability through integrated service delivery. Genpact anchors the domain-specific AI accelerator archetype, with its finance and supply chain specialization reflecting industry vertical depth. Bain & Company sits within the private-equity-integrated restructuring tier, its methodology shaped by portfolio company operational turnaround patterns. These three represent the structural segmentation visible across competitive positioning in workflow automation and change management service lines.
| Leading Market Players |
|---|
| Tallyfy |
| Panorama Consulting |
| The Hackett Group |
| Accenture Operations |
| Genpact |
| Bain & Company |
| Inteq Group |
| Infosys BPM |
| Clerestory |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EU AI Act pre-certified algorithmic governance frameworks and uncertified legacy methodologies splits contract value trajectories, with premium tiers commanding adoption-risk transfer pricing while commodity workflow automation faces margin compression from Bangalore-based IT-BPM exporters. This bifurcation concentrates supply chain leverage among embedded consulting-engineering hybrids possessing validated compliance architectures, while squeezing standalone automation vendors into price-competitive managed service arrangements.
Pricing Analysis
Volume-mass workflow automation contracts run on per-seat SaaS subscriptions, while margin-rich change management engagements deploy outcome-based milestone structures tied to measurable KPI baselines. Price differentiation hinges on algorithmic governance certification depth and embedded organizational psychology resources. Cost compression in standardized automation tiers intensifies as Indian delivery clusters scale touchless transaction processing capacity. Mid-market healthcare systems exhibit acute price sensitivity, whereas European banking procurement teams prioritize pre-certified vendor qualification over unit economics.
Supply Chain Analysis
India's Software Technology Parks of India scheme anchors delivery concentration for North American and European clients, with Bangalore and Hyderabad clusters feeding cross-border transformation pipelines. Talent inputs draw from domain-AI cross-functional professionals, cloud infrastructure provisioning, and behavioral science practitioner networks. Single-source vulnerability concentrates in specialized algorithmic governance certification capacity. Distribution runs through embedded consulting-engineering partnerships, direct enterprise sales to Fortune 500 CFOs, and IT-BPM exporter managed service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act compliance mandates are consolidating vendor qualification criteria around pre-certified algorithmic governance frameworks, forcing uncertified workflow automation specialists into subscale managed service margins or exit.
For Market Incumbents: Cement multi-year transformation contract sustainability through deeper vertical integration into cloud infrastructure provisioning and algorithmic governance certification investment. Threat substitution from modular process mining diagnostics demands preemptive embedding of behavioral science capabilities to capture change management premium pricing. Channel control over Bangalore-Hyderabad delivery clusters reinforces execution scale advantages against emerging AI-native challengers. For New Entrants and Emerging Players: Capture white space in HIPAA-compliant healthcare workflow redesign for US hospital systems seeking touchless patient intake and billing reconciliation. The most penetrable segment sits with mid-market providers lacking internal AI implementation expertise. Go-to-market leverage rests on outcome-based milestone payment structures guaranteeing measurable cycle-time reduction. For Investors and Strategic Acquirers: Re-rating potential sits with domain-specific AI accelerator platforms possessing pre-certified EU AI Act algorithmic governance frameworks, given accelerating vendor qualification consolidation in Frankfurt and Paris banking procurement. Long-term viability favors embedded consulting-engineering hybrids over standalone automation vendors. The signal to watch is unbundling of transformation contracts into discrete diagnostic sprints, indicating procurement power shift toward outcome-guaranteed delivery models.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Governance Pre-Certification | EU AI Act risk-classification tiers in Frankfurt and Paris banking procurement now mandate validated compliance architectures. |
| Change Management Capability Acquisition | Behavioral science practitioner networks address workforce resistance, the dominant source of project value leakage. |
| Cloud Infrastructure Vertical Integration | In-house provisioning removes deployment delays from implementation timelines under federal digital modernization directives. |
| Process Mining Platform Integration | Modular diagnostic sprints compress sales-to-delivery cycles from twelve-month engagements to six-week proof-of-concept structures. |
| Healthcare Vertical Expansion | HIPAA-compliant workflow redesign targets US hospital system CFOs demanding cycle-time reduction guarantees. |
Research Approach
Document review covered EU AI Act regulatory filings, FDA 21 CFR Part 11 validation guidelines, and SEC disclosure records, complemented by interviews with transformation program directors at financial institutions, healthcare system CFOs, IT-BPM delivery heads in Bangalore and Hyderabad, and procurement officers at European banking and telecom operators. Secondary validation drew from hyperscaler cloud capex disclosures, IT-BPM exporter financial statements, and hospital procurement database records. Bottom-up contract value aggregation and top-down market sizing triangulated volume estimates.
Cross-referencing historical workflow automation deployment patterns against expert panel input on EU AI Act implementation timelines shaped the analytical framework. Segmentation dimensions modeled span solution type, deployment mode, end-user vertical, and regional regulatory cluster. CAGRs were derived from trajectory analysis of compliance-driven re-engineering budgets and cloud-first mandate acceleration curves. Industry-specific inputs included BaFin supervisory guidance evolution and US federal digital modernization directive spending authorization patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between FDA validation requirements and EU AI Act risk-classification obligations, cross-functional talent scarcity compressing project margins, and behavioral adoption failure rates in change management engagements. Forecasts reflect documented assumptions on mandate implementation timelines and procurement unbundling velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Global Insurance Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
Contract Management Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market