
 Middle East and Africa Workforce Management Software Market | 2026-2036
Middle East and Africa Workforce Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Workforce Management Software Market Foresight
Channel partnerships between global software vendors and regional systems integrators is rewriting how workforce management platforms reach end users across the Middle East and Africa. Oracle Corporation leverages its established partner network to anchor deployments in Gulf state healthcare and education sectors. SAP SE competes through localized compliance modules that address national labor law variations across the region. UKG Inc. specializes in cloud-native scheduling architectures designed for mobile-first workforces in retail and manufacturing.
Workforce management software encompasses integrated applications that automate time tracking, labor scheduling, absence management, and regulatory compliance through real-time data capture and algorithmic optimization of staff allocation. Cloud-based deployment dominates new procurement as organizations prioritize remote accessibility and reduced capital expenditure, while on-premise installations persist in sectors with stringent data sovereignty requirements. Attendance management functionality leads current spending due to biometric integration mandates in Saudi Arabia and the UAE, though leave management modules represent the fastest expansion area as multinational employers standardize cross-border absence policies. The manufacturing end-user segment occupies the deepest margin pools through complex shift-pattern optimization and overtime control requirements.
POPIA in South Africa and the UAE's National In-Country Value program collectively reshape vendor qualification criteria, with data localization requirements and local content thresholds filtering market access for international providers. Saudi Arabia's National Data Management Office standards add another compliance layer governing employee information handling in cloud environments. Stakeholders must monitor evolving data residency rules and localization incentives as decisive variables in platform architecture and partnership strategy across jurisdictions.
Market Dynamics
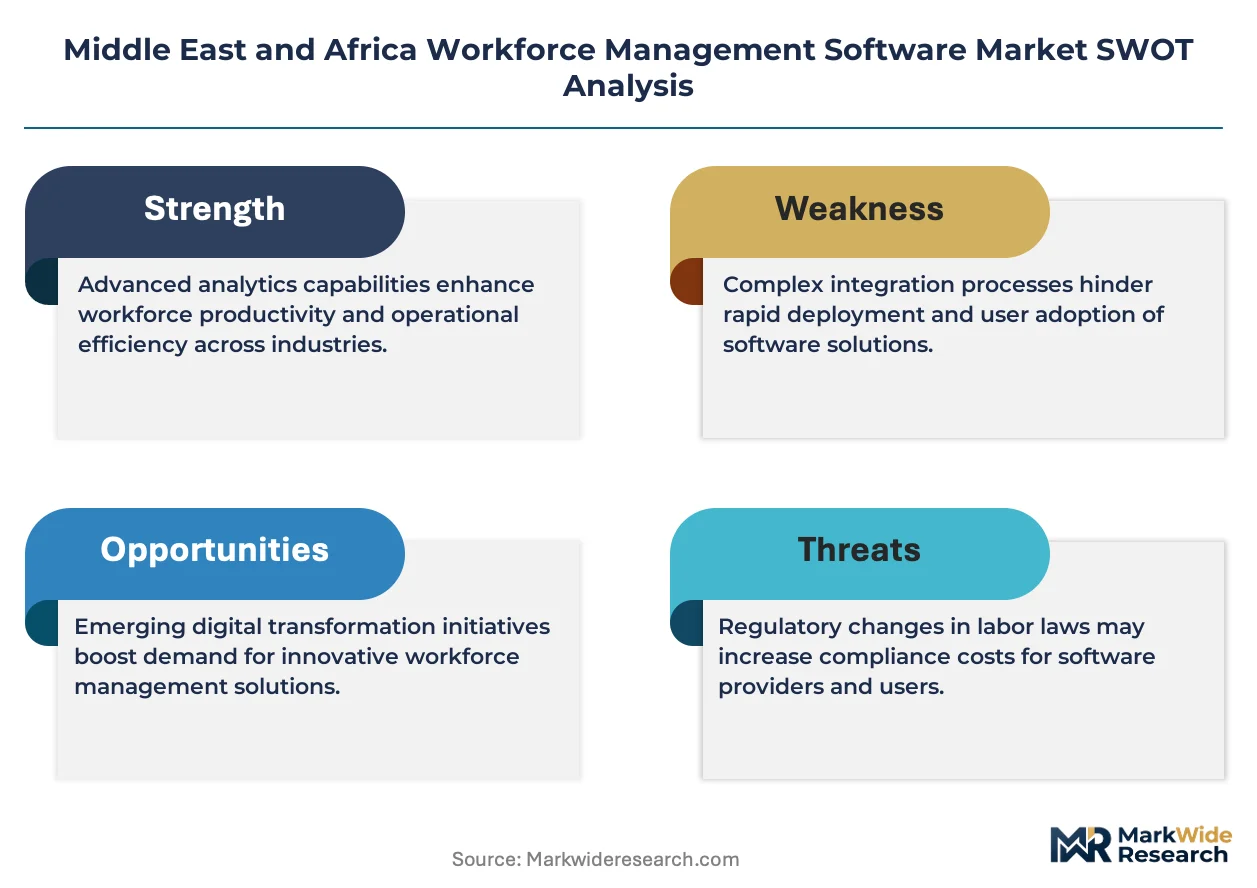
Gulf state governments are mandating biometric workforce tracking systems, forcing rapid cloud migration across healthcare and public sector employers while triggering compliance-driven procurement waves.
Growth Catalysts
- Biometric Integration Mandates:Saudi Arabia and the UAE now require biometric attendance systems in government-contracted enterprises, creating immediate replacement demand for legacy time-tracking infrastructure.
- POPIA Compliance Deadlines:South Africa's data protection enforcement timeline compels employers to audit human capital systems and replace non-compliant platforms before penalty phases activate.
- Clinical Staffing Optimization:GCC healthcare networks are deploying algorithmic scheduling to reduce nurse overtime burnout and meet Joint Commission International accreditation standards.
Market Restraints
- Data Localization Costs:Saudi Arabia's National Data Management Office standards force vendors to maintain in-country server infrastructure, raising operational overhead for international cloud providers.
- Skills Concentration in Dubai:Regional systems integrator expertise clusters in the UAE, creating bottlenecked implementation capacity for deployments in Egypt, Nigeria, and Kenya.
- Legacy On-Premise Persistence:Defense and oil-sector employers in Qatar and Kuwait retain air-gapped workforce systems due to classified facility access protocols, slowing cloud subscription conversion.
Strategic Opportunities
- Kenya's Digital Workforce Initiative:Nairobi's public sector digitization program creates first-mover advantage for vendors offering mobile-native platforms compatible with feature-phone penetration rates.
- AI-Powered Predictive Scheduling:Machine learning modules that forecast absenteeism patterns are penetrating retail and logistics verticals where seasonal demand fluctuation is severe.
- Nigeria's Subnational Procurement:Lagos and Kano state governments are decentralizing HR system purchasing, opening direct vendor relationships bypassing federal tender complexity.
Industry Challenges
- Localization Engineering Talent:Vendors struggle to hire Arabic-language UX designers and Sharia-compliant payroll calculation engineers for Saudi and UAE product teams.
- Interoperability with Legacy ERP:Manufacturing employers in South Africa's automotive belt require complex API bridges between new workforce platforms and decades-old SAP R/3 installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Workforce Management Software Market |
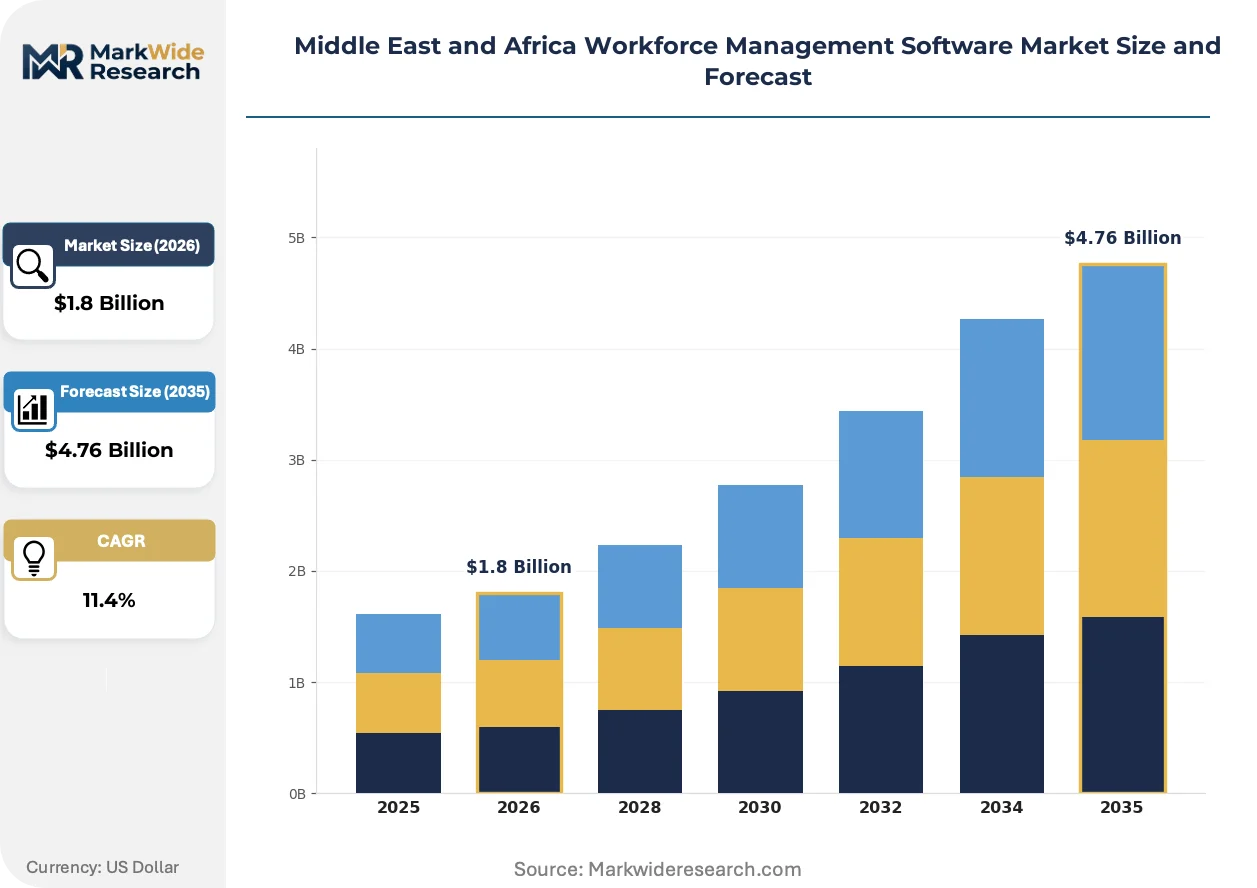
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time Tracking, Attendance Management, Scheduling, Leave Management Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Manufacturing, Retail, Healthcare, Education Functionality: Performance Management, Employee Self-Service, Reporting, Compliance |
| Companies Covered | ActiveOps plc, ADP LLC, Oracle Corporation, UKG Inc., SAP SE, Infor, NICE Ltd., Workday, Inc., Ceridian HCM Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Workforce Management Software Market Shifts & Advancements
Workforce management platforms are converging with identity verification and financial services, erasing traditional boundaries between HR tech, fintech, and physical security systems across Middle Eastern and African enterprises.
Mobile-first biometric authentication is collapsing the distinction between attendance verification and payment disbursement. Kenyan and Nigerian employers are adopting fingerprint-to-wallet systems that trigger salary release upon shift completion. This convergence eliminates separate payroll processing cycles and compresses working capital timelines for informal sector workforces.
South Africa's POPIA enforcement is accelerating vendor consolidation around platforms with pre-certified data governance architectures. Employers now disqualify providers lacking independent privacy audits, privileging established regional integrators over new market entrants. Healthcare and financial services verticals are driving this filtering mechanism hardest due to patient and client data exposure risks.
Subscription fatigue among mid-market employers is fragmenting procurement toward modular point solutions. Nigerian and Egyptian manufacturing firms are purchasing standalone absence management or shift-optimization tools rather than integrated suites, then demanding API connectivity to existing accounting software. This behavior pressures full-suite vendors to unbundle pricing and prove interoperability claims through live pilot programs.
Middle East and Africa Workforce Management Software Market Segmentation
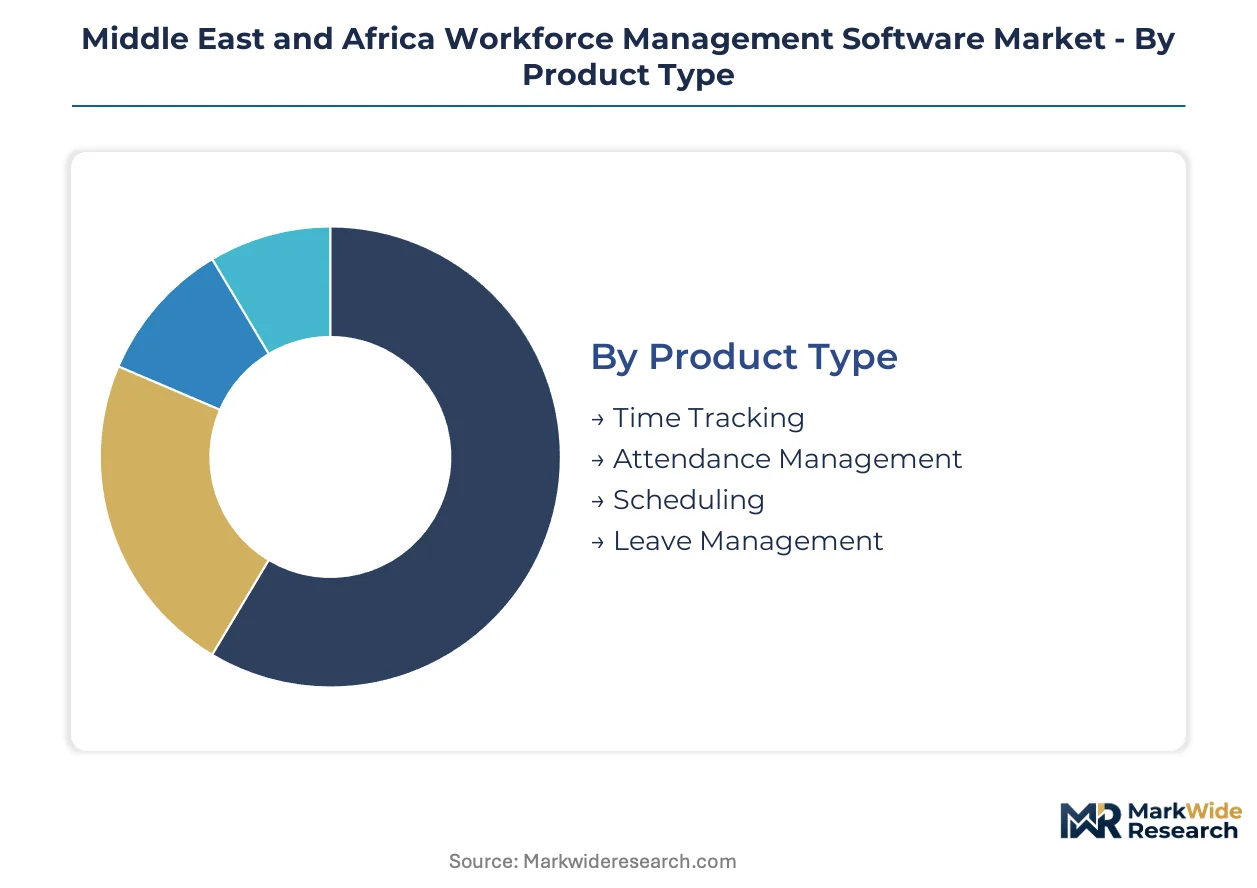
Workforce management software procurement across the Middle East and Africa fragments sharply by deployment architecture and regulatory exposure. Vendors must architect separate go-to-market motions for biometric-mandated public sector buyers versus modular-seeking mid-market manufacturers.
Product Type:
After-sales service intensity peaks with attendance management systems requiring biometric hardware calibration and firmware updates across dispersed Gulf state installations.
- Time Tracking:Captures work hours through digital clock-in interfaces, biometric scanners, and GPS-enabled mobile verification. Demand concentrates in Saudi construction and logistics camps where wage protection regulations mandate auditable hour records. POPIA compliance costs in South Africa filter vendor selection toward platforms with certified data lineage.
- Attendance Management:Integrates biometric authentication with real-time absence alerts and shift coverage dashboards. UAE government contractors drive replacement cycles as Nafis program mandates force legacy system upgrades. Hardware-software bundling creates sticky vendor relationships through multi-year maintenance contracts.
- Scheduling:Algorithmic staff allocation tools optimizing shift patterns against demand forecasts.
- Leave Management:Cross-border absence policy standardization tools for multinational employers.
By volume, Attendance Management leads. By growth pace, Leave Management is ahead.
Deployment:
Cost tier stratification separates capital-intensive on-premise buyers from subscription-oriented cloud adopters, with hybrid architectures capturing security-conscious mid-market budgets.
- On-Premise:Local server installations with dedicated IT infrastructure and air-gapped security protocols. Qatar defense and Kuwait oil facilities retain these configurations due to classified facility access requirements. High upfront capital expenditure and specialized maintenance contracts define the customer profile.
- Cloud-Based:Subscription-accessed platforms with remote data centers and automatic feature updates. South African healthcare networks and UAE retail chains prioritize these for reduced IT overhead and rapid scaling. Saudi data localization rules force regional cloud node investments by international providers.
- Hybrid:Split architectures keeping sensitive payroll data on-premise while routing scheduling through cloud interfaces.
- Mobile:Smartphone-native applications with offline functionality and biometric capture.
Cloud-Based deployments dominate new procurement. Hybrid configurations show the steepest expansion trajectory among security-sensitive verticals.
End User:
Application complexity varies dramatically, with manufacturing requiring shift-pattern optimization against retail's seasonal fluctuation management.
- Manufacturing:Complex workforce coordination across multi-shift production lines with overtime control and skill-based routing. South African automotive belt and Egyptian textile corridors drive demand for ERP-integrated platforms. API bridges to legacy SAP R/3 installations create implementation bottlenecks.
- Healthcare:Clinical staffing optimization ensuring Joint Commission International accreditation compliance and nurse burnout reduction. GCC hospital networks deploy these systems most aggressively, with Dubai Health Authority procurement setting regional standards. Algorithmic scheduling reduces agency nurse dependency.
- Retail:Seasonal demand fluctuation management with part-time workforce scaling.
- Education:Academic calendar-aligned staffing with substitute teacher dispatch systems.
Manufacturing captures the deepest margin pools. Healthcare is climbing the fastest as Gulf state hospital expansion accelerates.
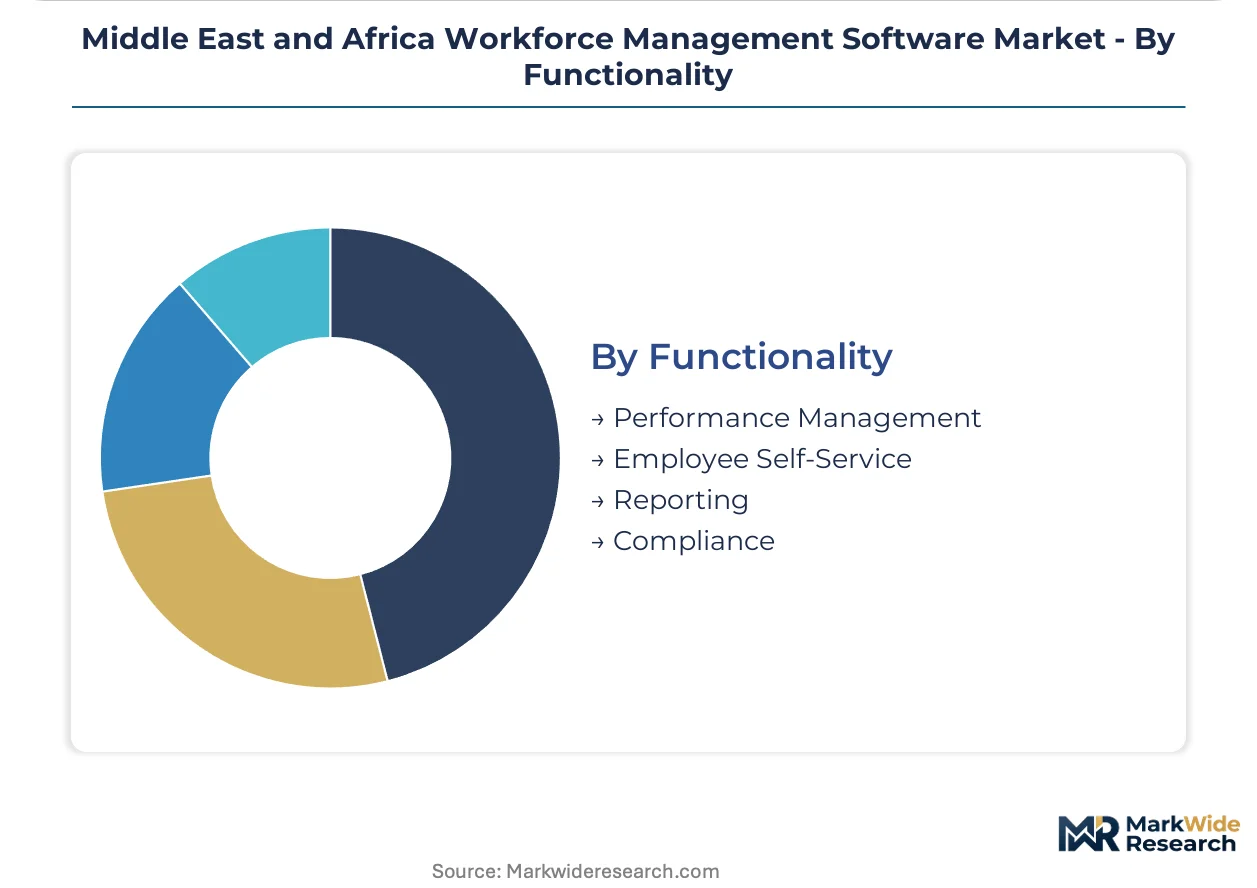
Functionality:
Maturity gradients separate basic reporting modules from AI-enhanced predictive systems, with compliance functionality commanding premium pricing in regulated verticals.
- Performance Management:Goal-setting, review cycles, and competency tracking modules integrated with compensation workflows. Multinational employers across Nigeria and Kenya standardize these for cross-border talent calibration. Localization challenges persist with Arabic-language UX and Sharia-compliant evaluation frameworks.
- Compliance:Automated regulatory adherence for labor law variations, data protection mandates, and audit documentation. South African POPIA enforcement and Saudi NDMO standards make this functionality non-negotiable for financial services and healthcare buyers. Pre-certified architectures filter vendor qualification.
- Employee Self-Service:Worker-facing portals for schedule viewing, leave requests, and profile management.
- Reporting:Standardized dashboards and custom analytics for workforce metrics visualization.
Compliance functionality leads current spending. Performance Management is gaining share fastest as employer digitization deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Cooperation Council's fiber-optic backbone and Red Sea submarine cable landings position the Middle East as a digital services corridor connecting European enterprise demand with Asian cloud infrastructure. This connectivity underwrites workforce software procurement velocity across the region.
United Arab Emirates
Dubai Health Authority procurement sets regional standards for clinical workforce platforms, with algorithmic nurse scheduling reducing agency dependency. The National In-Country Value program mandates local content thresholds for government contractors. Abu Dhabi's G42 cloud infrastructure anchors data residency compliance for international vendors.
Saudi Arabia
Nafis program workforce nationalization drives biometric attendance system mandates across government-contracted enterprises. National Data Management Office standards enforce employee data localization in cloud environments. Riyadh's King Abdullah Financial District concentrates fintech-integrated workforce platform adoption.
South Africa
Protection of Personal Information Act enforcement compels healthcare networks to audit human capital systems for certified data lineage. Johannesburg's automotive belt demands ERP-integrated scheduling platforms with complex API bridges to legacy SAP R/3 installations. Cape Town's financial services sector privileges pre-certified privacy architectures.
Nigeria
Lagos and Kano state governments are decentralizing HR system purchasing, opening direct vendor relationships that bypass federal tender complexity. Mobile-native platforms compatible with feature-phone penetration rates capture informal sector workforce management demand. Port Harcourt's oil services corridor retains hybrid cloud architectures for payroll data sovereignty.
Kenya
Nairobi's public sector digitization program creates first-mover advantage for vendors offering offline-capable mobile scheduling. M-Pesa integration enables fingerprint-to-wallet salary disbursement upon shift completion. Konza Technopolis anchors East African cloud node investments by international workforce software providers.
Middle East and Africa Workforce Management Software Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: global enterprise suites with regional compliance modules, cloud-native specialists with mobile-first architectures, and localized integrators with sovereign data handling certifications. Market structure favors vendors with pre-certified privacy architectures and established Arabic-language UX capabilities. Dominant competitive moves include strategic partnerships with regional systems integrators and unbundled modular pricing to address mid-market subscription fatigue.
Among global enterprise suite providers, Oracle Corporation and SAP SE anchor the premium tier through localized compliance modules addressing Gulf state labor law variations. UKG Inc. occupies a distinct position with cloud-native scheduling architectures designed for mobile-first workforces. These three exemplify the competitive archetypes reshaping channel partnerships across Middle Eastern and African markets: legacy platform extenders, compliance-first localizers, and mobile-native specialists.
| Leading Market Players |
|---|
| ActiveOps plc |
| ADP LLC |
| Oracle Corporation |
| UKG Inc. |
| SAP SE |
| Infor |
| NICE Ltd. |
| Workday, Inc. |
| Ceridian HCM Inc. |
| Others |
Supply & Pricing Matrix
Saudi Arabia's National Data Management Office data localization mandates function as a regulatory chokepoint that compresses margin spreads between international cloud providers and regional integrators while forcing supply chain restructuring toward in-country infrastructure investments. This compliance burden stratifies pricing tiers and reshapes vendor qualification pathways across Gulf state procurement.
Pricing Analysis
Volume-discount tiering structures separate enterprise-suite subscriptions from modular point solutions, with three-tier pricing stratification across premium compliance-certified platforms, standard cloud-native offerings, and economy-tier on-premise licenses. Price differentiation rests on certification grade against POPIA and NDMO standards plus Arabic-language localization depth. Cost compression in the mid-market intensifies because subscription fatigue drives unbundled procurement. Government contractors in the UAE and Saudi Arabia exhibit lowest price sensitivity due to National In-Country Value program mandates, while Nigerian and Egyptian manufacturing firms demonstrate highest sensitivity as they prioritize standalone modules over integrated suites.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing arrangements between global software vendors and regional systems integrators, straining working capital for implementation partners. Geographic supply concentration centers on the UAE for systems integration expertise, India for engineering talent, and South Africa for POPIA-certified data centers. Raw material dependencies encompass biometric hardware components, cloud server infrastructure, and API middleware licenses. Single-source vulnerability persists in Arabic-language UX design talent pools. Distribution runs through channel partnerships anchored by Oracle, SAP, and UKG with regional integrators holding sovereign data handling certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. Switching costs compound through biometric hardware-software bundling and multi-year maintenance contracts.
For Market Incumbents: Build certification moats by pre-emptively achieving NDMO and POPIA compliance certification ahead of enforcement phases. Deepen vertical integration into biometric hardware calibration services to capture aftermarket revenue streams. Emerging cloud-native specialists threaten premium-tier positioning through mobile-first architectures. For New Entrants and Emerging Players: Kenya's public sector digitization program represents the most penetrable white-space target, with Nairobi's offline-capable mobile scheduling demand outpacing supply. Port Harcourt's oil services corridor offers secondary entry through hybrid cloud payroll architectures. M-Pesa integration capability provides the decisive go-to-market angle for informal sector workforce management. For Investors and Strategic Acquirers: POPIA enforcement reshapes the acquisition landscape toward platforms with pre-certified data governance architectures. Long-term viability favors vendors with established Arabic-language UX capabilities and regional systems integrator relationships. Acquisition target archetypes include localized compliance module developers and biometric hardware-software bundlers. The signal to watch is NDMO audit timeline acceleration as a precursor to vendor consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| POPIA Compliance Certification | Pre-certified architectures filter vendor qualification in South African healthcare and financial services procurement. |
| Biometric Hardware-Software Bundling | Multi-year maintenance contracts create sticky relationships across UAE government contractor installations. |
| Arabic-Language UX Localization | Sharia-compliant payroll calculation modules unlock Saudi Arabia and UAE enterprise segments. |
| Regional Cloud Node Investment | In-country server infrastructure satisfies NDMO data residency requirements for international providers. |
| API Bridge Development | Legacy ERP interoperability captures South African automotive belt manufacturing demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with CTOs, HR technology procurement officers, regional systems integrators, and compliance officers across GCC and African enterprises; and secondary validation through SEC filings of listed software vendors, hyperscaler capex disclosures, and regulatory filings with South Africa's Information Regulator and Saudi Arabia's National Data Management Office. Bottom-up sizing of deployment volumes and top-down cross-check against aggregate procurement budgets enabled triangulation.
Forecast inputs encompassed deployment model segmentation across cloud, on-premise, and hybrid architectures; organization size tiers from mid-market to enterprise; vertical adoption patterns in healthcare, manufacturing, and retail; and regional regulatory cluster differentiation. CAGRs were derived through regression analysis of historical procurement velocity against biometric mandate implementation timelines and POPIA enforcement phases. Integration complexity and mobile penetration rates served as industry-specific forecast modifiers throughout the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by cloud-native specialists or accelerated NDMO audit timelines would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Rapid Application Development Market
Software & Services
Mind Mapping Software Market
Software & Services
Enterprise Content Management Software Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Business Email Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Proxy Services and Software Market
Software & Services
AR Remote Collaboration Software Market
Software & Services
Global Order Management Software Market
Software & Services
PCB Layout Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Test Automation Market
Software & Services
Adaptive Learning Software Market
Software & Services
Online Lottery Software Market