
 Contract Management Market | 2026-2036
Contract Management Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Management Market Intelligence
North American cloud infrastructure expansion is reconfiguring how contract management vendors distribute platform capacity across data residency zones. Icertis leverages enterprise-grade AI extraction to anchor its position in complex supply chain contracting. DocuSign CLM sustains broad market presence through deep e-signature integration and workflow continuity. Ironclad differentiates by specializing in legal-team-centric interface design that accelerates contract turnaround.
Contract management encompasses the systematic creation, negotiation, execution, and analysis of legally binding agreements through digital platforms that enforce version control, obligation tracking, and renewal alerts. Cloud-based deployment now dominates new implementations, while on-premise systems persist in highly regulated environments requiring localized data sovereignty. The corporate sector generates the largest volume of seats, though legal firms represent a concentrated margin pool where workflow automation commands premium pricing. Compliance management solutions are expanding fastest as GDPR, HIPAA, and sector-specific mandates multiply audit requirements across healthcare and financial services verticals.
FDA 21 CFR Part 11, HIPAA Security Rule, and EU GDPR shape product requirements by mandating electronic signature validity, access logging, and data portability across jurisdictions. The SEC's guidance on material contract disclosure further tightens visibility standards for publicly traded entities. Stakeholders must weigh data residency commitments against AI-enabled clause extraction capabilities when selecting platforms for multi-jurisdictional operations.
Market Dynamics
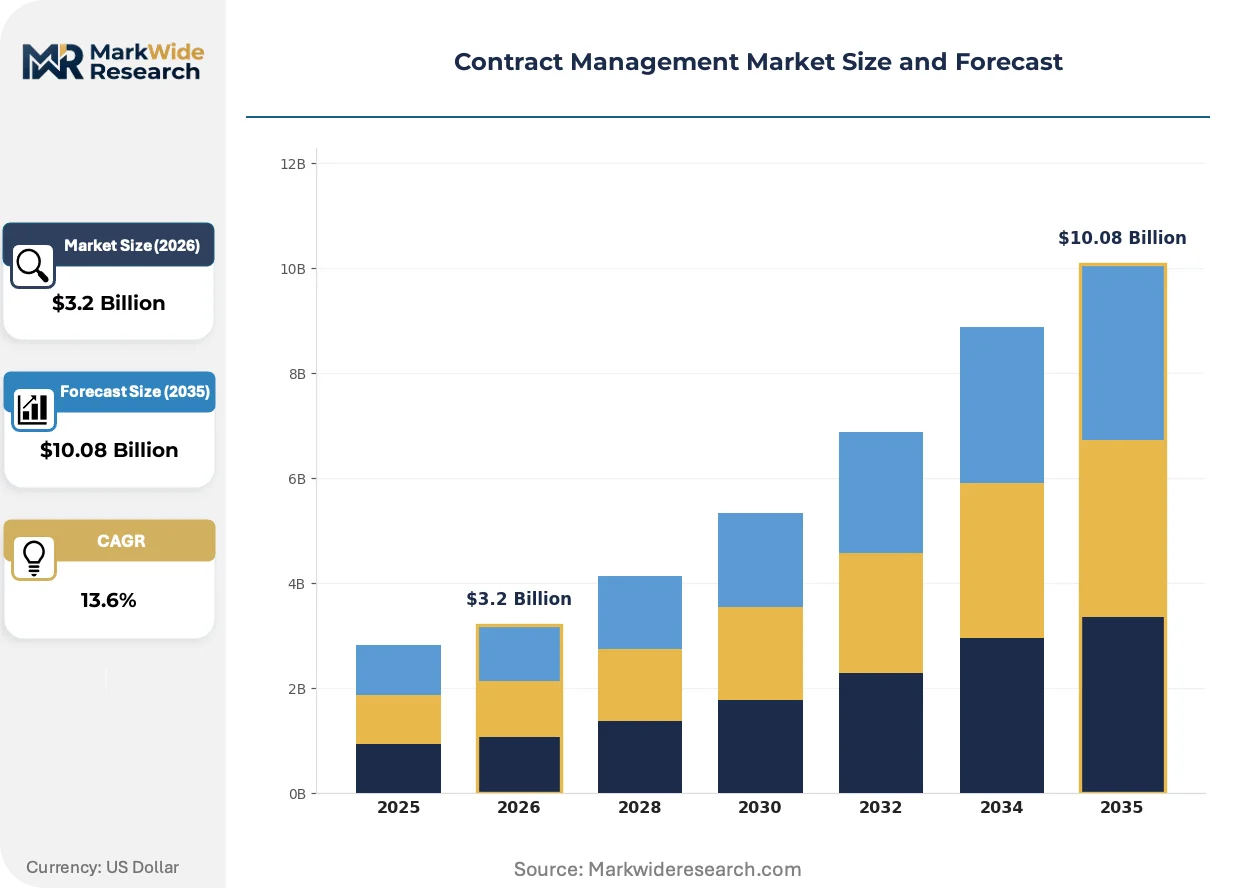
Cloud migration pressure is compressing deployment cycles for contract lifecycle platforms as healthcare and financial services organizations face audit mandates from HIPAA and SEC disclosure rules. This structural shift forces vendors to re-architect data residency and AI extraction capabilities simultaneously.
Growth Catalysts
- HIPAA Security Rule enforcement:Healthcare providers in the United States are accelerating digitization of supplier agreements to satisfy access logging and audit trail requirements.
- ISO 27001 certification demand:Enterprise procurement teams now require auditable digital infrastructure for third-party risk management and compliance verification.
- AI clause extraction:Natural language processing capabilities are automating obligation tracking and renewal alerts across complex supply chain portfolios.
Market Restraints
- Data sovereignty compliance costs:Multi-jurisdictional operations face fragmented requirements from GDPR, HIPAA, and sector-specific mandates that inflate platform architecture expenses.
- Legacy system integration friction:On-premise contract repositories in regulated industries resist cloud migration due to localized control requirements.
- Talent scarcity in legal-tech hybrid roles:Organizations struggle to staff teams combining contract domain expertise with platform administration skills.
Strategic Opportunities
- EU AI Act preparation:European enterprises require contract governance tools to document AI supplier liability and training data provenance.
- Mid-market legal department automation:Underpenetrated segments in Germany and France seek workflow solutions priced below enterprise tiers.
- Blockchain-anchored smart contracts:Convergence of distributed ledger technology with CLM platforms enables self-executing payment terms in supply agreements.
Industry Challenges
- SOC 2 Type II certification timelines:Vendors face 6-12 month audit windows that delay market entry for new platform entrants.
- Cross-border data transfer complexity:Schrems II rulings and adequacy decision uncertainty complicate EU-US contract data routing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Management Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $10.08 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Corporate Sector, Government Agencies, SMEs, Legal Firms Solution: Contract Drafting, Compliance Management, Reporting, Workflow Automation Industry Vertical: Manufacturing, Healthcare, Construction, Retail |
| Companies Covered | DocuSign CLM, LinkSquares, Sirion, Zefort, Juro, Ironclad, Agiloft, Conga Contracts, Icertis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Management Market Strategic Shifts & Innovations
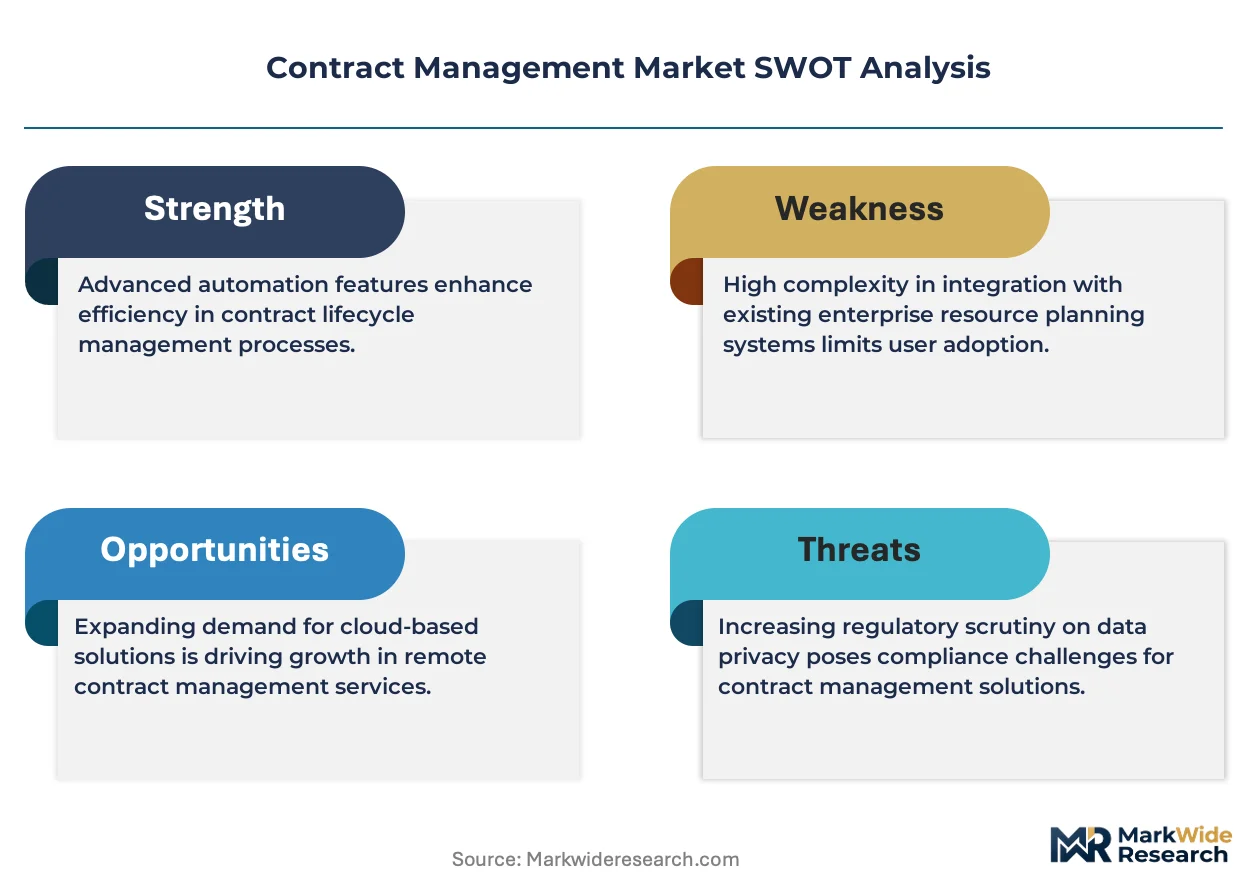
Generative AI is compressing contract drafting cycles while regulatory fragmentation multiplies compliance layer requirements. Platform vendors now compete on extraction accuracy and jurisdiction-specific rule engines rather than storage capacity.
Large language models trained on legal corpora are rendering obsolete manual clause comparison and redline generation. Corporate legal departments in the United States are deploying these tools for high-volume vendor agreements. The technology is rendering obsolete first-pass lawyer review for standard terms, compressing turnaround from days to hours.
EU GDPR Article 28 processor agreement requirements are mandating granular data processing documentation in cloud service contracts. SaaS vendors must now embed technical and organizational measures specifications directly into subscription agreements. Healthcare and financial services verticals in Germany and France are requiring dedicated data protection annexes with every renewal.
Enterprise buyers are consolidating contract visibility across procurement, legal, and finance functions through unified platform seats. Siloed point solutions for e-signature and repository management are losing share to integrated lifecycle suites. This consolidation pattern is most visible in United States federal contracting, where transparency mandates require cross-departmental audit access.
Contract Management Market Segmentation
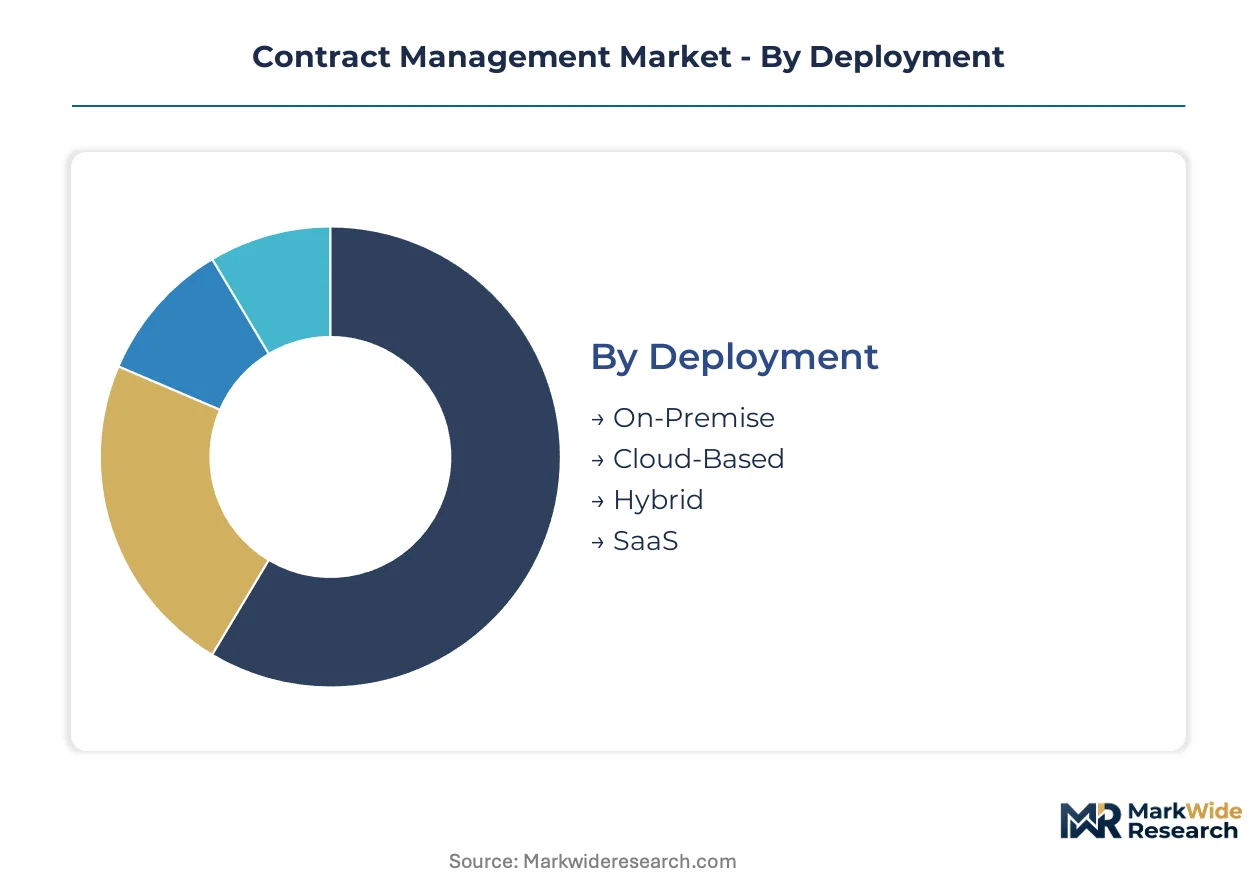
Contract management platforms fragment across deployment architectures, buyer sophistication, functional depth, and regulatory exposure. Understanding these divisions reveals where vendors must re-architect data residency, AI extraction capabilities, and pricing tiers to capture wallet share.
Deployment:
Use-case spectrum spans localized control for sovereign data requirements to fully managed cloud infrastructure for distributed teams.
- Cloud-Based:Multi-tenant architectures with automatic scaling now dominate new implementations. Healthcare providers in the United States select these platforms to satisfy HIPAA Security Rule audit trail mandates without capital expenditure.
- SaaS:Subscription delivery with embedded AI clause extraction accelerates deployment cycles. Corporate procurement teams favor this model for rapid supplier onboarding across multiple jurisdictions.
- On-Premise:Single-tenant installations persist in financial services where SEC disclosure rules require localized contract repositories.
- Hybrid:Split configurations anchor sensitive agreements on-site while routing routine workflows through cloud instances.
Established volume favors Cloud-Based; emerging adoption favors SaaS.
End User:
Customer type determines pricing tolerance, integration complexity, and sales cycle length across the market.
- Corporate Sector:Enterprise procurement and legal departments generate the largest seat volumes. These buyers demand unified lifecycle suites with cross-functional visibility.
- Legal Firms:Concentrated margin pool where workflow automation commands premium pricing. United States-based AmLaw 200 firms are deploying generative AI drafting tools to compress turnaround on vendor agreements.
- Government Agencies:Federal contracting transparency mandates in the United States require auditable version control and obligation tracking across departmental silos.
- SMEs:Underpenetrated segment seeking tiered solutions below enterprise price points, particularly in Germany and France.
Corporate Sector maintains dominant share; Legal Firms deliver steepest expansion trajectory.
Solution:
Functional modules compete on extraction accuracy and jurisdiction-specific rule engines rather than storage capacity alone.
- Compliance Management:Expanding most quickly as GDPR, HIPAA, and sector-specific mandates multiply audit requirements. Platforms embed technical and organizational measures specifications directly into agreement templates.
- Workflow Automation:Orchestrates approval routing, redline generation, and signature sequencing. Corporate legal departments deploy these tools to compress standard-term review from days to hours.
- Contract Drafting:Large language models trained on legal corpora now automate first-pass clause generation and comparison.
- Reporting:Cross-portfolio analytics on obligation status, renewal exposure, and counterparty risk concentration.
Compliance Management gains share fastest; Workflow Automation anchors renewal revenue.
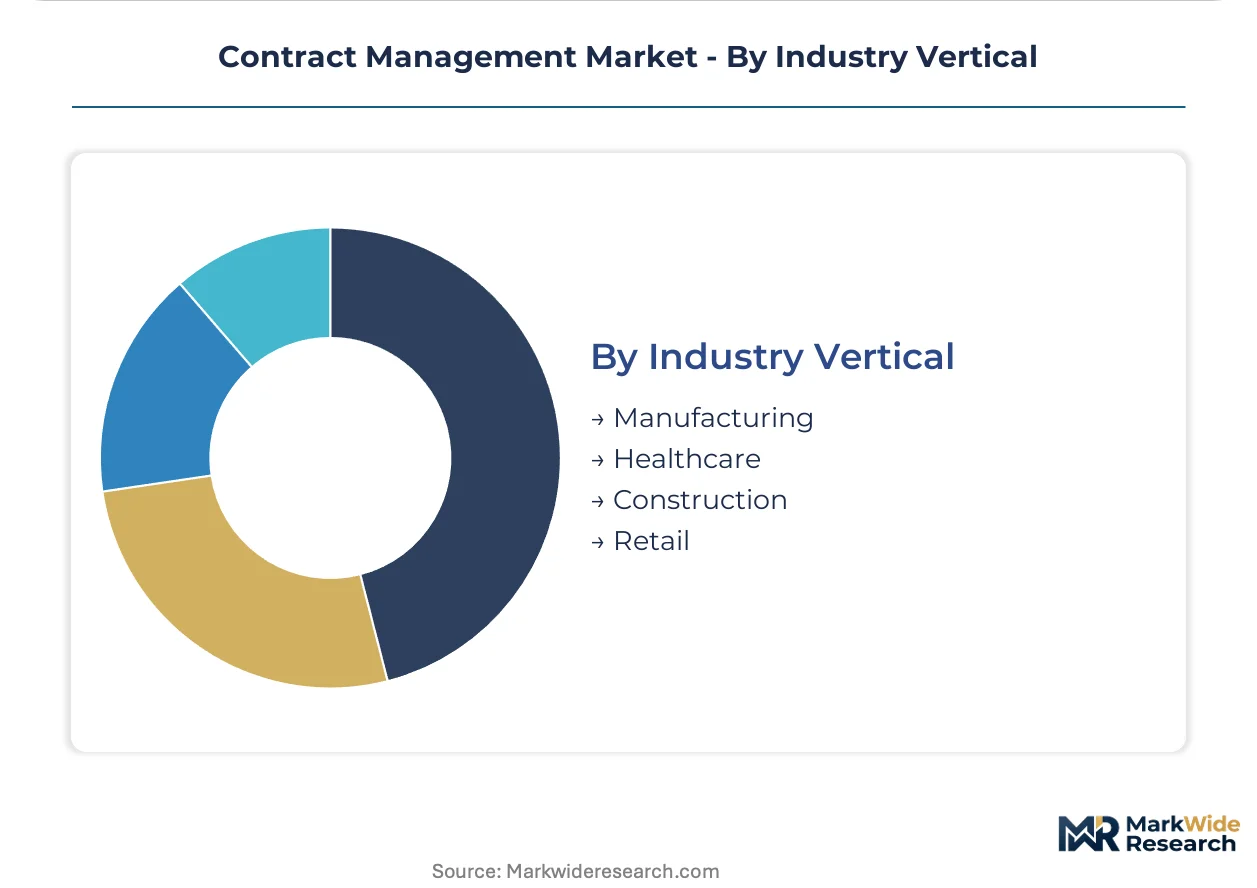
Industry Vertical:
Sector-specific regulatory frameworks dictate data residency commitments and certification requirements.
- Healthcare:HIPAA Security Rule and FDA 21 CFR Part 11 shape platform selection. Providers require electronic signature validity, access logging, and granular data processing documentation in every supplier agreement.
- Financial Services:SEC guidance on material contract disclosure tightens visibility standards. Firms maintain on-premise repositories for localized control over sensitive agreements.
- Manufacturing:Complex supply chain portfolios drive demand for AI-enabled obligation tracking and renewal alerts across multi-tier supplier networks.
- Construction:Project-based contracting with milestone-linked payment terms benefits from blockchain-anchored smart contract experimentation.
Healthcare leads regulatory-driven replacement cycles; Manufacturing scales seat deployment fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber cable networks landing in Virginia Beach and Marseille anchor the data residency architecture for contract management platforms serving multi-jurisdictional enterprises. These infrastructure nodes enable real-time clause extraction while satisfying divergent regulatory requirements across operating zones.
United States
Federal contracting transparency mandates and SEC disclosure rules drive enterprise procurement digitization. HIPAA Security Rule enforcement compels healthcare providers to deploy cloud-based platforms with auditable access logging. The Washington D.C.-Northern Virginia corridor concentrates federal contractor headquarters where compliance automation commands premium pricing.
Germany
EU AI Act preparation and GDPR Article 28 processor agreement requirements reshape supplier contracting workflows. The country's national data protection regulator enforces granular technical and organizational measures documentation. The Frankfurt-Rhine-Main financial cluster hosts compliance-heavy institutions maintaining hybrid cloud configurations for sensitive agreements.
United Kingdom
Post-Brexit regulatory divergence creates dual-track compliance obligations for multinational corporations. The Financial Conduct Authority tightens material contract visibility standards for listed entities. London's legal technology corridor attracts workflow automation vendors serving AmLaw 200 firms with generative AI drafting tools.
France
Healthcare vertical digitization accelerates under national hospital modernization programs requiring electronic signature validity. The country's national data protection regulator mandates dedicated data protection annexes in every cloud service renewal. The Paris-Saclay research cluster incubates blockchain-anchored smart contract pilots for construction milestone payments.
India
Enterprise procurement teams adopt SaaS delivery models for rapid supplier onboarding across multiple jurisdictions. The central bank's data localization guidelines influence platform architecture decisions for financial services contracts. The Bengaluru-Hyderabad technology corridor hosts delivery centers supporting global CLM implementations with legal-tech hybrid talent pools.
Contract Management Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with extraction engines and signature modules. The vendor base organizes around three strategic archetypes: enterprise-suite providers with cross-functional visibility, legal-team-centric workflow designers, and AI-native clause extraction engines. Consolidation pressure favors integrated lifecycle suites over siloed point solutions. Dominant competitive moves include strategic partnerships bridging data residency and AI capabilities, plus portfolio diversification into adjacent compliance automation.
Within the enterprise-suite tier, Icertis and DocuSign CLM occupy positions anchoring complex supply chain contracting and deep e-signature integration respectively. Ironclad exemplifies the legal-team-centric archetype with interface design specialization. These three California-based entities represent contrasting approaches to workflow continuity: AI extraction depth, signature ecosystem breadth, and legal-user experience precision.
| Leading Market Players |
|---|
| DocuSign CLM |
| LinkSquares |
| Sirion |
| Zefort |
| Juro |
| Ironclad |
| Agiloft |
| Conga Contracts |
| Icertis |
| Others |
Cost & Logistics Intelligence
Undercapacity in SOC 2 Type II audit capacity is compressing vendor certification timelines and inflating platform entry costs for new market entrants. This utilization squeeze simultaneously tightens pricing discipline among established providers and accelerates cloud infrastructure investment to capture unmet compliance demand.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with seat-based SaaS subscriptions scaling from mid-market legal departments to federal contractor headquarters. Price differentiation rests on AI extraction accuracy tiers and data residency certification levels, with HIPAA-compliant configurations commanding substantial premiums over standard cloud deployments. Pricing pressure stems from mid-market buyers in Germany and France demanding workflow solutions below enterprise thresholds. Corporate procurement teams exhibit highest price sensitivity, while legal firms absorbing generative AI drafting tools show lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration among hyperscale cloud providers anchors platform delivery, with Amazon Web Services, Microsoft Azure, and Google Cloud Platform holding dominant infrastructure capacity. Geographic supply concentration spans the United States, Ireland, and Singapore for primary data residency zones. Raw material dependencies center on GPU clusters for AI clause extraction, encrypted storage arrays, and transatlantic fiber capacity. Supply chain risk concentrates in single-source vulnerability for specialized legal corpus training data. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a defensive-moat story anchored by switching-cost entrenchment. Regulatory certification requirements and multi-year contract migration cycles embed customer relationships against displacement.
For Market Incumbents: Build switching-cost moats by embedding AI extraction engines deeply into client ERP systems and procurement workflows. Incumbents should deepen backward integration into specialized legal corpus training data to differentiate extraction accuracy. The threat of generative AI-native entrants with superior interface design demands preemptive UX investment. Certification maintenance in HIPAA and SOC 2 Type II anchors renewal revenue. For New Entrants and Emerging Players: France's mid-market legal automation gap offers the most penetrable white-space target, with national hospital modernization programs creating procurement urgency. New entrants should position workflow solutions priced below Icertis and DocuSign CLM enterprise tiers while embedding EU AI Act compliance documentation as a native feature. A channel partnership strategy with French systems integrators accelerates credibility without direct sales infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among AI-native clause extraction engines with embedded compliance rule engines. Long-term viability favors platforms demonstrating jurisdiction-specific regulatory entrenchment across three or more data residency zones. Acquisition targets should display concentrated legal-firm customer bases with workflow automation premium pricing. The signal to watch is EU AI Act liability documentation adoption rates among European enterprise buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified lifecycle suites displace siloed e-signature point solutions in federal contracting. |
| Strategic Partnership | Data residency commitments with Irish and Singaporean cloud zones satisfy GDPR Article 28 requirements. |
| Acquisition of Specialist Firm | Legal corpus training data providers anchor AI extraction accuracy differentiation. |
| Geographic Expansion | Frankfurt-Rhine-Main financial cluster penetration captures compliance-heavy hybrid cloud demand. |
| Product Launch | Blockchain-anchored smart contract modules enable self-executing construction milestone payments. |
Research Approach
Cross-validation between primary interviews with CLM platform executives and secondary validation through SEC 10-K disclosures anchors the qualitative findings. The report draws from conversations with procurement officers at healthcare systems, legal operations directors at AmLaw 200 firms, federal contracting compliance leads, and cloud infrastructure architects. Secondary sources include FDA 21 CFR Part 11 guidance documents, EU GDPR Article 28 processor agreement templates, and HIPAA Security Rule enforcement bulletins. Bottom-up seat deployment estimates triangulate against top-down enterprise IT spending allocations.
Calibration against historical cloud SaaS adoption curves and regulatory compliance investment cycles shapes the analytical framework. Segmentation dimensions span deployment architecture, end-user sophistication, functional module depth, and industry vertical regulatory exposure. CAGRs derive from elasticity modeling of procurement digitization rates against compliance mandate enforcement timelines. AI clause extraction accuracy improvement curves and data residency zone expansion patterns constitute key forecast inputs across the projection horizon.
Practitioners should monitor SOC 2 Type II certification backlog lengths and EU AI Act implementation guidance releases for early signals of vendor capacity constraints and compliance requirement shifts. Forecasts reflect assumptions regarding continued HIPAA enforcement intensity and SEC disclosure rule expansion. Quarterly review of federal contracting transparency mandate adoption rates and mid-market legal department automation penetration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Desktop Outsourcing Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market