
 Global Supply Chain Management BPO Market | 2026-2036
Global Supply Chain Management BPO Market Size, Share, and Industry Trends Forecast 2026-2036
Global Supply Chain Management BPO Market Foresight
Enterprise-grade service-level agreements are reorganizing competitive dynamics in supply chain BPO as buyers demand real-time visibility and predictive analytics integration. Accenture leverages its consulting heritage to anchor complex transformation programs across Fortune 500 manufacturing clients. Genpact sustains process excellence through proprietary Lean Digital methodologies that compress order-to-cash cycles. Tata Consultancy Services dominates India-origin delivery with scale advantages in multi-tower BPO engagements.
Supply chain management BPO encompasses the delegation of planning, procurement, logistics, and fulfillment operations to third-party specialists who deploy cloud-native platforms, API-driven integrations, and AI-augmented forecasting engines to optimize working capital and service levels. Procurement outsourcing commands the largest revenue pool due to direct spend leverage and supplier consolidation mandates, while cloud-based platforms represent the fastest-expanding deployment model as enterprises retire legacy ERP modules. Logistics management generates premium margins in pharmaceutical and consumer electronics verticals where temperature integrity and serialization compliance add complexity layers.
FDA validation requirements for pharmaceutical supply chain traceability and the EU AI Act's risk-classification framework for automated procurement decisions are tightening vendor qualification standards and extending contract diligence cycles. India's BIS certification for IT-enabled services and China's SAMR data-localization rules add jurisdictional compliance overhead for multi-country programs. Stakeholders must evaluate whether provider investments in generative AI and sovereign cloud architectures align with emerging regulatory enforcement patterns.
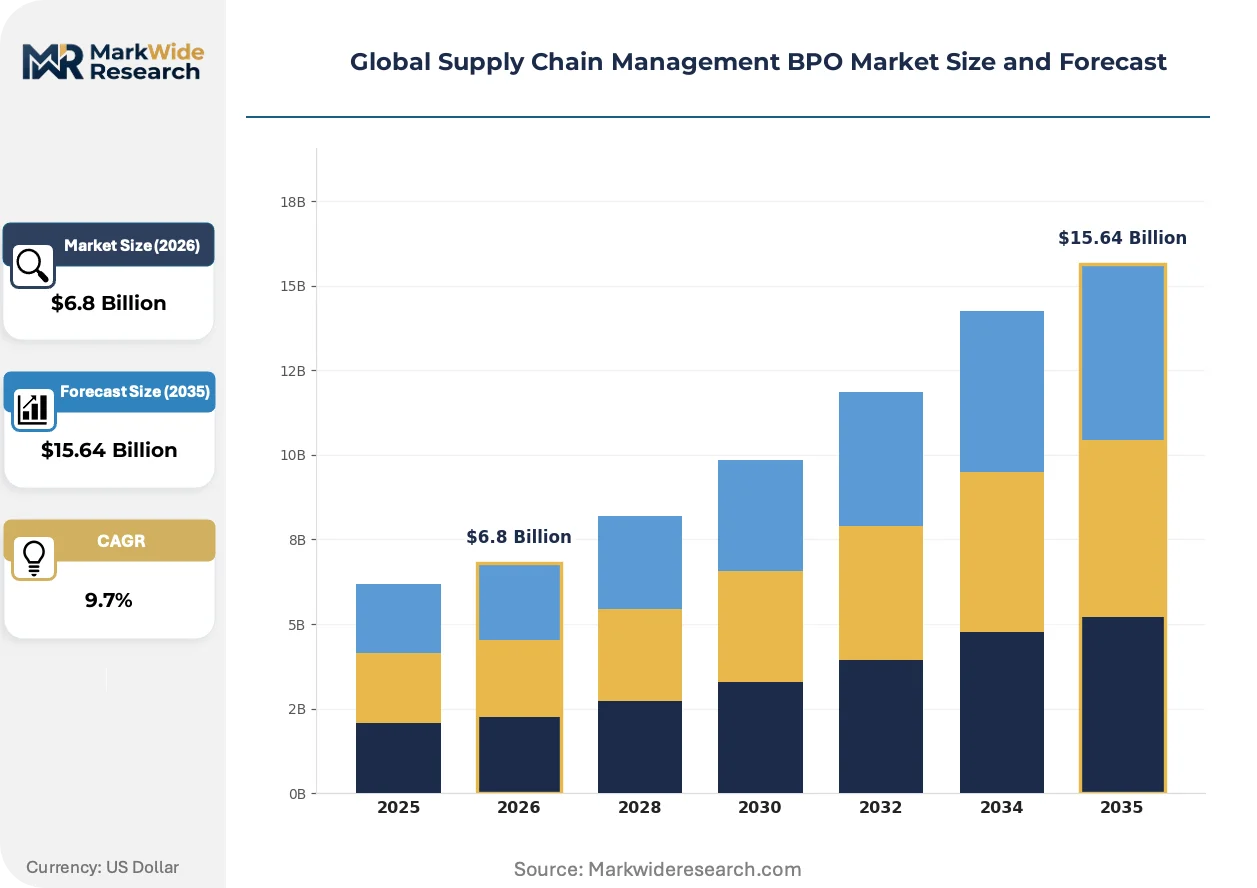
Market Dynamics
Generative AI deployment is fragmenting traditional process hierarchies in supply chain BPO, forcing providers to restructure talent models and platform architectures around autonomous decision engines rather than rule-based automation.
Growth Catalysts
- EU AI Act risk classification:Automated procurement systems face mandatory conformity assessments, creating specialized compliance service demand among European pharmaceutical and automotive manufacturers.
- Cold-chain logistics complexity:Temperature-sensitive biologics expansion drives outsourcing of serialization-tracked distribution networks with real-time monitoring capabilities.
- API-driven platform integration:Cloud-native middleware enables seamless ERP-to-TMS connectivity, compressing implementation timelines for multi-enterprise visibility programs.
Market Restraints
- Data localization mandates:China's SAMR requirements force redundant infrastructure deployment, elevating operational costs for cross-border programs.
- Specialized talent scarcity:Shortage of professionals combining supply chain domain expertise with machine learning implementation capabilities constrains scaling.
- Legacy system technical debt:Proprietary EDI protocols and custom ERP modules resist standard API migration, prolonging integration cycles.
Strategic Opportunities
- Sovereign cloud architectures:Germany's Gaia-X and India's MeitY-certified data centers enable compliant processing for defense and public sector contracts.
- Carbon accounting integration:EU CSRD scope 3 disclosure requirements position BPO providers as embedded emissions calculation partners for supplier networks.
- Generative AI-IoT convergence:Predictive maintenance models combining sensor telemetry with natural language processing unlock aftermarket service revenue streams.
Industry Challenges
- FDA validation timelines:Pharmaceutical traceability system qualification extends contract ramp periods by 8-14 months for 21 CFR Part 11 compliance.
- Cross-functional skill gaps:Procurement analysts lack sufficient fluency in Python-based forecasting tools, requiring expensive retraining or external hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Supply Chain Management BPO Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Procurement Outsourcing, Logistics Management, Inventory Management, Order Fulfillment, Customer Support Application: Demand Planning, Transportation Coordination, Warehouse Operations, Supplier Management, Risk Mitigation End User Industry: Manufacturing Enterprises, Retail Chains, Consumer Electronics, Pharmaceutical Companies, FMCG Corporations Deployment Model: On-Premise Solutions, Cloud-Based Platforms, Hybrid Infrastructure, Dedicated Hosting |
| Companies Covered | Accenture, IBM Corporation, Genpact, Capgemini, Tata Consultancy Services, Infosys, Wipro Limited, Cognizant, HCL Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Supply Chain Management BPO Market Shifts & Advancements
Agentic AI systems are reconfiguring how supply chain decisions get made, shifting authority from human analysts to autonomous software agents that negotiate supplier terms and reroute shipments without explicit approval workflows.
Large language models trained on procurement documentation and logistics exception patterns are fragmenting traditional category management roles. Pharmaceutical and aerospace buyers now pilot self-service contract generation tools that draft supplier agreements, flag regulatory non-compliance, and simulate total-cost-of-ownership scenarios. Tier-1 providers respond by reorganizing delivery teams around AI trainer and prompt engineer functions rather than transactional processors.
The EU AI Act's risk-based classification framework imposes documentation burdens on automated sourcing decisions affecting worker safety or critical infrastructure. High-risk procurement algorithms require human-in-the-loop architectures, algorithmic impact assessments, and CE-marking conformity procedures. German automotive manufacturers and French energy utilities accelerate provider vetting to secure compliant deployment timelines before enforcement phases activate.
Buyers now unbundle after-sales service contracts from core logistics agreements, selecting specialized providers for parts forecasting, field technician dispatch, and warranty claim processing. This disintermediation pressures integrated BPO operators to defend revenue through outcome-based performance guarantees rather than fixed-fee structures. Consumer electronics brands in South Korea and medical device manufacturers in Switzerland lead this decomposition trend.
Global Supply Chain Management BPO Market Segmentation
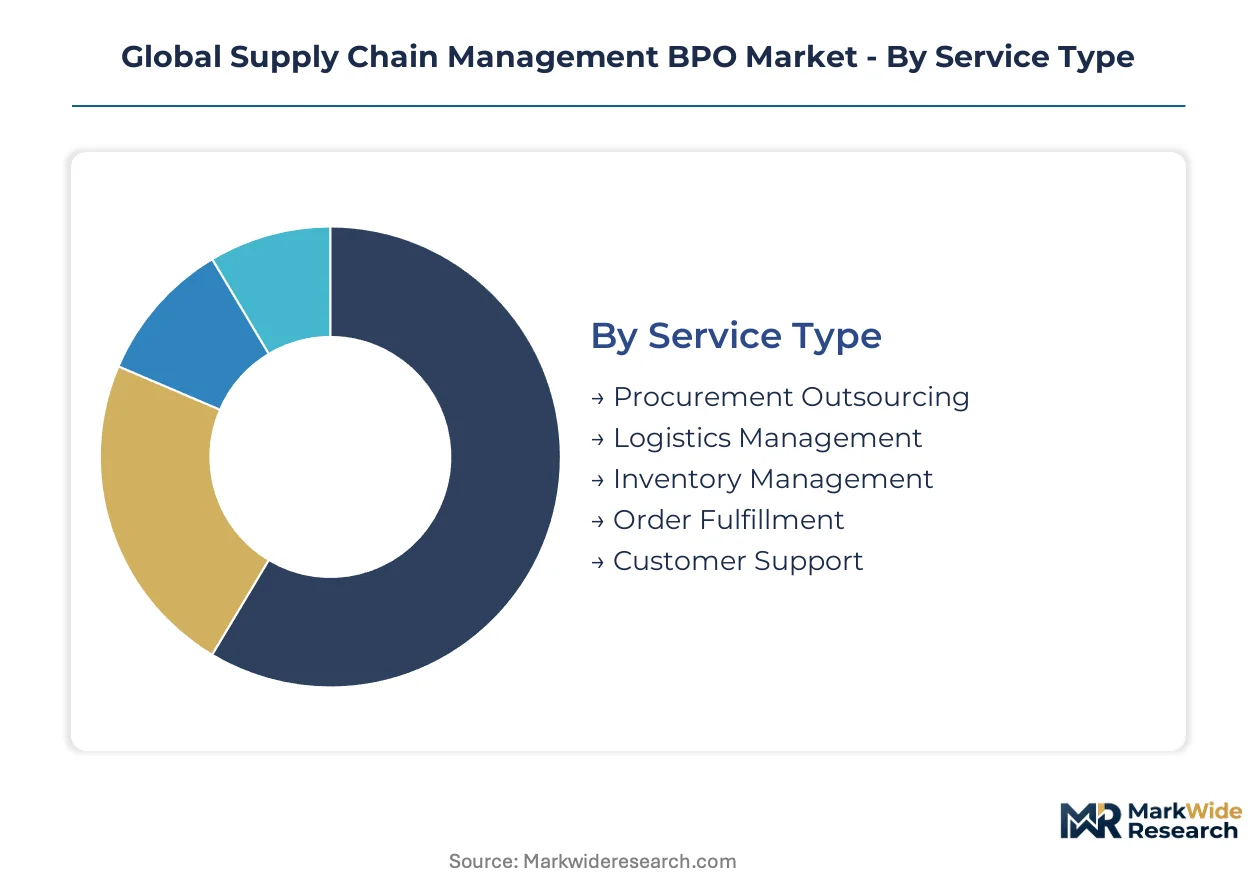
Supply chain BPO segmentation reveals how regulatory complexity and digital infrastructure investments reshape provider specialization. Buyers select segments based on compliance burden, integration maturity, and working capital sensitivity rather than cost alone.
Service Type:
FDA's 21 CFR Part 11 and the EU AI Act create divergent qualification requirements across service categories, with pharmaceutical traceability mandates elevating documentation standards for logistics and procurement functions.
- Procurement Outsourcing:Direct spend management and strategic sourcing powered by predictive analytics engines. Pharmaceutical and automotive manufacturers in Germany and France concentrate demand here as EU AI Act conformity assessments force algorithmic transparency investments.
- Logistics Management:Temperature-controlled distribution networks with serialization tracking for biologics and consumer electronics. India's cold-chain infrastructure expansion and China's SAMR data-localization rules drive provider facility investments in Mumbai and Shanghai.
- Inventory Management:Multi-echelon optimization balancing service levels against carrying costs.
- Order Fulfillment:Omnichannel orchestration spanning warehouse management systems and last-mile delivery networks.
- Customer Support:Post-sales service desk operations including warranty claims and field technician dispatch.
Procurement Outsourcing handles the majority of throughput; Logistics Management is the fastest mover on share.
Application:
Cost tier differentiation separates transactional coordination from predictive optimization, with premium pricing attaching to AI-augmented decision layers.
- Demand Planning:Statistical forecasting models integrating external signals from commodity markets and weather patterns. Retail chains in the United States and FMCG corporations in India deploy these systems to compress forecast error rates.
- Transportation Coordination:Multi-modal routing optimization with real-time visibility across ocean, air, and ground freight. EU CSRD scope 3 disclosure requirements embed carbon accounting into carrier selection algorithms.
- Warehouse Operations:Automated storage and retrieval systems with robotics integration.
- Supplier Management:Qualification workflows and performance scorecards.
- Risk Mitigation:Contingency planning for geopolitical disruption and supplier insolvency.
Demand Planning commands the highest contract values; Transportation Coordination is expanding most quickly as emissions tracking becomes mandatory.
End User Industry:
Volume concentration in manufacturing reflects procurement scale, while margin premiums concentrate in regulated verticals with compliance overhead.
- Manufacturing Enterprises:Heavy industry and industrial equipment producers with complex BOM structures and supplier networks. German automotive manufacturers and Japanese machinery builders anchor contract values through multi-tower engagements.
- Pharmaceutical Companies:Serialization-tracked cold-chain distribution for temperature-sensitive biologics. FDA validation timelines and EU Falsified Medicines Directive enforcement extend implementation cycles.
- Retail Chains:Omnichannel fulfillment and seasonal demand volatility management.
- Consumer Electronics:High-velocity inventory turns with rapid obsolescence windows.
- FMCG Corporations:Route-to-market optimization for distributed retail networks.
Manufacturing Enterprises handles the majority of throughput; Pharmaceutical Companies is climbing the fastest as biologics expansion accelerates.
Deployment Model:
Customer type separates legacy enterprises with technical debt from cloud-native entrants seeking API-first architectures.
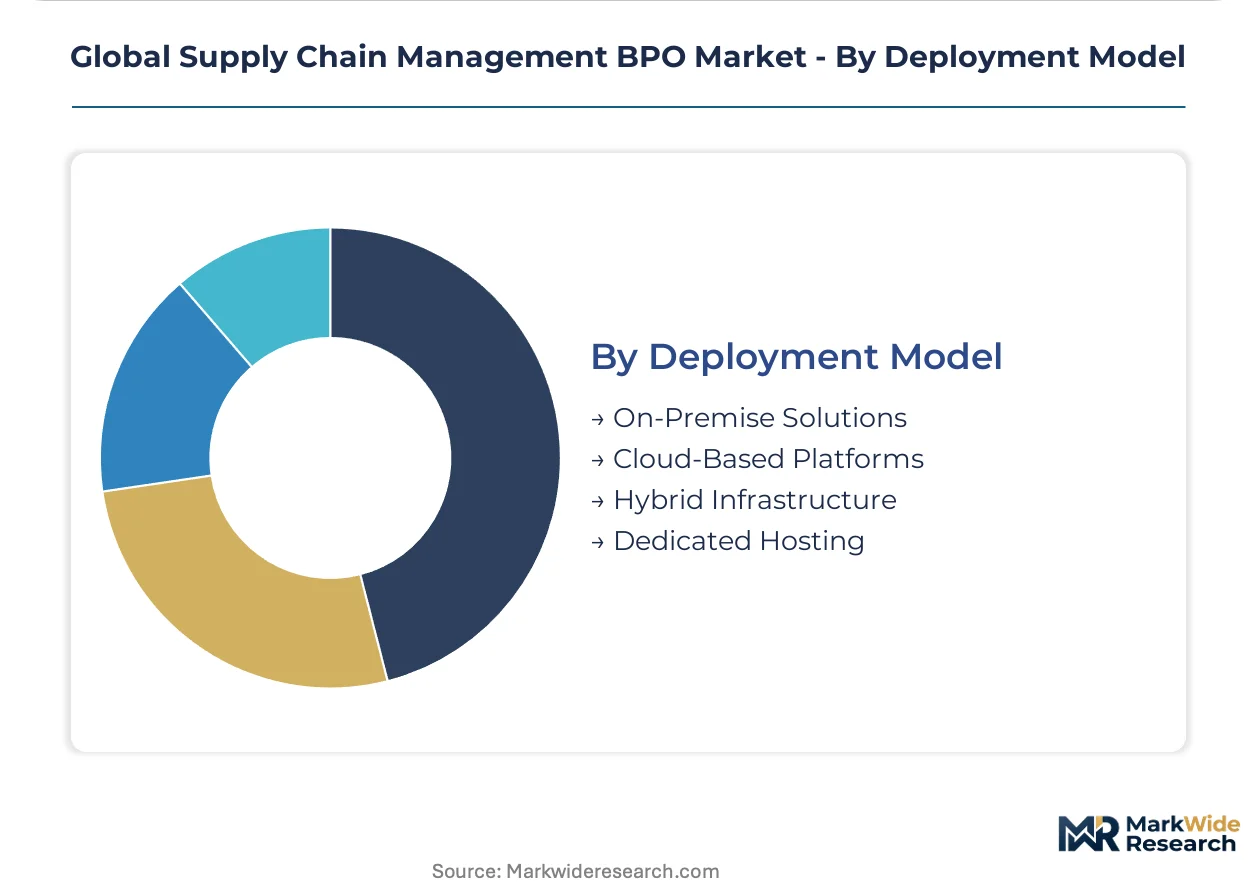
- Cloud-Based Platforms:API-driven middleware with elastic scaling and continuous deployment pipelines. India's MeitY-certified data centers and Germany's Gaia-X infrastructure enable sovereign processing for defense and public sector contracts.
- Hybrid Infrastructure:Segregated workloads with sensitive data on-premise and analytics in cloud environments. China's SAMR data-localization requirements force this architecture for cross-border programs.
- On-Premise Solutions:Legacy ERP-integrated systems in regulated industries with validation requirements.
- Dedicated Hosting:Single-tenant environments for security-sensitive operations.
Cloud-Based Platforms handles the majority of new deployments; Hybrid Infrastructure is gaining share fastest as data sovereignty mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances between manufacturing hubs and consumption centers are accelerating supply chain BPO demand as enterprises seek external expertise to manage cross-border complexity. The United States, Germany, India, China, and United Kingdom concentrate the majority of procurement outsourcing contracts, driven by pharmaceutical serialization mandates and automotive just-in-time requirements.
United States
FDA's 21 CFR Part 11 validation requirements and pharmaceutical traceability mandates drive cold-chain logistics outsourcing. The EPA's evolving emissions disclosure rules embed carbon accounting into transportation procurement decisions. New Jersey and Massachusetts pharmaceutical corridors anchor serialization-tracked distribution network investments from specialized BPO providers.
Germany
EU AI Act conformity assessments for automated procurement systems create specialized compliance service demand among automotive and industrial equipment manufacturers. The KBA and Gaia-X sovereign cloud infrastructure enable compliant processing for defense and public sector supply chain contracts. Bavaria's automotive supplier ecosystem concentrates multi-tower BPO engagements with predictive analytics integration.
India
MeitY-certified data centers and BIS certification for IT-enabled services position Mumbai and Bangalore as delivery hubs for pharmaceutical and FMCG procurement outsourcing. Cost arbitrage advantages combine with digital infrastructure investments to capture order-to-cash cycle compression contracts. Telangana's Hyderabad corridor attracts logistics management BPO for temperature-sensitive biologics distribution.
China
SAMR data-localization requirements force redundant infrastructure deployment for cross-border programs, elevating operational costs but creating captive market opportunities. Dual carbon goals and MIIT industrial internet standards reshape supplier qualification workflows. Shanghai's Yangtze River Delta manufacturing belt concentrates hybrid cloud deployments for hybrid infrastructure compliance.
United Kingdom
Post-Brexit customs complexity and MHRA pharmaceutical serialization requirements drive demand for trade compliance and cold-chain logistics outsourcing. The FCA's operational resilience expectations extend to supply chain continuity planning services. London's financial services corridor anchors procurement BPO for institutional investor ESG due diligence and scope 3 emissions calculation.
Global Supply Chain Management BPO Market Competitive Landscape
Listed leaders compete with private specialists across capital access and client intimacy dimensions, producing a tiered structure where scale advantages concentrate in consulting-origin providers while niche compliance expertise fragments among boutique operators. Three archetypes dominate: consulting-heritage integrators anchoring transformation programs, India-origin scale players capturing multi-tower engagements, and specialized logistics operators defending pharmaceutical cold-chain margins. Competitive moves center on generative AI platform investments and sovereign cloud infrastructure certifications to preempt regulatory enforcement patterns.
Within the consulting-heritage tier, Accenture and Capgemini exemplify providers leveraging advisory capabilities to anchor complex Fortune 500 manufacturing engagements. Among India-origin scale operators, Tata Consultancy Services and Infosys occupy positions defending multi-tower BPO market share through MeitY-certified delivery infrastructure. Genpact represents the process excellence archetype, sustaining competitive position through proprietary Lean Digital methodologies that compress working capital cycles for pharmaceutical and consumer electronics verticals.
| Leading Market Players |
|---|
| Accenture |
| IBM Corporation |
| Genpact |
| Capgemini |
| Tata Consultancy Services |
| Infosys |
| Wipro Limited |
| Cognizant |
| HCL Technologies |
| Others |
Supply & Pricing Matrix
Ninety-day implementation cycles for FDA-validated traceability systems compress margin structures for pharmaceutical logistics providers while amplifying pricing power for specialized cold-chain operators with pre-certified infrastructure. This lead-time differential separates premium-tier BPO contracts anchored in Mumbai and Hyderabad from standard procurement engagements competing on cost arbitrage alone.
Pricing Analysis
Industrial OEM buyers anchor a hybrid pricing structure blending per-transaction fees for procurement execution with outcome-based premiums tied to working capital reduction metrics. Price differentiation hinges on EU AI Act compliance certification and after-sales service bundling, with German automotive manufacturers showing lowest price sensitivity due to regulatory non-negotiability. Cost compression in standard-tier logistics management is intensifying because India's BIS-certified providers expand capacity, while premium pharmaceutical cold-chain contracts defend margins through FDA validation scarcity.
Supply Chain Analysis
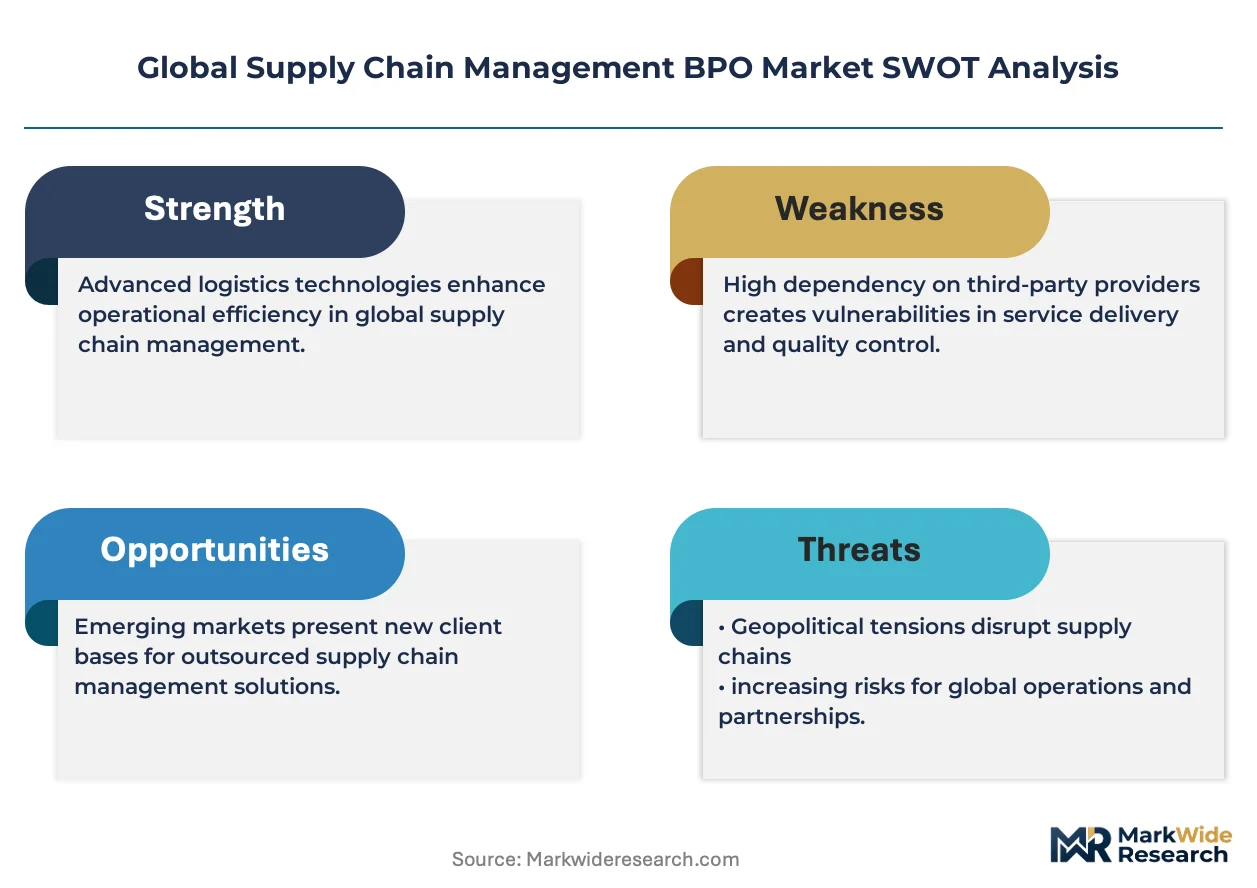
Inventory velocity for serialization-tracked biologics rests on redundant facility deployment across India, China, and Germany to satisfy data-localization and sovereign processing mandates. Provider infrastructure draws from MeitY-certified data centers, SAMR-compliant hybrid cloud architectures, and Gaia-X sovereign nodes. Single-source vulnerability concentrates in specialized temperature-monitoring sensor supply. Distribution runs through API-driven middleware layers connecting enterprise ERP systems to last-mile visibility platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates structural switching costs that extend contract tenures and elevate renewal rates for compliant operators.
For Market Incumbents: Shield margin structures by deepening backward integration into sovereign cloud infrastructure certifications before EU AI Act enforcement phases activate. Prioritize capacity addition in Telangana's Hyderabad corridor to capture biologics distribution demand. Counter emerging API-native platform entrants through outcome-based performance guarantees that embed carbon accounting and scope 3 disclosure capabilities. For New Entrants and Emerging Players: BIS certification fast-tracks for IT-enabled services unlock penetration into Mumbai's pharmaceutical procurement outsourcing cluster. White-space targets concentrate in aftermarket service contract unbundling for South Korean consumer electronics brands and Swiss medical device manufacturers. Go-to-market positioning centers on generative AI-IoT convergence for predictive maintenance revenue streams. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-entrenchment play because regulatory validation timelines create captive demand for pre-certified infrastructure. Acquisition targets cluster around boutique cold-chain operators with FDA 21 CFR Part 11 qualification and EU Falsified Medicines Directive serialization capabilities. Watch EU AI Act high-risk system enforcement activation as inflection signal for compliance service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | MeitY and Gaia-X certifications unlock defense and public sector contract eligibility in India and Germany. |
| Generative AI Platform Integration | Autonomous procurement agents reconfigure delivery teams around AI trainer functions rather than transactional processors. |
| Cold-Chain Infrastructure Expansion | Temperature-controlled serialization networks capture biologics distribution margins as FDA validation extends implementation cycles. |
| Carbon Accounting Service Embedding | EU CSRD scope 3 disclosure requirements position BPO providers as embedded emissions calculation partners. |
| API-Driven Middleware Development | Cloud-native ERP-to-TMS connectivity compresses multi-enterprise visibility program timelines for manufacturing clients. |
Research Methodology
Cross-validation between supply chain operations executives and regulatory compliance officers anchors the qualitative findings, with secondary validation drawing from FDA 21 CFR Part 11 guidance documents, EU AI Act implementation texts, and BIS certification registries. Primary fieldwork encompassed procurement directors at German automotive manufacturers, pharmaceutical logistics managers in New Jersey and Massachusetts corridors, and BPO delivery heads at India-origin scale operators. Bottom-up contract value analysis triangulates against top-down market sizing derived from IT-enabled services trade data and hyperscaler cloud infrastructure disclosures.
Sensitivity analysis across deployment model adoption curves and regulatory enforcement timelines shapes the analytical framework over the projection horizon. Segmentation dimensions span service type, application function, end-user industry vertical, and deployment architecture complexity. CAGRs derive from weighted scenario modeling across pharmaceutical serialization mandate acceleration, EU AI Act risk-classification rollout, and cloud-native platform replacement cycles for legacy ERP modules. Forecast inputs incorporate cold-chain infrastructure investment flows and sovereign data center certification velocity.
Underlying assumptions cover regulatory enforcement consistency and API standardization momentum, with deviation risk concentrated in SAMR data-localization rule expansion and FDA validation timeline extension. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
Middleoffice BPO Services Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
US Managed Print Services Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market