
 Global Insurance Business Process Outsourcing (BPO) Market | 2026-2036
Global Insurance Business Process Outsourcing (BPO) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insurance Business Process Outsourcing (BPO) Market Outlook
Modular service bundling is rebalancing how insurers procure BPO capabilities, shifting from monolithic contracts toward componentized engagements where claims processing, policy administration, and underwriting support can be sourced independently. Wipro leverages its India-based delivery network to anchor large-scale policy administration contracts for North American carriers. Genpact differentiates through domain-specific AI tools embedded within claims workflows. Accenture competes by extending consulting-led transformation programs that integrate BPO with broader digital modernization.
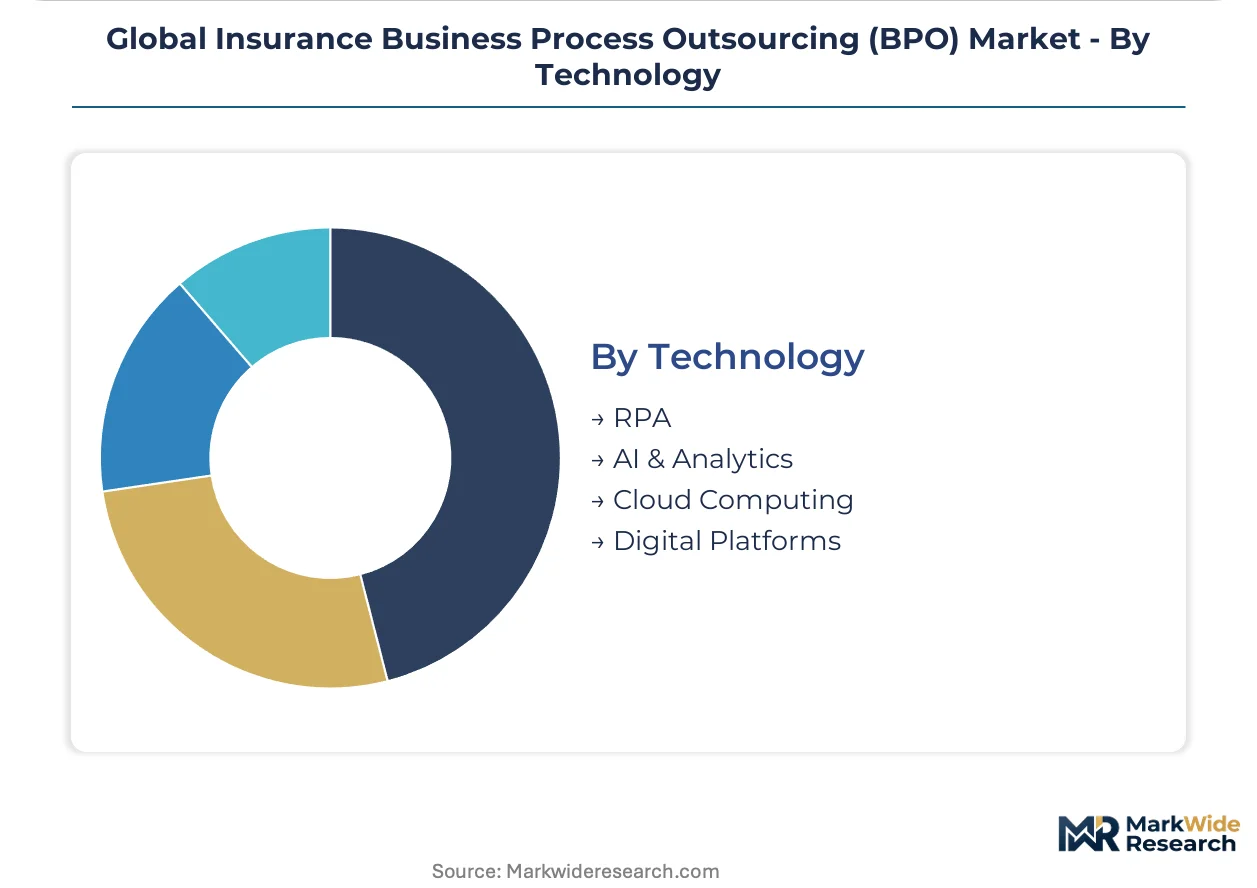
Insurance Business Process Outsourcing denotes the delegation of operational functions—claims processing, policy administration, customer support, and underwriting services—to third-party providers, typically governed by service-level agreements specifying turnaround times, accuracy rates, and regulatory compliance thresholds. Its primary purpose is to reduce operational expenditure while enabling insurers to scale capacity without proportional headcount expansion. Claims processing occupies the largest service type segment due to volume intensity and complexity-driven margin pools, while AI and Analytics within the technology segment represents the fastest-growing category as carriers demand predictive models for fraud detection and risk scoring. The hybrid delivery model is gaining structural prominence as clients seek cost arbitrage from offshore locations combined with onshore regulatory proximity.
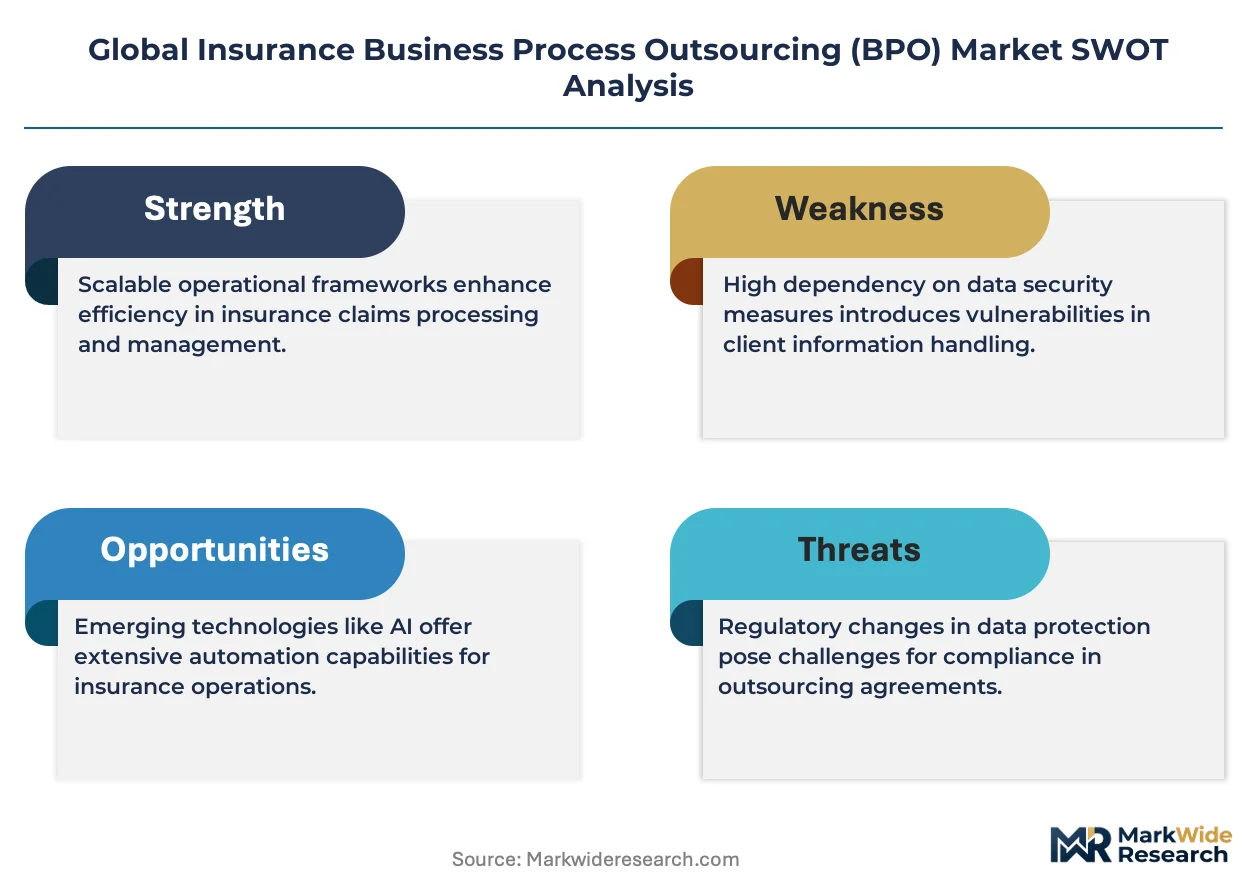
The US National Association of Insurance Commissioners coordinates state-level standards that directly influence BPO provider licensing and data handling protocols, while India's IRDAI mandates specific custodial requirements for outsourced policy records affecting vendor qualification. The EU's GDPR and emerging AI Act frameworks impose cross-border data governance obligations that reshape contract structuring for European insurance BPO relationships. Stakeholders must monitor evolving algorithmic accountability requirements as regulators scrutinize automated underwriting and claims decisions.
Market Dynamics
Cloud migration and AI integration are compressing vendor selection cycles as insurers demand predictive capabilities embedded directly into operational workflows rather than layered atop legacy systems.
Growth Catalysts
- GDPR and EU AI Act compliance requirements:European carriers are outsourcing data governance and algorithmic accountability functions to specialized BPO providers with established cross-border protocols.
- Claims adjudication automation:Life and annuity insurers are expanding contracts for AI-enabled fraud detection and straight-through processing to reduce loss adjustment expenses.
- India's IRDAI custodial mandates:The regulatory framework for outsourced policy records is driving carrier demand for India-based vendors with certified data vault infrastructure.
Market Restraints
- Offshore wage inflation in Indian tier-1 cities:Bangalore and Hyderabad delivery centers face 12-15% annual cost escalation, eroding the historical labor arbitrage that anchored initial outsourcing decisions.
- US state-by-state licensing fragmentation:The National Association of Insurance Commissioners lacks unified BPO provider standards, forcing vendors to maintain 50 separate compliance certifications.
- Legacy system API limitations:Core administration platforms from the 1990s lack modern integration endpoints, constraining real-time data exchange with external service providers.
Strategic Opportunities
- Underpenetrated UK Lloyd's syndicate market:Specialty and commercial insurers in London represent a white space for claims TPA services with marine and aviation domain expertise.
- Convergence of RPA and generative AI:Vendors combining robotic process automation with large language models can displace traditional document extraction workflows in underwriting support.
- Outcome-based pricing models:Carriers in the United States are piloting contracts tied to claims cost reduction rather than per-transaction fees, opening margin expansion for high-performance providers.
Industry Challenges
- Actuarial-technology hybrid talent scarcity:BPO providers struggle to recruit professionals who combine insurance domain knowledge with Python and cloud architecture skills.
- Multi-year system integration timelines:Policy administration migrations typically require 18-24 months, creating revenue recognition delays and client retention risk during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insurance Business Process Outsourcing (BPO) Market |
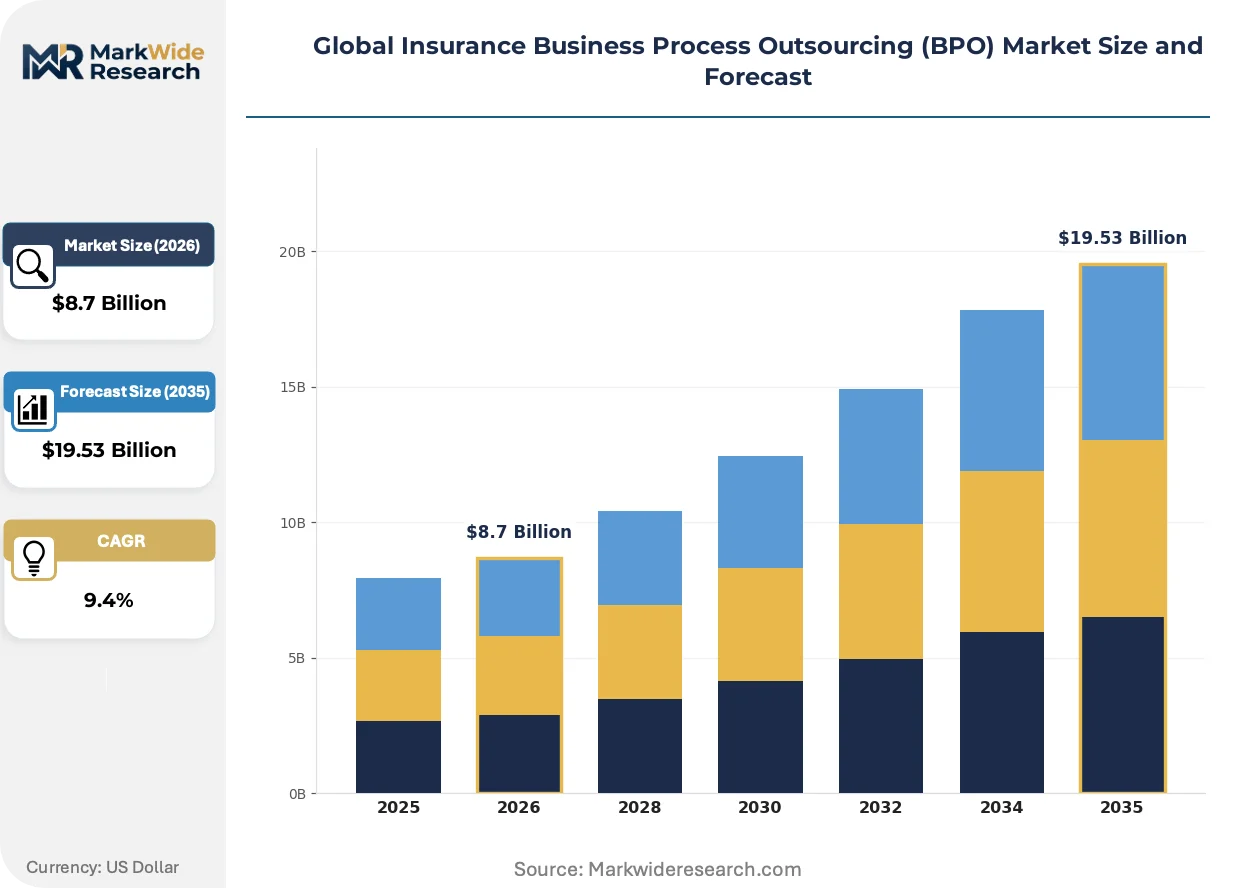
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Processing, Policy Administration, Customer Support, Underwriting Services Client Type: Insurance Companies, Brokers, Agents, Reinsurers Delivery Model: Onshore, Offshore, Nearshore, Hybrid Technology: RPA, AI & Analytics, Cloud Computing, Digital Platforms |
| Companies Covered | Wipro, Infosys, Accenture, WNS Global Services, Tata Consultancy Services, Genpact, Capgemini, DXC Technology, Cognizant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insurance Business Process Outsourcing (BPO) Market Strategic Shifts
Operational technology stacks are converging around embedded AI and API-first architectures, displacing the service-layer separation that defined traditional outsourcing relationships.
Intelligent document processing is consolidating fragmented data extraction workflows across claims intake and underwriting submission channels. Mid-market property-casualty carriers in the United States are deploying these tools at scale, compressing the traditional three-day document review cycle into hours while reducing manual indexing headcount.
The EU AI Act's risk classification framework for automated decision-making is forcing contract restructuring across European insurance BPO relationships. Vendors must now maintain algorithmic audit trails and human-in-the-loop protocols for claims triage and underwriting support functions, with French and German carriers leading compliance implementation.
Carrier procurement teams are unbundling monolithic BPO contracts into componentized engagements for claims, policy administration, and customer service. Large North American insurers now run separate RFP processes for each function, enabling best-of-breed vendor selection and compressing incumbent contract renewal rates.
Global Insurance Business Process Outsourcing (BPO) Market Segmentation
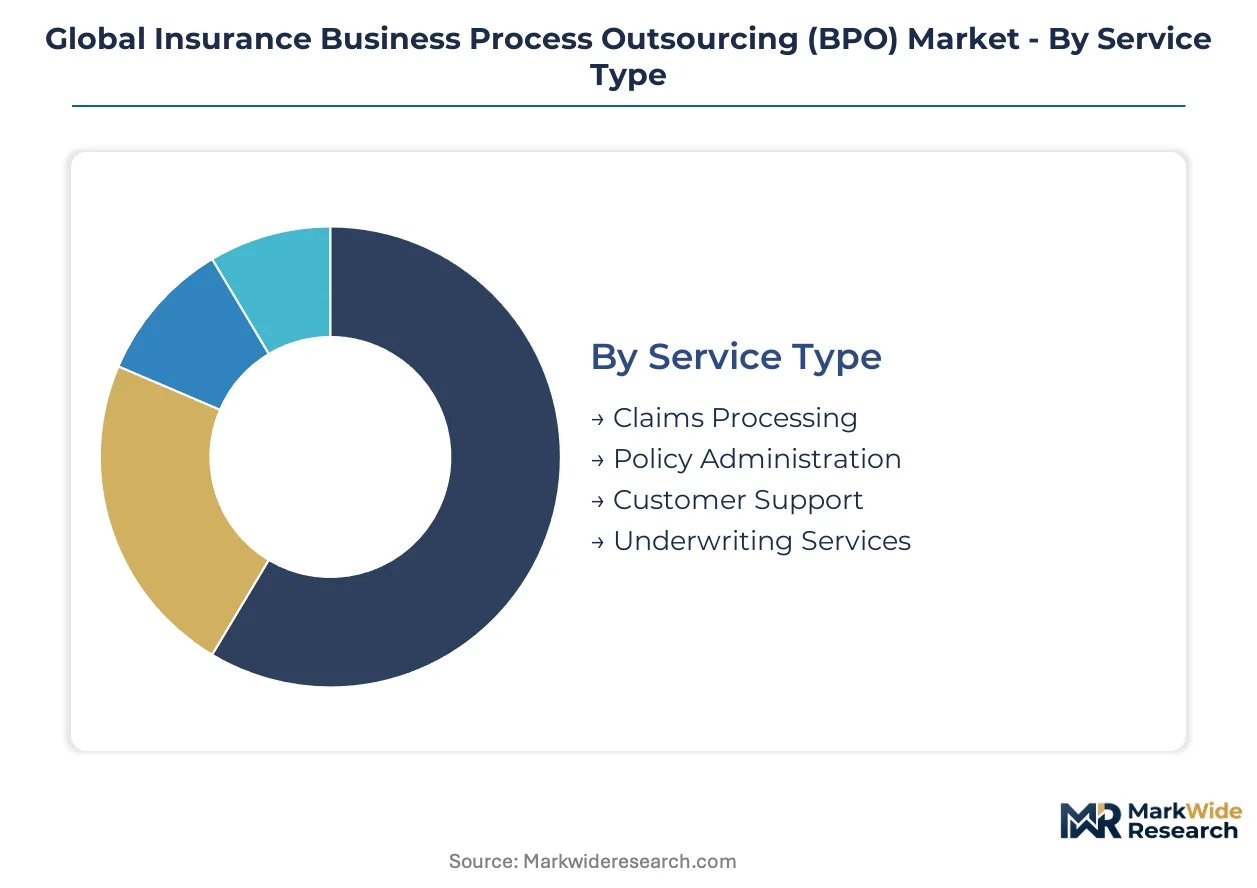
Segmentation in insurance BPO reveals how procurement teams unbundle monolithic contracts into discrete capability purchases. Vendor positioning and pricing power vary dramatically across these dimensions.
Service Type:
Standardization potential spans from highly codified transaction processing to judgment-intensive advisory functions.
- Claims Processing:High-volume transaction workflows encompassing first notice of loss, adjudication, and settlement disbursement. Life and annuity carriers in the United States concentrate demand here as loss adjustment expense reduction becomes a board-level priority.
- Policy Administration:End-to-end policy lifecycle management from issuance through renewal and endorsement processing. India's IRDAI custodial mandates are driving carrier demand for certified data vault infrastructure in this segment.
- Customer Support:Inbound inquiry handling, policy servicing requests, and complaint resolution through voice and digital channels.
- Underwriting Services:Risk assessment support, submission triage, and pricing model maintenance requiring actuarial-technology hybrid skills.
Most installed capacity flows through Claims Processing. Expansion is steepest in Policy Administration.
Client Type:
Buyer sophistication and contract scale correlate with balance sheet size and regulatory complexity exposure.
- Insurance Companies:Primary carriers with direct policyholder relationships and full regulatory licensing requirements. Property-casualty writers in the United States dominate contract value as they seek operational leverage without proportional headcount expansion.
- Reinsurers:Capacity providers assuming risk from primary carriers through treaty and facultative arrangements. Lloyd's syndicates in London represent underpenetrated white space for specialty claims expertise.
- Brokers:Intermediaries facilitating coverage placement and policy servicing on behalf of insureds.
- Agents:Appointed representatives with limited binding authority and localized customer relationships.
Contract concentration sits with Insurance Companies. Reinsurers are gaining share fastest.
Delivery Model:
Geographic configuration balances labor arbitrage against regulatory proximity and data sovereignty constraints.
- Offshore:Delivery from lower-cost jurisdictions, primarily India, for rules-based processing without customer-facing requirements. Bangalore and Hyderabad centers face wage inflation eroding historical cost advantages.
- Hybrid:Blended onshore-offshore structures combining cost arbitrage with regulatory proximity. GDPR and EU AI Act compliance requirements are accelerating carrier migration to this model for European operations.
- Onshore:Domestic delivery eliminating cross-border data transfer complexity but at premium cost structures.
- Nearshore:Regional delivery from adjacent time zones, typically Latin America for US carriers or Eastern Europe for UK and EU clients.
Hybrid deployments command the largest share of new contract awards. Nearshore is climbing the fastest.
Technology:
Technology segmentation tracks automation maturity from deterministic rules engines to probabilistic AI systems.
- AI & Analytics:Predictive models for fraud detection, risk scoring, and claims triage requiring algorithmic audit trails. French and German carriers lead EU AI Act compliance implementation in this segment.
- RPA:Robotic process automation for structured data extraction and repetitive workflow execution. Mid-market property-casualty carriers in the United States deploy these tools at scale.
- Cloud Computing:Infrastructure-as-a-service and platform migrations displacing on-premise legacy systems.
- Digital Platforms:Integrated customer-facing portals and agent workstations with embedded self-service capabilities.
RPA retains the largest installed base. AI & Analytics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The insurance BPO industry traces its modern scale to India, where policy administration outsourcing first achieved industrial density during the 1990s liberalization era. From this origin, delivery networks now span three continents with distinct regulatory and labor market characteristics.
United States
Property-casualty carriers in the United States drive contract value for claims adjudication and policy servicing. The National Association of Insurance Commissioners maintains state-by-state licensing requirements that fragment vendor compliance obligations. Delivery clusters concentrate in Texas and Florida, where hurricane exposure generates sustained demand for catastrophe claims processing capacity.
India
Life and annuity insurers from North America anchor the largest policy administration contracts in Bangalore and Hyderabad. The Insurance Regulatory and Development Authority of India mandates custodial infrastructure standards for outsourced records that shape vendor qualification. Wage inflation in tier-1 cities now erodes the historical arbitrage that attracted initial investment.
United Kingdom
Lloyd's syndicates and specialty commercial insurers in London represent underpenetrated white space for marine and aviation claims expertise. The Prudential Regulation Authority and Financial Conduct Authority impose operational resilience requirements that favor hybrid delivery models. Manchester and Birmingham have emerged as secondary hubs for back-office processing serving London-headquartered carriers.
Germany
French and German carriers lead EU AI Act compliance implementation for algorithmic audit trails in automated underwriting. The Federal Financial Supervisory Authority enforces strict data localization preferences that constrain pure offshore arrangements. Frankfurt's insurance technology cluster supports regulatory technology vendors embedding compliance tooling into BPO workflows.
Canada
Mid-market property-casualty writers in Ontario and Quebec are expanding BPO contracts for customer service and claims intake. Health Canada coordinates with provincial regulators on data handling protocols for health insurance outsourcing. Toronto serves as the primary delivery hub, with nearshore capacity in Latin America supporting after-hours coverage.
Global Insurance Business Process Outsourcing (BPO) Market Competitive Environment
Premium-margin players sit above commodity-margin players across the consulting-technology spectrum, with strategy-led transformation programs commanding pricing power over transactional processing contracts. The vendor base organizes into three tiers: global consultancies with integrated advisory capabilities, India-anchored scale operators with certified data infrastructure, and specialized claims technology providers with domain-specific AI tooling. Consolidation pressure runs through M&A activity targeting actuarial-technology hybrid talent, while geographic expansion into underpenetrated European markets represents a second competitive vector.
Within the India-based scale tier, Wipro and Tata Consultancy Services anchor large-scale policy administration relationships for North American carriers. Accenture occupies a position on the premium-consulting vector, extending transformation programs that embed BPO within broader digital modernization initiatives. Genpact exemplifies the specialized technology archetype, with domain-specific AI tools embedded within claims workflows differentiating its market position.
| Leading Market Players |
|---|
| Wipro |
| Infosys |
| Accenture |
| WNS Global Services |
| Tata Consultancy Services |
| Genpact |
| Capgemini |
| DXC Technology |
| Cognizant |
| Others |
Value Chain & Pricing Dynamics
Cloud-native delivery architectures are compressing infrastructure costs while redistributing vendor margins toward AI-enabled service tiers, concentrating pricing power among providers with certified data vault infrastructure in India and hybrid delivery capabilities in the United States and United Kingdom.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, with differentiation driven by automation maturity and regulatory certification grade. Premium tiers command margins through embedded AI analytics and EU AI Act compliance tooling, while economy tiers face cost compression from offshore wage inflation in Bangalore and Hyderabad. Large property-casualty carriers in the United States exhibit lowest price sensitivity, prioritizing outcome-based contracts tied to claims cost reduction.
Supply Chain Analysis
Single-source vulnerability sits with India-based delivery networks for policy administration and the United States for claims adjudication domain expertise. The supply chain draws from specialized labor pools in India, the Philippines, and Poland, with dependencies on cloud infrastructure providers, AI/ML development platforms, and certified data center operators. Tariff exposure on cross-border data transfers constrains pure offshore arrangements. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with wage differentials between Indian tier-1 cities and secondary hubs in Poland or Latin America creating margin expansion opportunities for vendors with flexible delivery footprints.
For Market Incumbents: Anticipate contract unbundling by accelerating componentized service offerings for claims, policy administration, and underwriting support. Defend against pure-play AI vendors by embedding algorithmic audit trails compliant with EU AI Act requirements. Prioritize backward integration into cloud infrastructure to reduce third-party dependency and capture infrastructure margin. For New Entrants and Emerging Players: Capture underpenetrated Lloyd's syndicate demand in London for marine and aviation claims expertise. Target mid-market property-casualty carriers in the United States with outcome-based pricing pilots tied to loss adjustment expense reduction. Lead with RPA-generative AI convergence tools that displace legacy document extraction workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among India-anchored scale operators facing wage inflation pressure but possessing IRDAI-certified data infrastructure. Long-term viability favors vendors with hybrid delivery models spanning regulatory proximity and cost arbitrage. Monitor EU AI Act enforcement intensity as an inflection indicator for compliance-tooling demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Delivery Model Expansion | Blends India-based cost arbitrage with onshore GDPR compliance for European carriers. |
| AI-Enabled Claims Automation | Embeds fraud detection and straight-through processing to reduce loss adjustment expenses. |
| Outcome-Based Contract Structuring | Ties vendor compensation to claims cost reduction rather than per-transaction fees. |
| Regulatory Technology Integration | Builds algorithmic audit trails and human-in-the-loop protocols for EU AI Act compliance. |
| Actuarial-Technology Talent Acquisition | Addresses scarcity of professionals combining insurance domain knowledge with Python and cloud skills. |
Study Parameters
Direct dialogue with BPO operations executives, insurance carrier procurement officers, regulatory compliance leads, and technology integration specialists grounded the qualitative foundation. Secondary validation drew from NAIC state licensing records, IRDAI custodial infrastructure filings, EU AI Act implementation guidance, SEC 10-K disclosures from publicly traded vendors, and Lloyd's market underwriting data. Bottom-up contract value estimates triangulated against top-down market sizing from carrier IT expenditure surveys.
Bottom-up modeling aggregated individual contract values across service type, client segment, and delivery model dimensions, while top-down analysis calibrated against aggregate carrier operational expenditure trends across the projection horizon. Segmentation variables included claims processing intensity, policy administration complexity, AI analytics penetration, and hybrid delivery configuration. CAGRs derived from historical contract renewal rates, automation adoption curves, and regulatory compliance cost trajectories.
Regulatory enforcement variance, AI technology maturation speed, and offshore labor cost trajectories are the dominant revision risks to forecast assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
Global Supply Chain Management BPO Market
Business Process Outsourcing (BPO)
Middleoffice BPO Services Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Customer Relationship Management (CRM) Outsourcing Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
BPO Business Analytics Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
US Managed Print Services Market