
 Asia-Pacific Business Process Outsourcing (BPO) Market | 2026-2036
Asia-Pacific Business Process Outsourcing (BPO) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Business Process Outsourcing (BPO) Market Outlook
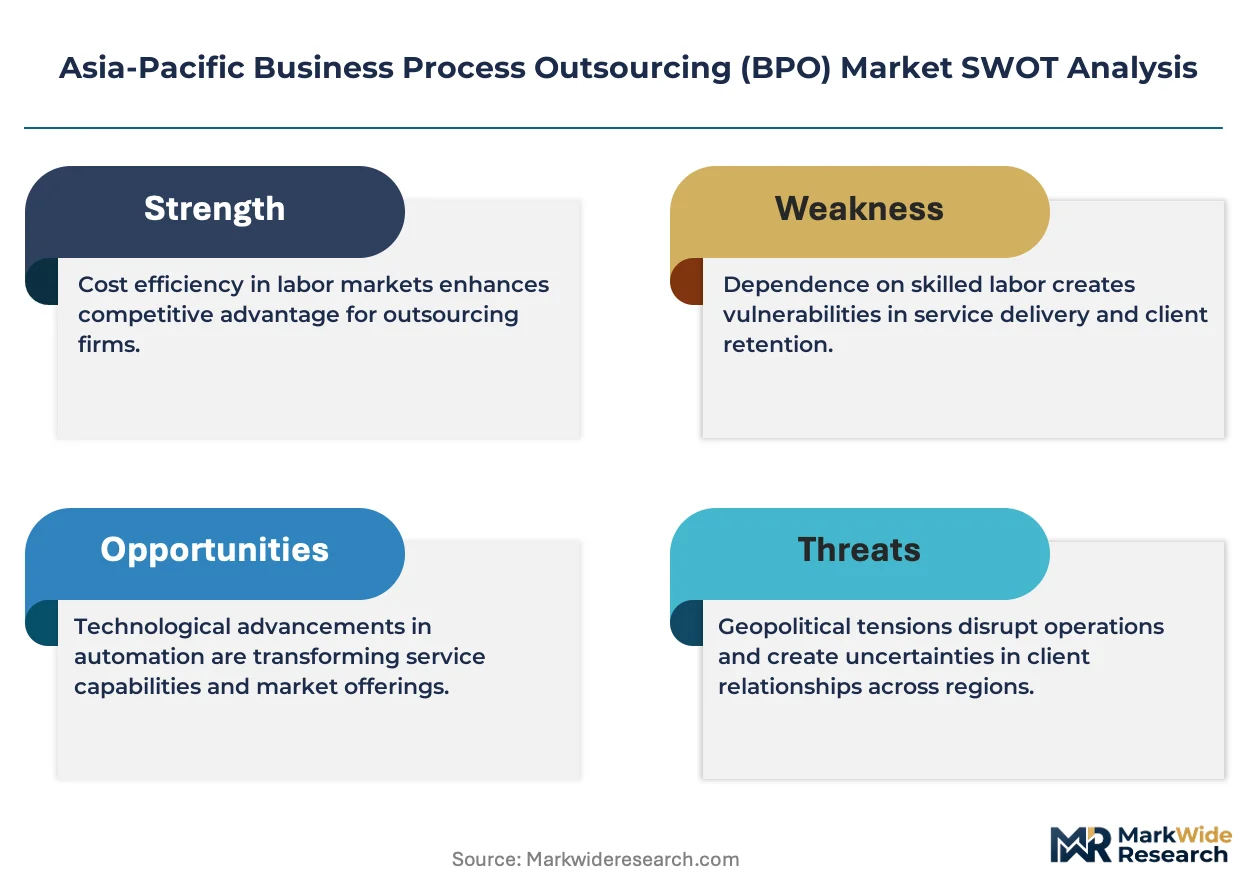
The capability gap between asset-heavy technology infrastructure and lean operational models is reorganizing competitive tiers across the Asia-Pacific BPO landscape. Accenture leverages proprietary automation platforms to command premium pricing in complex transformation engagements. Wipro Limited anchors its position through deep engineering heritage and captive delivery centers across Bangalore and Hyderabad. Teleperformance SE competes on multilingual workforce scale, sustaining dominance in European-language customer support routed through Asian hubs.
Asia-Pacific Business Process Outsourcing encompasses the delegation of non-core business functions—spanning customer interaction management, finance and accounting operations, human resource administration, and information technology services—to third-party providers operating under formal service-level agreements with defined turnaround times and quality metrics. The primary commercial purpose centers on cost arbitrage, operational scalability, and access to specialized talent pools that internal organizations cannot replicate efficiently. Customer Support Outsourcing remains the volume anchor, though IT Outsourcing captures disproportionate margin pools as enterprises migrate legacy systems to cloud-native architectures. Within End User segmentation, BFSI generates the most contract value, while Healthcare Sector engagement is expanding fastest as payers and providers confront administrative complexity.
India's TRAI governs data localization requirements for telecommunications clients, while Singapore's Personal Data Protection Commission enforces cross-border transfer restrictions that reshape delivery center placement. The Philippines' DICT and BSP jointly oversee cybersecurity standards for financial services outsourcing, tightening audit protocols for foreign-owned BPO facilities. Stakeholders must monitor evolving data sovereignty frameworks as ASEAN member states harmonize—or diverge—on digital trade governance.
Market Dynamics
Cloud migration mandates from India's TRAI and Singapore's data residency rules are forcing wholesale platform modernization across Asia-Pacific BPO delivery networks, compressing legacy infrastructure replacement cycles and redrawing competitive tiers.
Growth Catalysts
- Healthcare data compliance:Southeast Asian healthcare providers are expanding back-office outsourcing contracts to manage patient data governance requirements. This creates sustained contract volume in medical records processing and claims administration.
- TRAI localization mandates:India's telecommunications regulator requires data localization for telecom clients, driving captive center expansion and domestic delivery infrastructure investment.
- Cloud-native architecture migration:Enterprise IT outsourcing is capturing disproportionate margin pools as organizations migrate legacy systems, accelerating demand for specialized cloud engineering talent.
Market Restraints
- Cross-border transfer friction:Singapore's Personal Data Protection Commission enforces strict cross-border data transfer restrictions that reshape delivery center placement and limit operational flexibility.
- Cybersecurity audit intensity:The Philippines' DICT and BSP jointly oversee tightening cybersecurity standards for financial services outsourcing, extending compliance timelines and raising facility certification costs.
- Secondary hub infrastructure gaps:Vietnam and Malaysia lack mature telecommunications and power redundancy compared to established Indian and Philippine delivery clusters, constraining scale-up velocity.
Strategic Opportunities
- Vietnamese delivery expansion:Vietnam's emerging BPO corridor offers cost arbitrage below Philippine wage levels for multilingual customer support and software testing services.
- ASEAN digital trade harmonization:Evolving data sovereignty frameworks across ASEAN member states present first-mover advantages for providers structuring regional compliance architectures.
- Automation-amplified delivery:Convergence of robotic process automation with generative AI tools enables tier-one providers to compress unit economics and expand addressable contract scope.
Industry Challenges
- Specialized cloud engineering scarcity:Talent pipelines for Kubernetes, DevOps, and multi-cloud architecture skills lag behind enterprise migration demand across Bangalore, Hyderabad, and Manila.
- Legacy system integration complexity:BFSI clients maintain decades-old core banking platforms that resist API-native connectivity, extending transformation timelines and inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Business Process Outsourcing (BPO) Market |
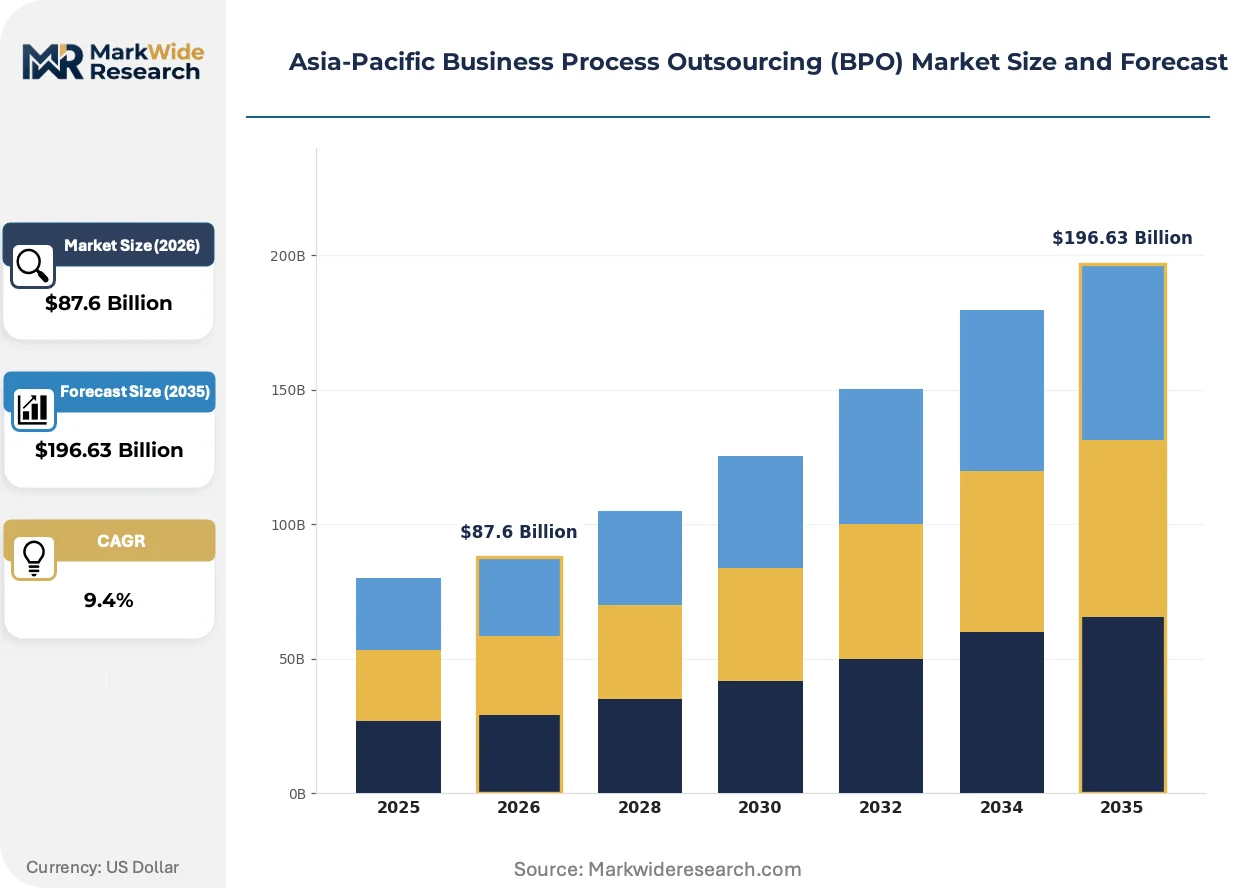
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IT Outsourcing, Human Resources Outsourcing, Customer Support Outsourcing, Accounting Outsourcing End User: Retail Sector, Healthcare Sector, BFSI, Telecommunications Deployment Model: On-Premises, Cloud-Based, Hybrid, Offshore Industry Vertical: Manufacturing, E-Commerce, Education, Logistics |
| Companies Covered | Cognizant, Teleperformance SE, Accenture, TTEC Holdings, WNS (Holdings), Wipro Limited, Infosys BPM, Concentrix Corporation, HCL Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Business Process Outsourcing (BPO) Market Strategic Shifts
Generative AI deployment and hyper-automation platforms are compressing traditional labor arbitrage models while regulatory fragmentation across ASEAN data regimes forces architectural flexibility investments.
Hyper-automation platforms combining robotic process automation with machine learning inference engines are miniaturizing the headcount requirements for standardized back-office functions. BFSI procurement teams in Singapore and Hong Kong are piloting these stacks for trade finance documentation and KYC verification workflows. The technology is miniaturizing the traditional seat-based pricing model toward transaction-volume economics, pressuring mid-tier providers lacking proprietary automation IP.
Singapore's Personal Data Protection Commission has tightened cross-border transfer consent requirements for financial and healthcare data categories. This regulatory friction is accelerating investment in domestic Singapore delivery infrastructure rather than regional hub models. Wealth management and private banking outsourcing contracts now specify in-country data residency as a mandatory provision, reshaping vendor selection criteria.
Enterprise buyers are unbundling monolithic outsourcing contracts into modular, outcome-based service components with shorter renewal cycles. BFSI and healthcare payers in Australia and Japan are segmenting customer support, claims processing, and IT infrastructure into separate vendor relationships. This pattern is most pronounced in Australian banking, where prudential regulators scrutinize operational concentration risk in single-provider arrangements.
Asia-Pacific Business Process Outsourcing (BPO) Market Segmentation
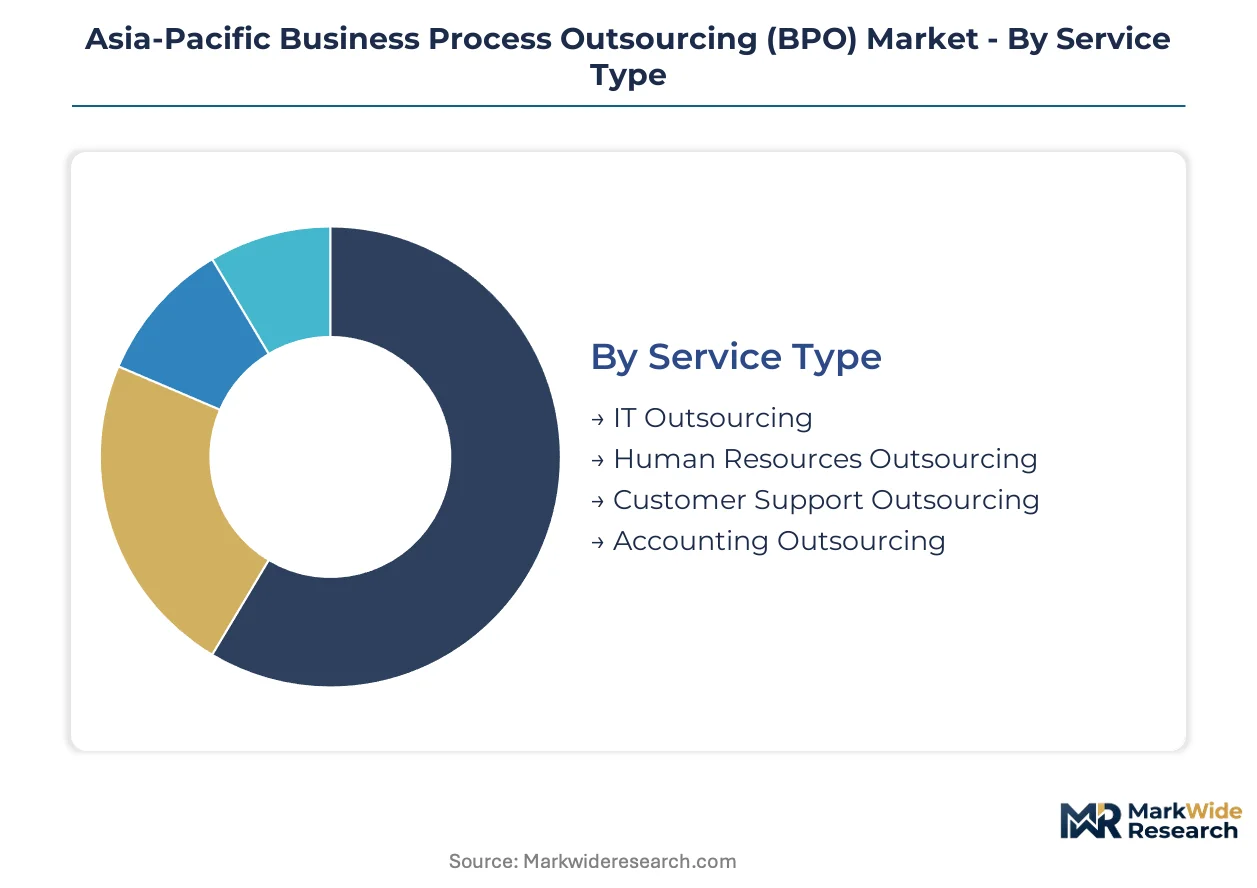
Segmentation in Asia-Pacific BPO reveals how automation threat intensity varies dramatically across service lines, with standardized processes facing displacement while specialized IT functions command premium positioning. Procurement teams in Singapore and Mumbai use these categories to structure vendor selection criteria and contract pricing models.
Service Type:
Substitution pressure from robotic process automation and generative AI tools concentrates most heavily on rule-based back-office functions, creating divergent margin trajectories across the four service categories.
- IT Outsourcing:Encompasses cloud infrastructure management, application development, and cybersecurity operations requiring specialized engineering credentials. Demand clusters in Bangalore and Hyderabad where Kubernetes and DevOps talent pools support enterprise migration from legacy systems to multi-cloud architectures. TRAI data localization mandates for telecommunications clients accelerate domestic captive center investment.
- Customer Support Outsourcing:Covers multilingual voice, chat, and email interaction management with defined response-time service levels. Philippine delivery hubs dominate European-language support while Vietnam gains traction for cost-sensitive English-language volumes. Hyper-automation platforms compress seat-based pricing toward transaction economics.
- Human Resources Outsourcing:Includes payroll administration, benefits management, and recruitment process outsourcing. Singapore's tight labor market drives employer-of-record services for regional headquarters expansion.
- Accounting Outsourcing:Spans accounts payable, receivable, and financial reporting standardization. Regulatory divergence in ASEAN tax frameworks limits cross-border service consolidation.
Customer Support Outsourcing anchors the volume base while IT Outsourcing gains share at the steepest rate.
End User:
Compliance burden intensity determines outsourcing penetration depth, with regulated industries maintaining captive relationships while retail pursues aggressive third-party consolidation.
- BFSI:Encompasses banking, insurance, and capital markets operations including claims processing, trade finance documentation, and KYC verification. Singapore's Monetary Authority and Hong Kong's HKMA scrutinize operational resilience in outsourcing arrangements, extending due diligence timelines. Private banking contracts now specify in-country data residency as mandatory.
- Healthcare Sector:Covers medical records processing, claims administration, and patient engagement services. Southeast Asian hospital networks expand back-office contracts to manage patient data governance requirements from Vietnam's Ministry of Health and Thailand's PDPC equivalent. Cloud migration accelerates for telemedicine platform support.
- Telecommunications:Includes billing operations, customer acquisition, and network operations center support. India's TRAI localization requirements reshape delivery center placement toward domestic infrastructure.
- Retail Sector:Spans order management, returns processing, and loyalty program administration. Australian and Japanese retailers unbundle monolithic contracts into modular components with shorter renewal cycles.
BFSI contributes the largest contract value pool while Healthcare Sector engagement expands most quickly.
Deployment Model:
Data sovereignty enforcement across ASEAN member states fragments architecture standardization, forcing providers to maintain multiple delivery configurations.
- Cloud-Based:Delivers services through public or private cloud infrastructure with API-native connectivity. Singapore's PDPC cross-border transfer restrictions accelerate domestic cloud region investment from AWS, Azure, and Google Cloud. Enterprise buyers prioritize FinOps and cloud cost optimization capabilities.
- Hybrid:Combines on-premises legacy system integration with cloud-native workload portability. BFSI clients in Australia and Japan maintain decades-old core banking platforms that resist full migration, extending transformation timelines.
- On-Premises:Retains infrastructure within client-controlled facilities for maximum data governance assurance. Wealth management outsourcing in Singapore specifies this model for sensitive portfolio data.
- Offshore:Locates delivery in cost-advantaged geographies separate from client headquarters. Philippine and Indian hubs retain dominance despite Vietnam and Malaysia emergence.
Offshore deployment anchors current volume while Cloud-Based architecture climbs the fastest.
Industry Vertical:
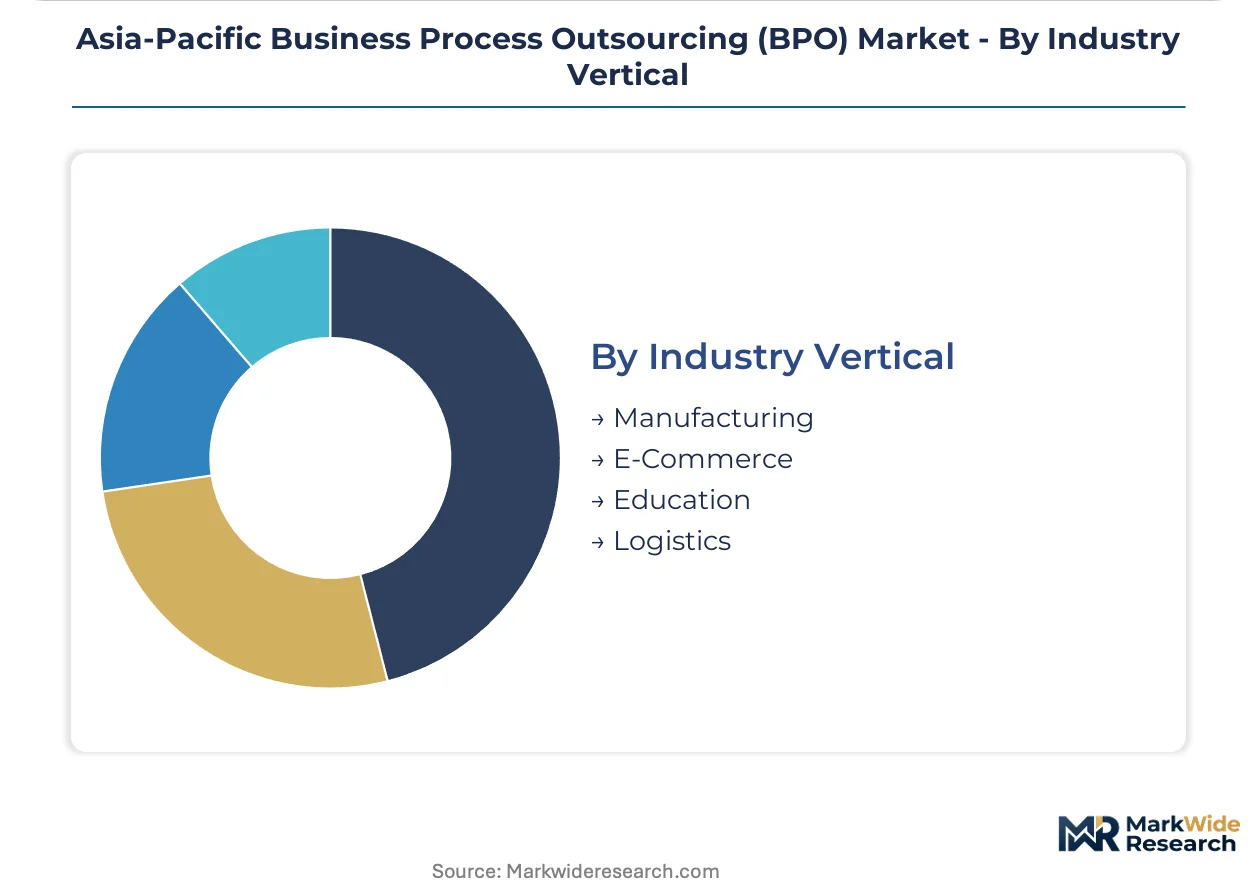
E-commerce platform complexity and supply chain digitization create divergent outsourcing maturity across manufacturing and logistics relative to digital-native sectors.
- E-Commerce:Encompasses marketplace seller support, fulfillment coordination, and returns logistics management. Southeast Asian platform operators in Jakarta and Bangkok outsource customer verification and payment reconciliation to specialized providers.
- Logistics:Covers freight documentation, customs brokerage, and warehouse management system administration. Port automation in Singapore and Busan drives demand for specialized trade finance processing.
- Manufacturing:Includes procurement support, vendor management, and quality documentation. Japanese automotive suppliers in Thailand pursue back-office consolidation.
- Education:Spans student enrollment processing, learning management system administration, and credential verification. Australian universities outsource international admissions assessment to Manila-based providers.
E-Commerce anchors vertical demand while Logistics demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes BPO services through massive-scale delivery infrastructure, while Singapore and Australia prioritize data sovereignty over cost arbitrage, and Southeast Asian markets seek multilingual customer engagement capabilities.
India
Telecommunications and BFSI verticals drive contract volume through Bangalore and Hyderabad delivery clusters. TRAI mandates data localization for telecom clients, forcing domestic captive center expansion. Mumbai anchors financial services outsourcing with specialized trade finance and KYC processing operations.
Philippines
European-language customer support and healthcare claims administration sustain delivery hub dominance. DICT and BSP jointly enforce tightening cybersecurity audit protocols for foreign-owned facilities. Metro Manila concentrates voice operations while Cebu and Davao emerge as secondary sites for cost-sensitive English-language volumes.
Singapore
Wealth management and private banking outsourcing specify in-country data residency as mandatory contract terms. PDPC cross-border transfer restrictions accelerate domestic cloud region investment from hyperscale providers. The central business district hosts premium-tier delivery infrastructure for regional headquarters back-office functions.
Vietnam
Software testing and multilingual customer support contracts expand as wage arbitrage persists below Philippine levels. Ministry of Health patient data governance requirements reshape healthcare BPO procurement. Ho Chi Minh City anchors the emerging delivery corridor with improving telecommunications redundancy.
Australia
Prudential regulatory scrutiny of operational concentration risk drives contract unbundling into modular vendor relationships. APRA oversight extends due diligence timelines for banking and insurance outsourcing arrangements. Sydney and Melbourne concentrate captive centers for superannuation administration and claims processing.
Asia-Pacific Business Process Outsourcing (BPO) Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with tier-one providers commanding premium positioning through proprietary automation platforms and deep engineering heritage. The middle tier competes on geographic arbitrage and vertical specialization. Strategic archetypes include automation-amplified integrators, scale-driven multilingual operators, and engineering-centric captive specialists. Competitive intensity concentrates on M&A-driven capability consolidation and cloud-native talent acquisition.
Among automation-focused integrators, Accenture and Cognizant exemplify the platform-proprietary tier that compresses unit economics through RPA-AI convergence. Wipro Limited and HCL Technologies occupy positions within the engineering-centric archetype, leveraging deep technical credentials for complex transformation engagements. Teleperformance SE represents the scale-driven multilingual operator model sustaining dominance in European-language customer support routed through Asian hubs.
| Leading Market Players |
|---|
| Cognizant |
| Teleperformance SE |
| Accenture |
| TTEC Holdings |
| WNS (Holdings) |
| Wipro Limited |
| Infosys BPM |
| Concentrix Corporation |
| HCL Technologies |
| Others |
Value Chain & Pricing Dynamics
Hyper-automation platform substitution for human labor arbitrage simultaneously redraws supply geography toward cloud-native delivery clusters and compresses pricing economics across standardized back-office functions. Seat-based contracts in Philippine voice operations face margin erosion as robotic process automation tools displace agent headcount, while specialized Kubernetes engineering in Bangalore commands premium rates unaffected by automation displacement.
Pricing Analysis
Extended automation licensing and managed service tiers now drive lifetime value more than initial seat-based contracts. Three-tier pricing structure across premium transformation engagements, standard process outsourcing, and economy voice operations reflects divergence in proprietary platform investment. Price differentiation stems from cloud engineering certification density and vertical specialization depth in healthcare compliance. Pricing pressure stems from generative AI tool commoditization of multilingual chat support. Retail sector buyers exhibit highest price sensitivity; Singapore wealth management clients show lowest.
Supply Chain Analysis
India and the Philippines anchor BPO service delivery, with Vietnam and Malaysia emerging as secondary production corridors for cost-sensitive volumes. Talent pipelines for DevOps, Kubernetes, and multi-cloud architecture skills feed from Indian Institutes of Technology and Philippine technical universities. Supply chain risk centers on single-source vulnerability in European-language voice operations concentrated in Metro Manila. Distribution runs through direct enterprise sales teams in Singapore and Mumbai, supplemented by systems integrator partnerships for complex transformation engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific BPO market functions as a defensive-moat arena where regulatory entrenchment around data residency requirements creates durable competitive barriers. Switching costs escalate as clients embed providers within compliance architectures spanning multiple ASEAN jurisdictions.
For Market Incumbents: Secure proprietary automation IP through targeted acquisition of robotic process automation specialists and generative AI tool providers. Expand captive delivery infrastructure in Vietnam before wage arbitrage windows narrow. The threat of cloud-native challengers with superior unit economics demands preemptive platform investment. Certification density in Singapore's PDPC compliance framework remains the priority defensive lever. For New Entrants and Emerging Players: Lead with specialized healthcare claims administration capabilities targeting Southeast Asian hospital networks confronting patient data governance requirements. Vietnamese software testing and quality assurance represents the most penetrable segment given infrastructure maturation and persistent wage gaps below Philippine levels. A direct sales approach emphasizing outcome-based pricing models with Australian superannuation funds bypasses incumbent relationship entrenchment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier providers holding vertical specialization in BFSI compliance but lacking automation platform scale. Long-term viability across a five-to-ten-year horizon hinges on successful RPA-AI convergence execution. The signal to watch is contract unbundling velocity in Australian banking, where prudential scrutiny of operational concentration risk accelerates vendor diversification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Platform Acquisition | Proprietary RPA-AI tools from Bangalore specialists compress unit economics against seat-based competitors. |
| Vietnamese Delivery Expansion | Ho Chi Minh City infrastructure investment captures wage arbitrage before Philippine cost convergence. |
| Singapore Cloud Region Buildout | Domestic AWS and Azure presence satisfies PDPC cross-border transfer restrictions for wealth management clients. |
| Healthcare Compliance Certification | Thailand PDPC-equivalent and Vietnam Ministry of Health credentials unlock Southeast Asian hospital network contracts. |
| Outcome-Based Contract Restructuring | Transaction-volume economics replace seat-based pricing for Australian retail and Japanese payer relationships. |
Study Parameters
Desk research of BPO industry association reports, ASEAN regulatory filings, and hyperscaler cloud infrastructure disclosures preceded structured interviews with procurement officers at Australian banks, operations directors at Philippine delivery centers, and compliance leads at Singapore wealth managers. Primary fieldwork with CTOs and IT procurement officers across Bangalore and Mumbai validated secondary estimates. Trade data from India's Software Technology Parks of India and Philippines' IT and Business Process Association anchored supply-side triangulation. Bottom-up contract value aggregation and top-down market sizing were cross-referenced for convergence.
Variance decomposition across service type, deployment model, and end-user vertical shaped the analytical framework over the projection horizon. Modeled dimensions encompassed IT outsourcing versus customer support segmentation, cloud-based versus hybrid architecture adoption, and BFSI versus healthcare end-user concentration. CAGRs were derived from weighted average growth rates across these segments calibrated to disclosed contract values. Cloud migration velocity from India's TRAI mandates and Singapore's data residency enforcement served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of data localization or accelerated generative AI tool adoption would require recalibration. Forecasts reflect documented assumptions regarding talent pipeline expansion in Vietnamese technical universities and telecommunications infrastructure investment in secondary hubs. Specific risk factors include cybersecurity audit intensity escalation from Philippines DICT and BSP, and legacy system integration complexity in Japanese core banking platforms. Recalibration cycles align with material shifts in ASEAN digital trade harmonization negotiations and hyperscaler domestic cloud region announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
Business Process Automation (BPA) Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Payroll Outsourcing Services Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market