
 Indonesia Enterprise Mobility Management Market | 2026-2036
Indonesia Enterprise Mobility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Enterprise Mobility Management Market Insights
Subscription-based SaaS licensing is narrowing the capital barrier for mid-sized Indonesian enterprises seeking enterprise mobility platforms. Microsoft Corporation leverages its Azure cloud footprint to anchor government and education sector deployments. PT Satya Amarta Prima (Samara) competes through localized compliance modules aligned with Indonesian data residency rules. VMware, Inc. differentiates via workspace virtualization stacks tuned for hybrid workforce architectures.
Enterprise Mobility Management encompasses the centralized administration of mobile devices, applications, and content through policy enforcement engines, containerization protocols, and over-the-air configuration management. The technology stack integrates mobile device management (MDM), mobile application management (MAM), and identity access controls to secure corporate data across employee-owned and corporate-issued endpoints. Cloud-Based deployment leads structural momentum as Indonesian firms bypass on-premise hardware investments, while Software Solutions capture the dominant margin pool through recurring license architectures. Large Enterprises currently occupy the deepest implementation base, though SME demand is accelerating fastest as bundled mobility suites drop entry price points.
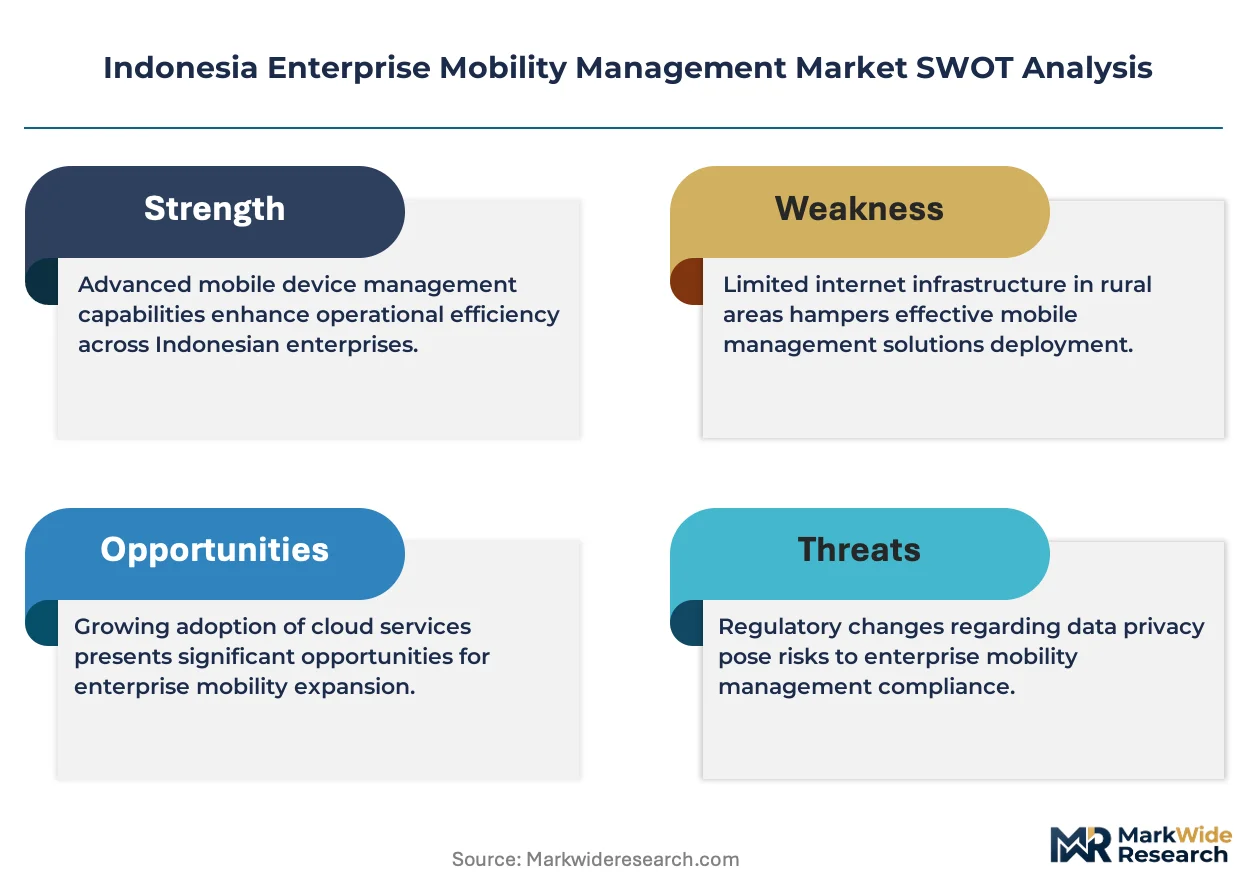
Indonesia's Ministry of Communication and Informatics enforces Personal Data Protection Law compliance across enterprise device fleets, while BIS certification requirements shape hardware security module standards for local deployments. The Financial Services Authority (OJK) mandates encrypted mobile channels for banking transactions, directly expanding managed services procurement. Stakeholders must monitor evolving cross-border data flow restrictions and decide between sovereign cloud partnerships or in-country infrastructure builds before regulatory clarity hardens.
Market Dynamics
Indonesia's Personal Data Protection Law enforcement is compressing procurement cycles for enterprise mobility platforms as banking and manufacturing firms scramble to achieve compliance before audit deadlines. This regulatory pressure is restructuring vendor selection criteria toward localized data residency capabilities.
Growth Catalysts
- Financial sector mandates:OJK encryption requirements for mobile banking channels are expanding managed services procurement across Jakarta's banking corridor. Regional lenders are accelerating device fleet hardening.
- Cloud migration:Indonesian enterprises are bypassing on-premise hardware investments through SaaS licensing models. Mid-sized firms in Surabaya's manufacturing belt are adopting bundled mobility suites.
- Data residency rules:Strict localization requirements under the Personal Data Protection Law are favoring domestic infrastructure builds. Sovereign cloud partnerships are gaining traction among government agencies.
Market Restraints
- Certification bottlenecks:BIS hardware security module standards create extended validation timelines for imported device management hardware. Procurement cycles stretch as a result.
- Skill scarcity:Containerization and zero-trust architecture expertise remains concentrated in Jakarta's enterprise corridor. Deployment velocity suffers outside the capital region.
- Legacy integration friction:Hybrid workforce architectures require costly middleware development to connect modern EMM stacks with aging on-premise identity systems.
Strategic Opportunities
- Eastern Indonesia expansion:Makassar and Denpasar enterprise corridors show underpenetrated demand for mobile workforce management among logistics and hospitality operators.
- AI-powered policy engines:Machine learning integration with mobile threat defense is creating new service tiers. Behavioral analytics vendors are entering the Indonesian market.
- Education sector digitization:Ministry of Education device distribution programs are opening bulk procurement channels for K-12 mobile management platforms.
Industry Challenges
- Cross-functional talent gaps:Security architects with simultaneous mobility, cloud, and Indonesian regulatory expertise command premium compensation. Hiring cycles extend deployment timelines.
- Multi-cloud orchestration complexity:Enterprises operating across Azure, Google Cloud, and local sovereign clouds face fragmented policy enforcement. Unified control planes remain immature.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Enterprise Mobility Management Market |
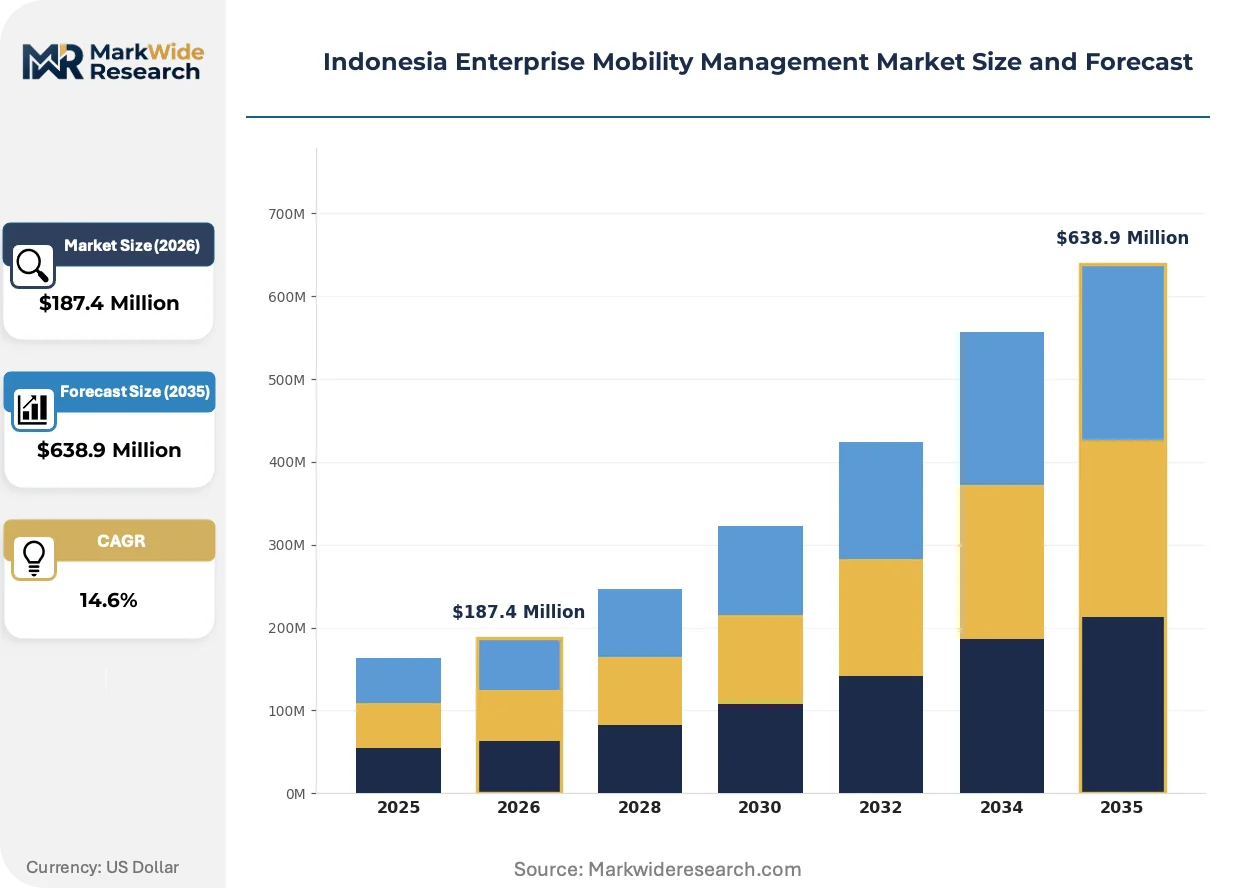
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Managed Services, Cloud Services, Consulting Services Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Industry Vertical: Healthcare, Manufacturing, Retail, Financial Services |
| Companies Covered | IBM Corporation, Microsoft Corporation, PT Satya Amarta Prima (Samara), PT Artha Mulia Trijaya (AMT) IT Solutions, PT Cisco Systems Indonesia (Cisco), VMware, Inc., Citrix Systems, Inc., BlackBerry Limited, SAP SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Enterprise Mobility Management Market Trends and Innovations
Containerization protocols are displacing traditional mobile device management approaches as Indonesian enterprises prioritize application-level security over full device control. This architectural pivot is redrawing competitive boundaries between platform vendors.
Zero-trust network access architectures are migrating from perimeter-based VPN models to continuous verification frameworks. Banking institutions in Jakarta are piloting software-defined perimeters for contractor and third-party access. This shift is compressing hardware security appliance markets while expanding identity-centric subscription revenues.
Indonesia's Ministry of Communication and Informatics is tightening cross-border data flow restrictions through implementing regulations under the Personal Data Protection Law. Multinational enterprises are responding by segregating Indonesian user data onto in-country Azure or local sovereign cloud instances. The financial services vertical faces the steepest compliance burden due to OJK transaction logging mandates.
Device-as-a-service procurement models are displacing traditional capital expenditure cycles for endpoint hardware. Large Indonesian conglomerates are bundling EMM licenses with Samsung or Apple fleet leases through telecom operators. This convergence is most visible in Jakarta's enterprise corridor where Telkomsel and Indosat Ooredoo Hutchison have launched integrated mobility packages.
Indonesia Enterprise Mobility Management Market Segmentation
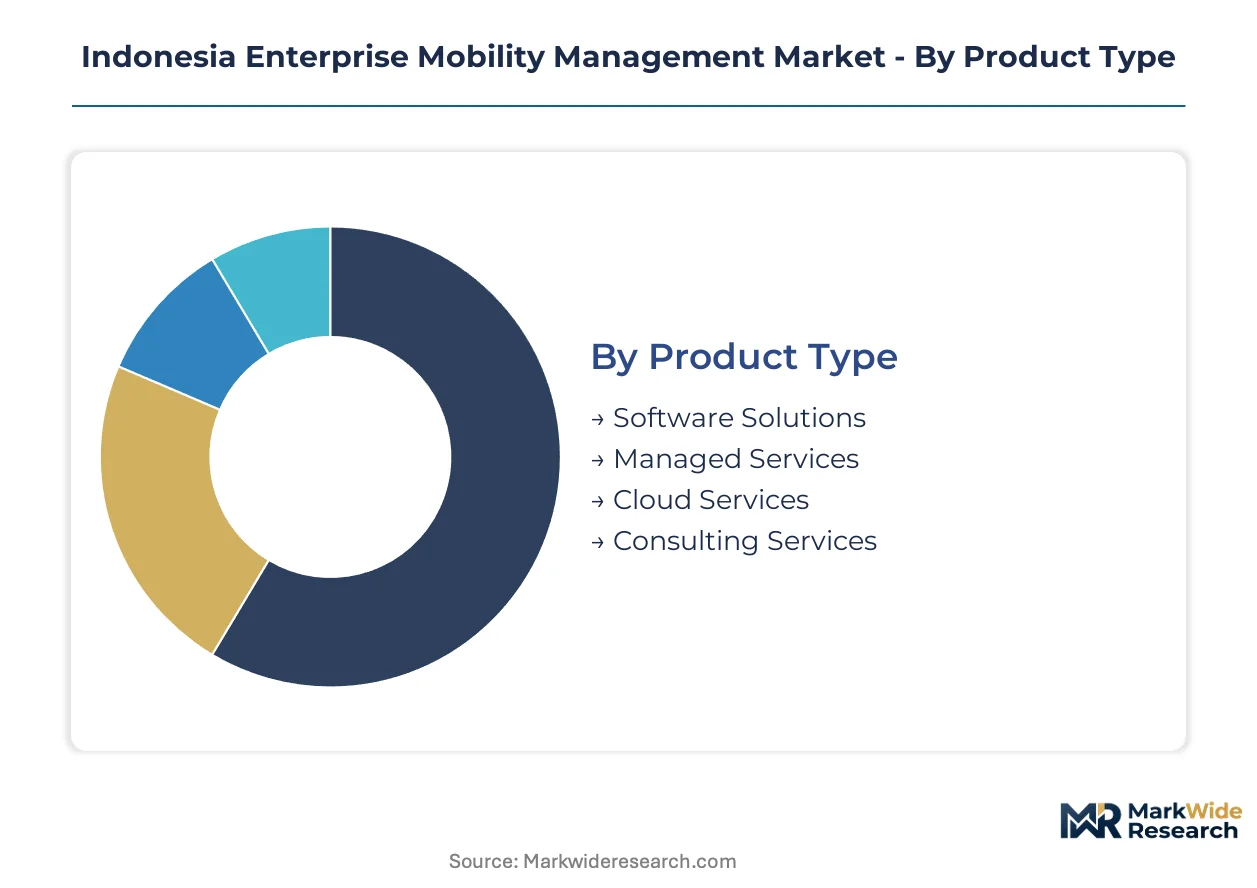
Segmentation in Indonesia's enterprise mobility management market reveals how regulatory pressure, cloud infrastructure maturity, and workforce digitization priorities reshape vendor targeting and solution architecture across distinct buyer profiles.
Product Type:
Use-case complexity spans from self-managed software stacks to fully outsourced operational support, with procurement patterns tracking internal IT capability depth.
- Software Solutions:Policy enforcement engines, containerization protocols, and identity access controls form the core licensed stack. Banking institutions in Jakarta's enterprise corridor favor perpetual licenses with customization rights to satisfy OJK audit requirements.
- Managed Services:Third-party providers assume device fleet administration, patch management, and compliance reporting. Surabaya's manufacturing belt shows concentrated demand where internal security expertise remains scarce.
- Cloud Services:Scalable infrastructure for over-the-air configuration and threat intelligence feeds without on-premise hardware. Government agencies prioritize sovereign cloud partnerships under data residency mandates.
- Consulting Services:Implementation planning, legacy system integration, and compliance gap assessments. Regional lenders outside Jakarta engage consultants to accelerate Personal Data Protection Law readiness.
Established volume favors Software Solutions; emerging adoption favors Managed Services.
Deployment:
Capital availability and data sovereignty requirements drive architectural choices across Indonesian enterprises with varying risk tolerances.
- On-Premise:Dedicated hardware within corporate data centers with full administrative control. Defense contractors and critical infrastructure operators maintain this model despite higher total cost of ownership.
- Cloud-Based:Multi-tenant platforms hosted on Azure, Google Cloud, or local sovereign instances. Mid-sized enterprises in Surabaya's manufacturing belt bypass hardware procurement through this route.
- Hybrid:Sensitive identity systems remain on-premise while device management shifts to cloud orchestration. Large conglomerates with legacy Active Directory investments favor this transitional architecture.
- SaaS:Subscription licensing with automatic feature updates and shared infrastructure economics. Educational institutions bulk-procure through Ministry of Education framework agreements.
Cloud-Based deployments claim the deepest installed base; SaaS licensing climbs the fastest as entry price points compress.
End User:
Organizational scale determines solution sophistication, with procurement authority and compliance exposure varying sharply across buyer types.
- SMEs:Bundled mobility suites with simplified policy templates and pre-configured compliance dashboards. Surabaya manufacturers adopt standardized packages through telecom operator channels.
- Large Enterprises:Custom-integrated platforms spanning multiple operating systems, geographies, and subsidiary entities. Jakarta-based conglomerates require dedicated customer success teams and local language support.
- Government Agencies:Sovereign cloud mandates with domestic data residency and enhanced audit trails. Ministry of Communication and Informatics procurement frameworks prioritize local vendors.
- Educational Institutions:Bulk device management for student and faculty fleets with content filtering and application whitelisting. K-12 programs drive seasonal procurement spikes aligned to academic calendars.
Large Enterprises anchor current revenue; Government Agencies show steepest expansion trajectory as digitization mandates broaden.
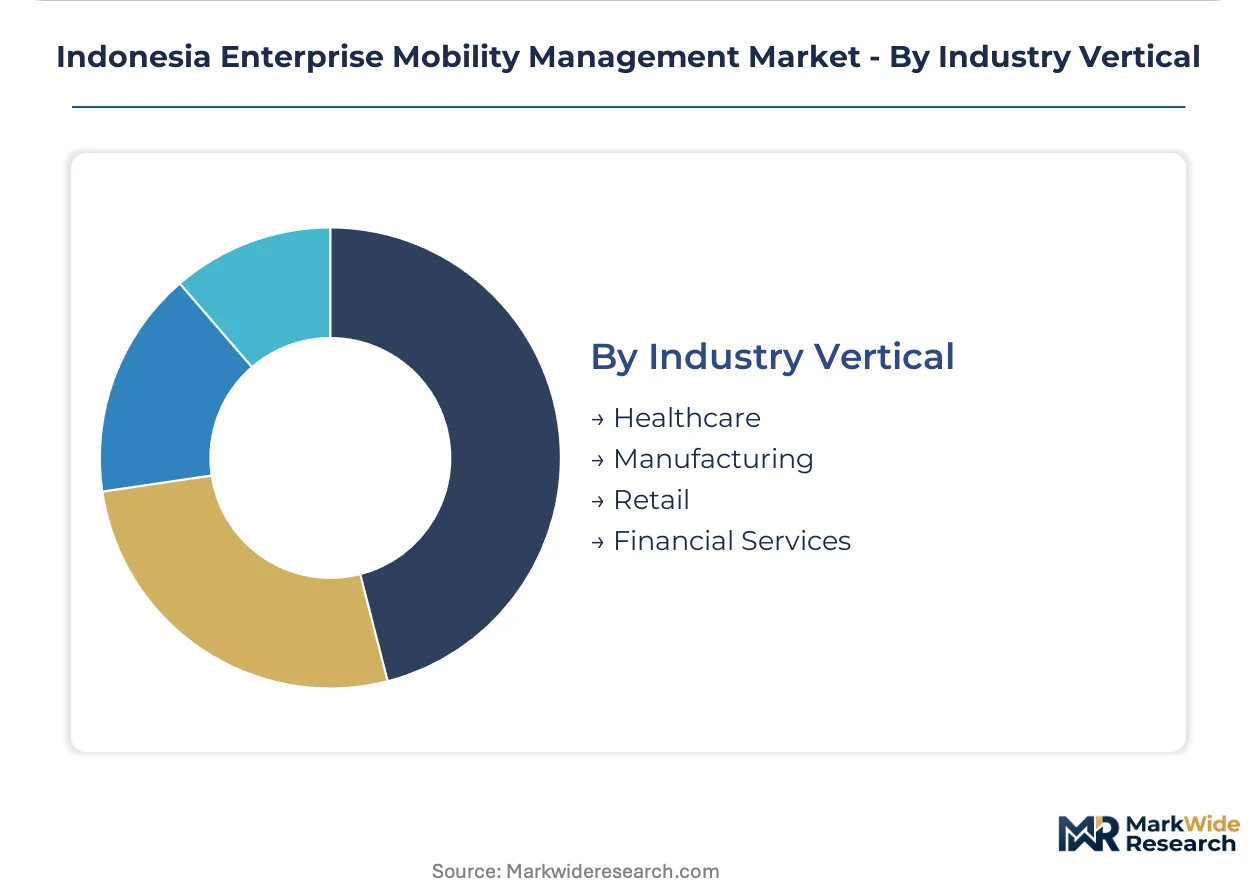
Industry Vertical:
Sector-specific regulatory exposure and mobile workforce intensity create divergent feature requirements and sales cycle lengths.
- Healthcare:HIPAA-aligned encryption for patient data access on clinician tablets and smartphones. Hospital networks in Jakarta pilot zero-trust architectures for contractor device access.
- Manufacturing:Rugged device support for factory floor environments and integration with operational technology networks. Surabaya's industrial belt demands offline capability and local data processing.
- Retail:Point-of-sale integration, inventory management apps, and customer-facing tablet deployments. National chains prioritize rapid device provisioning for seasonal workforce scaling.
- Financial Services:OJK-mandated transaction encryption and comprehensive audit logging for mobile banking channels. Regional lenders outside Jakarta accelerate compliance investments ahead of enforcement deadlines.
Financial Services commands premium pricing; Manufacturing represents the fastest-growing vertical as workforce mobility extends beyond white-collar roles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta commands pricing premiums unmatched by Surabaya's manufacturing belt, where bundled mobility suites trade at entry-level rates. This geographic asymmetry reflects divergent compliance exposure and IT maturity across Indonesia's enterprise corridors.
Java
Jakarta's banking corridor drives premium EMM procurement as OJK encryption mandates compress sales cycles for regional lenders. The Ministry of Communication and Informatics enforces Personal Data Protection Law audits across device fleets headquartered in the capital. Surabaya's manufacturing belt adopts standardized SaaS packages through Telkomsel and Indosat Ooredoo Hutchison channels.
Sumatra
Medan's plantation conglomerates and Palembang's energy operators are extending mobile workforce management to field operations. Local regulators align with Jakarta's data residency directives while permitting longer implementation timelines for non-financial sectors. Batam's free trade zone attracts multinational logistics operators piloting zero-trust architectures for cross-border contractor access.
Sulawesi
Makassar's logistics and hospitality sectors show underpenetrated demand for rugged device management and offline capability. The national government's Eastern Indonesia development programs are channeling infrastructure investment toward enterprise digitization. Nickel processing corridors near Morowali are integrating operational technology networks with mobile workforce platforms.
Bali and Nusa Tenggara
Denpasar's tourism operators are deploying tablet-based point-of-sale and inventory systems requiring rapid seasonal provisioning. Provincial education offices are participating in Ministry of Education bulk device distribution programs. Lombok's emerging hospitality developments are adopting cloud-based mobility suites to bypass capital expenditure constraints.
Kalimantan
Balikpapan and Samarinda energy operators are hardening device fleets against operational technology network intrusions. Mining concessions are adopting containerization protocols to separate corporate data from contractor-owned endpoints. Provincial regulators are enforcing BIS hardware security module standards for imported device management infrastructure.
Indonesia Enterprise Mobility Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying policy engines and containerization protocols. The vendor base organizes into three tiers: multinational cloud platforms with sovereign partnerships, domestic integrators with localized compliance modules, and telecom operators bundling hardware with managed services. Dominant competitive moves include strategic partnerships with local data center operators and portfolio diversification into AI-powered threat detection.
Within the multinational platform tier, Microsoft Corporation and VMware, Inc. anchor positions through Azure cloud deployments and workspace virtualization stacks respectively. PT Satya Amarta Prima (Samara) occupies a distinct position among domestic specialists, competing through alignment with Indonesian data residency rules. These three exemplify the competitive tension between global scale advantages and localized regulatory compliance capabilities.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| PT Satya Amarta Prima (Samara) |
| PT Artha Mulia Trijaya (AMT) IT Solutions |
| PT Cisco Systems Indonesia (Cisco) |
| VMware, Inc. |
| Citrix Systems, Inc. |
| BlackBerry Limited |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
The Tanjung Priok Port corridor freight cost dynamics compress margins for hardware security module imports while amplifying price differentiation between Jakarta's banking corridor buyers and Surabaya's manufacturing belt adopters. Supply concentration in Singapore and Malaysia data center nodes concentrates pricing power among regional distributors serving Indonesian system integrators.
Pricing Analysis
The customization-premium spread separates configured-to-order perpetual licenses for OJK-mandated banking deployments from standardized SaaS tiers adopted by Surabaya manufacturers. Three-tier pricing structure across premium, standard, and economy levels dominates, with certification grade and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from telecom operator bundling as Telkomsel and Indosat Ooredoo Hutchison compress standalone software margins. SMEs exhibit highest price sensitivity; Jakarta-based financial institutions demonstrate lowest sensitivity due to compliance-driven procurement urgency.
Supply Chain Analysis
Upstream feedstock for policy enforcement engines and containerization protocols draws from United States, Singapore, and India software development centers. Raw material dependencies center on semiconductor components for hardware security modules, Azure and Google Cloud infrastructure instances, and localized data center builds. Single-source vulnerability concentrates in BIS-certified hardware imports facing extended validation timelines. Distribution runs through domestic system integrators like PT Satya Amarta Prima and PT Artha Mulia Trijaya with direct enterprise sales overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's enterprise mobility management market sits in early-cycle recovery as Personal Data Protection Law enforcement deadlines compress procurement decisions across banking and manufacturing verticals.
For Market Incumbents: Entrench through sovereign cloud partnership expansion with local data center operators to neutralize data residency compliance threats from domestic specialists. Deepen vertical integration into AI-powered threat detection modules to defend against behavioral analytics entrants. Prioritize certification investment for BIS hardware security module pre-approval to shorten regional lender sales cycles. For New Entrants and Emerging Players: Build out presence in Makassar and Denpasar logistics corridors where mobility platform penetration remains underdeveloped among hospitality and field operations buyers. Target education sector bulk procurement channels through Ministry of Education framework agreements as the most penetrable segment. Pursue device-as-a-service bundling partnerships with regional telecom operators as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate IT subsidiaries seeking to monetize non-core mobility management assets accumulated during pandemic-era digitization drives. Long-term viability favors platforms with established sovereign cloud infrastructure and localized compliance module IP. Watch for OJK audit deadline clustering as the signal indicating accelerated consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Local data center alliances with PT Telkom Indonesia satisfy Ministry of Communication and Informatics data residency mandates. |
| AI-Powered Policy Engine Launch | Machine learning integration with mobile threat defense creates premium service tiers for Jakarta banking corridor buyers. |
| Device-as-a-Service Bundling | Telecom operator channel partnerships compress customer acquisition costs in Surabaya manufacturing belt. |
| Education Sector Framework Agreement | Ministry of Education bulk procurement participation locks in seasonal revenue predictability across K-12 deployments. |
| Zero-Trust Architecture Certification | Software-defined perimeter validation opens OJK-mandated regional lender segments beyond Jakarta headquarters. |
Research Methodology
Operator-level perspectives from CTOs, IT procurement officers, platform engineers, and channel partners anchored the qualitative base for this study. Primary interview data combined with secondary validation from SEC filings, hyperscaler capex disclosures, and Ministry of Communication and Informatics regulatory circulars. Bottom-up deployment modeling across software, managed services, cloud services, and consulting segments triangulated against top-down industry spend estimates from enterprise technology budget surveys.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning deployment model, organization size, industry vertical, and regional adoption pattern. CAGRs derived from installed base growth rates, replacement cycle compression, and new entrant capture assumptions. Forecast inputs incorporated OJK enforcement timeline probability distributions and BIS certification pipeline velocity estimates specific to Indonesian market conditions.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by multinational cloud platforms or accelerated sovereign cloud builds by domestic specialists would shift outcomes. Cross-checking against Ministry of Education device distribution program budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Asia Pacific B2C Legal Services Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Online Home Service Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Social Networking App Market
Digital Solutions
Workflow Content Automation (WCA) Market
Digital Solutions
Digital Twin Market
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
Global Asset Reliability Software Market