
 Cloud Computing Artificial Intelligence (AI) Market | 2026-2036
Cloud Computing Artificial Intelligence (AI) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Computing Artificial Intelligence (AI) Market Insights
The capital-intensity divergence between hyperscale cloud providers and niche AI infrastructure specialists is collapsing as training costs for large language models force consolidation at the top. Amazon Web Services leverages its global data center footprint to sustain pricing power in GPU-intensive compute instances. NVIDIA anchors the hardware layer through captive demand for its H100 and Blackwell architectures across major cloud platforms. Alibaba Cloud navigates geopolitical constraints while competing on cost-efficient inference services in Asia-Pacific markets.
Cloud Computing Artificial Intelligence denotes the delivery of machine learning, natural language processing, and computer vision capabilities through virtualized, on-demand compute resources accessed via API or web interface, typically running on clusters of specialized accelerators with high-bandwidth interconnects. The primary commercial purpose is to eliminate capital expenditure on physical AI infrastructure while enabling elastic scaling of model training and inference workloads. SaaS application layers currently capture the largest margin pools as enterprises prefer pre-built AI tools over custom model development. Hybrid cloud deployments are expanding fastest among regulated industries seeking to keep sensitive training data on-premises while tapping public cloud burst capacity. Managed services for MLOps and model fine-tuning represent an emerging structural opportunity as talent scarcity pushes enterprises toward outsourced AI operations.
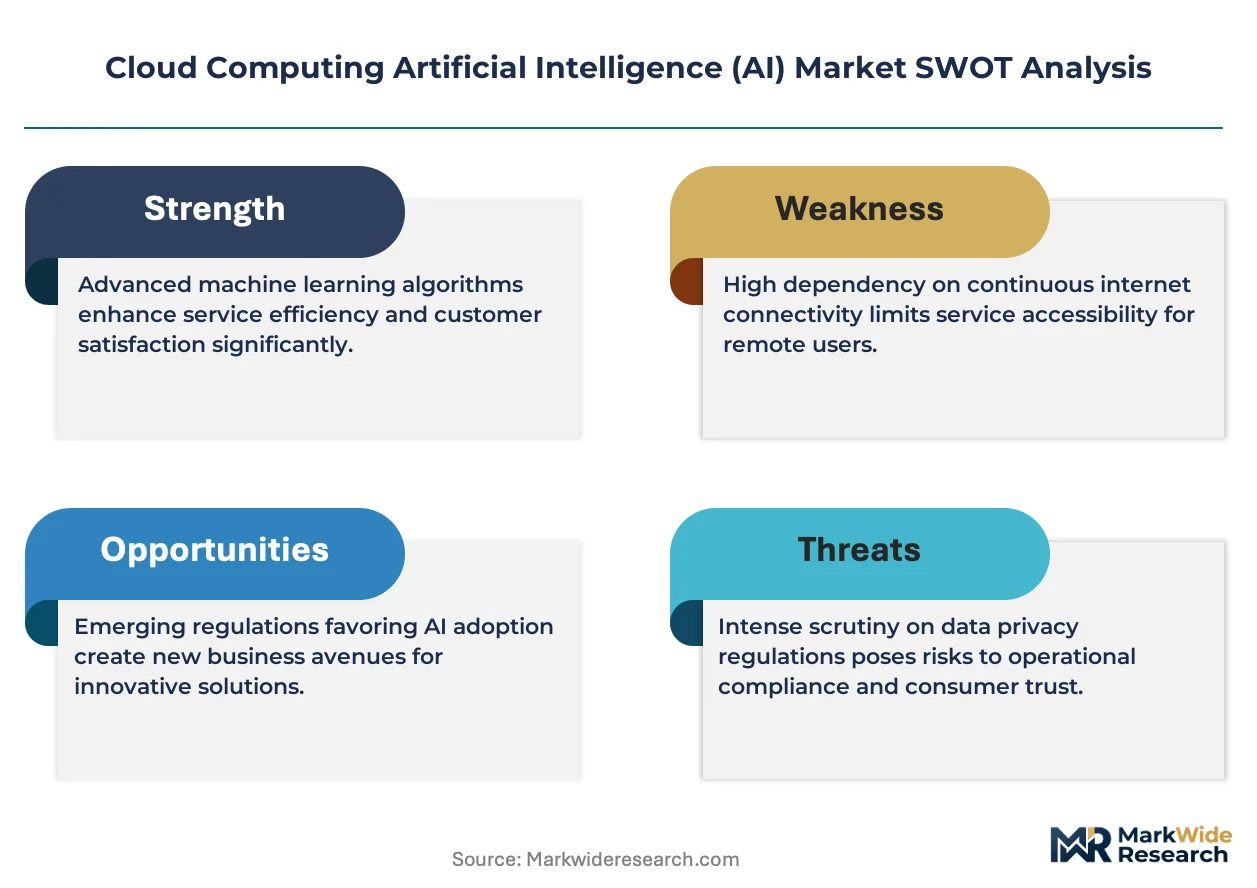
The EU AI Act, alongside FDA guidance on AI-enabled medical devices and China's algorithmic recommendation provisions under SAMR, is fragmenting compliance requirements across jurisdictions and forcing cloud providers to maintain region-specific infrastructure certifications. NIST's AI Risk Management Framework in the United States is shaping procurement standards for federal agencies, directly steering demand toward vendors with documented model governance. Stakeholders must monitor divergence between Brussels' risk-tier classification system and Washington's sector-specific agency rules, as this regulatory misalignment will determine which cloud-AI architectures achieve cross-border portability.
Market Dynamics
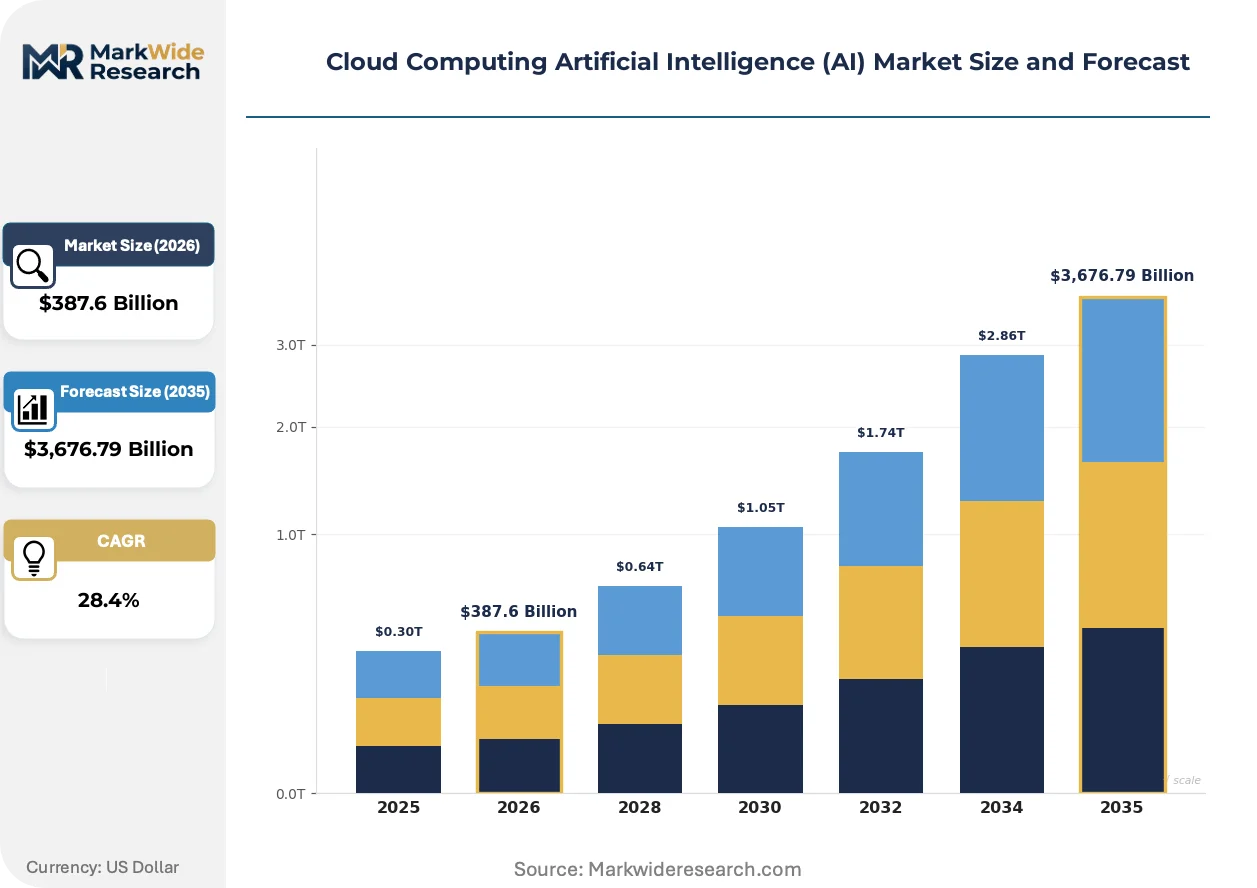
Training cost inflation for foundation models is forcing hyperscale consolidation while fragmenting compliance architectures across jurisdictions. Cloud providers must now maintain parallel infrastructure certifications to serve regulated enterprises without cross-border data exposure.
Growth Catalysts
- Federal cloud modernization mandates:United States agencies are accelerating procurement cycles for AI-enabled infrastructure under NIST's AI Risk Management Framework, directly steering demand toward vendors with documented model governance.
- Healthcare diagnostic expansion:Providers are deploying AI-driven imaging and pathology tools hosted on cloud infrastructure, eliminating capital expenditure on on-premises GPU clusters while enabling elastic scaling of inference workloads.
- GPU supply concentration:NVIDIA's H100 and Blackwell architectures anchor hardware demand across major platforms, creating captive pull-through for associated cloud compute instances and managed MLOps services.
Market Restraints
- Accelerator cost volatility:Foundry capacity constraints for advanced semiconductors concentrate pricing power with TSMC and Samsung, compressing cloud provider margins on GPU-intensive instances.
- EU AI Act compliance friction:Risk-tier classification requirements for high-risk automated systems force region-specific infrastructure builds, raising operational complexity for cross-border service delivery.
- On-premises inference substitution:Regulated enterprises are deploying edge AI appliances to keep sensitive training data local, reducing burst capacity demand for public cloud inference services.
Strategic Opportunities
- Managed MLOps services:Talent scarcity in model fine-tuning and pipeline engineering is pushing enterprises toward outsourced AI operations, creating structural margin pools for cloud-native service providers.
- Asia-Pacific inference cost competition:Alibaba Cloud is navigating geopolitical constraints to compete on cost-efficient inference services, capturing price-sensitive workloads across Southeast Asian markets.
- Hybrid cloud regulatory tailwind:China's SAMR algorithmic recommendation provisions and FDA guidance on AI-enabled medical devices are accelerating demand for architectures that keep sensitive data on-premises while tapping public cloud burst capacity.
Industry Challenges
- Model governance skill scarcity:Enterprises lack personnel capable of documenting training data provenance and bias mitigation under divergent NIST and EU AI Act requirements.
- Legacy system integration complexity:Financial services and healthcare incumbents face extended timelines connecting on-premises electronic health record and core banking systems to cloud-native AI pipelines.
- Cross-border certification timeline compression:Cloud providers must simultaneously satisfy Brussels' risk-tier system and Washington's sector-specific agency rules, fragmenting engineering roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Computing Artificial Intelligence (AI) Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $3,676.79 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IaaS, PaaS, SaaS, Managed Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Customer Type: Small Businesses, Enterprises, Startups, Government Application: Natural Language Processing, Machine Learning, Computer Vision, Predictive Analytics |
| Companies Covered | Amazon Web Services, Google Cloud, Microsoft Azure, IBM Cloud, Oracle Cloud, NVIDIA, Salesforce, Alibaba Cloud, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Computing Artificial Intelligence (AI) Market Trends and Innovations
Foundation model architectures are fragmenting into specialized, task-optimized systems that compress training economics while multiplying deployment complexity. This decomposition is reshaping how cloud providers structure compute offerings and how enterprises evaluate vendor lock-in risk.
Mixture-of-experts architectures are decomposing monolithic large language models into routed sub-networks that activate only relevant parameters per query. Healthcare and financial services enterprises are piloting these systems to reduce per-inference costs on proprietary clinical and trading data. The structural consequence is a compression of the unified-model value proposition, forcing cloud providers to offer granular, task-specific fine-tuning pipelines rather than generic API access.
The EU AI Act's risk-tier classification system is mandating documented conformity assessments for high-risk automated decision systems before market deployment. Cloud providers serving European healthcare and public sector clients must now maintain auditable model cards and human-in-the-loop verification infrastructure. Medical device manufacturers are responding by segregating EU-bound training pipelines onto region-certified infrastructure, fragmenting previously global model development workflows.
Enterprise procurement of AI infrastructure is fragmenting from centralized IT budgets into line-of-business ownership with consumption-based chargeback models. Manufacturing and logistics divisions are directly contracting managed computer vision services for quality control and warehouse optimization, bypassing traditional enterprise software procurement cycles. This pattern is most visible in United States industrial conglomerates, where operational technology teams hold independent vendor relationships distinct from corporate cloud master service agreements.
Cloud Computing Artificial Intelligence (AI) Market Segmentation
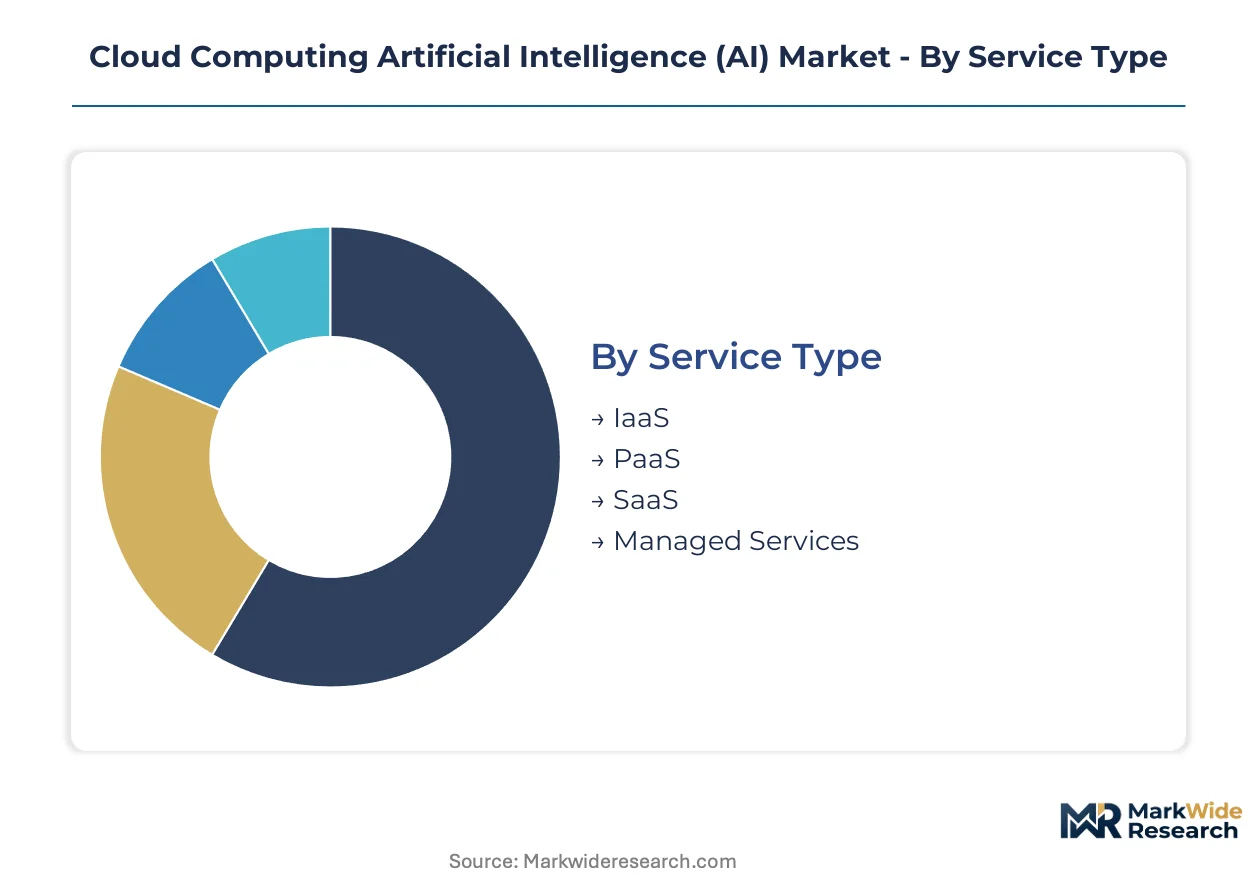
Cloud AI procurement patterns fragment sharply across service tiers and deployment architectures, with margin concentration shifting from infrastructure toward application layers as enterprises prioritize pre-built tools over custom development. Deployment choices increasingly trace regulatory boundaries rather than pure cost optimization.
Service Type:
Margin pools concentrate at the application layer where recurring subscription revenue compounds across enterprise accounts, while infrastructure services face pricing pressure from hyperscale competition.
- SaaS:Pre-built AI tools for document processing, code generation, and customer service automation command premium pricing through seat-based subscriptions. United States healthcare providers are consolidating procurement around FDA-aligned diagnostic SaaS platforms to streamline compliance documentation under NIST's AI Risk Management Framework.
- IaaS:Raw GPU compute instances with high-bandwidth interconnects for foundation model training. Demand clusters with defense contractors and research institutions in the United States pursuing federal AI modernization mandates.
- PaaS:Development environments with pre-configured MLOps pipelines and model serving infrastructure.
- Managed Services:Outsourced model fine-tuning, pipeline engineering, and governance documentation.
The dominant share belongs to SaaS, while Managed Services is closing the gap fastest as talent scarcity pushes enterprises toward outsourced AI operations.
Deployment Model:
Architecture choices increasingly bifurcate between latency-sensitive edge inference and centralized training clusters, with regulatory data residency forcing geographic fragmentation of infrastructure.
- Hybrid Cloud:Architectures maintaining sensitive training data on-premises while bursting inference workloads to public cloud capacity. Financial services and healthcare enterprises in the United States are deploying hybrid stacks to satisfy FDA guidance on AI-enabled medical devices without sacrificing elastic scaling.
- Public Cloud:Fully virtualized compute accessed via API with shared tenancy and utility pricing. Startups and digital-native enterprises dominate consumption, drawn by zero capital expenditure and rapid provisioning.
- Private Cloud:Dedicated infrastructure with single-tenant isolation for classified or proprietary workloads.
- Multi-Cloud:Orchestrated workloads across competing hyperscale platforms to mitigate vendor lock-in and optimize regional pricing.
Hybrid Cloud holds the dominant position, though Multi-Cloud architectures are expanding most quickly as procurement teams seek negotiating leverage through platform diversification.
Customer Type:
Budget authority is decentralizing from centralized IT to operational line-of-business units, reshaping contract structures toward consumption-based chargeback models.
- Enterprises:Multi-divisional organizations with dedicated AI centers of excellence and governance committees. Manufacturing and logistics divisions within United States industrial conglomerates are independently contracting computer vision services for quality control, bypassing corporate cloud master agreements.
- Government:Federal, state, and municipal agencies with stringent procurement and security classification requirements. United States agencies are accelerating vendor selection under documented model governance standards per NIST's AI Risk Management Framework.
- Small Businesses:Resource-constrained organizations accessing AI through low-code SaaS interfaces without dedicated technical staff.
- Startups:Venture-backed companies prioritizing speed-to-market over infrastructure control, consuming managed MLOps to compensate for limited hiring pipelines.
Enterprises command the dominant share, while Government procurement is climbing the fastest as federal cloud modernization mandates unlock multi-year contract vehicles.
Application:
Functional specialization is compressing the unified-model value proposition, forcing cloud providers to offer granular, task-optimized pipelines rather than generic API access.
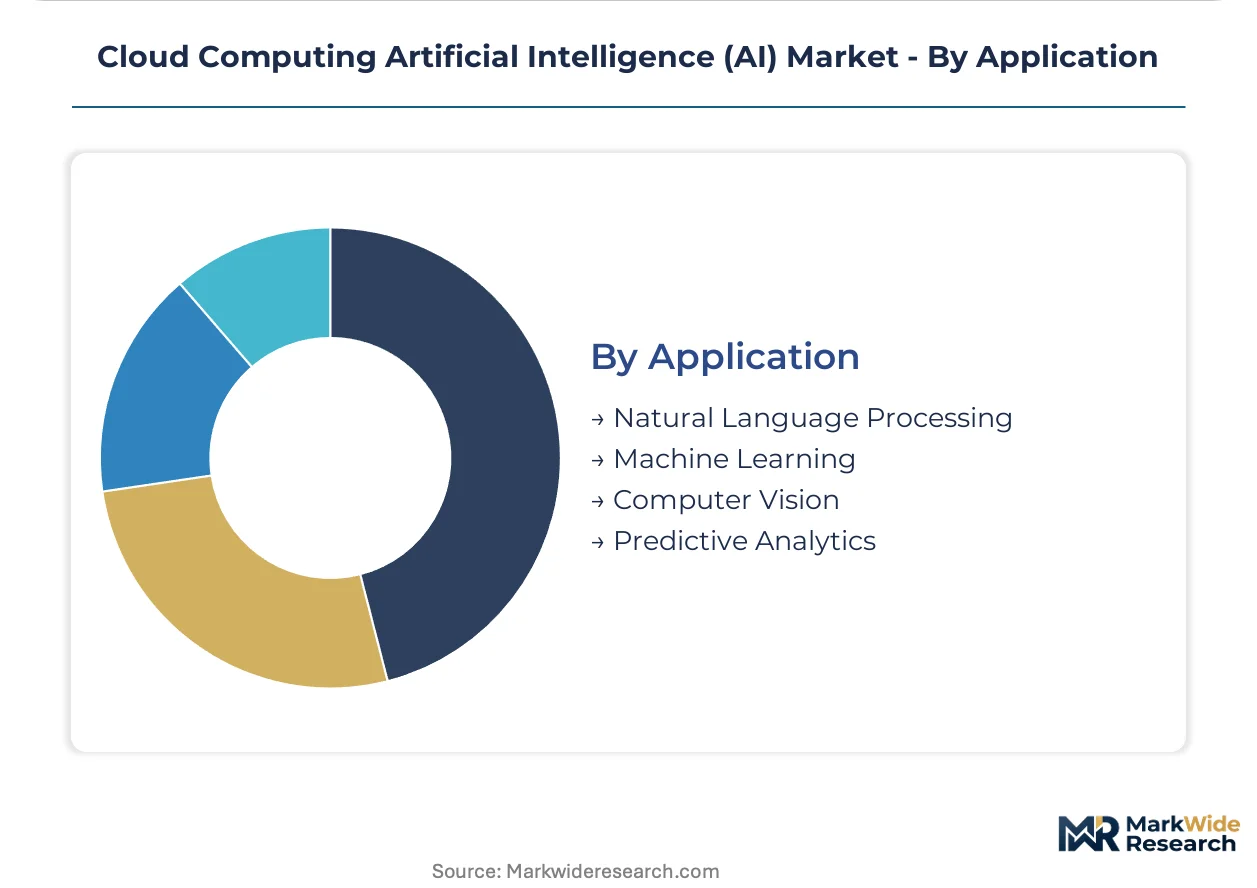
- Natural Language Processing:Text generation, summarization, and conversational interfaces delivered through token-based pricing. Enterprise customer service operations in the United States are consolidating around retrieval-augmented generation systems that ground outputs in proprietary document repositories.
- Computer Vision:Image classification, object detection, and video analysis for manufacturing quality control and medical imaging. Healthcare providers are deploying FDA-aligned diagnostic tools hosted on cloud infrastructure to eliminate on-premises GPU capital expenditure.
- Machine Learning:Custom model development and training pipelines for predictive and classification tasks.
- Predictive Analytics:Time-series forecasting and anomaly detection for supply chain and financial risk applications.
Natural Language Processing retains the dominant share, though Computer Vision is gaining share fastest as manufacturing and healthcare deployments accelerate regulatory-compliant inference at scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with United States defense contractors and federal agencies showing price-inelastic procurement for compliant infrastructure while Asia-Pacific startups and mid-market enterprises drive cost-sensitive consumption of inference services.
United States
Federal cloud modernization mandates and Pentagon AI contracts anchor hyperscale demand, with NIST's AI Risk Management Framework steering vendor selection toward documented model governance. Defense contractors in Northern Virginia and Seattle clusters consume GPU-intensive training clusters under multi-year contract vehicles. Healthcare providers in Boston and San Francisco metro areas deploy FDA-aligned diagnostic SaaS to eliminate on-premises capital expenditure.
China
SAMR algorithmic recommendation provisions and dual carbon goals reshape infrastructure deployment patterns, with state-backed enterprises prioritizing domestic accelerator supply chains. Alibaba Cloud anchors inference cost competition across Yangtze River Delta manufacturing hubs. Beijing-Tianjin-Hebei corridor concentrates government cloud procurement for smart city and surveillance AI workloads.
Germany
Industrial conglomerates in Bavaria and Baden-Württemberg pilot computer vision for quality control, bypassing corporate IT procurement through direct operational technology budgets. EU AI Act risk-tier classification forces documented conformity assessments for automotive and medical device AI. Frankfurt and Munich clusters host region-certified infrastructure for cross-border data residency compliance.
United Kingdom
Financial services firms in London deploy hybrid architectures to satisfy FCA operational resilience requirements while tapping public cloud burst capacity. NHS trusts trial AI diagnostic tools under MHRA guidance, segregating patient data onto UK-sovereign infrastructure. Cambridge and Oxford research clusters consume managed MLOps for foundation model fine-tuning.
India
Bengaluru and Hyderabad tech corridors drive startup consumption of low-code AI SaaS, with IT services exporters building proprietary fine-tuning pipelines for North American clients. BIS standards and RBI data localization norms accelerate domestic cloud infrastructure investment. Price-sensitive enterprise demand concentrates in Mumbai and Delhi-NCR for cost-efficient inference services.
Cloud Computing Artificial Intelligence (AI) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with hyperscale cloud providers dominating infrastructure scale while specialized hardware vendors capture pricing power at the accelerator layer. The market structure consolidates around three tiers: full-stack hyperscalers with global data center footprints, vertical AI infrastructure specialists, and regional cost-optimized challengers. Dominant competitive moves include strategic partnerships between cloud platforms and semiconductor vendors, plus geographic expansion through region-certified infrastructure builds.
Among hyperscale incumbents, Amazon Web Services, Microsoft Azure, and Google Cloud anchor the infrastructure layer, each representing a distinct geographic and regulatory positioning strategy. NVIDIA occupies the hardware archetype, exemplifying captive demand pull-through across all major cloud platforms. Alibaba Cloud sits within the regional challenger tier, navigating geopolitical constraints to compete on inference economics in price-sensitive Asian markets.
| Leading Market Players |
|---|
| Amazon Web Services |
| Google Cloud |
| Microsoft Azure |
| IBM Cloud |
| Oracle Cloud |
| NVIDIA |
| Salesforce |
| Alibaba Cloud |
| Intel Corporation |
| Others |
Pricing and Supply Chain Analysis
NIST's AI Risk Management Framework gates both supply qualification and price differentiation simultaneously, forcing cloud providers to maintain auditable model governance infrastructure that separates premium-certified instances from standard compute tiers. Compliance documentation costs concentrate in GPU-intensive training clusters serving United States federal agencies, while price-sensitive inference workloads migrate toward cost-optimized Asian facilities.
Pricing Analysis
Managed MLOps service contracts and extended fine-tuning support agreements drive lifetime value beyond raw compute provisioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under FDA-aligned diagnostic SaaS and NIST governance documentation. Cost compression in standard GPU instances is intensifying because hyperscale competition and Alibaba Cloud's Asia-Pacific inference economics force margin discipline. Startups and venture-backed companies exhibit highest price sensitivity, while United States defense contractors show price-inelastic procurement for compliant infrastructure.
Supply Chain Analysis
Inventory lead times for NVIDIA H100 and Blackwell architectures stretch across quarters due to TSMC foundry capacity constraints, concentrating pricing power at the accelerator layer. Hardware supply concentrates in Taiwan, South Korea, and the United States, with cloud providers drawing from captive NVIDIA allocations and Samsung memory supply. Single-source vulnerability around TSMC's advanced node production feeds from geopolitical exposure and export control friction. Distribution runs through direct hyperscale procurement contracts and channel partnerships with regional cloud challengers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where compliance certification creates switching costs that cement incumbent positions across federal and healthcare verticals.
For Market Incumbents: Fortify model governance documentation under NIST and EU AI Act requirements to deepen certification moats against emerging regional challengers. Expand backward integration into custom accelerator silicon through partnerships with TSMC and Samsung to secure foundry allocation. Prioritize capacity addition in Frankfurt and Northern Virginia clusters to capture cross-border data residency demand from regulated European enterprises. For New Entrants and Emerging Players: Differentiate on cost-efficient inference services for price-sensitive Southeast Asian manufacturing hubs, where Alibaba Cloud's geopolitical constraints create white-space for neutral infrastructure providers. Target India's Bengaluru and Hyderabad startup corridors with low-code MLOps SaaS that bypasses hyperscale procurement complexity. Pursue direct operational technology sales channels within United States industrial conglomerates, bypassing centralized IT procurement cycles. For Investors and Strategic Acquirers: EU AI Act enforcement milestones reshape the acquisition landscape toward targets with documented conformity assessment infrastructure and human-in-the-loop verification capabilities. Long-term viability hinges on regulatory entrenchment rather than pure technology differentiation, favoring vertical AI infrastructure specialists with embedded compliance workflows. Monitor FDA guidance publication timelines on AI-enabled medical devices as the signal indicating accelerated consolidation around certified diagnostic SaaS platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Region-Certified Infrastructure Buildout | EU AI Act risk-tier requirements force Frankfurt and Munich data center investments for cross-border compliance. |
| Managed MLOps Service Expansion | Talent scarcity in model fine-tuning pushes enterprises toward outsourced AI operations with recurring revenue structures. |
| Hybrid Cloud Architecture Partnerships | Financial services firms deploy on-premises GPU clusters with public cloud burst capacity under FCA guidance. |
| Accelerator Supply Agreement | NVIDIA H100 and Blackwell allocations anchor competitive positioning across United States defense contractor procurement. |
| Vertical Diagnostic SaaS Acquisition | FDA-aligned imaging platforms command premium pricing through seat-based subscriptions in Boston and San Francisco healthcare clusters. |
Research Methodology
Desk research of hyperscaler capex disclosures, federal procurement databases, and regulatory filing repositories preceded structured interviews with cloud platform engineers, healthcare IT procurement directors, federal agency technology officers, and MLOps service specialists. Primary fieldwork across United States, Germany, and India validated secondary data from NIST framework documentation, FDA guidance publications, and EU AI Act conformity assessment records. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure investment tracking.
Variance decomposition across service type, deployment model, and customer archetype dimensions structured the analytical framework over the projection horizon. Deployment architecture choices and regulatory compliance tier adoption patterns formed core segmentation inputs, with CAGRs derived from elasticity modeling against federal modernization spending trajectories. GPU supply concentration indices and managed services penetration rates served as industry-specific forecast modifiers throughout the modeling period.
Material uncertainties — export control expansion, foundry capacity allocation shifts, and divergent transatlantic regulatory enforcement — sit outside the modeled envelope. Forecasts reflect assumptions about sustained federal procurement velocity and stable accelerator supply relationships. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Enterprise Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Consumer Facing AI Products Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Assisted Robots Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Artificial Intelligence Chatbots Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market