
 Document Outsourcing Services Market | 2026-2036
Document Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Document Outsourcing Services Market Analysis
The direct sales channel for enterprise document outsourcing is fragmenting as vendor aggregators and managed service intermediaries capture mid-market accounts. Ricoh Company Ltd leverages its integrated hardware-software stack to sustain long-term service contracts with Japanese and European manufacturing clients. Iron Mountain Incorporated anchors its position through physical-to-digital lifecycle management, while Accenture Plc competes via consulting-led transformation engagements that bundle document workflow redesign with broader enterprise digitization.
Document outsourcing services encompass the transfer of document-intensive business processes to third-party providers, spanning physical printing, digital scanning, indexed storage, and automated data extraction with optical character recognition achieving accuracy rates above 99 percent in structured formats. These services eliminate in-house print infrastructure, reduce compliance risk, and accelerate retrieval times for regulated industries. Healthcare and BFSI verticals lead contract value due to stringent audit trail requirements and retention mandates, while hybrid delivery models capture the fastest growth as clients demand data residency controls alongside offshore cost advantages. Government agencies represent a concentrated margin pool where procurement cycles favor incumbent providers with security clearances and localized infrastructure.
HIPAA in the United States mandates access controls and audit logging for protected health information, directly expanding demand for compliant document management and destruction services. The EU AI Act and GDPR impose algorithmic transparency and data minimization requirements on automated document processing systems, reshaping vendor platform architectures. Stakeholders must monitor how emerging cross-border data transfer rulings affect offshore delivery economics and whether national security classifications restrict government contract participation by foreign-headquartered providers.
Market Dynamics
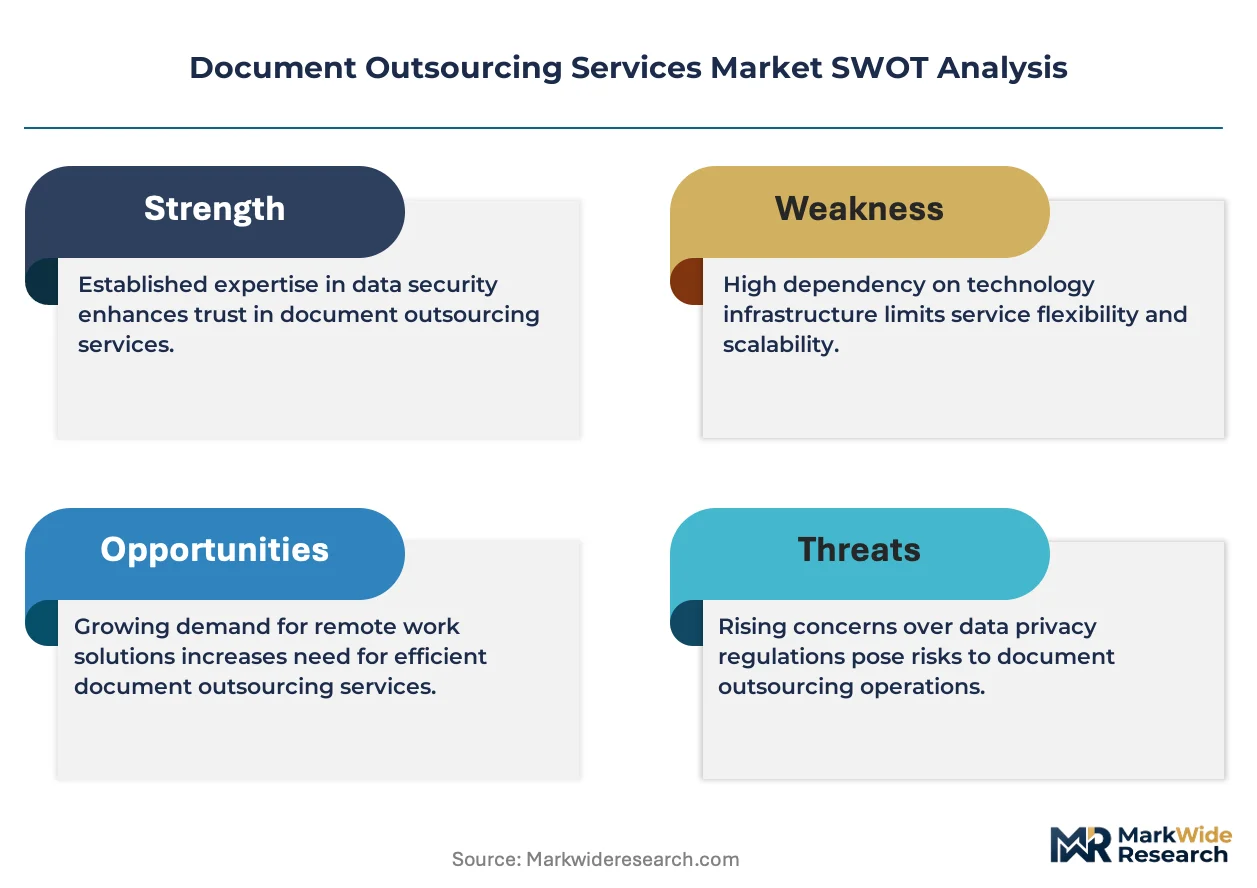
Cloud-native document platforms are compressing contract renewal cycles as enterprise buyers demand API-first architectures that bypass traditional print infrastructure entirely. HIPAA audit enforcement and EU AI Act algorithmic transparency mandates are accelerating replacement of legacy scanning workflows.
Growth Catalysts
- HIPAA Privacy Rule Enforcement:US healthcare providers face intensified OCR audits for protected health information handling, expanding demand for compliant document destruction and indexed storage services with immutable audit trails.
- AI-Driven OCR Convergence:Machine learning models achieving above 99 percent accuracy in structured format recognition are eliminating manual data entry bottlenecks in insurance claims and loan processing workflows.
- India BFSI Offshore Expansion:Mumbai and Bangalore delivery centers capture escalating contract volumes from North American and European banks seeking 24-hour document processing cycles through follow-the-sun operations.
Market Restraints
- Cross-Border Data Transfer Friction:Schrems II rulings and emerging adequacy decisions are complicating EU-US document flows, forcing vendors to provision redundant infrastructure in both jurisdictions.
- Specialized Hardware Concentration:High-speed production scanners and microfilm digitization equipment rely on concentrated Japanese and German component suppliers, exposing service providers to extended lead times.
- Substitution by Native Digital Workflows:Born-digital enterprise applications in SaaS-native sectors are bypassing paper-to-digital conversion entirely, compressing addressable market in technology-forward verticals.
Strategic Opportunities
- EU AI Act Compliance Services:Algorithmic transparency and human-in-the-loop documentation requirements create new revenue streams for vendors offering explainable OCR audit trails and model governance tooling.
- Hybrid Delivery Architecture:Clients demand data residency controls for sensitive categories alongside offshore cost advantages, favoring providers with tiered geographic processing capabilities.
- Small Law Firm Digitization:Underpenetrated sole practitioners and regional practices in Germany and France represent white space for standardized matter-file scanning and e-discovery preparation bundles.
Industry Challenges
- Legacy ECM Integration Complexity:Decades-old enterprise content management systems in government and healthcare require custom connector development, extending implementation timelines and eroding project margins.
- Certified Document Handler Shortage:Personnel with security clearances and chain-of-custody training for classified government material remain scarce, constraining expansion in federal contract pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Document Outsourcing Services Market |
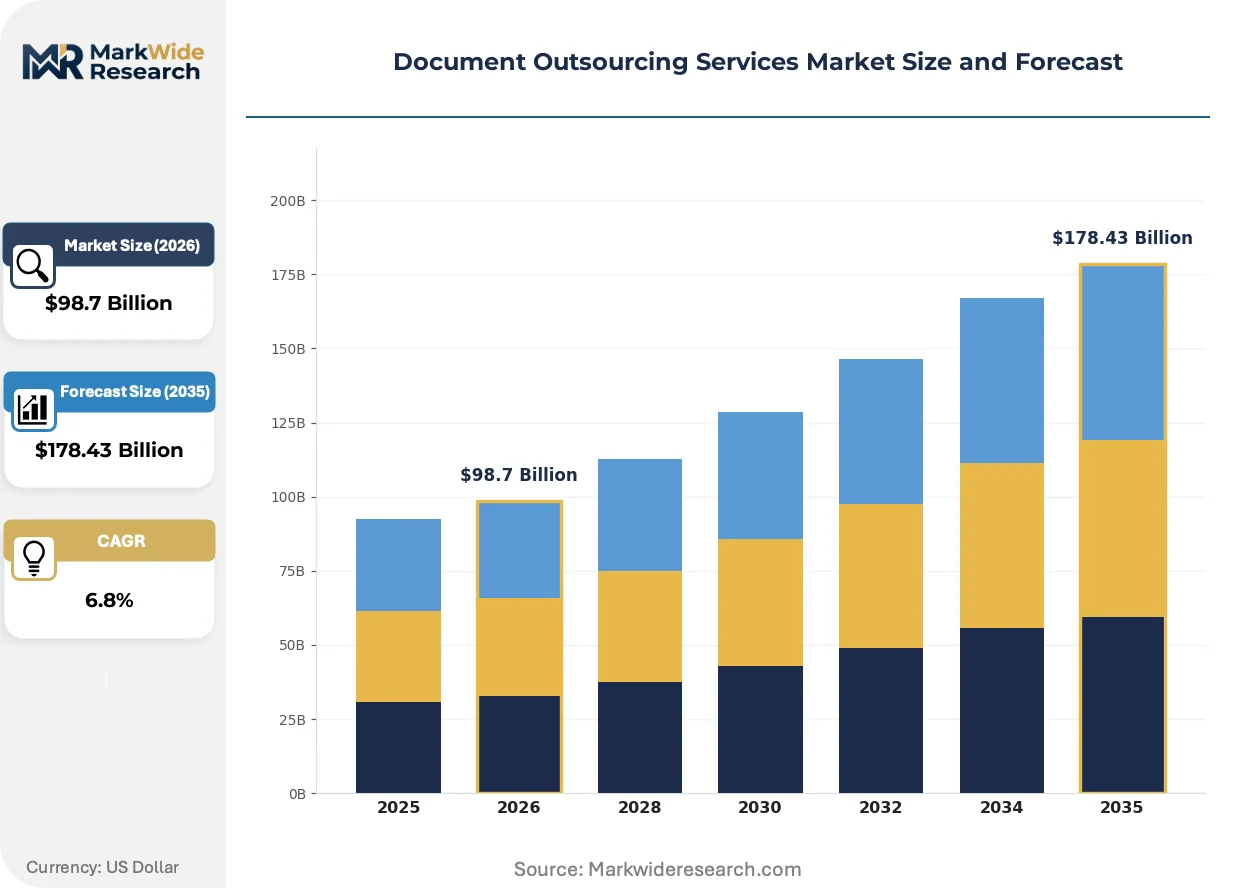
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Entry, Document Scanning, Document Management, Printing Services Industry Vertical: Healthcare, BFSI, Legal, Retail Delivery Model: Onshore, Offshore, Hybrid, Remote Client Type: SMEs, Corporates, Government Agencies, Non-Profit Organizations |
| Companies Covered | Ricoh Company Ltd, Iron Mountain Incorporated, HP Inc, Xerox Corporation, Fujifilm Business Innovation Co Ltd, Lexmark International Inc, Canon Inc, Konica Minolta Inc, Accenture Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Document Outsourcing Services Market Emerging Trajectories
Intelligent document processing is redefining service value from labor arbitrage toward cognitive automation, with vendors racing to embed generative capabilities that interpret unstructured content without template-based configuration.
Transformer-based large language models are rendering obsolete rules-based extraction systems that required thousands of manually labeled samples per document type. Healthcare revenue cycle management teams at US hospital networks are deploying these models for prior authorization document parsing, collapsing weeks of manual review into minutes while HIPAA audit logs capture every inference step.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on high-risk automated decision systems, including credit scoring and benefits eligibility document processing. Vendors serving European BFSI clients must now maintain technical documentation, human oversight protocols, and accuracy benchmarking that exceed prior GDPR accountability requirements. German automotive finance subsidiaries are restructuring vendor contracts to transfer algorithmic liability while demanding ISO-certified quality management systems.
Subscription-based consumption models are displacing per-page pricing in mid-market accounts, with buyers preferring predictable monthly fees aligned to document volume bands. Managed service intermediaries are capturing this shift by bundling scanning, storage, and extraction into unified SaaS offerings. This transition is most visible in UK professional services firms, where finance directors favor operational expenditure treatment over capital-intensive scanner procurement and facility expansion.
Document Outsourcing Services Market Segmentation
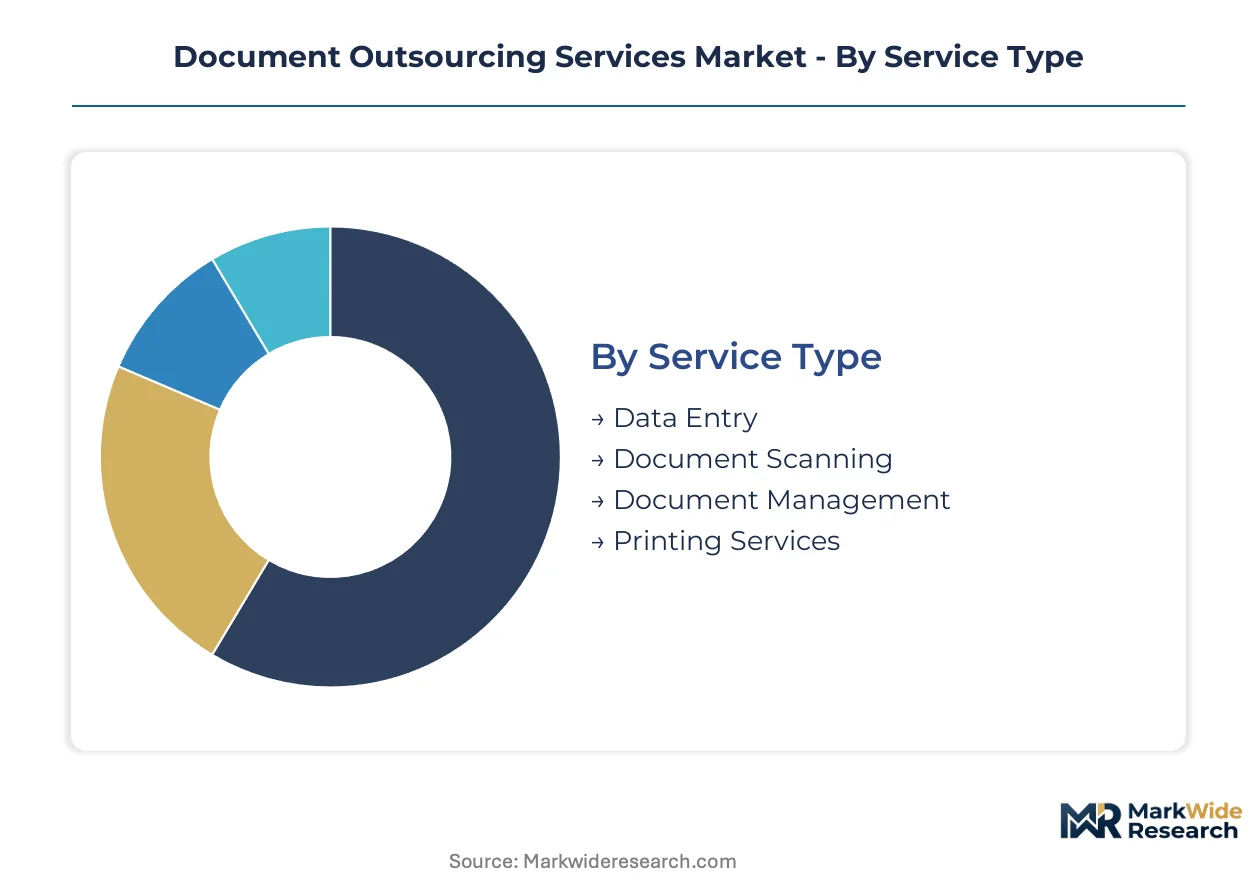
Document outsourcing services fragment across four critical dimensions that determine pricing architecture, delivery complexity, and compliance burden. Service type and delivery model configurations directly dictate infrastructure investment levels, while industry vertical and client type combinations shape regulatory exposure and contract duration patterns.
Service Type:
Mature process automation segments coexist with emerging cognitive extraction capabilities across the service spectrum.
- Data Entry:Manual transcription and structured field population from physical and digital sources, now augmented by human-in-the-loop validation layers. Demand concentrates in Indian BPO clusters serving US insurance claims processing, driven by HIPAA audit trail requirements that mandate dual-verification protocols for protected health information fields.
- Document Scanning:High-volume digitization with optical character recognition achieving above 99 percent accuracy in structured formats, encompassing microfilm conversion and large-format engineering drawings. German automotive suppliers and Japanese manufacturing affiliates in Thailand anchor demand, pressured by ISO-certified quality management mandates and supply chain documentation retention rules.
- Document Management:Cloud-native repository services with API-first architectures enabling enterprise system integration.
- Printing Services:Production print infrastructure for variable data marketing, transactional statements, and regulatory correspondence.
Document Scanning handles the majority of throughput; Data Entry is gaining share fastest as AI-augmented validation layers displace pure manual processing.
Industry Vertical:
Regulatory intensity varies sharply across verticals, with compliance-driven sectors commanding premium pricing for certified handling protocols.
- Healthcare:HIPAA-compliant destruction, indexed storage, and revenue cycle document parsing for US hospital networks and physician practice groups. OCR inference engines with immutable audit logs now collapse prior authorization review cycles from weeks to minutes, while OCR audit trails satisfy intensified Office for Civil Rights enforcement.
- BFSI:Loan origination document packages, KYC verification workflows, and trade finance documentation serving Mumbai and Bangalore delivery centers. EU AI Act algorithmic transparency requirements are restructuring vendor contracts for credit scoring automation, forcing conformity assessments and human oversight documentation.
- Legal:Matter-file digitization and e-discovery preparation for law firms and corporate legal departments.
- Retail:Supplier documentation, invoice processing, and customer correspondence management.
BFSI generates the highest contract values; Healthcare is expanding most quickly as OCR audit enforcement accelerates replacement of legacy scanning workflows.
Delivery Model:
Geographic configuration determines cost structure, data residency compliance, and operational continuity risk exposure.
- Onshore:Domestic processing centers satisfying strict data localization mandates for classified government material and sensitive financial records. US federal contracts and German automotive finance operations require cleared personnel and chain-of-custody certification that constrains supply expansion.
- Offshore:Follow-the-sun operations in Indian delivery centers capturing 24-hour processing cycles for North American and European banking clients. Schrems II rulings complicate EU-US document flows, forcing redundant infrastructure provisioning in both jurisdictions.
- Hybrid:Tiered geographic processing with sensitive categories handled onshore and bulk processing offshore.
- Remote:Distributed workforce models accelerated by cloud-native platform deployment.
Offshore maintains the largest volume base; Hybrid is climbing the fastest as clients demand data residency controls alongside cost advantages.
Client Type:
Procurement sophistication and contract scale diverge dramatically across organizational categories.
- SMEs:Subscription-based consumption models displacing per-page pricing, with UK professional services firms favoring operational expenditure treatment over capital-intensive scanner procurement. Standardized matter-file scanning bundles target underpenetrated sole practitioners in Germany and France.
- Corporates:Enterprise-wide master service agreements with integrated hardware-software stacks and long-term service contracts. Japanese and European manufacturing clients sustain relationships through embedded infrastructure and workflow redesign consulting.
- Government Agencies:Concentrated margin pools where procurement cycles favor incumbent providers with security clearances and localized infrastructure.
- Non-Profit Organizations:Grant-funded digitization initiatives and donor record management.
Corporates dominate absolute contract value; SMEs are expanding most quickly as managed service intermediaries capture mid-market accounts with unified SaaS offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Pune Expressway and Bangalore's Whitefield tech corridor anchor India's offshore delivery dominance, while Frankfurt's data center clusters and Tokyo's integrated manufacturing belts sustain onshore premium positioning.
United States
HIPAA Privacy Rule enforcement by the Office for Civil Rights accelerates healthcare provider migration to compliant document destruction and indexed storage services. Federal procurement cycles favor incumbent providers with security clearances for classified material handling. The Washington-Baltimore corridor concentrates government contract activity around cleared personnel pools.
Germany
EU AI Act algorithmic transparency mandates reshape vendor contracts for credit scoring automation in automotive finance subsidiaries. The country's national data protection regulator enforces GDPR data minimization requirements on automated document processing systems. Bavaria's Munich-Stuttgart industrial belt anchors demand from automotive suppliers facing ISO-certified quality management mandates.
India
Mumbai and Bangalore delivery centers capture escalating contract volumes from North American and European banks seeking 24-hour document processing cycles. The Reserve Bank of India's data localization guidelines pressure hybrid architecture adoption for sensitive financial records. Hyderabad's Gachibowli district emerges as a secondary hub for BFSI offshore expansion.
United Kingdom
Subscription-based consumption models displace per-page pricing among professional services firms favoring operational expenditure treatment. The Information Commissioner's Office enforces GDPR accountability requirements on automated decision systems. London's Square Mile and Canary Wharf concentrate legal sector digitization demand for matter-file scanning bundles.
Japan
Integrated hardware-software stacks sustain long-term service contracts with manufacturing clients facing supply chain documentation retention rules. METI's quality management standards pressure vendor certification for high-speed production scanner maintenance. Nagoya's Chubu industrial region anchors demand from automotive affiliates in Thailand requiring microfilm conversion services.
Document Outsourcing Services Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers. Hardware-integrated service providers leverage embedded infrastructure to capture multi-year contracts. Consulting-led transformation specialists bundle workflow redesign with broader enterprise digitization. Pure-play managed service intermediaries capture mid-market accounts through unified SaaS offerings. Dominant competitive moves include geographic footprint expansion through hybrid delivery architectures and technology licensing partnerships for AI-driven OCR capabilities.
Within the hardware-integrated tier, Ricoh Company Ltd and Canon Inc exemplify providers sustaining relationships through embedded print infrastructure and long-term service contracts. Accenture Plc occupies a distinct position among consulting-led transformation specialists, bundling document workflow redesign with enterprise-wide digitization engagements. Iron Mountain Incorporated anchors the physical-to-digital lifecycle management archetype, serving regulated industries with chain-of-custody certified handling protocols.
| Leading Market Players |
|---|
| Ricoh Company Ltd |
| Iron Mountain Incorporated |
| HP Inc |
| Xerox Corporation |
| Fujifilm Business Innovation Co Ltd |
| Lexmark International Inc |
| Canon Inc |
| Konica Minolta Inc |
| Accenture Plc |
| Others |
Supply Flow & Price Mechanics
Specialized hardware concentration in Japanese and German component suppliers determines both tiered pricing spreads and supply chain configuration. High-speed production scanners and microfilm digitization equipment anchor premium service tiers while extended lead times force buyers toward hybrid delivery architectures.
Pricing Analysis
Volume-discount tiering structures separate enterprise master service agreements from mid-market subscription bundles and transactional per-page arrangements. Three-tier pricing stratifies across HIPAA-certified healthcare handling, ISO-compliant manufacturing documentation, and standard business processing tiers. Cost compression in offshore delivery centers intensifies as Indian BPO clusters compete on 24-hour processing cycles. SMEs exhibit highest price sensitivity and favor operational expenditure models over capital-intensive infrastructure procurement.
Supply Chain Analysis
Contract manufacturing concentration rests with Japanese precision optics specialists and German engineering firms holding capacity for high-speed production scanner assembly. Component sourcing draws from Taiwan semiconductor foundries, Japanese imaging sensor fabricators, and German precision mechanical suppliers. Single-source vulnerability concentrates in specialized microfilm digitization equipment where replacement suppliers require extended qualification timelines. Distribution runs through vendor-direct enterprise sales, managed service intermediaries, and regional systems integrators serving mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Document outsourcing services function as a service-attach opportunity where AI-driven OCR subscriptions and compliance audit layers expand faster than hardware refresh cycles. Recurring revenue from algorithmic transparency documentation and human-in-the-loop validation protocols outpaces one-time digitization project fees.
For Market Incumbents: Harden defensible positions through embedded infrastructure lock-in with Japanese and European manufacturing clients facing supply chain documentation retention rules. Deepen certification investments for HIPAA and EU AI Act compliance to create switching costs. Acquire specialized AI OCR capabilities to preempt pure-play automation vendors from disintermediating data entry workflows. For New Entrants and Emerging Players: Pursue white-space penetration among underpenetrated sole practitioners and regional law practices in Germany and France lacking standardized matter-file scanning bundles. Target hybrid delivery architecture gaps where clients demand data residency controls alongside offshore cost advantages. Lead with subscription-based SaaS offerings that displace per-page pricing and capture operational expenditure budgets. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency mandates reshape the acquisition landscape toward vendors with explainable OCR audit trails and ISO-certified quality management systems. Long-term viability centers on providers bridging physical-to-digital lifecycle management with cognitive automation capabilities. Monitor Schrems II adequacy decisions as the signal indicating whether redundant EU-US infrastructure provisioning becomes a permanent cost structure or temporary friction.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven OCR Platform Integration | Machine learning models achieving above 99 percent accuracy in structured formats collapse manual review cycles from weeks to minutes. |
| Hybrid Delivery Architecture Expansion | Tiered geographic processing capabilities satisfy data residency controls for sensitive categories alongside offshore cost advantages. |
| EU AI Act Compliance Service Bundling | Algorithmic transparency documentation and human-in-the-loop protocols create new revenue streams beyond commoditized scanning. |
| Small Law Firm Digitization Packaging | Standardized matter-file scanning and e-discovery preparation bundles capture underpenetrated sole practitioners in Germany and France. |
| Certified Handler Workforce Development | Security clearance and chain-of-custody training programs unlock concentrated margin pools in federal government contract pools. |
Methodological Framework
Desk research of SEC filings, customs trade records, and healthcare procurement databases preceded structured interviews with document operations directors, compliance officers at HIPAA-covered entities, BFSI procurement leads, and managed service provider executives. Primary fieldwork across Mumbai, Bangalore, Frankfurt, and Tokyo delivery centers validated volume and pricing assumptions. Bottom-up service line analysis triangulated against top-down macroeconomic indicators and regulatory enforcement trends.
Assumptions held fixed include prevailing HIPAA audit enforcement intensity, Schrems II data transfer restrictions, and Indian BFSI offshore expansion trajectories. Variables modeled across the analysis window encompass AI OCR accuracy improvement curves, subscription pricing adoption rates, and hybrid delivery architecture penetration. Segmentation dimensions covered service type, industry vertical, delivery model, and client size tier. CAGRs derived from historical contract value analysis and forward pipeline assessment weighted by regulatory catalyst timing.
Macroeconomic conditions sit as an overlay; deviation in central bank rate cycles, cross-border data transfer rulings, or healthcare reimbursement compression would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption S-curves and regulatory enforcement cadence. Quarterly review of OCR accuracy benchmarking, HIPAA audit penalty trends, and EU AI Act conformity assessment timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Cloud Bpo Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Contract Management Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Business Process Re-Engineering Market
Business Process Outsourcing (BPO)
Business Process Automation (BPA) Market