
 Service Bureau Market | 2026-2036
Service Bureau Market Size, Share, and Industry Trends Forecast 2026-2036
Service Bureau Market Outlook
Aftermarket service revenue is fragmenting across document processing, cloud migration, and managed compliance activities. Iron Mountain Incorporated anchors its position through physical-to-digital archive transitions and information governance services. Ricoh Company, Ltd. competes via integrated print-cloud hybrid platforms targeting enterprise workflows. Xerox Corporation differentiates through AI-augmented document analytics and workflow automation tools.
A service bureau operates as a third-party processor handling high-volume data entry, document conversion, print production, and transactional output for client organizations, typically employing production-scale scanning infrastructure at resolutions exceeding 300 dpi and automated optical character recognition pipelines. The primary commercial purpose centers on reducing per-transaction processing costs while ensuring audit-ready chain-of-custody documentation. Document Management services occupy the mature margin pool as enterprises consolidate legacy paper archives, while Cloud-based delivery models represent the fastest-expanding segment as hybrid work policies persist. Billing Solutions within finance and healthcare verticals sustain premium pricing due to embedded compliance requirements.
FDA information governance standards for healthcare records, HIPAA privacy mandates, and GDPR data-localization rules in Europe collectively elevate vendor certification barriers and reshape procurement criteria toward audited security frameworks. The SEC's electronic recordkeeping requirements for financial intermediaries further tighten acceptable service bureau infrastructure standards. Stakeholders must evaluate vendor resilience against evolving multi-jurisdictional compliance obligations before committing to long-term outsourcing contracts.
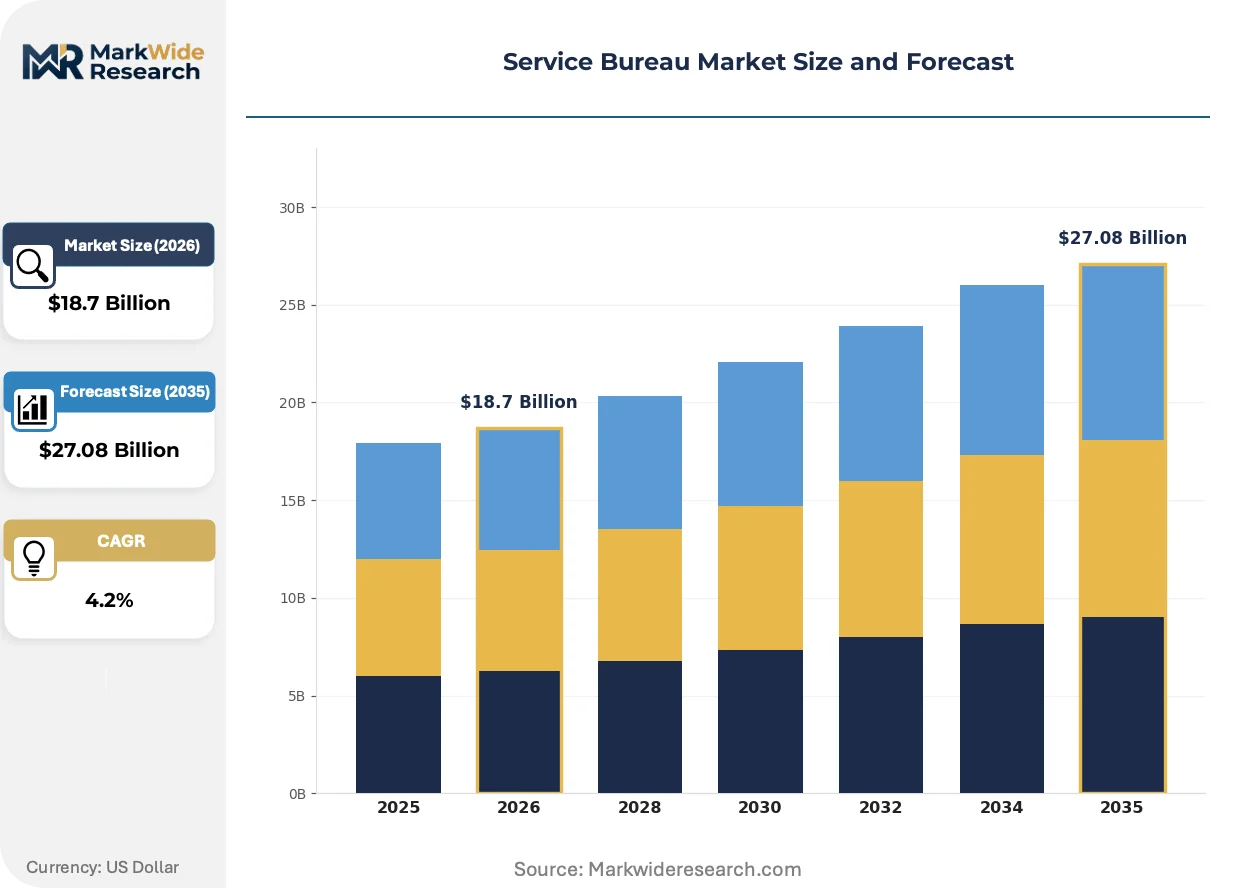
Market Dynamics
Cloud migration mandates and data sovereignty requirements are compressing vendor selection cycles while elevating compliance infrastructure costs. Healthcare and financial services buyers now demand audited security frameworks before contract execution.
Growth Catalysts
- HIPAA Privacy Mandates:Healthcare providers outsource document digitization to meet chain-of-custody requirements. Third-party processors with certified infrastructure capture expanding claims processing volumes.
- AI-Augmented OCR Pipelines:Automated character recognition at production scale reduces per-transaction costs. Enterprise buyers prioritize vendors with integrated analytics capabilities.
- United States:Federal agencies deepen back-office outsourcing under electronic recordkeeping directives. State-level Medicaid expansion drives document processing demand.
Market Restraints
- GDPR Data-Localization:European storage mandates fragment infrastructure deployment. Vendors face duplication costs across jurisdictional boundaries.
- Specialized Compliance Talent:Shortage of auditors familiar with FDA information governance standards extends certification timelines. Labor scarcity elevates wage pressure.
- Legacy Archive Migration:Physical-to-digital transitions require capital-intensive scanning infrastructure at 300+ dpi resolution. Smaller bureaus lack balance sheet capacity.
Strategic Opportunities
- SEC Electronic Recordkeeping:Financial intermediary mandates create certified vendor demand. Compliance-forward bureaus capture broker-dealer outsourcing.
- Hybrid Work Persistence:Distributed workforce models sustain cloud-based delivery growth. Document Management vendors expand managed service attachments.
- Print-Cloud Convergence:Integrated platforms bridge physical output and digital workflow. Enterprise buyers consolidate vendor relationships.
Industry Challenges
- Multi-Jurisdictional Certification:Vendors must maintain parallel HIPAA, GDPR, and SEC compliance frameworks. Audit costs consume operational resources.
- Legacy System Integration:Client ERP and ECM platforms require custom API development. Project delays erode margin on fixed-price contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Bureau Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Processing, Document Management, Print Services, Billing Solutions Industry Vertical: Healthcare, Finance, Retail, Education Delivery Model: On-premises, Cloud-based, Hybrid, Remote Customer Type: Small Enterprises, Large Corporations, Government Agencies, Non-profits |
| Companies Covered | Iron Mountain Incorporated, Ricoh Company, Ltd., Xerox Corporation, Canon Business Process Services, Exela Technologies, Inc., HP Inc., Konica Minolta, Inc., Kodak Alaris, ARC Document Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Bureau Market Strategic Shifts
Document processing infrastructure is hybridizing across physical and digital delivery modes. Regulatory pressure accelerates automation investment while buyer consolidation favors integrated platform vendors.
Intelligent document analytics is hybridizing transactional output with predictive workflow routing. Financial services buyers deploy these tools for real-time compliance monitoring. The technology compresses manual review cycles while embedding audit trails.
GDPR enforcement actions against cross-border data transfers are reshaping vendor infrastructure strategies. European buyers now require region-specific storage with cryptographic segregation. Healthcare and government segments in Germany and France lead procurement toward sovereign cloud architectures.
Buyer concentration among Fortune 500 enterprises is consolidating vendor relationships around full-service contracts. Mid-market bureaus face displacement unless they embed into larger platform ecosystems. The United States exhibits the fastest contract value compression as procurement teams standardize on three-year master agreements.
Service Bureau Market Segmentation
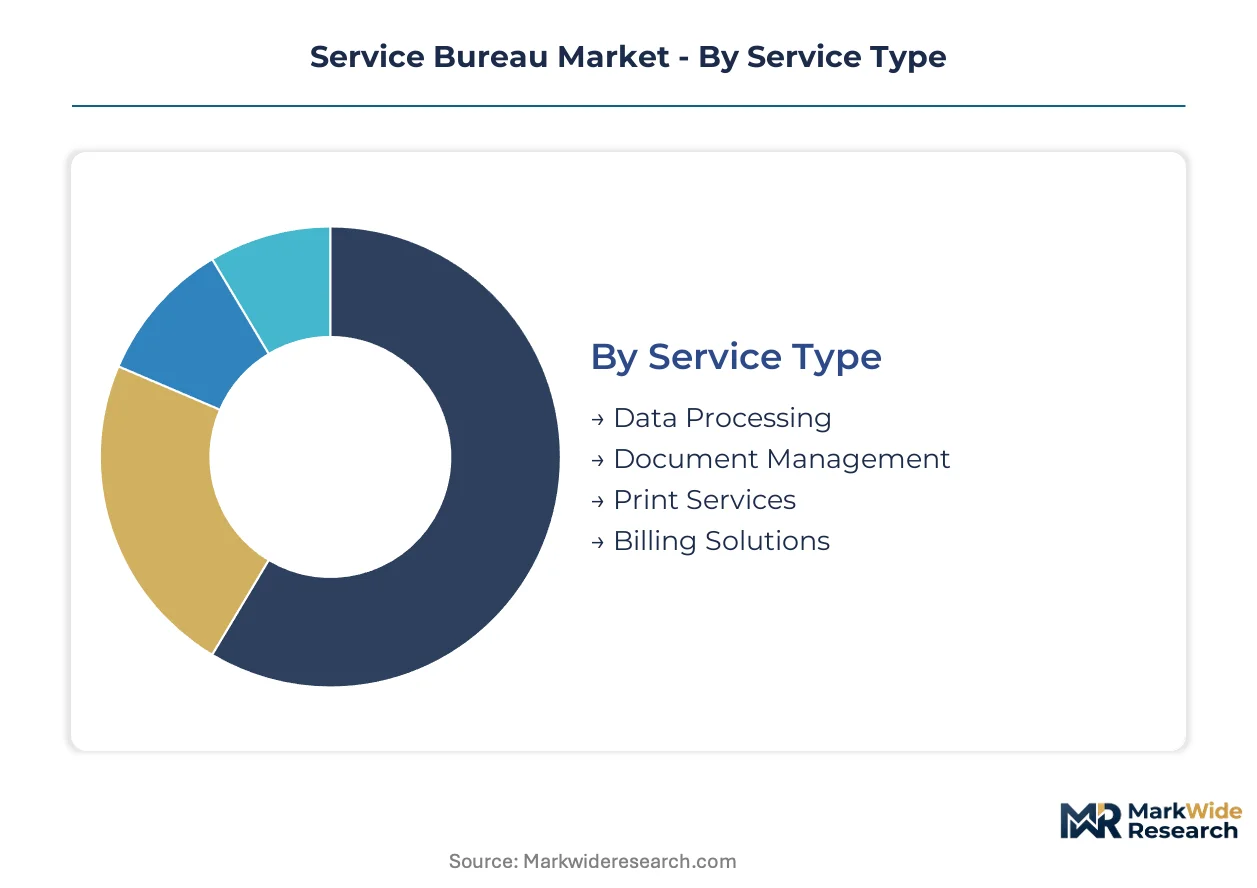
Service bureau procurement decisions hinge on compliance requirements, transaction volumes, and legacy infrastructure footprints. Segmentation reveals where margin pools concentrate and which delivery models capture expanding outsourcing mandates.
Service Type:
Use-case spectrum spans high-frequency transactional processing through archival governance and physical output management.
- Data Processing:High-volume transaction entry and validation pipelines handle claims, payments, and records at production scale. Healthcare providers and financial intermediaries outsource core processing to meet audit-ready chain-of-custody standards under HIPAA and SEC frameworks.
- Document Management:Physical-to-digital archive transitions and information governance services anchor mature revenue streams. Enterprise consolidation of legacy paper archives drives sustained demand across regulated industries requiring 300+ dpi scanning infrastructure and automated OCR pipelines.
- Print Services:Production-scale transactional output and variable data printing for statements, notices, and compliance documents.
- Billing Solutions:Embedded compliance workflows for healthcare claims and financial statements command premium pricing due to certification requirements.
Established volume favors Document Management; emerging adoption favors Data Processing.
Industry Vertical:
Cost tier stratification separates regulated sectors with certification premiums from price-sensitive volume segments.
- Healthcare:HIPAA-mandated digitization and FDA information governance standards elevate vendor barriers. Hospital systems and payers outsource claims processing and medical records conversion to certified bureaus with audited security frameworks.
- Finance:SEC electronic recordkeeping requirements and broker-dealer compliance create specialized demand for audit-trail documentation and real-time monitoring capabilities.
- Retail:High-volume transactional processing for statements and marketing communications prioritizes per-unit cost reduction over compliance premiums.
- Education:Credential verification and alumni record management represent fragmented, lower-margin opportunities.
Regulatory density favors Finance; transaction scale favors Retail.
Delivery Model:
Application requirements dictate infrastructure deployment across physical, cloud, and hybrid architectures.
- On-premises:Dedicated scanning and print infrastructure for classified government documents and sensitive financial records requiring air-gapped custody chains.
- Cloud-based:Distributed workforce enablement and elastic capacity for seasonal volume spikes in tax processing and enrollment periods. GDPR data-localization mandates fragment European deployment strategies.
- Hybrid:Bridging legacy physical archives with cloud analytics platforms, this model captures enterprise buyers consolidating vendor relationships across print-digital workflows.
- Remote:Home-agent data entry and quality assurance for non-sensitive transactions, constrained by information security audit requirements.
Compliance rigidity favors On-premises; flexibility demands favor Hybrid.
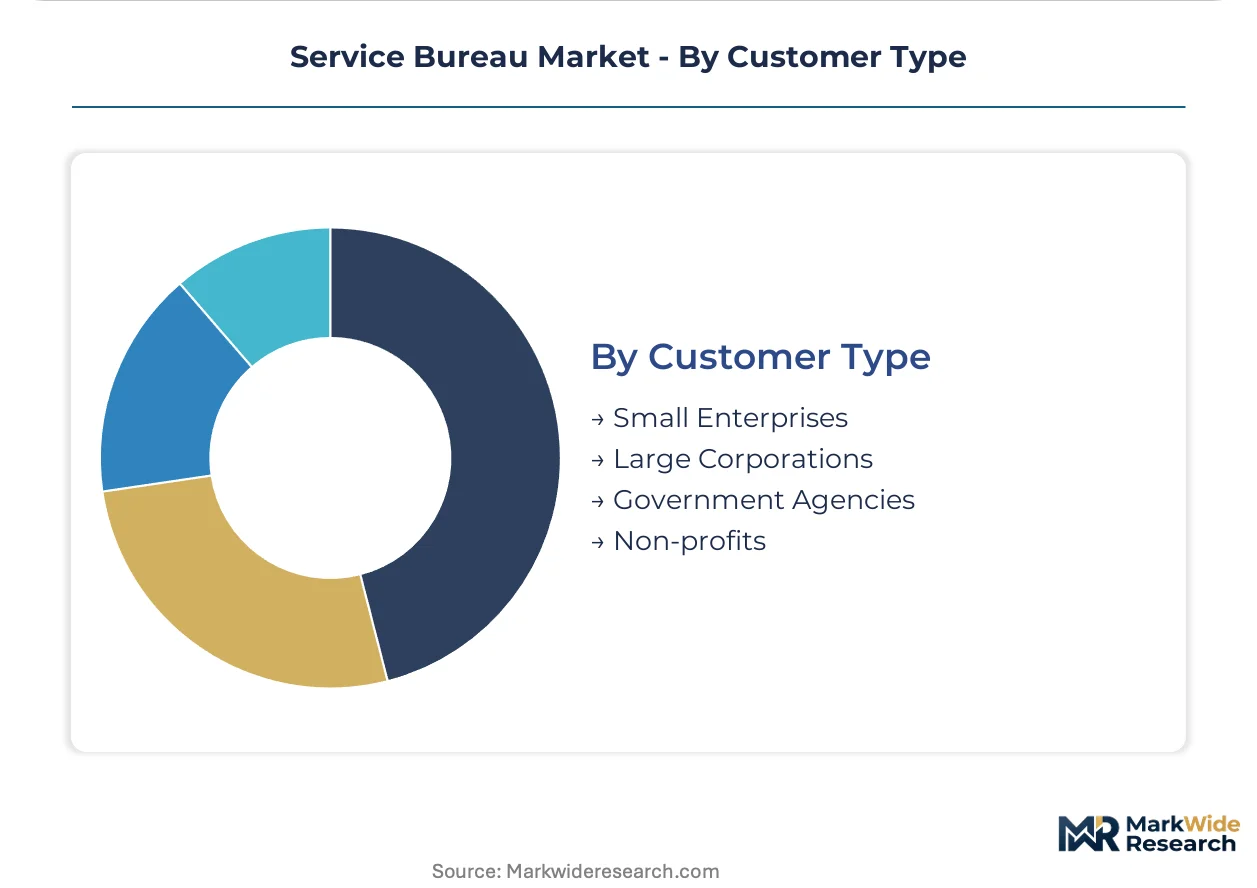
Customer Type:
Volume concentration and contract sophistication separate procurement behaviors across organizational scale.
- Small Enterprises:Transactional outsourcing of payroll, invoicing, and document conversion without dedicated compliance staff.
- Large Corporations:Master service agreements spanning multiple geographies with standardized security frameworks and three-year contract structures compressing vendor margins.
- Government Agencies:Federal electronic recordkeeping directives and state Medicaid expansion drive document processing demand with stringent certification timelines.
- Non-profits:Donor management and grant compliance documentation at reduced rates, sensitive to funding cycles.
Contract value favors Large Corporations; growth velocity favors Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity, absorbing compliance premiums for HIPAA and SEC-certified infrastructure, while retail and education segments in emerging markets drive commoditization pressure on per-transaction rates.
United States
Federal agencies and healthcare systems dominate procurement volume through electronic recordkeeping mandates and Medicaid expansion programs. HIPAA and SEC regulations enforce audited security frameworks as table stakes for contract eligibility. The Washington D.C.-Boston corridor concentrates government outsourcing demand, while Texas and California anchor commercial healthcare digitization clusters.
Germany
Industrial Mittelstand firms and automotive suppliers outsource document governance to meet CSRD reporting requirements and supply chain traceability standards. GDPR data-localization rules enforce cryptographic segregation for cross-border workflows. The Rhine-Ruhr and Stuttgart regions host dense concentrations of manufacturing headquarters driving hybrid print-cloud procurement.
United Kingdom
Financial services firms in the City of London and Canary Wharf deploy service bureaus for real-time compliance monitoring under FCA electronic recordkeeping rules. NHS digitization programs sustain healthcare document processing demand. Post-Brexit data adequacy negotiations complicate vendor selection for EU-facing operations.
Japan
Financial intermediaries and pharmaceutical manufacturers drive demand for JIS-compliant archival systems and METI-mandated electronic document retention. Aging workforce demographics accelerate automation investment in back-office functions. The Tokyo-Osaka corridor concentrates enterprise procurement, while regional banks outsource to certified bureaus for cost containment.
India
IT services exporters and domestic banks leverage service bureaus for RBI-mandated document retention and GST compliance workflows. Cost arbitrage attracts multinational corporations seeking offshore processing for non-sensitive transactions. Bengaluru and Hyderabad anchor technology-driven digitization demand, while Mumbai concentrates financial services outsourcing.
Service Bureau Market Competitive Environment
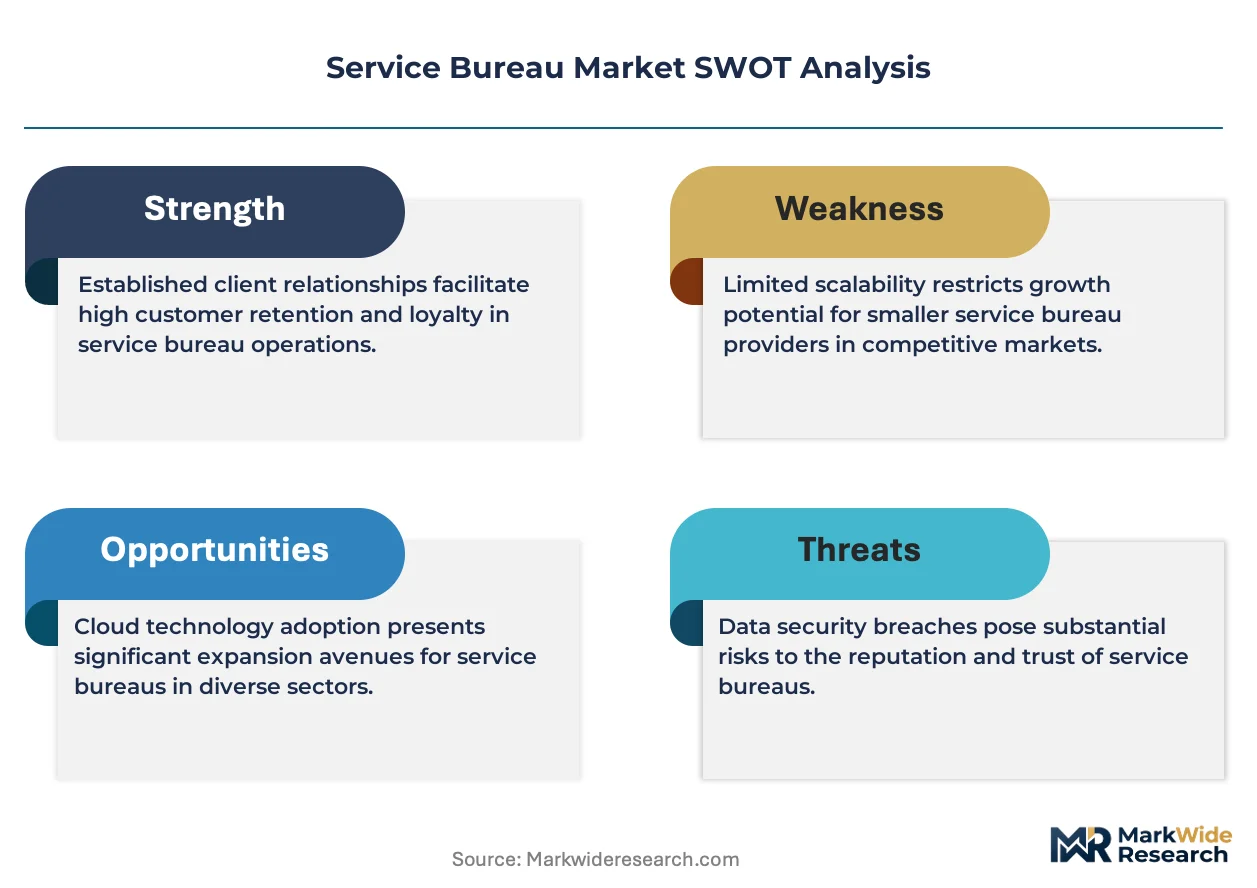
Capability concentration sits with specialized compliance infrastructure providers; scale advantage sits with integrated platform vendors spanning physical and digital delivery. The market exhibits tiered consolidation, with three to five full-service providers capturing Fortune 500 master agreements while mid-market specialists defend niche verticals. Strategic archetypes include compliance-forward certification leaders, print-cloud hybrid integrators, and legacy archive migration specialists. Competitive moves center on M&A to absorb regional compliance capabilities and strategic partnerships to embed analytics layers.
Within the integrated platform tier, Iron Mountain Incorporated and Ricoh Company, Ltd. exemplify divergent scale strategies—one anchored in physical-to-digital archive transitions, the other in enterprise workflow consolidation. Xerox Corporation occupies a position emphasizing AI-augmented document analytics as a differentiation vector against commoditized scanning services.
| Leading Market Players |
|---|
| Iron Mountain Incorporated |
| Ricoh Company, Ltd. |
| Xerox Corporation |
| Canon Business Process Services |
| Exela Technologies, Inc. |
| HP Inc. |
| Konica Minolta, Inc. |
| Kodak Alaris |
| ARC Document Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European GDPR-compliant data centers is compressing vendor margins while elevating pricing power for certified infrastructure providers serving healthcare and financial services buyers across Germany and France.
Pricing Analysis
Managed compliance service contracts drive lifetime value in this market. Three-tier pricing structure across certified-premium, standard-audit, and economy-basic levels captures divergent risk tolerances. HIPAA and SEC certification tiers command substantial premiums due to auditor scarcity. Cost compression in economy scanning services is intensifying because offshore competitors are entering transactional document processing. Retail and education segments exhibit highest price sensitivity; government agencies and large financial intermediaries show lowest elasticity.
Supply Chain Analysis
Extended payment terms from Fortune 500 procurement teams are forcing mid-tier bureaus to seek supply-chain finance facilities. Production-scale scanning infrastructure concentrates in the United States, Germany, and Japan. Supply chains draw from specialized optical components, production-grade scanner hardware, and certified data center real estate. Single-source vulnerability in high-resolution imaging sensor supply creates concentration risk. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified compliance infrastructure represents the scarcest capability in this market, with qualified HIPAA and SEC auditors commanding premium wages and extending vendor certification timelines by months.
For Market Incumbents: Insulate core revenue by embedding AI-augmented OCR capabilities into existing client workflows before cloud-native competitors achieve feature parity. Acquire regional compliance specialists in Germany and France to satisfy GDPR data-localization mandates without duplicating infrastructure costs. Prioritize certification investment as the defensive lever against margin compression. For New Entrants and Emerging Players: Establish a beachhead in mid-market healthcare digitization, where hospital systems lack internal compliance staff but require HIPAA-certified processing. Target state-level Medicaid expansion programs in the United States Southeast and Southwest as the most penetrable geography. Pursue channel partnerships with electronic health record vendors as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid print-cloud platform providers with three-year master service agreements. Long-term viability hinges on regulatory complexity persisting across HIPAA, GDPR, and SEC frameworks. Acquire compliance-forward bureaus with existing auditor relationships. Watch for SEC enforcement action intensity as the inflection signal for broker-dealer outsourcing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Investment | FDA and SEC auditor relationships create defensible moats against commodity competitors. |
| Hybrid Platform Integration | Print-cloud convergence captures enterprise buyers consolidating physical and digital vendor relationships. |
| Geographic Compliance Expansion | GDPR-localized data centers in Germany and France satisfy European healthcare procurement requirements. |
| AI-Augmented OCR Development | Automated character recognition at production scale reduces per-transaction costs for high-volume clients. |
| Strategic Partnership with EHR Vendors | Electronic health record integrations embed service bureaus into hospital system workflows. |
Study Parameters
The analysis maps document processing, cloud migration, and managed compliance sub-sectors, each validated through service bureau operations directors, healthcare IT procurement managers, financial services compliance officers, and government contracting specialists. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, FDA information governance guidance documents, GDPR enforcement action records, and hospital procurement databases. Bottom-up transaction volume estimates and top-down market sizing were triangulated to produce convergent figures.
Fixed assumptions included persistent hybrid work policies, continued HIPAA and SEC regulatory enforcement, and stable healthcare outsourcing appetite; varied conditions included GDPR cross-border data transfer rulings and federal Medicaid expansion velocity. The projection horizon spans service type, delivery model, industry vertical, and customer size tier dimensions. CAGRs were derived from regression analysis against historical outsourcing penetration rates and compliance cost inflation. Forecast inputs incorporated scanner infrastructure deployment cycles and certified auditor labor supply constraints.
Stress conditions across regulatory enforcement intensity, healthcare reimbursement policy shifts, and cloud infrastructure cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from multi-jurisdictional compliance evolution or technological substitution in document analytics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
BPO Business Analytics Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Employment Screening Services Market
Business Process Outsourcing (BPO)
Front Office BPO Services Market
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Direct to Customer Outsourced Fulfillment Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Cloud Based BPO Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Europe Business Process Outsourcing (BPO) Market