
 Business Processing Outsourcing Market | 2026-2036
Business Processing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Business Processing Outsourcing Market Outlook
Delivery channel architecture for enterprise outsourcing contracts is reconfiguring as buyers seek integrated digital-first partnerships. Accenture plc leverages its consulting-to-operations continuum to anchor complex transformation deals. Tata Consultancy Services Limited dominates captive center transitions with its Global Network Delivery Model. Cognizant competes on healthcare and banking vertical depth with domain-specific platforms.
Business processing outsourcing encompasses the delegation of operational functions—customer interaction management, financial transaction processing, human capital administration, and information technology operations—to third-party providers executing workflows through cloud-based platforms, AI-augmented automation tools, and standardized service level agreements. Its primary commercial purpose is cost arbitrage combined with operational scalability for enterprises seeking to convert fixed labor overhead into variable expenditure. Customer Support and Finance & Accounting represent mature, high-volume service lines where margin pools have compressed toward efficiency benchmarks, while IT Services and Human Resources segments attract premium pricing through specialized technical talent and compliance-driven demand. Offshore and Hybrid engagement types are expanding fastest as clients balance cost optimization with geopolitical risk mitigation across delivery locations.
India's BIS and IT Act frameworks govern data localization and cybersecurity standards for outsourcing providers handling sensitive client information. The EU GDPR and Digital Operational Resilience Act impose cross-border data transfer constraints and incident reporting obligations on European-destined services. India's PLI scheme for IT and BPM services shapes capacity investment incentives, while the Philippines' PEZA regulations sustain special economic zone status for voice operations. Stakeholders must monitor evolving data sovereignty mandates and automation displacement thresholds as determinants of contract structuring and geographic delivery strategy.
Market Dynamics
Generative AI deployment across customer interaction workflows is compressing headcount requirements while forcing providers to restructure pricing models away from per-seat toward outcome-based arrangements.
Growth Catalysts
- Healthcare RCM expansion:US hospital systems facing Medicare reimbursement complexity are delegating end-to-end revenue cycle functions to specialized BPO operators.
- India's PLI scheme:The production-linked incentive framework for IT and BPM services accelerates delivery center construction in Tier-2 cities.
- Cloud-native platforms:Containerized microservices architecture enables providers to onboard enterprise clients without legacy infrastructure integration delays.
Market Restraints
- Data localization mandates:India's BIS and IT Act frameworks impose physical server requirements that increase facility capex for cross-border contracts.
- Geographic concentration risk:Voice operations concentrate in Philippine PEZA zones, exposing buyers to typhoon disruption and geopolitical friction.
- Automation displacement threshold:Rule-based process automation eliminates tier-1 support roles faster than reskilling programs replenish mid-tier talent pipelines.
Strategic Opportunities
- Underpenetrated Middle East:Saudi Arabia and UAE healthcare privatization creates first-mover advantage for RCM and claims processing specialists.
- AI-human convergence:Combining large language models with domain-trained agents unlocks premium pricing for complex dispute resolution and clinical coding.
- EU DORA compliance services:The Digital Operational Resilience Act mandates incident reporting and third-party risk management, creating managed service demand.
Industry Challenges
- Agent attrition in voice operations:Philippine contact centers face 35-45% annual turnover, forcing continuous recruitment and training expenditure.
- Legacy system entanglement:Banking and insurance clients maintain decades-old core platforms that resist API-based integration with modern BPO workflows.
- GDPR cross-border friction:EU clients demand contractual guarantees on data residency that conflict with multi-shore delivery optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Processing Outsourcing Market |
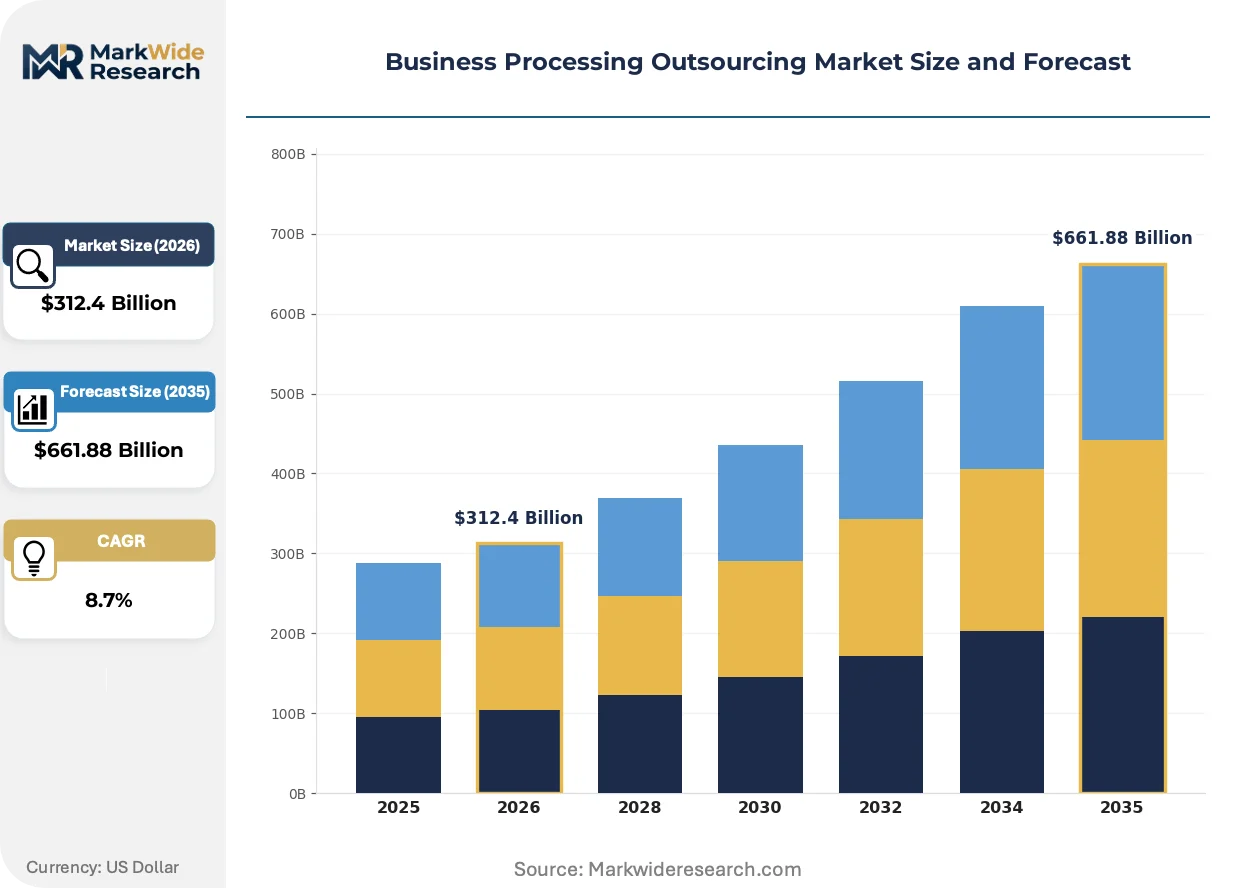
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $661.88 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IT Services, Customer Support, Finance & Accounting, Human Resources Industry Vertical: Healthcare, Retail, BFSI, Telecommunications Engagement Type: Onshore, Offshore, Nearshore, Hybrid Client Size: SMEs, Large Enterprises, Startups, Corporations |
| Companies Covered | Accenture plc, Tata Consultancy Services Limited, Concentrix Corporation, Teleperformance SE, Genpact Limited, Cognizant, Wipro Limited, TTEC Holdings, Inc., HCL Technologies Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Processing Outsourcing Market Strategic Shifts
Intelligent automation is dissolving the boundary between transactional processing and advisory services, forcing providers to retrain workforces and reengineer delivery architectures around real-time decision support rather than scripted responses.
Conversational AI is hybridizing rule-based chatbot infrastructure with generative response capabilities. Banking and telecom clients in North America and Western Europe are deploying these systems for tier-1 inquiry resolution at accelerating velocity. This convergence is compressing pricing for basic voice interactions while expanding margin pools for exception-handling and escalation management.
The EU AI Act imposes risk classification and documentation requirements on automated decision systems used in credit scoring and insurance underwriting. BPO providers serving European financial services must now maintain algorithmic audit trails and human-in-the-loop protocols. Healthcare claims processing and lending operations face the steepest compliance cost increases as they scramble to retrofit existing automation stacks.
Enterprise buyers are unbundling monolithic outsourcing contracts into modular, best-of-breed engagements. Procurement teams now source customer experience analytics, payment processing, and HR administration from separate specialists rather than single full-service vendors. This fragmentation is most pronounced among Fortune 500 manufacturers with complex multi-country footprints, who prioritize domain depth over relationship consolidation.
Business Processing Outsourcing Market Segmentation
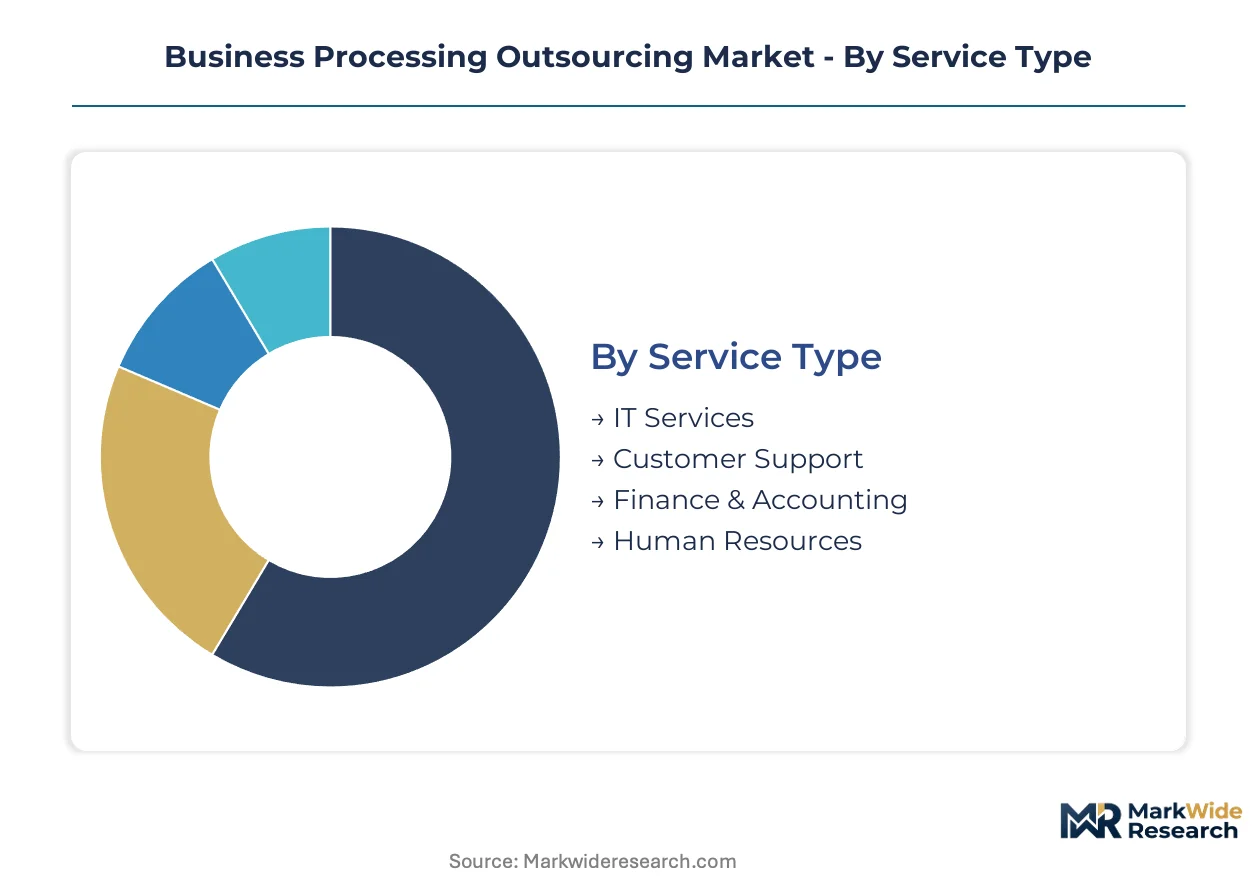
BPO procurement teams segment contracts by technical complexity and ongoing service intensity rather than upfront cost alone. Each segmentation dimension reveals distinct margin structures and renewal patterns that shape provider strategy.
Service Type:
After-sales-service intensity varies sharply across service lines, with technical support and compliance-driven functions demanding sustained client engagement.
- IT Services:Cloud infrastructure management and application development require continuous monitoring and iterative deployment cycles. Demand concentrates among US and European financial services firms modernizing legacy core systems under regulatory pressure from the EU Digital Operational Resilience Act.
- Customer Support:Voice and digital interaction management operates through tiered escalation protocols with 24/7 coverage obligations. Philippine delivery centers handle the majority of English-language voice volumes, though attrition rates of 35-45% annually inflate recruitment and training costs.
- Finance & Accounting:Accounts payable, receivable, and general ledger maintenance follow standardized month-end close cycles.
- Human Resources:Payroll processing and benefits administration hinge on jurisdiction-specific compliance requirements.
Customer Support holds the largest share; momentum sits with IT Services.
Industry Vertical:
Margin profiles diverge by vertical based on regulatory burden and process standardization potential.
- Healthcare:Revenue cycle management and claims processing require HIPAA compliance and clinical coding expertise. US hospital systems delegate end-to-end RCM functions to specialized operators as Medicare reimbursement complexity intensifies.
- BFSI:Banking, financial services, and insurance demand fraud detection, loan processing, and regulatory reporting with strict audit trails. EU AI Act documentation requirements for automated credit decisions are reshaping provider capabilities.
- Retail:Seasonal demand spikes and omnichannel fulfillment coordination characterize outsourcing relationships.
- Telecommunications:Subscriber acquisition and technical troubleshooting follow high-volume, low-margin economics.
Healthcare commands premium pricing; BFSI is climbing the fastest.
Engagement Type:
Geographic delivery configuration directly affects risk exposure and labor arbitrage capture.
- Offshore:India dominates IT and back-office functions through the PLI scheme for IT and BPM services, which accelerates Tier-2 city expansion. Physical server requirements under India's BIS and IT Act frameworks increase facility capital expenditure for cross-border contracts.
- Hybrid:Blended onshore-offshore models balance cost optimization with data residency demands. Fortune 500 manufacturers with multi-country footprints favor this structure to satisfy GDPR cross-border constraints while retaining offshore scale.
- Onshore:Domestic delivery meets strict data localization mandates and sensitive regulatory interactions.
- Nearshore:Proximity sourcing to client headquarters reduces time-zone friction for real-time collaboration.
Offshore retains volume leadership; Hybrid is gaining share fastest.
Client Size:
Contract structuring and sales cycle length correlate closely with organizational scale and procurement sophistication.
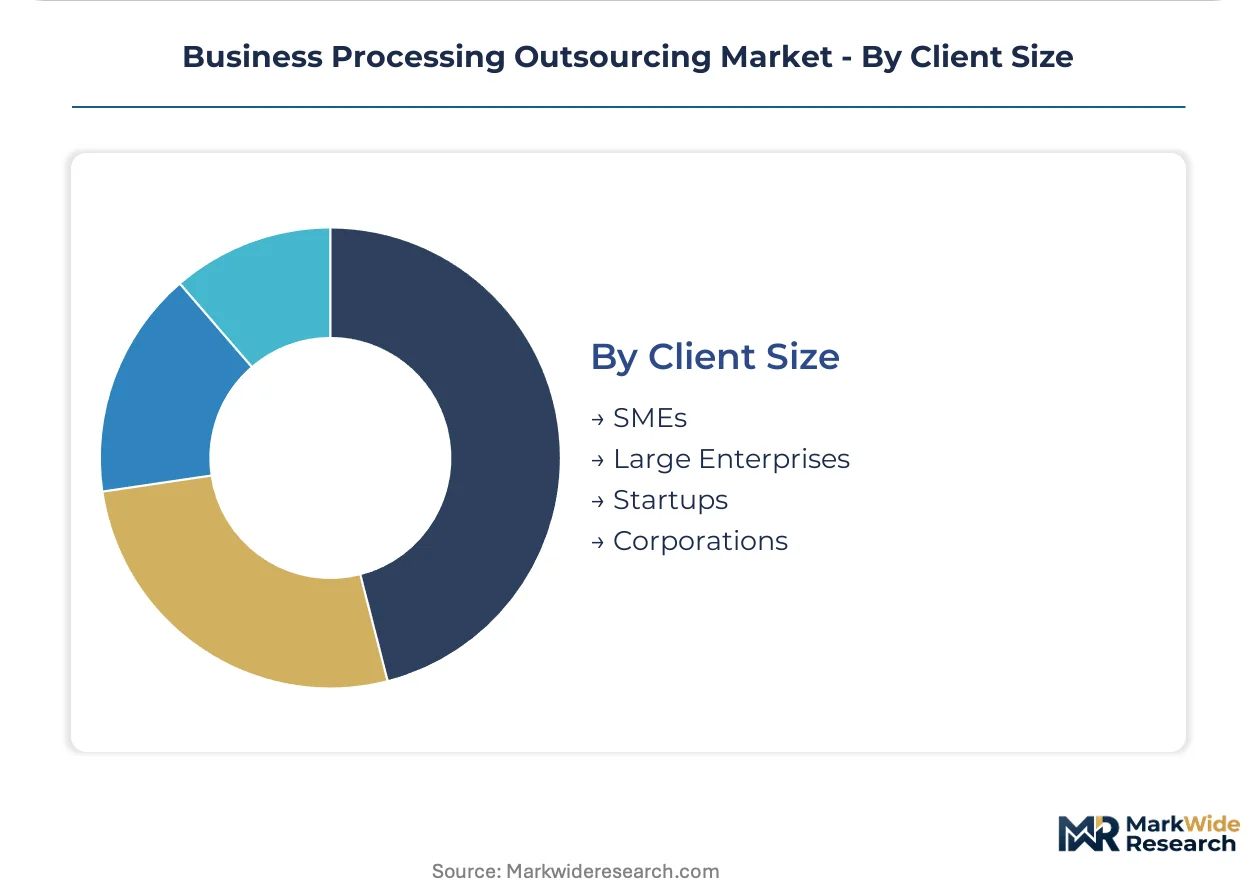
- Large Enterprises:Complex multi-tower deals spanning customer experience, finance, and HR functions. Procurement teams unbundle monolithic contracts into modular engagements, sourcing analytics, payment processing, and administration from separate specialists.
- SMEs:Mid-market buyers prioritize standardized, rapidly deployable platforms with minimal customization requirements.
- Corporations:Established entities with centralized vendor management functions.
- Startups:Early-stage companies seeking variable-cost structures without fixed labor overhead.
Large Enterprises dominate contract value; SMEs show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Philippines exceeds that in India for voice-centric contracts, while Indian IT-BPM providers capture premium rates for technical process automation. This asymmetry reflects divergent labor pool depths and regulatory exposure across delivery geographies.
United States
US hospital systems delegate revenue cycle management to specialized operators as Medicare reimbursement complexity intensifies. HIPAA compliance requirements govern all patient data handling by offshore providers. Dallas and Phoenix host major delivery centers where healthcare BPOs process claims and clinical coding workflows.
India
IT infrastructure management and finance process automation drive contract volumes from North American and European enterprises. The PLI scheme for IT and BPM services accelerates Tier-2 city expansion in Jaipur and Indore. Bengaluru and Hyderabad clusters concentrate application development and cloud migration talent pools.
Philippines
English-language voice support for North American telecom and banking clients dominates export revenue. PEZA regulations sustain special economic zone status with tax incentives for contact center operators. Metro Manila and Cebu City face 35-45% annual agent attrition, forcing continuous recruitment expenditure.
Germany
Automotive and industrial manufacturers outsource finance and accounting functions to reduce fixed labor overhead. The EU AI Act imposes documentation requirements on automated credit decisions processed by BPO partners. Frankfurt and Munich clusters host shared service centers serving DAX-listed corporations.
United Arab Emirates
Healthcare privatization in Saudi Arabia and UAE creates demand for revenue cycle management and claims processing capabilities. MOHAP regulations govern health data handling by third-party administrators. Dubai International Financial Centre attracts BPOs positioning for Middle East market entry.
Business Processing Outsourcing Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in narrow process automation niches. The vendor base organizes around three tiers: global consultancies anchoring transformation deals, offshore-scale operators capturing volume contracts, and vertical specialists commanding premium rates in regulated industries. Strategic archetypes include end-to-end platform providers, domain-specific process engineers, and captive center transition specialists. Competitive moves concentrate on AI capability acquisition and geographic diversification beyond Philippine voice concentration.
Among Ireland-registered professional services firms, Accenture plc exemplifies the consulting-to-operations continuum archetype. Tata Consultancy Services Limited and Cognizant occupy positions within the offshore-scale tier, representing contrasting approaches to healthcare and banking vertical depth versus global network delivery breadth.
| Leading Market Players |
|---|
| Accenture plc |
| Tata Consultancy Services Limited |
| Concentrix Corporation |
| Teleperformance SE |
| Genpact Limited |
| Cognizant |
| Wipro Limited |
| TTEC Holdings, Inc. |
| HCL Technologies Limited |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Philippine voice operations drives wage inflation and forces buyers toward hybrid delivery models that blend offshore scale with onshore premium pricing. India's Tier-2 city expansion under the PLI scheme absorbs overflow demand while compressing IT services margins through capacity addition.
Pricing Analysis
The customization-premium spread separates outcome-based transformation contracts from transactional FTE arrangements. Per-seat pricing dominates voice operations while outcome-based models capture premium rates for AI-augmented healthcare RCM and compliance-driven BFSI engagements. Price differentiation rests on vertical domain depth and GDPR data residency guarantees. Cost compression in tier-1 customer support intensifies as conversational AI displaces scripted interactions. SMEs exhibit highest price sensitivity; large enterprises prioritize domain expertise over rate cards.
Supply Chain Analysis
Third-party delivery center operators in India, the Philippines, and Poland hold concentrated capacity for enterprise outsourcing contracts. Talent pipelines draw from university partnerships in Bengaluru, Metro Manila technical institutes, and Krakow polytechnics. Supply chain risk centers on Philippine typhoon exposure and single-country voice concentration. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern BPO value capture as buyers unbundle monolithic contracts into modular API-connected services. Interoperability between specialized providers replaces single-vendor consolidation as the dominant procurement logic.
For Market Incumbents: Harden defensible positions in healthcare RCM and banking compliance verticals where domain certification creates switching costs. Accentuate captive center transition capabilities to capture enterprise transformation budgets. Invest in EU AI Act documentation infrastructure before automated decision systems face audit mandates.
For New Entrants and Emerging Players: Pursue white-space opportunity in Middle East healthcare privatization where first-mover advantage remains available. Target Saudi RCM and UAE claims processing as the most penetrable geography. Lead with cloud-native microservices architecture that bypasses legacy integration delays.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical specialists with multi-year healthcare and BFSI contracts. Long-term viability favors providers combining AI capability with regulatory compliance depth. Monitor agent attrition rates and reskilling program throughput as inflection indicators for operational sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Capability Acquisition | Generative AI deployment for clinical coding and dispute resolution commands premium pricing from healthcare payers. |
| Geographic Diversification | Tier-2 India expansion under PLI scheme reduces concentration risk while capturing cost arbitrage. |
| Vertical Specialization | HIPAA-certified RCM platforms create sticky relationships with US hospital systems facing Medicare complexity. |
| Compliance Infrastructure Investment | EU AI Act documentation capabilities unlock European financial services contracts requiring algorithmic audit trails. |
| Outcome-Based Contracting | Performance-linked pricing models align provider incentives with client cost reduction targets in mature segments. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with outsourcing procurement officers, delivery center operations directors, healthcare revenue cycle executives, and BFSI compliance leads; and secondary validation against SEC 10-K filings, EU regulatory databases, Indian PLI scheme disclosures, and Philippine PEZA investment reports. Bottom-up contract value aggregation triangulated against top-down market sizing from trade association data.
Forecast inputs span service type, industry vertical, engagement type, and client size segmentation across the projection horizon. CAGRs derive from historical trajectory analysis adjusted for automation displacement thresholds and regulatory compliance cost inflation. Healthcare RCM expansion rates and cloud-native platform adoption curves serve as primary demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in US healthcare reimbursement policy, EU data sovereignty enforcement, or Philippine labor market tightness would shift the trajectory. Forecasts reflect documented assumptions on automation penetration and reskilling program effectiveness. Quarterly review of agent attrition rates, Tier-2 capacity utilization, and GDPR enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
North America Business Process-As-A-Service (Bpaas) Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Healthcare BPO Market
Business Process Outsourcing (BPO)
Global Software Outsourcing Market
Business Process Outsourcing (BPO)
Global Document Outsourcing Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
Global Telecom Outsourcing Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
BFSI BPO Services Market
Business Process Outsourcing (BPO)
Document Outsourcing Services Market
Business Process Outsourcing (BPO)
Contact Center Outsourcing Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market