
 Front Office BPO Services Market | 2026-2036
Front Office BPO Services Market Size, Share, and Industry Trends Forecast 2026-2036
Front Office BPO Services Market Analysis
The EU AI Act is shifting how European enterprises procure customer-facing automation, forcing providers to redesign consent flows and human escalation protocols. Accenture leverages its consulting-to-operations pipeline to embed compliance architecture directly into client workflows. Cognizant anchors its competitive stance through AI governance tooling that preempts regulatory friction. EXL Service specializes in healthcare-specific front office modules, differentiating through vertical depth rather than horizontal scale.
Front office BPO services encompass customer-facing outsourced operations including voice and digital channel management, technical troubleshooting, sales acquisition, and campaign execution, typically governed by service level agreements specifying average handle time, first-call resolution rates, and customer satisfaction thresholds. These functions serve primarily to reduce fixed labor costs while accessing specialized talent pools and 24/7 coverage capabilities. Customer Support represents the most mature revenue pool with stable margins, while AI-driven delivery models capture the fastest expansion as enterprises replace rules-based chatbots with generative systems. Cloud-based infrastructure now dominates new contract structures, displacing on-premise telephony and enabling rapid agent scaling during seasonal demand spikes.
The EU AI Act and GDPR jointly constrain automated decision-making in European customer interactions, requiring human-in-the-loop architectures that elevate operational costs. India's TRAI regulations and the country's data localization debates create parallel compliance layers for offshore delivery models. BFSI end users face additional scrutiny from RBI guidelines on outsourced financial services and SEC disclosure requirements for US-listed entities. Stakeholders must monitor whether nearshore delivery premiums shrink as AI tooling reduces the importance of agent geography.
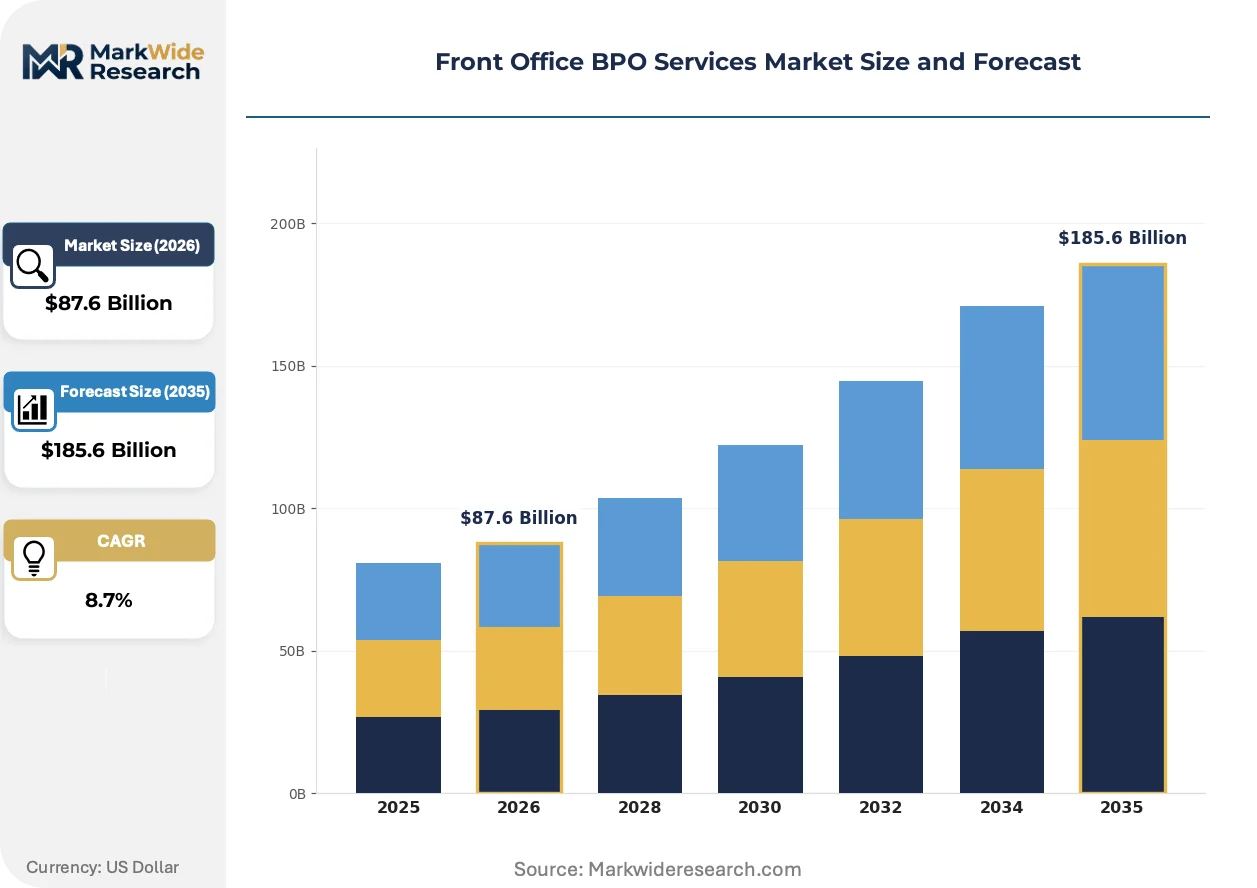
Market Dynamics
Generative AI deployment is compressing agent handle times and forcing providers to restructure pricing from per-seat to per-outcome models, while the EU AI Act mandates human-in-the-loop architectures that elevate European delivery costs above offshore alternatives.
Growth Catalysts
- Healthcare patient engagement outsourcing:US hospital systems are expanding voice and digital channel management to specialized BPO partners as value-based care contracts intensify billing accuracy requirements.
- EU AI Act compliance services:European enterprises require redesigned consent flows and human escalation protocols, creating specialized advisory and implementation revenue streams for providers with regulatory expertise.
- Cloud contact center infrastructure:AWS Connect and Twilio Flex are enabling rapid agent scaling during seasonal spikes, displacing on-premise telephony and reducing capital barriers to entry for mid-market buyers.
Market Restraints
- Data localization mandates:India's TRAI debates and RBI guidelines on outsourced financial services create parallel compliance layers that constrain pure offshore delivery models for BFSI clients.
- Agent wage inflation in India:Tier-1 cities like Bangalore and Hyderabad are experiencing double-digit annual increases in English-speaking talent costs, eroding the cost arbitrage that sustained historical offshore leadership.
- Substitution by native AI agents:Large language models with voice synthesis capabilities are displacing tier-1 support inquiries, threatening volume-based contracts that depend on high call volumes.
Strategic Opportunities
- Nearshore Eastern European delivery:Poland and Romania offer GDPR-native operations with cultural proximity to Western European clients, capturing share as EU AI Act compliance premiums shrink geography advantages.
- Voice biometrics integration:Converging speech recognition and fraud detection technologies are enabling authentication-as-a-service offerings that differentiate providers in financial services verticals.
- Outcome-based pricing penetration:First-call resolution guarantees and net promoter score linkages are displacing traditional per-hour contracts in enterprise renewals, aligning provider incentives with client success metrics.
Industry Challenges
- Agent reskilling for AI collaboration:Frontline staff require training in prompt engineering and exception handling as generative systems assume routine inquiry resolution, creating workforce transition friction.
- Legacy CRM integration complexity:Decades-old on-premise customer databases in insurance and telecom verticals resist API-based connectivity with modern cloud contact platforms, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Front Office BPO Services Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Customer Support, Technical Support, Sales, Marketing End User: Retail, Healthcare, Telecommunications, BFSI Delivery Model: Onshore, Offshore, Nearshore, Hybrid Technology: Cloud-based, AI-driven, VoIP, CRM Software |
| Companies Covered | Alorica, EXL Service, Accenture, Helpware, Firstsource, Cognizant, Atento, Unity Communications, Concentrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Front Office BPO Services Market Emerging Trajectories
Agentic AI systems are reshaping how customer interactions are triaged, executed, and measured, compressing the traditional hierarchy between human agents and automated workflows while forcing providers to redefine value propositions around exception handling rather than volume processing.
Large language models with retrieval-augmented generation capabilities are integrating directly into agent desktops, surfacing knowledge base articles and suggested responses in real-time during live customer conversations. BFSI and healthcare buyers are piloting these copilot configurations most aggressively, seeking to reduce average handle time without sacrificing compliance documentation. This integration is compressing the skill premium previously attached to experienced agents, as novice staff achieve parity outcomes with AI assistance.
The EU AI Act's risk classification framework for automated decision-making is forcing European deployments to maintain human oversight loops for high-stakes customer interactions including credit decisions and claims processing. Providers serving German and French enterprises must now architect explicit escalation triggers and audit trails that satisfy national regulators implementing the Brussels-mandated standards. BFSI contracts in the EU are absorbing 15-25% cost premiums for compliant delivery compared to identical services in non-regulated jurisdictions.
Enterprise procurement of front office services is fragmenting across specialized providers rather than consolidating with single-source mega-vendors, as buyers seek vertical-specific expertise over horizontal scale. Healthcare payers are contracting separately for member engagement, provider relations, and claims advocacy functions, each with distinct compliance requirements and performance metrics. This unbundling is most pronounced in the US market, where anti-consolidation sentiment and regulatory scrutiny of vendor concentration are accelerating multi-sourcing strategies.
Front Office BPO Services Market Segmentation
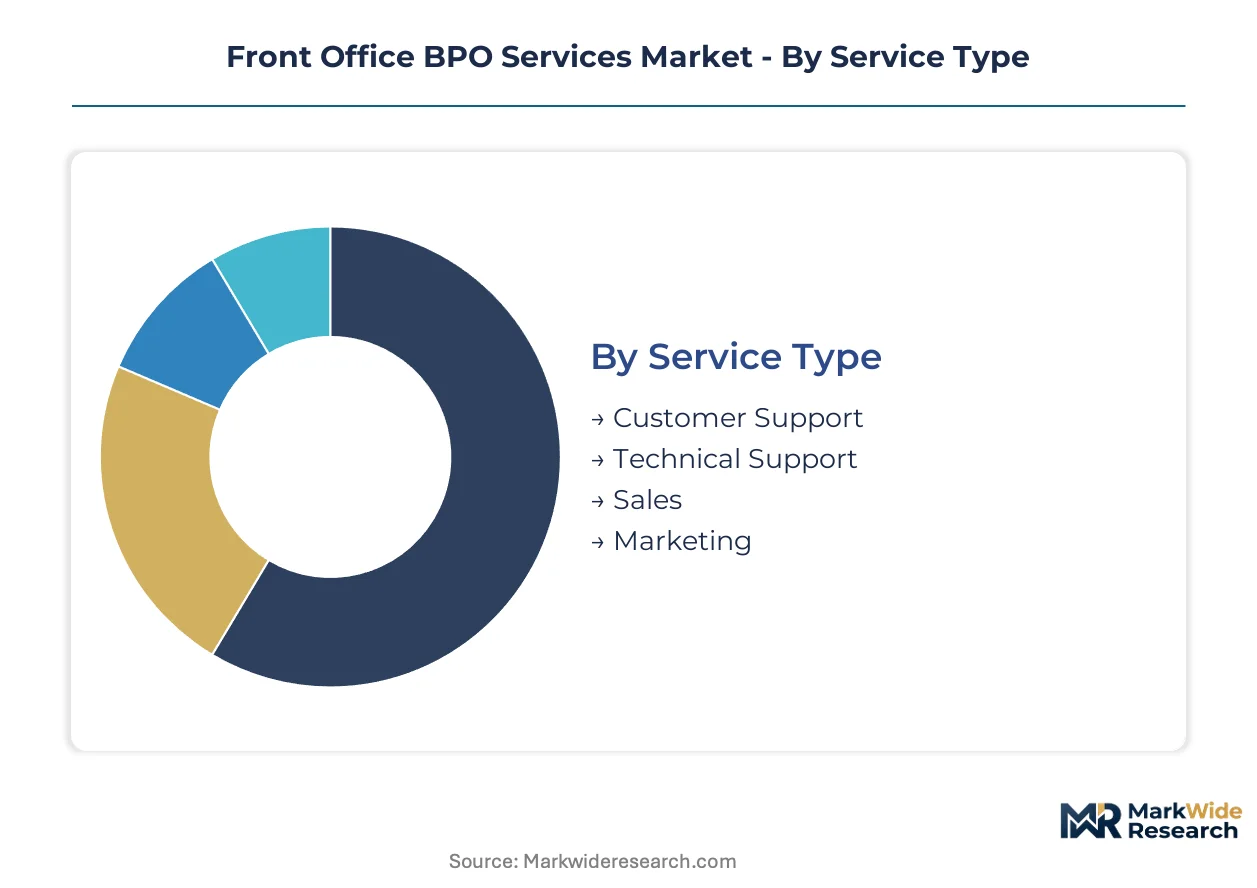
Front office BPO procurement divides sharply between cost-driven commodity segments and outcome-based specialized delivery, with technology architecture and regulatory exposure determining contract structures. Buyers select service configurations based on vertical compliance requirements, seasonal scalability needs, and the balance between automation depth and human oversight.
Service Type:
Supply concentration clusters around voice-centric functions in India and the Philippines, while digital-first segments distribute across Eastern European and Latin American delivery hubs.
- Customer Support:Voice and digital channel management for inquiry resolution, order tracking, and complaint handling. US hospital systems and retail chains concentrate demand here as value-based care contracts and e-commerce volume spikes force 24/7 coverage requirements. This segment absorbs the bulk of installed capacity; Technical Support is expanding most quickly.
- Technical Support:Troubleshooting for hardware, software, and connected device ecosystems, typically requiring certified agent pools. SaaS vendors and telecommunications providers drive demand in Bangalore and Hyderabad, where technical credentialing programs feed specialized talent pipelines.
- Sales:Outbound acquisition, upsell campaigns, and lead qualification across voice and digital channels. BFSI clients in credit cards and insurance dominate procurement, with seasonal spikes around fiscal year-ends and product launch windows.
- Marketing:Campaign execution, survey administration, and customer data enrichment services. Retail and CPG brands concentrate spending here, particularly for multilingual European market coverage requiring GDPR-compliant consent architectures.
Customer Support absorbs the bulk of installed capacity; Technical Support is expanding most quickly.
End User:
Cost tiers separate regulated verticals absorbing compliance premiums from retail segments competing purely on unit economics.
- Healthcare:Patient engagement, billing accuracy, and prior authorization management for US hospital systems and payers. HIPAA documentation requirements and value-based care contracts elevate pricing above commodity voice services.
- BFSI:Credit decision support, claims processing, and fraud prevention with heavy regulatory overlay. RBI guidelines in India and SEC disclosure requirements for US-listed entities constrain offshore delivery models for this vertical.
- Retail:Seasonal scaling for peak demand windows, order management, and returns processing. E-commerce platforms drive procurement with cloud contact center infrastructure enabling rapid agent deployment.
- Telecommunications:Technical troubleshooting, service provisioning, and churn reduction programs. Legacy CRM integration complexity in this vertical extends implementation timelines compared to cloud-native competitors.
BFSI commands the steepest pricing tier; Healthcare is climbing the fastest as value-based care contracts proliferate.
Delivery Model:
Volume concentration has historically favored offshore configurations, though EU AI Act compliance premiums are redistributing share toward nearshore alternatives.
- Offshore:India-centric delivery leveraging English-speaking talent pools and cost arbitrage. TRAI regulations and data localization debates create compliance layers constraining pure offshore delivery for BFSI clients.
- Nearshore:Poland and Romania for Western European clients, Mexico and Colombia for US Spanish-language requirements. GDPR-native operations capture share as EU AI Act mandates elevate European delivery premiums.
- Onshore:Domestic delivery for high-stakes interactions requiring cultural fluency or regulatory proximity. US healthcare and financial services procurement favors this model for patient-facing and credit decision workflows.
- Hybrid:Blended configurations routing routine inquiries offshore while retaining onshore capacity for escalation and compliance-sensitive transactions. Enterprise renewals increasingly specify this architecture.
Offshore retains the largest contract base; Nearshore is gaining share fastest as regulatory friction reshapes location decisions.
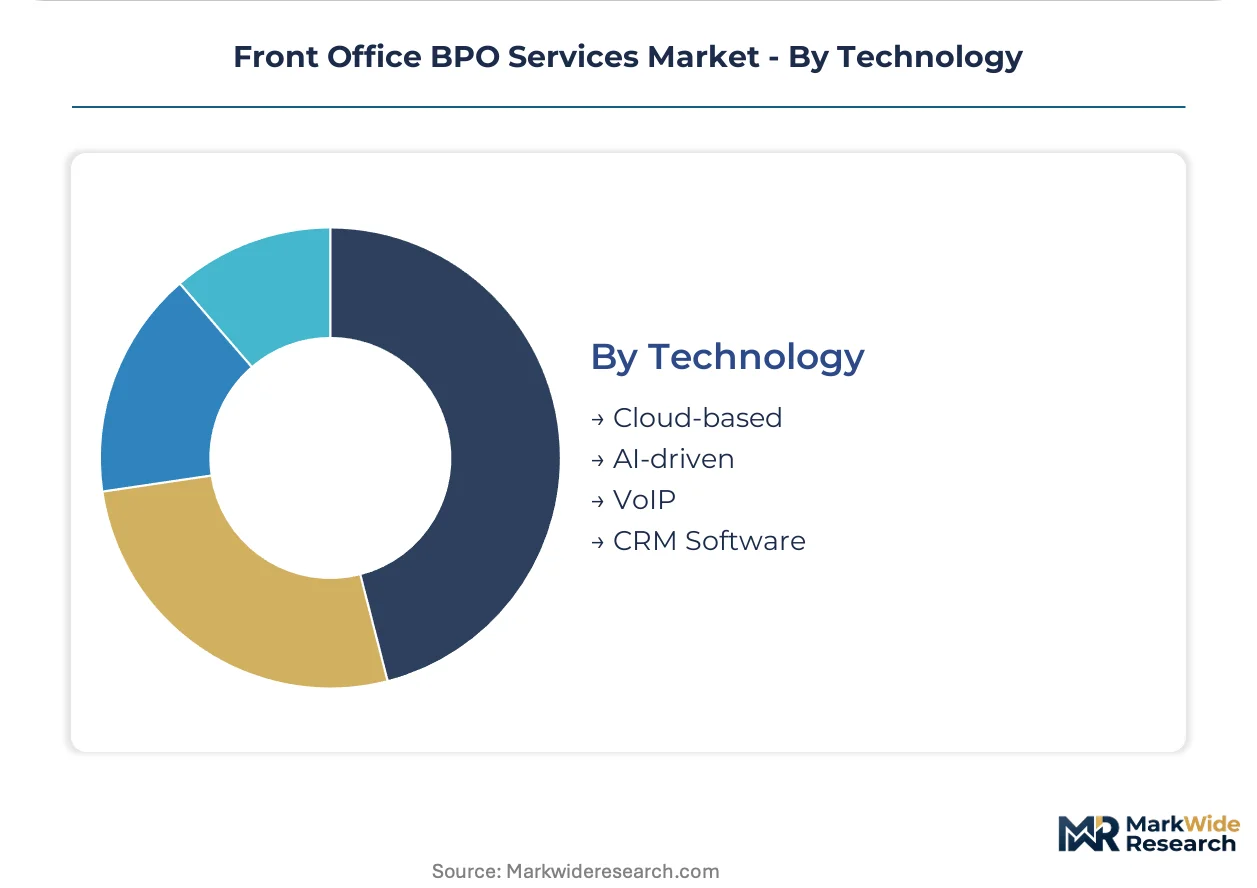
Technology:
Margin structures diverge between legacy infrastructure requiring integration investment and cloud-native platforms enabling rapid deployment.
- AI-driven:Generative systems and retrieval-augmented generation copilots compressing agent handle times. BFSI and healthcare buyers pilot these configurations most aggressively for compliance documentation and real-time response suggestions.
- Cloud-based:AWS Connect, Twilio Flex, and comparable platforms displacing on-premise telephony. Mid-market buyers favor this architecture for capital efficiency and seasonal scaling capabilities.
- CRM Software:Salesforce, Microsoft Dynamics, and vertical-specific customer data platforms. Insurance and telecom verticals face legacy database integration complexity extending implementation timelines.
- VoIP:Voice-over-IP infrastructure for cost-efficient telephony delivery. This segment faces displacement as cloud contact platforms subsume voice functionality into unified offerings.
Cloud-based platforms anchor new contract structures; AI-driven delivery is expanding most rapidly as generative systems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India generates the bulk of front office BPO delivery capacity while the United States consumes the largest share of outsourced patient engagement and financial services operations. European demand is shifting toward GDPR-native nearshore alternatives as compliance premiums reshape location economics.
United States
US hospital systems and health insurers drive demand for patient engagement outsourcing as value-based care contracts intensify billing accuracy requirements. HIPAA documentation mandates elevate pricing for domestic delivery compared to offshore alternatives. Dallas and Phoenix anchor major healthcare BPO clusters where specialized vendors manage prior authorization and claims advocacy workflows.
India
Bangalore and Hyderabad supply certified technical support talent pools for SaaS vendors and telecommunications providers seeking 24/7 coverage. RBI guidelines on outsourced financial services and SEBI disclosure requirements constrain pure offshore delivery for BFSI clients. Tier-1 cities are experiencing double-digit annual wage inflation for English-speaking agents, eroding historical cost arbitrage.
Germany
Automotive and industrial enterprises procure customer-facing automation requiring human-in-the-loop architectures under EU AI Act risk classifications. KBA and national regulators implementing Brussels-mandated standards demand explicit escalation triggers and audit trails. Berlin and Munich host delivery centers capturing compliance premiums of 15-25% above non-regulated jurisdictions.
Poland
GDPR-native operations in Krakow and Warsaw capture share from Western European clients seeking cultural proximity and regulatory alignment. The country's data protection framework satisfies EU AI Act requirements without the cost premiums of German delivery. BFSI contracts route high-stakes credit decision support through Polish centers to minimize compliance friction.
Philippines
Voice-centric customer support functions concentrate in Manila and Cebu for US retail and telecommunications clients seeking accent-neutral English delivery. The country's BPO sector competes with India on cost while offering stronger cultural alignment with North American consumers. Cloud contact center adoption is accelerating as AWS Connect and Twilio Flex displace legacy on-premise infrastructure.
Front Office BPO Services Market Vendor Landscape
The competitive structure tilts toward consulting-to-operations integrators with embedded regulatory expertise. Tier-one technology conglomerates and vertical specialists split contract flows, with healthcare and BFSI procurement fragmenting across specialized providers rather than consolidating with single-source vendors. Strategic moves concentrate on AI governance tooling deployment and outcome-based pricing restructures that align provider incentives with client success metrics.
Within the consulting-anchored tier, Accenture and Cognizant occupy positions that bridge advisory capabilities with scaled delivery infrastructure. EXL Service exemplifies vertical specialization, anchoring competitive stance through healthcare-specific front office modules rather than horizontal scale. These three entities represent the dominant archetypes: compliance-embedded integrators, AI governance platforms, and vertical depth specialists.
| Leading Market Players |
|---|
| Alorica |
| EXL Service |
| Accenture |
| Helpware |
| Firstsource |
| Cognizant |
| Atento |
| Unity Communications |
| Concentrix |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's human-in-the-loop mandate gates qualified supply for European delivery while elevating premium-tier pricing access for compliant providers. Buyers absorbing 15-25% cost premiums for GDPR-native operations face constrained vendor pools as offshore alternatives fail regulatory qualification.
Pricing Analysis
Value-based pricing anchored to first-call resolution guarantees and net promoter score linkages displaces traditional per-hour contracts in enterprise renewals. Three-tier pricing structure across premium compliance-native, standard hybrid, and economy offshore levels separates delivery models by regulatory exposure and automation depth. Pricing pressure stems from generative AI compression of agent handle times forcing outcome-based restructuring. Healthcare payers exhibit lowest price sensitivity due to HIPAA documentation mandates, while retail segments compete purely on unit economics.
Supply Chain Analysis
Dual-sourcing requirements from BFSI and healthcare buyers mandate multi-supplier qualification across India, Poland, and Philippines delivery hubs. Talent pipelines draw from certified agent pools in Bangalore technical support corridors, Krakow GDPR-native operations, and Manila voice-centric clusters. Single-source vulnerability concentrates in Tier-1 Indian cities experiencing double-digit wage inflation. Distribution runs through cloud contact center platforms displacing on-premise telephony infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where the EU AI Act creates a barrier-to-entry moat for providers with embedded regulatory architecture. Compliant players capture pricing premiums while non-qualified vendors face contract exclusion from European enterprise procurement.
For Market Incumbents: Hedge against native AI agent substitution by deepening vertical specialization in healthcare prior authorization and BFSI fraud prevention workflows. Accenture and Cognizant anchor positions through consulting-to-operations pipelines that embed compliance architecture directly into client systems. Capacity addition in Polish and Romanian delivery centers captures share as EU AI Act premiums reshape location economics. For New Entrants and Emerging Players: Voice biometrics integration with converging speech recognition and fraud detection technologies offers a technology-first wedge into financial services authentication-as-a-service segments. White-space targets concentrate in mid-market healthcare payers unbundling member engagement from claims advocacy functions. Nearshore Eastern European delivery for German automotive and industrial clients provides the most penetrable geography given cultural proximity and regulatory alignment. For Investors and Strategic Acquirers: Outcome-based pricing penetration exceeding 40% of enterprise renewals is the leading indicator that margin structures have stabilized for AI-augmented delivery models. Acquisition target archetypes cluster around vertical specialists with healthcare-specific front office modules and embedded HIPAA compliance documentation capabilities. Watch for deviation in EU AI Act enforcement intensity across national regulators as the signal for compliance premium compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Tooling Deployment | Cognizant's preemptive regulatory friction reduction embeds compliance into client workflows. |
| Outcome-Based Pricing Restructure | First-call resolution guarantees align provider incentives with healthcare payer success metrics. |
| Nearshore European Delivery Expansion | Polish GDPR-native operations capture 15-25% compliance premiums from German automotive clients. |
| Voice Biometrics Integration | Authentication-as-a-service offerings differentiate providers in RBI-regulated BFSI verticals. |
| Vertical Healthcare Module Development | EXL Service's patient engagement specialization commands pricing above horizontal scale competitors. |
Methodological Framework
Multi-period observation of contract renewal terms, pricing model transitions, and regulatory compliance premiums anchored the trend analysis, supplemented by interviews with BPO operations directors, healthcare payer procurement managers, EU regulatory affairs leads, and cloud contact platform engineers. Secondary validation drew from SEC filings of publicly traded providers, EU AI Act implementation guidance from national regulators, TRAI consultation papers, and CMS Medicare contractor performance data. Bottom-up aggregation of segment-level contract values triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting across service type, end user vertical, delivery model, and technology architecture informed the analytical framework. Modeled dimensions included voice versus digital channel mix, regulated versus non-regulated industry exposure, offshore-nearshore-onshore location tier, and AI-augmented versus legacy delivery method. CAGRs were derived from regression analysis of historical contract value trajectories and projected automation penetration curves. Industry-specific forecast inputs incorporated EU AI Act implementation timelines and Indian wage inflation trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruption to India-Philippines delivery corridors, breakthrough native AI agent capabilities eliminating tier-1 support entirely, and abrupt EU AI Act enforcement escalation. Forecasts reflect documented assumptions regarding automation adoption curves and regulatory stability. Deviation in RBI data localization mandates or SEC disclosure requirement expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
North America Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Asia-Pacific Business Process As a Service (Bpaas) Market
Business Process Outsourcing (BPO)
Middle East and Africa Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Data Entry Service Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Automotive Business Process Management Market
Business Process Outsourcing (BPO)
Contract Management Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
United States IT Outsourcing Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Cloud Bpo Market