
 Payroll Outsourcing Services Market | 2026-2036
Payroll Outsourcing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Payroll Outsourcing Services Market Analytics
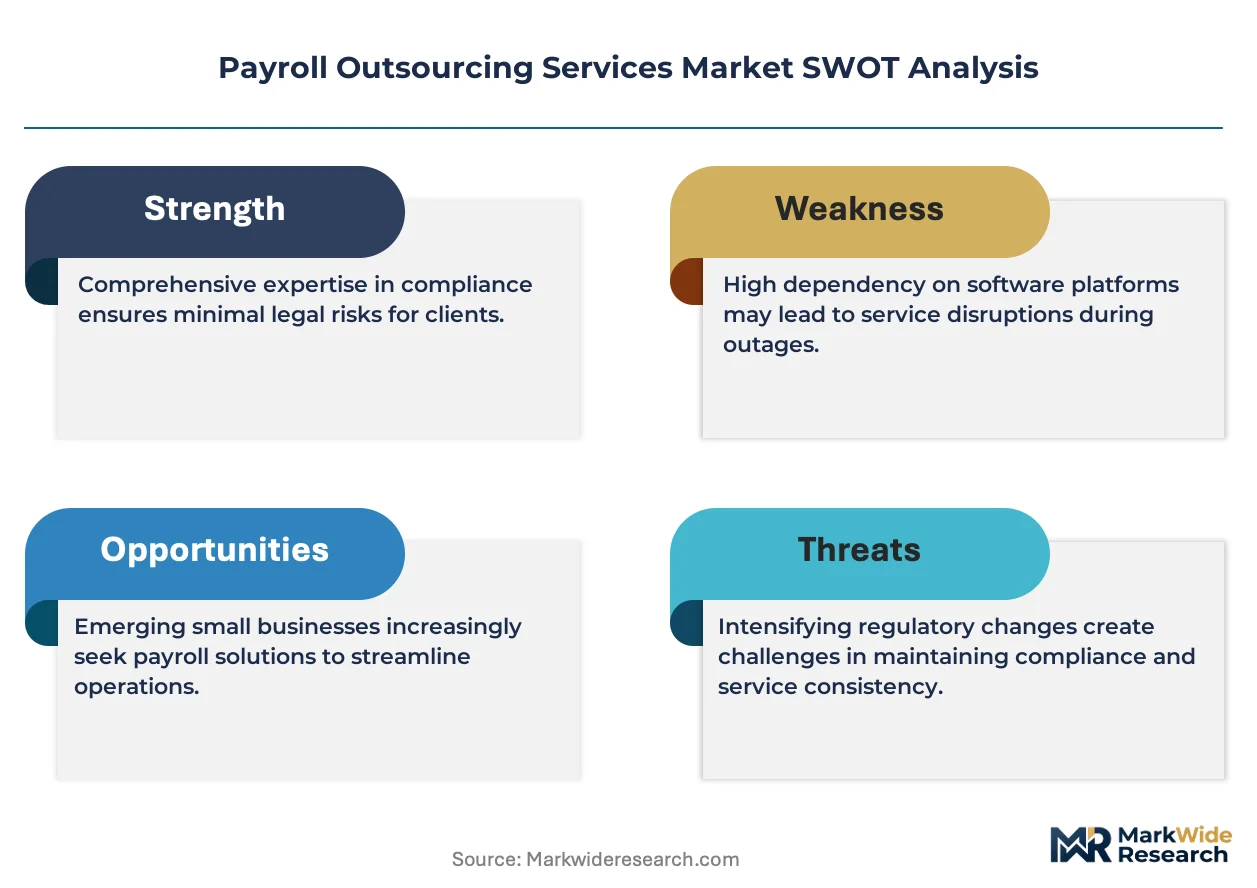
ISO 27001 certification is rotating as the decisive gating standard for payroll outsourcing vendors handling sensitive employee financial data. ADP leverages its decades of infrastructure investment to sustain dominance across enterprise-grade tax filing and benefits administration. Paychex anchors the small-business segment through specialized service bundles that reduce client administrative burden. Rippling competes by integrating payroll with broader workforce management software, extending platform stickiness beyond discrete pay cycles.
Payroll outsourcing services encompass the third-party management of wage calculation, tax withholding, direct deposit execution, and regulatory filing, typically delivered through cloud-native platforms with SOC 2 Type II audit requirements and encryption protocols for data in transit and at rest. Full-service arrangements capture the largest margin pools by bundling compliance management with ongoing regulatory monitoring, while cloud-based deployment represents the fastest-expanding technology dimension as clients abandon on-premises legacy systems. Partial-service and customized solutions occupy growing niches where organizations retain certain functions in-house while outsourcing jurisdictionally complex elements.
The US Internal Revenue Service and state-level labor departments collectively shape demand through escalating penalty structures for late or inaccurate payroll tax deposits, while the EU's GDPR framework imposes data-localization constraints on vendors serving European workforces. The US Department of Labor's evolving overtime exemption rules further compel employers to seek external expertise in classification and compensation compliance. Stakeholders must weigh vendor specialization against platform breadth as regulatory fragmentation intensifies across federal, state, and municipal wage jurisdictions.
Market Dynamics
The migration from batch-processed to real-time payroll systems is compressing vendor delivery timelines and forcing infrastructure overhauls across the competitive landscape. This technological pivot demands continuous compliance monitoring rather than periodic filing cycles.
Growth Catalysts
- GDPR data-localization mandates:European employers face escalating penalties for cross-border data transfers, compelling outsourced solutions with EU-based processing centers.
- Multi-jurisdiction tax complexity:Remote work dispersion across state and municipal boundaries generates demand for automated compliance engines that calculate withholdings in real time.
- AI-driven predictive analytics:Workforce planning modules that forecast labor costs and overtime exposure are attracting finance executives seeking budget precision.
Market Restraints
- Cloud infrastructure concentration:Dominant hyperscaler dependence in North American data centers creates systemic vulnerability to regional outages or pricing power.
- ISO 27001 certification bottlenecks:Audit backlogs and assessor scarcity extend vendor onboarding timelines by six to eighteen months.
- In-house ERP substitution:Workday and SAP continue strengthening native payroll modules, retaining enterprise clients who prioritize single-vendor integration.
Strategic Opportunities
- Gig-economy platform integration:On-demand worker classification and instant payment rails represent unaddressed white space in contingent workforce management.
- India's digital public infrastructure:Unified Payments Interface penetration and Aadhaar-linked verification enable low-cost payroll modernization for mid-market employers.
- Embedded finance convergence:Partnerships between payroll providers and neobanks allow earned wage access products that generate recurring interchange revenue.
Industry Challenges
- SOC 2 Type II audit cycles:Continuous monitoring requirements strain engineering resources and delay product roadmap execution.
- Legacy mainframe integration:COBOL-based government reporting systems in certain jurisdictions force expensive middleware development for compliance connectivity.
- Specialized compliance talent scarcity:Professionals holding dual expertise in software engineering and multi-state tax law command premium compensation that compresses service margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payroll Outsourcing Services Market |
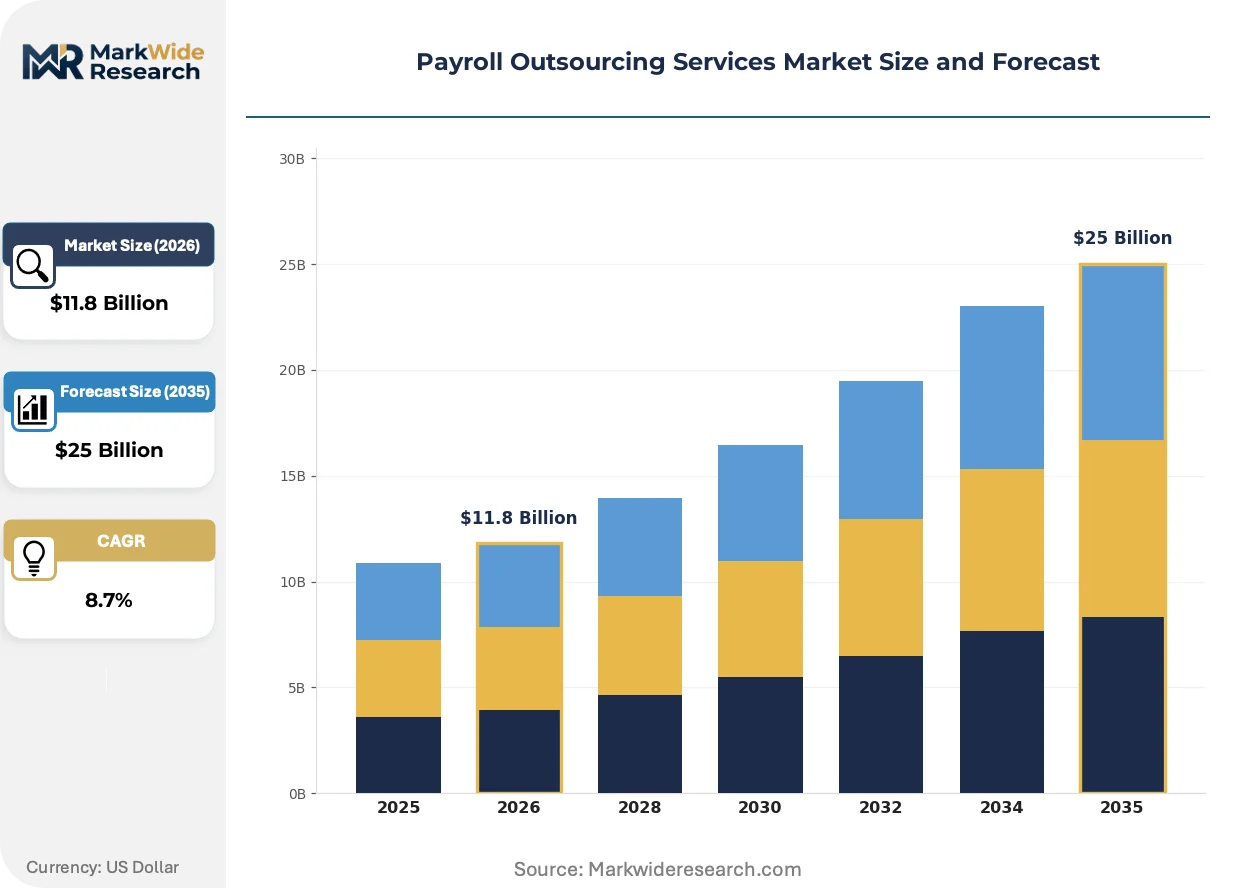
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Service, Partial Service, Customized Solutions, Compliance Management Client Type: Small Businesses, Large Enterprises, Startups, Nonprofits Technology: Cloud-Based, On-Premises, Hybrid Systems, Mobile Applications Industry Vertical: Healthcare, Manufacturing, Retail, Technology |
| Companies Covered | Insperity, Gusto, ADP, Justworks, Paycom, Paychex, Rippling, Paylocity, TriNet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payroll Outsourcing Services Market Evolving Landscape
Artificial intelligence and open banking rails are converging to transform payroll from a back-office cost center into a strategic workforce intelligence platform. Vendors race to embed financial wellness tools that deepen platform stickiness.
Generative AI for natural language query interfaces is decomposing traditional dashboard-centric analytics. Mid-market HR directors now interrogate payroll data through conversational prompts rather than pre-built reports. This capability compresses the time from data access to workforce decision, shifting competitive advantage toward vendors with superior language model integration.
The EU's CSRD sustainability reporting framework now mandates granular workforce disclosures including gender pay gaps and contractor ratios. Employers with operations in Germany, France, and the Netherlands face expanded audit trails that outsourced providers must architect into reporting workflows. Service contracts increasingly specify CSRD-ready data structures as table-stakes requirements.
Consolidated platform purchasing is displacing point-solution procurement among employers with two hundred to two thousand employees. Buyers now evaluate payroll modules within broader workforce management suites rather than selecting standalone vendors. This pattern concentrates contract value with integrated platform providers and compresses margins for specialized payroll-only offerings.
Payroll Outsourcing Services Market Segmentation
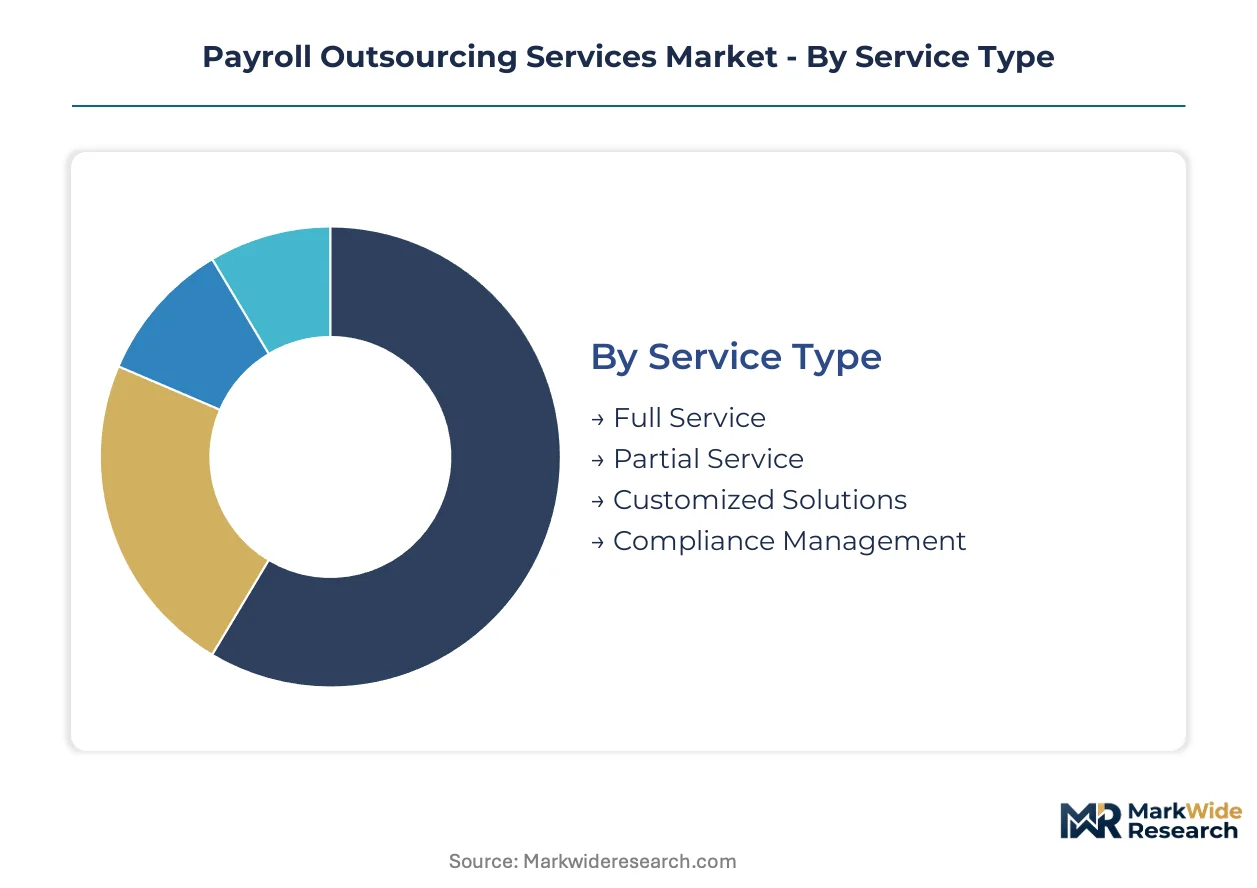
Segmentation in payroll outsourcing reveals how regulatory complexity and technology maturity shape vendor selection. Buyers match service depth to internal capabilities while weighing compliance exposure against cost efficiency.
Service Type:
Regulatory differentiation separates vendors capable of handling multi-jurisdiction tax filing from those limited to single-market compliance. Full-service providers absorb penalty risk through indemnification clauses, while partial offerings shift liability to clients.
- Full Service:Bundles wage calculation, tax withholding, direct deposit execution, and regulatory filing with ongoing compliance monitoring. Demand concentrates among mid-market employers in the United States where state-level wage law fragmentation creates penalty exposure. The Internal Revenue Service's escalating penalty structures for late deposits drive adoption.
- Partial Service:Clients retain core payroll functions while outsourcing jurisdictionally complex elements such as multi-state withholding or international contractor payments. Technology firms with distributed remote workforces represent the fastest-expanding adopter group.
- Customized Solutions:Hybrid arrangements tailored to organizations with unique compensation structures or union bargaining requirements.
- Compliance Management:Standalone regulatory monitoring and filing services for employers maintaining in-house payroll systems.
Established volume favors Full Service; emerging adoption favors Partial Service.
Client Type:
Cost tier differentiation drives procurement patterns, with per-employee pricing models creating natural segmentation thresholds.
- Small Businesses:Typically under 50 employees, these buyers prioritize administrative burden reduction over advanced analytics. Bundled service packages that include benefits administration and workers' compensation integration capture disproportionate share.
- Large Enterprises:Complex multi-entity structures with international operations demand dedicated account management and custom integration with ERP systems. Manufacturing conglomerates with unionized workforces generate specialized compliance requirements.
- Startups:Equity compensation handling and rapid headcount scaling create unique service needs distinct from mature small businesses.
- Nonprofits:Grant-funded payroll allocation and restricted fund accounting requirements necessitate specialized reporting capabilities.
Contract value concentrates with Large Enterprises; platform stickiness builds fastest with Small Businesses.
Technology:
Deployment architecture determines data residency compliance and integration flexibility.
- Cloud-Based:SOC 2 Type II audited platforms with encryption protocols for data in transit and at rest. GDPR data-localization mandates in Europe compel EU-based processing centers, accelerating infrastructure investment.
- On-Premises:Legacy installations persisting in defense contracting and classified government work where data sovereignty requirements prohibit third-party cloud access.
- Hybrid Systems:Sensitive payroll data remains on-premises while reporting and analytics leverage cloud connectivity.
- Mobile Applications:Earned wage access and instant payment rails for gig-economy platforms and contingent workforce management.
Cloud-Based deployment claims the steepest expansion trajectory; On-Premises retains niche defensive value.
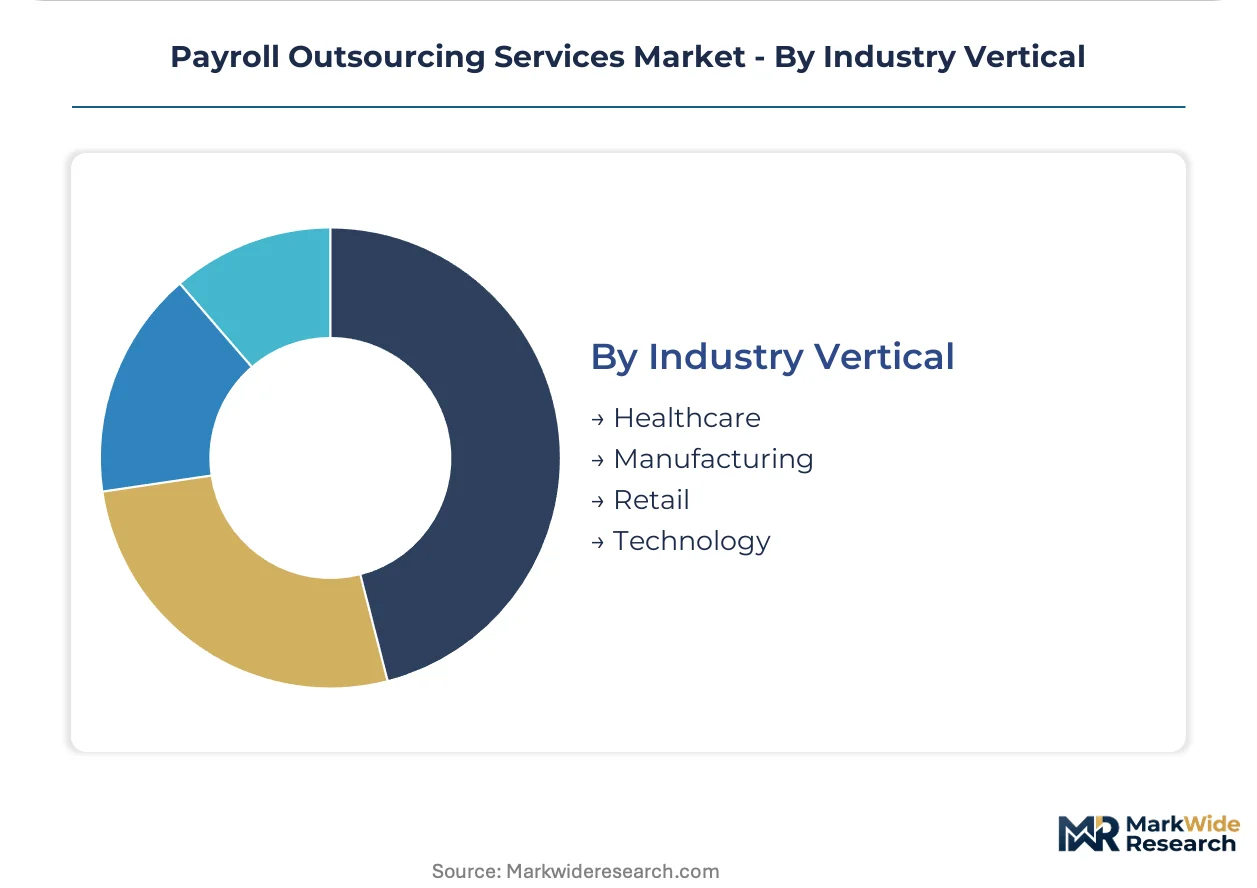
Industry Vertical:
Application-specific compliance requirements shape vertical specialization among vendors.
- Healthcare:Shift differential calculations, union contract administration, and HIPAA-aligned data handling for hospital systems. The Department of Labor's evolving overtime exemption rules create persistent classification challenges.
- Manufacturing:Piece-rate compensation, seasonal workforce fluctuations, and multi-site union negotiations dominate service complexity.
- Retail:High turnover rates and variable-hour scheduling demand automated onboarding and offboarding workflows.
- Technology:Equity compensation administration, remote work tax nexus issues, and international contractor payments.
Service margins compress in Retail; compliance premiums concentrate in Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' Automated Clearing House network processes trillions in annual payroll volume, anchoring North American outsourcing demand. Fiber-optic subsea cables linking London to Frankfurt and Amsterdam enable real-time EU payroll data synchronization. India's Unified Payments Interface infrastructure supports instant salary disbursement across its domestic market.
United States
State-level wage law fragmentation and IRS penalty escalation drive employer outsourcing intensity. The Department of Labor's evolving overtime exemption rules compel external classification expertise. Silicon Valley technology firms and New York financial services clusters generate concentrated demand for multi-jurisdiction compliance solutions.
Germany
CSRD sustainability reporting mandates now require granular workforce disclosures from employers operating in Germany. The country's national labor regulator enforces strict co-determination rules that complicate payroll administration for multinational employers. The Rhine-Ruhr industrial corridor and Munich technology cluster sustain robust demand for compliant outsourcing services.
United Kingdom
Post-Brexit regulatory divergence from EU labor standards creates dual compliance burdens for UK-based employers. HMRC's real-time information reporting requirements enforce strict submission timelines. London's financial services concentration and Manchester's expanding tech sector anchor domestic outsourcing demand.
India
Aadhaar-linked verification and UPI penetration enable low-cost payroll modernization for mid-market employers. The Reserve Bank of India's payment system oversight shapes vendor infrastructure requirements. Bangalore's technology corridor and Mumbai's financial district concentrate demand for cloud-native payroll platforms.
Netherlands
GDPR data-localization constraints compel EU-based processing center investment from payroll vendors serving Dutch employers. The country's central bank supervises payment system stability affecting salary disbursement rails. The Randstad metropolitan cluster houses headquarters for several European payroll service providers.
Payroll Outsourcing Services Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth and compliance specialization. The market exhibits tiered consolidation, with dominant platforms capturing enterprise contracts while niche operators serve vertical-specific requirements. Three archetypes prevail: infrastructure-heavy incumbents with decades of tax filing investment, cloud-native challengers bundling payroll with workforce management software, and compliance-focused specialists targeting multi-jurisdiction complexity. Competitive dynamics center on platform stickiness extension and real-time payment infrastructure deployment.
Within the infrastructure-incumbent tier, ADP and Paychex occupy positions representing divergent scale strategies. ADP exemplifies enterprise-grade depth across tax filing and benefits administration, while Paychex anchors the small-business segment through service bundle reduction of client administrative burden. Rippling sits within the cloud-native challenger archetype, competing through payroll integration with broader workforce management software to extend platform stickiness beyond discrete pay cycles.
| Leading Market Players |
|---|
| Insperity |
| Gusto |
| ADP |
| Justworks |
| Paycom |
| Paychex |
| Rippling |
| Paylocity |
| TriNet |
| Others |
Value Network & Pricing Analysis
Ninety-day ISO 27001 audit backlogs compress vendor onboarding timelines and concentrate pricing power among pre-certified incumbents, while per-employee SaaS tiers stratify procurement options across buyer segments. This lead-time bottleneck rewards established providers with SOC 2 Type II credentials and forces challengers to absorb certification costs or accept margin compression.
Pricing Analysis
Per-employee-per-month volume tiers dominate, with enterprise buyers above five hundred seats capturing forty to sixty percent discounts against small-business list rates. Price differentiation rests on compliance certification depth and multi-jurisdiction tax engine coverage, with GDPR-ready EU data residency commanding fifteen to twenty-five percent premiums over standard North American deployment. Cost compression in the mid-market tier intensifies as Workday and SAP strengthen native payroll modules, eroding standalone vendor pricing leverage. Small businesses under fifty employees exhibit highest price sensitivity and lowest switching costs, while large enterprises with unionized workforces and international operations demonstrate inelastic demand for indemnified full-service bundles.
Supply Chain Analysis
Just-in-time cloud infrastructure provisioning dominates vendor operations, with hyperscaler capacity reservations replacing owned data center investment across North American and European deployments. Engineering talent concentrates in India, Poland, and the United States, with Bangalore and Krakow emerging as primary development hubs for compliance automation and AI-driven analytics modules. Raw material dependencies include NVIDIA GPU allocations for machine learning workloads, encrypted fiber bandwidth for real-time payment rails, and specialized assessor hours for SOC 2 Type II audit maintenance. Single-source vulnerability to AWS, Azure, or Google Cloud regional outages represents the dominant structural risk. Distribution runs through direct enterprise sales teams, channel partnerships with HR consultancies, and embedded marketplace listings within workforce management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payroll outsourcing functions as a defensive-moat market where multi-decade tax filing infrastructure and embedded client workflow integration create switching costs that lock in recurring revenue streams.
For Market Incumbents: Compound platform stickiness through deeper integration with benefits administration and time-tracking modules, extending beyond discrete pay cycles into continuous workforce management. Prioritize real-time payment infrastructure deployment to capture interchange revenue from earned wage access products. Defend against cloud-native challengers by accelerating AI-driven predictive analytics roadmaps that finance executives prioritize for budget precision. Invest in EU-based processing centers ahead of GDPR enforcement escalation to maintain data-localization compliance premiums. For New Entrants and Emerging Players: Differentiate on gig-economy platform integration, where on-demand worker classification and instant payment rails remain unaddressed white space. Target mid-market technology firms with distributed remote workforces as the most penetrable segment, where multi-state tax nexus complexity outstrips in-house compliance capabilities. Pursue a vertical-specialist go-to-market anchored in healthcare shift differential calculations or manufacturing piece-rate compensation, where compliance expertise gaps create service margin expansion. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because payroll tax compliance is non-discretionary and penalty exposure compels sustained outsourcing relationships. Acquisition targets should display ISO 27001 certification, SOC 2 Type II audit completion, and concentrated client bases in penalty-intensive jurisdictions like California or New York. The signal to watch is IRS penalty structure escalation, which accelerates employer outsourcing intensity and expands addressable market for indemnified full-service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Payment Infrastructure Deployment | Captures interchange revenue from earned wage access products integrated with neobank partnerships. |
| AI-Driven Predictive Analytics Integration | Attracts CFO investment through workforce cost forecasting and overtime exposure modeling capabilities. |
| EU Data Center Expansion | Satisfies GDPR localization mandates and defends premium pricing against non-compliant competitors. |
| Gig-Economy Platform Partnership | Addresses contingent workforce classification gaps and instant payment demands in growing labor segments. |
| Vertical Compliance Specialization | Captures healthcare and manufacturing premiums through shift differential and union contract expertise. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, IRS penalty enforcement data, and GDPR regulatory guidance to establish market sizing and growth trajectory. Primary interviews engaged payroll operations directors, HR technology procurement officers, compliance automation engineers, and channel partnership managers across mid-market and enterprise employers. Secondary validation drew from SOC 2 Type II audit disclosure databases, state labor department enforcement statistics, and hyperscaler infrastructure investment reports. Bottom-up triangulation aggregated vendor-reported seat counts and pricing tiers; top-down validation cross-referenced employer outsourcing penetration rates against total addressable workforce populations.
Segmentation dimensions modeled include service type depth, client size tier, deployment architecture, and industry vertical compliance complexity across the projection horizon. The analytical framework applied regression-based extrapolation of historical outsourcing penetration against regulatory penalty escalation trends and real-time payment infrastructure adoption curves. CAGR derivation incorporated technology substitution effects from in-house ERP module strengthening and cloud-native platform displacement dynamics. Forecast inputs included remote work tax nexus proliferation rates and AI-driven analytics module attach rates.
The analysis sits within stated boundaries; outcomes outside sustained IRS penalty escalation, stable hyperscaler pricing, and continued GDPR enforcement would require recalibration. Forecasts reflect assumptions regarding mid-market employer technology adoption willingness and compliance automation engineering talent availability. Revision becomes warranted when in-house ERP substitution rates or generative AI query interface commoditization cross thresholds that erode vendor differentiation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Technical Support Outsourcing Market
Business Process Outsourcing (BPO)
Healthcare Supply Chain BPO Market
Business Process Outsourcing (BPO)
Indonesia Business Process Outsourcing Services Market
Business Process Outsourcing (BPO)
Public Cloud Business Process Services Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Service Procurement Market
Business Process Outsourcing (BPO)
Global IT Outsourcing Services Market
Business Process Outsourcing (BPO)
Contract Management Market
Business Process Outsourcing (BPO)
UAE Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
IT Outsourcing Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
Legal Process Outsourcing (LPO) Market
Business Process Outsourcing (BPO)
Back Office Outsourcing Market
Business Process Outsourcing (BPO)
North America Business Process-As-A-Service (Bpaas) Market