
 Healthcare BPO Market | 2026-2036
Healthcare BPO Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare BPO Market Intelligence
Consolidation among large hospital networks and insurance providers is recalibrating the procurement dynamics for business process outsourcing services. This shift favors larger BPO providers with scalable platforms and broad service portfolios. Accenture leverages its deep consulting expertise to offer end-to-end transformation services. Optum specializes in integrated health services and data analytics, while Tata Consultancy Services competes on the basis of its global delivery model.
Healthcare business process outsourcing involves contracting non-core operational functions, such as billing or patient data management, to specialized third-party vendors. This practice aims to reduce administrative costs, improve cash flow, and allow providers to focus on patient care. Revenue Cycle Management and Claims Processing constitute the largest service segments, driven by the sheer complexity of medical billing codes. Technology integration using Robotic Process Automation represents the fastest-growing area, promising significant efficiency gains.
Data security and patient privacy are paramount, governed by strict regulations like the Health Insurance Portability and Accountability Act (HIPAA) in the United States and GDPR in Europe. Adherence to these frameworks dictates vendor selection criteria, data handling protocols, and the viability of offshore delivery models. Vendors must continuously invest in security infrastructure and employee training to maintain market access and client trust.
Market Dynamics
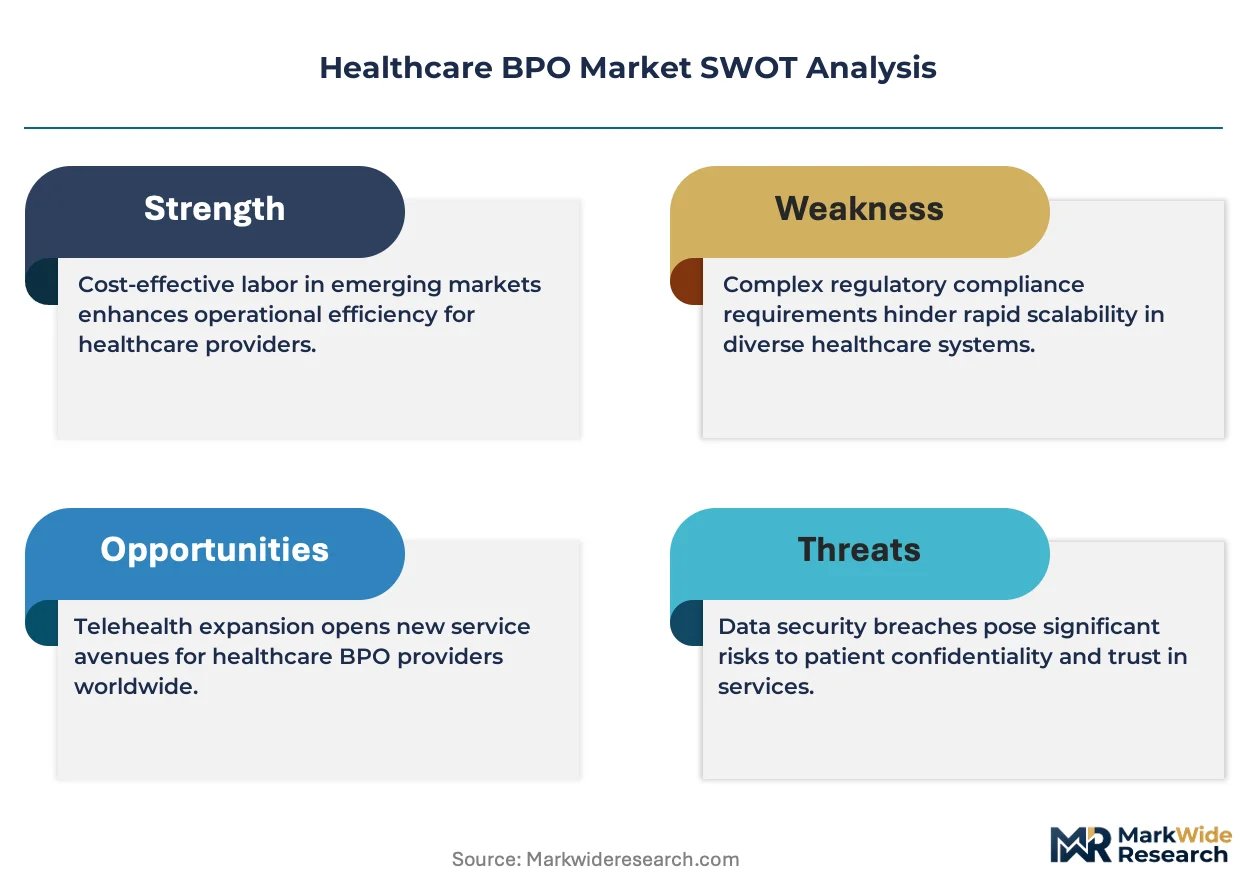
The central force shaping the healthcare BPO market is the intense pressure on providers to reduce administrative overhead while navigating an increasingly complex web of global regulations, including HIPAA in the US and GDPR in Europe.
Growth Catalysts
- Complex Coding Systems:The shift to frameworks like ICD-11 compels providers to outsource medical coding to specialized vendors to ensure billing accuracy and maintain revenue.
- Data Interoperability:Mandates for interoperability using standards like HL7 create demand for BPO firms to manage complex data integration between provider systems.
- Demographic Shifts:Aging populations in Japan and Germany increase healthcare utilization, expanding the volume of administrative work suitable for outsourcing.
Market Restraints
- Data Sovereignty Laws:Regulations in countries like China restrict cross-border health data transfers, limiting the viability of certain offshore BPO delivery models.
- EHR System Fragmentation:A lack of standardization among electronic health record systems creates significant integration costs and complexity for BPO vendors.
- High Implementation Costs:The initial investment in secure, HIPAA-compliant infrastructure can be a significant barrier for smaller healthcare providers considering outsourcing.
Strategic Opportunities
- Telehealth Support Services:The growth of virtual care creates new service lines for outsourced patient scheduling, technical support, and remote monitoring data management.
- Underpenetrated Markets:Mid-sized hospitals in countries like Brazil and Mexico represent a large, underserved client base for comprehensive BPO services.
- Predictive Analytics Services:Integrating AI with BPO workflows enables new offerings for predicting claims denials and identifying patient non-payment risk.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of professionals skilled in both medical coding and data science limits the ability of BPO providers to scale value-added services.
- Legacy System Integration:Connecting modern BPO platforms with clients' outdated hospital information systems is a major source of implementation delays and technical friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare BPO Market |
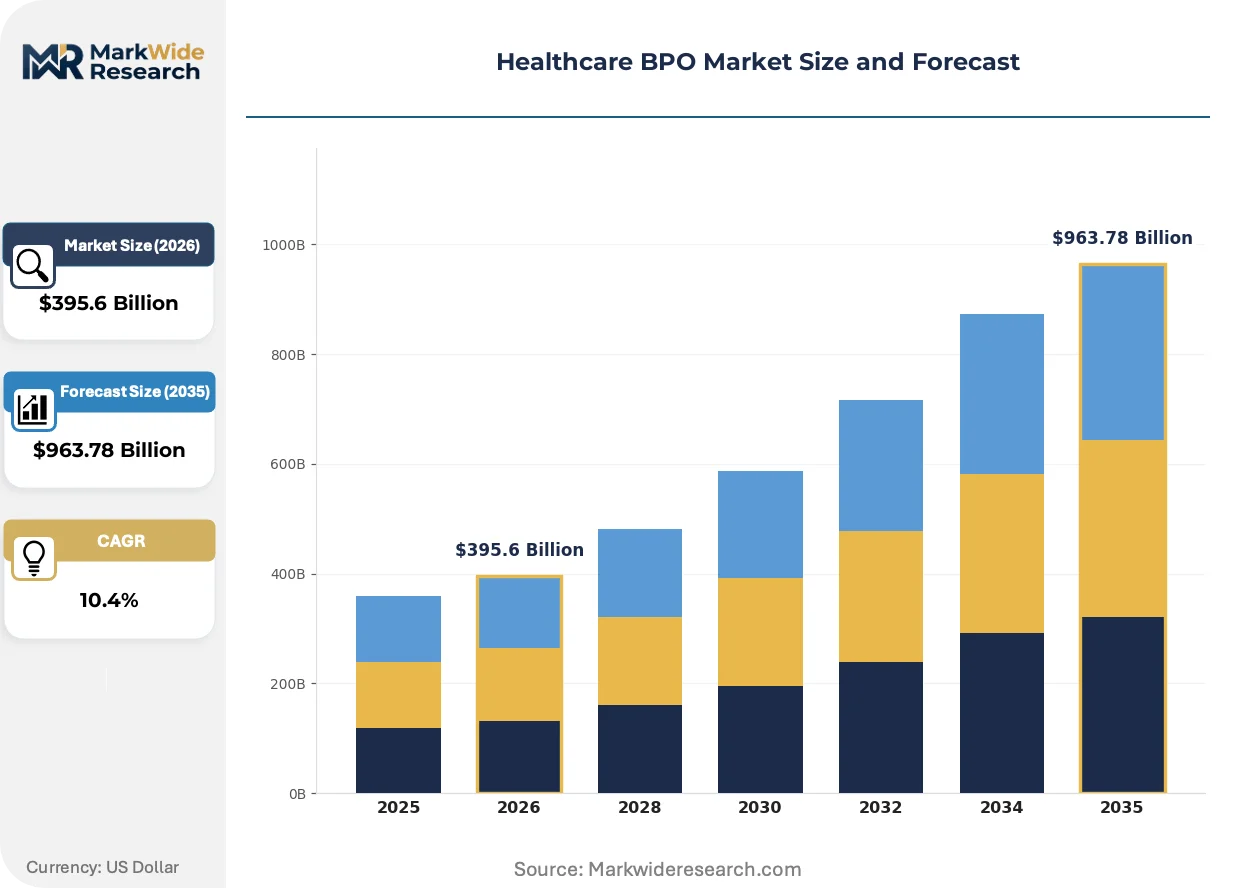
| Market Size in 2026 | $395.6 Billion |
| Market Size in 2035 | $963.78 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Processing, Medical Coding, Revenue Cycle Management, Patient Support, Telehealth Services, Compliance Management End User: Hospitals, Diagnostic Centers, Pharmacies, Ambulatory Centers, Insurance Providers, Clinical Laboratories Delivery Model: Onshore, Nearshore, Offshore, Hybrid, Cloud-Based, On-Premise Technology Integration: Robotic Process Automation, Artificial Intelligence, Electronic Health Records, Natural Language Processing, Blockchain, Chatbots |
| Companies Covered | Accenture, Cognizant Technology Solutions Corporation, Optum, Tata Consultancy Services, IBM, Infosys, Wipro, Genpact, IQVIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare BPO Market Strategic Shifts & Innovations
The evolution of healthcare BPO reflects a definitive pivot from simple labor arbitrage to technology-driven partnerships. Service providers are now evaluated on their ability to integrate automation and analytics to deliver measurable clinical and financial outcomes.
Robotic Process Automation, enhanced with artificial intelligence, is a foundational technology for modern healthcare BPO. Insurance companies and hospital networks are deploying these bots to handle high-volume, rule-based tasks like eligibility verification and data entry. This technology is automating manual back-office workflows, which reduces human error in medical billing and allows staff to focus on complex claims adjudication.
Adherence to the EU's General Data Protection Regulation (GDPR) has established a strict global benchmark for data privacy. This forces BPO vendors to segregate data, invest in advanced security infrastructure, and implement rigorous training protocols for all staff handling patient information. Offshore providers in India and the Philippines serving European clients are most impacted, requiring demonstrable compliance to secure and retain contracts.
A shift from transactional, fee-for-service contracts to value-based partnerships is altering procurement models. This change deemphasizes simple task completion in favor of integrated relationships where BPO vendors share financial risk and are compensated based on achieving specific outcomes, such as reduced claims denial rates. This model is most prominent among large integrated delivery networks in the United States.
Healthcare BPO Market Segmentation
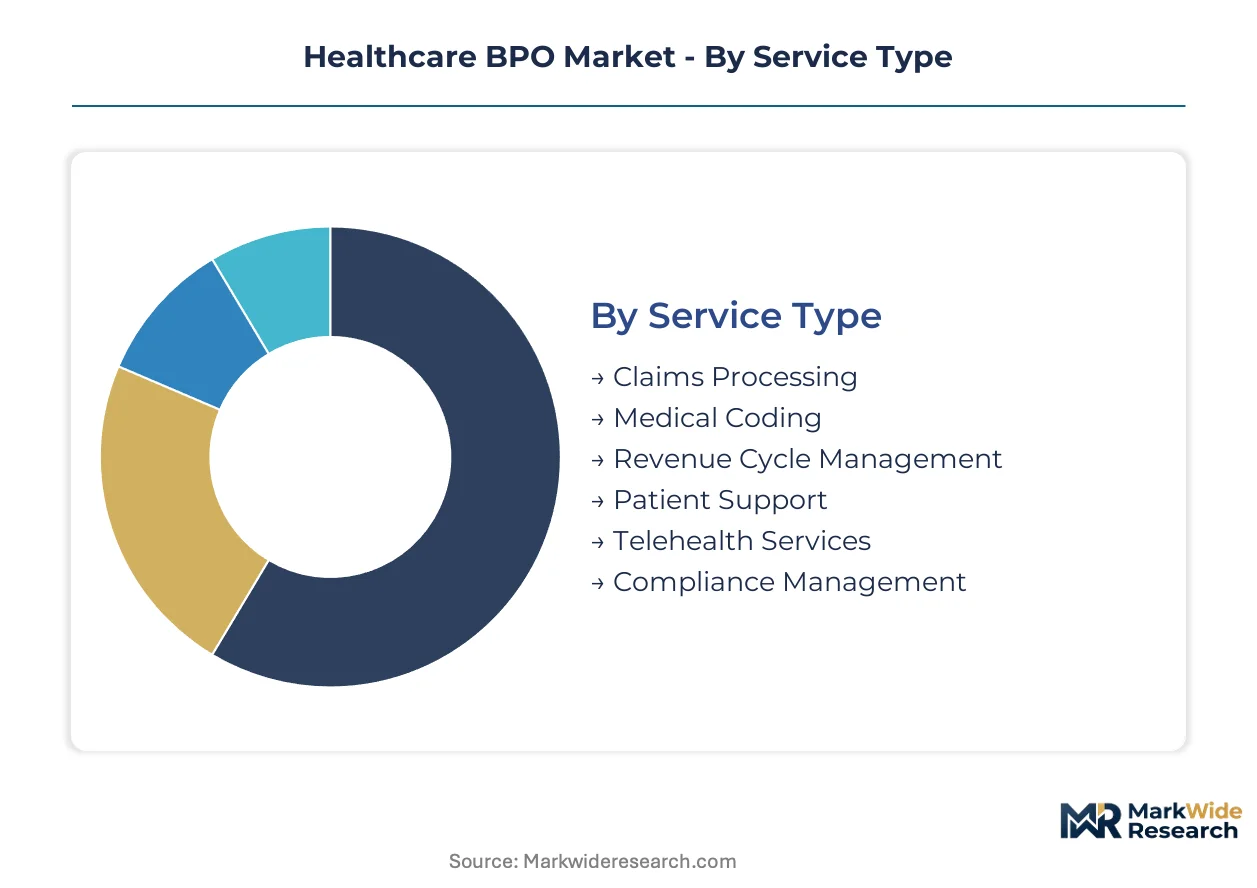
The healthcare BPO market exhibits diverse service offerings and operational models. Understanding these segments clarifies the varying client needs and the specialized capabilities required from providers. This segmentation highlights areas of significant investment and operational complexity.
Service Type:
The capital intensity in service type segmentation varies, with technology-driven offerings demanding substantial upfront investment in platforms and skilled personnel.
- Claims Processing:Involves the submission and follow-up of medical claims with health insurance companies to receive payment for services rendered. Demand concentrates among insurance providers in the United States, driven by the need to manage high volumes and reduce administrative burdens.
- Revenue Cycle Management:Encompasses all administrative and clinical functions that contribute to the capture, management, and collection of patient service revenue. Providers in Europe leverage RCM to optimize cash flow amidst evolving reimbursement models.
- Medical Coding:Translates medical diagnoses, procedures, and services into universal alphanumeric codes for billing and documentation.
- Patient Support:Includes services like appointment scheduling, patient inquiries, and post-discharge follow-ups, enhancing patient engagement.
- Telehealth Services:Manages virtual care logistics, technical support for platforms, and remote patient monitoring data.
- Compliance Management:Ensures adherence to healthcare regulations like HIPAA and GDPR, mitigating legal and financial risks.
Revenue Cycle Management absorbs the bulk of installed capacity; Telehealth Services is expanding most quickly.
End User:
The cost tier for end-user engagement differs significantly, with larger entities often commanding more favorable terms due to volume and long-term contracts.
- Hospitals:Large, integrated healthcare facilities requiring comprehensive BPO services for administrative functions, billing, and patient records. Demand from hospitals in Germany is high, seeking efficiency gains to manage rising operational costs.
- Insurance Providers:Organizations offering health insurance plans, outsourcing claims adjudication, enrollment, and customer service to specialized vendors. US-based insurers drive demand for BPO to streamline complex claims processing and reduce overhead.
- Diagnostic Centers:Outsource billing and patient scheduling to focus on specialized medical imaging and laboratory testing.
- Pharmacies:Utilize BPO for prescription processing, inventory management, and customer support services.
- Ambulatory Centers:Focus on outpatient surgical and procedural care, outsourcing revenue cycle and patient registration.
- Clinical Laboratories:Leverage BPO for test order entry, results management, and billing accuracy.
Hospitals concentrate the largest volume of BPO transactions; Clinical Laboratories show increasing BPO adoption for specialized tasks.
Delivery Model:
The application of various delivery models depends on client security requirements, cost considerations, and regulatory compliance across different geographies.
- Offshore:Services delivered from geographically distant locations, such as India and the Philippines, leveraging lower labor costs and large talent pools. Demand from European clients for offshore models is strong, driven by cost savings and access to skilled workforces.
- Hybrid:Combines elements of onshore, nearshore, and offshore models, optimizing for cost, cultural proximity, and specific regulatory needs. Large US hospital networks adopt hybrid models to balance data sensitivity with efficiency gains.
- Onshore:Services provided within the client's own country, ensuring cultural alignment and strict regulatory oversight.
- Nearshore:Services delivered from neighboring countries, offering a balance of cost savings and geographical proximity.
- Cloud-Based:BPO services hosted on cloud infrastructure, providing scalability, remote access, and reduced IT overhead for clients.
- On-Premise:BPO operations conducted within the client's physical location, often for highly sensitive data or specific security mandates.
Offshore delivery models offer the highest margin potential for BPO providers; Cloud-Based models are gaining traction due to scalability.
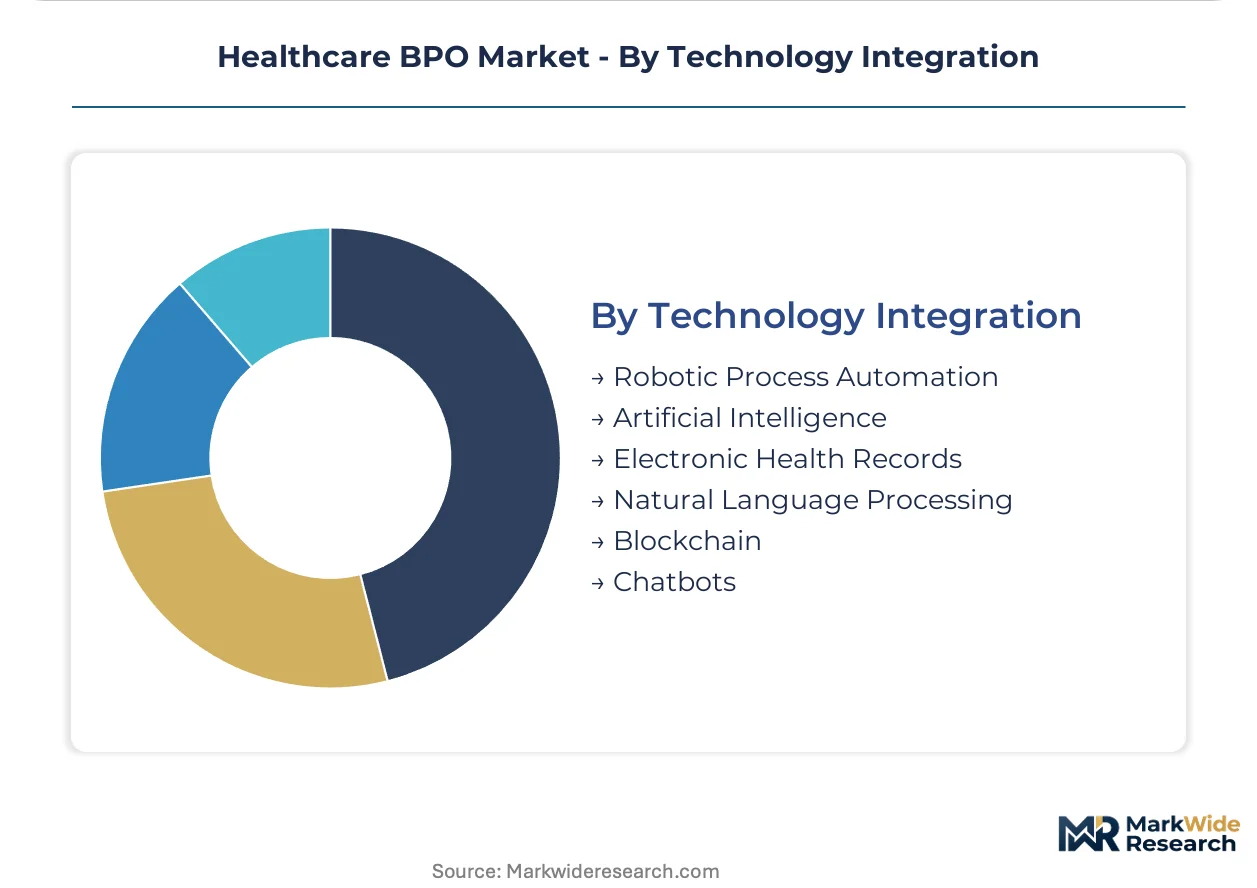
Technology Integration:
The volume of transactions dictates the necessity for advanced technology integration, enabling BPO providers to process large datasets efficiently and accurately.
- Robotic Process Automation:Utilizes software bots to automate repetitive, rule-based tasks such as data entry, claims processing, and eligibility verification. Insurance providers in the UK deploy RPA to significantly reduce manual errors and accelerate claims adjudication.
- Artificial Intelligence:Incorporates machine learning and cognitive computing to analyze complex healthcare data, predict claims denials, and identify patient non-payment risks. Healthcare systems in Canada use AI for predictive analytics to improve operational efficiency.
- Electronic Health Records:Focuses on the management, integration, and interoperability of digital patient health information across systems.
- Natural Language Processing:Extracts and interprets unstructured clinical data from medical notes and reports for improved insights.
- Blockchain:Offers secure, decentralized ledger technology for managing patient records and ensuring data integrity across the healthcare ecosystem.
- Chatbots:Provide automated patient support, answer frequently asked questions, and assist with appointment scheduling.
Robotic Process Automation represents a mature integration point; Blockchain is at an earlier stage of market adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for healthcare BPO services concentrates in regions with high administrative complexity and cost pressures. Insurance providers and hospital networks globally seek external expertise to streamline operations. This trend is particularly evident in developed economies and emerging outsourcing hubs, driving specialized service delivery.
United States
Complex medical billing codes and a large insurance provider base drive significant demand for healthcare BPO services. HIPAA dictates stringent data security and patient privacy protocols for all vendors operating in this market. The Dallas-Fort Worth metropolitan area sees substantial BPO activity, fueled by numerous healthcare providers and insurance companies.
India
India offers a cost-effective skilled workforce and established BPO infrastructure, making it a prominent offshore destination. The country's IT Act supports robust data protection, aligning with global standards for offshore services. Bengaluru and Chennai host major BPO delivery centers, attracting investments for claims processing and revenue cycle management.
Germany
An aging population in Germany increases healthcare utilization, creating demand for efficiency gains in hospital administration. GDPR compliance is a critical factor for BPO vendors handling patient data originating from Europe. Berlin and Munich are emerging hubs for BPO services, focusing on digital health and administrative support solutions.
Philippines
The Philippines benefits from high English proficiency and a large talent pool suitable for customer support and back-office functions. The Data Privacy Act of 2012 provides a legal framework for data protection, bolstering client confidence. Metro Manila and Cebu are primary locations for healthcare BPO operations, specializing in patient support and medical coding.
United Kingdom
The National Health Service's administrative burden and the need for efficiency in claims and patient management drive BPO demand. GDPR and UK data protection laws govern the handling of sensitive health information for all providers. London and Manchester are developing as centers for digital transformation in healthcare BPO, integrating AI and automation.
Healthcare BPO Market Key Industry Players
United States-based providers anchor one tier, emphasizing end-to-end solutions and stringent data security; India and Philippines-based specialists hold another, focusing on cost-efficiency and large-scale delivery. The market structure features a mix of global IT service giants, specialized healthcare BPO firms, and regional niche players. These archetypes compete through strategic partnerships, continuous technology integration, and portfolio diversification. Geographic expansion into underpenetrated markets also represents a significant competitive move.
Within the global IT services tier, Accenture exemplifies a provider leveraging deep consulting expertise to offer end-to-end transformation services across various healthcare functions. Optum, a United States-based entity, represents integrated health services and data analytics specialization within the market, focusing on complex operational challenges. Tata Consultancy Services, an India-based firm, occupies a position emphasizing a global delivery model for diverse BPO functions, particularly in offshore locations. These firms collectively demonstrate the varied strategic approaches to serving the healthcare sector's evolving needs.
| Leading Market Players |
|---|
| Accenture |
| Cognizant Technology Solutions Corporation |
| Optum |
| Tata Consultancy Services |
| IBM |
| Infosys |
| Wipro |
| Genpact |
| IQVIA |
| Others |
Cost & Logistics Intelligence
GDPR compliance gates access to European clients, directly influencing qualified supply and premium-tier pricing for healthcare BPO services. This regulatory framework mandates rigorous data handling protocols, impacting vendor selection and operational costs.
Pricing Analysis
Volume-based contracts often characterize foundational BPO services, while value-based partnerships command higher margins for specialized outcomes. Pricing differentiation stems from robust data security certifications and advanced technology integration, particularly for AI-driven solutions. Pricing pressure stems from the consolidation among large hospital networks, which seek greater cost efficiencies from their BPO partners. Mid-sized hospitals in emerging markets demonstrate higher price sensitivity compared to large integrated delivery networks in developed economies.
Supply Chain Analysis
Secure data handling and error remediation processes form the core of reverse logistics in healthcare BPO. Geographic supply concentrates significantly in India and the Philippines, leveraging their cost-effective, skilled workforces. The supply chain relies on specialized medical coding talent, secure IT infrastructure, and proprietary software licenses. Data sovereignty laws, such as those in China, pose a structural risk to cross-border data transfers. Distribution runs through direct service provision, typically via long-term B2B contracts with healthcare providers and insurance companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently engaged in a vertical-integration race, with players actively pursuing downstream technology integration as a key lever for differentiation.
For Market Incumbents: Deploy advanced automation platforms to enhance service delivery efficiency and reduce operational costs. Acquire specialized AI/RPA technology firms to counter the threat from niche tech-enabled BPO providers. Deepen consulting expertise to offer end-to-end transformation services, securing long-term contracts with large hospital networks. Invest continuously in security infrastructure to mitigate regulatory shifts and maintain client trust.
For New Entrants and Emerging Players: Enter via specialized telehealth support services, addressing the growing demand for virtual care logistics. Target predictive analytics for mid-sized hospitals in underpenetrated markets like Brazil and Mexico, offering tailored solutions. Focus on a niche technology angle, such as AI-driven claims denial prediction, to establish a distinct market position. Leverage flexible, cloud-based delivery models to minimize initial infrastructure costs.
For Investors and Strategic Acquirers: Increased regulatory enforcement of data privacy is the leading indicator that compliance-focused BPO firms will command premium valuations. The market offers sustainable long-term growth, driven by ongoing cost pressures on healthcare providers and continuous technological evolution. Target specialized BPO providers with proven AI/RPA capabilities and robust, auditable compliance frameworks. Practitioners should monitor the adoption rates of value-based care models in new geographies for early signals.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Claims Processing | Enhances efficiency for insurance providers, reducing manual errors in medical billing. |
| GDPR Compliance Certification | Secures contracts with European clients by demonstrating robust data protection protocols. |
| Telehealth Platform Integration | Expands service offerings for patient support, managing virtual care logistics. |
| Offshore Delivery Center Expansion | Leverages cost-effective talent pools in India and the Philippines for scalable operations. |
| Predictive Analytics Development | Identifies patient non-payment risk for healthcare systems, improving revenue cycle management. |
Research Approach
Document review covered industry association reports, government healthcare expenditure data, financial filings of public BPO firms, and academic research on healthcare IT, complemented by interviews with industry stakeholders. Primary research included conversations with BPO service executives, hospital administrators, insurance claims managers, and regulatory compliance officers. This approach facilitated bottom-up and top-down triangulation of market data.
Cross-referencing historical market data with expert panel input formed the basis of the forecast framework across the analysis window. The model integrated segmentation dimensions such as service type, end user, delivery model, technology integration, and regional demand. CAGRs were derived from a combination of historical trends and consensus among industry experts. Key industry-specific forecast inputs included healthcare utilization rates and anticipated regulatory changes like HIPAA updates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of geopolitical instability or rapid technological disruption. These forecasts reflect assumptions regarding market dynamics and regulatory stability. Practitioners should monitor new data privacy legislation and major healthcare reform initiatives for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Process Outsourcing (BPO)
Global Knowledge Process Outsourcing Market
Business Process Outsourcing (BPO)
Life Sciences BPO Market
Business Process Outsourcing (BPO)
Call Center Outsourcing Market
Business Process Outsourcing (BPO)
Global Outsourced Sales Service Market
Business Process Outsourcing (BPO)
Recruitment Process Outsourcing (RPO) Services Market
Business Process Outsourcing (BPO)
Business Process Management (BPM) Market
Business Process Outsourcing (BPO)
Service Bureau Market
Business Process Outsourcing (BPO)
Global Business Process Outsourcing (BPO) Market
Business Process Outsourcing (BPO)
South Africa Business Process Outsourcing Market
Business Process Outsourcing (BPO)
Technical Support Outsourcing Market
Business Process Outsourcing (BPO)
Digitalization in Bpo Market
Business Process Outsourcing (BPO)
Business Processing Outsourcing Market
Business Process Outsourcing (BPO)
Global Application Outsourcing Market
Business Process Outsourcing (BPO)
United States Healthcare BPO Market
Business Process Outsourcing (BPO)
Procurement Outsourcing Services Market
Business Process Outsourcing (BPO)
Global Contact and Call Center Outsourcing Market