
 Eddy Current Testing Market | 2026-2036
Eddy Current Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Eddy Current Testing Market Foresight
North American aerospace manufacturing capacity is reshaping competitive dynamics across the eddy current testing supply base. Eddyfi NDT leverages deep R&D intensity in advanced probe design to sustain technology leadership in phased-array applications. Mistras Group anchors its position through extensive service networks across power generation and oil and gas inspection contracts. Zetec competes aggressively on digital signal processing platforms that integrate with automated manufacturing lines.
Eddy current testing employs electromagnetic induction to detect surface and near-surface flaws in conductive materials, operating across frequency ranges from fifty hertz to several megahertz depending on inspection depth requirements. The method serves critical quality assurance functions in safety-intensive industries where material integrity failures carry catastrophic liability. Portable devices dominate volume shipments due to field inspection requirements in aerospace maintenance, while inline testers command premium positioning within automotive and manufacturing process control. Multi-frequency testing represents the fastest-expanding technology segment as complex component geometries demand simultaneous depth-resolved defect characterization.
FAA airworthiness directives and ASME boiler and pressure vessel codes collectively mandate periodic eddy current inspection intervals across regulated infrastructure, creating structural demand for certified equipment and trained operators. EPA leak detection standards in petrochemical applications further extend instrument deployment requirements. Stakeholders must monitor evolving NADCAP accreditation criteria and digital twin integration standards as these frameworks increasingly determine supplier qualification and contract eligibility.
Market Dynamics
Multi-frequency eddy current testing is collapsing inspection cycle times for complex aerospace geometries, forcing incumbent probe manufacturers to re-architect hardware platforms around software-defined signal processing rather than analog circuit dominance.
Growth Catalysts
- FAA Airworthiness Directives:Mandated inspection intervals for engine components and landing gear assemblies generate recurring instrument demand across US maintenance, repair, and overhaul facilities.
- TÜV Certification Standards:German industrial end-users face pressure to upgrade precision instruments, accelerating replacement cycles for single-frequency legacy systems.
- Phased-Array Probe Miniaturization:Advances in coil winding density enable handheld devices to match benchtop resolution, expanding field deployment in pipeline integrity programs.
Market Restraints
- Copper and Rare-Earth Magnet Costs:Probe manufacturing depends on copper windings and neodymium magnets, exposing margins to commodity volatility from Chinese supply concentration.
- Deep Subsurface Detection Limitation:Eddy current penetration depth remains constrained by skin effect physics, ceding thick-walled pressure vessel inspection to ultrasonic alternatives.
- NADCAP Accreditation Friction:Aerospace suppliers face 12-18 month qualification timelines for new inspection procedures, delaying technology refresh cycles.
Strategic Opportunities
- India Defense Manufacturing:Indigenous fighter jet and submarine programs under the country's PLI scheme create demand for certified non-destructive testing infrastructure.
- Digital Twin Integration:Convergence of eddy current data streams with physics-based simulation models enables predictive maintenance contracts in wind turbine blade monitoring.
- Automated Manufacturing Lines:Inline robotic inspection cells in electric vehicle battery tab welding operations represent greenfield deployment for high-speed multi-frequency systems.
Industry Challenges
- ASNT Level III Certification Scarcity:Qualified technicians capable of procedure development and auditor interpretation command premium wages, constraining service network expansion.
- Legacy System Integration Complexity:Retrofitting digital signal processing platforms into existing quality management databases requires custom middleware development.
- ISO/IEC 17025 Audit Burden:Calibration laboratory accreditation demands continuous proficiency testing and interlaboratory comparisons, elevating fixed cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eddy Current Testing Market |
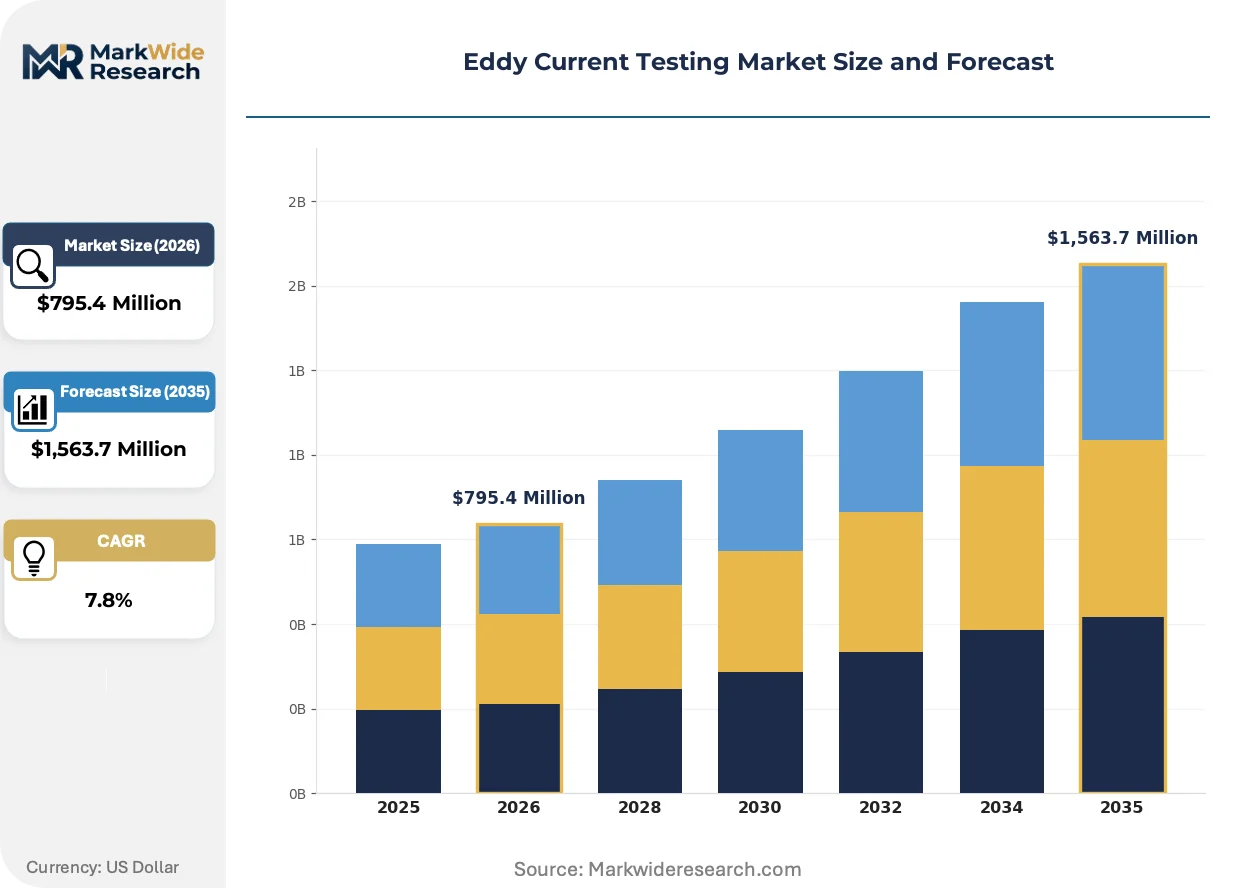
| Market Size in 2026 | $795.4 Million |
| Market Size in 2035 | $1,563.7 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Fixed Systems, Inline Testers, Customized Solutions End User: Aerospace, Automotive, Power Generation, Manufacturing Technology: Analytical Software, Wireless Technology, Digital Signal Processing, Multi-frequency Testing Application: Material Inspection, Thickness Measurement, Weld Integrity Assessment, Coating Thickness Testing |
| Companies Covered | Eddyfi NDT, Mistras Group, IBG NDT System Corporation, Fidgeon Limited, Ashtead Technology, Zetec, Magnetic Analysis Corporation, Ether NDE Limited, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eddy Current Testing Market Shifts & Advancements
Inspection hardware is shedding analog legacy architectures in favor of software-defined platforms that decouple probe physics from signal interpretation, compressing development cycles and enabling over-the-air feature expansion.
Remote-field eddy current technology is collapsing the boundary between internal and external pipeline inspection capabilities. Operators at TransCanada and Colonial Pipeline have deployed robotic crawlers carrying RFEC sensors through unpiggable lines, eliminating excavation requirements for corrosion mapping. This convergence of robotics and electromagnetic sensing is compressing the addressable market for radiographic alternatives in midstream infrastructure.
REACH substance restrictions on hexavalent chromium coatings are forcing probe manufacturers to migrate toward ceramic and polymer wear surfaces. German sensor suppliers face 2026 compliance deadlines for coil housing treatments, triggering reformulation partnerships with BASF and Evonik. The regulatory pressure is accelerating adoption of physical vapor deposition alternatives across EU-based instrument production.
Asset owners are unbundling inspection hardware purchases from service contracts, preferring capital-light rental models with guaranteed uptime clauses. North American power utilities now source eddy current systems through third-party fleet managers rather than direct OEM procurement, shifting margin capture toward logistics and certification providers. This financing innovation is most pronounced in combined cycle gas turbine blade inspection programs where seasonal demand volatility favors operational expenditure treatment.
Eddy Current Testing Market Segmentation
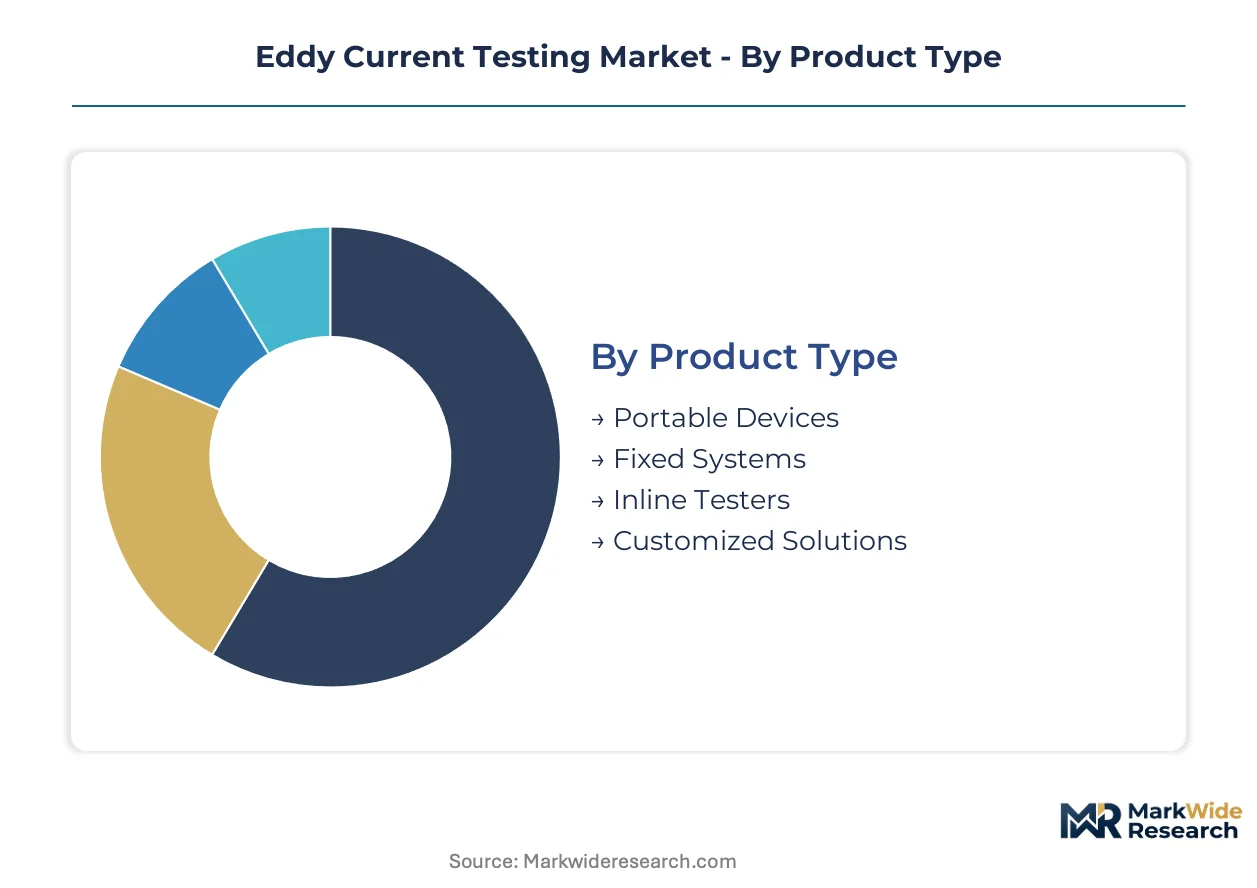
Eddy current testing segmentation reveals stark contrasts in equipment lifecycle economics. Portable devices turn over every 3-5 years under field abuse conditions, while inline testers operate on 10-15 year depreciation schedules tied to manufacturing line investments.
Product Type:
Replacement velocity varies dramatically across hardware categories, with field-deployable units cycling fastest and capital-intensive inline systems anchoring long-term revenue streams.
- Portable Devices:Handheld battery-powered units with integrated displays and interchangeable probe heads dominate aerospace MRO workflows. FAA-mandated engine inspections at Delta TechOps and United Airlines facilities drive recurring procurement as vibration damage accumulates.
- Inline Testers:Robotic inspection cells integrated into automotive welding lines perform 100% coverage of EV battery tab joints. Tesla Gigafactory Berlin and BMW Spartanburg deploy these systems with 0.3-second cycle times per weld.
- Fixed Systems:Benchtop laboratory instruments serve materials characterization at university research centers and metallurgical labs.
- Customized Solutions:Application-specific probe arrays address unique geometries in nuclear steam generator tube inspection.
Portable devices anchor the volume base while inline testers gain share at the steepest rate.
End User:
Customer procurement sophistication separates price-sensitive volume buyers from specification-driven premium purchasers across industrial verticals.
- Aerospace:AS9100-certified suppliers at Boeing Charleston and Airbus Mobile enforce NADCAP-accredited inspection protocols. Landing gear borescopes and engine fan blade scans require traceable calibration chains.
- Automotive:Tier-1 stampers at Gestamp and Novelis deploy eddy current for heat-treat verification in aluminum body-in-white panels. Cycle time pressure favors multi-frequency systems that collapse inspection stations.
- Power Generation:Combined cycle gas turbine operators at Duke Energy and Dominion Energy contract seasonal blade inspection services.
- Manufacturing:General fabrication shops source entry-level single-frequency units for basic crack detection.
Aerospace commands the premium pricing tier while automotive delivers the steepest volume expansion trajectory.
Technology:
Software capabilities now determine competitive positioning more than probe hardware, compressing development cycles and enabling feature expansion without physical redesign.
- Multi-frequency Testing:Simultaneous excitation across 50 Hz to 10 MHz enables depth-resolved defect characterization in complex turbine blade geometries. Siemens Energy and GE Vernova specify these systems for rotating equipment programs.
- Digital Signal Processing:FPGA-based real-time analysis platforms filter noise in electrically noisy manufacturing environments. Schaeffler Group deploys these for bearing raceway inspection at its Schweinfurt facility.
- Analytical Software:Cloud-connected platforms store inspection histories and enable predictive maintenance algorithms.
- Wireless Technology:Bluetooth probe-to-tablet connectivity eliminates cable fatigue in confined-space inspections.
Digital signal processing anchors installed base economics while multi-frequency testing climbs the fastest on new equipment specifications.
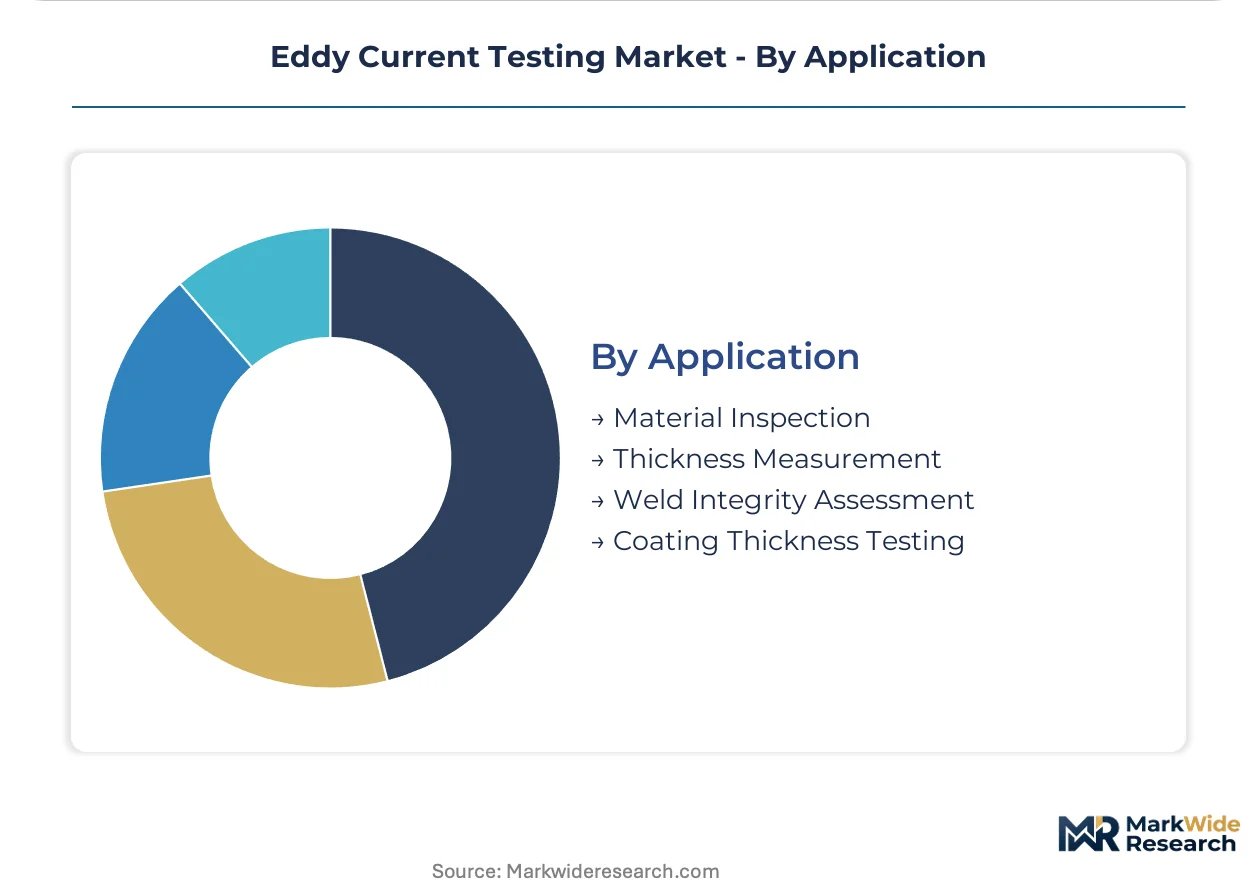
Application:
Functional use cases stratify by inspection depth requirements and surface condition tolerance, with some applications ceding ground to ultrasonic alternatives.
- Material Inspection:Surface and near-surface crack detection in aircraft landing gear and pipeline girth welds. TransCanada's integrity management program specifies eddy current for external corrosion mapping where coating removal is prohibited.
- Weld Integrity Assessment:Automated scanning of resistance spot welds in automotive production. Volkswagen Chattanooga and Hyundai Montgomery rely on these systems for structural joint verification.
- Thickness Measurement:Non-contact gauging of conductive coatings and claddings in chemical processing equipment.
- Coating Thickness Testing:Quality control of anodized layers and paint systems in architectural aluminum.
Material inspection holds the broadest installed base while weld integrity assessment accelerates most quickly on automotive electrification investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor demand concentration in the United States, where aerospace maintenance networks drive instrument procurement cycles. German TÜV certification standards and Japanese industrial precision requirements create secondary demand poles across distinct regulatory environments.
United States
Delta TechOps and United Airlines maintenance facilities in Atlanta and Chicago sustain recurring portable device demand for engine component inspections. FAA-mandated landing gear and fan blade inspection intervals create structural procurement obligations across MRO networks. Boeing Charleston's AS9100-certified supplier base enforces NADCAP-accredited protocols throughout the Southeast manufacturing corridor.
Germany
Schaeffler Group's bearing raceway inspection requirements at Schweinfurt drive digital signal processing platform adoption. TÜV certification standards accelerate replacement cycles for single-frequency legacy systems across industrial end-users. Siemens Energy and GE Vernova specify multi-frequency systems for rotating equipment programs anchored in Bavaria's power generation cluster.
Japan
Automotive electrification investments at Toyota and Nissan facilities favor inline robotic inspection cells with sub-second cycle times. METI industrial standards emphasize precision instrument calibration chains for export-oriented manufacturing. Kansai and Chubu industrial corridors concentrate demand for handheld devices serving confined-space weld verification.
China
MIIT industrial upgrading initiatives push domestic NDT infrastructure expansion across Yangtze River Delta manufacturing zones. GB standards alignment with international certification frameworks enables supplier qualification for aerospace export contracts. Shanghai and Shenzhen clusters concentrate probe manufacturing capacity serving regional maintenance networks.
India
PLI scheme incentives for indigenous fighter jet and submarine programs create certified NDT infrastructure demand. BIS standards harmonization with NADCAP criteria accelerates supplier qualification timelines for defense contractors. Bengaluru and Hyderabad defense manufacturing corridors anchor instrument procurement for aerospace and naval applications.
Eddy Current Testing Market Competitive Landscape
Technology specialists and integrated service providers split the market between hardware innovation and contract inspection networks. The vendor base concentrates around probe design expertise, digital signal processing platforms, and extensive field service footprints. Two archetypes dominate: R&D-intensive instrument manufacturers competing on phased-array resolution, and service-network operators capturing recurring maintenance contracts. Competitive moves center on software-defined platform architecture shifts and third-party fleet management partnerships that convert capital expenditure to operational expenditure treatment.
Within the technology-specialist tier, Eddyfi NDT and Zetec exemplify probe design and digital platform differentiation respectively. Mistras Group anchors the integrated-service archetype through contract-based inspection networks. These three occupy positions spanning hardware innovation, signal processing software, and field-deployed service capacity across regulated aerospace and power generation verticals.
| Leading Market Players |
|---|
| Eddyfi NDT |
| Mistras Group |
| IBG NDT System Corporation |
| Fidgeon Limited |
| Ashtead Technology |
| Zetec |
| Magnetic Analysis Corporation |
| Ether NDE Limited |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Chinese concentration in neodymium magnet and copper winding production anchors probe manufacturing costs, concentrating margin capture with OEMs who control coil design IP and calibration certification chains rather than raw material processors.
Pricing Analysis
North American aerospace MRO facilities pay 40-60% premiums over German industrial buyers for identical multi-frequency hardware due to FAA-mandated traceability documentation and NADCAP audit requirements. Pricing stratifies across NADCAP-accredited premium tiers, TÜV-compliant standard tiers, and uncertified economy tiers for general fabrication. Cost compression in the economy segment is intensifying as Chinese probe manufacturers bypass distributor networks. Tier-1 aerospace suppliers at Boeing and Airbus facilities show the least price sensitivity, while general manufacturing shops in the US Midwest and India's SME sector drive hard bargaining on single-frequency portable units.
Supply Chain Analysis
Export control regimes under US EAR and EU dual-use regulations restrict phased-array probe technology flows to Chinese defense-adjacent entities, fragmenting global component sourcing. Manufacturing concentrates in Germany for precision coil winding, China for magnet and copper component processing, and the United States for FPGA-based signal processing boards. Probe assembly rests on neodymium magnets from Chinese rare-earth processors, copper wire from Chilean-German trading houses, and ceramic substrates from Japanese suppliers. Single-source vulnerability runs through Chinese magnet concentration, with distribution running through authorized distributor networks in aerospace and direct OEM sales for automotive inline systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through fleet management outsourcing at North American power utilities and third-party rental consolidation, shifting procurement leverage from fragmented MRO shops toward aggregated volume negotiators.
For Market Incumbents: Entrench position through backward integration into FPGA firmware development and captive calibration laboratory accreditation, defending against ultrasonic substitution in thick-walled pressure vessel inspection. Prioritize NADCAP audit-ready documentation packages that compress 12-18 month qualification timelines for new aerospace suppliers. Expand service network density in India's Bengaluru defense corridor ahead of PLI scheme infrastructure deployment. For New Entrants and Emerging Players: Pursue white-space opportunity in wireless probe-to-tablet connectivity for confined-space pipeline inspection, where cable fatigue drives replacement demand. Target India's indigenous submarine program certification requirements as the most penetrable defense vertical. Lead with rental-plus-certification bundled offerings that convert capital expenditure to operational expenditure treatment for seasonal gas turbine blade inspection programs. For Investors and Strategic Acquirers: Capital is best deployed toward software-defined platform specialists with over-the-air feature expansion capabilities rather than legacy analog probe manufacturers facing REACH compliance deadlines. Long-term viability over a 5-10 year window favors vendors integrating digital twin data streams for predictive maintenance contracts. Watch for inflection in NADCAP accreditation criteria updates that privilege cloud-connected inspection history platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Migration | Decouples probe hardware from signal processing, enabling FPGA-based feature expansion without physical redesign cycles. |
| NADCAP Calibration Laboratory Accreditation | Compresses aerospace supplier qualification timelines from 18 months to under 12 months at Delta TechOps and United Airlines facilities. |
| Digital Twin Integration Partnership | Converges eddy current data streams with Siemens Energy physics-based models for predictive rotating equipment maintenance. |
| Third-Party Fleet Management Alliance | Shifts margin capture from OEM hardware sales toward logistics providers serving Duke Energy seasonal inspection demand. |
| REACH-Compliant Probe Surface Reformulation | Accelerates ceramic and polymer wear surface adoption ahead of 2026 German compliance deadlines for hexavalent chromium coatings. |
Research Methodology
The analysis maps portable device, inline tester, fixed system, and customized solution sub-sectors, each validated through maintenance directors at aerospace MRO facilities, NDT service contract managers at power utilities, probe design engineers at instrument manufacturers, and calibration laboratory accreditation officers. Primary interviews combined with secondary validation against FAA airworthiness directive filings, TÜV certification registries, NADCAP audit documentation, EPA leak detection standards, and ASME boiler code inspection interval requirements. Bottom-up equipment shipment tracking and top-down end-use industry spend analysis were triangulated for convergence.
Assumptions held fixed include current FAA-mandated inspection interval schedules, REACH substance restriction timelines, and NADCAP accreditation criteria frameworks, while variables included copper and rare-earth magnet commodity price trajectories, India PLI scheme infrastructure buildout pace, and automotive electrification investment cycles. The analytical framework models product type, end user vertical, technology segment, and application dimensions across the projection horizon. CAGRs were derived from equipment replacement velocity differentials between 3-5 year portable cycles and 10-15 year inline depreciation schedules, with inputs including aerospace fleet expansion forecasts and EV battery tab welding line automation capex.
Sensitivities concentrate around FAA interval extension or compression, REACH coating restriction acceleration, and Chinese rare-earth export quota shifts. Forecasts reflect these documented assumptions. Material shifts in NADCAP digital twin integration standards or India BIS-NADCAP harmonization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Radiation Tester Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Metal Testing Equipment Market
Test and Measurement
Smart Implant Telemetry and Reliability Test Equipment Market
Test and Measurement
Tube Tester Market
Test and Measurement
Fluorometers Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Hardness Testing Machine Market
Test and Measurement
Shock Testing System Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Test Benches Market