
 Electronically Commutated (EC) Fan Market | 2026-2036
Electronically Commutated (EC) Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Electronically Commutated (EC) Fan Market Analysis
Distribution through industrial HVAC wholesalers is fragmenting as direct OEM procurement and specialized online channels capture volume from traditional intermediaries. Greenheck Fan Corporation leverages its captive fabrication network to control lead times on custom centrifugal configurations. ebm-papst Group anchors European supply with deep motor-manufacturing integration in Germany. Delta Electronics, Inc. competes aggressively in Asia-Pacific server cooling contracts through in-house semiconductor and fan assembly capacity.
An electronically commutated fan integrates a brushless DC motor with permanent magnet rotors and embedded electronic commutation circuitry, typically achieving efficiency above 90 percent at variable speeds through sinusoidal or trapezoidal drive algorithms. This architecture eliminates slip losses inherent in induction motors, making it the default choice for continuous-duty ventilation and thermal management. Centrifugal fans command the largest installed base in commercial HVAC, while axial configurations represent the fastest-expanding category driven by data center rack-density requirements. Sensorless technology is displacing Hall-effect sensing in cost-sensitive blower applications, concentrating margin pools in digital control firmware and magnet material supply.
The U.S. Department of Energy enforces minimum efficiency standards on commercial ventilation equipment under 10 CFR 431, directly elevating EC motor penetration in replacement cycles. The European Commission's Ecodesign Directive and associated Energy-related Products regulations mandate fan efficiency metrics that conventional shaded-pole and AC induction designs fail to meet. China's GB standards on motor efficiency, administered by the Standardization Administration, create parallel compliance pressure in manufacturing and export-oriented production. Stakeholders must monitor divergence between regional efficiency test protocols and magnet material sourcing constraints as dual imperatives shaping procurement strategy and supplier qualification.
Market Dynamics
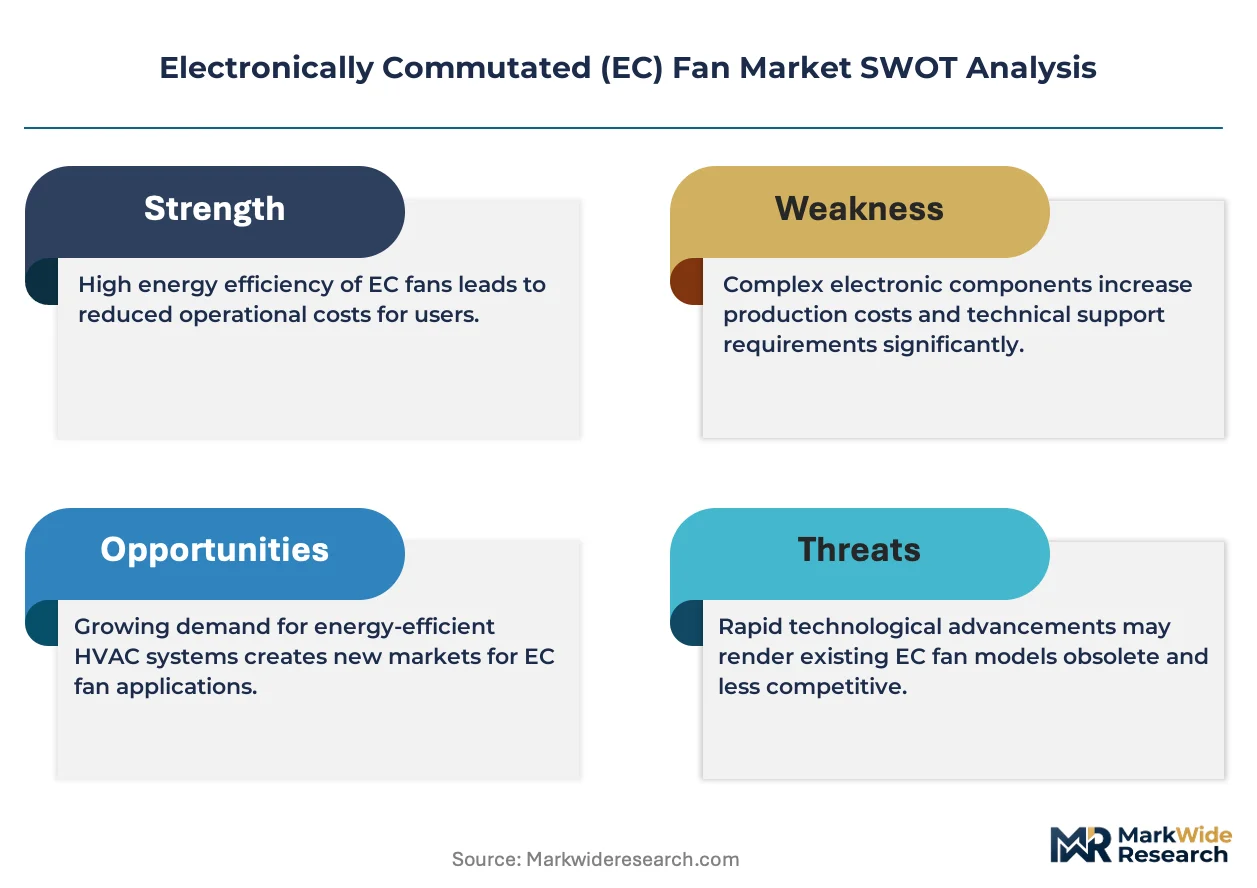
Permanent-magnet rotor integration and embedded digital control firmware are compressing motor architecture into single-source platforms, eliminating the supplier fragmentation that characterized AC induction supply chains for decades.
Growth Catalysts
- EPA and DOE efficiency mandates:10 CFR 431 standards in the United States compel facility managers to replace shaded-pole and AC induction fans with electronically commutated alternatives during routine replacement cycles.
- Data center rack-density requirements:Hyperscale operators in Germany and the Netherlands are specifying axial EC configurations for precision cooling arrays serving GPU-intensive workloads.
- Sensorless commutation algorithms:Trapezoidal and sinusoidal drive schemes without Hall-effect sensors are reducing BOM cost in cost-sensitive blower applications while maintaining 90-plus percent efficiency.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China, exposing motor manufacturers to export quota volatility and price spikes.
- Dual carbon goals compliance costs:China's GB motor efficiency standards impose parallel testing and certification burdens on export-oriented production without harmonized protocols.
- AC induction residual base:Legacy shaded-pole motors in installed commercial HVAC equipment continue to operate past theoretical replacement thresholds due to capital budget inertia.
Strategic Opportunities
- Industrial HVAC retrofit wave in Germany:Facility modernization programs targeting 2030 climate targets are creating replacement volume for centrifugal EC arrays in manufacturing plants.
- Direct OEM procurement channels:Fan manufacturers are bypassing traditional wholesale distribution to capture margin through specialized online platforms and captive specification relationships.
- EU Ecodesign Directive expansion:Energy-related Products regulations are extending efficiency metrics to previously exempt fan categories, mandating EC architecture in new product introductions.
Industry Challenges
- Firmware control expertise scarcity:Digital commutation algorithm development requires embedded systems engineering talent that competes with automotive and consumer electronics sectors for limited personnel pools.
- Magnet material qualification timelines:Alternative magnet formulations free of heavy rare-earth elements require extended validation cycles against established temperature and demagnetization specifications.
- Legacy building automation integration:EC fan digital control interfaces must bridge Modbus, BACnet, and proprietary legacy protocols without full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronically Commutated (EC) Fan Market |
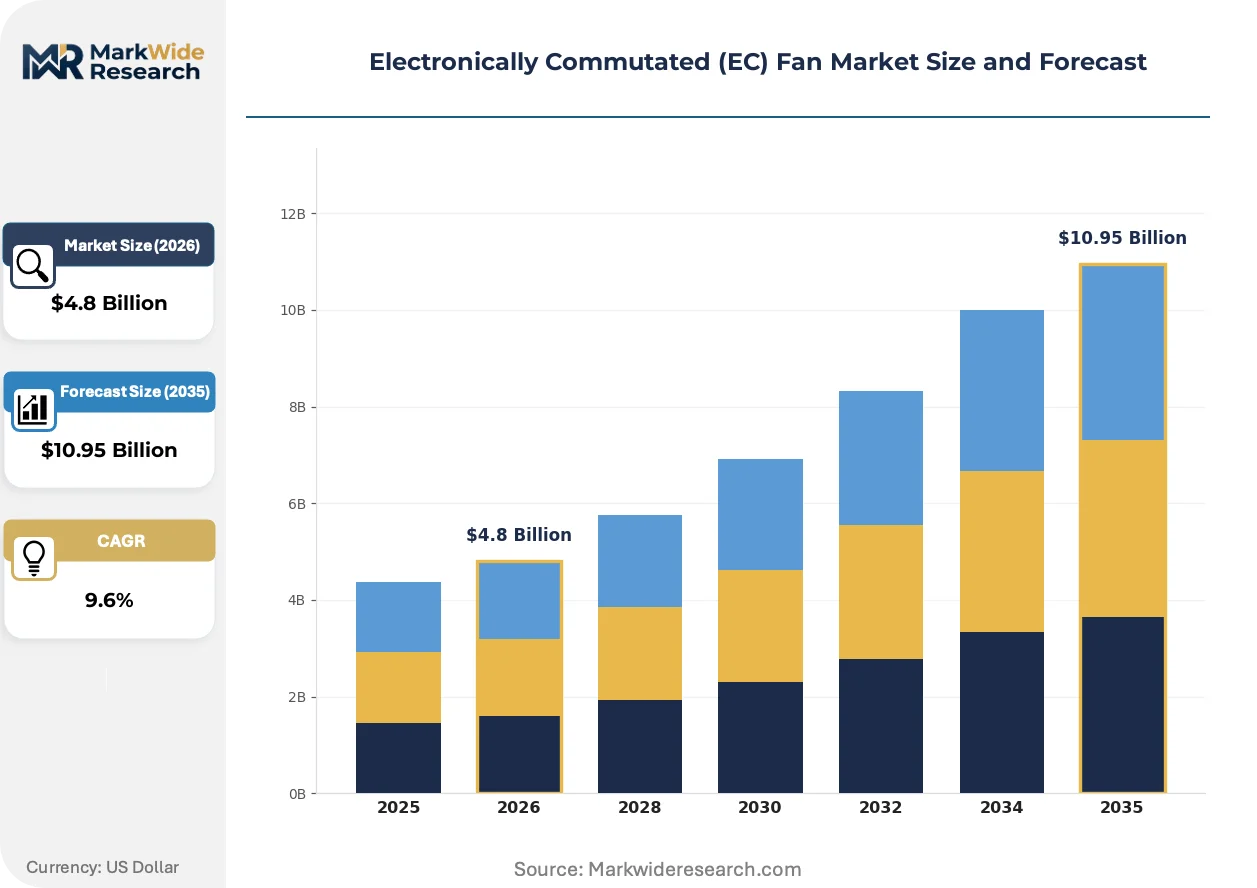
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Blower Fans, Mixed Flow Fans Application: Industrial Ventilation, Residential Cooling, HVAC Systems, Server Cooling Technology: Brushless DC, Permanent Magnet, Digital Control, Sensorless Technology End User: Manufacturing, Commercial Buildings, Data Centers, Transportation |
| Companies Covered | Greenheck Fan Corporation, Johnson Controls International Plc., ebm-papst Group, Continental Fan, Regal Rexnord Corporation, Nidec Corporation, Systemair AB, Soler & Palau, Delta Electronics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronically Commutated (EC) Fan Market Emerging Trajectories
Magnet material chemistry and commutation firmware are converging to collapse motor efficiency curves into narrower operational bands, squeezing competitive differentiation toward thermal management integration and predictive maintenance capabilities.
Sensorless field-oriented control is rendering obsolete Hall-effect position sensing in mid-range blower applications. Foodservice ventilation contractors are specifying these architectures for grease-laden environments where sensor contamination previously drove maintenance costs. The elimination of discrete position sensors is compressing BOM line items and shifting value capture toward magnet-grade optimization and control algorithm licensing.
The European Commission's F-Gas Regulation is accelerating refrigerant containment requirements that indirectly tighten fan efficiency specifications. Cold storage and commercial refrigeration OEMs must demonstrate lower energy consumption to offset higher-GWP refrigerant system costs. German and French cold-chain operators are consequently specifying EC motor arrays for evaporator and condenser duty cycles.
Specification authority is migrating from mechanical contractors toward controls integrators and energy service companies. Data center engineering firms in Ireland and Denmark are writing performance-based fan specifications that prioritize watt-per-CFM guarantees over brand loyalty. This disintermediation of traditional HVAC distribution is compressing channel margins and rewarding manufacturers with captive thermal modeling software and remote monitoring platforms.
Electronically Commutated (EC) Fan Market Segmentation
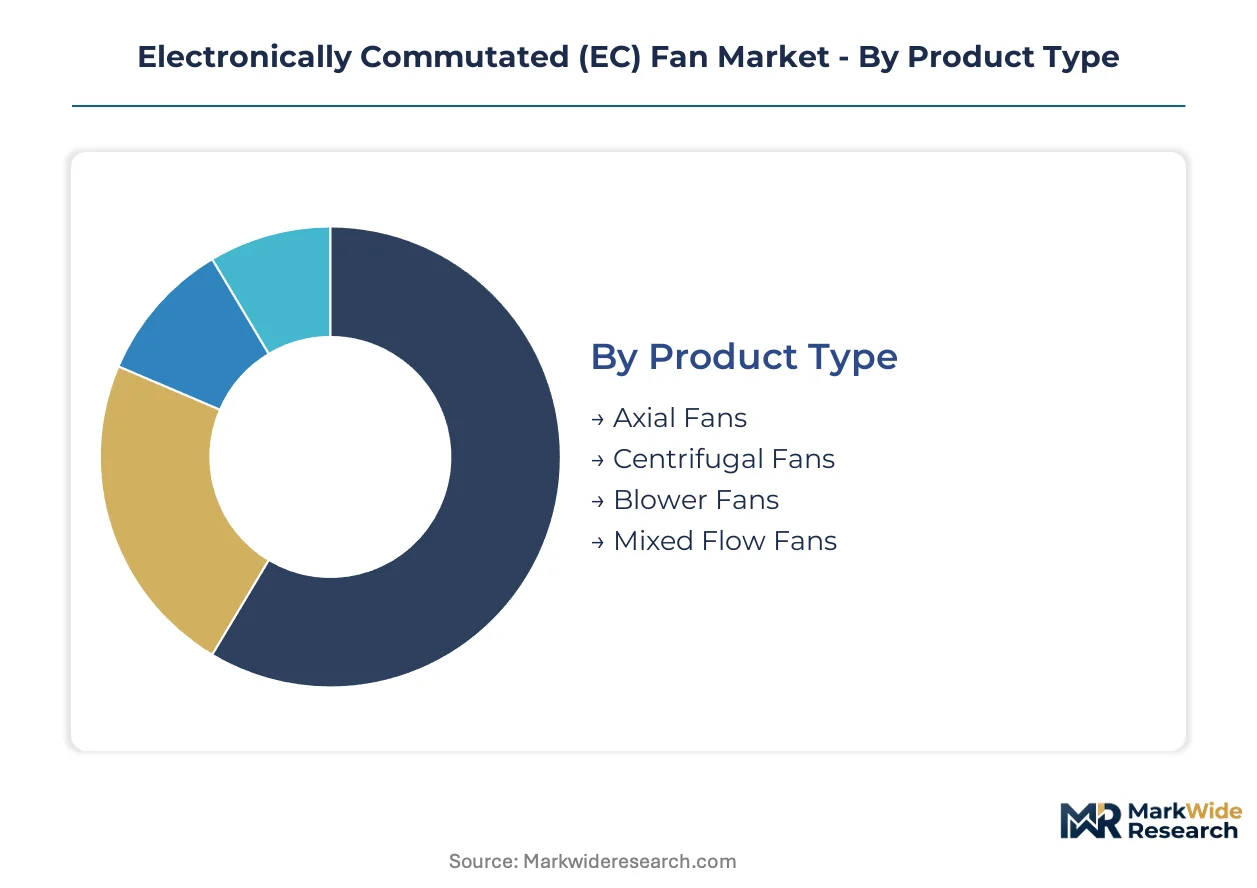
EC fan procurement patterns diverge sharply across application contexts, with data center operators demanding predictive maintenance integration while industrial buyers prioritize retrofit compatibility. Segment-specific service intensity shapes supplier margin structures and channel economics throughout the value chain.
Product Type:
After-sales service intensity varies dramatically by impeller architecture, with centrifugal arrays requiring specialized balancing and bearing replacement protocols that axial configurations rarely demand.
- Axial Fans:Propeller-style impellers move air parallel to the motor shaft, achieving high flow rates at low static pressure. Hyperscale data centers in Ireland and Denmark specify these for rack-level cooling where GPU density demands precise airflow modulation. Demand concentrates in server cooling contracts with performance-based watt-per-CFM guarantees.
- Centrifugal Fans:Forward-curved or backward-inclined blades accelerate air radially outward, generating substantial static pressure for ducted systems. German industrial HVAC retrofits drive sustained replacement volume for these configurations in manufacturing plant ventilation networks.
- Blower Fans:Compact scroll-housed designs deliver focused airflow for appliance and equipment integration. Foodservice ventilation contractors in France specify sensorless variants for grease-laden environments.
- Mixed Flow Fans:Hybrid impeller geometry combines axial throughput with centrifugal pressure capability. Emerging adoption in compact commercial rooftop units.
Centrifugal fans hold the largest share; momentum sits with axial configurations.
Application:
Cost tier stratification separates premium precision-cooling installations from commodity replacement cycles, with specification authority migrating toward controls integrators in high-value segments.
- Industrial Ventilation:Continuous-duty extraction and supply systems in manufacturing environments. Germany's facility modernization programs targeting climate targets create replacement volume for EC arrays in automotive and chemical processing plants.
- Residential Cooling:Heat pump air handlers and mechanical ventilation with heat recovery units. EU Ecodesign Directive efficiency mandates are accelerating EC penetration in new European housing stock.
- HVAC Systems:Commercial building climate control including air handling units and rooftop packages. EPA 10 CFR 431 standards in the United States compel facility managers to replace shaded-pole motors during routine upgrade cycles.
- Server Cooling:Precision thermal management for compute-intensive workloads. The Netherlands and Ireland host hyperscale operators specifying axial EC configurations for GPU-intensive AI training clusters.
HVAC Systems capture the largest installed base; Server Cooling climbs the fastest.
Technology:
Application maturity separates proven brushless architectures from emerging sensorless implementations that compress bill-of-material costs in price-sensitive blower segments.
- Brushless DC:Electronic commutation replaces mechanical brushes, eliminating wear components and enabling variable-speed operation. Dominates mid-range commercial and industrial applications with established reliability records.
- Permanent Magnet:Rare-earth rotor materials enable high torque density and efficiency above 90 percent. Neodymium supply concentration in China exposes manufacturers to quota volatility and price spikes.
- Digital Control:Embedded microcontrollers execute sinusoidal or trapezoidal drive algorithms. Firmware expertise scarcity competes with automotive and consumer electronics sectors for limited engineering talent pools.
- Sensorless Technology:Back-EMF detection eliminates Hall-effect position sensors, reducing maintenance costs in contaminated environments. Foodservice and agricultural ventilation contractors are migrating specifications toward these architectures.
Brushless DC retains the largest share; Sensorless Technology gains share fastest.
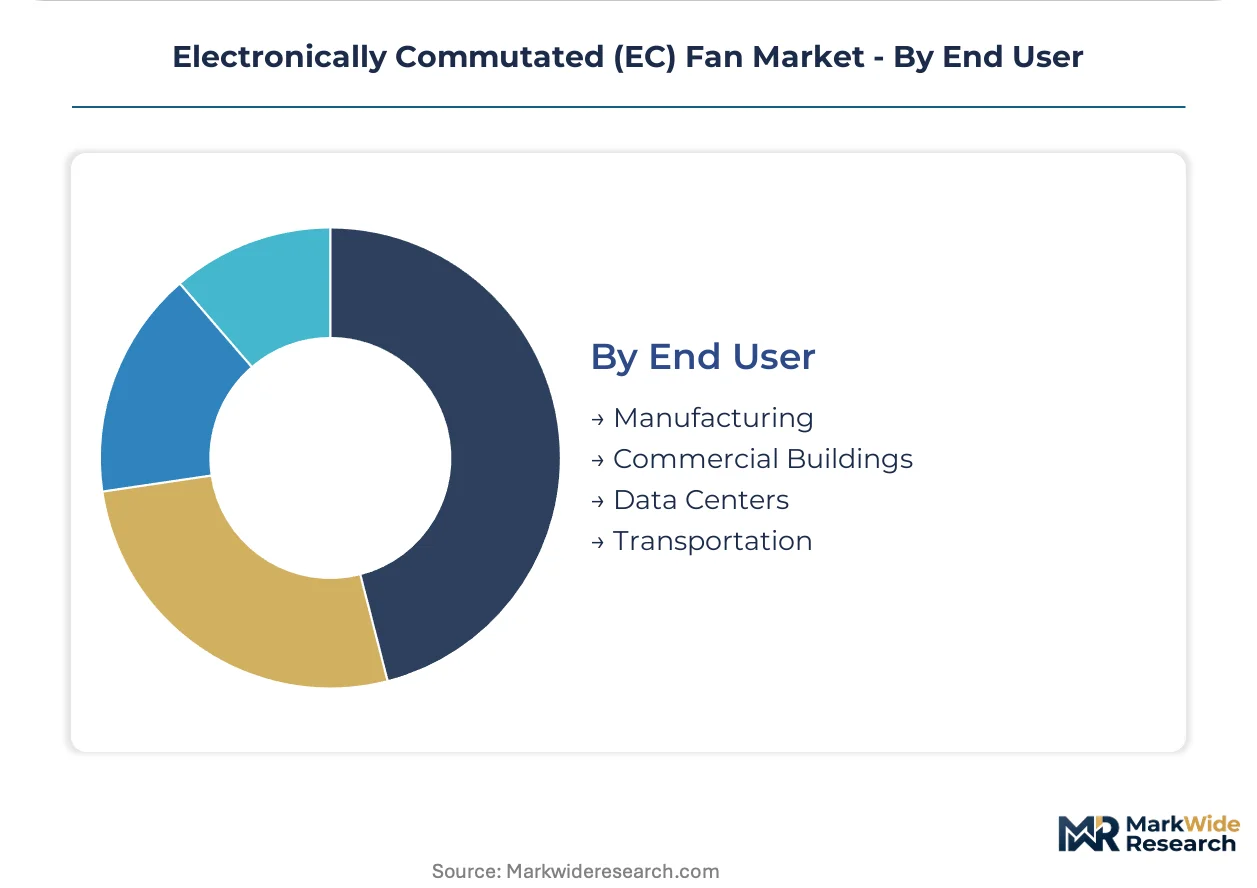
End User:
Customer type differentiation separates specification-driven data center engineering firms from price-sensitive commercial building operators with capital budget inertia.
- Manufacturing:Process ventilation, fume extraction, and environmental control in production facilities. German industrial retrofit programs prioritize centrifugal EC arrays for energy efficiency compliance.
- Commercial Buildings:Office, retail, and institutional climate control systems. Legacy building automation integration challenges require digital control interfaces bridging Modbus, BACnet, and proprietary protocols.
- Data Centers:Hyperscale and colocation facilities with rack-density thermal management requirements. Engineering firms in Denmark write performance-based specifications prioritizing watt-per-CFM guarantees over brand loyalty.
- Transportation:Rail HVAC, electric vehicle battery cooling, and auxiliary ventilation. Emerging demand from European rail fleet electrification programs.
Commercial Buildings represent the largest addressable base; Data Centers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA 10 CFR 431 efficiency standards in the United States and EU Ecodesign Directive mandates are accelerating replacement cycles across commercial HVAC infrastructure. Facility managers in Germany, the Netherlands, and Ireland are prioritizing EC fan arrays for data center precision cooling. China's GB motor efficiency standards create parallel compliance pressure on export-oriented manufacturing.
United States
Data center operators in Northern Virginia and Dallas-Fort Worth are expanding procurement of axial EC configurations for GPU-intensive AI workloads. The Department of Energy enforces minimum efficiency standards under 10 CFR 431, directly elevating EC motor penetration in commercial ventilation replacement cycles. Greenheck Fan Corporation leverages its captive fabrication network from Wisconsin to control lead times on custom centrifugal configurations serving industrial HVAC retrofits.
Germany
Industrial facility modernization programs targeting 2030 climate targets are creating sustained replacement volume for centrifugal EC arrays in automotive and chemical processing plants. The European Commission's Ecodesign Directive and associated Energy-related Products regulations mandate fan efficiency metrics that conventional AC induction designs fail to meet. Frankfurt and Munich host hyperscale data center construction driving specification of axial EC configurations for rack-density thermal management.
China
Domestic data center construction in Beijing-Tianjin-Hebei and Yangtze River Delta regions is absorbing EC fan volume for server cooling applications. GB standards on motor efficiency administered by the Standardization Administration impose compliance burdens on export-oriented production without harmonized protocols with Western test methods. Nidec Corporation and Delta Electronics anchor Asia-Pacific supply through in-house semiconductor and fan assembly capacity concentrated in manufacturing clusters.
Netherlands
Hyperscale operators in Amsterdam and Eindhoven are specifying axial EC configurations for precision cooling arrays serving AI training clusters. The EU F-Gas Regulation accelerates refrigerant containment requirements that indirectly tighten fan efficiency specifications for cold storage applications. Dutch engineering firms are writing performance-based fan specifications that prioritize watt-per-CFM guarantees over established brand relationships.
India
Commercial building construction in Mumbai and Bangalore is incorporating EC motor arrays for HVAC efficiency compliance in premium developments. The Bureau of Indian Standards and Central Electricity Authority are strengthening motor efficiency norms that favor electronically commutated architectures in new installations. Data center operators in Hyderabad and Chennai are migrating specifications toward EC fans as rack densities increase with cloud and AI workload expansion.
Electronically Commutated (EC) Fan Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated motor manufacturers and specialized fan fabricators with captive control firmware capabilities. Permanent-magnet rotor integration and embedded digital control are compressing motor architecture into single-source platforms, eliminating supplier fragmentation that characterized AC induction supply chains. Three archetypes dominate: European motor specialists with deep magnet-material integration, Asia-Pacific electronics conglomerates with semiconductor-to-system capabilities, and North American HVAC incumbents with distribution channel control. Competitive moves concentrate on strategic partnerships for magnet material security and capacity expansion for data center contract fulfillment.
Among European motor specialists, ebm-papst Group and Systemair AB exemplify the integrated-manufacturer archetype with deep manufacturing roots in Germany and Sweden respectively. Greenheck Fan Corporation represents the North American HVAC incumbent model with fabrication network control. Delta Electronics, Inc. anchors the Asia-Pacific electronics conglomerate pattern through captive semiconductor and fan assembly integration. These three occupy positions across distinct geographic and technological vectors without direct product-line overlap in core specifications.
| Leading Market Players |
|---|
| Greenheck Fan Corporation |
| Johnson Controls International Plc. |
| ebm-papst Group |
| Continental Fan |
| Regal Rexnord Corporation |
| Nidec Corporation |
| Systemair AB |
| Soler & Palau |
| Delta Electronics, Inc. |
| Others |
Supply Flow & Price Mechanics
Neodymium and dysprosium processing capacity clustering in China concentrates magnet material pricing power upstream, compressing motor manufacturer margins while shifting value capture toward embedded control firmware and thermal management integration downstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates data center precision-cooling contracts with performance guarantees from commodity HVAC replacement cycles. Price differentiation hinges on certification grade and volume scale, with hyperscale operators least sensitive and commercial building operators most reactive to capital budget constraints. Pricing pressure stems from rare-earth magnet cost volatility, forcing manufacturers to absorb input spikes or risk volume loss to AC induction residual base.
Supply Chain Analysis
Contract manufacturing concentration rests with Nidec Corporation and Delta Electronics in Asia-Pacific, plus ebm-papst Group's captive German fabrication. Raw material dependencies center on Chinese rare-earth processing, Taiwanese semiconductor foundries, and Japanese bearing supply. Single-source vulnerability in magnet chemistry exposes producers to export quota disruptions. Distribution runs through direct OEM procurement channels and specialized online platforms, bypassing traditional HVAC wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates durable defensive moats for established EC fan manufacturers, as EPA 10 CFR 431 and EU Ecodesign Directive compliance requirements raise qualification barriers that new entrants cannot easily replicate.
For Market Incumbents: Harden magnet material security through long-term offtake agreements with Chinese processors or alternative chemistry investments in heavy rare-earth-free formulations. Expand captive control firmware development capacity to offset commodity motor margin compression from AC induction residual competition. Certification investment in EU Ecodesign and EPA efficiency tiers reinforces specification authority against emerging Asian electronics conglomerates. For New Entrants and Emerging Players: Build out sensorless commutation expertise for cost-sensitive blower applications in foodservice and agricultural ventilation, where Hall-effect sensor contamination creates maintenance cost arbitrage. Target India's commercial building construction in Mumbai and Bangalore, where Bureau of Indian Standards efficiency norms favor EC architectures but incumbent presence remains thin. Partner with local HVAC contractors for specification influence in retrofit cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial HVAC specialists lacking captive motor manufacturing. Long-term viability favors platforms with integrated magnet sourcing and firmware control capabilities. Monitor neodymium export quota announcements from China's Ministry of Commerce as inflection indicator for margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Material Security Partnership | Long-term rare-earth offtake agreements with Chinese processors insulate against quota-driven cost spikes. |
| Sensorless Control Firmware Development | Elimination of Hall-effect sensors reduces BOM line items and maintenance costs in contaminated environments. |
| Direct OEM Procurement Channel Investment | Bypassing traditional wholesale distribution captures margin through captive specification relationships. |
| EU Ecodesign Certification Acceleration | Preemptive compliance with expanding Energy-related Products regulations mandates EC architecture adoption. |
| Data Center Thermal Management Integration | Predictive maintenance platforms and watt-per-CFM guarantees secure hyperscale contract renewals. |
Methodological Framework
Initial hypotheses were tested against primary input from data center engineering directors, HVAC procurement managers, motor manufacturer R&D leads, and foodservice ventilation contractors and refined through secondary validation against EPA 10 CFR 431 filings, EU Ecodesign Directive implementing measures, Chinese GB standard publications, and customs trade data for rare-earth magnet flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers produced convergent volume estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling impeller architecture, application context, technology maturity, and end-user type as core segmentation dimensions. CAGRs were derived from replacement cycle velocity and new installation penetration curves, with specific inputs including data center rack-density trajectories and industrial facility modernization program commitments in Germany.
Stress conditions across rare-earth export quota severity, AC induction residual base persistence, and firmware engineering talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of neodymium pricing indices, EPA enforcement actions, and hyperscale data center capex announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Electrical Fuses Market
Electrical Equipment
Medium Voltage Fuse Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
Global Dehumidifier Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Motor Protection Devices Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
North America Circuit Breakers Market