
 Magnetic Contactors Market | 2026-2036
Magnetic Contactors Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Contactors Market Analytics
Silver-cadmium oxide contact material is expanding its share as manufacturers phase out pure silver designs to reduce material cost volatility and improve arc resistance under frequent switching cycles. Eaton leverages backward integration into contact metallurgy to protect margin structures. Siemens anchors European demand through IEC-certified product families. Fuji Electric specializes in compact AC contactor architectures for Asian industrial OEMs.
A magnetic contactor is an electromechanical switching device that uses a magnetically operated coil to open or close power circuits, typically rated from 9 A to over 2,000 A with AC or DC control coils between 24 V and 600 V. Its primary purpose is to remotely control motor loads, heating systems, and capacitor banks while providing overload protection coordination. AC contactors occupy the largest volume share due to pervasive three-phase motor applications across factories and commercial buildings. DC contactors represent the fastest-expanding category as battery energy storage and electric vehicle charging infrastructure multiply high-voltage direct-current switching requirements. DIN rail mounted installation dominates retrofit and control panel builds where space density and service accessibility determine specification.
IEC 60947-4-1 governs contactor performance and endurance testing across European and Asian export markets, while UL 60947-4-1 shapes North American product certification and insurance liability. The EPA's emerging rules on electrical equipment lifecycle assessment are beginning to influence contactor material declarations and end-of-service recycling protocols. Stakeholders must monitor arc-quenching material restrictions and voltage class harmonization between IEC and NEMA frameworks to avoid stranded inventory in cross-border projects.
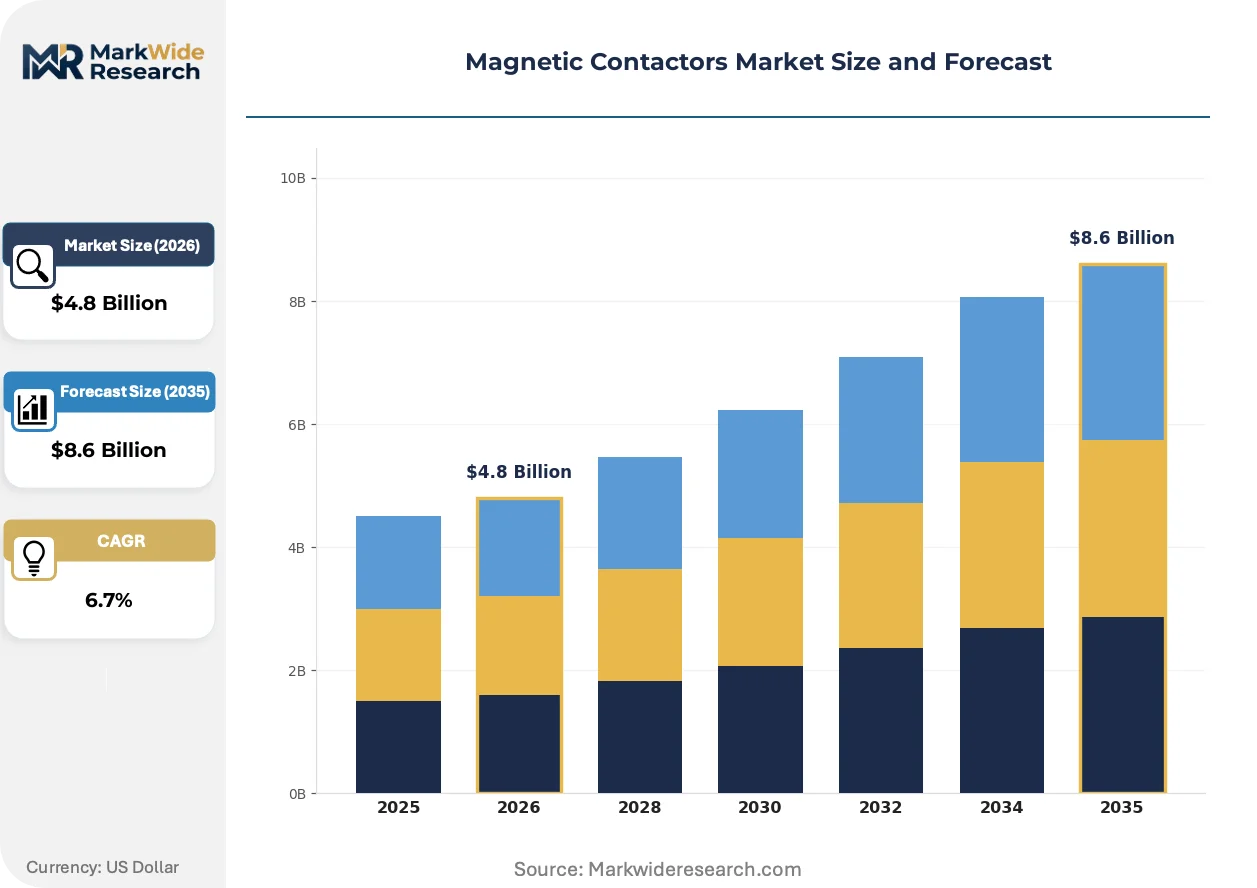
Market Dynamics
Electrification of industrial infrastructure is compressing replacement cycles for magnetic contactors as facilities upgrade motor control systems to meet stricter energy efficiency mandates and accommodate variable-frequency drive integration.
Growth Catalysts
- Data Center Electrification:Hyperscale facility construction in China, India, and Germany is accelerating procurement of high-amperage contactors for UPS and cooling redundancy systems.
- IEC 60947-4-1 Arc-Quenching Standards:Tighter endurance testing requirements are forcing facility upgrades across European and Asian export markets, stimulating replacement demand.
- Silver-Cadmium Oxide Metallurgy:Improved arc resistance under frequent switching cycles is extending contactor lifespan in stamping presses and robotic welding cells.
Market Restraints
- Silver Price Volatility:Contact material costs fluctuate with precious metal markets, compressing margins for manufacturers without backward integration into metallurgy.
- Supply Concentration in East Asia:Lamination steel and electromagnetic coil winding capacity clusters in China and South Korea, creating vulnerability to regional logistics disruptions.
- DC Contactor Technical Limitations:Arc interruption without natural current zero-crossing requires complex magnetic blowout designs that increase unit cost and maintenance complexity.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for domestic electrical equipment production are opening localized supply opportunities for IEC-certified product families.
- Battery Energy Storage Integration:Utility-scale BESS installations require high-voltage DC contactors for inverter isolation and fault protection.
- DIN Rail Retrofit Channel:Control panel builders are shifting from screw-terminal to snap-in mounting systems, favoring compact contactor architectures with tool-free installation.
Industry Challenges
- IEC-NEMA Certification Divergence:Voltage class and coil terminal configuration differences force manufacturers to maintain dual product lines, inflating inventory carrying costs.
- Legacy Motor Control Integration:Retrofitting smart contactors with predictive maintenance capabilities into existing MCC buckets requires custom adapter hardware and extended commissioning timelines.
- Arc-Quenching Material Compliance:EPA lifecycle assessment rules and emerging restrictions on cadmium content in electrical contacts are forcing reformulation of proven contact metallurgies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Contactors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Contactors, DC Contactors, Contactor Relays, Combination Starters End User: Industrial Sector, Commercial Sector, Residential Sector, Utility Providers Control Voltage: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage Installation Type: Panel Mounted, DIN Rail Mounted, Surface Mounted, Embedded |
| Companies Covered | Eaton, Fuji Electric, ABB, LS Electric, Mitsubishi Electric, Schneider Electric, Rockwell Automation, Hubbell Incorporated, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Contactors Market Evolving Landscape
Contactor architecture is fragmenting into application-specific platforms as end-users reject universal designs in favor of optimized footprints for renewable energy, data center, and electric vehicle charging deployments.
Hybrid AC/DC coil systems with universal voltage input ranges are modularizing control circuit design across multinational facilities. Facility managers in Germany and the United States are specifying these platforms to reduce spare parts inventory. This standardization is compressing procurement lead times and enabling centralized maintenance protocols.
REACH substance restrictions and RoHS recast directives are accelerating cadmium-free contact material development across European manufacturing. Suppliers are qualifying silver-tin oxide and silver-nickel alternatives for high-duty applications. Industrial OEMs in Germany and France are prioritizing CE-marked contactors with full material declarations to preempt supply chain audit requirements.
Buying committees are consolidating vendor relationships around integrated motor control platforms rather than discrete component sourcing. Distributors in China and India are responding with bundled stocking programs that combine contactors, overload relays, and communication modules. This concentration is most visible in automotive stamping and food processing verticals where line integration complexity favors single-source accountability.
Magnetic Contactors Market Segmentation
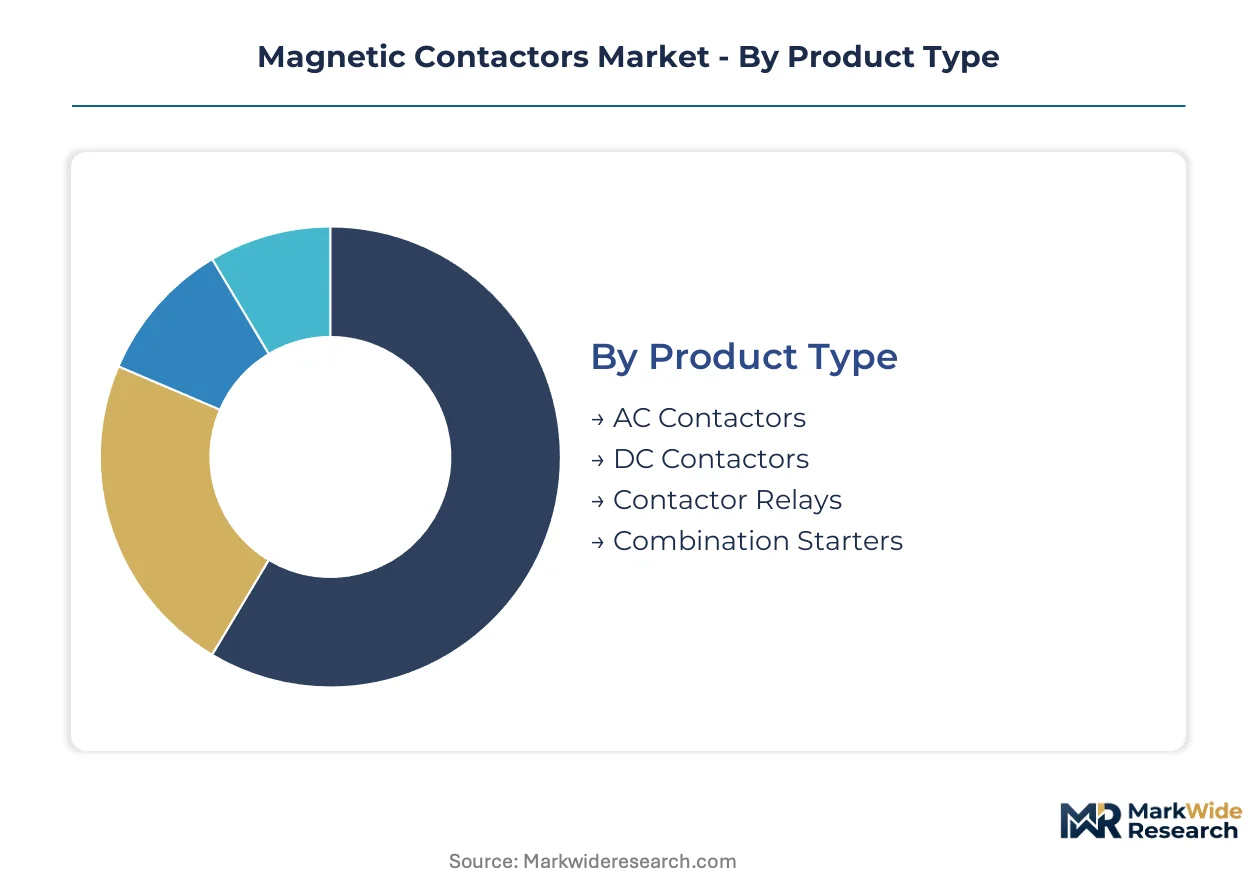
Magnetic contactor procurement splits sharply between high-volume standard configurations and premium engineered variants. Specification committees weigh arc-quenching performance against panel space constraints and maintenance accessibility. Each segmentation dimension carries distinct margin implications and competitive dynamics.
Product Type:
AC contactors dominate unit volumes through pervasive three-phase motor applications, while DC contactors command premium positioning in emerging electrification infrastructure.
- AC Contactors:Electromechanical switches rated 9 A to 2,000 A for three-phase motor control, heating systems, and capacitor banks. Demand concentrates in Chinese and German manufacturing facilities upgrading motor control centers to meet IEC 60947-4-1 efficiency mandates.
- DC Contactors:High-voltage direct-current switching devices with complex magnetic blowout designs for arc interruption without natural current zero-crossing. Battery energy storage installations in India and utility-scale solar farms in Germany are accelerating procurement of 1,500 V DC rated units.
- Contactor Relays:Auxiliary switching devices for control circuit logic and interlocking functions.
- Combination Starters:Integrated motor control units combining contactor, overload relay, and disconnect in single enclosures.
Today's leader: AC Contactors. Tomorrow's challenger: DC Contactors.
End User:
Industrial buyers prioritize endurance ratings and predictive maintenance integration, while commercial and residential segments emphasize compact footprints and contractor familiarity.
- Industrial Sector:Heavy-duty motor control in stamping presses, robotic welding cells, and material handling systems. Automotive OEMs in Germany and food processors in China are specifying silver-cadmium oxide contact materials for extended lifespan under frequent switching cycles.
- Commercial Sector:HVAC, elevator, and lighting control in office buildings and retail facilities. Specifiers in Indian metropolitan construction favor DIN rail mounted contactors for service accessibility in cramped electrical rooms.
- Residential Sector:Pool pumps, air conditioning compressors, and home automation integration.
- Utility Providers:Grid infrastructure switching, capacitor bank control, and distribution automation.
Industrial buyers absorb 60% of premium-tier contactor value despite representing narrower unit volumes than commercial procurement.
Control Voltage:
Voltage class selection tracks application safety requirements and coil thermal performance, with low voltage configurations serving retrofit markets and higher tiers addressing new infrastructure specifications.
- Low Voltage:Control coils from 24 V to 600 V AC/DC for standard industrial and commercial motor control. Panel builders across China and India stock 230 V and 400 V variants for compatibility with domestic distribution standards.
- Medium Voltage:1 kV to 36 kV switching for distribution feeders and substation equipment.
- High Voltage:Specialized contactors for transmission-level isolation and utility switching operations.
- Extra High Voltage:Ultra-high-voltage DC applications in long-distance transmission and grid-scale energy storage.
Low voltage contactors anchor replacement demand. Medium voltage configurations are climbing fastest through utility modernization programs.
Installation Type:
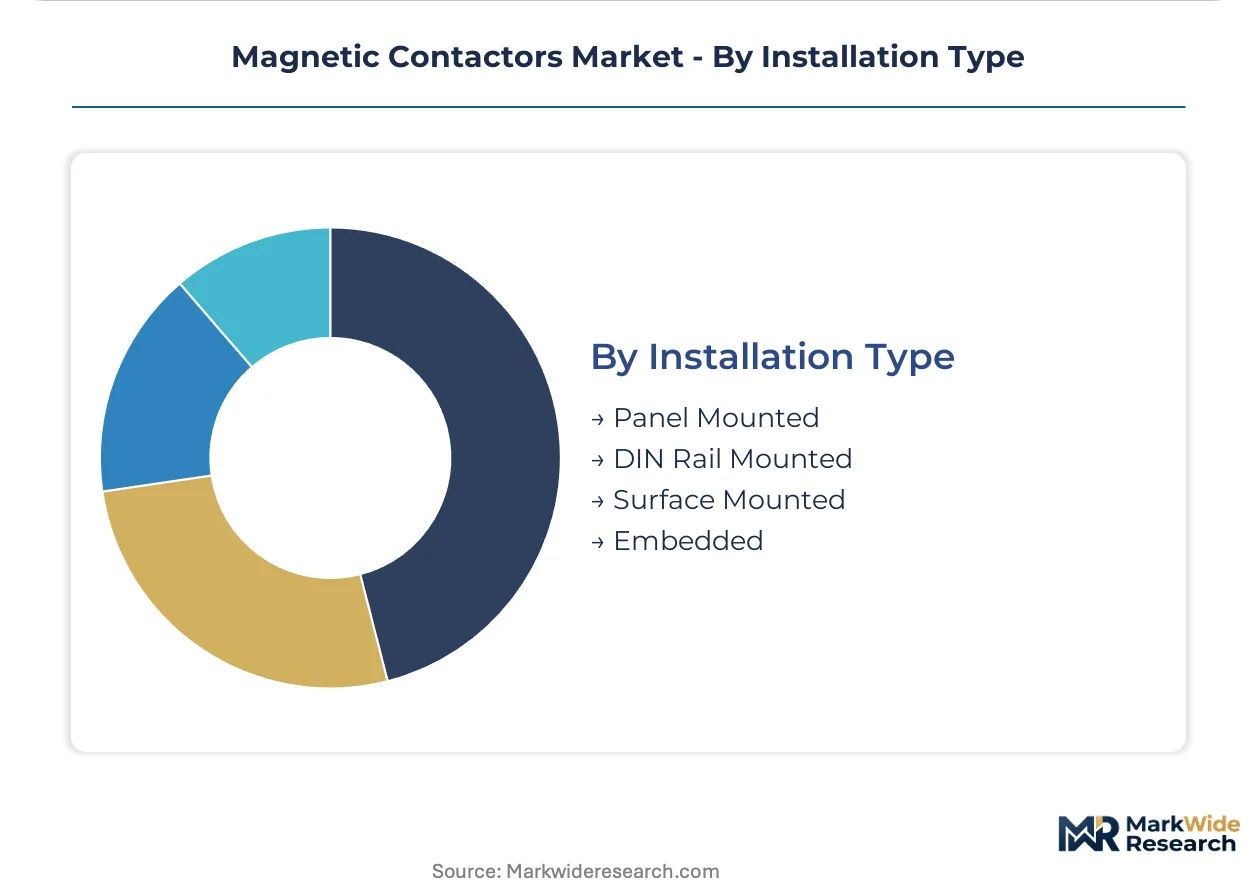
Mounting methodology determines labor cost, panel density, and service interval economics, with DIN rail systems displacing traditional panel mounted architectures in retrofit channels.
- Panel Mounted:Direct screw-terminal attachment to custom-fabricated backplanes in original equipment builds. German machine tool OEMs maintain this specification for vibration resistance in heavy manufacturing environments.
- DIN Rail Mounted:Snap-in installation on standardized 35 mm top-hat rails enabling tool-free replacement and space-efficient control panel layouts. Indian and Chinese control panel builders are converting entire product lines to DIN rail compatibility for maintenance accessibility.
- Surface Mounted:Direct wall or equipment mounting for standalone motor control applications.
- Embedded:Integration into packaged equipment such as HVAC units, compressors, and elevator controllers.
DIN rail architectures are displacing panel mounted alternatives in retrofit specifications across all three major demand clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing clusters anchor procurement volumes for IEC-certified contactor families serving automotive stamping and machine tool OEMs. Grid modernization programs and data center construction across China, India, and Germany are compressing replacement cycles and accelerating specification of high-amperage units.
China
Hyperscale data center construction in Beijing-Tianjin-Hebei and Yangtze River Delta clusters is driving procurement of 1,000 A+ contactors for UPS redundancy systems. MIIT efficiency mandates for industrial motor systems are forcing facility upgrades in Guangdong and Jiangsu provinces. Shenzhen and Shanghai panel builders are converting entire product lines to DIN rail architectures for maintenance accessibility.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify silver-cadmium oxide contact materials for robotic welding cells under frequent switching cycles. REACH substance restrictions are accelerating cadmium-free contact material qualification across European manufacturing. Siemens anchors demand through IEC-certified product families serving Stuttgart and Munich industrial zones.
India
PLI scheme incentives for domestic electrical equipment production are opening localized supply opportunities for IEC-certified contactor families. CEA grid modernization directives are stimulating utility-scale procurement across Maharashtra and Gujarat. Bangalore and Chennai control panel builders favor DIN rail mounted contactors for service accessibility in cramped electrical rooms.
United States
Variable-frequency drive integration in Midwest manufacturing is compressing replacement cycles for motor control center upgrades. EPA lifecycle assessment rules are beginning to influence contactor material declarations and end-of-service recycling protocols. Texas and California data center construction is accelerating procurement of high-amperage contactors for cooling redundancy systems.
South Korea
Battery energy storage installations in Gyeonggi-do and Chungcheong provinces are accelerating procurement of 1,500 V DC rated contactors for inverter isolation. METI-aligned efficiency standards for industrial equipment are shaping specification patterns among export-oriented manufacturers. Busan-Ulsan shipbuilding clusters are specifying marine-grade contactor architectures for propulsion motor control.
Magnetic Contactors Market Competitive Landscape
Global majors compete with regional champions across certification standards and metallurgy capabilities. The vendor base splits between consolidated multinational electrical equipment groups and specialized contactor fabricators with captive silver-alloy production. Three archetypes dominate: integrated motor control platform providers, backward-integrated metallurgy specialists, and compact architecture designers for Asian OEM channels. Competitive moves concentrate on M&A for contact material supply security and capacity expansion in Indian PLI-eligible manufacturing zones.
Within the integrated platform tier, Eaton and Siemens exemplify multinational scale with captive contact metallurgy and IEC-NEMA dual certification portfolios. Fuji Electric occupies a position among compact architecture specialists serving Asian industrial OEMs with space-optimized AC contactor designs. These three anchors represent distinct competitive vectors: backward integration into silver-cadmium oxide production, European anchor demand through IEC-certified families, and compact form factors for DIN rail density requirements.
| Leading Market Players |
|---|
| Eaton |
| Fuji Electric |
| ABB |
| LS Electric |
| Mitsubishi Electric |
| Schneider Electric |
| Rockwell Automation |
| Hubbell Incorporated |
| Siemens |
| Others |
Value Network & Pricing Analysis
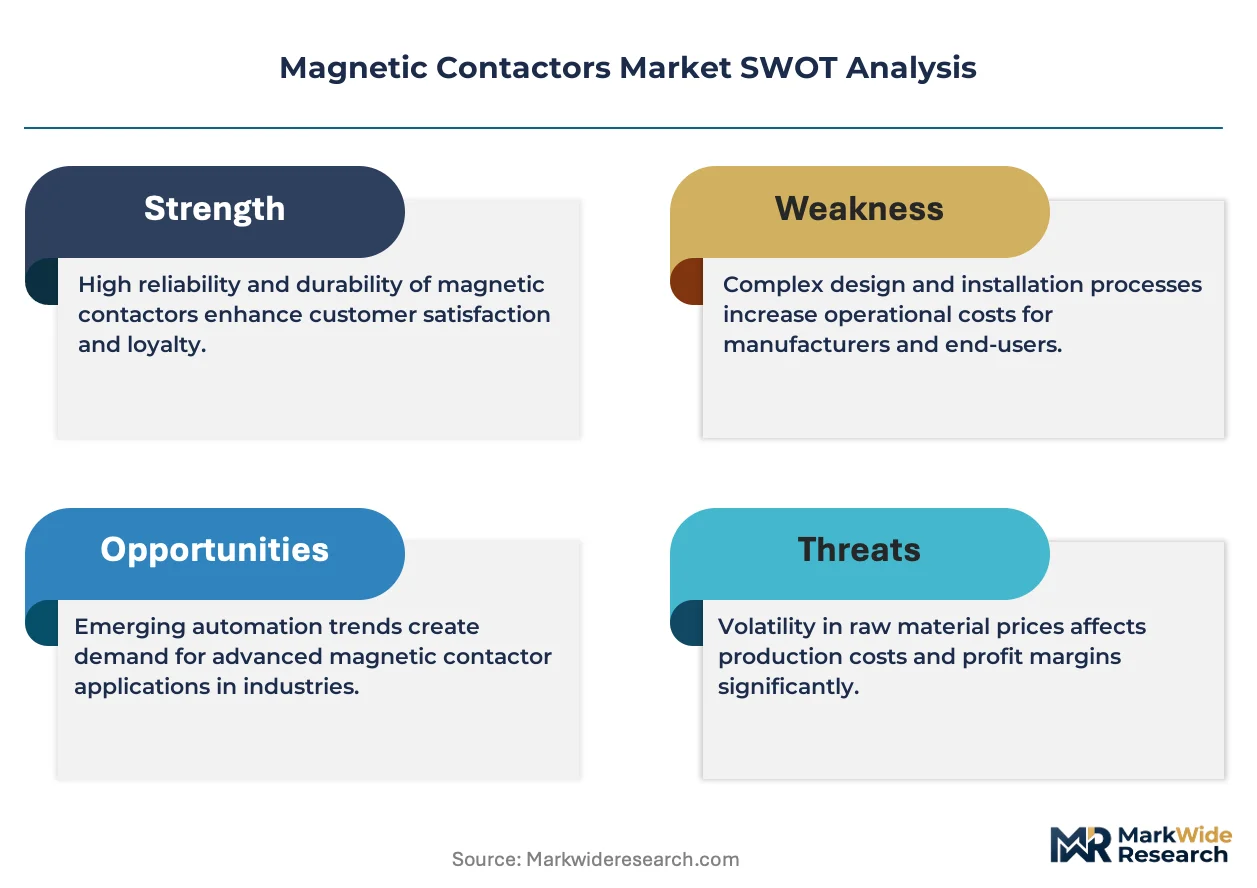
Backward integration into silver-cadmium oxide metallurgy anchors both supply security and pricing power for manufacturers like Eaton, insulating margin structures from precious metal volatility while locking in arc-quenching performance advantages. This captive production model creates tiered pricing separation between integrated majors and component-dependent fabricators.
Pricing Analysis
Input-cost pass-through from silver spot markets drives pricing volatility for contact material, compressing margins for manufacturers without captive metallurgy. Pricing stratifies across IEC-NEMA dual-certified premium tiers, single-standard economy lines, and application-specific engineered variants. Cost compression in standard AC contactor tiers is intensifying because Chinese panel builders are consolidating procurement around bundled motor control platforms. Commercial HVAC specifiers in India exhibit highest price sensitivity, while German automotive OEMs absorb premium positioning for robotic welding cell endurance ratings.
Supply Chain Analysis
Single-source vulnerability sits with lamination steel and electromagnetic coil winding capacity clustering in China and South Korea, exposing the ecosystem to regional logistics disruptions. Raw material dependencies draw from silver-alloy contact metallurgy, cold-rolled silicon steel for magnetic cores, and copper magnet wire for coil windings. Tariff exposure on Chinese electrical steel imports threatens cost structures for North American fabricators. Distribution runs through authorized electrical distributors in China and India, direct OEM supply agreements in Germany, and industrial MRO channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's PLI-subsidized manufacturing zones and China's established component clusters, exploiting the regulatory cost differential for IEC-certified production.
For Market Incumbents: Cement backward integration into contact metallurgy to defend against silver price volatility and emerging cadmium-free material mandates. Lock in DIN rail retrofit channel partnerships with Indian and Chinese panel builders before regional champions consolidate shelf space. Prioritize dual IEC-NEMA certification investment to capture cross-border infrastructure projects without stranded inventory.
For New Entrants and Emerging Players: Control panel builders in India's PLI-eligible zones represent the most penetrable channel partner type for localized IEC-certified supply. Target utility-scale battery energy storage DC contactor specifications in South Korea and Germany where technical barriers favor specialized engineering over scale economics. Pursue white-label manufacturing partnerships with established silver-alloy metallurgy suppliers to bypass capital-intensive foundry investment.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap contactor fabricators with captive silver-cadmium oxide production because REACH and EPA lifecycle rules are accelerating consolidation around compliant material platforms. Five-to-ten year viability hinges on cadmium-free metallurgy transition execution. Watch EPA contact material declaration enforcement timelines as the inflection signal for stranded inventory risk and acquisition discounting.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Metallurgy | Eaton's captive silver-cadmium oxide production insulates margins from precious metal spot volatility. |
| IEC-NEMA Dual Certification Investment | Siemens anchors cross-border project capture without dual product line inventory carrying costs. |
| PLI-Eligible Manufacturing Expansion | Localized Indian production opens supply opportunities for Maharashtra and Gujarat grid modernization. |
| DIN Rail Retrofit Channel Partnership | Snap-in mounting adoption by Shenzhen panel builders compresses procurement lead times. |
| Cadmium-Free Material Platform Development | Silver-tin oxide qualification preempts REACH substance restriction supply chain audit requirements. |
Research Methodology
Direct dialogue with plant engineers, OEM procurement teams, electrical distributor category managers, and aftermarket service heads grounded qualitative findings in operational reality. Secondary validation drew from IEC 60947-4-1 certification registries, customs trade data for lamination steel and silver alloy flows, SEC filings of listed electrical equipment groups, and utility procurement databases for grid modernization contracts. Bottom-up unit demand modeling triangulated against top-down market sizing across product type, end user, control voltage, and installation type segmentation dimensions.
Market value and volume trajectories emerged from integrating macroeconomic drivers, regulatory compliance timelines, and technology substitution patterns across the projection horizon. Segmentation modeling captured AC versus DC contactor splits, industrial-commercial-residential end-use distribution, low-medium-high voltage class evolution, and DIN rail versus panel mounted installation shifts. CAGRs derived from fitted growth curves applied to base-year sizing, with sensitivity testing around silver price scenarios and PLI scheme uptake rates in India.
Revisions become necessary when EPA lifecycle assessment enforcement intensifies, REACH cadmium restrictions expand, or China-South Korea steel supply disruptions materialize. Forecasts embed assumptions about IEC-NEMA harmonization progress and data center construction cadence in Beijing-Tianjin-Hebei and Frankfurt-Rhine-Main clusters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Current Clamps Market
Electrical Equipment
Busbar Systems Market
Electrical Equipment
US Electric Enclosure Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Electrical Resistor Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
Axial Fans Market
Electrical Equipment
Electrical Fuses Market