
 Tunnel Sensor Market | 2026-2036
Tunnel Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Tunnel Sensor Market Analysis
EU F-Gas Regulation is decoupling refrigerant-based sensor cooling from cost-efficient tunnel monitoring designs, forcing vendors to reengineer thermal management architectures. SICK AG leverages its optical sensing heritage to dominate high-precision smoke detection for road tunnel installations. DURAG GROUP anchors European market presence through particulate measurement specialization aligned with EN 50545 compliance requirements. Trolex Ltd competes in mining-adjacent tunnel segments where explosive atmosphere certification creates distinct qualification barriers.
A tunnel sensor constitutes an electromechanical or photonic device engineered to detect environmental parameters including temperature, pressure, particulate concentration, or structural vibration within enclosed subterranean passages, typically operating across temperature ranges from minus twenty to plus sixty degrees Celsius with ingress protection ratings of IP65 or higher. Its primary commercial purpose is to enable automated safety responses and ventilation control in transportation and utility infrastructure where human exposure risks escalate rapidly. Smoke detectors command the largest product-type revenue pool due to mandatory installation density requirements under fire safety codes, while vibration sensors represent the fastest-expanding category as structural health monitoring extends from railway tunnels into aging road tunnel portfolios. IoT-enabled sensors concentrate margin expansion potential by replacing periodic manual calibration with continuous remote diagnostics, though wired sensors sustain volume dominance where electromagnetic interference from traction systems degrades wireless reliability.
The European Committee for Standardization maintains EN 50545 as the definitive gas detection framework for road tunnels, while the US DOT Federal Highway Administration prescribes National Tunnel Inspection Standards that mandate periodic sensor functionality verification. China's MIIT enforces GB standards for urban utility tunnel monitoring that diverge materially from European electromagnetic compatibility thresholds, fragmenting certification pathways for multinational suppliers. Stakeholders must calibrate R&D roadmaps against which regulatory jurisdiction will tighten emission or safety thresholds first, as divergent standard evolution risks stranding development investments in non-compliant architectures.
Market Dynamics
EU F-Gas Regulation is decoupling refrigerant-based sensor cooling from cost-efficient tunnel monitoring designs, forcing vendors to reengineer thermal management architectures around solid-state alternatives. This regulatory pressure cascades through procurement specifications across German federal tunnel renovation programs and Swiss alpine corridor upgrades.
Growth Catalysts
- EN 50545 compliance mandates:European road tunnel operators must replace legacy gas detection hardware with certified multi-sensor networks, accelerating replacement cycles for installations exceeding fifteen years of service.
- Structural health monitoring extension:Railway asset managers in Austria and Italy are deploying vibration sensors beyond tracks into tunnel linings, expanding addressable hardware volumes for predictive maintenance contracts.
- IoT-enabled remote diagnostics:Cellular-connected sensor nodes eliminate manual calibration labor, allowing transportation authorities to redeploy maintenance crews toward critical infrastructure repairs.
Market Restraints
- Electromagnetic interference from traction systems:Wireless sensor reliability degrades in electrified railway tunnels, forcing continued dependence on costly wired installations with specialized shielding.
- Input cost volatility in optical components:Precision photodiodes and laser diodes for smoke detection face supply concentration among East Asian foundries, exposing European integrators to currency and logistics risk.
- Certification pathway fragmentation:China's GB standards for urban utility tunnels diverge materially from European electromagnetic compatibility thresholds, requiring parallel development tracks for multinational suppliers.
Strategic Opportunities
- Norwegian subsea tunnel expansion:The country's fjord-crossing infrastructure program creates demand for corrosion-resistant pressure and gas sensors operating in high-humidity, saline environments.
- AI-driven predictive ventilation:Machine learning algorithms processing real-time particulate and traffic flow data enable dynamic airflow optimization, reducing energy consumption in Swiss and Austrian alpine tunnels.
- Utility tunnel convergence:District heating and fiber optic corridors in Danish and Swedish cities require integrated environmental monitoring, opening adjacent application spaces beyond transportation.
Industry Challenges
- Specialized calibration technician scarcity:EN 50545 certification requires personnel trained on multi-gas reference standards, creating recruitment bottlenecks for maintenance contractors across Central Europe.
- Legacy system integration complexity:Analog-era ventilation control systems in older Italian and French tunnels resist digital sensor interface protocols, demanding costly middleware development.
- IP disputes over optical scattering algorithms:Patent thickets around laser-based particulate measurement are triggering licensing negotiations between component suppliers and system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunnel Sensor Market |
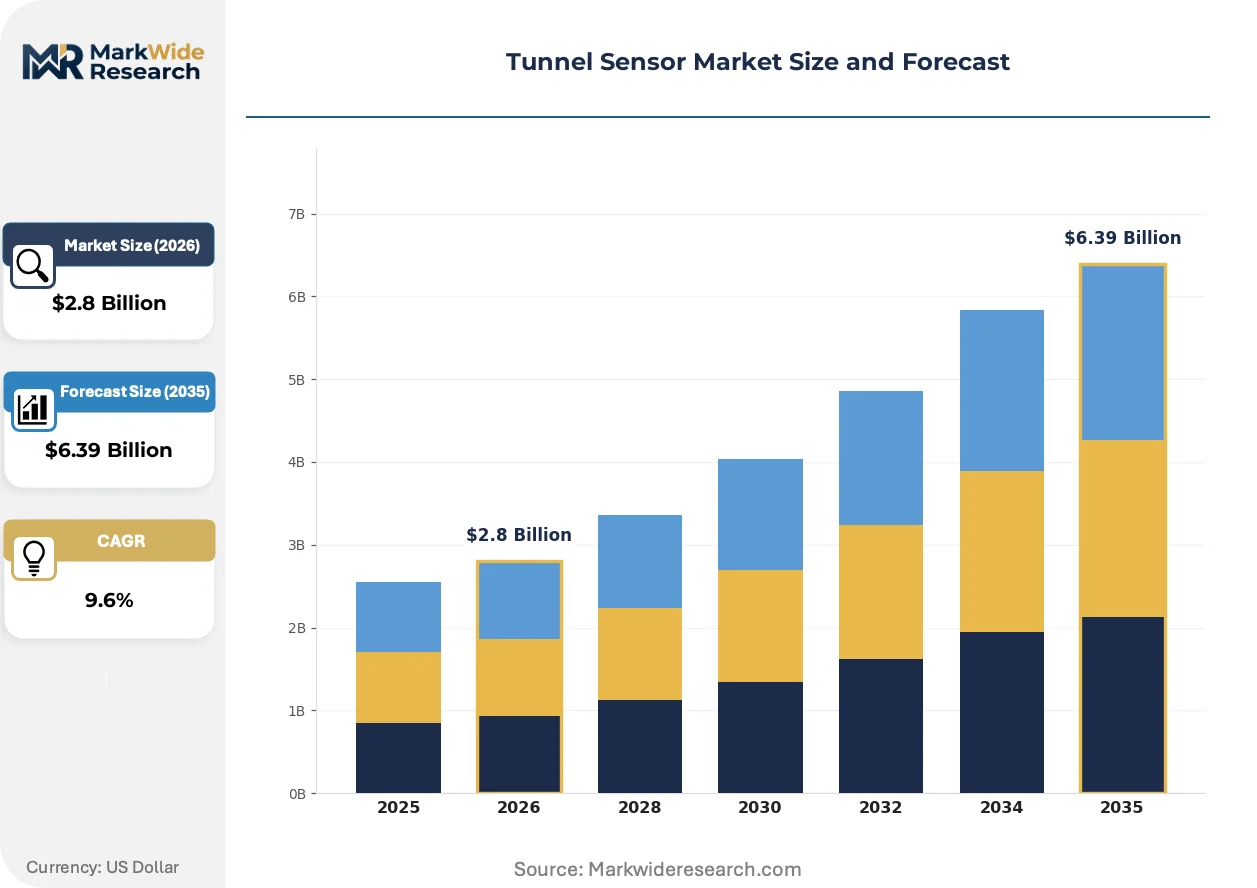
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Smoke Detectors, Vibration Sensors End User: Transportation Authorities, Mining Companies, Infrastructure Developers, Public Safety Agencies Technology: Wireless Sensors, Wired Sensors, IoT-enabled Sensors, Smart Sensors Application: Aviation Tunnels, Road Tunnels, Railway Tunnels, Utility Tunnels |
| Companies Covered | DURAG GROUP, Geonica, SICK AG, Advance Technologies Asia, Acoem, Tunnel Sensors Ltd, Altech Corporation, Trolex Ltd, CODEL International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunnel Sensor Market Emerging Trajectories
Photonic sensing architectures and edge-computing analytics are actively displacing electromechanical detector designs across European tunnel portfolios. These shifts compress response latency while expanding parameter detection breadth beyond traditional smoke and gas thresholds.
Silicon photonics is rewriting smoke detection economics by integrating laser sources, waveguides, and detectors onto single chips. German tunnel operators are piloting these solid-state replacements for legacy ionization chambers in high-traffic corridors. The technology is compressing unit costs and eliminating radioactive material handling compliance entirely.
EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in cooled infrared detectors, compelling sensor vendors to adopt thermoelectric or uncooled alternatives. This industrial consequence elevates power consumption trade-offs against detection sensitivity in alpine tunnel designs. Road tunnel segments with moderate traffic density are accepting performance compromises to maintain regulatory compliance timelines.
Swiss and Austrian transportation authorities are unbundling sensor hardware from long-term service contracts, shifting procurement toward performance-based availability agreements. System integrators must now price remote diagnostics, calibration labor, and replacement parts across extended tenures rather than upfront equipment sales. This behavior change concentrates margin pressure on vendors lacking established service networks in Alpine regions.
Tunnel Sensor Market Segmentation
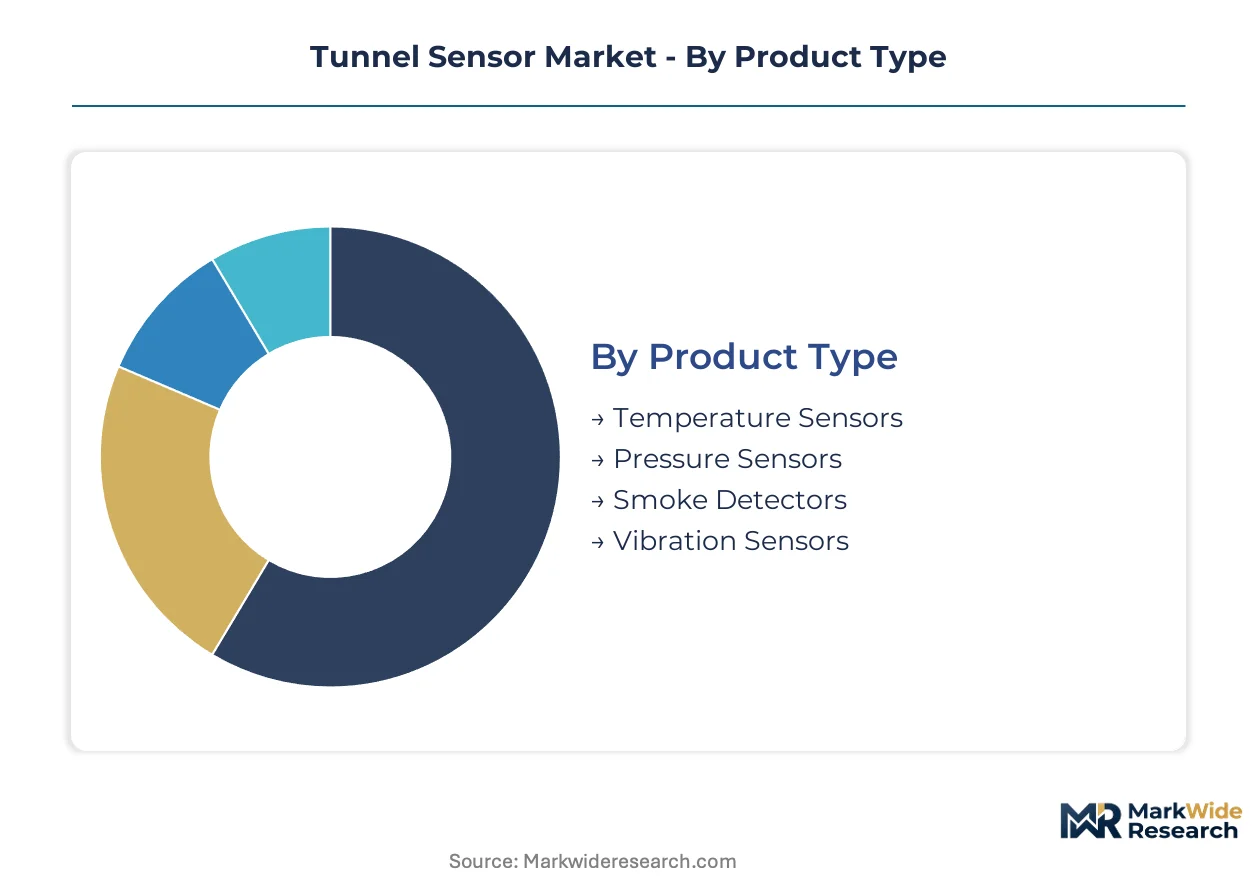
Segmentation in the tunnel sensor market determines procurement specifications, certification pathways, and integration complexity for transportation authorities and infrastructure developers. Product type dictates hardware replacement cycles and regulatory compliance burdens, while technology selection constrains deployment feasibility in electrified or subterranean environments.
Product Type:
Standalone detectors dominate road tunnel installations where regulatory mandates specify discrete device density, while embedded multi-parameter arrays gain traction in railway structural health monitoring.
- Smoke Detectors:Optical and ionization-based devices detect combustion particulates across temperature ranges from minus twenty to plus sixty degrees Celsius. German federal tunnel renovation programs mandate installation densities that sustain the largest revenue pool in this category, though EN 50545 compliance is accelerating replacement of legacy ionization chambers.
- Vibration Sensors:Piezoelectric and MEMS-based accelerometers measure structural resonance and crack propagation in tunnel linings. Austrian and Italian railway asset managers are deploying these beyond track beds into concrete segments, driving the steepest expansion trajectory as predictive maintenance contracts proliferate.
- Temperature Sensors:Thermocouple and resistance-temperature-detector elements monitor fire risk and ventilation thermal loads.
- Pressure Sensors:Piezoresistive and capacitive transducers track barometric differentials for ventilation control and flood detection.
Volume placements concentrate in smoke detectors; the faster expansion belongs to vibration sensors.
End User:
Cost tier differentiation separates centralized procurement by national agencies from fragmented purchasing by private mining operators and municipal utilities.
- Transportation Authorities:Federal and state road agencies issue multi-year framework agreements specifying EN 50545-certified networks with remote diagnostics integration. Swiss and Austrian authorities are unbundling hardware from long-term service contracts, shifting toward performance-based availability agreements that concentrate margin pressure on vendors lacking Alpine service networks.
- Mining Companies:Underground operators require explosive atmosphere certification under ATEX directives, creating distinct qualification barriers that limit vendor pools. Trolex Ltd anchors market presence in this segment through mining-adjacent tunnel applications where methane and coal dust hazards dominate specification requirements.
- Infrastructure Developers:Private concessionaires and public-private partnerships procure integrated environmental monitoring for new-build tunnel projects.
- Public Safety Agencies:Fire departments and emergency management authorities influence specification standards without direct procurement authority.
Transportation authorities command the highest absolute volumes; mining companies generate premium pricing through hazardous environment certification requirements.
Technology:
Application environment dictates connectivity architecture, with electromagnetic interference from traction systems degrading wireless reliability in electrified railway corridors.
- Wired Sensors:Shielded copper and fiber-optic connections deliver deterministic latency in high-interference environments. Electrified railway tunnels in Italy and France sustain dependence on these installations despite higher cabling costs, as electromagnetic compatibility thresholds under EN 50121 preclude wireless alternatives near traction power systems.
- IoT-enabled Sensors:Cellular and mesh-networked nodes transmit continuous diagnostic data to cloud analytics platforms. Transportation authorities in Germany and Switzerland are deploying these to eliminate manual calibration labor, redeploying maintenance crews toward critical infrastructure repairs while accepting subscription-based operational expenditure models.
- Wireless Sensors:Battery-powered and energy-harvesting devices suit low-density deployments in utility tunnels with minimal electromagnetic interference.
- Smart Sensors:Edge-computing architectures embed AI inference for localized anomaly detection and ventilation control decisions.
Wired sensors sustain volume dominance in railway applications; IoT-enabled architectures are climbing the fastest in road tunnel portfolios with reliable cellular coverage.
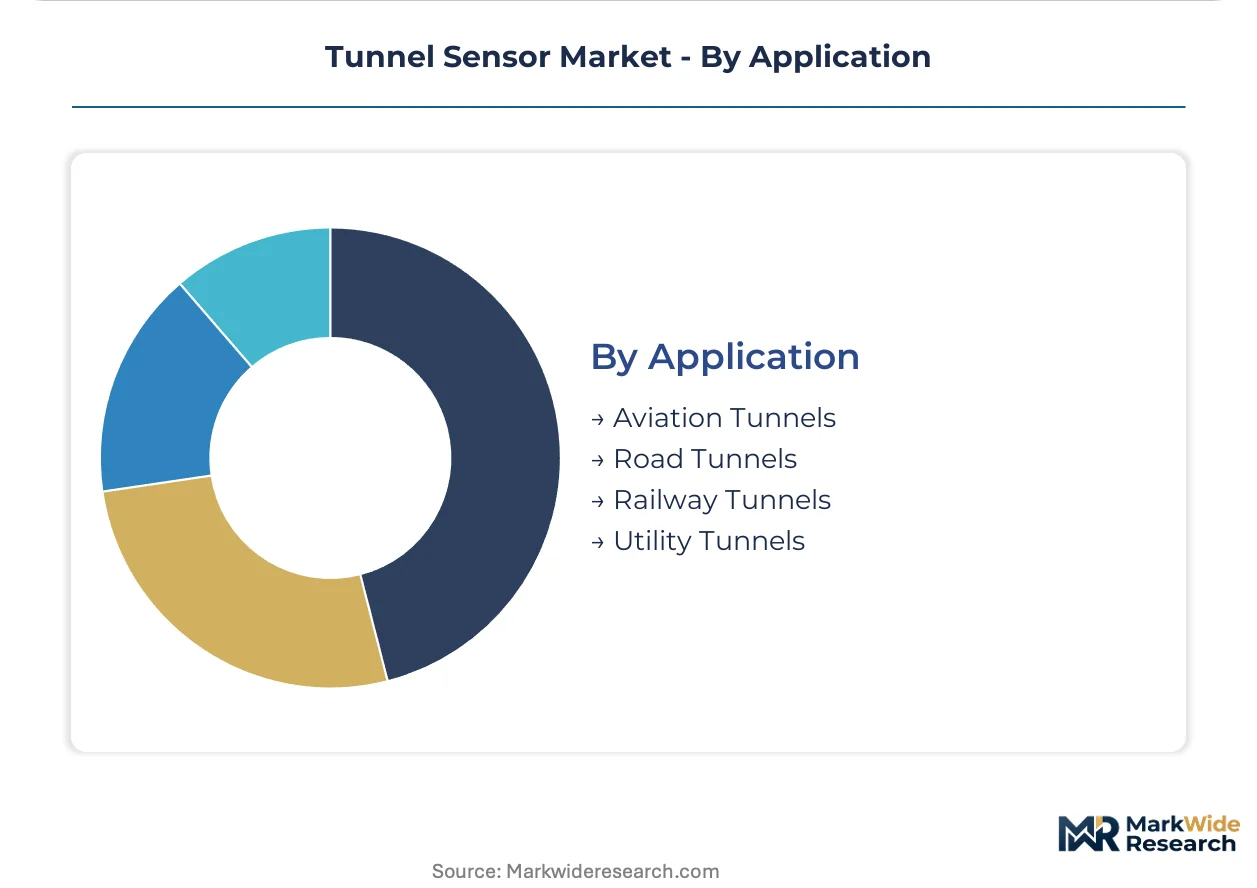
Application:
Geographic and structural constraints fragment specification requirements, with alpine corridors demanding corrosion resistance and subsea tunnels requiring pressure-rated housings.
- Road Tunnels:Vehicular emissions monitoring and fire safety systems drive sensor density requirements under national building codes. German federal programs prioritize integrated environmental sensing networks in renovation portfolios, while Norwegian subsea tunnel expansion creates demand for corrosion-resistant pressure and gas sensors in high-humidity saline environments.
- Railway Tunnels:Structural health monitoring and traction power interference mitigation define technology selection. Austrian and Italian asset managers are extending vibration sensor deployments from tracks into tunnel linings, expanding predictive maintenance contract volumes for integrated system providers.
- Utility Tunnels:District heating and fiber optic corridors require temperature and humidity monitoring without combustion detection mandates.
- Aviation Tunnels:Airport subterranean roadways and automated people mover tunnels follow modified fire safety protocols.
Deployment volumes concentrate in road tunnels; railway tunnels are gaining share fastest through structural health monitoring extension.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Alpenrhein Valley Economic Region spanning Vorarlberg and eastern Switzerland concentrates tunnel sensor procurement through coordinated cross-border infrastructure planning and joint safety standard harmonization.
Germany
Federal tunnel renovation programs prioritize integrated environmental sensing networks across the Rhine-Main corridor. EN 50545 compliance mandates from the European Committee for Standardization accelerate replacement cycles for legacy gas detection hardware exceeding fifteen years of service. Bavarian alpine tunnels near Garmisch-Partenkirchen deploy corrosion-resistant pressure sensors for high-humidity saline conditions.
Switzerland
Gotthard Base Tunnel operators unbundle sensor hardware from long-term service contracts, shifting procurement toward performance-based availability agreements. Swiss Federal Roads Office specifications under FEDRO mandate remote diagnostics integration for all new tunnel installations. Alpine corridor upgrades around the Lötschberg Base Tunnel drive demand for solid-state thermal management architectures compliant with EU F-Gas Regulation.
Austria
Railway asset managers extend vibration sensor deployments from track beds into tunnel linings along the Brenner Base Tunnel route. ÖBB-Infrastruktur AG procurement frameworks specify predictive maintenance contracts with integrated structural health monitoring. Tyrolean road tunnels near Innsbruck pilot AI-driven ventilation optimization processing real-time particulate and traffic flow data.
Norway
Subsea tunnel expansion across fjord-crossing infrastructure creates demand for corrosion-resistant pressure and gas sensors operating in high-humidity saline environments. Norwegian Public Roads Administration procurement prioritizes IP67-rated housings for Rogaland corridor projects. Tromsø region tunnel networks test thermoelectric alternatives to refrigerant-based cooling systems.
Italy
Legacy analog-era ventilation control systems in Apennine tunnels resist digital sensor interface protocols, demanding costly middleware development for EN 50545 compliance. Autostrade per l'Italia framework agreements specify multi-sensor networks with cellular-connected diagnostic nodes. Alpine tunnels near the Frejus Tunnel approach deploy specialized shielding for electromagnetic compatibility near traction power systems.
Tunnel Sensor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-dependent procurement channels. The vendor base stratifies into three tiers: optical sensing heritage firms commanding premium positioning in smoke detection, particulate measurement specialists anchoring compliance-driven replacement cycles, and mining-adjacent operators exploiting hazardous atmosphere certification barriers. Market concentration remains moderate with regional procurement fragmentation preventing dominant share accumulation. Competitive dynamics center on technology licensing for solid-state thermal architectures and strategic partnerships for Alpine service network coverage.
Among German-origin precision engineering firms, SICK AG exemplifies the optical sensing heritage archetype through its positioning in high-precision detection applications. DURAG GROUP occupies a position within the particulate measurement specialization tier, reflecting its alignment with European environmental compliance frameworks. Trolex Ltd represents the mining-adjacent tunnel segment archetype, leveraging explosive atmosphere certification requirements that create distinct qualification barriers limiting vendor pools. These three anchors illustrate how regulatory compliance pathways shape competitive positioning more than scale economies alone.
| Leading Market Players |
|---|
| DURAG GROUP |
| Geonica |
| SICK AG |
| Advance Technologies Asia |
| Acoem |
| Tunnel Sensors Ltd |
| Altech Corporation |
| Trolex Ltd |
| CODEL International Ltd |
| Others |
Supply Flow & Price Mechanics
Transportation authorities in Germany and Switzerland concentrate procurement through multi-year framework agreements, binding pricing to performance-based availability models rather than discrete equipment transactions. This buyer concentration compresses margins for vendors lacking established service networks while elevating premium capture for integrators offering bundled calibration and remote diagnostics.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with Swiss Federal Roads Office contracts penalizing delays in alpine corridor deployments. Pricing stratifies across EN 50545 certification tiers, silicon photonics integration levels, and after-sales service bundling. Cost compression in standard-grade smoke detection intensifies as German federal programs consolidate volumes, while mining-certified sensors under ATEX directives sustain premium positioning due to scarce qualified suppliers.
Supply Chain Analysis
Domestic-content mandates under EU public procurement directives reshape sourcing toward European component suppliers, displacing East Asian photodiode dependencies where feasible. Precision laser diodes and MEMS accelerometers draw from German, Japanese, and South Korean manufacturing clusters. Single-source vulnerability concentrates in cooled infrared detector substrates, with F-Gas Regulation accelerating thermoelectric alternative qualification. Distribution runs through specialized system integrators holding regional service certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into solid-state thermal management and edge-computing architectures, as vendors race to control component costs and differentiate on AI-driven predictive maintenance capabilities.
For Market Incumbents: Cement dominance in EN 50545-certified networks by acquiring regional calibration service providers in Alpine corridors, neutralizing the threat from mining-adjacent specialists expanding into hazardous atmosphere road tunnels. Deepen upstream control over silicon photonics foundry capacity to defend margin position against optical component price volatility. For New Entrants and Emerging Players: Municipal utility tunnel operators in Danish and Swedish district heating corridors represent the most penetrable buyer archetype, with fragmented procurement and minimal explosive atmosphere certification barriers. Pursue white-label partnerships with established Alpine service networks to bypass direct certification investments, targeting predictive maintenance contracts for aging Italian ventilation control retrofits. For Investors and Strategic Acquirers: The window for entry favors mid-cap sensor specialists with mining heritage and transferable ATEX certification infrastructure. Long-term viability hinges on regulatory tightening in subsea tunnel safety standards across Norwegian fjord infrastructure. Watch for AI-driven ventilation optimization pilot outcomes in Tyrolean road tunnels as the inflection signal for predictive analytics platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Photonics | Compresses unit costs for smoke detection while eliminating radioactive material handling compliance under German federal mandates. |
| Acquisition of Alpine Service Networks | Secures performance-based contract eligibility under Swiss FEDRO unbundling procurement frameworks. |
| AI-Driven Predictive Maintenance Platform | Enables dynamic ventilation optimization processing real-time particulate data from Austrian Brenner Base Tunnel deployments. |
| ATEX Certification Expansion | Opens mining-adjacent tunnel segments where explosive atmosphere requirements limit vendor pools for Trolex Ltd competitors. |
| Thermoelectric Thermal Management Transition | Maintains EU F-Gas Regulation compliance timelines for cooled detector alternatives in Norwegian subsea corridors. |
Methodological Framework
Multi-period observation of EN 50545 replacement cycles, F-Gas Regulation compliance timelines, and silicon photonics adoption rates anchored the trend analysis, supplemented by interviews with tunnel infrastructure procurement officers, railway asset managers, sensor system integrators, and calibration service technicians. Secondary validation drew from European Committee for Standardization technical documentation, German Federal Highway Administration renovation program disclosures, Swiss FEDRO procurement registers, and customs data on optical component trade flows. Bottom-up equipment shipment estimates and top-down infrastructure investment allocations were triangulated to constrain forecast variance.
Segment-weighting applied product type, end user, technology, and application dimensions across the projection horizon, with road tunnel smoke detection volumes, railway vibration sensor expansion trajectories, and IoT-enabled remote diagnostics penetration serving as primary demand-side inputs. CAGRs were derived from logistic diffusion curves fitted to regulatory mandate implementation schedules and technology substitution elasticities calibrated against historical ionization chamber replacement patterns.
Revisions become necessary when EU F-Gas Regulation phase-down schedules accelerate, Chinese GB standard harmonization with European electromagnetic compatibility thresholds advances, or breakthroughs in uncooled infrared sensitivity displace thermoelectric architectures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
Global Signal Conditioning Modules Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Global Industrial Smart Sensors Market