
 North America Circuit Breakers Market | 2026-2036
North America Circuit Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Circuit Breakers Market Analytics
Licensed electrician shortages across the United States and Canada is rotating installation capacity toward prefabricated panel solutions that reduce on-site labor hours. Eaton Corporation leverages its North American manufacturing footprint to sustain same-day distribution in major metropolitan hubs. Schneider Electric anchors utility-grade contracts through integrated digital monitoring platforms that reduce commissioning time. Powell Industries specializes in custom-engineered medium-voltage assemblies for oil and gas installations along the Gulf Coast.
A circuit breaker is an automatically operated electrical switch designed to protect circuits from overload or short-circuit conditions, with ratings spanning fractions of an ampere to thousands of amperes and interruption capacities up to several hundred kiloamperes. Its primary industrial purpose is to isolate fault currents while preserving system continuity in power distribution networks. Molded case breakers dominate residential and light commercial channels where standardized ratings and distributor availability matter most, while air circuit breakers command premium positioning in large industrial facilities and utility substations requiring higher interrupting ratings and adjustable trip settings. The utilities end-user segment is outpacing industrial growth as grid hardening investments accelerate across the continent.
UL 489 and IEEE C37 standards govern product certification in the United States, while CSA C22.2 No. 5 applies in Canada, with both frameworks mandating verified interrupting capacity and endurance testing that shapes manufacturer R&D priorities. NERC reliability standards impose mandatory replacement timelines for aging protective devices, creating recurring demand cycles that insulate the market from pure greenfield volatility. Stakeholders must monitor how state-level renewable portfolio standards and interconnection queue reforms reshape breaker specification requirements for inverter-based generation sources.
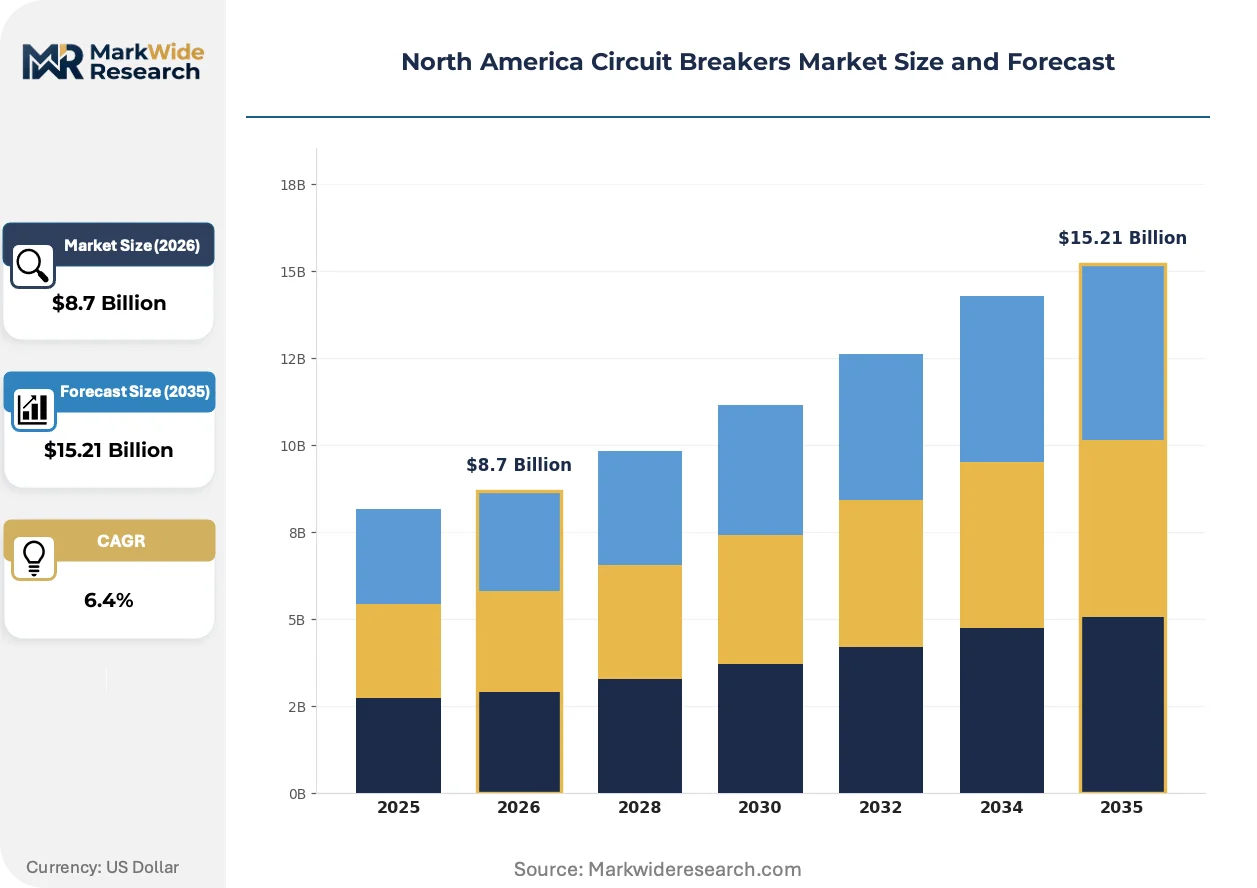
Market Dynamics
NERC reliability standards are forcing mandatory replacement timelines for aging protective devices across United States and Canadian transmission networks, creating recurring demand cycles that insulate manufacturers from pure greenfield volatility. This regulatory pressure concentrates procurement among utilities with hard compliance deadlines.
Growth Catalysts
- Grid Hardening Mandates:NERC CIP-014 physical security standards and IEEE 1547 interconnection rules require upgraded fault protection at renewable integration points across Texas and California.
- Data Center Buildouts:Hyperscale facilities in Northern Virginia and Phoenix demand medium-voltage switchgear with higher interrupting ratings to manage fluctuating AI training loads.
- Copper-Intensive Infrastructure:Busbar and conductor upgrades in Ontario's transmission corridors drive concurrent breaker replacement programs to match elevated current capacities.
Market Restraints
- Silver Contact Volatility:Price swings in silver-cadmium oxide contact materials compress margin predictability for molded case breaker producers serving residential distributors.
- Specialized Fabrication Concentration:Medium-voltage vacuum interrupter manufacturing clusters in Germany and Japan expose North American OEMs to extended lead times during supply shocks.
- UL 489 Revision Friction:Pending updates to branch circuit protection standards create inventory obsolescence risk for distributors holding pre-certified stock.
Strategic Opportunities
- Canadian Arctic Electrification:Remote community microgrids in Nunavut and Northwest Territories require cold-climate-rated breakers with extended operating temperature ranges.
- Digital Twin Convergence:Integration of breaker trip units with SCADA analytics platforms enables predictive maintenance contracts for industrial facilities seeking uptime guarantees.
- Prefabricated Substations:Skid-mounted E-houses reduce on-site labor dependencies, opening utility procurement to integrated breaker-transformer packages from non-traditional panel builders.
Industry Challenges
- Journeyman Electrician Scarcity:Installation capacity constraints in Texas and Arizona rotate demand toward factory-commissioned solutions that minimize field wiring hours.
- Legacy Protocol Integration:Communication retrofitting between IEC 61850-enabled breakers and existing DNP3.0 utility networks demands specialized systems integration expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Circuit Breakers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature, Molded Case, Air, Oil End User: Residential, Commercial, Industrial, Utilities Installation Type: Panel Mounted, Din Rail Mounted, Surface Mounted, Embedded Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | ABB Ltd, Schneider Electric, Eaton Corporation, Siemens AG, General Electric, Mitsubishi Electric, Hitachi, Toshiba, Powell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Circuit Breakers Market Evolving Landscape
Digitalization of protective relay functions is compressing hardware differentiation while expanding software and service revenue pools for breaker manufacturers. This shift reconfigures competitive advantage toward data analytics capabilities rather than pure electromechanical performance.
Solid-state circuit breaker technology employing silicon carbide power semiconductors is decomposing the traditional electromechanical interruption paradigm. Data center operators in Oregon and Nevada are piloting these devices for sub-cycle fault clearing to protect sensitive server loads. The technology is decomposing established market boundaries between breaker manufacturers and power electronics specialists.
IEEE C37.60 revision proceedings for reclosing control standards are tightening coordination requirements between distribution automation systems and feeder protection. Utilities in California must retrofit existing installations to meet synchronized islanding detection mandates for solar-rich circuits. Medium-voltage product lines face the steepest redesign timelines to satisfy accelerated certification deadlines.
Buying committees at municipal utilities are consolidating procurement authority from decentralized plant engineers toward centralized supply chain functions with standardized specifications. Distributor technical specialists are losing direct access to specification decisions as purchasing departments enforce approved vendor lists. This concentration is most visible across Midwestern cooperative utilities seeking volume leverage through multi-year framework agreements.
North America Circuit Breakers Market Segmentation
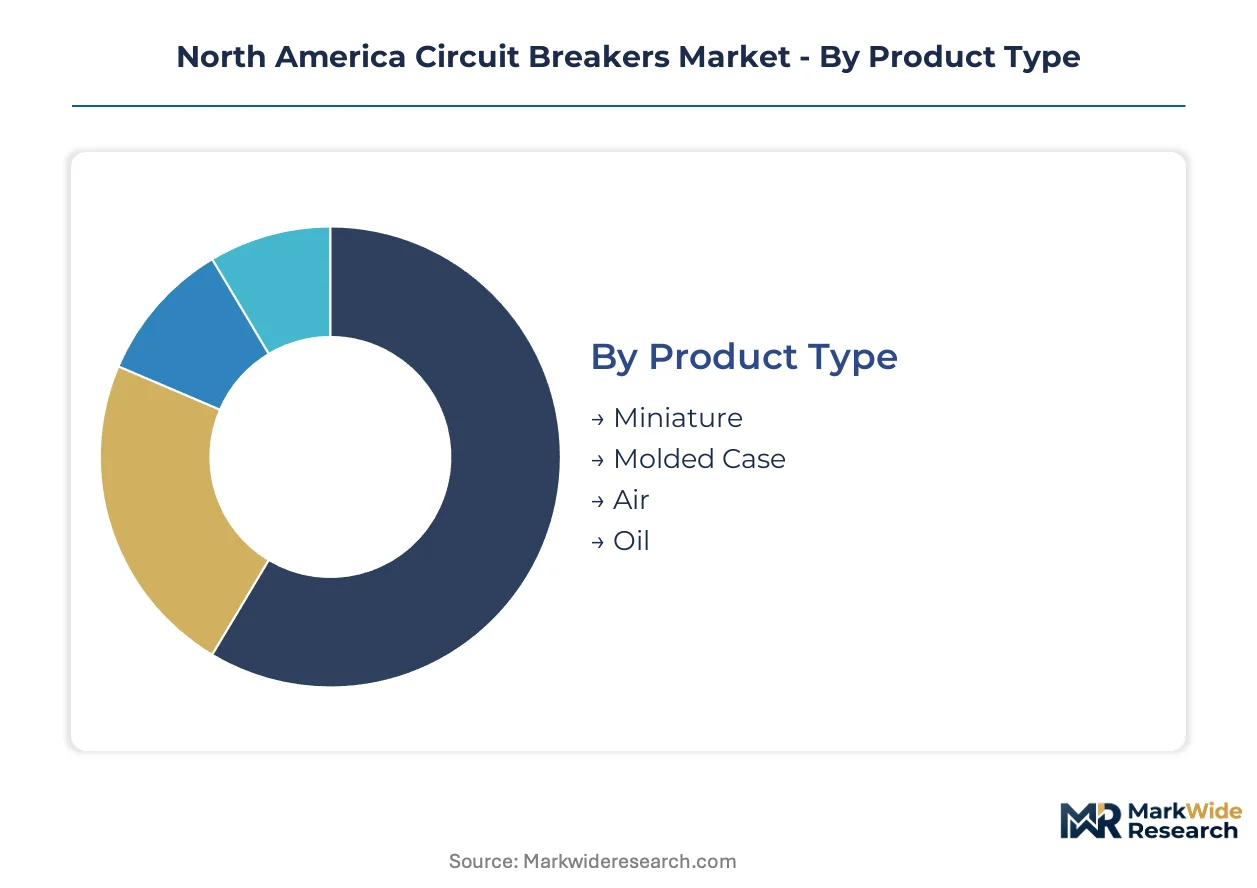
Circuit breaker segmentation reveals divergent substitution pressures across product architectures, with solid-state alternatives threatening electromechanical incumbents in high-value applications while cost-sensitive segments resist displacement. Understanding these fracture lines enables targeted portfolio positioning against both traditional competitors and emerging power electronics specialists.
Product Type:
Miniature breakers face the most acute substitution threat from residual-current devices with integrated overcurrent protection, while air circuit breakers defend their position through irreplaceable interrupting capacity in utility applications.
- Miniature:Single-pole and multi-pole units rated below 100 amperes protect branch circuits in residential and light commercial installations across Texas and California. Demand concentrates in retrofit markets where aging Federal Pacific and Zinsco panels drive replacement cycles in suburban housing stock.
- Molded Case:Thermoset plastic housings encase thermal-magnetic trip mechanisms in ratings from 15 to 2,500 amperes, dominating commercial construction and light industrial feeder protection. Procurement in Ontario's manufacturing corridors favors these units for their balance of cost and field serviceability.
- Air:Open-frame construction with arc chutes achieves interrupting ratings exceeding 100 kiloamperes for utility substations and large industrial facilities.
- Oil:Immersed interruption chambers persist in legacy high-voltage installations and specialized mining applications requiring explosion containment.
Molded case breakers anchor the volume base while air circuit breakers gain share at the steepest rate through utility grid hardening investments.
End User:
Customer type segmentation tracks divergent procurement sophistication, with utilities consolidating specifications through centralized supply chain functions while residential demand fragments across distributor branches.
- Residential:Single-family and multi-family construction drives demand for standardized miniature and molded case units with UL 489 certification. California Title 24 energy codes mandate arc-fault circuit interrupter integration in new construction, reshaping product mix toward combination AFCI-GFCI devices.
- Commercial:Office buildings, retail centers, and hospitality facilities require coordinated panelboard solutions with selective trip coordination. Northern Virginia data center buildouts specify medium-voltage switchgear with digital trip units for remote monitoring capabilities.
- Industrial:Manufacturing plants and process facilities demand adjustable trip settings and communication-enabled breakers for integration with plant SCADA systems.
- Utilities:Transmission and distribution operators procure reclosers and sectionalizers under NERC reliability compliance deadlines.
Utilities command the highest average selling prices while residential channels move the largest unit volumes through distributor stocking programs.
Installation Type:
Mounting configuration determines labor content and field modification flexibility, with prefabrication trends favoring factory-integrated solutions over traditional field-wired assemblies.
- Panel Mounted:Bolted installation within switchgear enclosures or panelboards dominates new construction and major renovations. Arizona and Texas contractor shortages accelerate demand for factory-pre-wired panel solutions that minimize journeyman electrician hours on site.
- Din Rail Mounted:Snap-on attachment to standardized 35mm rails enables rapid installation and modular expansion in control cabinets and industrial machinery. Machine builders in Ontario's automotive supply chain specify these units for production line flexibility.
- Surface Mounted:Exposed installation in retrofit applications and temporary power distribution.
- Embedded:Integration within OEM equipment such as HVAC units, elevators, and medical imaging systems.
Panel mounted configurations generate the largest revenue pool while Din rail mounting expands most quickly through industrial automation proliferation.
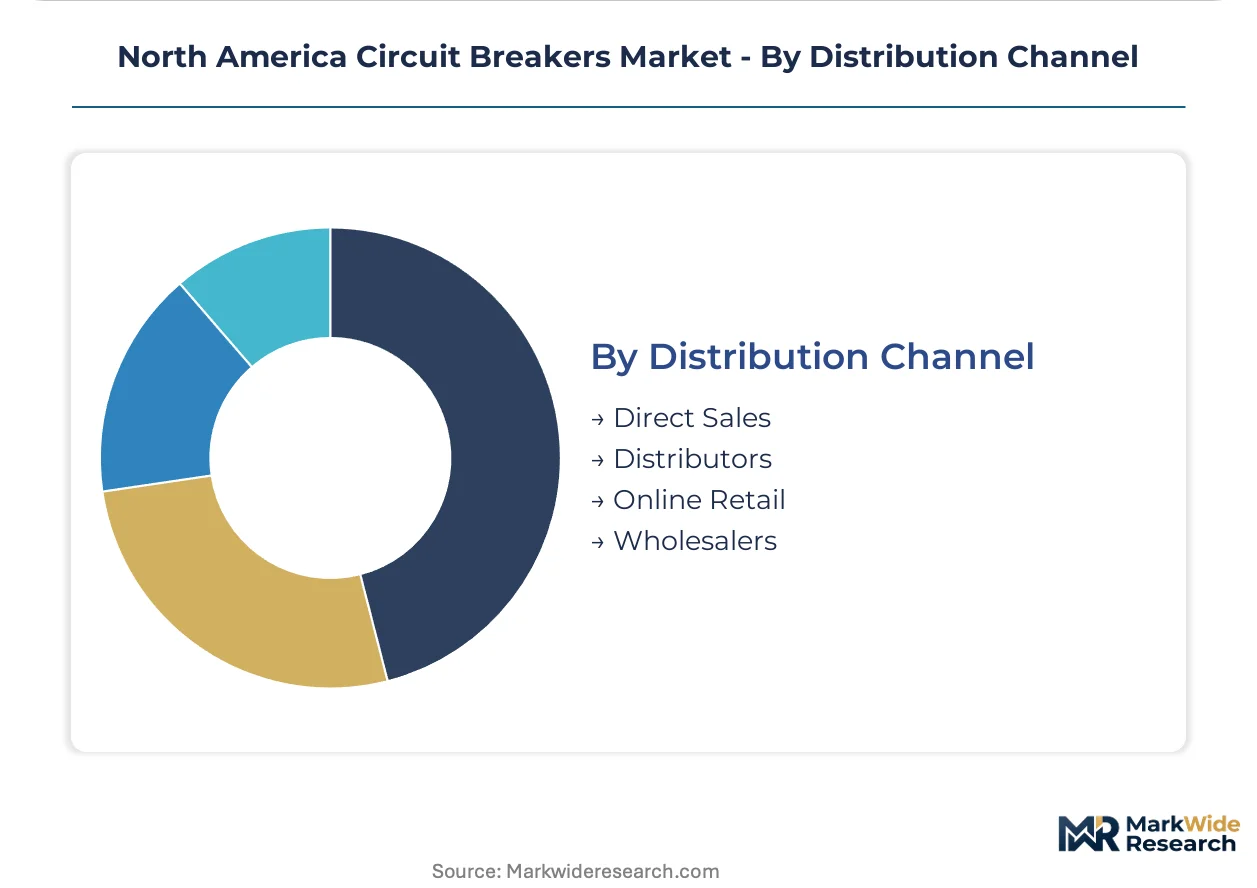
Distribution Channel:
Channel structure reflects the tension between specification influence and procurement efficiency, with manufacturer-direct relationships eroding distributor technical advisory roles at large utilities.
- Direct Sales:Manufacturer account teams engage utility procurement departments and large industrial end-users on multi-year framework agreements. Consolidated buying committees at Midwestern cooperatives bypass distributor technical specialists to negotiate volume pricing directly with Eaton and Schneider Electric.
- Distributors:Electrical supply houses maintain local inventory and provide emergency replacement services for contractors and maintenance departments. Graybar and Rexel branches in Phoenix and Dallas compete on same-day availability for construction projects with tight schedules.
- Online Retail:E-commerce platforms serve small contractors and facility maintenance staff seeking price transparency on standard ratings.
- Wholesalers:Bulk purchasing organizations aggregate demand from smaller electrical contractors.
Direct sales capture the highest-value utility contracts while distributors retain volume leadership through contractor relationships and emergency service capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC reliability mandates and NERC standards anchor United States demand, while Canadian provincial utilities and Mexican industrial corridors complete the North American circuit breaker landscape across distinct regulatory and procurement environments.
United States
Texas ERCOT grid hardening and California renewable interconnection queues drive medium-voltage breaker procurement at the fastest rate. NERC CIP-014 physical security standards mandate upgraded fault protection at transmission substations. Northern Virginia data center clusters specify digital trip units for hyperscale facilities managing AI training loads.
Canada
Ontario transmission corridor upgrades and Alberta oil sands electrification anchor utility-grade demand across provincial Crown corporations. CSA C22.2 No. 5 certification requirements shape product specifications for cross-border supplier qualification. Nunavut remote community microgrids require cold-climate-rated breakers with extended operating temperature ranges.
Mexico
Nuevo León automotive manufacturing expansion and Mexico City Metro distribution network modernization concentrate industrial demand. CFE transmission infrastructure investments under the national utility's grid reinforcement program create procurement opportunities. Bajío Region industrial parks specify molded case breakers for foreign-owned manufacturing facilities.
North America Circuit Breakers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America circuit breakers market. Three multinational electrical equipment conglomerates control utility-grade procurement channels through framework agreements with centralized buying committees. Specialist fabricators occupy custom-engineered niches in oil and gas and heavy industrial applications. Competitive positioning depends on manufacturing footprint proximity to major metropolitan distribution hubs and digital monitoring platform integration capabilities.
Among the integrated leaders, ABB Ltd and Schneider Electric exemplify the full-spectrum archetype spanning residential through utility voltage classes. Eaton Corporation occupies a distinct position emphasizing North American manufacturing proximity and same-day distribution logistics. Powell Industries represents the specialist tier, anchoring custom medium-voltage assembly capabilities for Gulf Coast industrial applications.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric |
| Eaton Corporation |
| Siemens AG |
| General Electric |
| Mitsubishi Electric |
| Hitachi |
| Toshiba |
| Powell Industries |
| Others |
Value Network & Pricing Analysis
Sixteen-week lead times for medium-voltage vacuum interrupters from German and Japanese manufacturing clusters concentrate pricing power with incumbent suppliers while compressing margin predictability for North American OEMs facing urgent NERC compliance deadlines. This supply concentration interacts with silver-cadmium oxide contact material volatility to create divergent pricing dynamics across product tiers.
Pricing Analysis
Geographic price spreads of 12-18% separate Gulf Coast utility procurement from Midwestern cooperative bids, reflecting divergent specification complexity and after-sales service bundling. Three-tier pricing structure across utility-grade, industrial-specified, and residential-distributor levels anchors the market, with UL 489 certification grade and interrupting capacity rating as primary differentiation drivers. Cost compression in residential molded case segments is intensifying because distributor consolidation erodes price transparency for small contractors. Municipal utilities exhibit lowest price sensitivity due to NERC-mandated replacement timelines, while residential distributors face acute margin pressure from online retail encroachment.
Supply Chain Analysis
Strategic stockpiling of silver contact materials and vacuum interrupter assemblies dominates inventory strategy over just-in-time approaches, given NERC compliance deadline rigidity and overseas supplier lead-time volatility. Manufacturing concentration in Germany, Japan, and select Mexican maquiladora facilities for medium-voltage components creates single-source vulnerability during semiconductor supply shocks affecting solid-state breaker production. Raw material dependencies center on copper busbar, silver-cadmium oxide contacts, and thermoset plastic resin systems. Distribution runs through authorized electrical distributors for contractor channels and direct manufacturer relationships for utility procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fabrication expertise for medium-voltage assemblies and IEC 61850 protocol integration capabilities are concentrated among a narrow supplier base, creating acquisition premiums and partnership bottlenecks for buyers seeking grid modernization solutions.
For Market Incumbents: Compound digital monitoring platform capabilities with predictive maintenance service contracts to capture recurring revenue streams as hardware differentiation compresses. Solid-state circuit breaker entrants from power electronics sectors threaten traditional electromechanical margins in data center applications. Prioritize backward integration into vacuum interrupter production or captive North American fabrication capacity to reduce overseas lead-time exposure. For New Entrants and Emerging Players: Differentiate on cold-climate operating range specifications to penetrate Canadian Arctic microgrid opportunities where incumbent coverage remains thin. Remote community electrification in Nunavut and Northwest Territories offers the most penetrable geographic white space. Prefabricated E-house integration partnerships with non-traditional panel builders provide a direct go-to-market angle bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core electrical equipment divisions with stranded utility-grade certification capabilities. Long-term viability hinges on software-analytics integration rather than pure manufacturing scale. Acquisition candidates with IEC 61850-DNP3.0 protocol bridging expertise warrant premium multiples. Watch solid-state breaker pilot performance in Oregon and Nevada data centers as the critical inflection signal for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Breaker trip unit convergence with SCADA analytics enables predictive maintenance contracts for industrial uptime guarantees. |
| Cold-Climate Certification Investment | Extended temperature range validation opens procurement channels for Nunavut remote community microgrid deployments. |
| Vacuum Interrupter Backward Integration | Captive North American production reduces 16-week overseas lead times during NERC compliance deadline crunches. |
| Prefabricated E-House Partnership | Skid-mounted substation integration bypasses journeyman electrician scarcity in Texas and Arizona construction markets. |
| IEC 61850 Protocol Bridging | Communication retrofitting expertise unlocks utility contracts requiring legacy DNP3.0 network integration. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility procurement directors, electrical contractor estimators, OEM panel builders, and aftermarket service managers. Secondary validation drew from FERC reliability filings, NERC compliance databases, IEEE standards documentation, and customs import records for vacuum interrupter assemblies. Bottom-up triangulation against top-down utility capital expenditure tracking ensured forecast robustness.
Across the analysis window, projections incorporate product type, end-user segment, installation configuration, and regional regulatory cluster dimensions. CAGRs were derived from utility replacement cycle modeling, renewable interconnection queue processing rates, and data center power infrastructure buildout tracking. Forecast inputs include NERC CIP-014 physical security mandate implementation timelines and IEEE 1547 interconnection standard revision adoption curves.
Material uncertainties — commodity price swings in silver contact materials, UL 489 revision finalization, and solid-state breaker technology maturation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory deadline adherence and supply chain normalization. Revision becomes warranted when solid-state breaker pilot performance crosses commercial viability thresholds or NERC mandates accelerate replacement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
US Electric Enclosure Market
Electrical Equipment
MCB and MCCB Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
High-Vacuum Fiber Feedthrough Flanges Market
Electrical Equipment
Global Electrical Steel Market
Electrical Equipment
Electrical Measuring Instrument Market
Electrical Equipment
Europe Electrical Bushing Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Magnetic Contactors Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Copper and Aluminum Terminal Blocks Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
Vacuum Interrupter Market