
 Global Digital Panel Meter Market | 2026-2036
Global Digital Panel Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Panel Meter Market Intelligence
A transition from single-source component agreements to diversified multi-sourcing for key microelectronics is pivoting the supply chain structure for manufacturers. Siemens leverages its extensive portfolio in industrial automation to offer integrated solutions. OMRON Corporation differentiates through its specialization in high-precision control components for manufacturing plants. Murata Manufacturing sustains its market presence by providing critical electronic modules and power supplies to other device makers.
A digital panel meter is an instrument that presents an input signal in a numeric format on a display. These devices utilize an analog-to-digital converter to achieve high accuracy in measurements like voltage, current, and temperature. Their primary industrial purpose is to provide operators with clear, precise readouts for process monitoring and control. Digital product types are steadily displacing older analog meters, while touchscreen technology gains preference over standard LED or LCD displays in advanced automation control applications.
Product design is shaped by multiple regulatory frameworks. CE marking in Europe enforces strict electromagnetic compatibility and low-voltage directives. In the United States, the FCC sets limits on radio frequency emissions, while BIS certification is mandatory for market access in India. Vendor success depends on balancing enhanced feature integration with compliance to evolving international energy efficiency standards.
Market Dynamics
The convergence of industrial automation with Internet of Things (IoT) connectivity is the central force shaping the digital panel meter market. This integration compels manufacturers to embed real-time data analytics capabilities directly into devices for critical process and grid monitoring applications.
Growth Catalysts
- Smart Grid Investment:National-level investment in smart grid infrastructure, particularly in China, creates sustained demand for advanced meters capable of real-time voltage and current monitoring to improve grid stability and efficiency.
- Industrial Process Optimization:The push for higher precision in manufacturing plants drives the adoption of digital panel meters for monitoring temperature, pressure, and flow, replacing less accurate analog instruments in process control loops.
- Energy Efficiency Regulations:Mandates such as the European Union's energy efficiency directives incentivize industrial facilities to install accurate sub-metering, creating a compliance-driven need for digital panel meters to track and report energy consumption.
Market Restraints
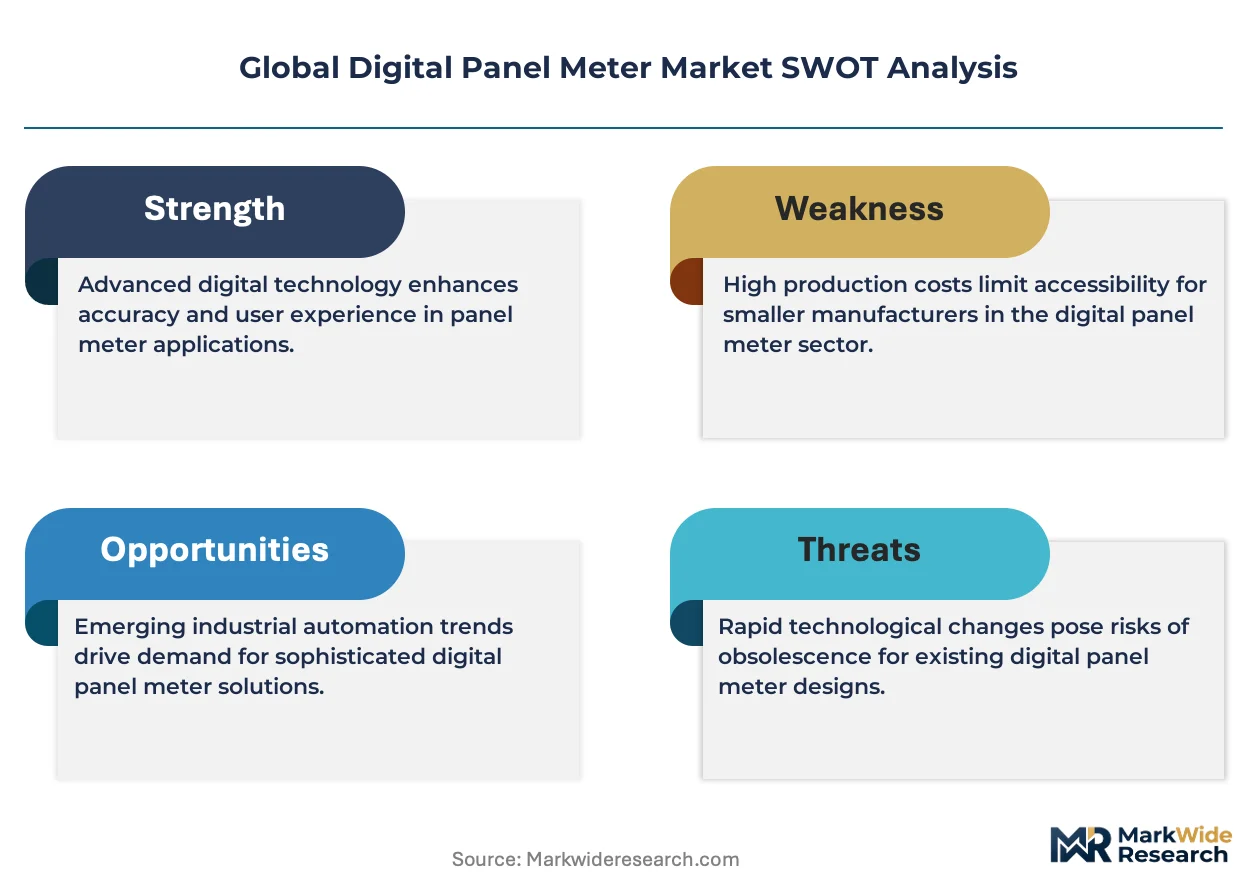
- Component Supply Volatility:The supply of critical microelectronics, especially high-performance analog-to-digital converters (ADCs) and microcontrollers, is subject to price fluctuations and lead-time variability, creating production bottlenecks for meter manufacturers.
- Substitution by Integrated HMI Systems:Digital panel meters face a substitution threat from more comprehensive Human-Machine Interface (HMI) and SCADA systems that integrate monitoring functions, reducing the need for standalone display units in new installations.
- Complex International Certifications:The cost and time required to secure multiple mandatory certifications, such as CE marking in Europe, FCC approval in the US, and BIS in India, act as a significant barrier for new entrants and strain resources for existing vendors.
Strategic Opportunities
- IoT-Enabled Predictive Maintenance:There is an opportunity to develop meters with embedded analytics that transmit operational data to cloud platforms, enabling predictive maintenance alerts for industrial equipment before failures occur.
- Renewable Energy Sector Expansion:The build-out of solar and wind energy installations presents a white-space opportunity for specialized panel meters designed for monitoring DC power systems, inverters, and grid-tie synchronization points.
- Advanced User Interfaces:Upgrading product lines with high-resolution touchscreen displays and intuitive graphical user interfaces can capture higher-value segments in advanced automation, where operator interaction and data visualization are critical.
Industry Challenges
- Legacy System Integration:A primary operational challenge is ensuring seamless interoperability between new, network-enabled digital panel meters and the installed base of older, non-IP-based industrial control systems and PLCs.
- Firmware and Cybersecurity:The integration of IoT connectivity introduces the challenge of securing devices against cyber threats, requiring robust firmware development, secure boot processes, and ongoing patch management throughout the product lifecycle.
- Standardization of Communication Protocols:A lack of universal standardization for communication protocols across different industrial automation ecosystems complicates product development and forces manufacturers to support multiple standards like Modbus, Profinet, and EtherNet/IP.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Panel Meter Market |
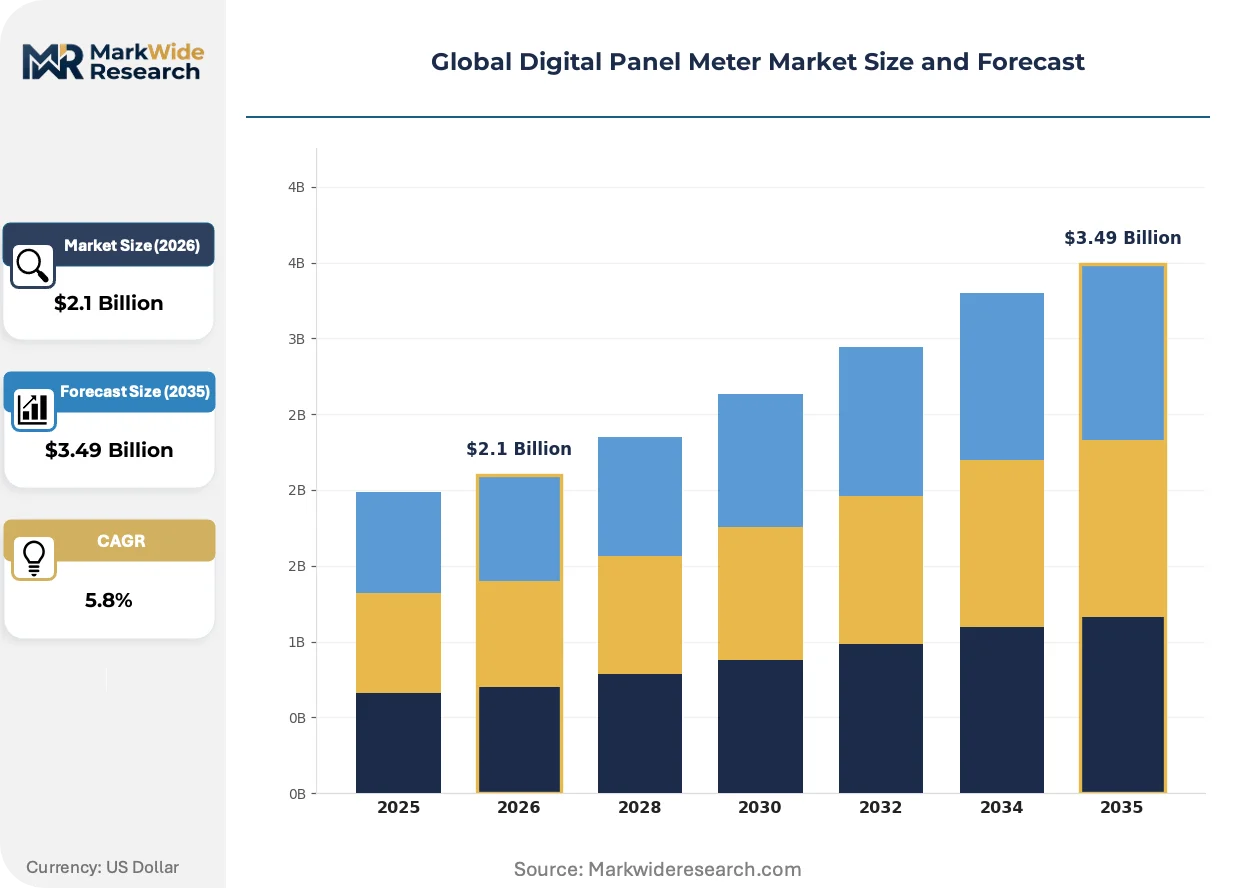
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Hybrid, Smart Technology: LED, LCD, OLED, VFD, Touchscreen Application: Process Monitoring, Power Measurement, Test & Measurement, Automation Control, Laboratory Instrumentation End User: Manufacturing Plants, Energy Utilities, Research Institutes, Automation Firms |
| Companies Covered | Murata Manufacturing, OMRON Corporation, Siemens, Autonics Corporation, Trumeter, Yokogawa Electric Corporation, Red Lion Controls, Carlo Gavazzi, Phoenix Contact, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Panel Meter Market Strategic Shifts & Innovations
Product evolution is transforming digital panel meters from standalone measurement instruments into intelligent nodes within larger industrial data networks. This development is steered by demands for greater device intelligence, stricter regulatory compliance for connected hardware, and changing procurement behaviors in key end-use sectors.
System-on-Chip (SoC) architectures are becoming central to next-generation product design. These integrated circuits combine analog-to-digital converters, microcontrollers, and wireless connectivity modules onto a single piece of silicon. Industrial automation and energy utility operators are adopting SoC-based meters to enable more compact and power-efficient devices for real-time monitoring. The use of these integrated components is consolidating the device bill of materials and simplifying assembly processes for manufacturers.
The EU's updated directives for CE marking, specifically concerning electromagnetic compatibility (EMC), are influencing product engineering. These rules impose stricter limits on radio frequency emissions and susceptibility, particularly for devices incorporating wireless technologies like Wi-Fi or LoRaWAN. This regulatory pressure is forcing manufacturers to invest more in circuit shielding and signal integrity testing. The industrial control segment is most affected, as product redesigns are often necessary to maintain market access.
A move toward modular product platforms is altering purchasing patterns for large-scale industrial projects. Instead of procuring fixed-function meters, system integrators now specify base models with options for field-upgradable connectivity cards or enhanced display modules. This allows for greater flexibility and future-proofing of installations without requiring a full instrument replacement. This purchasing behavior is most visible in the data center and building automation verticals, where scalability is a primary design requirement.
Global Digital Panel Meter Market Segmentation
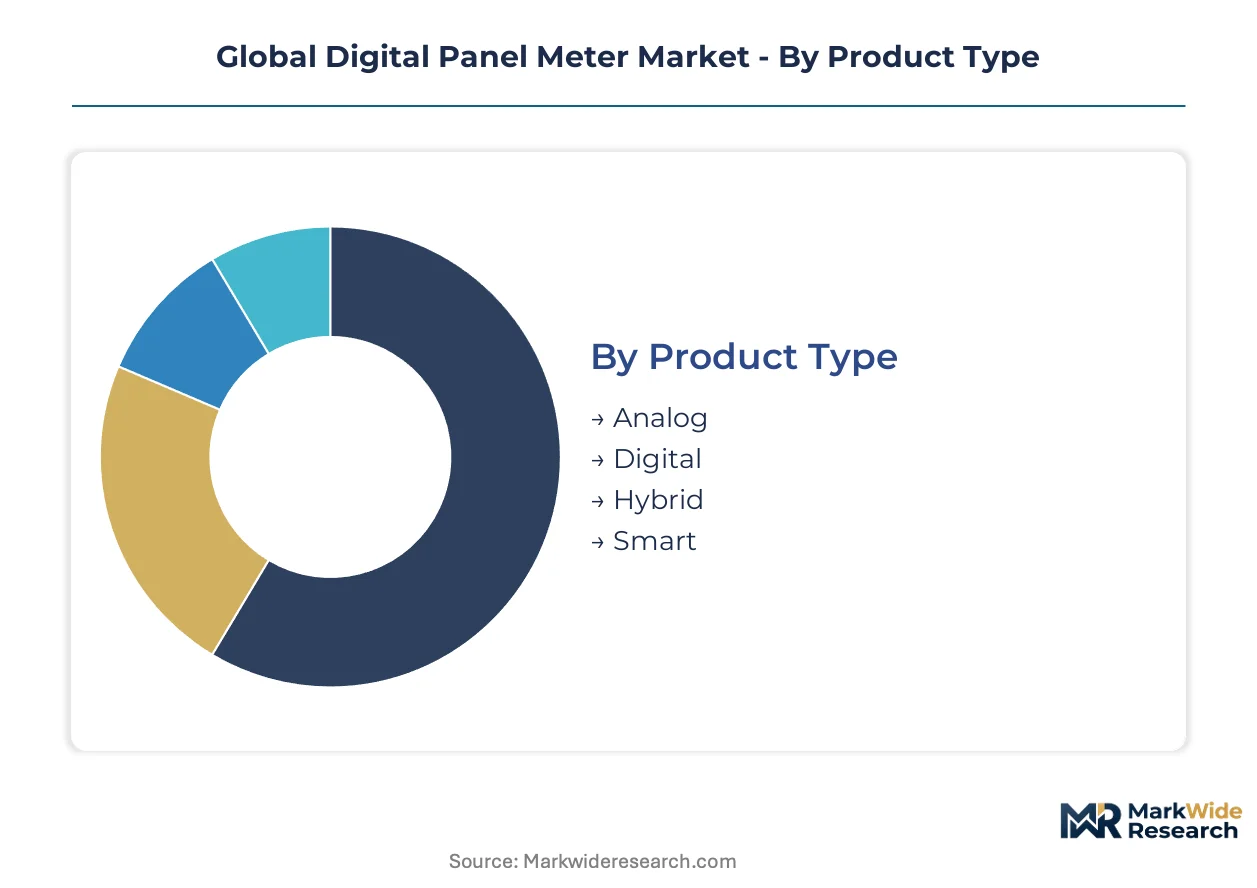
Understanding the varied segments within the digital panel meter market is crucial for manufacturers to align product development with specific industry demands. This segmentation provides a granular view of how different product types, technologies, applications, and end-users influence market dynamics and strategic investment.
Product Type:
The market for digital panel meters is delineated by the depth of integration, distinguishing standalone measurement devices from those embedded within larger systems.
- Digital:These meters display measurements numerically, utilizing an analog-to-digital converter for high accuracy in parameters like voltage, current, and temperature. Industrial process optimization in manufacturing plants drives substantial demand for these precise readouts.
- Smart:Incorporating advanced features like IoT connectivity and embedded analytics, smart meters enable real-time data transmission and remote monitoring capabilities. Energy utilities, particularly in China, are rapidly adopting smart meters for advanced grid monitoring applications.
- Analog:Older analog meters provide visual representations of measurements via a needle on a scale. These are steadily being displaced by digital alternatives across most industrial settings due to lower precision.
- Hybrid:Hybrid meters combine aspects of both analog and digital displays, offering both numerical and graphical representations. These find niche applications where both precise numerical values and trend visualization are beneficial.
Digital meters lead volumes today; Smart meters are gaining share fastest.
Technology:
Display technology choice significantly impacts user interaction and visual clarity for digital panel meters, influencing their suitability for diverse operating environments.
- Touchscreen:These advanced displays offer intuitive graphical user interfaces and enhanced data visualization capabilities. Automation control applications in high-end manufacturing are increasingly preferring touchscreen interfaces for operator interaction.
- LED:Light-Emitting Diode displays provide bright, clear numerical readouts, making them suitable for environments with varying light conditions. Many standard industrial process monitoring systems continue to rely on robust LED displays for essential data presentation.
- LCD:Liquid Crystal Display technology offers a cost-effective solution for displaying numerical and alphanumeric information. LCDs are commonly found in general-purpose digital panel meters where high brightness and wide viewing angles are not primary requirements.
- OLED:Organic Light-Emitting Diode displays offer superior contrast and wider viewing angles compared to LCDs, often in more compact form factors. OLED technology is emerging in specialized instrumentation requiring high-fidelity visual output.
- VFD:Vacuum Fluorescent Displays offer high brightness and a wide operating temperature range, making them durable for harsh industrial environments. VFDs maintain a presence in legacy systems and specific heavy industrial applications.
Demand for LED displays remains strong, while Touchscreen technology continues its rapid expansion.
Application:
Digital panel meters serve various critical functions across industrial and commercial sectors, each demanding specific performance characteristics and integration capabilities.
- Process Monitoring:This application involves continuous oversight of industrial parameters like temperature, pressure, and flow to ensure operational stability and product quality. Manufacturing plants extensively deploy digital panel meters for precise control loops and immediate feedback to operators.
- Automation Control:Meters in automation control systems provide critical data inputs for programmable logic controllers (PLCs) and distributed control systems (DCS). The push for higher precision in complex manufacturing processes drives adoption of advanced meters for integration into automated lines.
- Power Measurement:Digital panel meters accurately measure electrical parameters such as voltage, current, frequency, and power factor within electrical grids and industrial facilities. National smart grid investments, particularly in China, are creating significant demand for these meters for real-time energy management.
- Test & Measurement:These applications involve using meters for calibration, diagnostics, and performance verification of equipment and systems. Research institutes and specialized engineering firms utilize these meters for accurate data acquisition.
- Laboratory Instrumentation:Digital panel meters are integrated into various laboratory equipment for precise measurement and display of experimental parameters. These devices support scientific research and quality control processes across diverse industries.
Process Monitoring applications drive significant volume, with Automation Control exhibiting notable growth due to specific industry mandates.
End User:
The diverse range of end-users for digital panel meters reflects the broad applicability of these instruments across different operational contexts and industry verticals.
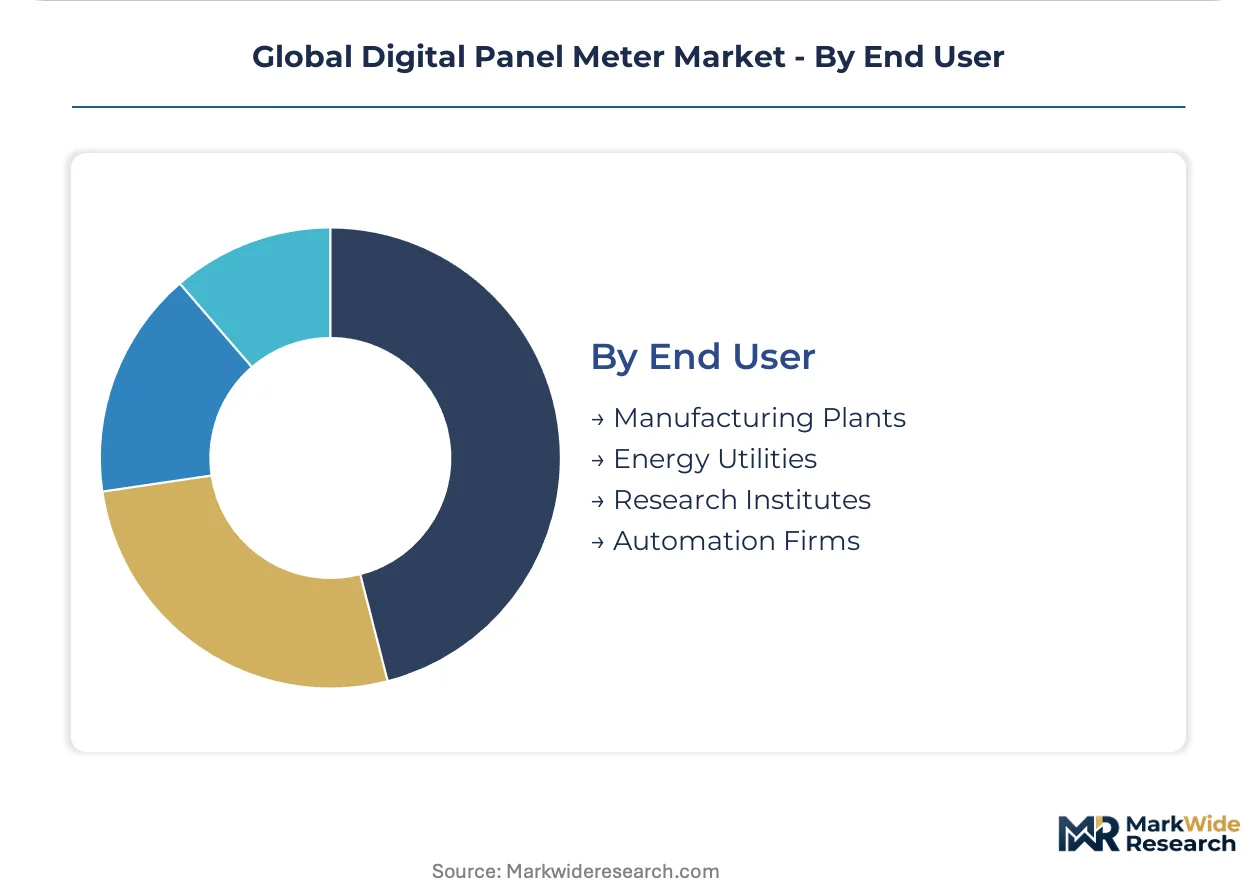
- Manufacturing Plants:These facilities utilize digital panel meters for precision control, quality assurance, and operational efficiency across production lines. The push for industrial automation and higher throughput directly fuels demand in this sector.
- Energy Utilities:Power generation, transmission, and distribution companies deploy digital panel meters for monitoring grid stability, energy consumption, and asset performance. Smart grid infrastructure projects globally are a primary catalyst for meter adoption here.
- Research Institutes:Academic and commercial research organizations integrate digital panel meters into experimental setups for accurate data collection and analysis. These institutions require high-precision instruments for scientific validation.
- Automation Firms:Companies specializing in industrial automation solutions integrate digital panel meters into larger control systems and custom machinery. These firms specify meters based on client requirements for system interoperability and performance.
The largest deployments are consistently observed in Manufacturing Plants and Energy Utilities sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive smart grid infrastructure development drives significant demand for digital panel meters. This investment across Asia positions the country as a focal point for market growth. The global market sees varied regional adoption influenced by industrial maturity and regulatory frameworks.
China
China's national smart grid investment creates sustained demand for advanced meters capable of real-time voltage and current monitoring. The dual carbon goals encourage energy-efficient monitoring solutions across industrial and commercial sectors. Manufacturing plants in the Yangtze River Delta and Pearl River Delta extensively deploy these devices for process control and automation.
United States
United States energy utilities require advanced meters for grid stability and efficiency in power measurement applications. FCC regulations limit radio frequency emissions, influencing product design for connected devices with IoT capabilities. Industrial clusters in the Midwest, particularly around Detroit, integrate digital panel meters into automotive manufacturing for precision control.
Germany
German industrial automation initiatives drive demand for high-precision digital panel meters in manufacturing plants. CE marking enforces strict electromagnetic compatibility standards, ensuring market access for European products. Manufacturing facilities in Bavaria, including those near Munich, adopt advanced meters for quality control and process optimization.
India
Indian industrial expansion and energy efficiency mandates fuel demand for digital panel meters across various sectors. BIS certification is mandatory for market access, ensuring product quality and safety for consumers. Major industrial corridors like those in Maharashtra integrate these meters for process optimization and energy management.
Japan
Japanese manufacturers prioritize high-precision control components for advanced automation systems in their facilities. METI guidelines encourage technological innovation and standardization in industrial equipment design and deployment. The Kanto region, including Tokyo, houses numerous electronics and automation firms utilizing these meters for sophisticated instrumentation.
Global Digital Panel Meter Market Key Industry Players
Global majors compete with regional champions across industrial automation and specialized control components. The market exhibits a tiered structure, with large conglomerates offering integrated solutions alongside niche specialists. Two primary archetypes emerge: broad industrial automation providers and focused precision component manufacturers. Strategic partnerships for IoT integration and portfolio diversification into software solutions are dominant competitive moves.
Specialists in industrial automation and high-precision control exemplify market positioning across various tiers. Siemens, a German-based AG, represents a broad industrial automation provider, leveraging its extensive portfolio to offer integrated solutions. OMRON Corporation, a Japanese-based entity, anchors the segment for high-precision control components, particularly for complex manufacturing plants. Murata Manufacturing, another Japanese-based corporation, sits within the critical electronic modules and power supplies segment, providing essential components to other device makers. These companies collectively illustrate the diverse strategic approaches in the digital panel meter ecosystem.
| Leading Market Players |
|---|
| Murata Manufacturing |
| OMRON Corporation |
| Siemens |
| Autonics Corporation |
| Trumeter |
| Yokogawa Electric Corporation |
| Red Lion Controls |
| Carlo Gavazzi |
| Phoenix Contact |
Cost & Logistics Intelligence
Microchip component pricing volatility, particularly for analog-to-digital converters, cascades through the digital panel meter supply chain, influencing final product pricing tiers for end-users.
Pricing Analysis
Input-cost pass-through for critical microelectronics directly impacts digital panel meter pricing. The market primarily operates on a tiered premium-mid-economy pricing differentiation. Price differentiation stems from certification levels, such as CE marking or FCC approval, and the degree of after-sales service bundled with integrated solutions. Cost compression in standard digital meters intensifies due to increased competition from Asian manufacturers. Energy utilities, driven by smart grid investments, exhibit lower price sensitivity compared to price-conscious manufacturing plants.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke models characterize the downstream distribution of digital panel meters. Geographic supply concentration for key components centers in China, Japan, and Germany. Raw material dependencies include high-performance analog-to-digital converters, microcontrollers, and advanced display modules. Single-source vulnerability for specialized microelectronics represents a significant structural risk. Distribution runs through a combination of direct sales to large industrial clients and specialized distributors serving smaller system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global digital panel meter market functions as a stable compounder, with sustained demand from industrial automation initiatives driving consistent growth.
For Market Incumbents:
Deploy diversified multi-sourcing strategies for key microelectronics to mitigate supply volatility and production bottlenecks. Focus R&D investment into System-on-Chip (SoC) architectures to enhance device intelligence and reduce bill of materials costs. This approach counters the substitution threat from integrated HMI systems. Prioritize ongoing investment in robust cybersecurity features and regulatory compliance, particularly for new IoT-enabled product lines, to maintain market access.
For New Entrants and Emerging Players:
Niche technology integration, such as specialized meters designed for DC power systems in renewable energy installations, offers a penetrable market segment. Develop advanced user interfaces with high-resolution touchscreen displays and intuitive graphical elements to capture higher-value segments. Focus on modular product platforms that allow for field-upgradable connectivity cards, addressing the demand for future-proofing in data center and building automation verticals. Target applications requiring high-fidelity visual output, leveraging OLED technology.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized component manufacturers possessing strong intellectual property in analog-to-digital converters or wireless connectivity modules. The market demonstrates long-term viability, underpinned by sustained industrial automation and energy efficiency mandates. Acquisition targets should exhibit robust regulatory compliance frameworks and established relationships within energy utility or high-precision manufacturing sectors. The adoption rate of SoC architectures in new product lines serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversified Microelectronics Sourcing | Reduces supply chain risk for critical components like ADCs and microcontrollers. |
| IoT Connectivity Integration | Enables predictive maintenance and real-time data analytics for industrial equipment. |
| Advanced Display Technology Development | Captures higher-value segments in automation control with intuitive user interfaces. |
| Regulatory Compliance Investment | Ensures market access in regions like Europe (CE marking) and India (BIS certification). |
| Modular Product Platform Expansion | Offers greater flexibility and future-proofing for large-scale industrial projects. |
Research Approach
Coverage spans China, United States, Germany, India, and Japan, with primary inputs from each region. The methodology combines in-depth interviews with industrial automation engineers, energy utility managers, R&D directors, and procurement specialists. Secondary validation draws from national smart grid investment reports, industrial output statistics, regulatory body publications such as FCC and BIS, and company financial disclosures. This approach ensures robust bottom-up and top-down triangulation.
The rate-of-change decomposition framework underpins the analytical model, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user, and geographic region. Compound annual growth rates are derived through a combination of regression analysis and expert consensus. Key industry-specific forecast inputs include smart grid investment levels and industrial automation expenditure across manufacturing plants.
The model holds under current macroeconomic conditions and established regulatory frameworks; deviation in microelectronics supply volatility or rapid HMI system adoption would shift projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
India Electrical Enclosures Market
Electrical Equipment
Ultra High Voltage (UHV) Appliances Market
Electrical Equipment
Central Vacuum Receivers Market
Electrical Equipment
Hermetic Reciprocating Refrigerator Compressor Market
Electrical Equipment
Slip Ring Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
Global General Purpose Contactor Market
Electrical Equipment
Current Clamps Market
Electrical Equipment
Switchgear Monitoring System Market
Electrical Equipment
HID Ballast Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Electric Wall Heaters Market
Electrical Equipment
Electronically Commutated (EC) Fan Market
Electrical Equipment
Copper and Copper Alloy Busbars Market
Electrical Equipment
Busbar Trunking System Market