
 Hermetic Reciprocating Refrigerator Compressor Market | 2026-2036
Hermetic Reciprocating Refrigerator Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Hermetic Reciprocating Refrigerator Compressor Market Analysis
Commercial cold storage is recalibrating demand profiles across the hermetic reciprocating refrigerator compressor landscape. Huayi Compressor leverages its manufacturing scale to anchor supply for domestic refrigerator OEMs across Asia. Secop sustains technology leadership in variable-speed architectures for precision cooling applications. Embraco competes through geographic dominance in Latin American aftermarket channels.
A hermetic reciprocating refrigerator compressor is a fully sealed electromechanical device where motor and compressor share a common welded steel housing, typically operating with displacement volumes between 3 cc and 20 cc and relying on crankshaft-driven piston action to compress refrigerant vapor. Its primary purpose is to maintain temperature-controlled environments in sealed refrigeration systems by circulating compressed refrigerant through condenser and evaporator circuits. Fixed-speed units still occupy the largest volume share in residential applications, though variable-speed compressors are capturing margin pools in premium segments through energy efficiency gains. The cold storage application is expanding fastest as logistics operators retrofit aging facilities with compliant refrigerant systems.
The US EPA SNAP program and EU F-Gas Regulation are compressing product development cycles by banning high-GWP refrigerants and mandating leak detection protocols. China's GB standards and MIIT energy efficiency labeling rules are forcing domestic manufacturers to redesign motor windings and valve plates. Stakeholders must monitor refrigerant chemistry transitions and regional certification divergence to avoid stranded inventory in cross-border supply chains.
Market Dynamics
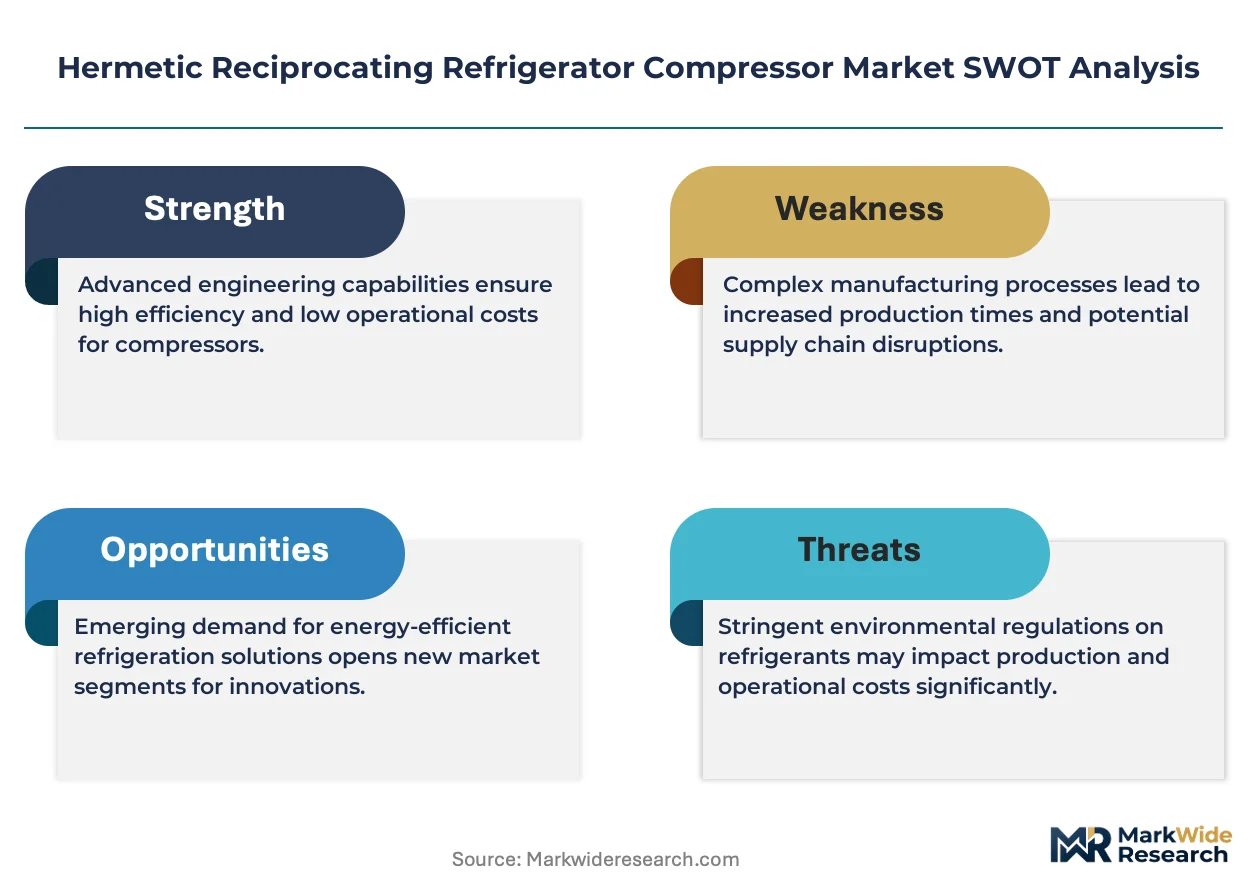
The refrigerant transition mandated by the US EPA SNAP program and EU F-Gas Regulation is forcing compressor architecture redesigns, compressing development cycles and redistributing competitive advantage toward manufacturers with in-house chemistry and motor-winding capabilities.
Growth Catalysts
- Commercial cold storage expansion:Food retail chains in China and Southeast Asia are retrofitting distribution centers with compliant refrigeration systems, pulling demand for higher-displacement hermetic units.
- MIIT energy efficiency labeling:China's tightened GB standards for household appliances are accelerating replacement cycles in domestic refrigerator OEM supply chains.
- Variable-speed inverter adoption:Precision cooling requirements in medical and laboratory applications are displacing fixed-speed architectures in premium equipment segments.
Market Restraints
- Copper and steel input volatility:Welded steel housings and motor windings face cost pressure from commodity price swings, squeezing margin pools for mid-tier manufacturers.
- Refrigerant chemistry uncertainty:The phasedown of R-134a and R-404A under EPA SNAP creates stranded inventory risk for compressors optimized to legacy thermal profiles.
- Substitution by scroll compressors:Large-capacity cold storage facilities above 20 kW cooling load are migrating to scroll technology, capping addressable market for reciprocating designs.
Strategic Opportunities
- India cold chain infrastructure:The country's National Cold Chain Grid expansion and FSSAI food safety mandates are opening demand for compliant hermetic units in warehousing and transport refrigeration.
- Natural refrigerant convergence:R-290 (propane) and R-600a (isobutane) compatibility is creating white space for compressor redesigns targeting European and Japanese OEM specifications.
- Direct-to-fleet aftermarket channels:Logistics operators are bypassing traditional distributor networks to source replacement compressors for refrigerated truck fleets, enabling margin capture by original manufacturers.
Industry Challenges
- Refrigerant-handling certification gaps:Technician training for flammable hydrocarbon systems lags deployment timelines in markets adopting R-290, delaying field service capacity.
- Cross-border certification divergence:Compressor designs must simultaneously satisfy EPA SNAP, EU F-Gas, and China GB testing protocols, fragmenting product platforms and extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hermetic Reciprocating Refrigerator Compressor Market |
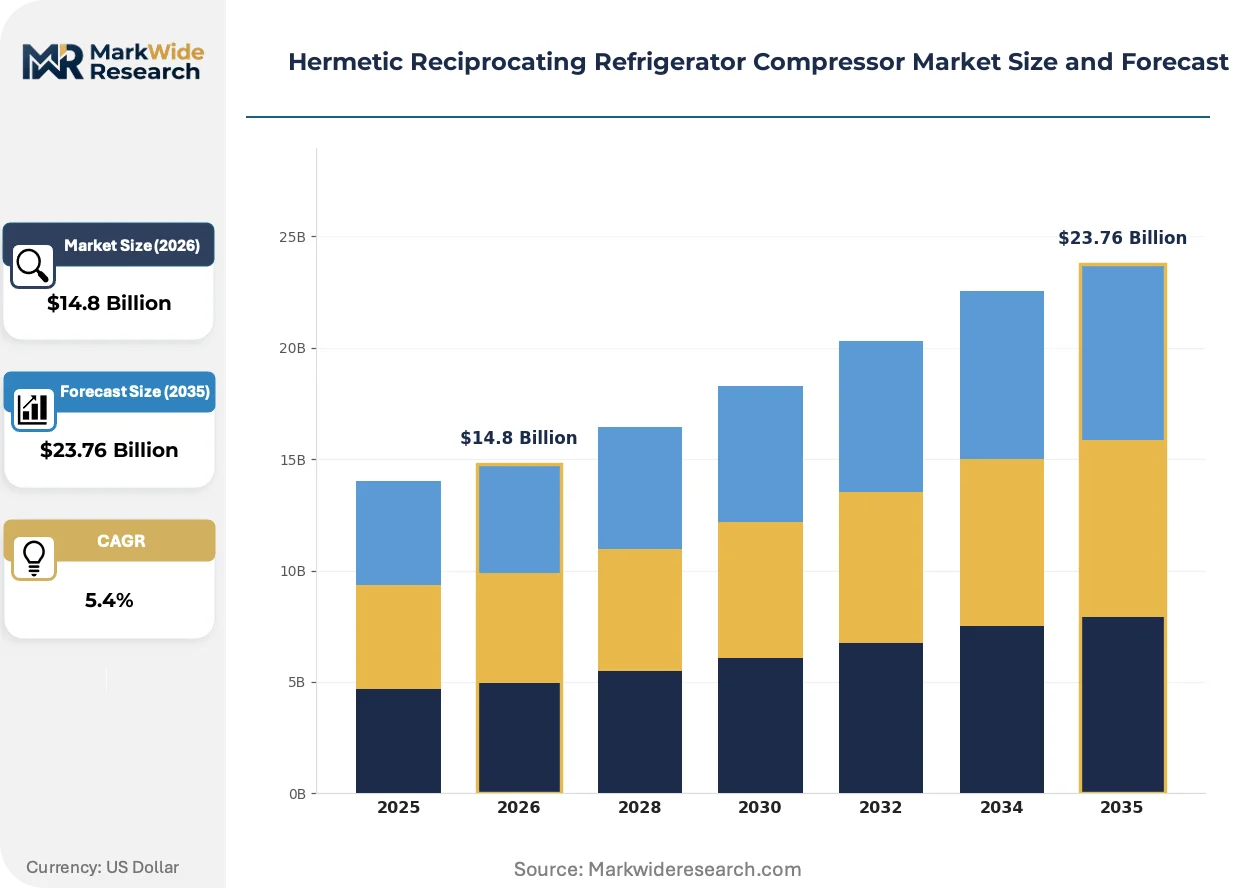
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Speed, Variable Speed, Low-Capacity, High-Capacity End User: Residential, Commercial, Industrial, OEMs Application: Refrigeration, Air Conditioning, Chillers, Cold Storage Technology: Vapor Compression, Direct Drive, Linear, Scroll |
| Companies Covered | Embraco, Secop, Huayi Compressor, LG Electronics, Samsung Electronics, Tecumseh Products Company, Donper, Qianjiang, Jiaxipera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hermetic Reciprocating Refrigerator Compressor Market Emerging Trajectories
Refrigerant chemistry transitions and motor-control electronics are converging to redefine compressor performance benchmarks, with efficiency mandates and supply chain regionalization acting as simultaneous forcing functions.
Permanent magnet synchronous motors with integrated inverter drives are consolidating as the dominant architecture for variable-speed hermetic compressors. Cold storage operators in Germany and Japan are specifying these units for precision temperature control in pharmaceutical distribution. The technology is consolidating supplier relationships around motor-winding specialists with captive controller production.
The EU F-Gas Regulation's 2030 phase-down targets for hydrofluorocarbons are compressing product development timelines for compressor OEMs serving European appliance manufacturers. Leak detection and containment protocols now add certification layers to unit designs. Residential and light commercial segments in France and Italy are seeing accelerated model turnover as OEMs preempt compliance deadlines.
Refrigerated logistics operators are unbundling compressor procurement from complete system purchases, establishing direct supplier relationships for aftermarket replacement and fleet standardization. Third-party cold storage providers in Brazil and Mexico are driving this pattern, consolidating purchasing power across multi-site operations. The shift pressures traditional HVAC-R distributor margins while rewarding manufacturers with regional parts depots and technical service networks.
Hermetic Reciprocating Refrigerator Compressor Market Segmentation
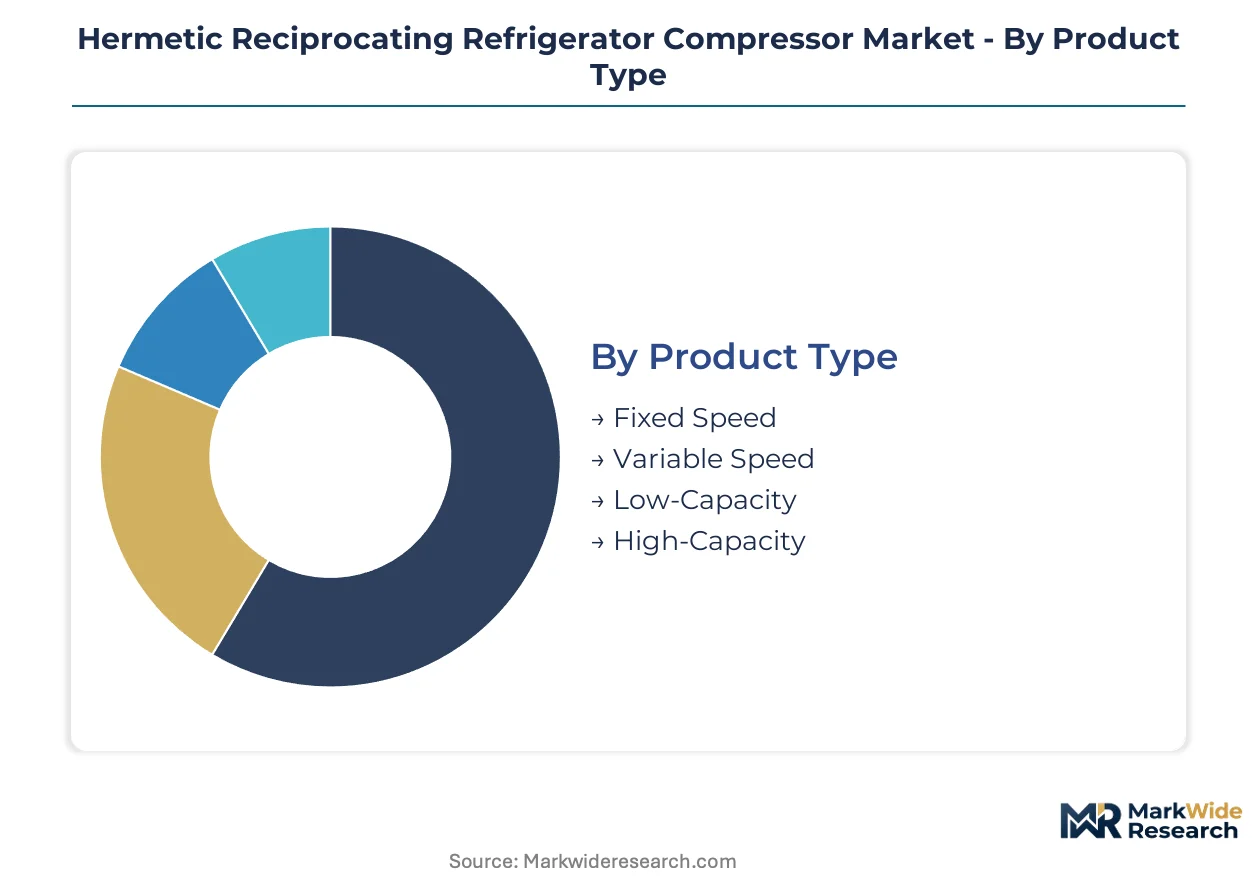
Hermetic reciprocating refrigerator compressor procurement patterns diverge sharply between cost-optimized residential replacement cycles and precision-engineered commercial installations. Segment boundaries increasingly blur as inverter technology penetrates downward and cold storage operators demand fleet standardization.
Product Type:
Volume concentration sits with fixed-speed units serving replacement markets, while premium capture concentrates in variable-speed architectures for OEM specification.
- Fixed Speed:These compressors operate at constant motor speed with on-off cycling, typically displacing 3-15 cc per revolution. Demand concentrates in China's domestic refrigerator OEM supply chains, where MIIT energy efficiency labeling forces redesigns but cost floors prevent inverter adoption. The segment absorbs commodity copper and steel volatility through thin margin pools.
- Variable Speed:Inverter-driven permanent magnet motors enable continuous modulation of refrigerant flow. Medical cold chain operators in Germany and Japan specify these units for pharmaceutical distribution, paying premium multiples for temperature stability within ±0.5°C. The technology consolidates supplier relationships around captive controller production.
- Low-Capacity:Units below 10 cc displacement dominate portable refrigeration and compact residential appliances across Southeast Asian manufacturing clusters.
- High-Capacity:Compressors exceeding 15 cc displacement serve commercial walk-in coolers and transport refrigeration, where India's National Cold Chain Grid expansion is pulling volume.
Mature deployment sits with fixed-speed units. Newer deployment is concentrated in variable-speed compressors.
End User:
Application requirements reshape procurement logic from standardized residential replacement to engineered commercial specifications.
- Residential:End-users purchase through appliance OEM channels with minimal technical involvement. China's state-backed subsidy programs for energy-efficient appliances accelerate replacement cycles in tier-2 and tier-3 cities, compressing product lifecycles toward seven-year averages.
- Commercial:Cold storage operators and food retail chains source compressors as capital equipment with total-cost-of-ownership analysis. Brazil's third-party logistics providers are unbundling compressor procurement from complete system purchases, establishing direct supplier relationships for multi-site fleet standardization.
- Industrial:Process cooling applications in chemical and pharmaceutical manufacturing require compressors with extended duty cycles and corrosion-resistant coatings.
- OEMs:Original equipment manufacturers in Mexico and Thailand integrate compressors into complete refrigeration systems for export markets, demanding volume pricing and technical co-development support.
Residential channels move the highest unit volumes. Commercial channels generate the steepest expansion trajectory as cold storage infrastructure retrofits accelerate.
Application:
Refrigerant chemistry transitions fragment application requirements between legacy system maintenance and new-build compliance specifications.
- Refrigeration:Household and commercial cooling applications dominate unit demand, with R-600a compatibility now mandatory for European residential OEM specifications.
- Air Conditioning:Hermetic reciprocating designs face displacement by rotary and scroll technologies in residential AC above 3 kW cooling load.
- Chillers:Process cooling and HVAC systems in institutional buildings specify hermetic units for noise-sensitive installations.
- Cold Storage:Distribution centers and refrigerated warehouses are retrofitting aging facilities with EPA SNAP-compliant refrigerant systems, pulling demand for higher-displacement hermetic units in the 15-20 cc range.
Refrigeration applications retain the largest installed base. Cold storage applications are gaining share fastest as logistics operators expand refrigerated footprints.
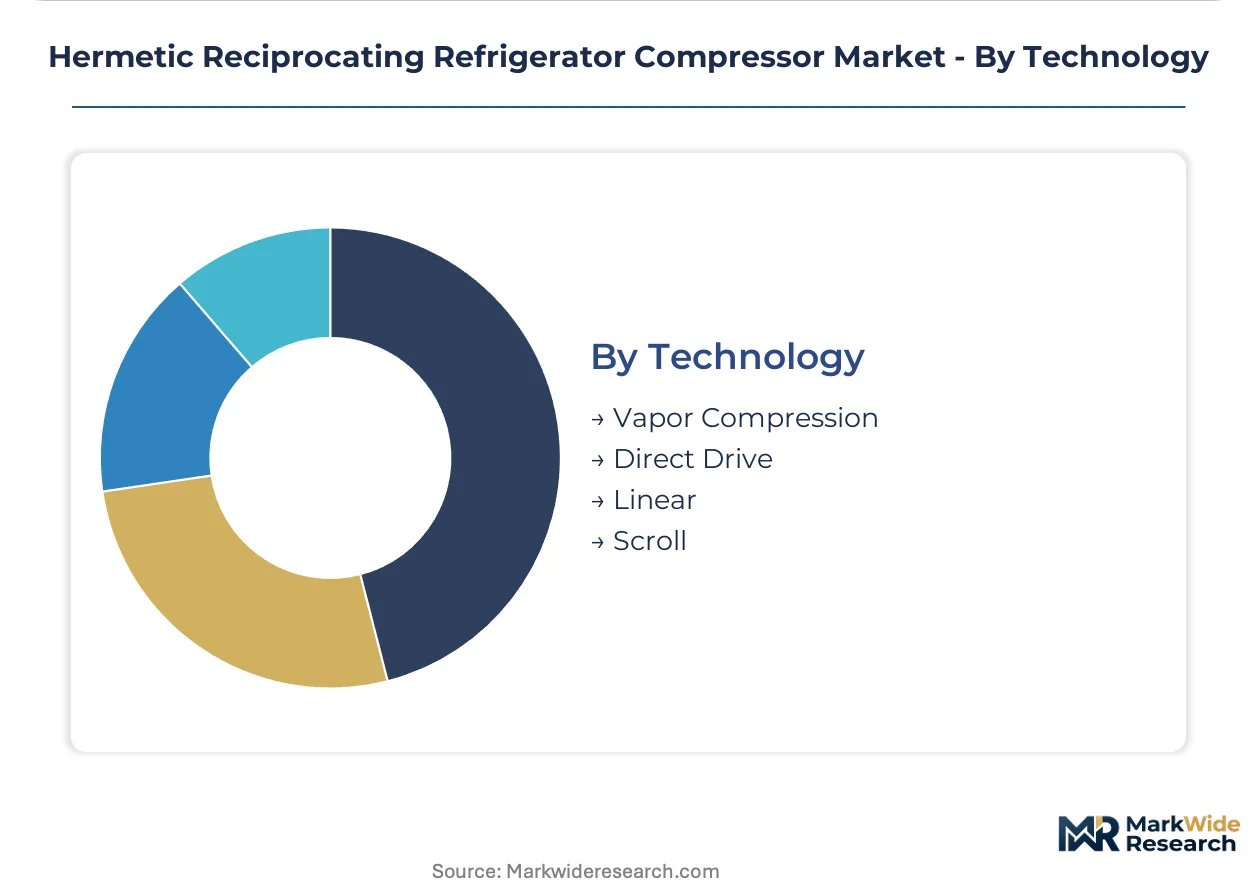
Technology:
Motor-winding capabilities and controller integration determine competitive positioning across technology architectures.
- Vapor Compression:The dominant thermodynamic cycle for hermetic reciprocating designs, using piston-driven crankshaft action to compress refrigerant vapor. EPA SNAP and EU F-Gas refrigerant mandates are forcing redesigns of valve plates and motor windings to accommodate lower-GWP alternatives.
- Direct Drive:Elimination of crankshaft mechanisms reduces mechanical losses and vibration signatures. Japanese laboratory equipment OEMs specify direct-drive linear compressors for precision temperature control in analytical instrumentation.
- Linear:Oil-free operation enables extended maintenance intervals in medical and semiconductor process cooling applications.
- Scroll:Though technically distinct from reciprocating architectures, scroll compressors compete for the same cold storage applications above 20 kW cooling load, capping addressable market for piston-based designs.
Vapor compression dominates current deployment. Direct drive and linear architectures are climbing the fastest in premium precision-cooling segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT-designated energy efficiency zones concentrate compressor manufacturing in coastal special economic corridors. State-backed subsidy programs accelerate replacement cycles across tier-2 and tier-3 cities. Domestic appliance OEM clusters in Guangdong and Zhejiang provinces pull volume for fixed-speed and variable-speed architectures alike.
United States
Food retail chains expand refrigerated distribution footprints across the Southeast and Midwest. The EPA SNAP program bans high-GWP refrigerants and mandates leak detection protocols for commercial installations. Compressor demand concentrates in Dallas-Fort Worth and Atlanta logistics corridors where cold storage operators retrofit aging facilities.
Germany
Pharmaceutical cold chain operators specify precision temperature control systems for biologics distribution. The EU F-Gas Regulation compresses product development timelines with 2030 phase-down targets for hydrofluorocarbons. Manufacturing and R&D activity clusters in Baden-Württemberg, where laboratory equipment OEMs source variable-speed hermetic units.
India
The National Cold Chain Grid expansion and FSSAI food safety mandates open demand for compliant hermetic compressors in warehousing and transport refrigeration. BIS energy efficiency labeling rules tighten compliance thresholds for imported and domestic equipment. Industrial corridors in Maharashtra and Gujarat attract cold storage infrastructure investment from third-party logistics providers.
Brazil
Third-party cold storage providers unbundle compressor procurement from complete system purchases, establishing direct supplier relationships for multi-site fleet standardization. ANVISA pharmaceutical storage regulations drive precision cooling requirements in São Paulo and Rio de Janeiro distribution hubs. Refrigerated logistics operators in the Southeast region consolidate purchasing power across regional networks.
Japan
Medical and laboratory applications displace fixed-speed architectures with inverter-driven permanent magnet motors for temperature stability within tight tolerances. METI energy efficiency standards accelerate model turnover in residential and light commercial segments. Manufacturing and technical development concentrates in the Chubu region around Nagoya, where precision equipment OEMs specify direct-drive linear compressor architectures.
Hermetic Reciprocating Refrigerator Compressor Market Vendor Landscape
Top-tier vendors anchor the premium specification segment, while mid-tier fabricators compete on volume pricing for replacement markets. The vendor base stratifies across three tiers: integrated motor-compressor specialists with captive controller production, scale-driven OEM suppliers serving domestic appliance manufacturers, and regional aftermarket distributors with technical service networks. Strategic archetypes include chemistry-capable redesign specialists, inverter-technology licensors, and fleet-standardization service providers. Competitive moves concentrate on backward integration into motor winding capabilities and geographic expansion through regional parts depot establishment.
Within the integrated specialist tier, Secop and Embraco exemplify archetypes positioned around precision cooling and geographic aftermarket dominance respectively. Huayi Compressor occupies a scale-driven position serving domestic refrigerator OEM supply chains across Asia. These three anchors represent contrasting competitive vectors: technology leadership through variable-speed architectures, channel control in Latin American replacement markets, and manufacturing scale under state-backed efficiency mandates.
| Leading Market Players |
|---|
| Embraco |
| Secop |
| Huayi Compressor |
| LG Electronics |
| Samsung Electronics |
| Tecumseh Products Company |
| Donper |
| Qianjiang |
| Jiaxipera |
| Others |
Supply Flow & Price Mechanics
China's domestic refrigerator OEM procurement clusters anchor pricing power in contract-based long-term offtake agreements, compressing spot-market liquidity and forcing mid-tier manufacturers toward volume-discount positioning. The concentration of state-backed efficiency mandates in Guangdong and Zhejiang provinces concentrates buyer leverage, squeezing margin pools for suppliers without captive motor-winding capabilities.
Pricing Analysis
Short lead-time premiums command pricing separation in the hermetic compressor trade, with OEMs paying multiples for guaranteed delivery windows against MIIT labeling deadlines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with ISO-compliant variable-speed units capturing margin premiums. Price erosion runs through fixed-speed residential replacement tiers as commodity copper and steel volatility transmits downstream. Cold storage operators exhibit lowest price sensitivity, prioritizing temperature stability specifications over unit economics.
Supply Chain Analysis
Skilled motor-winding technician availability constrains capacity expansion in China's coastal special economic corridors, particularly around Ningbo and Foshan manufacturing hubs. Supply concentrates in China, South Korea, and Thailand, with welded steel housings and permanent magnet materials drawing from concentrated metallurgical suppliers. Single-source vulnerability sits with rare-earth magnet feedstock from integrated upstream processors. Distribution runs through appliance OEM direct procurement and refrigerated logistics fleet standardization channels, bypassing traditional HVAC-R distributors in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hermetic reciprocating compressor market sits in a technology-transition phase, with variable-speed inverter architectures displacing fixed-speed legacy designs across precision cooling applications. Permanent magnet synchronous motors with integrated controller electronics are consolidating supplier relationships and fragmenting competitive positioning.
For Market Incumbents: Acquire captive controller production capabilities to anchor inverter technology positioning against Secop's precision cooling dominance. Backward integration into rare-earth magnet sourcing hedges supply disruption risk from China's export licensing protocols. Defend margin pools by establishing regional parts depots in São Paulo and Mumbai logistics corridors, preempting fleet-standardization bypass of distributor networks. For New Entrants and Emerging Players: Fleet-standardization service relationships offer the most penetrable channel wedge, targeting Brazil's third-party cold storage providers and India's National Cold Chain Grid contractors with direct technical support models. India's warehousing retrofit cycle presents white-space demand for EPA SNAP-compliant hermetic units, with BIS certification investment unlocking import substitution opportunities. Position around R-290 hydrocarbon compatibility as European OEMs accelerate F-Gas Regulation compliance timelines. For Investors and Strategic Acquirers: The window for entry favors motor-winding specialists with inverter controller integration, ahead of EU F-Gas 2030 phase-down enforcement tightening OEM specification requirements. Long-term viability centers on chemistry-capable redesign capabilities accommodating natural refrigerant transitions. Watch technician certification capacity for flammable hydrocarbon systems as the inflection signal—training program deployment rates will determine field service scalability and aftermarket capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Winding | Captive production of permanent magnet windings insulates margin pools from rare-earth price volatility. |
| Regional Parts Depot Establishment | São Paulo and Mumbai depots enable direct fleet-standardization relationships with logistics operators. |
| R-290 Compatibility Certification | EU F-Gas Regulation compliance unlocks specification access to German and French appliance OEMs. |
| Technician Training Program Deployment | Flammable refrigerant handling certification closes field service capacity gaps delaying R-290 adoption. |
| Inverter Controller Platform Development | Integrated variable-speed electronics consolidate supplier relationships in medical cold chain segments. |
Methodological Framework
Independent corroboration across compressor OEM procurement directors, cold storage facility engineers, and motor-winding plant managers underwrites the qualitative findings in this study. Primary fieldwork with appliance manufacturer supply chain leads and refrigerated logistics fleet operators combined with secondary validation from MIIT efficiency labeling disclosures, EPA SNAP program rulings, and EU F-Gas Regulation implementation guidance. Trade data from China's General Administration of Customs and compressor import records from India's DGFT anchored volume triangulation, with bottom-up unit economics cross-referenced against top-down market sizing.
Rate-of-change decomposition across product type, application, cooling capacity tier, and regional regulatory cluster structured the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by replacement cycle timing and efficiency mandate enforcement schedules. Modeled inputs incorporated refrigerant chemistry transition timelines, cold storage infrastructure investment pipelines, and motor-control electronics adoption curves in medical and laboratory equipment specifications.
Caveats apply where refrigerant-handling certification delays, copper price volatility spikes, or cross-border testing protocol divergence could materially shift the outlook. Forecasts embed assumptions regarding MIIT labeling enforcement consistency and EU F-Gas phase-down adherence without contingency for regulatory suspension or acceleration. Material deviation in technician training deployment rates or rare-earth export licensing protocols warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Medium Voltage Transformer Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
Smart Heater Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
High Voltage Porcelain Bushing Market
Electrical Equipment
United States Busbar Market
Electrical Equipment
Global Electric Plugs and Sockets Market
Electrical Equipment
Europe Busbar Market
Electrical Equipment
Transient Protection Device Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Heat Shrink Terminations Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Electric Enclosure Market
Electrical Equipment
United States Electric Insulator Market
Electrical Equipment
PDU Power Cords Market