
 Insulation Testing Instrument Market | 2026-2036
Insulation Testing Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Insulation Testing Instrument Market Outlook
Skilled electrical technician shortages across developed economies is unwinding maintenance backlogs and forcing asset owners toward automated diagnostic platforms. Megger leverages decades of analog heritage to sustain trust among utility procurement teams. Fluke Corporation anchors its position through dense distribution networks in North American industrial corridors. HIOKI E.E. CORPORATION specializes in high-precision digital architectures that dominate Japanese manufacturing quality protocols.
Insulation testing instruments measure electrical resistance between conductive parts and insulating materials to detect degradation before catastrophic failure, typically applying test voltages from 50 V to 15 kV depending on equipment class. Megohmmeters remain the mature revenue backbone while smart testers with Bluetooth logging and cloud connectivity represent the fastest-expanding margin pool. Digital technology segments command premium positioning over analog equivalents, particularly in renewable energy applications where remote monitoring reduces turbine downtime. Multi-functional testers are displacing single-purpose units in HVAC contractor toolkits as building electrification codes tighten.
FDA oversight of medical-grade electrical safety, IEC 61543 live-working equipment standards, and OSHA electrical safety requirements collectively mandate periodic insulation verification across healthcare, utility, and industrial installations. CE marking under EU low-voltage directives shapes market access for Asian manufacturers exporting into European power distribution sectors. Stakeholders must weigh captive calibration service investments against third-party laboratory partnerships as regulatory traceability requirements tighten.
Market Dynamics
Grid modernization mandates across Southeast Asian electrical utilities are compressing replacement cycles and forcing procurement teams toward multi-functional diagnostic platforms that reduce technician deployment costs.
Growth Catalysts
- IEC 61543 Safety Standards:Stricter live-working equipment requirements across European power distribution sectors are accelerating scheduled replacement of legacy analog testers. Utility procurement teams now prioritize certified digital architectures.
- India Transmission Upgrades:Central Electricity Authority directives for grid reliability are concentrating demand for high-voltage megohmmeters in state-owned transmission infrastructure projects. Domestic manufacturing incentives amplify local sourcing.
- Bluetooth Cloud Connectivity:Smart testers with wireless logging capabilities are capturing premium positioning in renewable energy maintenance contracts. Remote turbine monitoring reduces downtime for offshore wind operators.
Market Restraints
- Semiconductor Component Volatility:Precision ADC chips and isolated power modules face supply concentration in East Asian foundries. Lead times for 24-bit sigma-delta converters now stretch beyond 26 weeks.
- Analog Heritage Lock-In:Utility procurement specifications in mature markets still reference MIL-STD-202G test procedures designed for electromechanical instruments. Digital-native architectures struggle against entrenched trust patterns.
- Portable Multimeter Substitution:General-purpose electrical testers with insulation resistance functions are eroding addressable market for dedicated megohmmeters in HVAC contractor segments. Price compression follows feature convergence.
Strategic Opportunities
- Vietnam Grid Expansion:National Power Development Plan VIII targets 150,000 kilometers of new transmission lines by 2030. Local calibration service partnerships unlock preferred vendor status for foreign instrument manufacturers.
- Medical Equipment Safety Mandates:FDA 21 CFR Part 820 quality system regulations for electromedical devices create recurring revenue streams from hospital biomedical engineering departments. Patient leakage current testing integrates with insulation verification.
- AI-Assisted Diagnostics:Machine learning algorithms analyzing historical resistance trending data are converging with handheld tester hardware. Predictive maintenance subscriptions transform capital equipment sales into recurring service models.
Industry Challenges
- Calibration Technician Scarcity:Accredited high-voltage metrology labs require specialized training in traceable resistance standards. Aging workforce in developed economies constrains service network expansion.
- Legacy System Integration:Utility asset management platforms built on proprietary SCADA protocols resist seamless data ingestion from Bluetooth-enabled field instruments. API development consumes disproportionate R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulation Testing Instrument Market |
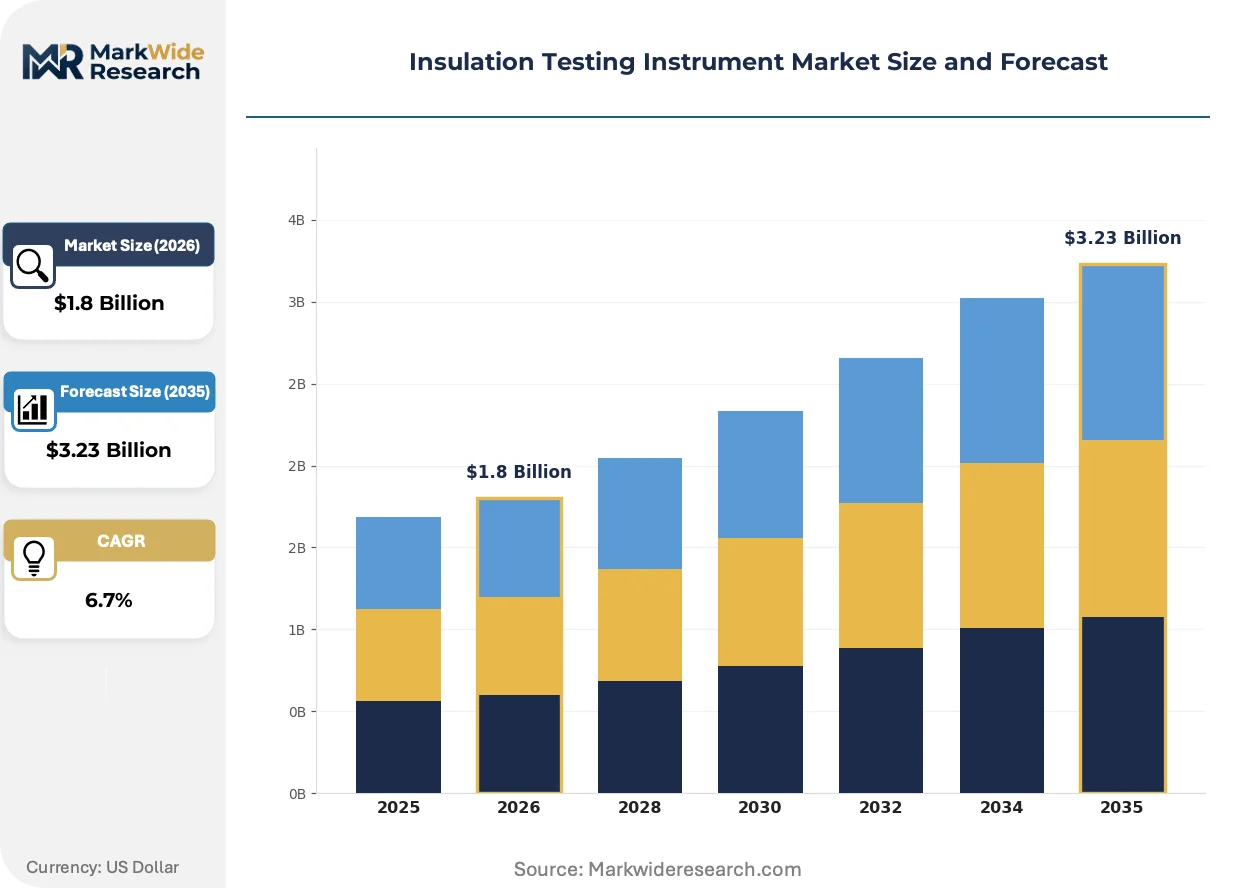
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation Resistance Testers, Megohmmeters, Multi-functional Testers, Capacitance Testers Technology: Analog, Digital, Wireless, Smart End User: Electrical Utilities, Manufacturing, Automotive, Aerospace Application: HVAC, Power Distribution, Industrial Equipment, Renewable Energy |
| Companies Covered | Megger, Fluke Corporation, HIOKI E.E. CORPORATION, Meco Instruments Pvt. Ltd., Motwane, Chauvin Arnoux, Eaton, Yokogawa Electric Corporation, SONEL S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulation Testing Instrument Market Strategic Shifts
Digital architectures are compressing form factors while expanding functional integration, reshaping how maintenance teams deploy field diagnostic equipment across distributed infrastructure assets.
Silicon carbide-based isolated DC-DC converters are miniaturizing high-voltage test source electronics previously requiring oil-filled transformers. Offshore wind technicians now carry palm-sized 10 kV testers that weigh under 800 grams. This form factor reduction is miniaturizing maintenance crew toolkits and enabling single-technician turbine blade inspections that previously demanded two-person teams.
EU F-Gas Regulation phase-down schedules for SF6 switchgear are mandating accelerated inspection protocols for gas-insulated substations. Insulation resistance verification intervals compress from annual to quarterly cycles in German transmission zones. Manufacturers are responding with rapid-charge battery systems supporting 200+ tests per field deployment.
Building electrification codes in California and New York are tightening contractor certification requirements for heat pump installations. HVAC service aggregators now specify brand-locked tester ecosystems that synchronize diagnostic data with customer-facing service reports. This vertical integration of field instrumentation with service documentation platforms concentrates purchasing authority at regional distributor level.
Insulation Testing Instrument Market Segmentation
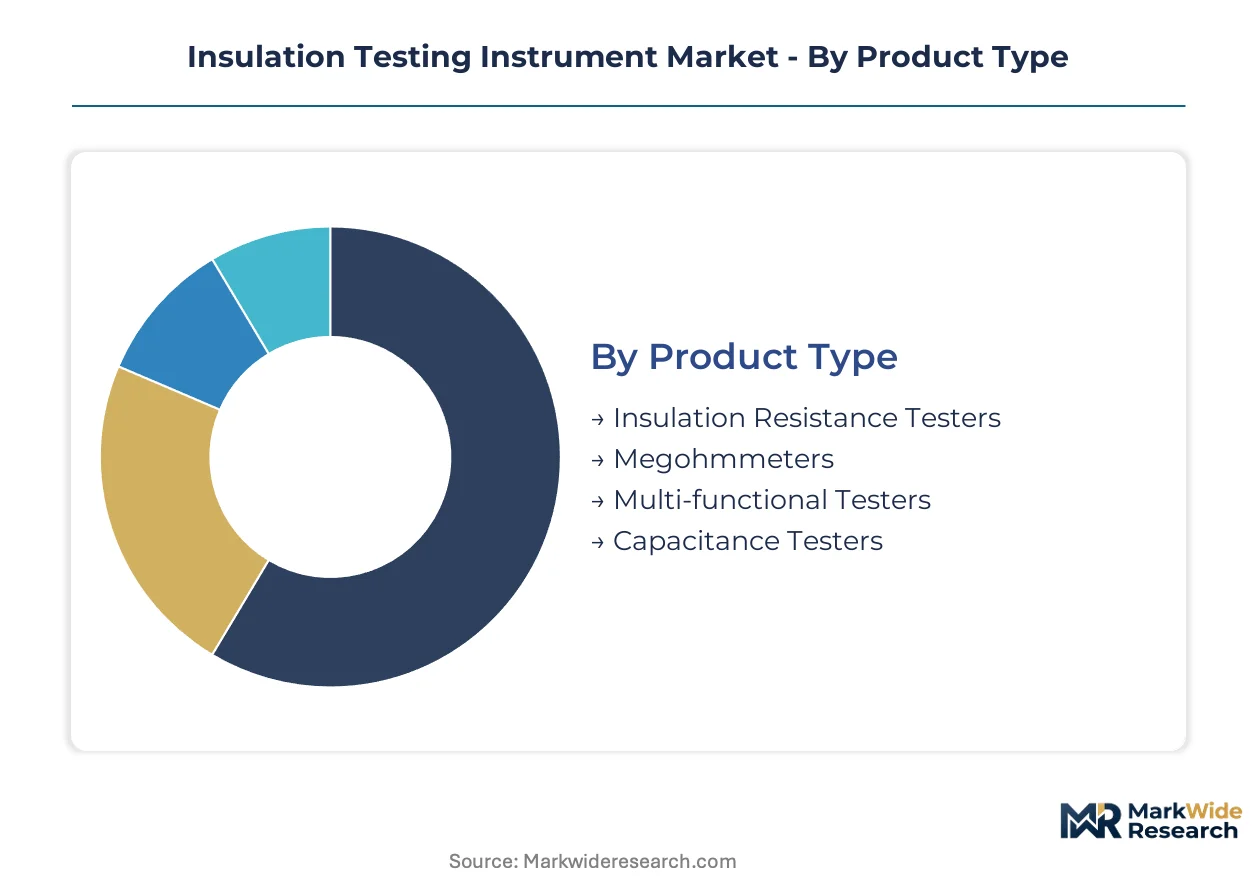
Segmentation in the insulation testing instrument market reveals where portable multimeters and general-purpose electrical testers exert the strongest substitution pressure. Procurement teams prioritize segments that resist feature convergence through specialized high-voltage architectures or regulatory-mandated precision.
Product Type:
Multi-functional testers face the most acute substitution threat from general-purpose electrical testers adding insulation resistance capabilities, while dedicated high-voltage instruments maintain defensible positions through certification requirements.
- Insulation Resistance Testers:Portable instruments applying test voltages from 50 V to 15 kV to measure resistance between conductive parts and insulating materials. Demand concentrates in German transmission zones where quarterly verification intervals for SF6 switchgear replacement create recurring instrument deployment.
- Megohmmeters:Electromechanical and electronic instruments specifically designed for high-resistance measurement, representing the mature revenue backbone of the category. India's Central Electricity Authority transmission infrastructure upgrades concentrate procurement for high-voltage digital architectures replacing legacy analog units.
- Multi-functional Testers:Combined instruments integrating insulation testing with continuity, loop impedance, and RCD testing functions. HVAC contractor segments in California and New York show brand-locked ecosystem preferences.
- Capacitance Testers:Specialized instruments measuring capacitive elements in motor windings and cable installations. Japanese manufacturing quality protocols drive precision requirements.
Megohmmeters retain volume leadership; multi-functional testers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium digital architectures from economy analog alternatives, with wireless connectivity commanding intermediate positioning.
- Analog:Electromechanical instruments with pointer-based displays, sustained by utility procurement specifications referencing MIL-STD-202G test procedures. Mature market trust patterns resist displacement despite functional limitations.
- Digital:Microprocessor-based instruments with LCD displays and data logging capabilities. IEC 61543 safety standards for live-working equipment accelerate scheduled replacement across European power distribution sectors.
- Wireless:Bluetooth-enabled instruments transmitting measurement data to mobile devices. Offshore wind operators in the North Sea reduce turbine downtime through remote monitoring integration.
- Smart:Cloud-connected platforms with predictive analytics and machine learning diagnostics. AI-assisted resistance trending transforms capital sales into recurring service subscriptions.
Digital architectures dominate revenue; smart connectivity gains share fastest.
End User:
Application-specific regulatory mandates create divergent procurement patterns across customer types, with medical and aerospace segments demanding traceable calibration chains.
- Electrical Utilities:Grid operators performing preventive maintenance on transmission and distribution infrastructure. Southeast Asian modernization programs compress replacement cycles toward multi-functional platforms.
- Manufacturing:Industrial facilities verifying motor winding integrity and cable insulation. Japanese automotive production lines specify HIOKI precision protocols.
- Automotive:EV battery pack and charging infrastructure testing. High-voltage safety requirements in electric vehicle service bays drive dedicated instrument procurement.
- Aerospace:Aircraft wiring harness and avionics insulation verification. FAA oversight mandates periodic verification with traceable metrology chains.
Electrical utilities anchor volume demand; aerospace segments climb fastest on electrification tailwinds.
Application:
Geographic concentration of end-use activity shapes regional product preferences, with renewable energy clusters driving smart instrument adoption.
- HVAC:Heat pump and building electrification system verification. California and New York contractor certification tightening concentrates brand-locked ecosystem purchasing.
- Power Distribution:Substations, switchgear, and underground cable testing. Vietnam's National Power Development Plan VIII targets 150,000 kilometers of new transmission lines.
- Industrial Equipment:Motor, generator, and transformer maintenance. Manufacturing quality protocols in Japan and Germany specify precision digital architectures.
- Renewable Energy:Wind turbine and solar inverter insulation verification. Offshore wind technicians deploy palm-sized 10 kV silicon carbide instruments for single-person blade inspections.
Power distribution retains installed base dominance; renewable energy shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA directives in India anchor the dominant geography for transmission infrastructure procurement, while IEC 61543 standards reshape European replacement cycles and Southeast Asian utilities compress modernization timelines.
India
State-owned transmission projects concentrate demand for high-voltage digital architectures replacing legacy analog units. Central Electricity Authority grid reliability mandates accelerate procurement cycles across state electricity boards. Domestic manufacturing incentives under the PLI scheme amplify local sourcing from Gujarat and Maharashtra industrial corridors.
Germany
EU F-Gas Regulation phase-down schedules compress SF6 switchgear inspection intervals from annual to quarterly cycles. CE marking under low-voltage directives shapes certification requirements for distribution network equipment. Transmission zones in North Rhine-Westphalia deploy rapid-charge battery systems supporting 200-plus tests per field deployment.
United States
OSHA electrical safety requirements mandate periodic insulation verification across industrial installations. FDA 21 CFR Part 820 quality system regulations create recurring revenue streams from hospital biomedical engineering departments. California and New York building electrification codes tighten contractor certification requirements for heat pump installations.
Vietnam
National Power Development Plan VIII targets 150,000 kilometers of new transmission lines by 2030. Local calibration service partnerships unlock preferred vendor status for foreign instrument manufacturers. Grid expansion in the Northern Key Economic Region concentrates procurement for multi-functional diagnostic platforms.
Japan
METI industrial standards drive precision requirements for manufacturing quality protocols. HIOKI E.E. CORPORATION anchors domestic high-precision digital architectures serving automotive production lines. Kansai and Chubu industrial clusters specify traceable metrology chains for motor winding integrity verification.
Insulation Testing Instrument Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around heritage analog manufacturers defending utility relationships and digital-native entrants capturing renewable energy contracts. Three archetypes dominate: legacy electromechanical specialists leveraging MIL-STD certification trust, precision digital architects serving manufacturing quality protocols, and smart connectivity platforms targeting predictive maintenance subscriptions. Competitive moves concentrate on strategic partnerships for calibration service networks and portfolio diversification into multi-functional tester ecosystems.
Within the heritage specialist tier, Megger represents decades of analog instrument trust among utility procurement teams. Fluke Corporation exemplifies dense distribution network positioning across North American industrial corridors. HIOKI E.E. CORPORATION occupies a precision digital architecture position serving Japanese manufacturing quality protocols.
| Leading Market Players |
|---|
| Megger |
| Fluke Corporation |
| HIOKI E.E. CORPORATION |
| Meco Instruments Pvt. Ltd. |
| Motwane |
| Chauvin Arnoux |
| Eaton |
| Yokogawa Electric Corporation |
| SONEL S.A. |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for 24-bit sigma-delta converters concentrate procurement power among East Asian foundry customers and compress margin structures for instrument assemblers lacking volume commitments or captive component stocks.
Pricing Analysis
Asian-manufactured digital architectures command 15-25% discounts versus European equivalents in Indian transmission tenders. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61543-certified smart testers from analog heritage units and portable multimeter substitutes. Cost compression in the multi-functional tester tier intensifies as HVAC contractors consolidate purchases through brand-locked distributor ecosystems. State electricity boards in India exhibit highest price sensitivity; aerospace maintenance depots with FAA traceability mandates show lowest.
Supply Chain Analysis
Port congestion at Shanghai-Ningbo and container availability constraints on Asia-Europe lanes elevate inbound logistics costs for precision ADC chips and isolated power modules. Component manufacturing concentrates in Taiwan, South Korea, and Japan; final assembly clusters in China and Vietnam for export markets. Semiconductor supply rests on silicon carbide substrate availability and precision resistor networks. Single-source vulnerability persists for 24-bit sigma-delta converter foundries. Distribution runs through authorized distributor networks with calibration service bundling in developed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as grid modernization across Southeast Asia and renewable energy expansion create specialized procurement niches that resist commoditization.
For Market Incumbents: Secure calibration service network density in Vietnam and India before local laboratory partnerships lock out foreign instrument manufacturers. Deepen backward integration into precision resistor manufacturing to offset semiconductor foundry pricing power. Defend utility relationships by accelerating IEC 61543 certification timelines ahead of analog heritage competitors.
For New Entrants and Emerging Players: Differentiate on AI-assisted diagnostic platforms that transform capital equipment sales into predictive maintenance subscriptions. Target offshore wind operators in the North Sea with palm-sized silicon carbide testers enabling single-technician blade inspections. Pursue white-label partnerships with HVAC service aggregators in California and New York seeking brand-locked ecosystem integration.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with dormant electrical testing divisions lacking smart connectivity roadmaps. Long-term viability hinges on recurring service revenue attachment rates rather than hardware shipment volumes. Watch for inflection when utility procurement specifications drop MIL-STD-202G references in favor of digital-native architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Local laboratory partnerships in Vietnam unlock preferred vendor status under National Power Development Plan VIII procurement. |
| AI-Assisted Diagnostic Platform Launch | Machine learning resistance trending transforms Megger and Fluke hardware sales into recurring predictive maintenance subscriptions. |
| Silicon Carbide Miniaturization Investment | Palm-sized 10 kV testers reduce offshore wind technician deployment costs and enable single-person turbine blade inspections. |
| IEC 61543 Certification Acceleration | Digital architecture certification ahead of analog heritage competitors captures European utility replacement cycles. |
| HVAC Ecosystem Integration Partnership | Brand-locked data synchronization with California and New York contractor service platforms concentrates purchasing authority. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of utility procurement databases, IEC standard documentation, and SEC filings from listed instrument manufacturers. Primary interviews engaged utility maintenance directors, biomedical engineering managers, HVAC contractor procurement leads, and aftermarket service heads across India, Germany, the United States, Vietnam, and Japan. Secondary sources included CEA directive filings, EU F-Gas Regulation implementation reports, FDA 21 CFR Part 820 guidance documents, and METI industrial standard publications. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled span product type, technology architecture, end-user vertical, and application across the analysis window. Forecast outputs derive from instrument shipment volumes, replacement cycle compression rates, and regulatory mandate implementation timelines. Renewable energy capacity additions and grid modernization expenditure trajectories inform demand elasticity assumptions. CAGRs reflect weighted average growth across country-level projections with regulatory enforcement probability adjustments.
The analysis sits within stated boundaries; outcomes outside continued IEC 61543 enforcement, semiconductor supply normalization, or sustained transmission infrastructure investment would require recalibration. Forecasts reflect documented assumptions regarding skilled technician availability, calibration laboratory accreditation capacity, and Bluetooth-enabled instrument adoption curves in offshore wind maintenance contracts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Pump Testers Market
Test and Measurement
Fluorometers Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Uniaxial Tester Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
LCR Meter Market