
 North America Bus Market | 2026-2036
North America Bus Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bus Market Insights
Zero-emission certification tiers is unwinding legacy procurement patterns across the North America Bus Market. New Flyer leverages its integrated battery-electric platform to dominate municipal transit contracts in major Canadian and U.S. cities. Blue Bird Corporation anchors the school bus segment with dedicated electric manufacturing capacity in Georgia. Lion Electric specializes in purpose-built electric chassis for medium-duty bus applications.
A bus is a road vehicle designed to carry multiple passengers on a fixed route or charter basis, typically constructed with a steel or aluminum frame, diesel or electric powertrain, and passenger capacities ranging from ten to over one hundred seats, serving public transit, education, and intercity mobility needs. City bus configurations lead volume demand as metropolitan transit authorities modernize aging fleets, while electric fuel type represents the fastest-expanding category driven by total cost of ownership improvements and charging infrastructure deployment. School services application maintains stable replacement cycles supported by federal and state pupil transportation mandates.
The EPA, NHTSA, and Transport Canada shape product standards through emissions thresholds, safety compliance mandates, and cross-border manufacturing rules that determine market access for suppliers. California Air Resources Board regulations function as de facto national standards for zero-emission bus deployment timelines. Stakeholders must monitor state-level funding allocations and utility rate structures as these determine the pace of fleet conversion and charging infrastructure buildout.
Market Dynamics
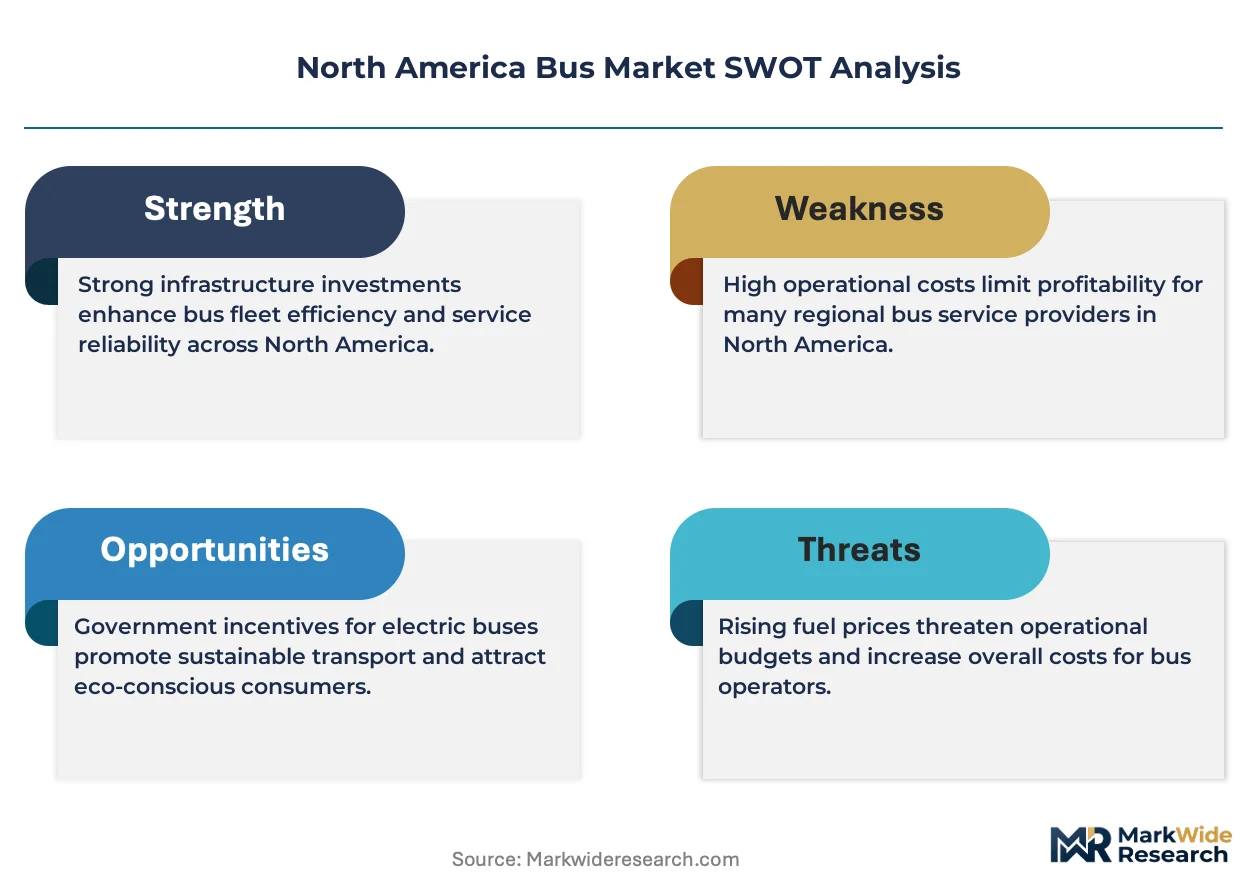
Zero-emission fleet mandates are compressing diesel bus replacement cycles across U.S. and Canadian transit authorities, forcing capital reallocation toward charging infrastructure and battery-electric platforms before total cost parity is achieved.
Growth Catalysts
- EPA Clean School Bus Program:Federal rebate structures covering up to 100% of electric school bus costs are accelerating procurement timelines in disadvantaged districts across the United States.
- California Advanced Clean Trucks:This regulation mandates escalating zero-emission sales quotas for medium and heavy-duty vehicles, creating binding compliance obligations for fleet operators through 2035.
- Texas grid-scale charging corridors:Utility-backed depot electrification projects along I-35 and I-10 are enabling intercity electric coach viability where range anxiety previously blocked adoption.
Market Restraints
- Lithium-ion cell supply concentration:Cathode active material processing clusters in East Asia create import dependency and price volatility exposure for North American bus manufacturers.
- Copper busbar cost inflation:Electrified powertrains require 3-4x copper intensity versus diesel equivalents, amplifying input cost pressure during commodity supercycles.
- Utility interconnection queues:Depot charging projects face 18-36 month grid connection delays in Ontario and California, stretching fleet conversion timelines beyond procurement schedules.
Strategic Opportunities
- V2G revenue stacking:Bidirectional charging capabilities allow transit agencies to sell grid services, offsetting capital costs through FERC Order 2222-enabled wholesale market participation.
- Autonomous shuttle corridors:Mixed-traffic autonomous bus pilots in Texas and Arizona are creating first-mover positions for purpose-built low-speed electric platforms.
- Indigenous community transit:Remote First Nations reserves in Canada represent unserved demand for solar-battery microgrid-dependent electric bus services outside utility grid reach.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack certified EV specialists, forcing reliance on OEM service contracts that inflate operating expenditures.
- Depot civil works coordination:Underground conduit installation and transformer upgrades require synchronized utility, municipal permitting, and construction timelines that frequently misalign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bus Market |
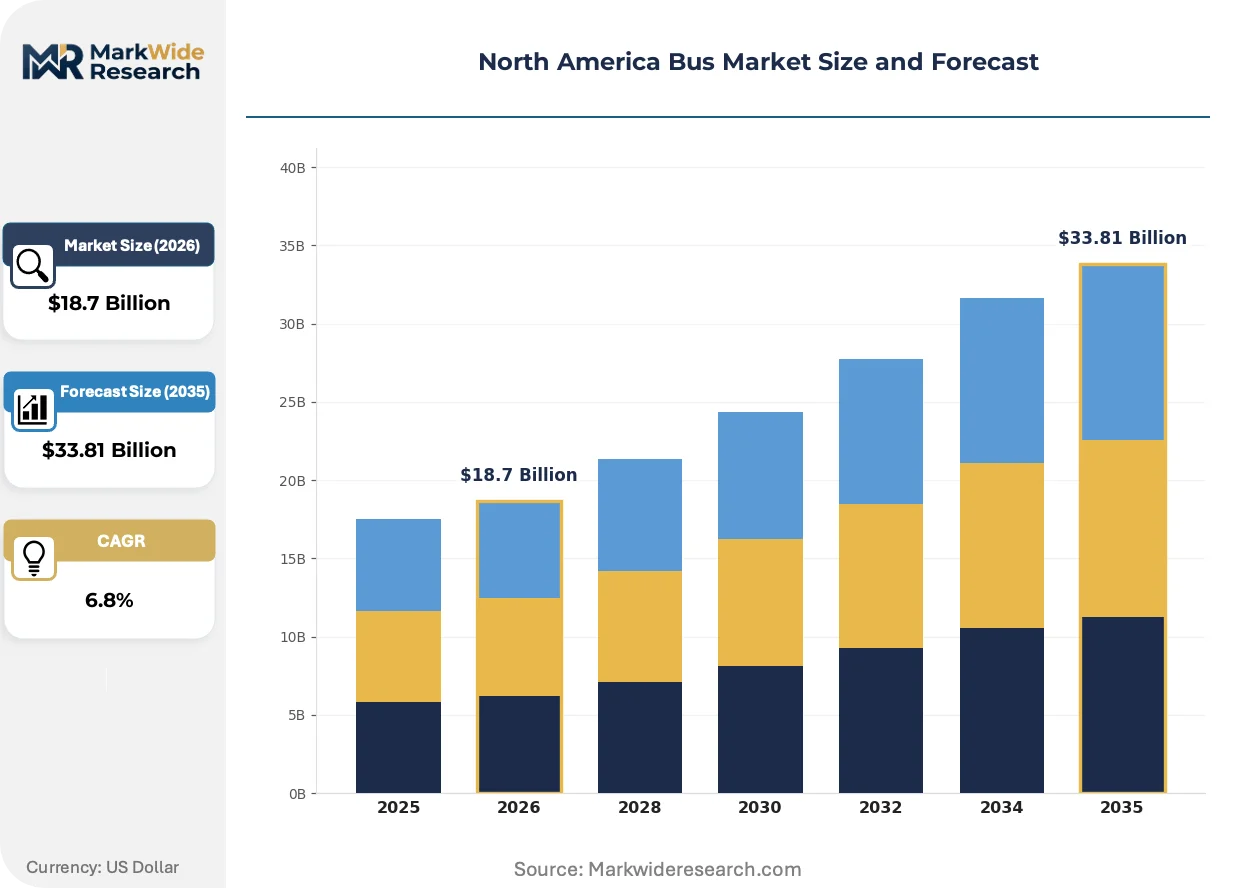
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: City Bus, Intercity Bus, School Bus, Coach Bus Fuel Type: Diesel, Electric, CNG, Hybrid Application: Public Transport, Private Transportation, Tourism, School Services Size: Standard, Maxi, Mini, Double Decker |
| Companies Covered | New Flyer, Blue Bird Corporation, Gillig, Lion Electric, Thomas Built Buses, Daimler Buses, Nova Bus, Proterra, GreenPower Motor, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bus Market Trends and Innovations
Battery pack architecture standardization is collapsing proprietary system boundaries that previously locked transit agencies into single-source supplier relationships. Three developments are compressing industry structure.
Modular battery skateboard platforms are decomposing the traditional integrated chassis-body manufacturing model. Transit agencies in California and Ontario are specifying swappable battery configurations that separate cell procurement from vehicle assembly. This architecture is decomposing incumbent supplier power by enabling multi-source battery sourcing and third-party refurbishment services.
The EPA's greenhouse gas Phase 3 standards for heavy-duty vehicles are tightening CO2 intensity thresholds through 2032. Manufacturers must deploy battery-electric or fuel-cell powertrains to achieve fleet-average compliance. School bus and transit bus categories face the most stringent subcategory limits, driving platform redesign toward dedicated electric architectures rather than diesel retrofit conversions.
Performance-based service contracting is displacing traditional capital acquisition in municipal transit. Agencies in Texas and Georgia are signing 10-15 year availability agreements where contractors guarantee vehicle uptime and energy costs per mile. This transfers residual value risk to manufacturers while demanding predictive maintenance capabilities and charging infrastructure ownership.
North America Bus Market Segmentation
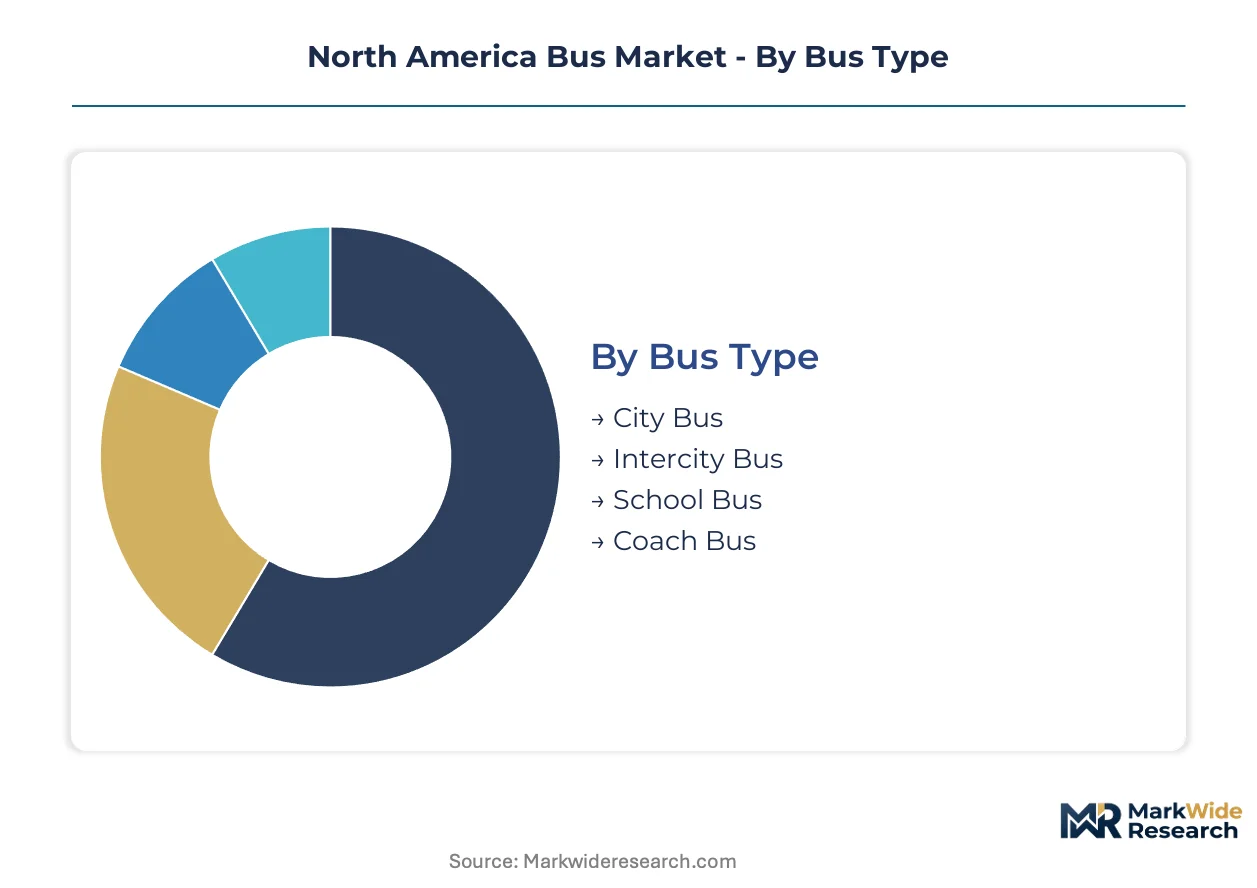
Segmentation in the North America Bus Market reveals where capital flows concentrate and where regulatory pressure is reshaping procurement patterns. Transit agencies, school districts, and private operators allocate budgets across distinct vehicle configurations based on route profiles, passenger volumes, and compliance obligations.
Bus Type:
Substitution pressure from zero-emission mandates weighs heaviest on segments with the shortest duty cycles and highest daily mileage, compressing replacement timelines for diesel-dependent configurations.
- City Bus:Urban transit authorities specify low-floor, high-capacity platforms with frequent-stop durability ratings. California and Ontario agencies prioritize battery-electric variants with 250+ mile daily range capability to satisfy CARB compliance deadlines.
- Intercity Bus:Operators along Texas I-35 and I-10 corridors test electric coaches with megawatt charging at terminal depots, though diesel still dominates routes exceeding 300 miles between stops.
- School Bus:Purpose-built Type C and Type D configurations with reinforced passenger compartments serve K-12 pupil transportation mandates.
- Coach Bus:Premium long-distance configurations emphasize luggage capacity and reclining seating for private charter and scheduled line-haul services.
City Bus retains volume leadership; Electric variants within this category hold the steepest expansion curve.
Fuel Type:
Cost tier stratification separates capital-intensive electric platforms from lower-first-cost diesel alternatives, with total cost of ownership calculations determining procurement viability across fleet sizes.
- Diesel:Compression-ignition powertrains with EPA Tier 4 Final emissions compliance dominate rural school districts and long-haul coach operations where refueling infrastructure limits electric feasibility.
- Electric:Battery-electric buses with lithium-iron-phosphate or nickel-manganese-cobalt chemistry require depot charging infrastructure and utility interconnection upgrades. Texas and California utilities offer demand-charge mitigation programs to improve operating cost economics.
- CNG:Compressed natural gas configurations serve California transit agencies seeking interim emissions reductions ahead of full electrification mandates.
- Hybrid:Diesel-electric parallel architectures capture regenerative braking energy for urban stop-and-go duty cycles, though procurement has plateaued as battery-electric ranges improve.
Diesel maintains fleet share dominance; Electric platforms are gaining share fastest as total cost of ownership converges with diesel parity.
Application:
Customer type segmentation distinguishes publicly funded procurement with multi-year replacement cycles from private operator decisions driven by route profitability and asset utilization rates.
- Public Transport:Municipal transit authorities in Toronto, Los Angeles, and New York specify 40-foot and 60-foot articulated buses with ADA-compliant accessibility features and real-time passenger information systems.
- Private Transportation:Corporate shuttle operators and airport ground transport services prioritize passenger comfort and brand presentation over minimum specification compliance.
- Tourism:Open-top double-decker and premium coach configurations serve sightseeing markets in San Francisco, Washington DC, and Niagara Falls with seasonal demand fluctuations.
- School Services:Federal and state pupil transportation mandates create stable replacement demand tied to school district budget cycles and EPA Clean School Bus Program rebate eligibility.
Public Transport commands procurement volume; Private Transportation shows the most rapid adoption of premium electric configurations.
Size:
Application context determines size selection, with route geometry and passenger load profiles dictating dimensional requirements across metropolitan, suburban, and specialized service environments.
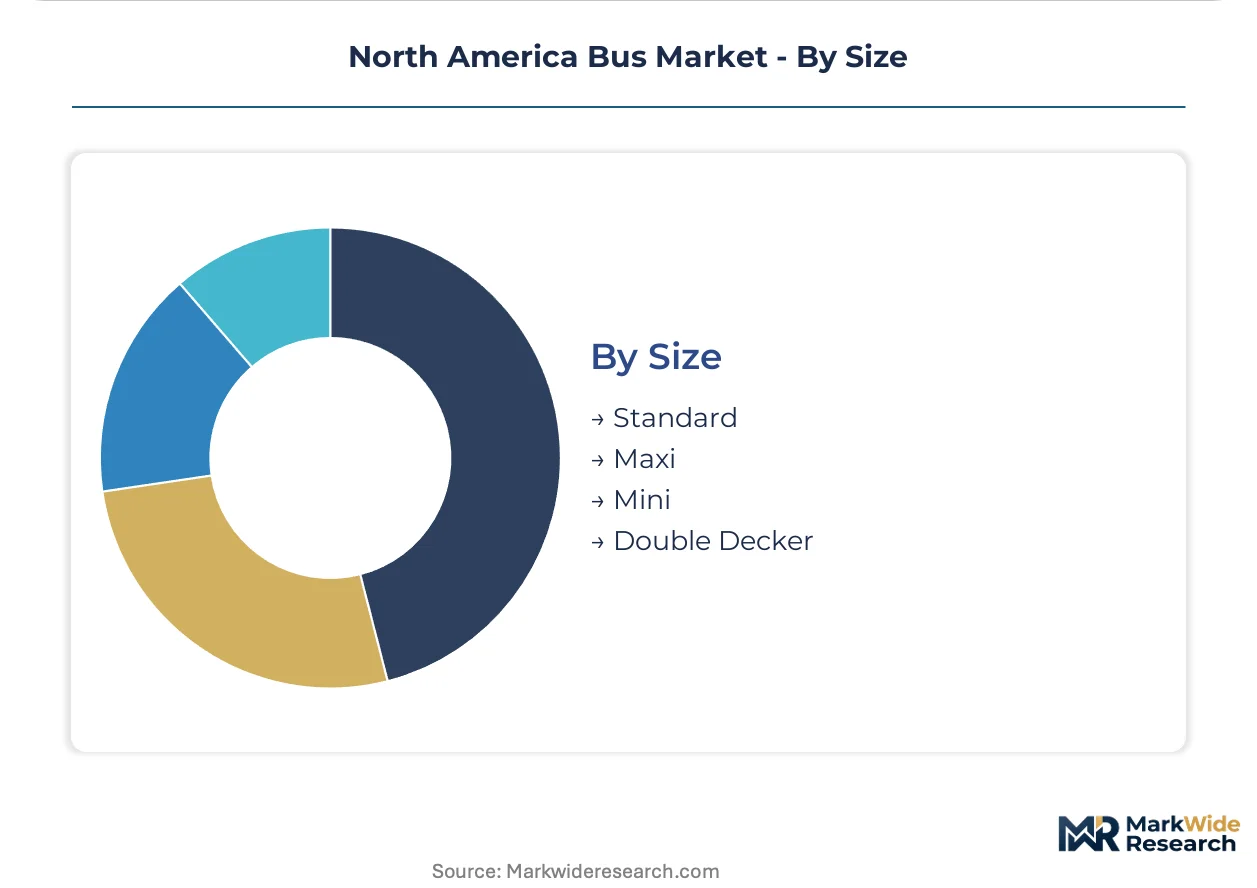
- Standard:40-foot single-deck configurations with 35-40 passenger capacity serve as the baseline for urban transit and school bus applications.
- Maxi:60-foot articulated buses with 100+ passenger capacity address high-ridership corridors in Seattle, Vancouver, and Mexico City where platform length accommodates extended vehicles.
- Mini:20-30 foot cutaway and purpose-built platforms serve paratransit demand-response services and low-density rural routes.
- Double Decker:Two-level configurations maximize passenger capacity within road width constraints, deployed in Las Vegas tourist corridors and select Toronto commuter routes.
Standard size dominates unit shipments; Maxi configurations are expanding most quickly as agencies consolidate high-frequency routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian manufacturers export electric transit platforms to California and Texas transit authorities, while Mexican suppliers feed cutaway chassis components to U.S. school bus assemblers along the I-35 corridor.
United States
California transit agencies in Los Angeles and San Francisco procure battery-electric city buses to meet CARB zero-emission mandates, while Texas utilities build depot charging infrastructure along I-35 and I-10 intercity corridors. The EPA Clean School Bus Program funds electric conversions in disadvantaged districts nationwide. Southeastern manufacturing clusters in Georgia and Alabama assemble Type C school buses for distribution across the Midwest and Atlantic states.
Canada
Toronto and Vancouver transit authorities deploy 60-foot articulated electric buses on high-ridership corridors, with Ontario provincial funding covering charging infrastructure at suburban depots. Transport Canada safety standards harmonize with U.S. NHTSA rules to enable cross-border fleet procurement. Quebec-based manufacturers supply low-floor transit platforms to Montreal and Ottawa systems while exporting to U.S. northeastern cities.
Mexico
Mexico City Metro operates compressed natural gas and diesel bus fleets serving 5.5 million daily passengers across the Valley of Mexico urban area. Federal transport subsidies support intercity coach modernization on routes connecting Mexico City to Guadalajara and Monterrey. Northern border states Nuevo León and Baja California test electric shuttle services for maquiladora worker transport between industrial parks and residential zones.
North America Bus Market Competitive Landscape
Listed leaders compete with private specialists across integrated platform versus component supply dimensions, creating a tiered structure where scale-driven transit manufacturers face purpose-built electric challengers. The vendor base separates into three archetypes: legacy chassis integrators with diesel heritage, dedicated electric platform specialists, and battery-technology-forward entrants from adjacent automotive sectors. Dominant competitive moves include strategic partnerships between bus assemblers and charging infrastructure providers, plus geographic expansion into state-level procurement corridors where electrification mandates concentrate demand.
Within the legacy transit tier, New Flyer and Nova Bus occupy positions as established platform suppliers to Canadian and U.S. municipal authorities. Among school bus specialists, Blue Bird Corporation and Thomas Built Buses exemplify the diesel-to-electric transition archetype, with dedicated manufacturing capacity in southeastern U.S. states. Lion Electric represents the purpose-built electric challenger model, anchoring the medium-duty battery-electric segment with specialized chassis architecture for urban and suburban applications.
| Leading Market Players |
|---|
| New Flyer |
| Blue Bird Corporation |
| Gillig |
| Lion Electric |
| Thomas Built Buses |
| Daimler Buses |
| Nova Bus |
| Proterra |
| GreenPower Motor |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements for battery cell supply lock in procurement visibility for North American bus manufacturers while capping exposure to lithium price volatility through indexed pricing floors. These contracts tie California transit agencies and Georgia school bus assemblers to Korean and Japanese cathode suppliers, embedding cost predictability into multi-year fleet electrification budgets.
Pricing Analysis
Next-generation solid-state battery platforms command premium pricing over current lithium-iron-phosphate configurations, widening the technology-generation gap as NMC chemistry loses cost advantage. Three-tier pricing structure across premium, standard, and economy levels separates CARB-certified zero-emission buses from interim CNG conversions and legacy diesel replacements. Cost compression in standard-tier electric buses is intensifying because Chinese cell manufacturers are expanding North American tolling arrangements. Rural school districts exhibit highest price sensitivity due to limited access to EPA Clean School Bus Program rebates, while California municipal authorities prioritize total cost of ownership over first-cost differentials.
Supply Chain Analysis
China and South Korea dominate cathode active material processing, while Japan anchors separator and electrolyte production for North American bus battery supply. Cell manufacturing draws from lithium carbonate sourced through Chilean and Australian mining operations, plus cobalt hydroxide from the DRC processed in Chinese refineries. Single-source vulnerability concentrates in high-nickel cathode chemistries where Korean suppliers control NCM 811 production capacity. Distribution runs through tiered supplier networks: cell makers ship to module assemblers in Michigan and Ontario, who feed integrated battery pack production at bus manufacturing facilities in California, Georgia, and Quebec.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent bus manufacturers face substitution defense as battery-electric platforms displace diesel chassis architectures and captive fleet operators explore in-house electrification capabilities.
For Market Incumbents: Consolidate service network density in California and Texas corridors where charging infrastructure complexity locks customers into OEM maintenance contracts. Secure backward integration into battery pack assembly through joint ventures with Korean cell suppliers, insulating margin pressure from cathode material cost spikes while meeting CARB zero-emission delivery deadlines. For New Entrants and Emerging Players: EPA Clean School Bus Program certification fast-tracks market access for electric school bus specialists targeting disadvantaged districts in the Southeast. Indigenous community transit in remote Canadian provinces offers unserved demand for solar-battery microgrid configurations outside utility interconnection constraints. Partner with tribal development corporations to bypass conventional utility procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward purpose-built electric platform specialists with captive chassis architecture and established utility rate-case relationships. Long-term viability hinges on charging infrastructure ownership models that generate recurring revenue streams beyond vehicle sales. Watch FERC Order 2222 implementation pace as the inflection signal for V2G revenue stacking economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in lithium-ion cell access for California CARB compliance deadlines. |
| Charging Infrastructure Partnership | Enables utility-backed depot electrification along Texas I-35 corridor. |
| Platform Standardization | Reduces engineering overhead across school bus and transit variants. |
| Geographic Manufacturing Footprint | Positions assembly capacity near Ontario and Quebec provincial funding sources. |
| Software-Defined Vehicle Investment | Supports predictive maintenance guarantees in performance-based service contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with municipal transit procurement officers, school district fleet managers, OEM platform engineers, and utility demand-side management specialists. Secondary validation incorporated EPA Clean School Bus Program disbursement records, CARB zero-emission bus deployment databases, FERC interconnection queue filings, and customs trade data for lithium-ion cell imports. Bottom-up unit shipment estimates triangulated against top-down fleet replacement cycle analysis across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by bus type, fuel architecture, application, and size tier, with regional regulatory clusters treated as separate demand pools. CAGRs were derived from replacement cycle compression rates under zero-emission mandates and total cost of ownership convergence assumptions. Forecast inputs included utility rate structure evolution, battery pack cost curves, and state-level funding allocation trajectories.
Decision-makers should treat outputs as directional under assumptions of continued EPA and CARB regulatory stringency; material deviation in federal funding levels or battery cell trade policy would warrant model refresh. Recalibration cycles align with material shifts in utility interconnection timelines and cathode material supply contract renegotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Intercity Bus Travel Market
Buses
Hydrogen CNG Bus Market
Buses
Airport Shuttle Bus Market
Buses
Bus Transmission System Market
Buses
Bus Charter Services Market
Buses
Fuel Cell Electric Bus Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Electric Intercity Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Solar Bus Market
Buses
Intelligent Bus Shelter Market
Buses
Hydrogen Buses Market
Buses
Canada Transit Buses Market
Buses
Buses & Coaches Market
Buses
Luxury Coaches Market
Buses
Africa Electric Bus Market