
 Luxury Bus Market | 2026-2036
Luxury Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Bus Market Insights
Asset-light leasing and pay-per-kilometer fleet arrangements is reshaping competitive entry in luxury coach procurement. Volvo leverages captive finance subsidiaries to lower operator capital barriers across Nordic markets. Yutong anchors its position through integrated battery manufacturing that compresses electric coach delivery cycles. Scania AB differentiates via modular chassis architectures that accommodate both diesel and hybrid powertrains without platform redesign.
A luxury bus denotes a purpose-built passenger vehicle exceeding twelve meters in length, typically configured with premium materials, active suspension systems, and climate-controlled cabin zones designed for extended-duration travel comfort. Coach buses command the largest installed base among product type segments, though sleeper buses capture disproportionate margin pools on overnight intercity routes in Asia. Electric powertrains within the fuel type category are expanding fastest where depot charging infrastructure reaches commercial density. Corporate clients in the end user dimension sustain premium pricing tolerance through contracted employee mobility programs.
EU Green Deal frameworks and ECHA REACH chemical standards jointly constrain interior material selection and powertrain emissions compliance for manufacturers serving European operators. EPA heavy-duty vehicle regulations and NHTSA bus safety standards govern product certification for United States market entry. Stakeholders must monitor how zero-emission zone expansions in core city pairs reshape route economics and fleet replacement timing.
Market Dynamics
EU Green Deal diesel-phaseout timelines are compressing fleet replacement cycles across European coach operators, forcing capital reallocation toward zero-emission platforms before infrastructure maturity matches vehicle availability.
Growth Catalysts
- EU Green Deal Emissions Framework:Binding CO2 reduction targets for heavy-duty vehicles accelerate operator commitments to electric and hydrogen coach procurement across Germany, France, and the Netherlands.
- Long-Distance Coach Liberalization:Germany's 2013 market opening and subsequent route expansions intensified premium service competition, driving demand for differentiated luxury specifications on intercity corridors.
- Corporate Mobility Programs:Multinational firms in technology and financial services sectors contract dedicated employee shuttle fleets with premium seating configurations and onboard connectivity standards.
Market Restraints
- Battery Cell Supply Concentration:Lithium-ion cell production clusters in China and South Korea create geographic dependency risks for European electric coach assembly timelines.
- Depot Charging Infrastructure Gap:Grid connection permitting delays and transformer capacity constraints at coach terminals extend fleet electrification payback periods beyond operator financing horizons.
- ECHA REACH Chemical Compliance:Restricted substance lists for interior foams, adhesives, and surface treatments force material reformulation costs and supplier qualification delays.
Strategic Opportunities
- Overnight Sleeper Route Expansion:Underpenetrated premium overnight services connecting Germany to Scandinavia and Alpine corridors offer margin capture above standard daytime coach yields.
- Pay-Per-Kilometer Leasing Models:Asset-light fleet arrangements reduce capital barriers for mid-sized tour operators entering luxury segments without balance sheet expansion.
- Integrated Battery Manufacturing:Vertical control over cell and pack production compresses delivery cycles and insulates margins from commodity cell pricing volatility.
Industry Challenges
- High-Voltage Technician Scarcity:Electric powertrain servicing requires certified specialists whose training pipelines lag fleet electrification schedules across Nordic and Central European markets.
- Homologation Timeline Compression:Simultaneous compliance with EU Whole Vehicle Type Approval, UN ECE regulations, and national safety standards extends new platform launch cycles.
- Legacy Fleet Stranding Risk:Diesel coach residual values deteriorate faster than depreciation schedules assume as zero-emission zone expansions accelerate in core city pairs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Bus Market |
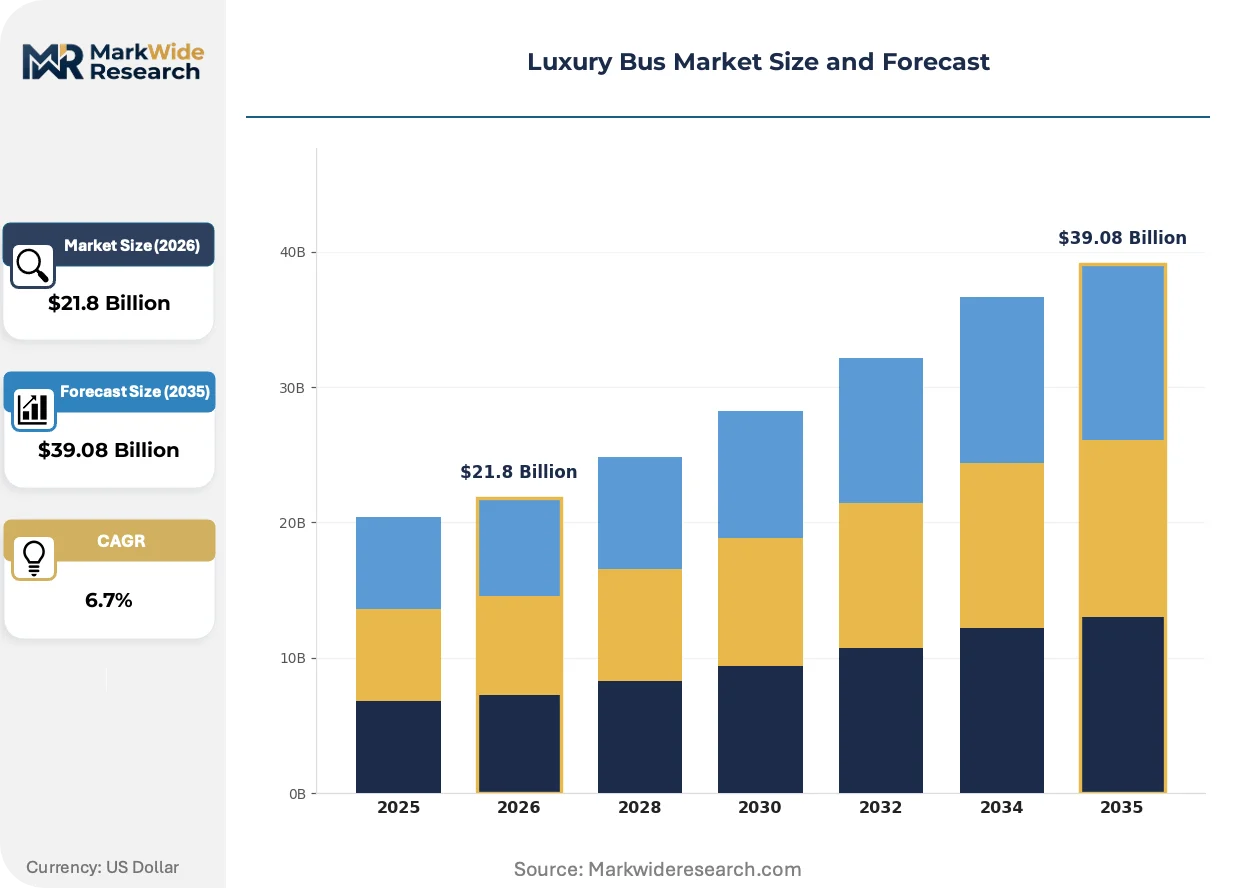
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $39.08 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coach Buses, Sleeper Buses, Double-Decker Buses, Executive Buses End User: Corporate Clients, Tour Operators, Premium Rentals, Government Agencies Features: Onboard Wi-Fi, Luxury Seating, Entertainment Systems, Climate Control Fuel Type: Diesel, Electric, Hybrid, Compressed Natural Gas |
| Companies Covered | Volvo, Scania AB, Daimler, Yutong, BYD, MAN Truck & Bus, King Long, Zhongtong Bus Holding, Mercedes-Benz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Bus Market Trends and Innovations
Powertrain architecture decisions now precede bodywork design in coach development programs, reversing decades of chassis-first engineering sequences and compressing supplier negotiation windows.
Modular platform engineering is hybridizing diesel, hybrid, and fully electric configurations within single chassis architectures. Scania AB and Volvo deploy adaptable frame rails and standardized battery mounting zones that accommodate powertrain swaps without structural redesign. German and Nordic fleet operators accelerate procurement of these flexible platforms to hedge regulatory uncertainty across 10-year asset lifecycles.
EU Green Deal frameworks and ECHA REACH chemical standards jointly constrain interior material selection and powertrain emissions compliance for manufacturers serving European operators. Interior component suppliers face dual pressure: flame-retardant foam formulations must eliminate halogenated compounds while maintaining rail and coach fire safety certifications. Tier-2 seating and panel suppliers in Poland and the Czech Republic consolidate to spread compliance testing costs across larger volume bases.
Tour operators are consolidating vendor relationships around full-service fleet management contracts that bundle vehicles, maintenance, and residual value guarantees. Premium intercity carriers in Germany and Austria now procure mobility-as-a-service packages rather than discrete asset purchases, transferring utilization risk to manufacturers and their captive finance arms. This procurement compression favors suppliers with integrated leasing subsidiaries and established service networks over pure manufacturing specialists.
Luxury Bus Market Segmentation
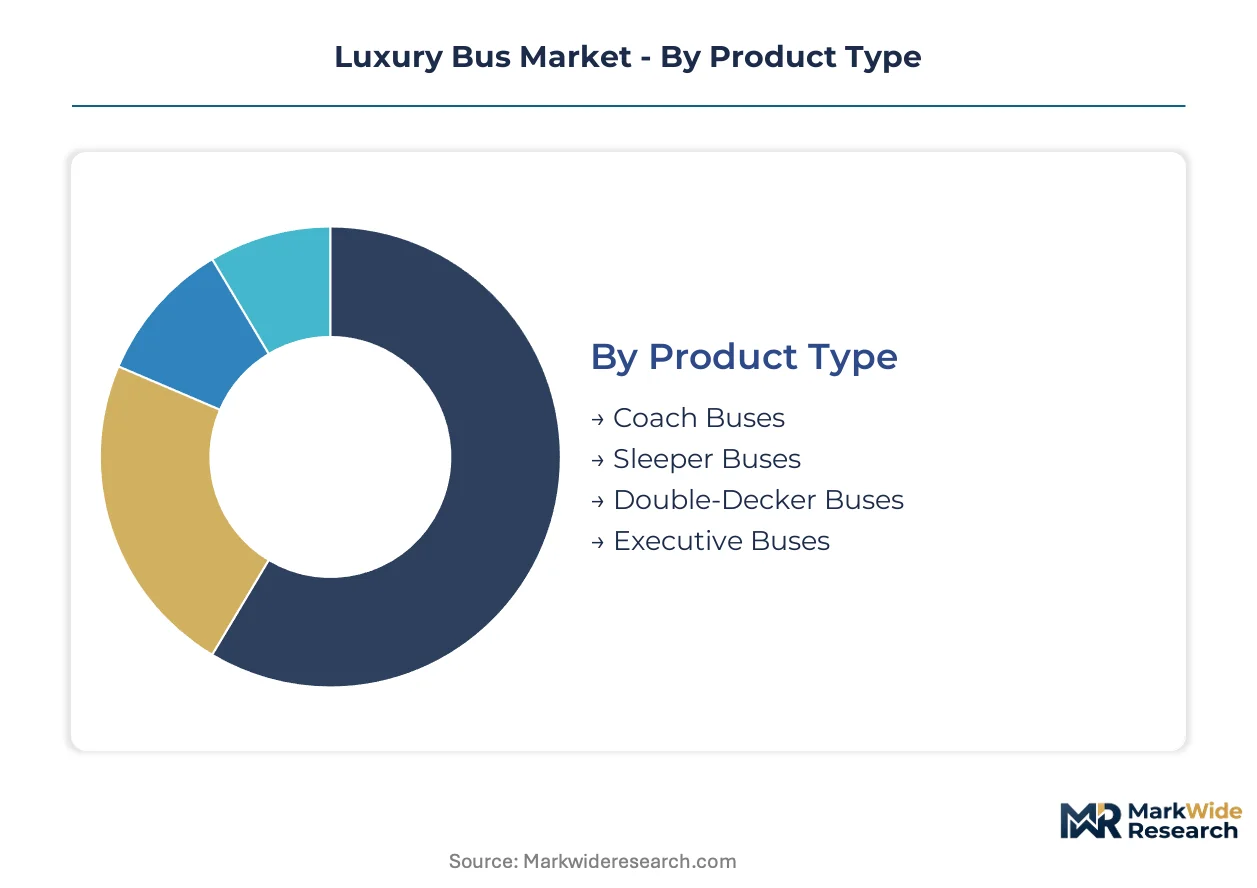
Luxury bus segmentation reveals how procurement priorities diverge across operator business models and passenger journey profiles. Product architecture and fuel technology choices now determine fleet financing structures and residual value exposure.
Product Type:
Mature configurations dominate intercity corridors while emerging formats capture overnight route premiums.
- Coach Buses:Standard twelve-meter-plus configurations with premium materials and active suspension systems serve high-frequency intercity corridors. Demand concentrates in Germany where long-distance coach liberalization has intensified service competition on trunk routes.
- Sleeper Buses:Reclining berth configurations with privacy partitions and dedicated lavatory facilities address overnight journey comfort requirements. Tour operators across Alpine and Scandinavia corridors are expanding premium overnight commitments as these routes yield margins above standard daytime yields.
- Double-Decker Buses:Two-deck passenger configurations maximize seat density on high-volume trunk routes.
- Executive Buses:Reduced-capacity layouts with conference seating and onboard connectivity target corporate shuttle contracts.
Coach buses retain volume leadership; sleeper buses hold the steepest expansion curve.
End User:
Customer type determines pricing tolerance and contract structure across the procurement landscape.
- Corporate Clients:Multinational technology and financial services firms contract dedicated employee mobility programs with premium seating and guaranteed connectivity standards. Procurement concentrates through mobility-as-a-service packages rather than discrete asset purchases.
- Tour Operators:Fleet-dependent carriers across European intercity corridors face compressed replacement cycles under EU Green Deal diesel-phaseout timelines. German operators intensify premium service competition through differentiated luxury specifications.
- Premium Rentals:Event-based and charter operators serve discretionary travel segments with variable utilization profiles.
- Government Agencies:Public sector procurement emphasizes compliance certification and total cost of ownership metrics over premium feature sets.
Corporate clients sustain premium pricing tolerance; tour operators drive the steepest fleet refresh activity.
Features:
Feature bundling now follows powertrain platform decisions rather than chassis-first engineering sequences.
- Onboard Wi-Fi:Guaranteed connectivity standards have become table stakes for corporate shuttle contracts and premium intercity services. Installation concentrates in Nordic markets where passenger expectations for uninterrupted connectivity are highest.
- Luxury Seating:Active suspension-compatible seat frames with extended recline ranges address extended-duration comfort requirements. German fleet operators specify these configurations most aggressively as service differentiation intensifies.
- Entertainment Systems:Seatback screens and distributed audio systems serve overnight route passenger engagement needs.
- Climate Control:Multi-zone cabin conditioning with individual vent controls supports premium positioning on long-haul corridors.
Luxury seating retains specification frequency leadership; onboard Wi-Fi shows the steepest expansion trajectory.
Fuel Type:
Powertrain selection determines infrastructure dependency and regulatory compliance exposure across asset lifecycles.
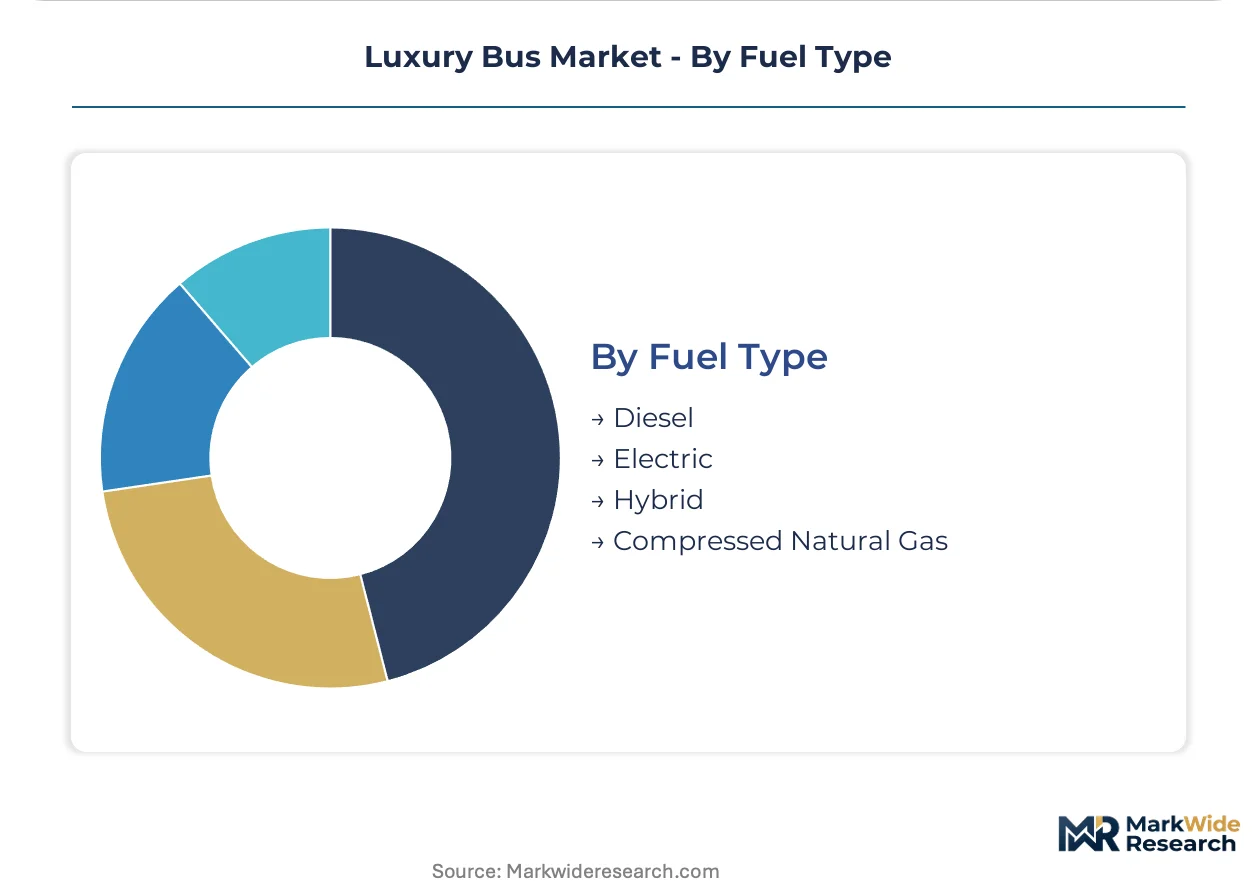
- Diesel:Conventional compression-ignition powertrains face accelerated residual value deterioration as zero-emission zone expansions compress depreciation schedules. Fleet operators in Germany and France front-load replacement commitments to avoid stranded asset risk.
- Electric:Battery-electric configurations with depot charging dependency are expanding fastest where grid connection permits reach commercial density. Integrated battery manufacturing compresses delivery cycles for suppliers with captive cell production.
- Hybrid:Dual-powertrain architectures accommodate regulatory uncertainty across ten-year asset lifecycles through modular platform engineering.
- Compressed Natural Gas:Gaseous fuel configurations offer intermediate emissions reduction where electric infrastructure remains immature.
Diesel retains installed base leadership; electric powertrains gain share fastest on infrastructure-mature corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a structural trade surplus in luxury coach assemblies while importing battery cell components from East Asian suppliers. France and the Netherlands balance domestic production with cross-border fleet procurement from German and Swedish manufacturers. China exports complete electric coach platforms to Southeast Asian and Middle Eastern operators.
Germany
Long-distance coach liberalization since 2013 has intensified premium service competition on intercity corridors, with FlixBus and Deutsche Bahn Intercity Bus driving fleet refresh cycles. The KBA enforces EU Whole Vehicle Type Approval with additional national safety standards for sleeper configurations. Manufacturing concentrates in Bavaria and Baden-Württemberg, where Munich-based operators contract modular platforms from Stuttgart-area assembly plants.
France
Corporate mobility programs in Paris and Lyon sustain demand for executive shuttle configurations with guaranteed connectivity standards. The EU Green Deal emissions framework binds French operators to accelerated diesel-phaseout timelines through 2030. Production activity clusters in Île-de-France and Auvergne-Rhône-Alpes, where Lyon-area bodywork specialists supply premium interior assemblies to domestic and export markets.
Netherlands
Depot charging infrastructure density in Amsterdam-Rotterdam-The Hague corridor enables electric coach deployment ahead of neighboring markets. ECHA REACH chemical standards restrict interior foam formulations and adhesive compounds used in Dutch-assembled vehicles. Eindhoven-region suppliers consolidate seating and panel manufacturing to spread compliance testing costs across larger volume bases.
Sweden
Nordic tour operators specify active suspension and climate-controlled cabin zones for extended-duration Alpine and Scandinavian routes. Volvo leverages captive finance subsidiaries to lower operator capital barriers across Stockholm and Gothenburg markets. Manufacturing concentrates in Västra Götaland, where Gothenburg-headquartered platform integrators deploy modular chassis architectures across diesel, hybrid, and electric configurations.
China
Integrated battery manufacturing compresses electric coach delivery cycles for domestic and export procurement. MIIT dual carbon goals and GB standards govern heavy-duty vehicle emissions and safety certification. Production gravity centers on Zhengzhou and Xiamen, where Yutong and King Long anchor electric platform assembly with captive cell supply chains.
Luxury Bus Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with concentrated supply positions in seating, climate systems, and powertrain assemblies. The vendor base structures around three tiers: multinational chassis manufacturers with captive finance arms, national bodywork specialists with regional service networks, and tier-2 component suppliers consolidating to absorb compliance testing costs. Strategic moves center on modular platform engineering that accommodates powertrain swaps without structural redesign, and pay-per-kilometer leasing arrangements that transfer utilization risk from operators to manufacturers.
Within the integrated manufacturing tier, Volvo, Scania AB, and Yutong occupy positions that exemplify divergent competitive approaches. Volvo represents the captive finance model, lowering capital barriers through subsidiary lending structures. Scania AB anchors modular chassis architecture, accommodating diesel, hybrid, and electric configurations within standardized frame rail designs. Yutong exemplifies backward integration into battery cell production, compressing delivery cycles and insulating margins from commodity pricing volatility.
| Leading Market Players |
|---|
| Volvo |
| Scania AB |
| Daimler |
| Yutong |
| BYD |
| MAN Truck & Bus |
| King Long |
| Zhongtong Bus Holding |
| Mercedes-Benz |
| Others |
Pricing and Supply Chain Analysis
Rhine-Alpine corridor freight cost volatility feeds directly into chassis delivery pricing and downstream fleet procurement structures across European luxury coach markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on powertrain certification level and after-sales service bundling. Price differentiation stems from EU Whole Vehicle Type Approval tier and volume scale commitments. Pricing pressure intensifies as battery cell commodity volatility compresses margin buffers on electric platform deliveries. Mid-sized tour operators exhibit highest price sensitivity; corporate mobility programs sustain lowest sensitivity through guaranteed utilization contracts.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for battery cell and powertrain component sourcing. Manufacturing gravity centers on Germany, Sweden, and China for chassis assemblies, with Poland and the Czech Republic feeding tier-2 interior components. Raw material dependencies span lithium carbonate, cobalt sulfate, and high-grade aluminum extrusions. Distribution runs through captive finance subsidiaries and full-service fleet management contracts rather than discrete asset sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage technician pipelines lag fleet electrification schedules across core manufacturing clusters, constraining service network expansion and aftermarket revenue capture.
For Market Incumbents: Harden residual value guarantees through captive leasing subsidiaries to offset diesel coach stranding risk from zero-emission zone expansions. Deepen backward integration into battery pack assembly to compress delivery cycles and insulate margins from East Asian cell pricing volatility. Prioritize modular platform engineering that accommodates powertrain swaps without structural redesign. For New Entrants and Emerging Players: Establish a beachhead in overnight sleeper route segments connecting Germany to Scandinavia and Alpine corridors, where premium yields exceed standard daytime coach economics. Target pay-per-kilometer leasing arrangements for mid-sized tour operators seeking asset-light fleet expansion without balance sheet expansion. Lead with integrated battery manufacturing partnerships to differentiate delivery reliability. For Investors and Strategic Acquirers: Carve-out targets emerge from national bodywork specialists with regional service networks and established ECHA REACH compliance testing capabilities. Long-term viability favors suppliers with captive finance arms and full-service fleet management contract portfolios over pure manufacturing specialists. Monitor depot charging infrastructure permitting velocity as the critical inflection signal for electric coach deployment scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Engineering | Scania AB and Volvo deploy adaptable frame rails accommodating diesel, hybrid, and electric configurations without structural redesign. |
| Captive Finance Subsidiary Expansion | Volvo leverages subsidiary lending structures to lower operator capital barriers across Nordic markets. |
| Integrated Battery Manufacturing | Yutong anchors competitive position through in-house cell and pack production compressing delivery cycles. |
| Full-Service Fleet Management Contracts | German premium intercity carriers now procure mobility-as-a-service packages transferring utilization risk to manufacturers. |
| Overnight Sleeper Route Development | Alpine and Scandinavia corridor expansion yields margins above standard daytime coach economics. |
Research Methodology
A standing panel of fleet procurement directors, powertrain platform engineers, captive finance executives, and ECHA compliance specialists provided ongoing calibration throughout the study. Primary interview data combined with secondary validation from KBA vehicle registration databases, EU Whole Vehicle Type Approval filings, customs trade records, and SEC 10-K disclosures from listed manufacturers. Bottom-up unit economics triangulated against top-down market sizing across product type, fuel technology, and end-user segments.
Scenario bracketing around infrastructure deployment velocity, regulatory phaseout timelines, and battery commodity pricing informed projection boundaries across the analysis window. Segmentation modeling spanned coach configuration, powertrain architecture, customer type, and regional production cluster. CAGRs derived from logistic diffusion curves fitted to fleet replacement cycle data and charging infrastructure density thresholds. Specific forecast inputs included EU Green Deal compliance cost trajectories and lithium-ion cell supply concentration indices.
Stress conditions across grid connection permitting delays, transformer capacity constraints, and high-voltage technician training pipeline gaps were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding depot charging infrastructure commercialization velocity and zero-emission zone expansion schedules. Material shifts in EU battery cell import tariff structures or ECHA REACH substance restriction timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Airport Bus Market
Buses
Europe Bus Market
Buses
Bus Flooring Market
Buses
Bus Charter Services Market
Buses
Electric Intercity Bus Market
Buses
Bus Bellows Market
Buses
Intercity Bus Travel Market
Buses
Europe Trolley Bus Market
Buses
Global Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Bus Chassis Market
Buses
North America Bus Market
Buses
Global Luxury Shuttle Bus Market
Buses
Trolley Bus Market
Buses
Hydrogen CNG Bus Market
Buses
Bus Rental Market