
 Electric Intercity Bus Market | 2026-2036
Electric Intercity Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Intercity Bus Market Foresight
The performance gap between premium long-range coaches and standard single-deck commuter units is broadening. BYD Company Limited leverages in-house battery production to control cost structures across its coach lineup. Scania AB anchors its position through modular chassis architectures that accommodate multiple charging interfaces. Proterra specializes in high-energy-density pack integration for extended intercity routes.
An electric intercity bus is a battery-electric or overhead-catenary-powered road vehicle engineered for passenger transport between urban centers, typically featuring gross vehicle weights exceeding 12 tonnes, drive ranges of 300-500 kilometers per charge cycle, and regenerative braking systems. These vehicles serve commercial operators replacing diesel-powered coaches on fixed-route and charter services. Single-deck configurations dominate current procurement volumes due to operational flexibility and lower per-unit capital requirements. Plug-in charging technology leads installed infrastructure, though battery swap systems are gaining traction among fleet operators prioritizing minimal dwell time. Coach-type buses command premium pricing based on passenger amenity specifications and extended-range battery pack configurations.
The US EPA and NHTSA coordinate greenhouse gas emission standards that phase in stringent CO2 limits for heavy-duty vehicles, directly accelerating fleet electrification timelines. Europe's EMA and EU Green Deal framework mandate CO2 reductions for new heavy-duty vehicles, with the F-Gas Regulation further restricting climate-warming refrigerants in thermal management systems. China's MIIT enforces GB standards for electric commercial vehicle safety and energy consumption, while SAMR oversees market access certification. Stakeholders must monitor regulatory divergence around battery recycling mandates and charging interoperability standards as these frameworks mature.
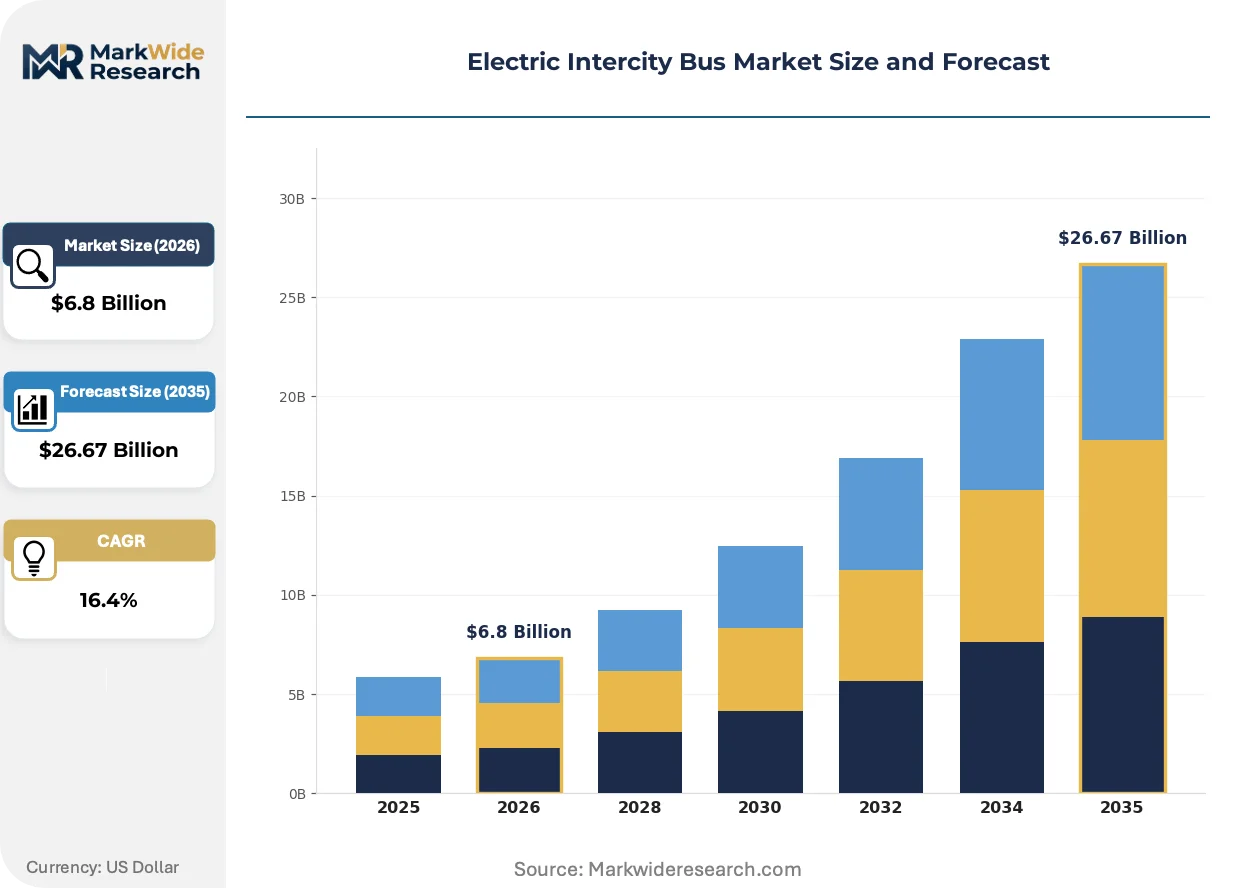
Market Dynamics
Fleet procurement mandates from Germany's KBA and France's ANSM are compressing diesel coach replacement timelines across European intercity corridors. Lithium iron phosphate cell chemistry advances are simultaneously extending operational range thresholds beyond 400 kilometers per charge cycle.
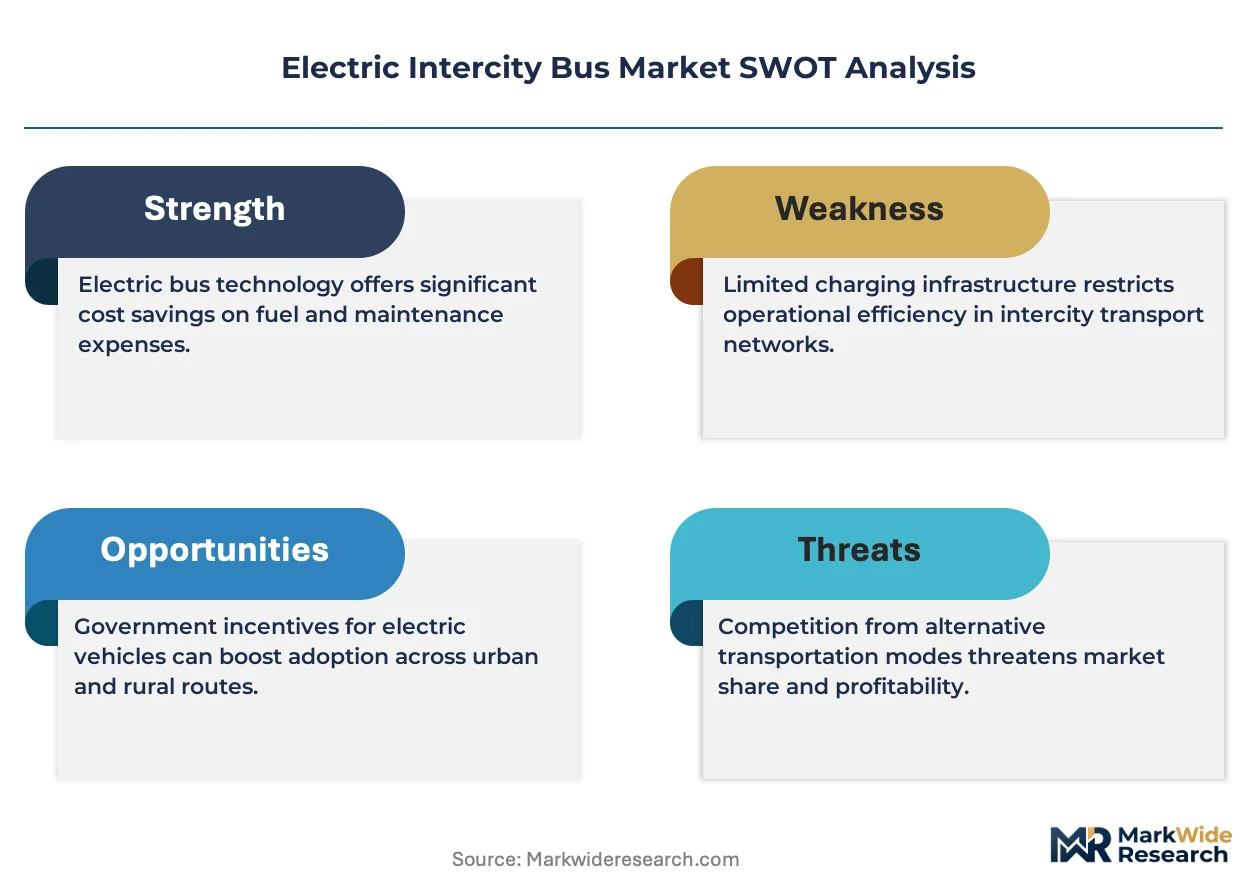
Growth Catalysts
- Zero-emission procurement mandates:Transit agencies in Germany must achieve full fleet electrification on specified intercity routes under KBA-enforced CO2 reduction frameworks.
- Battery chemistry evolution:Lithium iron phosphate formulations are eliminating thermal runaway risks while extending cycle life for high-utilization coach applications.
- Overhead catenary infrastructure:Corridor electrification projects along China's Beijing-Shanghai expressway are enabling continuous-power intercity services without range limitations.
Market Restraints
- Charging infrastructure gaps:Rural highway corridors in France lack 350kW ultra-fast charging stations necessary for 45-minute turnaround cycles.
- Battery supply concentration:Cathode active material processing concentrates in China's Hunan and Fujian provinces, creating single-source vulnerability for European coach assemblers.
- Grid capacity constraints:Distribution network operators in Germany's Saxony region cannot guarantee simultaneous depot charging for fleets exceeding 50 vehicles.
Strategic Opportunities
- India's intercity corridor electrification:The CEA's national electric mobility mission offers tariff subsidies for fleet operators deploying battery-electric coaches on Delhi-Jaipur and Mumbai-Pune routes.
- Battery swap standardization:China's MIIT is mandating interoperable swap pack dimensions, enabling third-party infrastructure providers to serve multiple OEM platforms.
- Carbon credit monetization:The EU Green Deal's emissions trading system allows coach operators to sell surplus allowances from zero-emission fleet deployments.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack certified personnel for 800V battery pack diagnostics and cell-level replacement procedures.
- Depot charging infrastructure capex:Grid connection upgrades and transformer installations require capital allocations exceeding vehicle procurement costs in Germany's rural Bavarian districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Intercity Bus Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Double-Decker, Single-Deck, Articulated, Coach Charging Technology: Overhead Catenary, Plug-in, Inductive, Battery Swap End User: Government, Private Operators, Educational Institutions, Tour Operators Battery Capacity: 100 kWh, 200 kWh, 300 kWh, 400 kWh |
| Companies Covered | Daimler AG, Iveco Bus, BYD Company Limited, Scania AB, MAN, Zhengzhou Yutong Bus Co., Ltd., Proterra, NFI Group, AB Volvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Intercity Bus Market Shifts & Advancements
Silicon carbide power electronics are compressing drivetrain energy losses while enabling higher motor speeds. Solid-state battery prototyping is accelerating validation timelines for next-generation intercity platforms.
Silicon carbide MOSFETs are replacing insulated-gate bipolar transistors in traction inverters, cutting switching losses by half during high-speed cruising. German fleet operators are specifying SiC-based drivetrains for premium long-distance coach configurations. This semiconductor transition is integrating higher thermal efficiency into vehicle architectures previously constrained by silicon device limitations.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in bus thermal management systems, forcing adoption of CO2 heat pumps. Coach OEMs must redesign HVAC units to accommodate transcritical CO2 cycles by specified compliance deadlines. Long-range premium configurations face the steepest engineering burden due to passenger comfort specifications demanding precise cabin temperature control.
Public transit agencies are consolidating procurement through framework agreements rather than individual vehicle tenders, compressing vendor negotiation cycles. Germany's federal states are pooling intercity fleet requirements through KBA-coordinated purchasing consortia. This buyer concentration is most visible in Baden-Württemberg and North Rhine-Westphalia, where combined orders now exceed single-year production capacity of mid-tier coach assemblers.
Electric Intercity Bus Market Segmentation
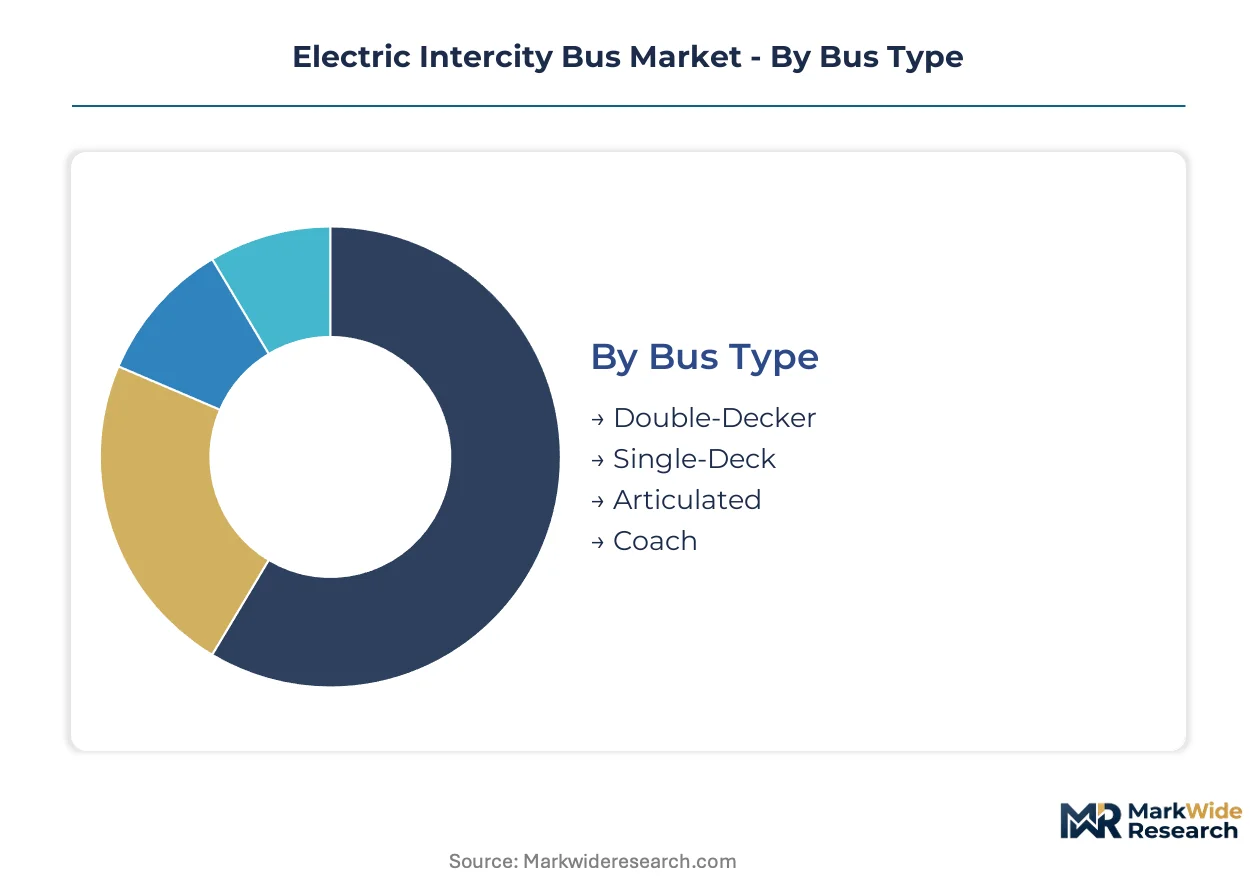
Segmentation in the electric intercity bus market determines procurement specifications, infrastructure investment priorities, and total cost of ownership calculations. Fleet operators select configurations based on route distance profiles, passenger volume patterns, and available charging infrastructure along corridor networks.
Bus Type:
Route distance and passenger density dictate chassis selection more than capital cost considerations alone.
- Single-Deck:These configurations utilize 12-meter platforms with 40-50 passenger capacities and modular battery pack layouts. German transit agencies in North Rhine-Westphalia specify single-deck units for regional express routes under 250 kilometers, prioritizing operational flexibility over maximum passenger throughput.
- Coach:Premium long-distance platforms integrate 400 kWh battery systems, reclining seat configurations, and auxiliary climate control for passenger comfort. Tour operators across France's Lyon-Marseille corridor demand coach-type buses for their superior range thresholds and amenity specifications on extended intercity services.
- Double-Decker:High-capacity urban-suburban configurations maximize passenger volume on congested corridor segments.
- Articulated:Extended 18-meter platforms serve high-frequency trunk routes with dedicated busway infrastructure.
Single-Deck leads on scale; Coach leads on momentum.
Charging Technology:
Dwell time requirements and route electrification status determine charging modality selection across operator fleets.
- Plug-in:Conductive charging via CCS2 or GB/T connectors dominates current infrastructure deployment, with 350 kW ultra-fast stations enabling 45-minute turnaround cycles. China's State Grid Corporation has installed plug-in corridors along the Beijing-Shanghai expressway, supporting continuous intercity operations without battery swap infrastructure.
- Battery Swap:Automated pack exchange systems eliminate charging downtime entirely, with standardized dimensions mandated by China's MIIT enabling multi-OEM compatibility. Fleet operators in Shenzhen prioritize swap-capable platforms for 24-hour utilization schedules on high-frequency intercity shuttles.
- Overhead Catenary:Continuous power supply eliminates range constraints on electrified corridor segments.
- Inductive:Wireless charging pads enable opportunity charging at terminal stations without physical connector wear.
Plug-in leads on scale; Battery Swap leads on momentum.
End User:
Procurement authority and subsidy access differentiate buyer categories more than operational requirements alone.
- Government:Transit agencies leverage KBA and ANSM procurement mandates to consolidate fleet electrification timelines, with framework agreements covering 50-vehicle minimum orders. Germany's federal states pool requirements through coordinated purchasing consortia, compressing vendor negotiation cycles and standardizing technical specifications across Baden-Württemberg and Bavaria.
- Private Operators:Commercial coach companies optimize total cost of ownership calculations without mandate-driven replacement schedules, prioritizing residual value and financing flexibility. French private fleets serving Paris-Lyon routes evaluate battery lease structures to reduce upfront capital exposure.
- Tour Operators:Seasonal demand patterns and premium passenger expectations drive amenity-focused specifications.
- Educational Institutions:University shuttle services and inter-campus transport programs utilize simplified procurement processes with reduced technical complexity requirements.
Government leads on scale; Private Operators leads on momentum.
Battery Capacity:
Route length and charging opportunity frequency determine energy storage specifications more than vehicle weight class alone.
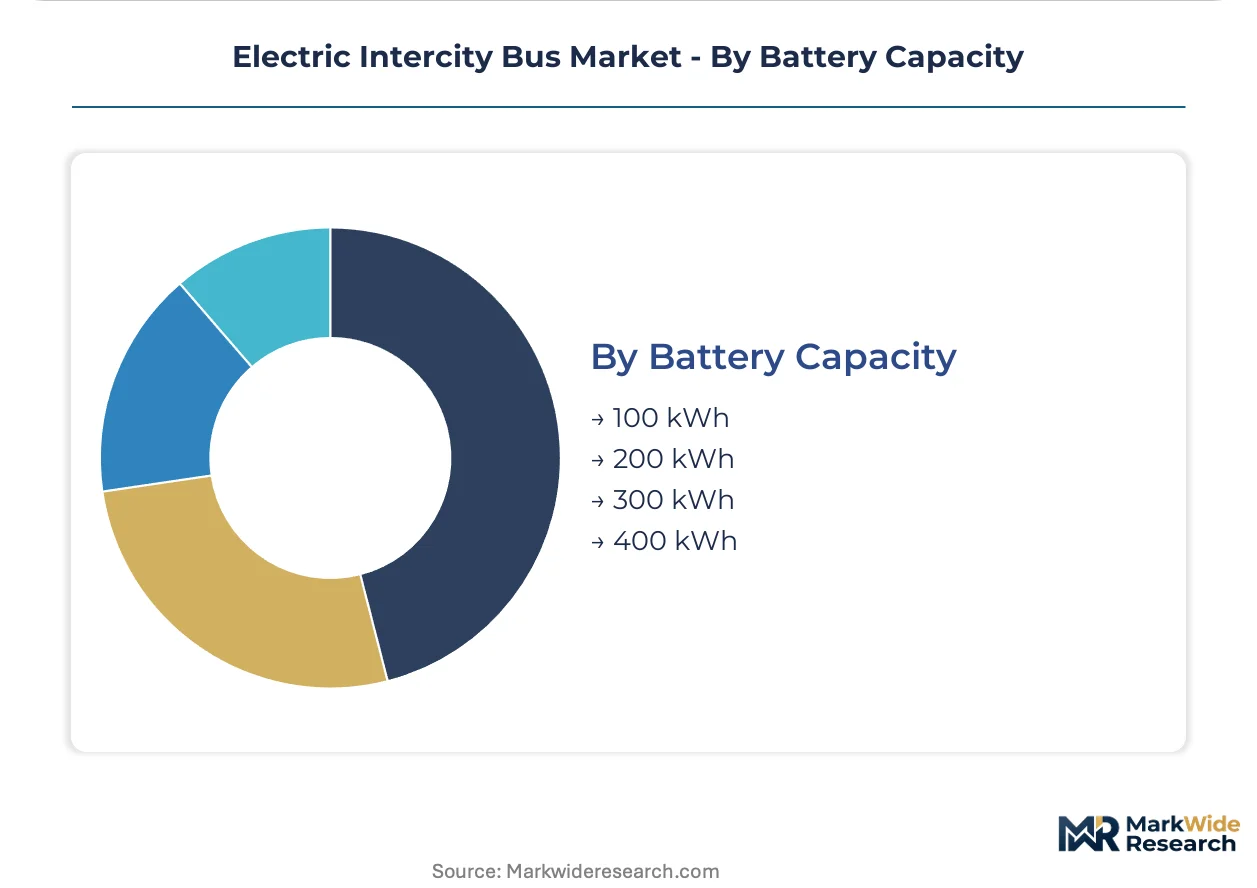
- 400 kWh:Maximum-range configurations enable 500-kilometer intercity segments without intermediate charging, utilizing lithium iron phosphate cell chemistry for thermal stability. Premium coach operators on Germany's Hamburg-Munich corridor specify 400 kWh packs to eliminate range anxiety on longest-distance scheduled services.
- 300 kWh:Mid-range platforms balance capital cost against operational flexibility, serving 350-kilometer routes with single intermediate charging stops. China's provincial operators deploy 300 kWh configurations on intercity networks connecting secondary cities where 350 kW infrastructure is available but swap stations are not.
- 200 kWh:Compact energy storage suits shorter regional routes with frequent terminal charging access.
- 100 kWh:Minimum viable configurations serve shuttle and feeder applications with guaranteed depot charging.
400 kWh leads on scale; 300 kWh leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Shenzhen, and Detroit anchor regional electrification programs. Battery systems integration expertise concentrates in university-industry clusters spanning Germany, China, and the United States.
China
Provincial corridor networks connecting Beijing, Shanghai, and Guangzhou drive fleet procurement volumes. MIIT enforces GB standards for electric commercial vehicle safety while mandating interoperable battery swap pack dimensions. The Yangtze River Delta cluster around Shanghai hosts multiple OEM final assembly facilities serving intercity express routes.
Germany
Transit agencies in Baden-Württemberg and North Rhine-Westphalia pool requirements through KBA-coordinated purchasing consortia. The KBA enforces CO2 reduction frameworks that compress diesel coach replacement timelines on specified intercity routes. Stuttgart's automotive engineering ecosystem supplies traction motor and power electronics subsystems to domestic coach assemblers.
France
Private operators serving the Lyon-Marseille corridor demand premium coach-type buses with extended-range configurations. ANSM procurement mandates align with EU Green Deal CO2 reduction targets for new heavy-duty vehicles. The Auvergne-Rhône-Alpes region hosts thermal management system suppliers adapting to F-Gas Regulation phase-down requirements.
United States
EPA and NHTSA coordinated greenhouse gas emission standards phase in stringent CO2 limits for heavy-duty vehicles. California's Air Resources Board supplements federal frameworks with state-level zero-emission fleet mandates affecting interstate coach operators. The Pacific Northwest corridor between Seattle and Portland attracts early deployment of silicon carbide drivetrain configurations.
India
The CEA's national electric mobility mission offers tariff subsidies for fleet operators on Delhi-Jaipur and Mumbai-Pune routes. State electricity regulatory commissions negotiate demand-charge structures for depot charging infrastructure. The Delhi-NCR region concentrates pilot deployments of 300 kWh battery configurations on high-frequency intercity shuttles.
Electric Intercity Bus Market Competitive Landscape
Top-tier vendors anchor premium long-distance coach segments, while mid-tier assemblers compete on single-deck regional configurations. European and Chinese manufacturers dominate procurement frameworks through distinct technology positioning. Three archetypes define competitive structure: integrated battery producers controlling cell-to-pack cost structures, modular chassis specialists accommodating multiple charging interfaces, and drivetrain component suppliers licensing power electronics platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves as operators consolidate procurement through multi-year framework agreements.
Within the integrated battery tier, BYD Company Limited and Proterra exemplify cost-structure control through captive cell production. European modular chassis positioning is occupied by Scania AB. Among established automotive conglomerates, Daimler AG and AB Volvo occupy positions spanning multiple weight classes and geographic markets. Zhengzhou Yutong Bus Co., Ltd. represents scale-driven manufacturing archetypes serving high-volume procurement programs.
| Leading Market Players |
|---|
| Daimler AG |
| Iveco Bus |
| BYD Company Limited |
| Scania AB |
| MAN |
| Zhengzhou Yutong Bus Co., Ltd. |
| Proterra |
| NFI Group |
| AB Volvo |
| Others |
Supply & Pricing Matrix
Captive battery cell production anchors both supply security and pricing power for integrated OEMs like BYD, while modular assemblers relying on external cell supply face margin compression from cathode active material concentration in China's Hunan and Fujian provinces. This structural divergence between in-house and outsourced energy storage configurations shapes competitive positioning across premium coach and single-deck segments.
Pricing Analysis
Bundled battery lease structures separate from chassis purchase are gaining traction among private operators seeking to reduce upfront capital exposure. Three-tier pricing structure across premium, standard, and economy levels differentiates coach configurations by range threshold and amenity specifications. Cost compression in mid-range single-deck segments is intensifying because procurement consortia in Germany's federal states consolidate volume leverage. Government transit agencies demonstrate lowest price sensitivity due to mandate-driven replacement schedules, while private charter operators exhibit highest sensitivity to total cost of ownership calculations.
Supply Chain Analysis
Lithium iron phosphate cathode supply rests on Chinese specialty chemical processors dominating global precursor refining capacity. Cell manufacturing draws from South Korean and Japanese equipment suppliers for coating and formation lines. Single-source vulnerability concentrates in cathode active material processing, where European coach assemblers lack qualified alternative suppliers. Distribution runs through OEM-direct fleet sales for large government orders, with dealer networks handling private operator aftermarket service and parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where KBA-enforced CO2 reduction frameworks in Germany and parallel ANSM mandates in France lock in demand visibility regardless of fuel price cyclicality.
For Market Incumbents: Acquire battery swap infrastructure assets to preempt third-party platform control on high-frequency intercity corridors. Secure captive lithium iron phosphate cell supply through offtake agreements with Chinese cathode processors before European recycling mandates tighten material access. Defensive positioning requires countering emerging modular chassis specialists threatening premium coach margins through flexible charging interface compatibility. For New Entrants and Emerging Players: Capture India's Delhi-Jaipur and Mumbai-Pune intercity corridors where CEA tariff subsidies reduce fleet operator payback periods and incumbent presence remains limited. Target 300 kWh battery configurations for provincial Chinese operators seeking operational flexibility without swap station dependency. Go-to-market positioning should emphasize silicon carbide drivetrain efficiency as a differentiated total cost of ownership lever against legacy silicon inverter platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier assemblers lack scale to meet framework agreement minimum order thresholds set by Germany's pooled procurement consortia. Long-term viability favors integrated battery producers controlling cell-to-pack cost structures or modular chassis platforms accommodating multiple charging standards. Watch battery swap standardization progress under China's MIIT as the inflection signal determining infrastructure winner-take-most dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium iron phosphate cell access from Hunan-based processors for European assembly. |
| Charging Infrastructure Partnership | Enables 350 kW ultra-fast corridor deployment along France's Lyon-Marseille route. |
| Platform Standardization | Accommodates CCS2, GB/T, and battery swap interfaces on single modular chassis architecture. |
| Geographic Manufacturing Footprint | Positions final assembly within Yangtze River Delta cluster serving Beijing-Shanghai expressway demand. |
| Software-Defined Vehicle Investment | Integrates silicon carbide inverter control with predictive thermal management for extended range. |
Research Methodology
Bottom-up fleet operator procurement modeling reconciled against top-down OEM production tracking forms the analytical core of this study. Primary interviews with transit agency procurement directors, coach OEM platform engineers, battery system integration specialists, and grid infrastructure planners combined with secondary validation from MIIT GB standard filings, KBA type-approval databases, and State Grid Corporation charging corridor deployment records. Triangulation across these sources ensures volume estimates reflect actual fleet deployment timelines rather than manufacturer production announcements alone.
Historical trendline analysis of lithium iron phosphate cell cost curves and charging infrastructure buildout rates informs projection assumptions across the analysis window. Segmentation dimensions include bus type, charging technology, end user category, battery capacity tier, and regional regulatory cluster. CAGRs derive from fitted adoption curves weighted by mandate enforcement schedules and infrastructure readiness indicators. Silicon carbide penetration trajectories and battery swap standardization progress serve as key technology-specific forecast inputs.
Regulatory delay, cathode material supply disruption, and grid connection capacity shortfalls are the dominant revision risks to deployment assumptions. Forecasts reflect documented assumptions about mandate enforcement consistency and infrastructure investment continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Luxury Coaches Market
Buses
Solar Bus Market
Buses
Airport Shuttle Bus Market
Buses
Airport Bus Market
Buses
Intelligent Bus Shelter Market
Buses
Bus Seat Market
Buses
Africa Electric Bus Market
Buses
Bus Rental Market
Buses
Luxury Bus Market
Buses
Bus Flooring Market
Buses
Canada Transit Buses Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Bus Transmission System Market
Buses
School Bus Market
Buses
Europe Bus Market
Buses
Bus Bellows Market