
 Bus Chassis Market | 2026-2036
Bus Chassis Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Chassis Market Outlook
The bus chassis market is recalibrating around a widening gap between premium electric platforms and commodity diesel architectures. Daimler Truck leverages its integrated powertrain division to command premium positioning in zero-emission chassis. Tata Motors anchors its competitive stance through cost-optimized steel-frame designs purpose-built for high-volume emerging markets. Ashok Leyland specializes in modular low-entry configurations that dominate Indian metropolitan procurement cycles.
A bus chassis constitutes the structural load-bearing frame, suspension mounting points, and powertrain interface that supports the complete vehicle body without the passenger enclosure or interior fittings. Modern aluminum-intensive chassis designs achieve weight reductions exceeding conventional steel constructions while maintaining torsional rigidity thresholds mandated by rollover safety protocols. Electric type segments now attract disproportionate engineering investment as battery-pack integration demands dedicated frame architectures with reinforced floor pans and thermal management routing. Steel material categories retain volume leadership across price-sensitive procurement channels, though composite-reinforced variants gain traction in premium tour bus specifications where corrosion resistance extends service intervals.
Europe's EMA and F-Gas Regulation constrain refrigerant choices and thermal system architectures in climate-controlled chassis variants. India's BIS and CEA enforce localized structural testing protocols that shape import eligibility for foreign manufacturers. The US NHTSA and EPA maintain divergent compliance calendars for greenhouse gas standards and crashworthiness mandates. Stakeholders must track how regulatory asymmetries between these jurisdictions fragment platform standardization strategies and force region-specific engineering commitments.
Market Dynamics
Fleet electrification mandates are forcing chassis manufacturers to abandon legacy platform architectures and engineer dedicated battery-electric frames with integrated thermal routing and reinforced floor structures.
Growth Catalysts
- EU Green Deal CO2 standards:Binding emission reduction targets for heavy-duty vehicles accelerate municipal procurement of zero-emission chassis across German and French transit authorities.
- Brazil urban corridor densification:São Paulo and Rio de Janeiro metropolitan expansion drives articulated bus fleet renewal with higher-capacity low-floor configurations.
- Battery-pack integration engineering:Dedicated frame architectures with structural battery mounting points enable longer-range electric bus designs without sacrificing passenger capacity.
Market Restraints
- High-voltage component cost volatility:Lithium-ion cell and power electronics pricing instability compresses margins on electric chassis platforms.
- Steel supply concentration:Brazilian and Chinese mill dominance in structural-grade steel creates input vulnerability for cost-optimized frame producers.
- Range limitation in extreme climates:Battery thermal degradation in high-temperature Middle Eastern and South Asian operating environments constrains electric platform viability.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced automotive technology attract chassis localization investments serving domestic and export markets.
- Autonomous shuttle integration:Convergence of electric drivetrains and sensor-embedded frame designs opens dedicated architectures for self-driving transit pods.
- Retrofit electrification kits:Aftermarket chassis conversion packages address installed diesel fleet base in Eastern European and Southeast Asian markets.
Industry Challenges
- High-voltage safety certification complexity:Divergent IEC and national electrical safety protocols for electric bus systems extend homologation timelines across export markets.
- Multi-material joining expertise gap:Shortage of welding and adhesive bonding technicians qualified for aluminum-steel hybrid frame construction limits production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Chassis Market |
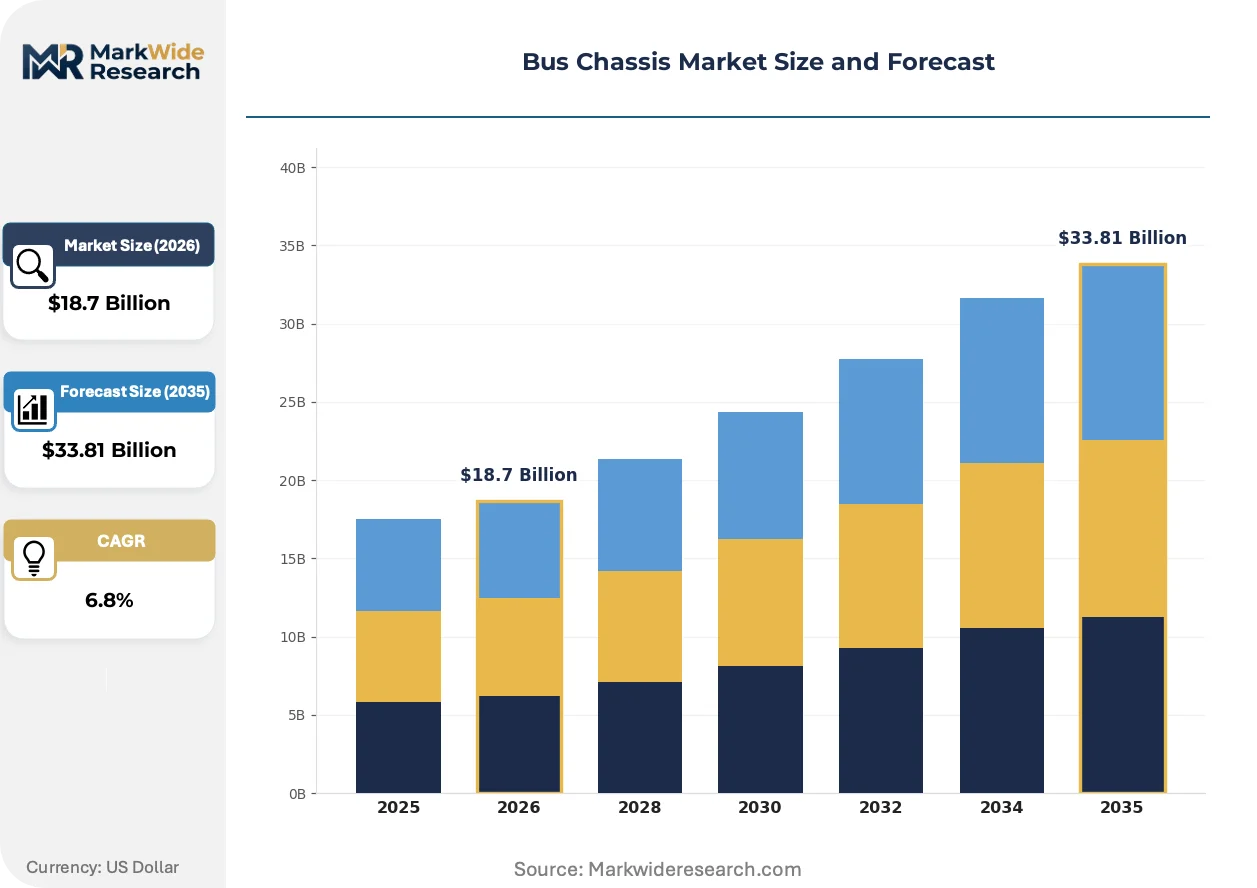
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Conventional, Electric, Hybrid, Low-Entry Application: Public Transport, School Buses, Tour Buses, Shuttle Services Material: Aluminum, Steel, Composite, Fiberglass End User: Government, Private Operators, NGOs, Rental Services |
| Companies Covered | Tata Motors, Daimler Truck, AB Volvo, Scania, Ashok Leyland, MAN Truck & Bus, Mercedes-Benz, Iveco, Blue Bird Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Chassis Market Strategic Shifts
Digital manufacturing and predictive design tools are compressing chassis development cycles while regulatory pressure on vehicle lifecycle emissions reshapes material selection priorities across the supply base.
Modular skateboard platforms are automating chassis-body integration by standardizing battery placement, suspension geometry, and steering interfaces across multiple bus lengths and configurations. European manufacturers adopting these architectures report reduced engineering change orders and faster variant proliferation. The approach is automating procurement consolidation as transit agencies specify platform families rather than individual models.
Europe's F-Gas Regulation and EMA climate mandates constrain refrigerant selection in thermal management systems, forcing redesign of HVAC-integrated chassis variants with lower-global-warming-potential cooling circuits. Component suppliers must recalibrate heat exchanger specifications and compressor architectures to maintain cooling performance under tighter chemical restrictions. Tour and intercity coach segments face the steepest compliance costs due to larger climate-controlled cabin volumes.
Lifecycle cost modeling now dominates municipal tender evaluation, displacing upfront purchase price as the primary award criterion. Brazilian and Indian transit authorities increasingly contract total-cost-of-ownership frameworks incorporating energy consumption, maintenance intervals, and residual value guarantees. This recalibration favors aluminum-intensive and composite-reinforced chassis designs despite higher initial capital outlay.
Bus Chassis Market Segmentation
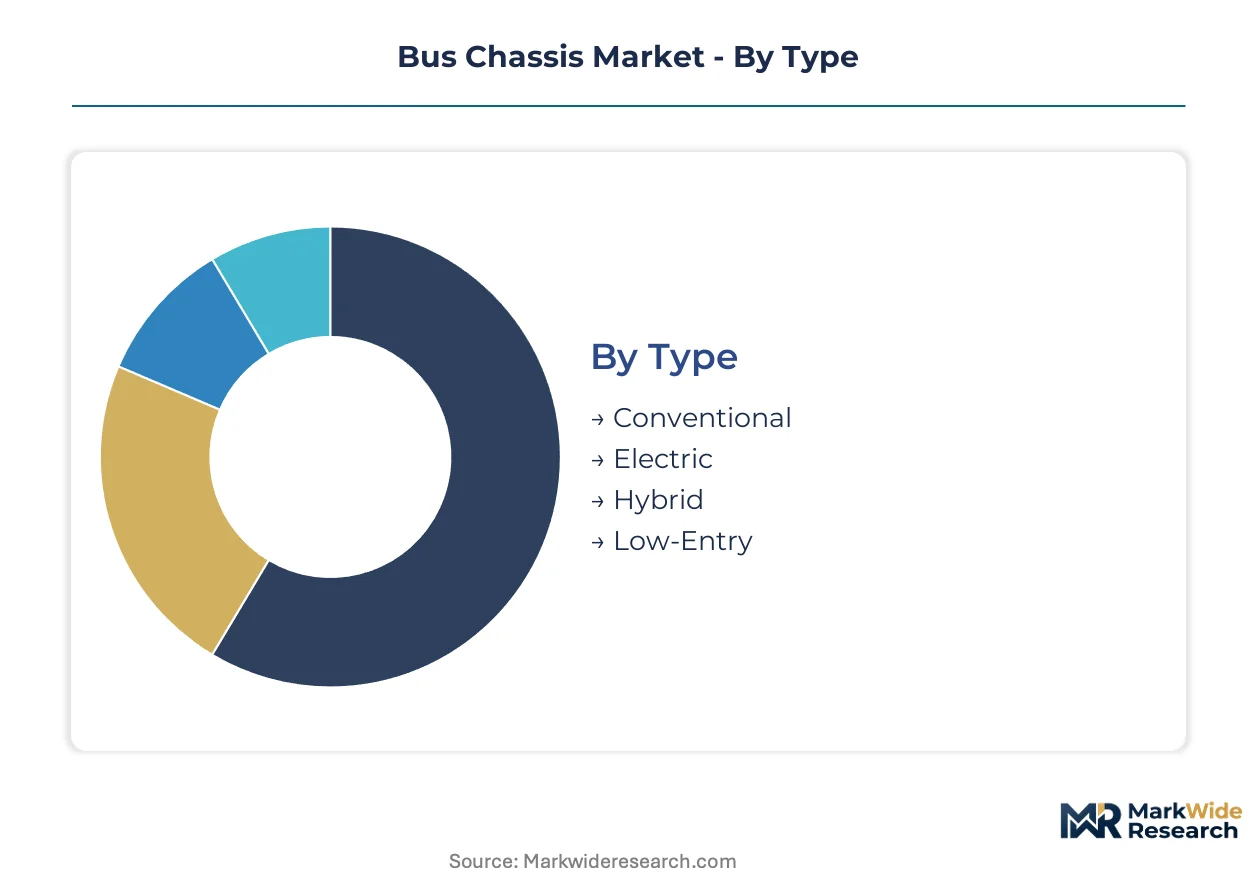
Bus chassis segmentation reveals how procurement priorities split between electrification-ready platforms and legacy diesel architectures. Fleet managers weigh total-cost-of-ownership models against upfront capital constraints when selecting across type, material, and application categories.
Type:
Replacement cycles for municipal fleets are compressing as zero-emission mandates force earlier retirement of diesel platforms across German, French, and Brazilian transit authorities.
- Electric:Dedicated frame architectures integrate structural battery mounting points with reinforced floor pans and thermal management routing. São Paulo and Rio de Janeiro metropolitan procurement programs favor these configurations for articulated corridor services.
- Conventional:Steel-frame diesel architectures retain dominance in price-sensitive emerging markets where charging infrastructure remains sparse. Indian state transport undertakings continue high-volume procurement of these proven designs.
- Hybrid:Dual-powertrain configurations bridge infrastructure gaps in intermediate electrification markets.
- Low-Entry:Reduced-floor designs dominate Indian metropolitan accessibility mandates and European urban procurement.
Volume placements concentrate in Conventional; the faster expansion belongs to Electric.
Application:
Cost tier differentiation separates premium intercity specifications from standardized urban transit configurations.
- Public Transport:Municipal tender frameworks now prioritize lifecycle cost modeling over upfront purchase price. Brazilian and Indian authorities contract total-cost-of-ownership structures incorporating energy consumption and maintenance intervals.
- Tour Buses:Climate-controlled cabin volumes drive aluminum-intensive and composite-reinforced specifications where corrosion resistance extends service intervals. Europe's F-Gas Regulation imposes steep compliance costs on HVAC-integrated variants.
- School Buses:Safety-mandated structural reinforcements dominate North American procurement specifications.
- Shuttle Services:Autonomous-ready sensor mounting points are emerging as a design requirement for airport and campus circulation fleets.
Public Transport captures the largest installed base; Tour Buses command the highest per-unit margins.
Material:
Supply concentration in Brazilian and Chinese structural-grade steel mills shapes input vulnerability for cost-optimized frame producers.
- Steel:Conventional high-strength grades retain volume leadership across price-sensitive procurement channels. Tata Motors anchors competitive positioning through cost-optimized steel-frame designs purpose-built for emerging markets.
- Aluminum:Intensive designs achieve weight reductions exceeding conventional steel while maintaining torsional rigidity thresholds mandated by rollover safety protocols. Premium tour and intercity segments absorb higher initial capital outlay.
- Composite:Reinforced variants gain traction in corrosion-critical applications with extended duty cycles.
- Fiberglass:Specialized enclosures and non-structural panels serve niche retrofit and aftermarket segments.
Steel dominates unit placements; aluminum is climbing the fastest on lifecycle cost advantages.
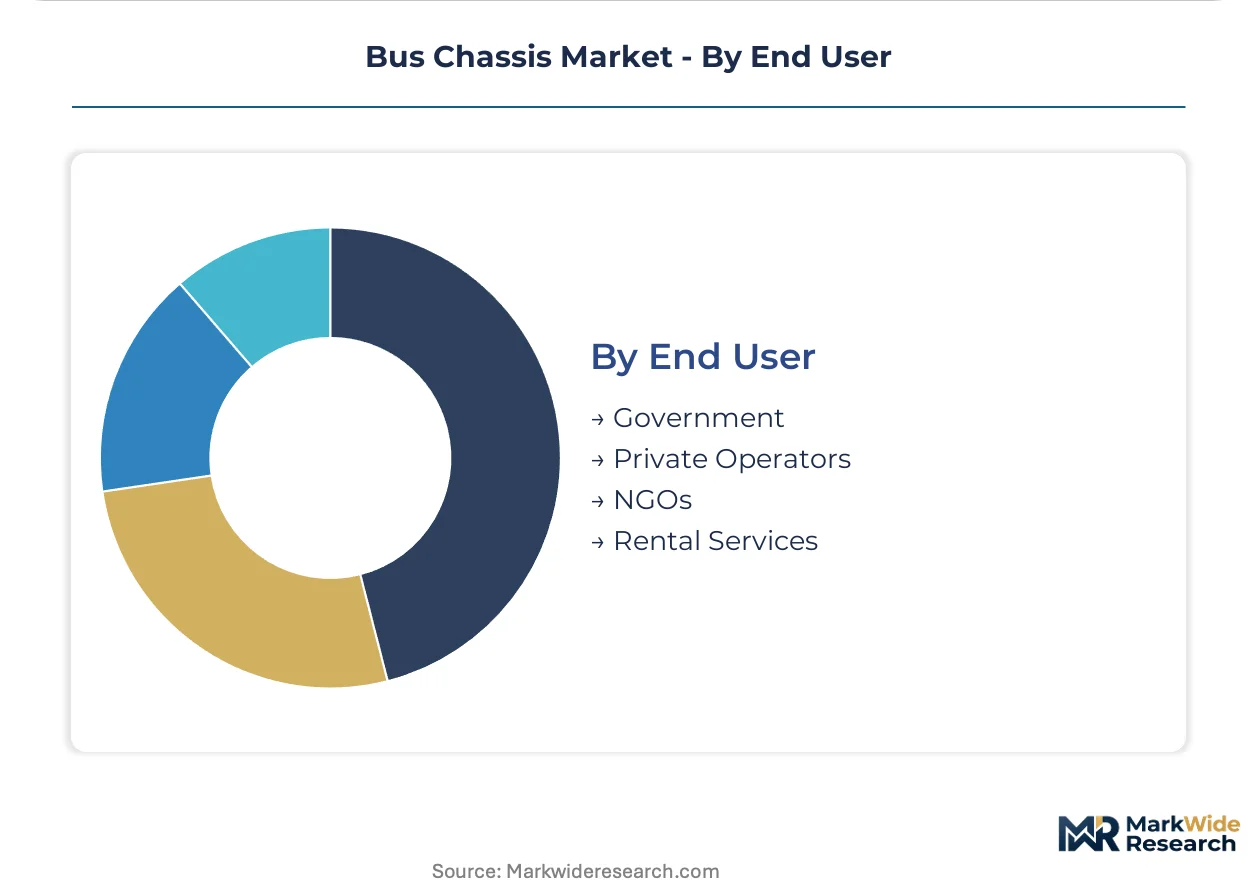
End User:
Customer type determines specification rigor, with government tenders enforcing stricter homologation and domestic content requirements than private procurement.
- Government:Municipal transit agencies drive fleet electrification programs through binding emission reduction targets. India's BIS and CEA protocols enforce localized structural testing that shapes import eligibility.
- Private Operators:Margin-focused procurement favors standardized platforms with proven residual value performance. Rental and charter segments prioritize rapid turnaround compatibility across multiple body configurations.
- NGOs:Development-funded fleet programs specify ruggedized designs for adverse road infrastructure in sub-Saharan and South Asian corridors.
- Rental Services:Asset-light operators demand modular platform families enabling flexible capacity scaling across seasonal demand fluctuations.
Government agencies anchor procurement volume; Private Operators are gaining share fastest through outsourced transit concessions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's metropolitan corridor densification anchors procurement volume for articulated low-floor chassis serving Brazil's urban transit renewal. Fleet electrification mandates in German and French transit authorities compress replacement cycles for diesel platforms. Indian state transport undertakings sustain high-volume demand for steel-frame conventional architectures.
Germany
Municipal transit agencies in Berlin and Munich accelerate zero-emission fleet procurement under binding CO2 reduction targets. The EU Green Deal and KBA certification protocols enforce stringent homologation timelines for electric chassis platforms. Baden-Württemberg's automotive cluster concentrates engineering resources for integrated battery-thermal management systems.
Brazil
São Paulo and Rio de Janeiro metropolitan expansion drives articulated bus fleet renewal with higher-capacity low-floor configurations. ANVISA and CONTRAN safety mandates shape structural testing requirements for import eligibility. Minas Gerais industrial corridors host domestic steel-frame fabrication serving price-sensitive state transport operators.
India
Maharashtra and Karnataka state transport undertakings sustain high-volume procurement of cost-optimized steel-frame designs. BIS structural testing protocols and CEA electrical safety standards enforce localized certification for foreign manufacturers. Tamil Nadu's automotive belt concentrates chassis-body integration facilities serving metropolitan accessibility mandates.
United States
California Air Resources Board zero-emission mandates and EPA greenhouse gas standards compress procurement calendars for school and transit bus operators. NHTSA crashworthiness protocols enforce safety-mandated structural reinforcements. Michigan and Ohio industrial corridors concentrate legacy platform manufacturing serving North American fleet replacement cycles.
China
Beijing and Shanghai municipal authorities mandate fleet electrification through dual carbon policy implementation. MIIT new energy vehicle standards and GB structural safety protocols shape platform architecture requirements. Yangtze River Delta manufacturing clusters concentrate aluminum-intensive frame production for premium tour bus export specifications.
Bus Chassis Market Competitive Environment
Premium-margin players sit above commodity-margin players across electrification-readiness and materials-engineering capabilities. Market structure consolidates around integrated powertrain specialists, cost-optimized steel fabricators, and modular platform architects. Strategic archetypes span captive vertical integration, emerging market localization, and skateboard standardization. Dominant competitive moves include dedicated battery-electric platform launches and multi-material joining capability acquisitions.
Within the integrated powertrain tier, Daimler Truck and AB Volvo exemplify premium positioning through dedicated zero-emission chassis architectures. Tata Motors anchors the cost-optimized steel-frame segment purpose-built for high-volume emerging market procurement. Ashok Leyland occupies a specialist position in modular low-entry configurations dominating Indian metropolitan tender cycles.
| Leading Market Players |
|---|
| Tata Motors |
| Daimler Truck |
| AB Volvo |
| Scania |
| Ashok Leyland |
| MAN Truck & Bus |
| Mercedes-Benz |
| Iveco |
| Blue Bird Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of battery-thermal management systems anchors Daimler Truck's premium pricing power while forcing commodity steel-frame competitors into thinner margin positions. This integration choice separates lifecycle-cost-optimized municipal procurement from upfront-price-sensitive emerging market tenders.
Pricing Analysis
Outcome-based pricing tied to total-cost-of-ownership guarantees now dominates German and Brazilian municipal tender evaluations. Three-tier pricing structure across premium aluminum-intensive, standard hybrid steel-aluminum, and economy all-steel configurations reflects certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because Brazilian and Chinese mill concentration erodes bargaining leverage for volume buyers. State transport undertakings in India exhibit highest price sensitivity; European tour bus operators absorb premium positioning for corrosion-resistant specifications.
Supply Chain Analysis
Single-source vulnerability sits with Chinese structural-grade steel and South Korean lithium-ion cell suppliers feeding electric platform production. Brazilian Minas Gerais corridors and Yangtze River Delta clusters anchor steel and aluminum supply respectively, while German Baden-Württemberg engineering centers feed thermal management component design. Tariff exposure on battery-grade aluminum and high-strength steel creates margin volatility for frame fabricators. Distribution runs through OEM captive networks and authorized body-builder partnerships serving municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase where dedicated battery-electric architectures displace legacy diesel platform derivatives. Frame engineering now separates winners from commodity assemblers.
For Market Incumbents: To counter margin erosion from lithium-ion cost volatility, deepen backward integration into battery-thermal management systems and reinforce aluminum-steel hybrid joining capabilities through technician certification programs. Lock long-term offtake agreements with Brazilian and Chinese steel mills to defend input cost positions against spot market swings. For New Entrants and Emerging Players: Digital direct-to-municipality tender platforms offer the lowest-friction entry path for specialized electric chassis variants. Target Indian state transport accessibility mandates and Eastern European retrofit electrification kits as penetrable white-space segments. Lead with lifecycle cost modeling tools that displace upfront price evaluation in procurement committees. For Investors and Strategic Acquirers: Exit pathways concentrate in platform standardization specialists with multi-material joining IP and established municipal fleet relationships. Five-to-ten year viability hinges on electrification-readiness certification breadth rather than diesel legacy volume. Watch for inflection signals in India's PLI scheme disbursement velocity as a proxy for localization commitment durability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Thermal Management Integration | Captive engineering of heat exchanger and compressor architectures satisfies EU F-Gas Regulation compliance mandates. |
| Multi-Material Joining Capability Acquisition | Aluminum-steel hybrid welding expertise unlocks premium tour bus specifications with extended corrosion resistance. |
| Skateboard Platform Standardization | Modular frame families reduce engineering change orders for Daimler Truck and AB Volvo variant proliferation. |
| Municipal Lifecycle Cost Contracting | Total-cost-of-ownership frameworks displace upfront price criteria in Brazilian and Indian tender evaluations. |
| Retrofit Electrification Kit Development | Aftermarket conversion packages address installed diesel base in Southeast Asian and Eastern European corridors. |
Study Parameters
SEC 10-K filings, EU transport authority procurement databases, and IHS Markit vehicle registration data formed the secondary backbone. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, and municipal fleet managers combined with secondary validation through bottom-up and top-down triangulation. Conversations with body-builder operations heads and aftermarket service distributors filled channel structure gaps.
Bottom-up modeling aggregated segment-level volume and value outputs across the projection horizon. Segmentation dimensions included propulsion architecture, material grade tier, application type, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical replacement cycle compression and electrification mandate timelines. Battery-pack integration engineering intensity and steel-aluminum price spreads served as industry-specific forecast inputs.
Inputs from OEM disclosure filings and municipal tender databases were available through the study window; gaps in private operator fleet deployment schedules introduce uncertainty bands around electric platform adoption velocity. Forecasts reflect documented assumptions on charging infrastructure buildout rates and battery cell cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Luxury Bus Market
Buses
Bus Seat Market
Buses
Intercity Bus Travel Market
Buses
Europe Trolley Bus Market
Buses
Bus Charter Services Market
Buses
Canada School Bus Market
Buses
Global Bus Market
Buses
Bus Transmission System Market
Buses
United States School Bus Market
Buses
Africa Electric Bus Market
Buses
Hydrogen Buses Market
Buses
United States Electric Bus Market
Buses
Europe Bus Market
Buses
Airport Bus Market
Buses
Fuel Cell Electric Bus Market
Buses
Bus Flooring Market