
 Africa Electric Bus Market | 2026-2036
Africa Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Electric Bus Market Outlook
Skilled battery-electric technician availability is redrawing competitive boundaries across the continent. BYD Auto Co., Ltd. leverages its integrated cell-to-pack manufacturing footprint to undercut module-level assemblers on total cost of ownership. Kiira Motors Corporation anchors Uganda's nascent electric mobility industrialization through local chassis assembly partnerships. BasiGo competes on pay-as-you-drive financing models that eliminate upfront capital barriers for Nairobi and Kigali operators.
An electric bus denotes a battery-electric transit vehicle propelled by permanent magnet synchronous motors, typically employing lithium iron phosphate or nickel manganese cobalt cell chemistries with nominal pack voltages between 400V and 800V, designed for high-cycle urban passenger duty. Single deck configurations dominate African procurement due to road geometry constraints and lower per-unit capital requirements, while LFP battery technology leads on thermal stability and cycle life under tropical operating conditions. Fast charging infrastructure commands disproportionate attention from fleet planners, though depot charging sustains the majority of operational deployments where overnight dwell times exceed eight hours.
Kenya's Energy and Petroleum Regulatory Authority, South Africa's National Regulator for Compulsory Specifications, and Rwanda's Rwanda Utilities Regulatory Authority collectively shape vehicle homologation, grid interconnection standards, and import tariff structures. The report notes that stakeholders must track how each national regulator sequences charging infrastructure licensing relative to fleet procurement timelines, as misalignment strands capital in underutilized assets. Procurement committees in Addis Ababa, Dar es Salaam, and Accra now face decisive vendor selection moments where after-sales service density matters more than headline unit pricing.
Market Dynamics
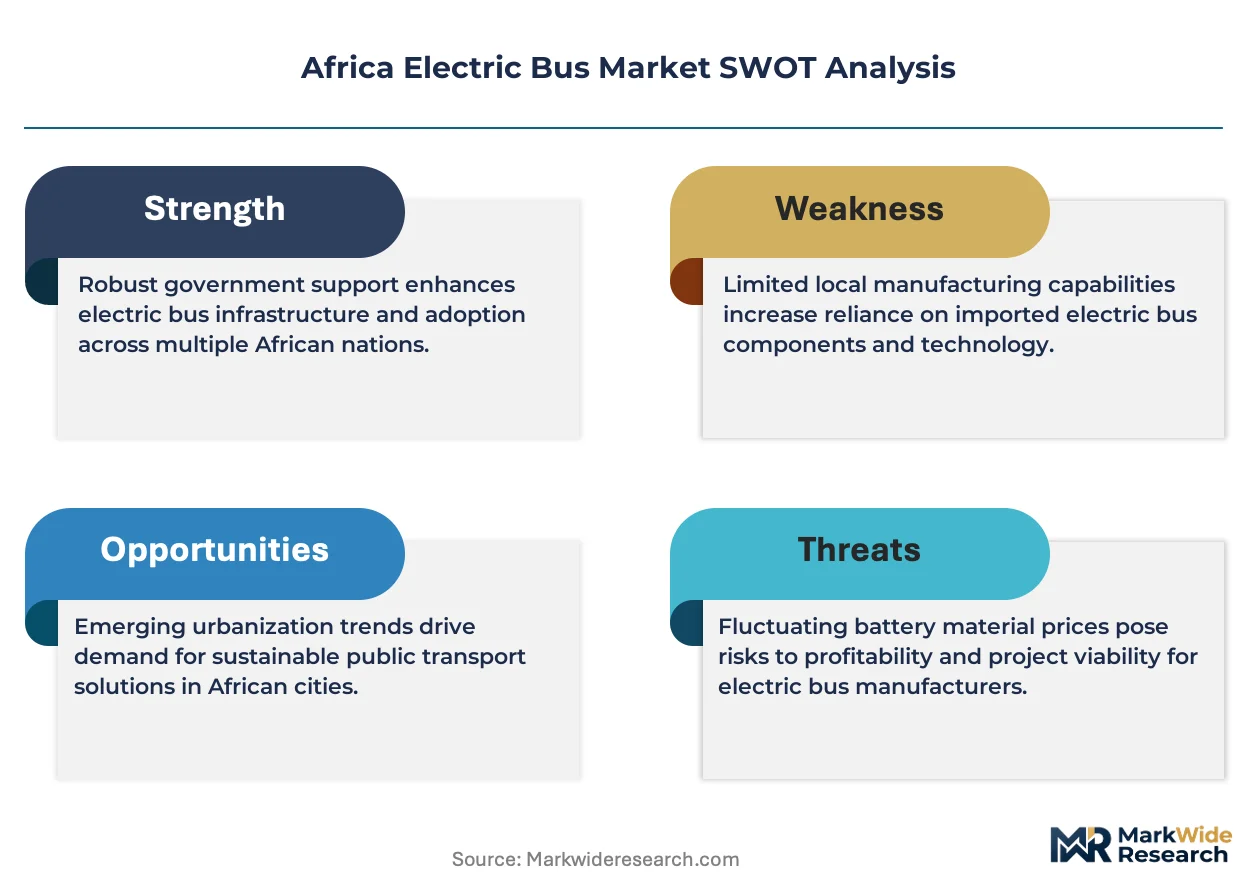
The battery-electric bus market across Africa is being fundamentally restructured by the emergence of pay-as-you-drive financing models that eliminate upfront capital barriers for fleet operators. This shift is compressing procurement cycles and redrawing competitive boundaries between integrated manufacturers and local assemblers.
Growth Catalysts
- South Africa's carbon tax adjustments:These fiscal instruments are accelerating battery-electric bus deployment by internalizing externalities and improving total cost of ownership calculations for municipal transit agencies.
- Bus rapid transit electrification programs:Corridor cities across East Africa are advancing dedicated lane infrastructure that prioritizes zero-emission vehicle compatibility and high-frequency service patterns.
- Lithium iron phosphate cell chemistry:This battery technology leads procurement specifications due to superior thermal stability and cycle life under tropical operating conditions with minimal active thermal management.
Market Restraints
- Charging infrastructure capital intensity:Grid interconnection upgrades and fast charging hardware require substantial upfront investment that strains municipal budgets before fleet revenue materializes.
- Skilled technician scarcity:The limited availability of battery-electric drivetrain specialists concentrates service capacity in major metropolitan areas, leaving secondary cities underserved.
- Import tariff structures:Rwanda's Rwanda Utilities Regulatory Authority maintains vehicle homologation requirements that extend lead times for non-regional suppliers.
Strategic Opportunities
- Depot charging optimization:Overnight dwell times exceeding eight hours in Nairobi and Kigali enable slow charging infrastructure that reduces grid interconnection costs versus fast charging alternatives.
- Local chassis assembly partnerships:Uganda's nascent electric mobility industrialization creates captive supply opportunities for regional component manufacturers seeking tariff advantages.
- Renewable energy procurement rules:South Africa's regulatory framework mandates clean electricity sourcing for public fleets, creating bundled energy-transportation service models.
Industry Challenges
- Homologation timeline fragmentation:Kenya's Energy and Petroleum Regulatory Authority, South Africa's National Regulator for Compulsory Specifications, and Rwanda's Rwanda Utilities Regulatory Authority maintain non-harmonized certification requirements that multiply compliance costs for multi-country operators.
- After-sales service density requirements:Procurement committees in Addis Ababa, Dar es Salaam, and Accra now prioritize vendor selection based on spare parts warehousing and technician deployment proximity over headline unit pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Electric Bus Market |
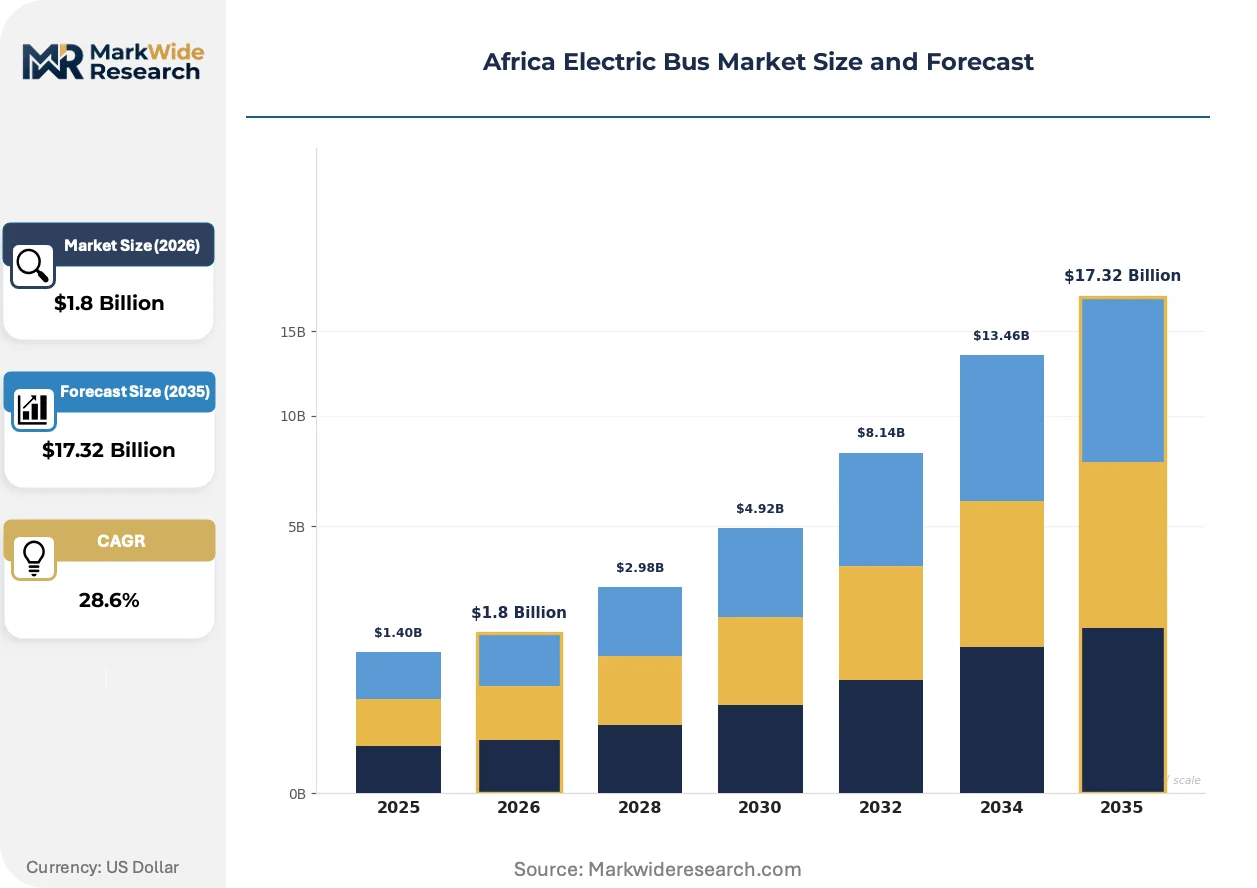
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Double Decker, Single Deck, Articulated, Mini Bus Battery Technology: LFP, NMC, LTO, Others Power Output: 150 kW, 200 kW, 250 kW, 300 kW Charging Infrastructure: Fast Charging, Depot Charging, Wireless Charging, On-route Charging |
| Companies Covered | BYD Auto Co., Ltd., Zhengzhou Yutong Bus Co., Ltd., King Long United Automotive Industry Co., Ltd., Zhongtong Bus Holding Co., Ltd., Kiira Motors Corporation, Xiamen Golden Dragon Bus Co., Ltd., BasiGo, Scania AB, Volvo Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Electric Bus Market Strategic Shifts
Technology convergence and regulatory sequencing are actively compressing deployment timelines across African electric bus markets. Fleet planners are reallocating capital from vehicles toward integrated energy-transportation systems.
Permanent magnet synchronous motors paired with 800V nominal pack architectures are supplanting 400V systems in premium procurement specifications. Nairobi and Kigali operators are adopting these higher-voltage platforms to reduce charging duration and cable gauge requirements. The voltage transition is enabling depot layout densification where land constraints limit charging bay expansion.
Kenya's Energy and Petroleum Regulatory Authority is sequencing charging infrastructure licensing ahead of fleet procurement timelines to prevent capital stranding in underutilized assets. This regulatory sequencing is forcing vendors to pre-commit grid interconnection capacity before securing vehicle purchase orders. Municipal transit agencies in corridor cities are responding by bundling energy and mobility procurement into single-tender structures.
After-sales service unbundling is disrupting traditional vehicle-only sales relationships across Cairo, Lagos, and Nairobi. Fleet operators are separating drivetrain maintenance contracts from body and chassis service agreements to access specialized battery-electric technician pools. This contractual fragmentation is most visible in East African BRT programs where uptime guarantees now exceed manufacturer warranty periods.
Africa Electric Bus Market Segmentation
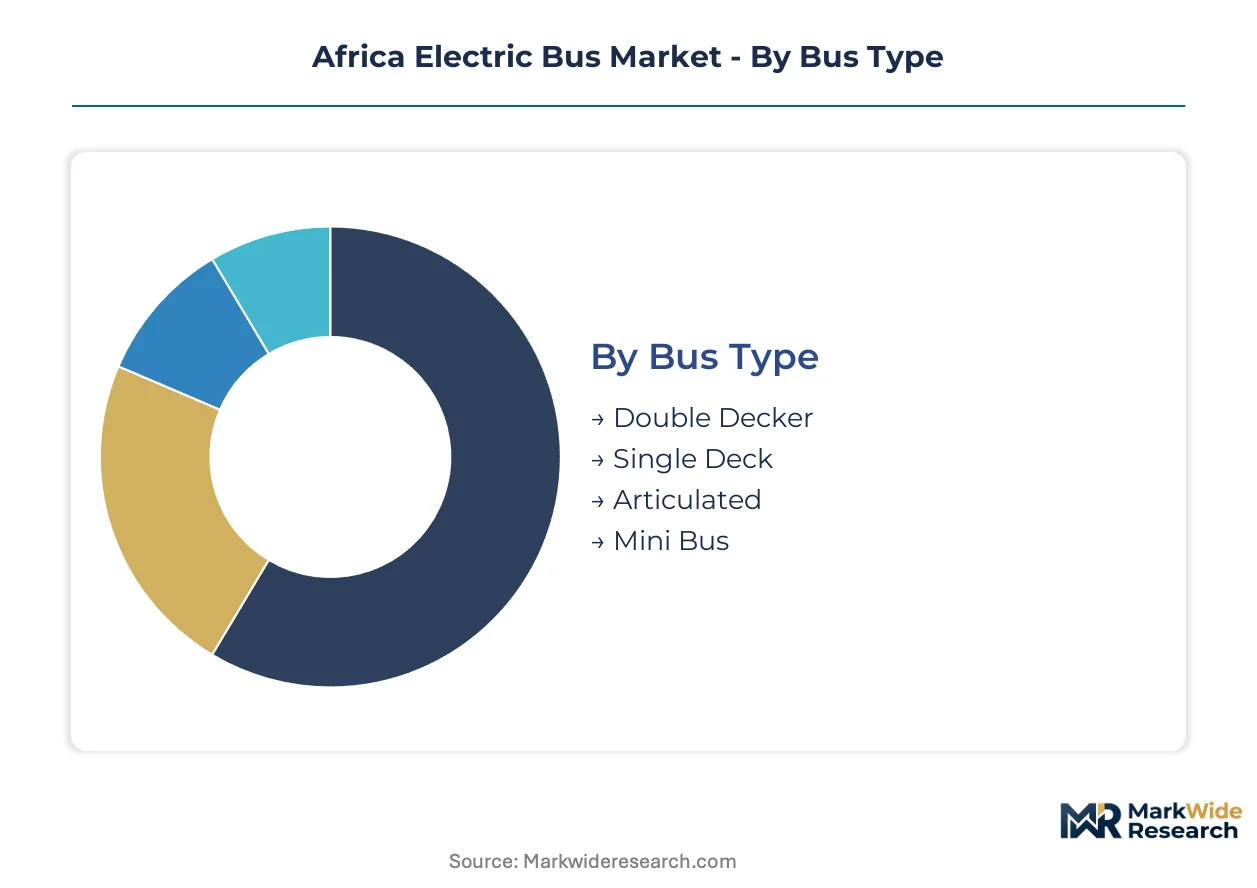
Segmentation in the Africa electric bus market reveals how procurement priorities diverge across climate zones, grid reliability profiles, and municipal budget cycles. Fleet operators in Nairobi and Lagos face fundamentally different constraints than those in Cairo or Cape Town, driving distinct technology preferences within each category.
Bus Type:
Domestic demand concentrates on single-deck configurations suited to narrow colonial-era street grids and tight turning radii, while articulated units serve export-led BRT corridor ambitions in Ethiopian and Tanzanian markets.
- Single Deck:Dominates procurement volumes across East and West African cities where road geometry constraints limit vehicle length. Nairobi's matatu replacement programs and Lagos BRT electrification specify 12-meter single-deck platforms with 80+ passenger capacity to maximize throughput on constrained rights-of-way.
- Double Decker:Limited deployment concentrates in South African metropolitan areas with dedicated bus lanes and higher bridge clearances. Cape Town's MyCiTi service evaluates these platforms for premium commuter corridors where passenger volume per road space unit justifies the vertical complexity.
- Articulated:Deployed exclusively in dedicated BRT corridors where platform-level boarding and segregated lanes justify the 18-meter length. Addis Ababa's Sheger Express and Dar es Salaam's DART expansion specify these for high-frequency trunk routes.
- Mini Bus:Serves feeder routes and peri-urban penetration where full-size buses face accessibility constraints. Kigali's last-mile electrification pilots test 7-meter platforms for hillside residential access.
Single deck holds the largest share; momentum sits with articulated configurations as BRT electrification accelerates.
Battery Technology:
Cost tier differentiation separates premium NMC deployments in temperature-controlled South African fleets from value-engineered LFP specifications dominating tropical East African markets.
- LFP:Comprises lithium iron phosphate cells with superior thermal stability and 3,000+ cycle life under minimal active cooling. Procurement committees in Kampala, Kigali, and Mombasa prioritize this chemistry for depot-charged fleets where overnight dwell times enable slow charging and ambient heat stresses battery longevity.
- NMC:Nickel manganese cobalt formulations deliver higher energy density for weight-constrained double-decker and articulated applications. Johannesburg and Cape Town operators specify these where air-conditioned depots permit tighter thermal management and route lengths demand maximum range per charge.
- LTO:Lithium titan oxide cells tolerate extreme fast charging cycles but carry prohibitive cost premiums for African municipal budgets. Limited pilot deployments in Cairo's central business district shuttle services test 10-minute opportunity charging.
- Others:Emerging sodium-ion and solid-state chemistries remain pre-commercial for heavy-duty transit applications. Moroccan and Egyptian research partnerships evaluate these for future manufacturing localization.
LFP dominates installed capacity; NMC is expanding most quickly in premium corridor specifications.
Power Output:
Application-driven power requirements separate urban stop-start duty from peri-urban express services, with 150 kW units serving flat terrain mini-bus routes and 300 kW platforms tackling hilly BRT corridors.
- 150 kW:Serves mini-bus and short-route single-deck applications in flat terrain cities like Dakar and Lomé where acceleration demands remain modest and energy conservation priorities dominate.
- 200 kW:Standard specification for 12-meter single-deck urban duty cycles across Nairobi, Lagos, and Accra, balancing hill-climbing capability with motor cost containment.
- 250 kW:Deployed in articulated BRT configurations and double-decker applications where passenger load variability and air conditioning draw strain electrical systems. Dar es Salaam's DART trunk routes specify this threshold.
- 300 kW:Reserved for high-performance articulated platforms in mountainous terrain and premium express services. Addis Ababa's elevation changes and Kigali's hillside corridors drive limited procurement.
200 kW anchors the installed base; 250 kW is gaining share fastest as BRT electrification scales.
Charging Infrastructure:
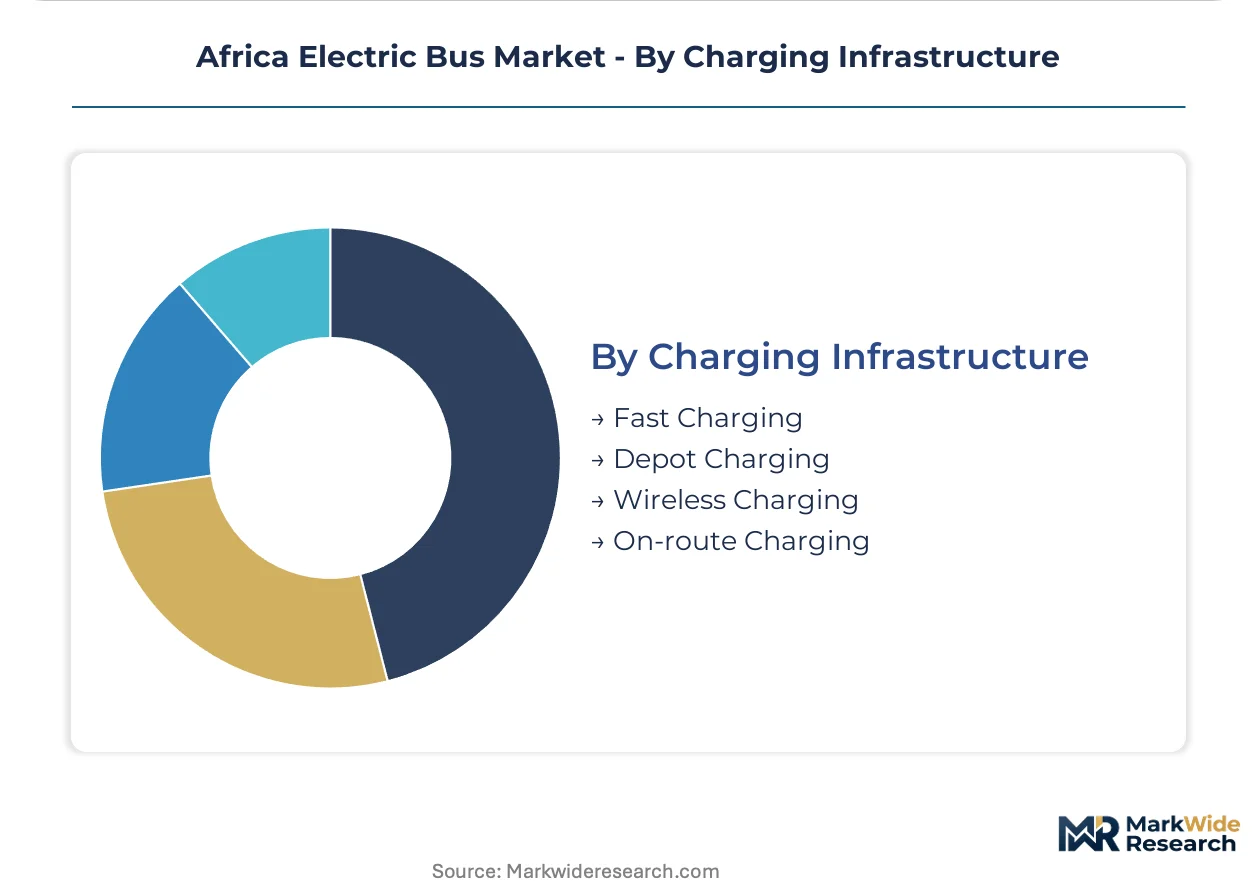
Supply concentration in Chinese and European charging hardware vendors shapes procurement patterns, with depot charging sustaining operational deployments and fast charging commanding disproportionate planning attention.
- Depot Charging:Overnight slow charging at 50-150 kW dominates operational economics where fleets return to central facilities for 8+ hour dwell periods. Nairobi and Kigali operators optimize around this model to minimize grid interconnection costs and battery degradation.
- Fast Charging:350+ kW opportunity charging enables extended range operation but requires substantial grid upgrades and demand charge management. Cairo's grid stability and South Africa's renewable procurement rules create viable deployment conditions absent elsewhere.
- On-route Charging:Pantograph or plug-in infrastructure at terminal stations extends effective range without full fast charging investment. Lagos BRT terminals and Accra's Aayalolo stations evaluate this for interlining flexibility.
- Wireless Charging:Inductive systems remain pilot-stage across African markets due to cost premiums and alignment precision requirements. Limited testing in Casablanca and Tunis explores autonomous bus compatibility.
Depot charging holds the largest share; on-route charging shows steepest expansion trajectory as interlining requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's National Regulator for Compulsory Specifications anchors the continent's most advanced electric bus certification framework. The country's carbon tax adjustments and renewable energy procurement rules create fiscal conditions that improve total cost of ownership calculations for municipal fleet operators.
South Africa
Cape Town's MyCiTi service and Johannesburg's Rea Vaya network drive procurement volumes for premium double-decker and articulated configurations. The National Regulator for Compulsory Specifications maintains stringent homologation timelines that favor established suppliers with local service infrastructure. Industrial clustering concentrates in Gauteng province where aftermarket parts warehousing and technician training facilities serve the Southern African Development Community corridor.
Kenya
Nairobi's matatu replacement programs and BRT electrification specify 12-meter single-deck platforms with 80-plus passenger capacity. The Energy and Petroleum Regulatory Authority sequences charging infrastructure licensing ahead of fleet procurement to prevent capital stranding. Manufacturing partnerships in Thika and Athi River industrial zones localize chassis assembly for East African Community markets.
Rwanda
Kigali's last-mile electrification pilots test 7-meter mini-bus platforms for hillside residential access routes. The Rwanda Utilities Regulatory Authority maintains vehicle homologation requirements that extend lead times for non-regional suppliers. The Kigali Special Economic Zone hosts battery pack assembly operations serving the Northern Corridor transit corridor.
Egypt
Cairo's municipal transit agencies expand zero-emission fleets across the Greater Cairo metropolitan area with grid stability enabling fast charging deployment. The country's national transport regulator coordinates with utility planners on demand charge management for 350-plus kilowatt opportunity charging infrastructure. Industrial activity clusters in the 10th of Ramadan City automotive manufacturing zone.
Ethiopia
Addis Ababa's Sheger Express BRT corridor specifies articulated 18-meter platforms for high-frequency trunk routes. The Ethiopian Transport Authority aligns fleet procurement with the country's national electrification strategy and renewable energy expansion. The Eastern Industrial Zone outside Addis Ababa anchors assembly partnerships for regional export markets.
Africa Electric Bus Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Africa electric bus market. Integrated cell-to-pack manufacturers command pricing power through captive battery supply chains, while local assemblers compete on tariff advantages and proximity to end-users. The vendor base separates into three strategic archetypes: Chinese integrated manufacturers with full vertical control, regional African assemblers with government partnerships, and European premium specialists with service density commitments. Dominant competitive moves include local chassis assembly partnerships that circumvent import duties, and pay-as-you-drive financing models that eliminate upfront capital barriers for fleet operators.
Among Chinese integrated manufacturers, BYD Auto Co., Ltd. and Zhengzhou Yutong Bus Co., Ltd. represent the scale-driven archetype with established African market presence. Kiira Motors Corporation occupies a position within the regional assembler tier, anchoring Uganda's electric mobility industrialization through government-backed partnerships. BasiGo exemplifies the financing-innovation archetype, competing on operational expenditure models rather than capital equipment sales. These three company types collectively illustrate how competitive boundaries are redrawn across technology integration, local content requirements, and capital structure innovation.
| Leading Market Players |
|---|
| BYD Auto Co., Ltd. |
| Zhengzhou Yutong Bus Co., Ltd. |
| King Long United Automotive Industry Co., Ltd. |
| Zhongtong Bus Holding Co., Ltd. |
| Kiira Motors Corporation |
| Xiamen Golden Dragon Bus Co., Ltd. |
| BasiGo |
| Scania AB |
| Volvo Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-120-day battery pack lead times from Chinese cell manufacturers concentrate pricing power with integrated producers holding captive lithium carbonate positions, while African fleet operators face working capital strain that favors pay-as-you-drive intermediaries over direct procurement. This temporal compression in component availability is reshaping how municipal transit agencies evaluate total cost of ownership against headline unit prices.
Pricing Analysis
Price spreads between Cairo and Kigali exceed fifteen percent due to divergent import tariff structures and local assembly incentives. Three-tier pricing structure across premium, standard, and economy levels separates BYD's integrated cell-to-pack offerings from module-level assemblers and refurbished second-life battery platforms. Cost compression in the economy tier is intensifying because Kenyan and Rwandan operators prioritize thermal stability specifications over energy density. Mini-bus fleet owners in Kigali exhibit highest price sensitivity, while South African BRT procurement committees prioritize after-sales service density over per-unit savings.
Supply Chain Analysis
Container availability constraints on the Shanghai-Mombasa trade lane inflate landed costs for chassis and drivetrain components, forcing procurement committees to extend order horizons. Supply concentrates in China's lithium processing corridor, South Korea's cathode material production, and South Africa's downstream assembly zones. Raw material dependencies span lithium carbonate from Chilean and Australian spodumene, cobalt hydroxide from the Democratic Republic of Congo, and copper busbars from Zambian smelters. Single-source vulnerability in LFP cell supply creates exposure to China's export license protocols. Distribution runs through Nairobi and Johannesburg regional warehousing hubs serving East and Southern African Community markets respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal transit agency consolidation into multi-city procurement consortia across the Northern Corridor is shifting bargaining power toward volume-aggregated buyers and away from fragmented single-fleet negotiations.
For Market Incumbents: Compound service density advantages by pre-positioning battery-electric technician pools in secondary cities before competitor entry. Anchor spare parts warehousing in Gauteng and Nairobi industrial zones to defend against pay-as-you-drive financing entrants eroding capital equipment sales. Prioritize backward integration into LFP cell assembly through partnerships with Morocco and Egypt's emerging battery manufacturing zones. For New Entrants and Emerging Players: Lead with depot charging optimization software targeting Nairobi and Kigali operators where overnight dwell times exceed eight hours. White-space targets include peri-urban feeder routes in Addis Ababa and Accra where full-size bus accessibility constraints create mini-bus electrification demand. Go-to-market angle: bundle energy procurement with vehicle leasing under single-tender municipal structures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant automotive assembly licenses in East African Community countries. Long-term viability hinges on regulatory sequencing alignment between charging infrastructure licensing and fleet procurement timelines. Acquisition archetype: regional assemblers with established government partnerships and tariff-advantaged chassis production. Signal to watch: harmonization progress between Kenya's Energy and Petroleum Regulatory Authority and Rwanda's Rwanda Utilities Regulatory Authority on cross-border vehicle homologation.| Strategic Initiative | Industry Significance |
|---|---|
| Local Chassis Assembly Partnership | Circumvents East African Community import duties while satisfying local content requirements for municipal tenders. |
| Pay-as-You-Drive Financing Model | Eliminates upfront capital barriers for Nairobi and Kigali operators, compressing procurement cycles versus traditional vehicle sales. |
| Depot Charging Infrastructure Pre-commitment | Prevents capital stranding by sequencing grid interconnection ahead of fleet procurement timelines per Kenyan regulatory guidance. |
| After-Sales Service Unbundling | Enables specialized battery-electric technician access for East African BRT programs demanding uptime guarantees exceeding manufacturer warranties. |
| LFP Battery Chemistry Localization | Reduces dependency on Chinese cell imports while leveraging thermal stability advantages under tropical operating conditions. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal transit procurement managers, fleet operations directors, battery-electric drivetrain engineers, charging infrastructure planners, and regulatory affairs specialists at national energy authorities. Secondary validation drew from vehicle registration databases, customs import records, national regulator licensing disclosures, and power utility grid interconnection filings. Bottom-up fleet deployment tallies triangulated against top-down market sizing from automotive production statistics and lithium-ion battery trade flows.
Across the analysis window, projections integrated bus type segmentation by configuration, battery chemistry tiering, power output banding, and charging infrastructure modality. Modeled dimensions included urban duty cycle intensity, grid reliability profiles, and municipal budget cycle phasing. CAGRs derived from logistic diffusion curves fitted to early-adopter deployment trajectories in South Africa and Kenya, calibrated against carbon tax adjustment schedules and renewable energy procurement rule implementation pacing.
Forecasts assume regulatory continuity in South Africa's National Regulator for Compulsory Specifications, Kenya's Energy and Petroleum Regulatory Authority, and Rwanda's Rwanda Utilities Regulatory Authority; material policy shifts in homologation timelines or import tariff structures would require re-modeling. Forecasts reflect assumptions on lithium carbonate price stability, grid interconnection capacity expansion, and technician training pipeline throughput. Recalibration cycles align with material shifts in national carbon pricing mechanisms and BRT corridor electrification program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
United States School Bus Market
Buses
School Bus Market
Buses
Intercity Bus Travel Market
Buses
Europe Bus Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Bus Flooring Market
Buses
Bus Charter Services Market
Buses
Bus Chassis Market
Buses
Canada School Bus Market
Buses
United States Electric Bus Market
Buses
Hydrogen CNG Bus Market
Buses
Solar Bus Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Global Bus Market
Buses
Airport Bus Market
Buses
Bus Transmission System Market