
 Bus Rental Market | 2026-2036
Bus Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Rental Market Analysis
Composite body panels and aluminum chassis components are restructuring total cost of ownership equations for fleet operators replacing traditional steel frames. Academy Bus leverages its Northeast corridor density to sustain contracted commuter volumes. GOGO Charters competes through technology leadership in digital booking interfaces. National Charter Bus anchors its position with geographic dominance across multiple metropolitan markets.
Bus rental denotes the commercial provision of motorized passenger vehicles with seating capacities typically exceeding fifteen occupants, operated under temporary charter agreements rather than scheduled public transit routes. These vehicles incorporate diesel, compressed natural gas, battery-electric, or hydrogen fuel cell powertrains depending on regulatory environment and route profile. Corporate Rentals and Event Charters command the largest revenue pools given contracted multi-year agreements and premium pricing for dedicated service. Luxury Coaches represent the fastest-growing vehicle category as executive travel and high-end tourism segments expand procurement. Online Platforms are displacing Phone Reservations as the dominant booking channel, concentrating margin capture with digitally integrated fleet operators.
The EPA and NHTSA govern emissions and safety standards for US-based fleets, while Euro VI and the EU Green Deal shape European procurement toward zero-emission transitions. CARB regulations in California function as a de facto national standard for US operators serving interstate routes. Fleet managers must monitor battery-electric total cost crossover points against diesel baselines and assess charging infrastructure commitments before committing to capital-intensive fleet transitions.
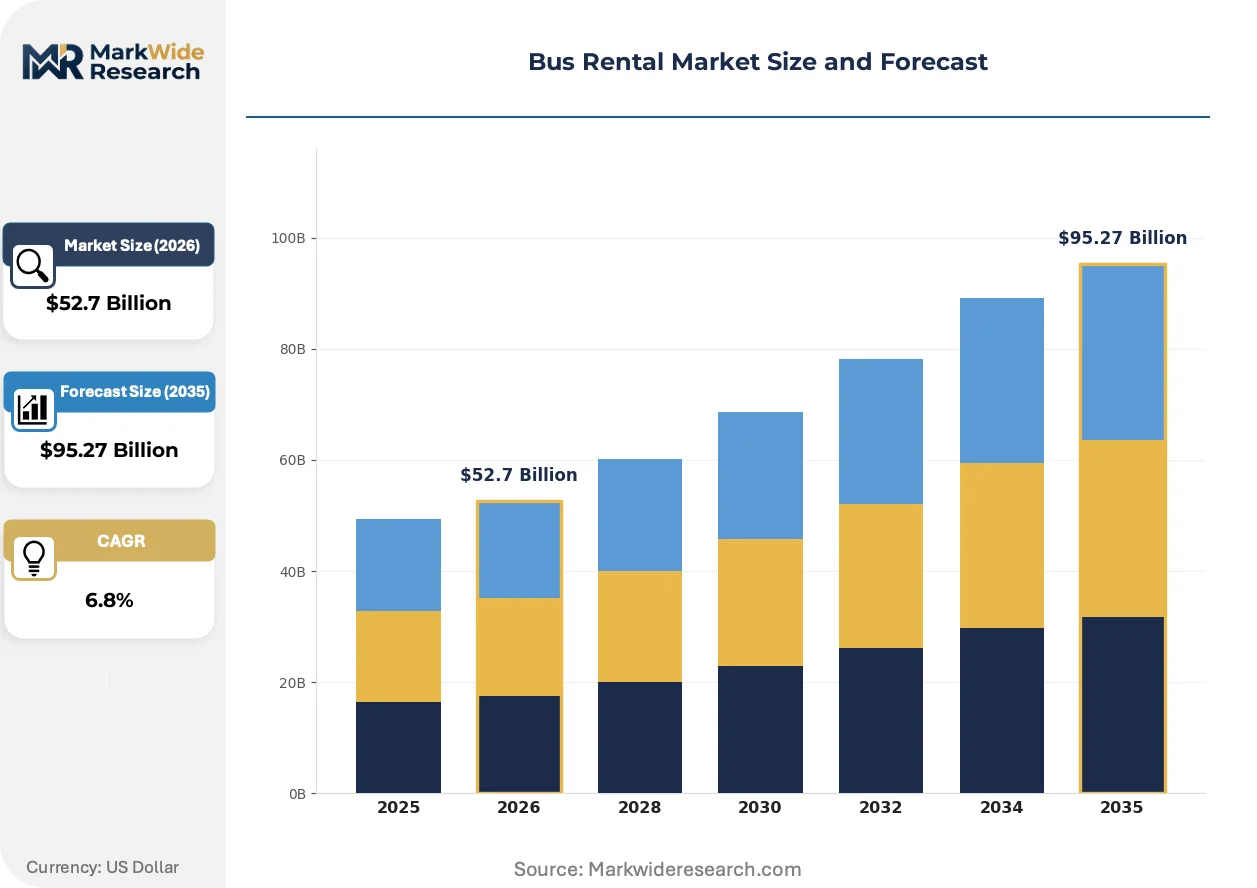
Market Dynamics
Fleet electrification timelines are compressing procurement cycles as operators weigh battery-electric total cost of ownership against diesel baselines before California's CARB mandates take full effect.
Growth Catalysts
- Corporate Shuttle Outsourcing:Technology campuses in the United States are expanding dedicated commuter contracts to reduce parking infrastructure costs and meet Scope 3 emissions targets.
- Euro VI Compliance Deadlines:German and French fleet operators are replacing aging diesel inventories ahead of enforcement windows, creating replacement demand for low-emission coaches.
- Lithium-Ion Battery Cost Curves:Cell price declines are narrowing the capital expenditure gap between electric and combustion powertrains for high-utilization route profiles.
Market Restraints
- Charging Infrastructure Gaps:Depot electrification requires utility interconnection timelines that stretch 18-36 months in constrained grid zones.
- Steel and Aluminum Volatility:Chassis material input costs swing with energy-intensive smelting economics, pressuring contract pricing stability.
- Driver Shortage Concentration:Commercial license attainment bottlenecks in the United States and Germany limit fleet expansion regardless of vehicle availability.
Strategic Opportunities
- Intercity Tourism Recovery:Chinese domestic travel corridors are rebuilding charter volumes as visa processing friction diverts outbound demand inward.
- Hydrogen Fuel Cell Pilots:German federal transport subsidies are covering fuel cell bus trials on routes exceeding battery-electric range thresholds.
- Dynamic Pricing Platforms:Real-time yield management software is penetrating the phone-reservation channel, capturing margin from price-inelastic event segments.
Industry Challenges
- High-Voltage Technician Scarcity:Battery-electric maintenance requires specialized certification programs that vocational institutions have not yet scaled to fleet demand.
- Depot Retrofit Capex Burden:Electrical infrastructure upgrades consume capital that competes with vehicle procurement in multi-year budget cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Rental Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Rentals, Event Charters, Group Travel, School Trips Vehicle Type: Passenger Buses, Luxury Coaches, Mini Buses, Sleeper Buses Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Phone Reservations Client Type: Corporations, Educational Institutions, Tour Operators, Private Clients |
| Companies Covered | Prime Charter Bus, Academy Bus, GOGO Charters, San Francisco Charter Bus Company, NYC Charter Bus Company, National Charter Bus, Nationwide Bus Charter, Anaheim Regional Transportation, TCS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Rental Market Emerging Trajectories
Digital booking interfaces and connected fleet management systems are redistributing market power toward operators with real-time asset visibility and automated dispatch capabilities.
Telematics integration with route optimization software is decentralizing fleet control from centralized dispatch centers to driver-facing mobile applications. Regional operators in Germany and the United States are deploying these tools to reduce empty-mile ratios on charter assignments. The technology is decentralizing profit capture from large metropolitan incumbents to mid-cap specialists with leaner overhead structures.
California's CARB Advanced Clean Fleets regulation is mandating zero-emission sales quotas for heavy-duty vehicles beginning with 2024 model years. Fleet operators serving interstate routes must now spec electric or hydrogen coaches to maintain California market access. The policy is accelerating pre-buy activity ahead of compliance deadlines while compressing residual values for non-compliant diesel inventories.
Corporate travel managers are consolidating ground transportation procurement under sustainability-linked vendor scorecards. Phone-based charter brokers are losing share to platform-booking interfaces that embed carbon accounting and real-time tracking. This shift is most visible in United States technology corridors where environmental disclosure requirements now extend to Scope 3 commuter emissions.
Bus Rental Market Segmentation
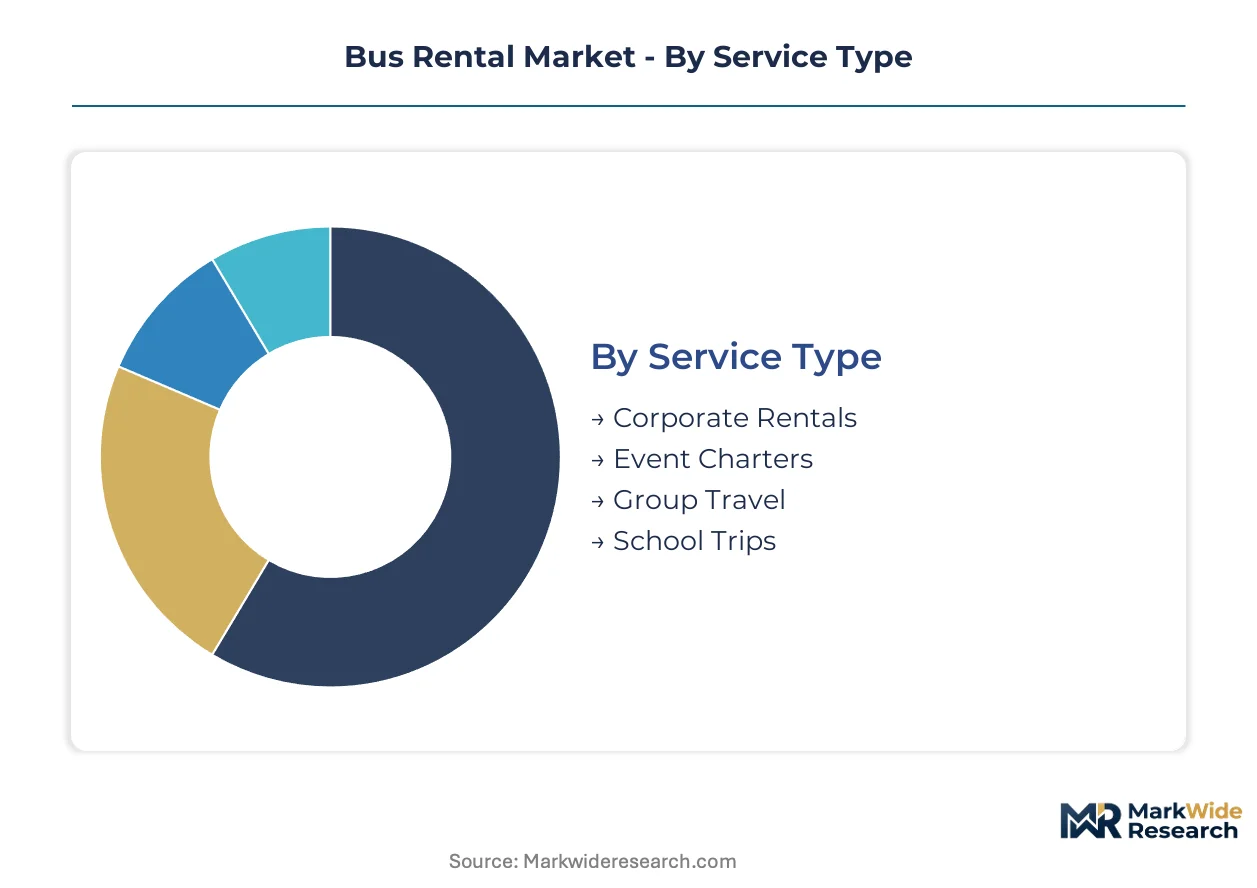
Bus rental operators structure fleet deployment and pricing architecture around four distinct segmentation axes. Service type determines contract duration and margin structure. Vehicle type dictates capital intensity and maintenance protocols. Booking channel shapes customer acquisition costs and platform economics. Client type governs seasonality patterns and payment terms.
Service Type:
Standalone charter contracts operate independently of recurring subscription models, while embedded service agreements integrate with broader corporate mobility programs.
- Corporate Rentals:Multi-year contracted shuttle services with dedicated fleet allocation and fixed pricing schedules. Technology campuses in the United States and Germany are expanding these agreements to reduce parking infrastructure costs and meet Scope 3 emissions disclosure requirements.
- Event Charters:Short-duration assignments for conventions, sporting events, and entertainment venues with premium surge pricing capabilities. Demand concentrates in metropolitan clusters where convention center throughput drives peak-season utilization rates.
- Group Travel:Intercity and regional movement for affinity groups, religious organizations, and social clubs with flexible routing requirements.
- School Trips:Recurring educational transportation with stringent safety certification mandates and seasonal volume concentration during academic calendars.
Corporate Rentals lead volumes today; Event Charters are gaining share fastest.
Vehicle Type:
Cost tier stratification separates premium-configured coaches from utilitarian passenger configurations across depreciation schedules and residual value curves.
- Passenger Buses:Standard-configuration vehicles with 40-60 seat capacities and diesel or compressed natural gas powertrains. Fleet operators in Germany are replacing aging Euro IV and Euro V inventories ahead of enforcement windows, creating replacement demand for compliant replacements.
- Luxury Coaches:Executive-class vehicles with reclining seating, onboard entertainment systems, and enhanced climate control. Executive travel segments in the United States and high-end tourism corridors in China are expanding procurement of these configurations.
- Mini Buses:Reduced-capacity vehicles serving last-mile connectivity and narrow-route accessibility requirements.
- Sleeper Buses:Overnight-configured coaches with berth accommodations for extended intercity routes.
Passenger Buses dominate fleet composition today; Luxury Coaches show the steepest expansion trajectory.
Booking Channel:
Customer acquisition economics vary sharply between digitally native platforms and legacy telephone-based reservation systems.
- Online Platforms:Digital interfaces with real-time availability, automated dispatch integration, and embedded carbon accounting tools. Corporate travel managers in United States technology corridors are consolidating procurement through these channels to satisfy environmental disclosure requirements.
- Travel Agencies:Intermediary-mediated bookings with package bundling and commission structures.
- Direct Booking:Operator-customer relationships bypassing third-party platform fees.
- Phone Reservations:Legacy voice-based booking systems losing share to platform interfaces but retaining price-inelastic event segments.
Online Platforms are displacing legacy channels; Direct Booking retains margin advantages for established operators.
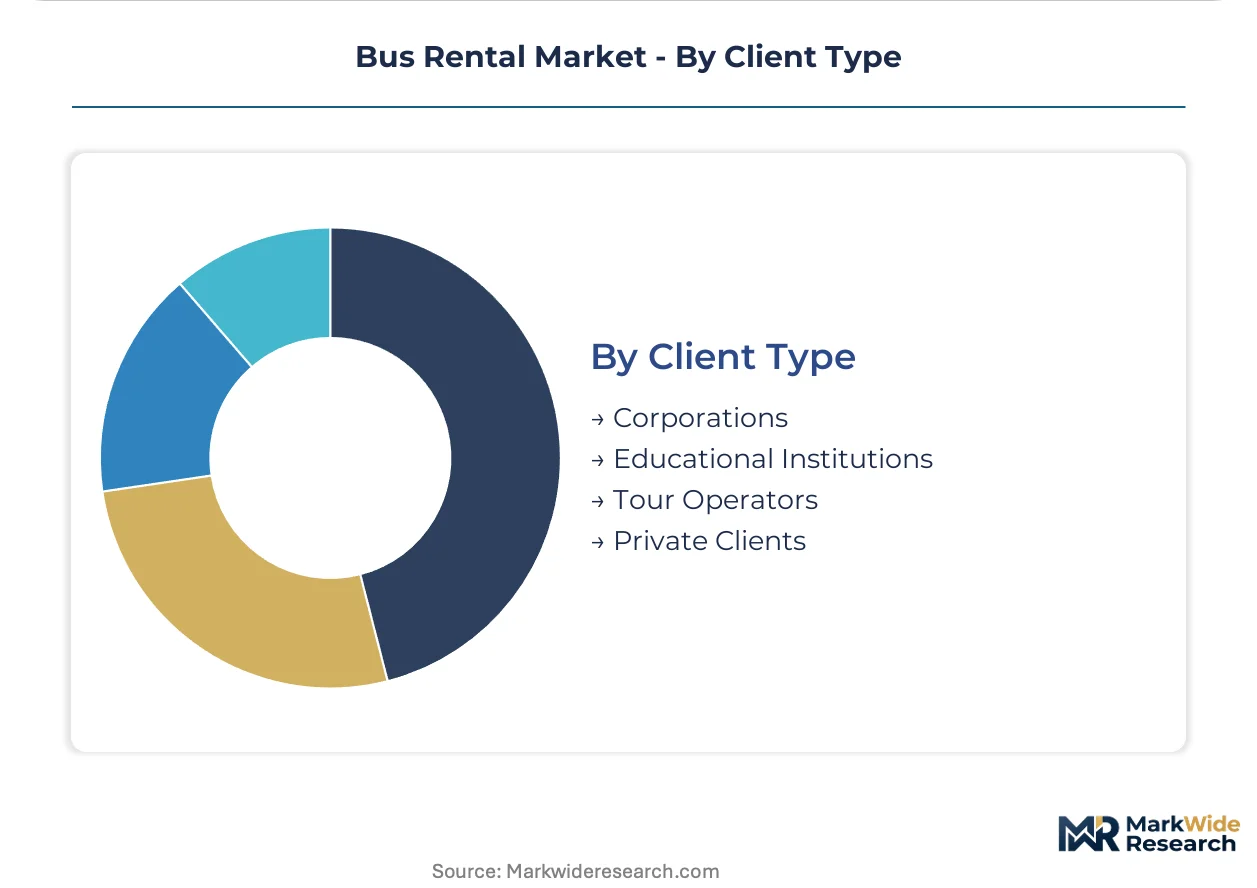
Client Type:
Volume concentration and payment reliability diverge across institutional versus individual customer bases.
- Corporations:Enterprise clients with contracted multi-year agreements, centralized procurement functions, and sustainability-linked vendor scorecards. Technology sector demand in the United States is accelerating as commuter shuttle programs expand.
- Educational Institutions:Schools and universities with seasonal demand patterns, safety certification requirements, and public procurement compliance obligations.
- Tour Operators:Intermediary clients aggregating leisure and business travel demand with itinerary customization requirements.
- Private Clients:Individual and small-group bookings with sporadic demand and higher price sensitivity.
Corporations anchor revenue stability today; Tour Operators are climbing fastest as tourism corridors rebuild.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area technology corridor generates substantial contracted shuttle demand as enterprise campuses expand commuter fleet outsourcing to manage parking costs and emissions disclosures.
United States
Corporate shuttle contracts from technology campuses in California and Washington state are displacing employee parking infrastructure. EPA and NHTSA emissions standards interact with California's CARB Advanced Clean Fleets regulation to accelerate zero-emission procurement timelines. The Northeast corridor from Boston to Washington DC sustains the densest concentration of intercity charter operators serving contracted commuter volumes.
Germany
Industrial manufacturing clusters in Bavaria and Baden-Württemberg are expanding workforce transportation contracts as labor markets tighten. Euro VI compliance deadlines and the EU Green Deal are forcing fleet turnover toward battery-electric and hydrogen fuel cell configurations. The Rhine-Ruhr metropolitan region hosts the highest density of charter operators replacing aging diesel inventories ahead of enforcement windows.
China
Domestic tourism recovery across Yangtze River Delta and Pearl River Delta corridors is rebuilding charter volumes as visa friction diverts outbound demand inward. MEE emission standards and dual carbon goals are pressuring fleet electrification in major metropolitan areas. The Beijing-Tianjin-Hebei cluster is piloting hydrogen fuel cell coaches on extended intercity routes exceeding battery-electric range thresholds.
United Kingdom
Corporate procurement consolidation in London and the Southeast is shifting ground transportation contracts toward platform-booking interfaces with embedded carbon accounting. The UK Department for Transport zero-emission bus mandates are compressing diesel residual values ahead of 2030 phase-out targets. The Midlands manufacturing belt is emerging as a secondary hub for fleet operators serving industrial workforce mobility contracts.
France
Convention center throughput in Paris and Lyon is driving peak-season utilization for event charter specialists with surge pricing capabilities. ANSM transport subsidies are covering fuel cell bus trials on cross-country routes. The Provence-Alpes-Côte d'Azur tourism corridor is expanding luxury coach procurement as high-end travel segments rebuild post-pandemic demand.
Bus Rental Market Vendor Landscape
Global majors compete with regional champions across fleet scale and geographic coverage density. The vendor base organizes into three tiers: metropolitan specialists with corridor-specific density, national platform operators with digital booking integration, and diversified transportation conglomerates with cross-modal service portfolios. Consolidation pressure concentrates among mid-cap operators seeking route network expansion. Dominant competitive moves include strategic partnerships with technology platforms and backward integration into charging infrastructure development.
Among US-based charter operators, Academy Bus, GOGO Charters, and National Charter Bus exemplify contrasting strategic archetypes. Academy Bus occupies a position as a Northeast corridor density specialist with sustained commuter contract volumes. GOGO Charters represents technology-forward platform integration with digital booking interface leadership. National Charter Bus anchors the multi-metropolitan geographic coverage archetype across dispersed urban markets. These three operators collectively illustrate the segmentation between regional density, technology differentiation, and geographic breadth as competing vectors for market position.
| Leading Market Players |
|---|
| Prime Charter Bus |
| Academy Bus |
| GOGO Charters |
| San Francisco Charter Bus Company |
| NYC Charter Bus Company |
| National Charter Bus |
| Nationwide Bus Charter |
| Anaheim Regional Transportation |
| TCS |
| Others |
Supply Flow & Price Mechanics
Corporate shuttle procurement concentration among United States technology campuses anchors contract-based long-term offtake as the dominant pricing model, with multi-year agreements insulating fleet operators from spot-market volatility while compressing margins through sustainability-linked vendor scorecards.
Pricing Analysis
Input-cost pass-through from battery-electric chassis and aluminum-intensive body structures is compressing contract pricing stability as fleet operators negotiate steel and aluminum volatility into index-linked agreements. Three-tier pricing structure across premium, standard, and economy levels differentiates by vehicle configuration and service bundling, with luxury coaches commanding brand premiums for executive travel segments. Cost compression in standard passenger bus tiers is intensifying because lithium-ion cell price declines narrow capital expenditure gaps against diesel baselines. Educational institutions exhibit highest price sensitivity due to public procurement compliance obligations, while corporate technology clients demonstrate lowest sensitivity given Scope 3 emissions disclosure requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese lithium-ion cell manufacturers and German chassis component suppliers as fleet electrification accelerates procurement timelines. Battery-electric powertrain assembly draws from China, South Korea, and Japan, while aluminum smelting feeds from Australia, Russia, and Canada. Chassis fabrication rests on high-strength steel from integrated mills, composite body panels from specialized tier suppliers, and semiconductor content for telematics integration. Tariff exposure on battery cells and rare earth magnet materials presents structural risk as trade policy shifts disrupt cost curves. Distribution runs through depot-based fleet operators with direct corporate contracting relationships, bypassing intermediary layers for recurring shuttle volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bus rental functions as a stable compounder anchored by contracted corporate shuttle demand, with technology campus outsourcing creating predictable revenue streams that compound through multi-year agreement renewals.
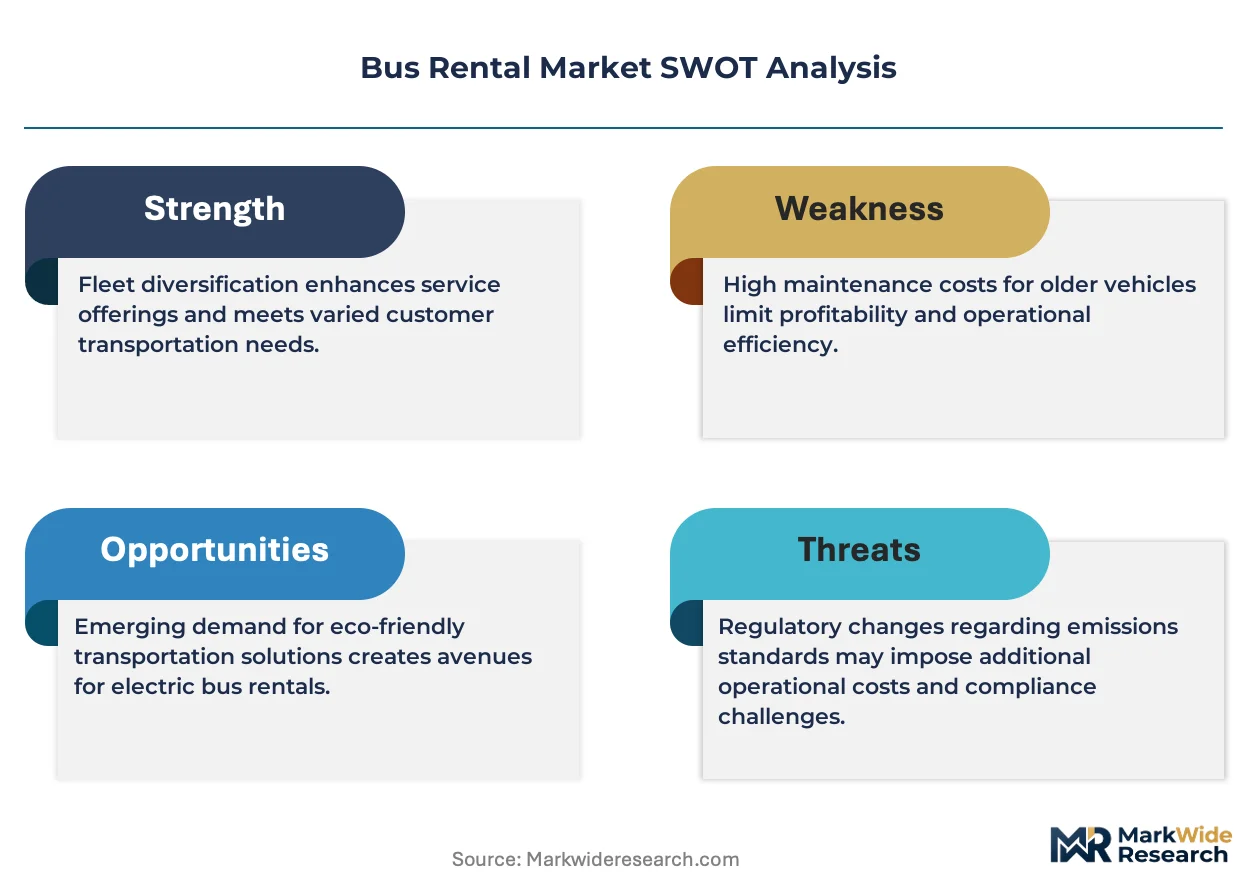
For Market Incumbents: Acquire charging infrastructure assets and depot real estate in constrained grid zones to lock in utility interconnection capacity before 18-36 month timelines stretch further. Consolidate regional operators along the Northeast corridor and California technology clusters to deepen route network density against platform-based entrants. Battery-electric maintenance certification programs represent the critical defensive lever as high-voltage technician scarcity threatens service quality differentiation.
For New Entrants and Emerging Players: Capture hydrogen fuel cell pilot contracts on extended intercity routes exceeding battery-electric range thresholds, particularly in Germany where federal transport subsidies cover trial deployments. Target event charter segments in metropolitan convention center clusters where surge pricing capabilities offset seasonal volume concentration. Partner with dynamic pricing software vendors to embed real-time yield management into digital booking interfaces, displacing phone-reservation incumbents.
For Investors and Strategic Acquirers: Diversified transportation conglomerates with cross-modal service portfolios are the most active acquirers in this space, seeking fleet scale and geographic coverage density through mid-cap operator consolidation. Acquisition target archetype: metropolitan specialists with corridor-specific density and contracted commuter volumes in technology corridor markets. Monitor California CARB compliance deadline acceleration as the signal to watch for pre-buy activity inflection and diesel residual value compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Utility interconnection commitments in constrained grid zones lock in depot electrification capacity ahead of competitor timelines. |
| Platform Integration | Real-time yield management software penetration captures margin from price-inelastic event segments and corporate procurement. |
| Backward Integration | In-house production of high-voltage maintenance capabilities addresses technician scarcity threatening service quality differentiation. |
| Geographic Expansion | Corridor-specific density acquisition along Northeast and California technology clusters compounds contracted commuter volumes. |
| Green Certification Program | Zero-emission fleet transitions satisfy CARB mandates and corporate Scope 3 emissions disclosure requirements simultaneously. |
Methodological Framework
Bottom-up corporate shuttle and event charter modeling reconciled against top-down fleet operator capacity tracking forms the analytical core. Primary interviews with fleet procurement directors, corporate travel managers, depot operations heads, and charging infrastructure developers combined with secondary validation from EPA emissions filings, CARB regulatory dockets, Euro VI compliance databases, and customs trade data on chassis component imports. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map vehicle deployment by service type, powertrain configuration, booking channel, and client vertical across the analysis window. Segmentation dimensions include corporate versus leisure demand, battery-electric versus hydrogen versus combustion propulsion, platform versus phone reservation capture, and metropolitan density tier. CAGRs derive from contracted volume growth trajectories, fleet turnover timelines tied to regulatory enforcement windows, and tourism corridor recovery patterns. Forecast inputs incorporate lithium-ion cost curve projections and utility interconnection queue data.
Regulatory enforcement delays, battery cell supply disruptions, and commercial driver license attainment bottlenecks are the dominant revision risks. Forecasts reflect assumptions about technology campus outsourcing continuity and emission standard adherence timelines without guarantee. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Bus Bellows Market
Buses
Europe Trolley Bus Market
Buses
Global Bus Market
Buses
Trolley Bus Market
Buses
Europe Bus Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Luxury Bus Market
Buses
Airport Bus Market
Buses
Intelligent Bus Shelter Market
Buses
Electric Intercity Bus Market
Buses
Africa Electric Bus Market
Buses
School Bus Market
Buses
Hydrogen Buses Market
Buses
Canada Transit Buses Market
Buses
Buses & Coaches Market
Buses
Bus Seat Market