
 Europe Bus Market | 2026-2036
Europe Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bus Market Insights
Multi-source battery procurement is hardening as a competitive requirement across the European bus supply chain. Mercedes-Benz Group AG leverages in-house cell partnerships to secure volume commitments for its eCitaro platform. Solaris Bus & Coach anchors its position through Polish manufacturing scale and flexible platform architecture that accommodates multiple cell suppliers. VDL Bus & Coach differentiates via Dutch engineering integration and captive module assembly in Eindhoven.
A bus is a road vehicle designed to carry multiple passengers, typically featuring a gross vehicle weight exceeding 3.5 tonnes, a length range of 8 to 18 metres, and a service life target of 12 to 15 years under European operating conditions. Its primary commercial purpose is to provide scheduled public mobility, charter transport, or dedicated shuttle services at lower per-passenger cost than individual road transport. City bus configurations dominate procurement volumes across European tenders, while electric fuel type captures the fastest expansion as battery energy density improvements and depot charging infrastructure reduce total cost of ownership gaps versus diesel. Coach applications retain stronger margin pools due to premium interior specifications and longer route economics that justify higher upfront investment.
The EU Green Deal and F-Gas Regulation shape powertrain transition timelines, while ECHA chemical compliance and CE marking requirements govern material sourcing and vehicle type approval. National regulators including Germany's KBA and France's ANSM-aligned transport authorities enforce local zero-emission zone mandates that filter fleet procurement specifications. Stakeholders must monitor subsidy continuity under the EU AI Act's emerging autonomous vehicle classification framework and the CSRD's supply chain disclosure rules that will expose embedded carbon in bus manufacturing.
Market Dynamics
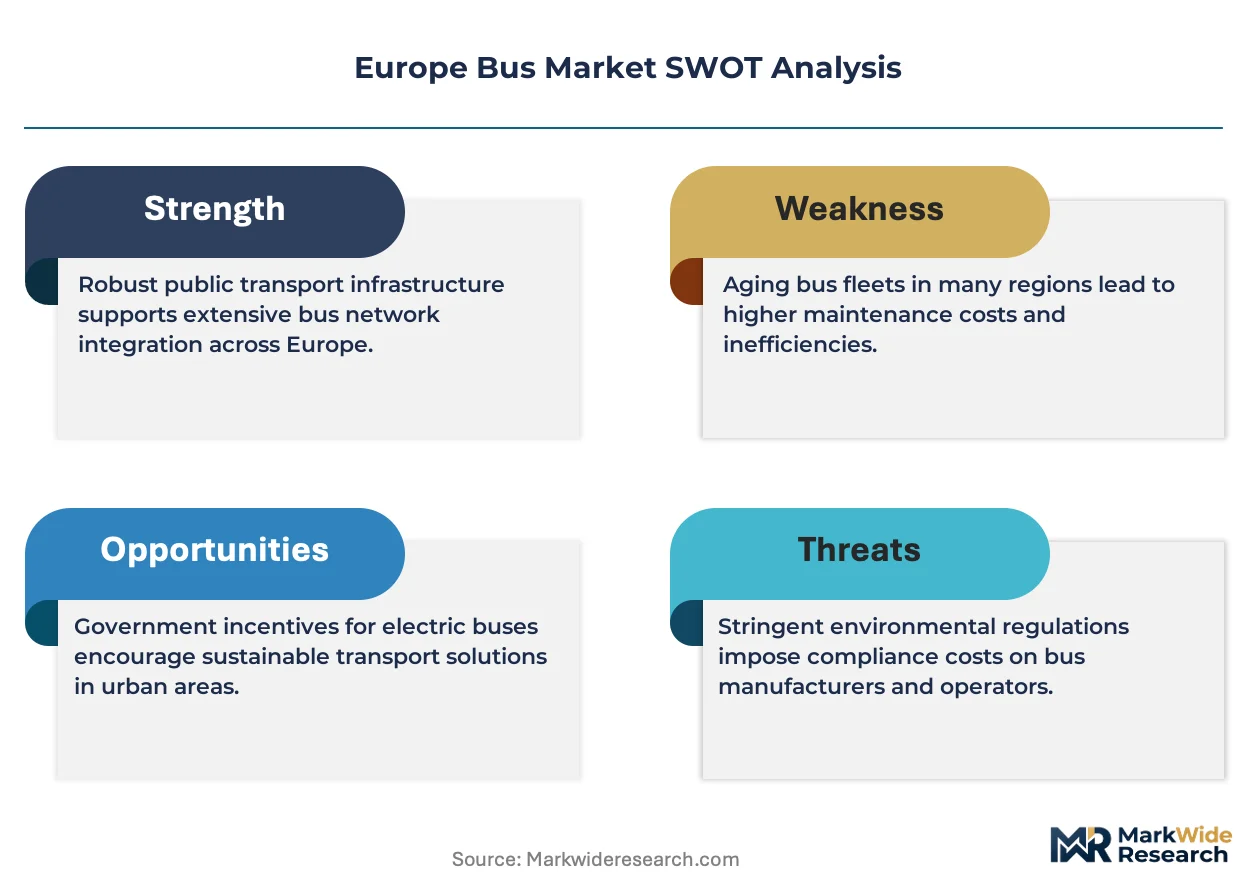
EU Green Deal zero-emission mandates are compressing diesel bus replacement cycles across municipal fleets, forcing operators to absorb electrification capex before full TCO parity materializes.
Growth Catalysts
- EU Green Deal mandates:National zero-emission zone designations in Germany and France are compelling transit authorities to accelerate fleet renewals ahead of statutory deadlines.
- Depot charging infrastructure:Grid-scale charging installations in Dutch and Belgian transport hubs are reducing range anxiety and enabling longer electric route assignments.
- Battery energy density gains:Cell chemistry improvements are extending daily operating ranges for 12-meter city configurations without mid-route opportunity charging.
Market Restraints
- Lithium supply concentration:European cell manufacturers remain dependent on upstream refining capacity concentrated outside the continent, exposing procurement to input cost volatility.
- Grid connection delays:Distribution network reinforcement timelines in dense urban centers are stretching 18-24 months beyond vehicle delivery schedules.
- Residual value uncertainty:Secondary market demand for retired electric buses remains undeveloped, compressing lease rate competitiveness versus diesel benchmarks.
Strategic Opportunities
- Polish manufacturing scale:Central European production clusters offer labor cost advantages and EU funding access for capacity expansion serving Eastern European tender growth.
- Autonomous depot maneuvering:SAE Level 4 automation for parking and washing operations is converging with telematics platforms to reduce overnight labor requirements.
- CSRD supply chain disclosure:Embedded carbon reporting requirements are creating first-mover advantage for operators with verified low-carbon manufacturing credentials.
Industry Challenges
- High-voltage technician scarcity:Qualified electricians capable of 800V system maintenance are concentrated in automotive sectors, forcing transit operators to compete for talent.
- Multi-supplier battery integration:Cell chemistry variations across procurement batches are complicating thermal management calibration and warranty claim attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bus Market |
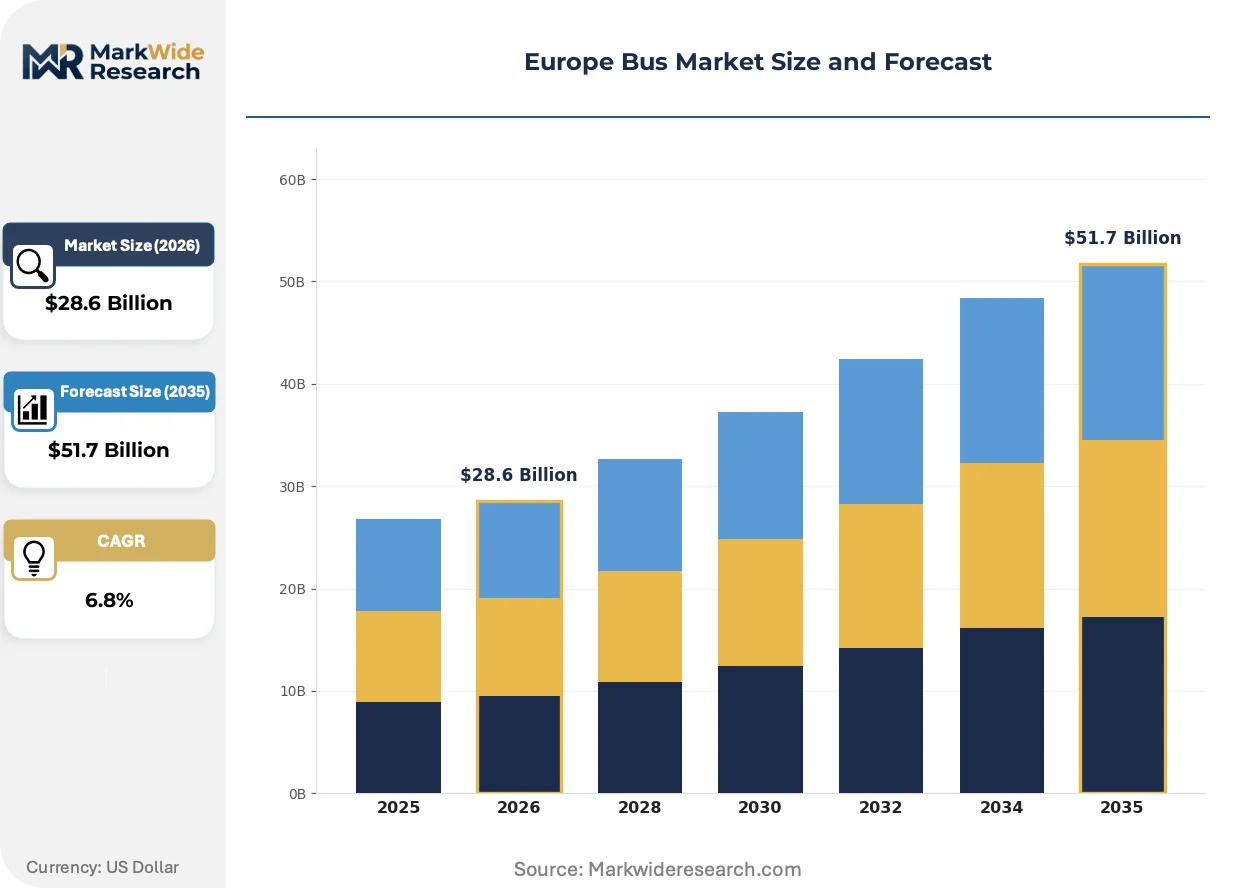
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: City Bus, Intercity Bus, School Bus, Coach Fuel Type: Diesel, Electric, CNG, Hybrid Application: Public Transport, Tourism, Shuttle Services, Logistics End User: Private Operators, Municipalities, Tour Operators, Government |
| Companies Covered | Mercedes-Benz Group AG, Yutong Bus, Iveco Bus, Solaris Bus & Coach, Volvo Buses, MAN Truck & Bus, Daimler Buses, VDL Bus & Coach, Scania, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bus Market Trends and Innovations
Platform architecture standardization is enabling faster variant development across body lengths and powertrain configurations. Three developments are restructuring competitive positioning.
Cell-to-pack battery architecture is modularizing energy storage design for European bus platforms. Tier-1 suppliers are offering scalable 35-70 kWh base modules that manufacturers configure into 350-560 kWh total capacity. This modularity is compressing engineering lead times for custom range specifications.
F-Gas Regulation phase-down schedules are accelerating heat pump adoption for cabin climate control. The 2024-2027 refrigerant quota reductions are banning R-134a in new vehicle types, forcing suppliers to qualify CO2-based systems. Coach applications with longer duty cycles face the steepest re-engineering burden.
Tender specifications are hardening around total cost of ownership guarantees rather than upfront capital cost. German Verkehrsverbünde and Dutch concessionaires are requiring 12-year energy and maintenance commitments from OEMs. This performance contracting is visible most acutely in Rhine-Ruhr and Randstad corridor procurements.
Europe Bus Market Segmentation
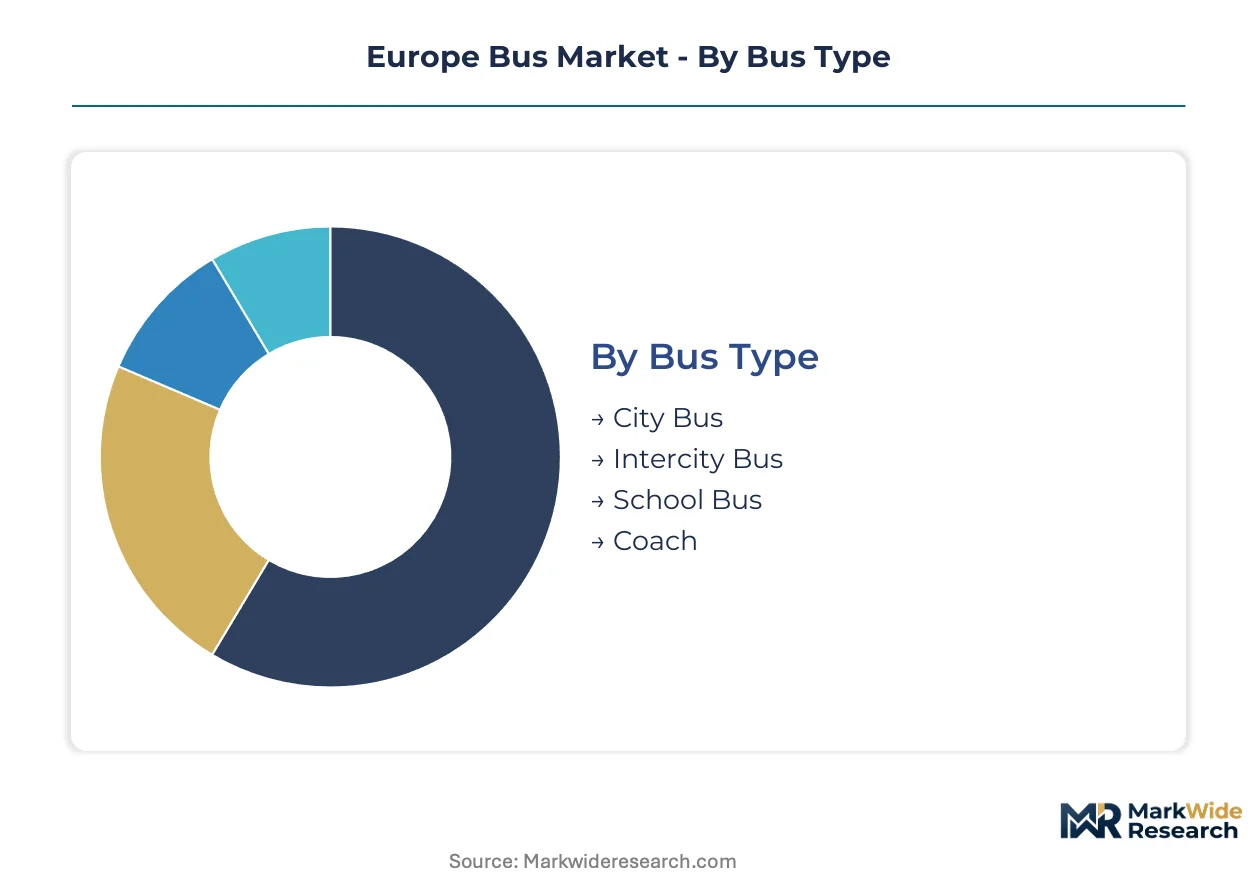
European bus procurement operates through segmented tender specifications that prioritize route economics, emissions compliance, and passenger capacity requirements. Fleet operators align vehicle configuration decisions with concession contract durations, depot infrastructure constraints, and local zero-emission zone timelines. Understanding segment boundaries clarifies where OEMs concentrate platform development versus where customization dominates order books.
Bus Type:
Municipal tender specifications prioritize passenger throughput and maneuverability in dense urban corridors over long-distance comfort features.
- City Bus:Single-deck configurations with low-floor access and 12-meter standard length dominate procurement volumes across German Verkehrsverbünde and Dutch concessionaires. German municipalities in Rhine-Ruhr and Bavaria are consolidating orders for 18-meter articulated variants to address peak-hour capacity constraints on trunk routes.
- Coach:Premium specifications with reclining seats, luggage compartments, and extended range fuel tanks serve tour operators and intercity scheduled services. French and Italian tour operators are renewing fleets ahead of F-Gas Regulation phase-down deadlines for climate control systems.
- Intercity Bus:Configurations balance passenger comfort with operational flexibility for regional scheduled services and private charter contracts.
- School Bus:Specialized safety equipment and dedicated stop-sign systems address regulatory requirements for student transport services.
Volume sits with City Bus configurations; growth tilts toward Coach applications as tourism recovery accelerates fleet renewal cycles.
Fuel Type:
Total cost of ownership calculations now incorporate carbon pricing mechanisms and residual value risk assessments alongside energy and maintenance expenditures.
- Electric:Battery-electric platforms with 350-560 kWh pack configurations and depot overnight charging are displacing diesel in Dutch and Belgian municipal tenders. Cell-to-pack architecture from Tier-1 suppliers is reducing thermal management complexity for 12-meter city configurations.
- Diesel:Compression-ignition powertrains retain procurement share in Eastern European markets where grid infrastructure lags vehicle delivery schedules and electrification capex strains municipal budgets.
- CNG:Compressed natural gas systems serve operators with established biomethane supply agreements in Sweden and Switzerland seeking interim emissions reductions.
- Hybrid:Diesel-electric parallel configurations address route electrification gaps in peri-urban corridors with insufficient charging infrastructure density.
Procurement volumes concentrate in Electric powertrains; Hybrid retains relevance in infrastructure-constrained geographies.
Application:
Contract duration and revenue stability determine whether operators prioritize capital efficiency or performance specifications in vehicle selection.
- Public Transport:Scheduled municipal services with 12-15 year asset lifecycles and concession-based revenue models drive standardization around 12-meter electric platforms. Dutch transport authorities in Randstad corridors are requiring 12-year energy and maintenance commitments from OEMs.
- Tourism:Seasonal demand patterns and premium passenger expectations justify higher upfront investment in coach configurations with enhanced interior specifications.
- Shuttle Services:Corporate campus and airport transfer contracts favor mid-size configurations with rapid boarding characteristics and flexible routing capability.
- Logistics:Parcel and freight adaptation of bus platforms serves last-mile distribution requirements in urban center access restrictions.
Public Transport commands absolute procurement volume; Tourism applications are climbing fastest as cross-border travel normalizes.
End User:
Capital access and subsidy eligibility create divergent procurement behaviors between public and private fleet operators.
- Municipalities:German and French transit authorities leverage EU Green Deal funding streams and national zero-emission mandates to accelerate diesel fleet retirement ahead of statutory deadlines. KBA type-approval requirements and local zone designations filter specification compliance.
- Private Operators:Commercial fleet managers prioritize residual value certainty and financing structure flexibility in lease-versus-buy decisions.
- Tour Operators:Seasonal revenue exposure and route flexibility requirements drive demand for multi-specification fleet pools.
- Government:Defense and institutional transport services maintain specialized procurement channels with dedicated safety and security requirements.
Municipalities anchor procurement volume; Private Operators are expanding fastest as deregulated tender markets open to competitive entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium refining capacity in Portugal and Spain underpins Iberian ambitions to anchor European battery supply chains for electric bus manufacturing.
Germany
Rhine-Ruhr and Bavarian transport authorities are consolidating orders for 18-meter articulated electric buses to address peak-hour capacity constraints. KBA type-approval requirements and local zero-emission zone designations filter procurement specifications toward depot-charged platforms. Eindhoven-based VDL Bus & Coach captures Dutch engineering integration contracts serving German municipal tenders.
France
ANSM-aligned transport authorities enforce zero-emission mandates that accelerate diesel fleet retirement ahead of statutory deadlines. French tour operators are renewing coach fleets ahead of F-Gas Regulation phase-down deadlines for climate control systems. Auvergne-Rhône-Alpes clusters concentrate biomethane supply agreements for interim CNG deployments.
Netherlands
Randstad corridor concessionaires require 12-year energy and maintenance commitments from OEMs, hardening tender specifications around total cost of ownership guarantees. Grid-scale charging installations in Dutch transport hubs reduce range anxiety and enable longer electric route assignments. Eindhoven manufacturing anchors captive module assembly for regional supply security.
Poland
Solaris Bus & Coach leverages Polish manufacturing scale and flexible platform architecture accommodating multiple cell suppliers. Central European production clusters offer labor cost advantages and EU funding access for capacity expansion serving Eastern European tender growth. Polish manufacturing output addresses procurement volumes across German and Dutch border regions.
Belgium
Flemish transport authorities deploy depot charging infrastructure density sufficient for full-electric route assignments without mid-route opportunity charging. Distribution network reinforcement timelines in dense Brussels urban centers stretch 18-24 months beyond vehicle delivery schedules. Belgian hubs serve as logistics nodes for battery module distribution into French and German assembly plants.
Europe Bus Market Competitive Landscape
Global majors compete with regional champions across electrification platform development and concession contract servicing. Market structure tilts toward consolidated procurement relationships where municipal authorities favor established type-approval track records. Three archetypes dominate: diversified automotive conglomerates with captive battery partnerships, specialized bus manufacturers with modular platform architectures, and engineering-integrated specialists with captive module assembly. Competitive moves concentrate on multi-source battery procurement commitments and performance contracting for 12-year total cost of ownership guarantees.
Within the diversified automotive tier, Mercedes-Benz Group AG and Volvo Buses exemplify conglomerate-scale electrification strategies. Solaris Bus & Coach represents the specialized manufacturer archetype with Polish production scale. VDL Bus & Coach occupies the engineering-integrated specialist position through Dutch module assembly capabilities.
| Leading Market Players |
|---|
| Mercedes-Benz Group AG |
| Yutong Bus |
| Iveco Bus |
| Solaris Bus & Coach |
| Volvo Buses |
| MAN Truck & Bus |
| Daimler Buses |
| VDL Bus & Coach |
| Scania |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists across Poland and the Netherlands anchor European bus manufacturing, their conservative balance sheets limiting aggressive price competition while EU Green Deal compliance costs filter through to municipal tender premiums. KBA and ANSM type-approval requirements create fixed certification overheads that smaller assemblers cannot amortize across thin order books, compressing margin flexibility for non-compliant entrants.
Pricing Analysis
Warranty and service bundling separates German Verkehrsverbünde procurement from Eastern European spot purchases, with Rhine-Ruhr authorities demanding 12-year energy and maintenance commitments that inflate headline contract values. Three-tier pricing structure across premium, standard, and economy levels tracks battery pack density and thermal management sophistication, with 560 kWh configurations commanding substantial premiums over 350 kWh base models. Pricing pressure stems from lithium refining cost volatility concentrated outside the continent, with Polish manufacturing clusters offering partial insulation through labor arbitrage. Private tour operators exhibit highest price sensitivity due to seasonal revenue exposure, while Dutch municipal concessionaires prioritize TCO guarantees over upfront capital minimization.
Supply Chain Analysis
Qualified electricians capable of 800V system maintenance concentrate in Eindhoven and Stuttgart manufacturing corridors, forcing transit operators to compete with automotive sectors for scarce high-voltage technician talent. Cell chemistry inputs draw from South Korean and Chinese refining capacity, with Portuguese lithium projects offering prospective European sourcing diversification. Module assembly rests on Polish production clusters serving German and Dutch border demand, while Belgian logistics nodes distribute battery systems into French assembly plants. Single-source vulnerability runs through concentrated cathode precursor supply, with distribution running through Rotterdam and Hamburg port infrastructure into inland manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's zero-emission mandate timeline constructs a compliance moat that rewards incumbent OEMs with established type-approval track records while straining capital-constrained challengers. F-Gas Regulation phase-down schedules for climate control systems impose additional engineering burdens that favor players with captive R&D scale.
For Market Incumbents: Deepen captive module assembly capabilities in Eindhoven and Polish manufacturing corridors to secure supply continuity against lithium refining bottlenecks. Expand 12-year performance contracting offerings to Rhine-Ruhr and Randstad concessionaires, locking out challengers lacking balance sheet depth for long-term TCO guarantees. Battery chemistry standardization across platform variants reduces thermal management calibration complexity and warranty claim exposure. For New Entrants and Emerging Players: EU AI Act autonomous vehicle classification frameworks in Germany and France open a window for SAE Level 4 depot maneuvering specialists to partner with established OEMs lacking in-house automation engineering. Target peri-urban hybrid configurations in Belgian and Eastern European markets where grid infrastructure lags vehicle delivery schedules. Position through telematics platform integration rather than complete vehicle assembly to bypass KBA type-approval capital requirements. For Investors and Strategic Acquirers: Consolidation of 18-meter articulated electric bus orders across Bavarian transport authorities is the leading indicator that scale economics are shifting toward platforms with flexible length variants. Long-term viability centers on manufacturers with verified low-carbon manufacturing credentials under CSRD supply chain disclosure rules. Acquisition focus should target engineering-integrated specialists with captive module assembly and established Dutch or German municipal service relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Multi-source cell procurement from South Korean partners secures volume commitments for eCitaro-scale platforms. |
| Platform Standardization | Cell-to-pack architecture reduces engineering lead times for custom range specifications across 12-18 meter variants. |
| Charging Infrastructure Partnership | Grid-scale depot installations in Randstad corridors enable longer electric route assignments without opportunity charging. |
| Geographic Manufacturing Footprint | Polish production clusters leverage EU funding access and labor cost advantages for Eastern European tender growth. |
| Software-Defined Vehicle Investment | Telematics integration for autonomous depot maneuvering converges with SAE Level 4 automation requirements. |
Research Methodology
Document review covered EU Green Deal implementation timelines, F-Gas Regulation phase-down schedules, and national zero-emission zone designations, complemented by interviews with municipal procurement directors at German Verkehrsverbünde, platform engineers at Dutch concessionaires, and high-voltage technician training coordinators. Secondary validation drew from KBA type-approval databases, ANSM transport authority filings, and ECHA chemical compliance registries. Bottom-up tender analysis across Rhine-Ruhr, Randstad, and Auvergne-Rhône-Alpes corridors triangulated against top-down production capacity estimates from Polish and Eindhoven manufacturing clusters.
Segment-level projections across bus type, fuel type, application, and end user dimensions fed into platform-specific demand models spanning the analysis window. CAGRs derived from weighted average of historical procurement trajectories and policy-mandated replacement schedules, with battery energy density improvement curves and depot charging infrastructure build-out timelines as key forecast inputs. Electric powertrain penetration assumptions incorporated grid connection delay distributions from distribution network operator disclosures.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for thermal management system specifications and warranty cost structures. Forecasts reflect documented assumptions regarding subsidy continuity under EU funding programs and lithium refining capacity expansion timelines. Material deviation in F-Gas Regulation enforcement intensity or CSRD supply chain disclosure implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Bus Rental Market
Buses
Intelligent Bus Shelter Market
Buses
Global Bus Market
Buses
Buses & Coaches Market
Buses
North America Bus Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Bus Flooring Market
Buses
Electric Intercity Bus Market
Buses
Canada Transit Buses Market
Buses
Trolley Bus Market
Buses
Europe Trolley Bus Market
Buses
Hydrogen CNG Bus Market
Buses
Bus Chassis Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Airport Bus Market
Buses
Global Luxury Shuttle Bus Market