
 Hydrogen Buses Market | 2026-2036
Hydrogen Buses Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Buses Market Outlook
The divergence between premium fuel cell platforms and cost-optimized hybrid configurations is realigning procurement patterns across transit agencies. Daimler Buses leverages its integrated powertrain architecture to anchor premium positioning in European tenders. Solaris Bus & Coach competes aggressively on manufacturing scale across Central and Eastern European markets. Yutong dominates domestic Chinese procurement through captive supply of fuel cell stacks and compressed hydrogen storage systems.
Hydrogen buses are zero-emission transit vehicles that generate electric power through electrochemical reaction of hydrogen and oxygen, typically producing 200-350 kW continuous output for urban duty cycles. Fuel cell buses lead current deployments due to proven range and refueling parity with diesel, while hydrogen internal combustion engine variants gain traction as retrofit-friendly alternatives for existing bus OEMs. Public transport operators concentrate the largest end-user demand pool, though corporate fleet pilots in logistics and airport shuttle services represent the fastest-growing adoption segment.
Fuel cell bus certification in Europe requires compliance with ECHA REACH substance restrictions, EU Green Deal emission benchmarks, and CE marking for electrical safety, while the US EPA and NHTSA jointly govern tailpipe and crashworthiness standards. Japan's METI subsidizes hydrogen station infrastructure that directly enables fleet expansion by Tokyo and Osaka transit authorities. Stakeholders must monitor electrolysis cost curves and green hydrogen supply guarantees before committing to multi-hundred-unit fleet contracts.
Market Dynamics
The divergence between PEM fuel cell architectures and emerging solid oxide systems is compressing procurement timelines as transit agencies weigh proven reliability against thermal efficiency gains. This technology tension is reshaping supplier qualification criteria and fleet planning horizons.
Growth Catalysts
- German BImSchV emission ceilings:Federal transport authorities must retire diesel fleets by 2030, forcing municipal operators into zero-emission tenders.
- Airport shuttle electrification:Ground transport operators at Frankfurt, Incheon, and Los Angeles International are piloting hydrogen bus corridors to meet scope-3 reduction targets.
- Electrolyzer cost curves:Green hydrogen production economics are improving through alkaline and PEM electrolysis scale-up, enabling supply guarantees for multi-hundred-unit contracts.
Market Restraints
- Platinum group metal dependency:PEM fuel cell catalyst requirements expose fleet operators to palladium and rhodium price volatility from South African and Russian supply concentration.
- Hydrogen infrastructure gap:Station deployment lags fleet procurement in all markets except Japan, where METI subsidization has achieved corridor coverage.
- Diesel hybrid substitution:Cost-optimized mild-hybrid buses from incumbent OEMs satisfy emission benchmarks at lower capital outlay in transitional regulatory windows.
Strategic Opportunities
- India's National Hydrogen Mission:State transport undertakings in Delhi, Maharashtra, and Karnataka are issuing pilot tenders ahead of 2030 fleet electrification mandates.
- Fuel cell-battery hybrid convergence:Combined powertrain architectures are enabling route flexibility and depot charging reduction for operators with uneven hydrogen station coverage.
- Corporate mobility-as-a-service:Technology campus shuttles and logistics park circulators represent white-space demand outside traditional municipal procurement channels.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack certified personnel for 600V fuel cell powertrain diagnostics and stack replacement protocols.
- CE marking timeline compression:ECHA REACH substance documentation and EU Green Deal conformity assessment are extending homologation cycles by 8-14 months.
- Legacy depot retrofit requirements:Existing maintenance facilities require hydrogen detection, ventilation, and electrical isolation upgrades to accommodate fuel cell bus servicing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Buses Market |
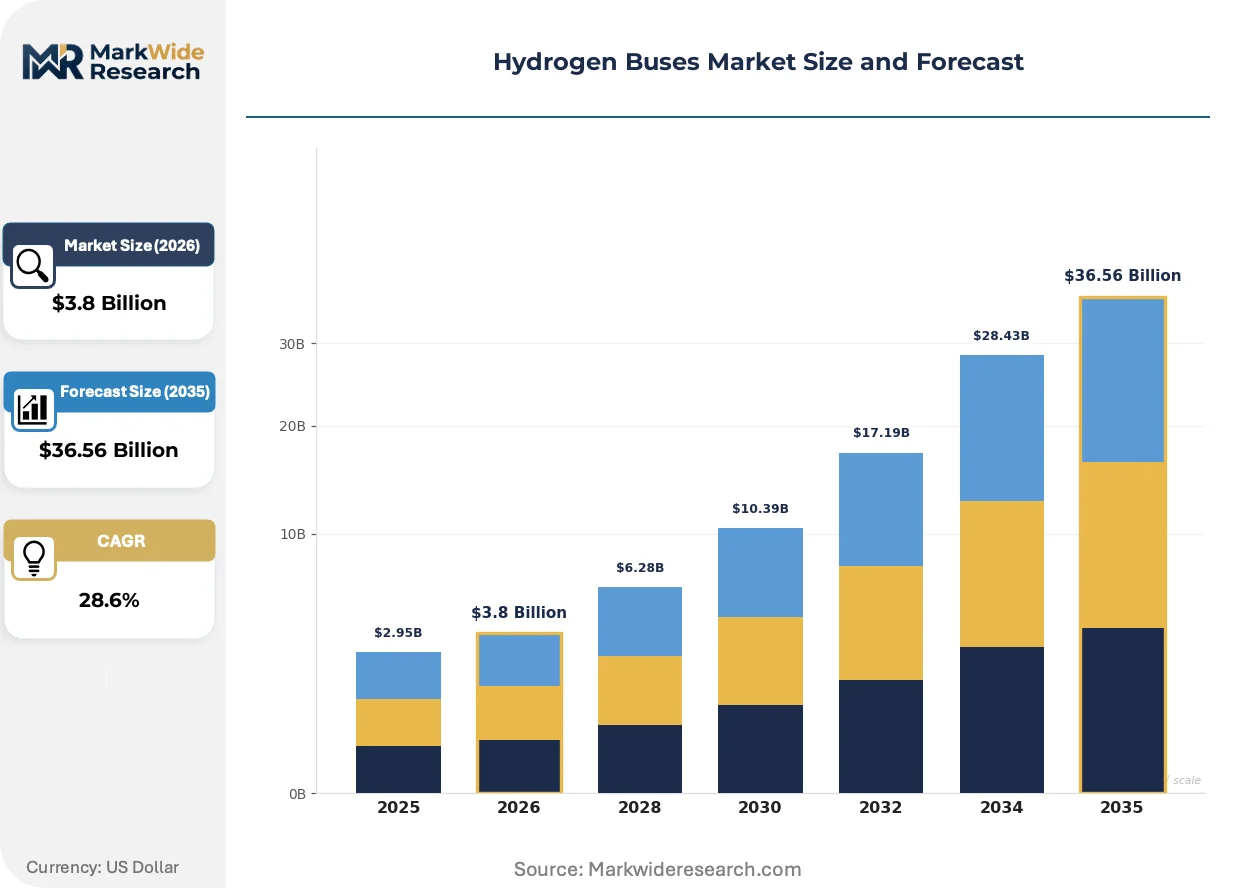
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Cell Buses, Hybrid Buses, Hydrogen Internal Combustion Engine Buses, Others End User: Public Transport Operators, Private Transport Companies, Government Agencies, Corporate Fleets Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Others Fuel Source: Electrolysis, Natural Gas Reforming, Biomass Gasification, Others |
| Companies Covered | Hyundai Motor Company, Toyota Motor Corporation, Daimler Buses, Wrightbus, Solaris Bus & Coach, Ballard Power Systems, New Flyer Industries, Volvo Group, Yutong, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Buses Market Strategic Shifts
Technology maturation is converging with regulatory hardening to accelerate platform consolidation. Transit agencies are narrowing supplier pools as certification burdens and infrastructure dependencies favor integrated system providers over component assemblers.
PEM fuel cell technology is consolidating urban bus deployments through improved cold-start performance and load-following characteristics. German and Japanese operators are standardizing on 70 MPa storage systems to achieve 350-450 km range parity with diesel. This consolidation is compressing the competitive field around vertically integrated powertrain specialists with captive stack production.
EU Green Deal emission benchmarks are tightening fleet-average CO2 calculations for municipal tender evaluation. The regulation is disqualifying diesel-hybrid configurations from zero-emission procurement categories in France, Netherlands, and Nordic markets. Bus manufacturers are responding with dedicated fuel cell product lines rather than adaptable chassis platforms.
Lifecycle contracting is displacing capital purchase models in European public transport. Operators in London, Paris, and Berlin are procuring hydrogen bus service by kilometer rather than vehicle unit, transferring fuel cost and maintenance risk to OEMs. This shift is most advanced in markets with established green hydrogen supply certification through TÜV or Bureau Veritas schemes.
Hydrogen Buses Market Segmentation
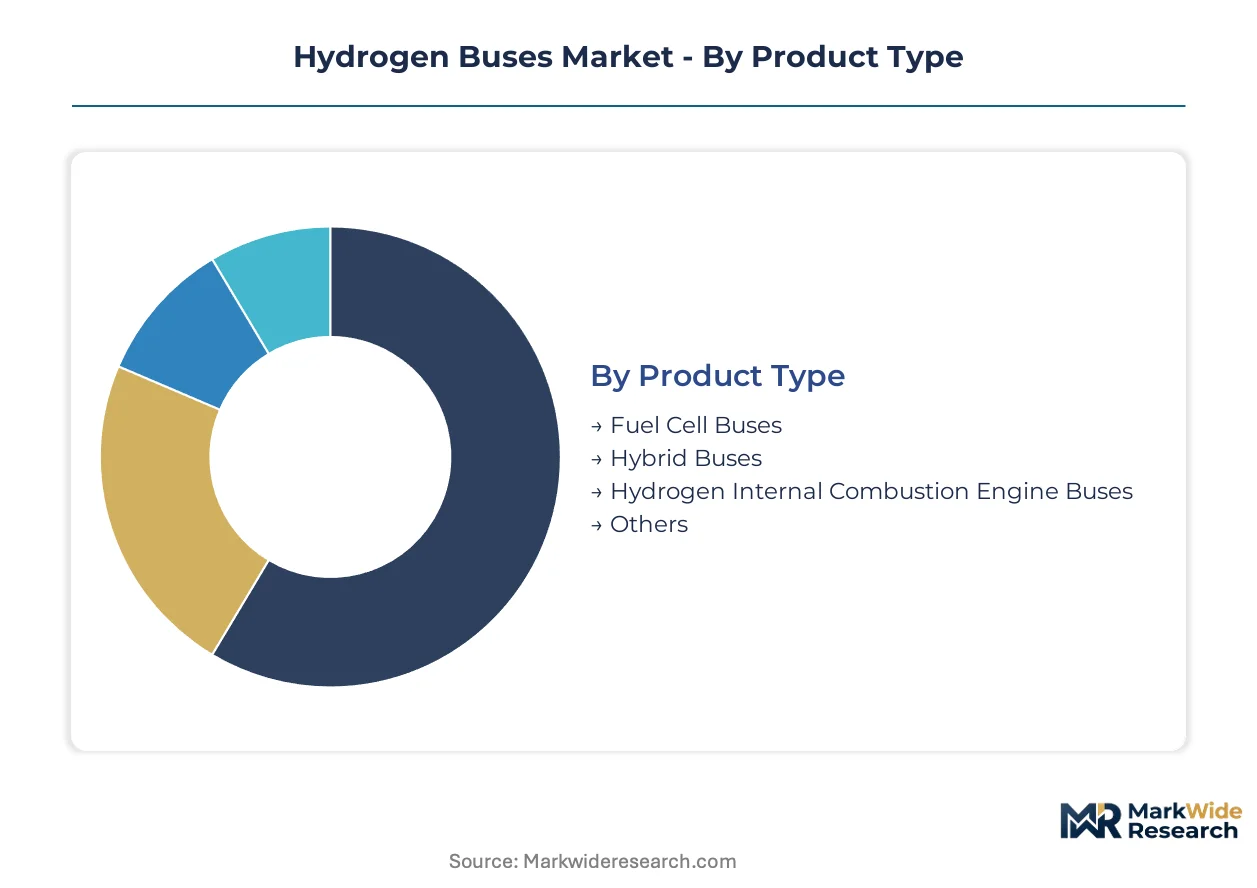
Transit agencies structure procurement around duty-cycle requirements, infrastructure readiness, and total cost of ownership across vehicle lifecycles. Segmentation reveals how technology choices cascade through fleet planning, maintenance protocols, and fuel supply contracting. Understanding these dimensions clarifies why certain configurations dominate specific operational contexts while others remain niche.
Product Type:
Fleet replacement cycles favor platforms with proven depot compatibility and technician training pathways, compressing adoption windows for novel architectures.
- Fuel Cell Buses:Electrochemical hydrogen-oxygen reaction generates 200-350 kW continuous output through PEM or solid oxide stacks. German municipal operators in Hamburg and Cologne concentrate procurement here, driven by BImSchV diesel phase-out mandates and established hydrogen corridor coverage.
- Hybrid Buses:Combined fuel cell-battery architectures enable route flexibility with partial depot charging capability. Demand clusters in markets with uneven station distribution, including early-deployment corridors in California and South Korea where infrastructure buildout lags fleet commitments.
- Hydrogen Internal Combustion Engine Buses:Retrofit-friendly powertrains adapt existing bus OEM production lines with minimal chassis redesign.
- Others:Experimental configurations including range-extender fuel cell trailers and modular swap systems remain pre-commercial.
Volume placements concentrate in fuel cell buses; the faster expansion belongs to hybrid configurations.
End User:
Procurement authority structures determine contract scale, financing mechanisms, and service-level specifications across buyer categories.
- Public Transport Operators:Municipal and regional transit authorities issue multi-hundred-unit tenders with lifecycle cost evaluation. Berlin's BVG and Tokyo's Toei Bus anchor demand concentration, leveraging sovereign green bond financing and guaranteed hydrogen supply contracts through national infrastructure programs.
- Corporate Fleets:Technology campus shuttles, logistics park circulators, and airport ground transport represent emerging demand outside traditional municipal channels. Frankfurt Airport and Incheon International pilot hydrogen bus corridors to satisfy scope-3 emission reduction commitments.
- Private Transport Companies:Charter and intercity operators test hydrogen configurations on fixed routes with predictable duty cycles.
- Government Agencies:Federal and state fleet procurement supports technology demonstration with standardized maintenance protocols.
Contract value concentrates in public transport operators; corporate fleets are expanding most quickly.
Technology:
Stack architecture selection trades thermal efficiency against cold-start performance and load-following capability in urban duty cycles.
- Proton Exchange Membrane:Polymer electrolyte membranes operate at 60-80°C with rapid startup and dynamic response to acceleration demands. Japanese and South Korean deployments standardize on PEM through Toyota and Hyundai captive stack production, supported by METI and MOTIE subsidization programs.
- Solid Oxide:Ceramic electrolyte systems achieve 60% electrical efficiency at 700-1000°C operating temperatures. R&D investment concentrates in European university-industry partnerships targeting long-haul applications where steady-state operation dominates.
- Alkaline:Liquid electrolyte systems offer capital cost advantages with lower power density constraints.
- Others:Phosphoric acid and molten carbonate variants remain experimental for mobile applications.
Deployment volume concentrates in proton exchange membrane; solid oxide holds the steepest expansion trajectory among emerging alternatives.
Fuel Source:
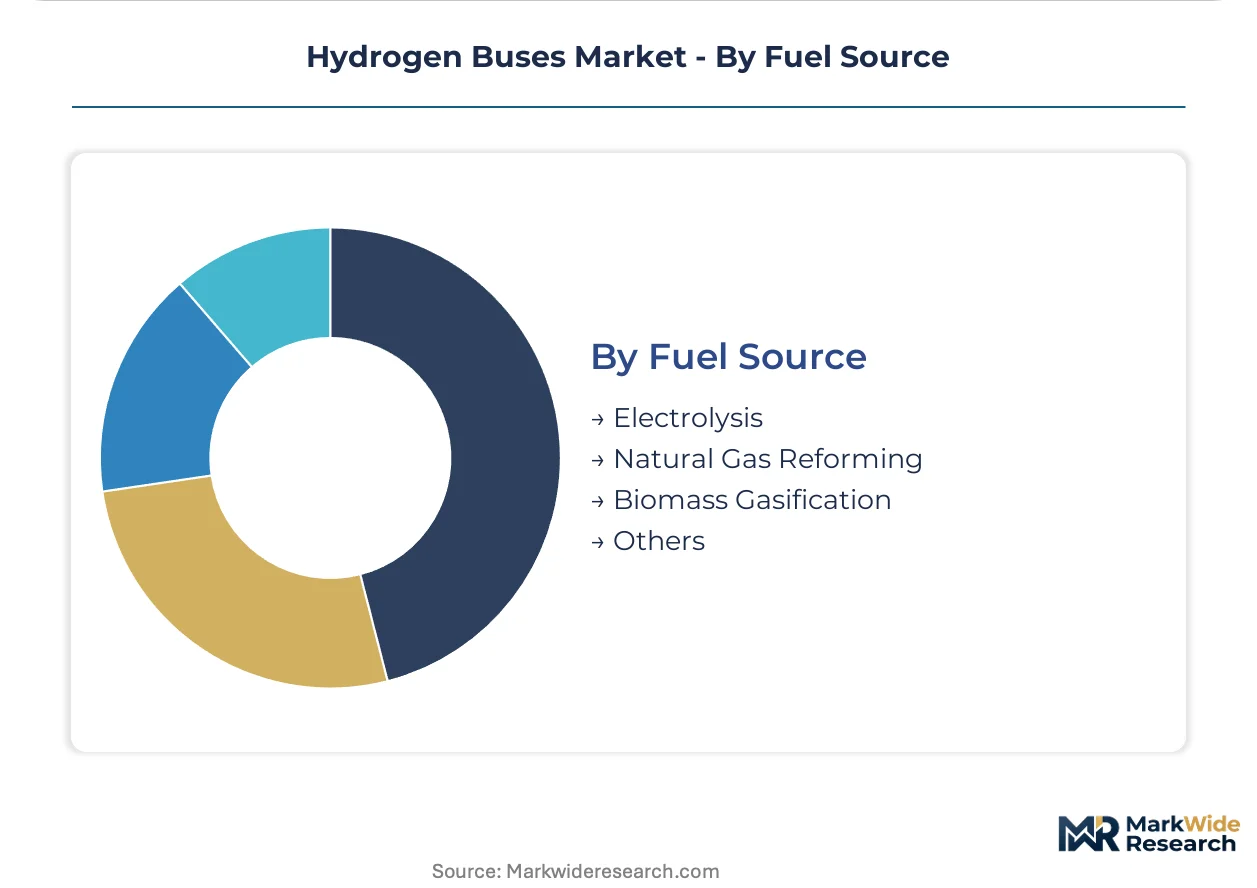
Hydrogen production pathway determines carbon intensity certification and supply security for fleet operators with multi-decade asset horizons.
- Electrolysis:Water splitting via alkaline or PEM electrolyzers produces zero-carbon hydrogen when powered by renewable electricity. Norwegian and Danish transit agencies prioritize electrolysis-derived supply through Power-to-X certification schemes, leveraging abundant wind and hydro resources.
- Natural Gas Reforming:Steam methane reforming with carbon capture offers transitional supply scale as electrolyzer capacity expands.
- Biomass Gasification:Agricultural and forestry waste conversion provides regionally concentrated renewable hydrogen in Nordic and Baltic markets.
- Others:Pyrolysis and thermochemical water splitting remain pre-commercial at bus-fleet scale.
Certified supply concentrates in electrolysis; biomass gasification is gaining share fastest in markets with established waste-to-energy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the most concentrated hydrogen bus deployment corridor, with metropolitan transit authorities operating over 100 fuel cell units across the Kanto region's hydrogen station network.
Japan
Tokyo and Osaka municipal operators drive fleet procurement through METI-subsidized hydrogen infrastructure. The country's national hydrogen regulator coordinates station deployment with transit corridor planning. Toyota Motor Corporation's domestic manufacturing base supplies fuel cell stacks directly to regional bus operators.
Germany
Hamburg and Cologne transit authorities execute multi-hundred-unit tenders under BImSchV diesel phase-out mandates. The KBA enforces EU Green Deal conformity assessment for zero-emission vehicle certification. Daimler Buses anchors production in Stuttgart and Mannheim industrial clusters for European export markets.
South Korea
Seoul and Busan metropolitan governments scale procurement through MOTIE hydrogen economy roadmaps. The national transport ministry mandates clean fleet percentages in municipal tender evaluations. Hyundai Motor Corporation integrates captive fuel cell production with domestic bus assembly in Ulsan.
China
Beijing and Shanghai pilot zones concentrate fleet demonstrations ahead of 2035 carbon neutrality targets. The MIIT governs fuel cell vehicle subsidy eligibility through GB standard compliance. Yutong leverages Zhengzhou manufacturing scale for domestic procurement dominance and Belt and Road export positioning.
United States
California transit agencies in Los Angeles and the San Francisco Bay Area lead deployment through CARB zero-emission fleet mandates. The EPA and NHTSA jointly administer tailpipe and safety certification requirements. New Flyer Industries serves municipal operators across the Western states with fuel cell platform integration.
Hydrogen Buses Market Competitive Environment
Premium-margin players sit above commodity-margin players across powertrain integration depth and captive fuel cell stack production. The vendor base stratifies between vertically integrated automotive conglomerates with in-house fuel cell manufacturing and chassis specialists sourcing stacks from third-party suppliers. Three archetypes dominate: integrated powertrain OEMs with captive hydrogen technology, regional bus manufacturers with modular fuel cell sourcing, and pure-play fuel cell stack suppliers licensing to chassis builders. Competitive moves concentrate on backward integration into fuel cell stack production and strategic partnerships with hydrogen infrastructure operators.
Within the integrated automotive tier, Hyundai Motor Corporation, Toyota Motor Corporation, and Daimler Buses exemplify powertrain control strategies. Hyundai anchors Korean market positioning through captive fuel cell manufacturing. Toyota represents Japanese deployment scale with metropolitan corridor focus. Daimler occupies a premium-tier position in European tender markets through integrated chassis-stack architecture.
| Leading Market Players |
|---|
| Hyundai Motor Company |
| Toyota Motor Corporation |
| Daimler Buses |
| Wrightbus |
| Solaris Bus & Coach |
| Ballard Power Systems |
| New Flyer Industries |
| Volvo Group |
| Yutong |
| Others |
Value Chain & Pricing Dynamics
Certified fuel cell technician scarcity in Germany and South Korea widens labor-cost differentials between integrated OEM service networks and third-party maintenance providers, compressing pricing-tier spreads toward outcome-based contracts.
Pricing Analysis
Lifecycle cost-per-kilometer contracts anchor value-based pricing for municipal fleet operators, transferring fuel and maintenance risk to OEMs. Three-tier pricing structure across premium integrated powertrains, modular fuel cell conversions, and refurbishment programs differentiates by certification grade and captive stack production. Cost compression in mid-tier configurations intensifies as Ballard and other stack suppliers expand licensing to regional chassis builders. Public transport authorities exhibit lowest price sensitivity due to sovereign green bond financing, while private charter operators demand capital-purchase options with transparent stack replacement cost schedules.
Supply Chain Analysis
Fuel cell stack refurbishment and end-of-life catalyst recovery flows are emerging as reverse-logistics priorities, with platinum group metal reclamation feeding back into PEM manufacturing. Stack production concentrates in Japan, South Korea, and Germany through Toyota, Hyundai, and Daimler captive facilities. The supply chain draws from South African palladium mines, Canadian graphite suppliers, and Chinese membrane electrode assembly producers. Single-source vulnerability in platinum group metal refining exposes fleet operators to price volatility. Distribution runs through OEM-direct channels for integrated powertrains and specialized hydrogen mobility distributors for modular retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen bus market operates as a cost-of-compliance arena where EU Green Deal zero-emission benchmarks and BImSchV diesel phase-out mandates erect regulatory moats favoring certified incumbents with proven homologation track records.
For Market Incumbents: Anticipate margin compression from Chinese stack suppliers entering European tender markets through Yutong and Weichai partnerships. Defend positioning by deepening backward integration into membrane electrode assembly production and securing long-term green hydrogen supply contracts through Power-to-X certification schemes. For New Entrants and Emerging Players: Launch via corporate mobility-as-a-service channels rather than contested municipal procurement corridors. India's National Hydrogen Mission pilot tenders and airport ground transport electrification at Frankfurt and Incheon represent the most penetrable white-space targets. Partner with established hydrogen infrastructure operators to de-risk fuel supply guarantees. For Investors and Strategic Acquirers: The window for entry favors pure-play fuel cell stack specialists with captive intellectual property and established OEM licensing revenue. Long-term viability hinges on electrolyzer cost curves achieving parity with reforming pathways. Monitor green hydrogen supply certification adoption rates through TÜV and Bureau Veritas schemes as the critical inflection signal for fleet contract scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stack Manufacturing | Daimler and Hyundai control powertrain margins through captive PEM production in Stuttgart and Ulsan. |
| Hydrogen Infrastructure Partnership | OEM alliances with Linde and Air Liquide secure station coverage for fleet contract viability. |
| Lifecycle Service Contract Expansion | London BVG and Paris RATP procurement shifts transfer operational risk to manufacturers. |
| Regional Assembly Localization | Solaris and Yutong establish Polish and Hungarian plants to satisfy EU content requirements. |
| Certification Pre-Investment | Early ECHA REACH documentation accelerates CE marking timelines for tender participation. |
Study Parameters
Document review covered EU Green Deal regulatory filings, METI hydrogen infrastructure disclosures, and KBA homologation records, complemented by interviews with municipal fleet procurement directors, fuel cell stack engineering leads, hydrogen station operators, and transit authority maintenance chiefs. Secondary validation drew from IEA hydrogen project databases, national transport ministry tender announcements, and electrolyzer manufacturer capacity disclosures. Bottom-up fleet deployment counts were triangulated against top-down national hydrogen roadmap targets.
Historical deployment trajectories were cross-referenced against expert panel assessments of infrastructure buildout timelines. The analytical framework modeled vehicle class, propulsion architecture, fuel source certification, and regional regulatory cluster across the projection horizon. CAGRs were derived from electrolyzer cost curve assumptions and fleet replacement cycle analysis. Green hydrogen supply certification adoption rates and platinum group metal price volatility were incorporated as scenario-weighted inputs.
Policy subsidy discontinuation, hydrogen station deployment delays, and fuel cell stack durability shortfalls are the dominant revision risks to deployment forecasts. Practitioners should monitor national hydrogen roadmap funding commitments and electrolyzer manufacturer order backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Bus Rapid Transit System (BRT) Market
Buses
Electric Intercity Bus Market
Buses
Bus Transmission System Market
Buses
Europe Bus Market
Buses
Luxury Bus Market
Buses
Global Luxury Shuttle Bus Market
Buses
Europe Trolley Bus Market
Buses
United States School Bus Market
Buses
Buses & Coaches Market
Buses
Bus Charter Services Market
Buses
Airport Bus Market
Buses
Global Bus Market
Buses
Bus Flooring Market
Buses
Intelligent Bus Shelter Market
Buses
Canada School Bus Market
Buses
City Bus Low-Floor Axle Systems Market