
 United States Electric Bus Market | 2026-2036
United States Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Bus Market Intelligence
Domestic battery pack assembly capacity in the Midwest is restructuring supplier relationships across the electric bus value chain. Proterra Inc. leverages in-house cell-to-pack manufacturing to secure cost advantages for transit authority contracts. BYD Motors Inc. anchors its position through vertically integrated battery production and California-based final assembly. New Flyer of America Inc. competes with modular platform architectures that span battery-electric and hydrogen fuel cell configurations.
The United States electric bus comprises a heavy-duty transit vehicle propelled by electric traction motors drawing energy from onboard battery storage, with typical configurations utilizing lithium-ion phosphate or nickel-manganese-cobalt chemistries in 200-600 kWh packs for 150-300 mile daily duty cycles, designed to replace diesel powertrains in fixed-route and scheduled service operations. Battery Electric Bus configurations dominate unit shipments due to total cost of ownership parity achieved against diesel at high-utilization duty cycles, while Hydrogen Fuel Cell Bus segments capture premium corridor applications where sub-10-minute refueling windows prove operationally critical. Public Transport Authorities represent the deepest procurement pool, though School Districts emerge as a structurally distinct growth vector following federal rebate program expansion.
The Federal Transit Administration administers capital grants requiring Buy America compliance for rolling stock, while the EPA Clean School Bus Program directs rebate funding toward zero-emission replacements in disadvantaged communities, and NHTSA FMVSS standards govern crashworthiness and electrical system safety for commercial bus platforms. California Air Resources Board mandates through Innovative Clean Transit rulemaking compel statewide fleet conversion timelines that cascade into supplier order books. Stakeholders must monitor state-level utility rate design evolution and depot charging infrastructure interconnection queues as binding constraints on deployment velocity.
Market Dynamics
The Federal Transit Administration's Buy America compliance requirements are restructuring supplier geography across the electric bus value chain, compelling battery pack assembly relocation to domestic facilities and rewiring procurement relationships between transit authorities and component vendors.
Growth Catalysts
- EPA Clean School Bus Program:Rebate funding accelerates zero-emission replacements in disadvantaged communities, unlocking school district procurement pools previously constrained by capital budgets.
- California Innovative Clean Transit:CARB's fleet conversion mandates cascade into binding order timelines that absorb manufacturer capacity years in advance.
- Midwest battery assembly:Domestic cell-to-pack manufacturing is shortening lead times for transit authority contracts and reducing tariff exposure on imported energy storage systems.
Market Restraints
- Lithium carbonate volatility:Cathode material cost swings compress margin predictability for bus OEMs locked into multi-year municipal pricing agreements.
- Depot charging interconnection queues:Utility infrastructure approval timelines in dense urban service territories delay fleet electrification schedules regardless of vehicle availability.
- Hydrogen fuel cell substitution:Sub-10-minute refueling windows in premium corridor applications siphon high-utilization routes away from battery-electric configurations.
Strategic Opportunities
- Texas transit districts:Unpenetrated Sun Belt markets with expanding urban populations offer volume deployment potential absent legacy fleet replacement obligations.
- V2G integration:Bidirectional charging convergence with grid services revenue streams transforms parked bus assets into distributed energy resources.
- Utility rate design evolution:Time-of-use tariffs and demand charge restructuring create operational savings white space for fleets with flexible charging windows.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments face recruitment gaps for personnel certified on 600+ volt battery systems and thermal management diagnostics.
- FMVSS electrical safety certification:Crashworthiness validation timelines for new battery pack architectures extend product development cycles beyond typical municipal procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Bus Market |
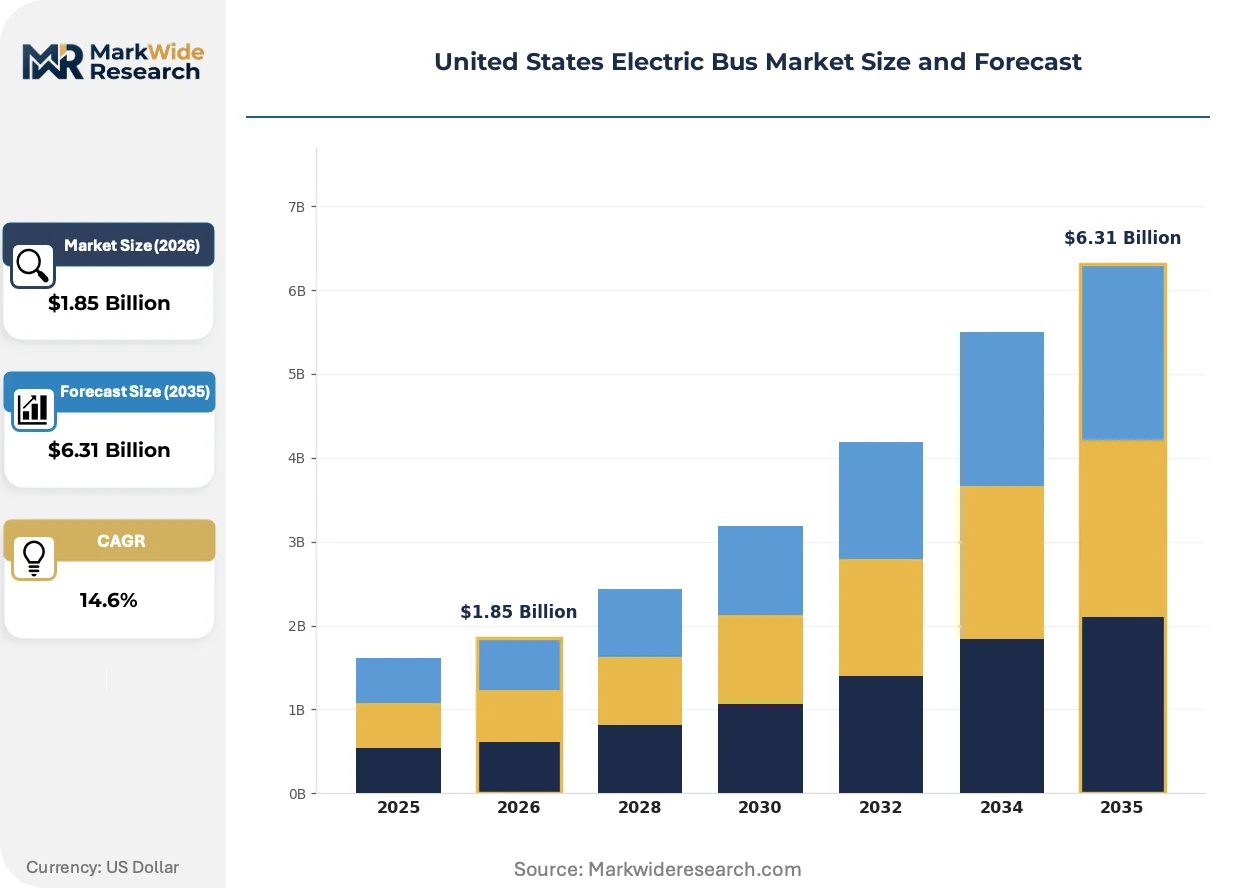
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Battery Electric Bus, Plug-in Hybrid Bus, Extended Range Electric Bus, Hydrogen Fuel Cell Bus End User: Public Transport Authorities, School Districts, Private Operators, Fleet Operators Charging Infrastructure: Fast Chargers, Depot Chargers, Opportunity Chargers, Wireless Charging Systems Application Area: Urban Transport, Campus Transport, Suburban Transport, Shuttle Services |
| Companies Covered | Proterra Inc., BYD Motors Inc., GreenPower Motor Company Inc., New Flyer of America Inc., Blue Bird Corporation, Lion Electric Co., Gillig LLC, Thomas Built Buses Inc., REV Group Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Bus Market Strategic Shifts & Innovations
Solid-state battery prototyping is advancing through transit manufacturer R&D pipelines, while silicon-anode chemistries and modular platform architectures are compressing development cycles across the supplier base.
Lithium iron phosphate cell technology is expanding into high-cycle transit applications where thermal stability and calendar life outweigh energy density requirements. Transit authorities in California and the Northeast Corridor are specifying LFP-dominant configurations for 12-year service life contracts. This chemistry shift is expanding into procurement specifications that previously favored nickel-manganese-cobalt alternatives, compressing supplier qualification burdens for domestic pack assemblers.
The EPA Clean School Bus Program rebate structure is redirecting federal capital toward zero-emission replacements in air quality non-attainment zones. School districts in disadvantaged communities are prioritizing battery-electric configurations over propane or compressed natural gas alternatives. This regulatory mechanism is most visible in California's San Joaquin Valley and Texas border regions, where particulate exposure thresholds trigger priority funding allocation.
Municipal procurement offices are consolidating fleet electrification decisions under sustainability officers rather than traditional maintenance directors. This organizational shift elevates total cost of ownership analytics above upfront capital metrics in vendor evaluation scorecards. The pattern is most pronounced in King County, Washington and Multnomah County, Oregon, where climate action mandates intersect with transit authority governance structures.
United States Electric Bus Market Segmentation
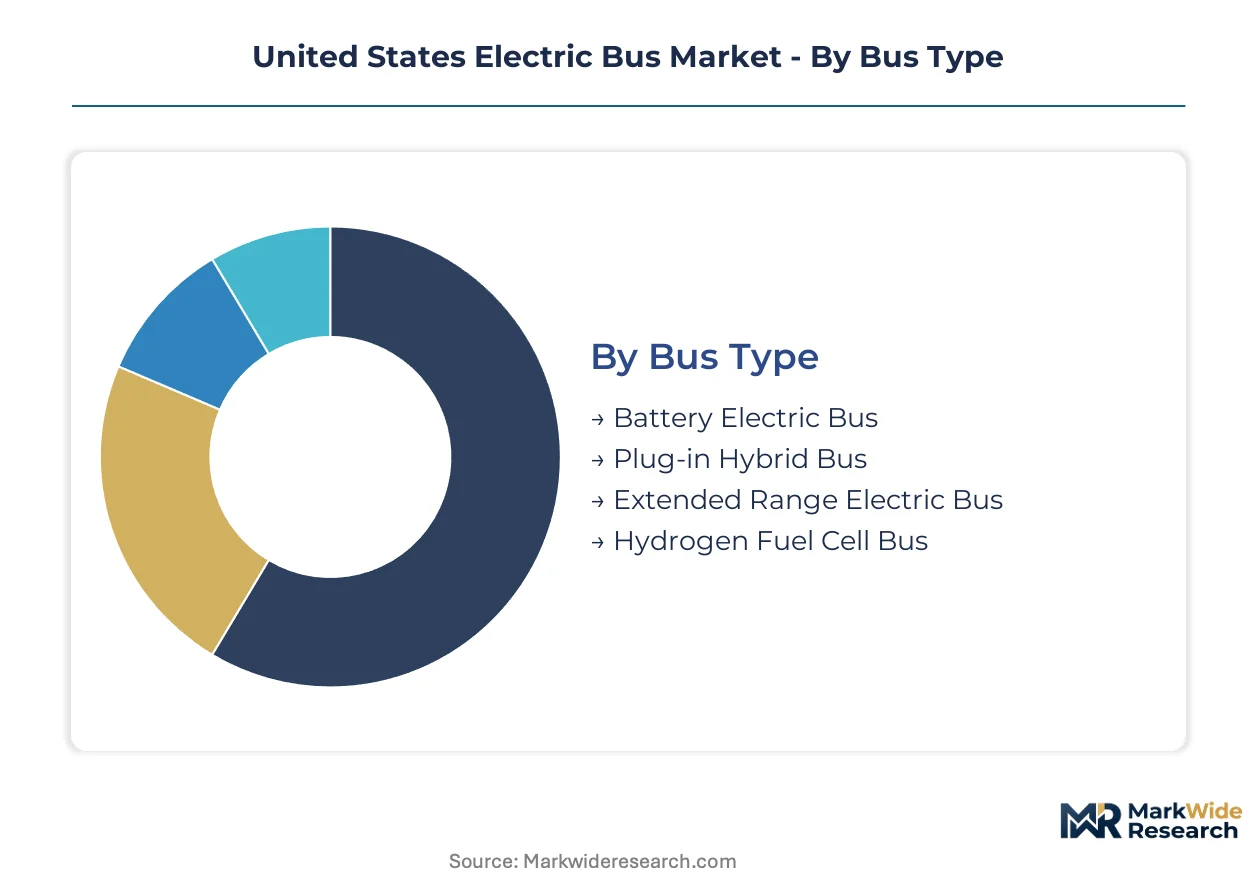
Electric bus procurement patterns diverge sharply across operational contexts, with certification requirements, duty cycle demands, and infrastructure constraints reshaping how manufacturers configure product portfolios. Segment boundaries increasingly determine which suppliers qualify for specific contract tiers.
Bus Type:
NHTSA FMVSS electrical safety certification applies differentially across propulsion architectures, with hydrogen fuel cell platforms facing additional EPA emissions compliance and DOT hazardous materials protocols.
- Battery Electric Bus:Lithium-ion phosphate or nickel-manganese-cobalt battery packs in 200-600 kWh configurations deliver 150-300 mile daily ranges. California transit districts and the Northeast Corridor zero-emission mandates absorb the majority of domestic production capacity for fixed-route service.
- Hydrogen Fuel Cell Bus:Proton exchange membrane stacks paired with 35-70 MPa compressed hydrogen storage enable sub-10-minute refueling windows. Premium corridor applications in high-utilization routes where battery charging downtime proves operationally prohibitive concentrate demand.
- Plug-in Hybrid Bus:Dual-mode architectures retain diesel range extenders for contingency operations.
- Extended Range Electric Bus:Series-hybrid configurations with downsized combustion generators target suburban routes with variable daily mileage.
Leading the category by volume: Battery Electric Bus. Growing fastest: Hydrogen Fuel Cell Bus.
End User:
Capital availability and procurement authority structures fragment the customer base into distinct contracting behaviors, with federal rebate eligibility reshaping competitive dynamics.
- Public Transport Authorities:Municipal and regional transit agencies with dedicated capital funding streams and FTA grant access dominate unit procurement. California's Innovative Clean Transit rulemaking and New York MTA electrification commitments absorb manufacturer capacity years in advance.
- School Districts:EPA Clean School Bus Program rebates unlock zero-emission procurement for capital-constrained districts in air quality non-attainment zones. San Joaquin Valley and Texas border region districts prioritize battery-electric configurations over propane alternatives.
- Private Operators:Airport shuttles and corporate campus fleets with shorter duty cycles.
- Fleet Operators:Multi-site logistics and rental bus companies with centralized maintenance infrastructure.
Public Transport Authorities command the largest contract values. School Districts are climbing the fastest.
Charging Infrastructure:
Utility interconnection timelines and rate design structures segment deployment feasibility across infrastructure categories.
- Depot Chargers:Overnight AC or DC systems at 50-150 kW enable complete fleet replenishment during dwell periods. Dense urban service territories face utility infrastructure approval queues that delay electrification schedules regardless of vehicle availability.
- Fast Chargers:350+ kW DC systems for opportunity charging at route termini. High-frequency corridors with sub-15-minute layover windows in King County and Multnomah County concentrate initial deployment.
- Opportunity Chargers:Pantograph or plug-in systems at intermediate stops for partial state-of-charge management.
- Wireless Charging Systems:Inductive pads embedded at bus stops for dynamic charging during passenger loading.
Depot Chargers anchor current deployment volumes. Fast Chargers are expanding most quickly.
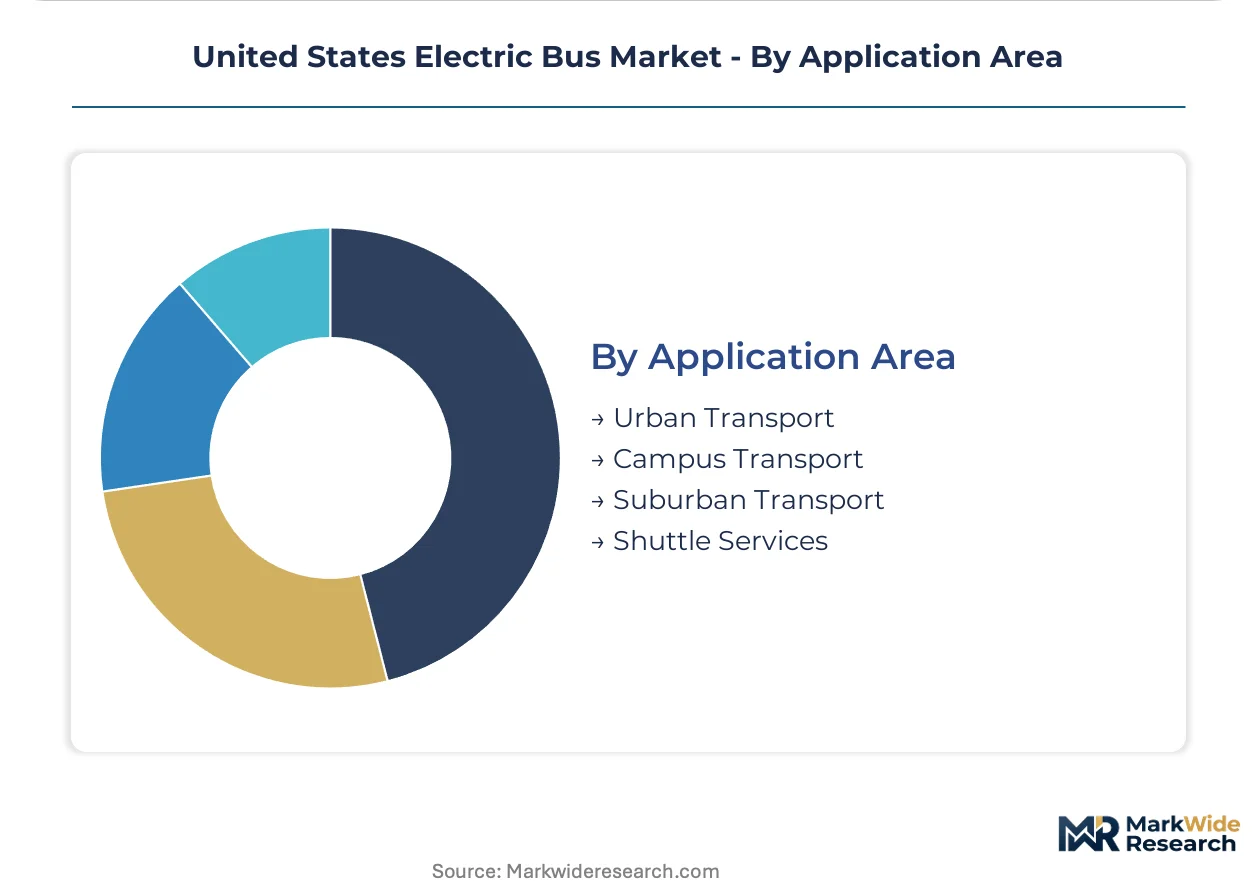
Application Area:
Duty cycle predictability and route density determine which propulsion configurations achieve total cost of ownership parity.
- Urban Transport:Fixed-route service with high passenger volumes and predictable stop-and-go patterns. California SB 100-aligned transit districts and Northeast Corridor zero-emission mandates concentrate battery-electric specification.
- Campus Transport:Closed-loop operations with controlled charging infrastructure and moderate daily mileage. University and corporate campus fleets in Washington and Oregon states prioritize sustainability metrics in procurement scorecards.
- Suburban Transport:Longer inter-stop distances with variable passenger loads.
- Shuttle Services:On-demand or scheduled services with irregular routing patterns.
Urban Transport dominates segment revenue. Campus Transport shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate processing capacity in Nevada's Clayton Valley anchors domestic battery supply chains for electric bus deployment across the United States.
California
Transit agencies in Los Angeles County and the San Francisco Bay Area command the nation's deepest procurement pipelines for battery-electric buses. The California Air Resources Board's Innovative Clean Transit rule mandates complete fleet conversion by 2040, binding manufacturer capacity years in advance. Proterra's Union City assembly facility and BYD's Lancaster manufacturing plant concentrate production capacity in the state's inland empire region.
New York
The Metropolitan Transportation Authority's electrification commitments absorb substantial domestic production volume for fixed-route service. Federal Transit Administration capital grants with Buy America compliance requirements shape supplier selection criteria for municipal procurement offices. New Flyer of America maintains engineering and assembly operations in the Buffalo-Niagara region to serve Northeast Corridor demand.
Texas
Dallas Area Rapid Transit and Houston Metro represent unpenetrated volume potential in Sun Belt markets with expanding urban populations. The state's deregulated electricity market enables innovative rate structures for depot charging infrastructure. School districts in the Rio Grande Valley prioritize battery-electric configurations through EPA Clean School Bus Program rebate allocation.
Washington
King County Metro's sustainability mandates intersect with climate action commitments from the Seattle metropolitan government. Municipal procurement offices consolidate fleet electrification authority under chief sustainability officers rather than traditional maintenance directors. Pacific Northwest utility rate design evolution creates operational savings for fleets with flexible overnight charging windows.
Illinois
The Chicago Transit Authority's electrification roadmap drives demand for heavy-duty transit configurations in the Midwest's largest metropolitan area. Domestic battery pack assembly capacity in the broader Great Lakes region shortens lead times for transit authority contracts. Manufacturing clusters in Michigan and Ohio supply drivetrain components and thermal management systems to bus assemblers serving Illinois procurement offices.
United States Electric Bus Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche specialization and geographic white space. The vendor base concentrates around three strategic archetypes: integrated battery manufacturers with captive pack assembly, modular platform specialists spanning multiple propulsion configurations, and school bus incumbents pivoting from diesel dominance. Competitive dynamics center on capacity reservation agreements with transit authorities and backward integration into cell-to-pack manufacturing to secure cost positions.
Among domestic producers with integrated manufacturing footprints, Proterra Inc., BYD Motors Inc., and New Flyer of America Inc. exemplify contrasting strategic postures. Proterra represents the vertically integrated archetype with in-house battery production. BYD anchors the Chinese-headquartered multinational position through California-based final assembly. New Flyer occupies the modular platform specialist tier with configurable architectures spanning battery-electric and hydrogen fuel cell variants.
| Leading Market Players |
|---|
| Proterra Inc. |
| BYD Motors Inc. |
| GreenPower Motor Company Inc. |
| New Flyer of America Inc. |
| Blue Bird Corporation |
| Lion Electric Co. |
| Gillig LLC |
| Thomas Built Buses Inc. |
| REV Group Inc. |
| Others |
Cost & Logistics Intelligence
Lithium carbonate cathode material traces a volatile path from South American brine operations through battery pack assemblers in the Midwest to municipal transit authority procurement tiers, compressing margin predictability for OEMs locked into multi-year fixed-price contracts while rewarding suppliers with captive cell-to-pack manufacturing capabilities.
Pricing Analysis
Warranty and service bundling separates premium transit authority contracts from capital-constrained school district procurements, with extended battery coverage and depot maintenance packages commanding substantial premiums. Pricing stratifies across integrated-battery manufacturers, modular platform specialists, and diesel incumbents pivoting to electric configurations based on vertical integration depth and FTA Buy America compliance certification. Cost compression in the school bus segment is intensifying because EPA Clean School Bus Program rebate structures cap effective pricing regardless of base vehicle cost. Public transport authorities with dedicated capital funding streams exhibit the lowest price sensitivity, while rural school districts dependent on federal rebates face severe budget constraints.
Supply Chain Analysis
Workforce availability for high-voltage battery assembly in Michigan, Ohio, and California manufacturing clusters constrains domestic pack production expansion despite surging transit authority demand. Cell manufacturing draws from South Korean and Japanese suppliers, with lithium carbonate processing anchored in Nevada's Clayton Valley and cathode active material production concentrated in East Asian chemical processing hubs. Single-source vulnerability for proton exchange membrane stacks in hydrogen fuel cell configurations creates procurement risk for dual-platform manufacturers. Distribution runs through direct OEM-transit authority relationships for heavy-duty configurations and dealer networks for school bus segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States electric bus market functions as a vertical-integration race where control over battery cell supply and pack assembly determines cost position and contract win rates across municipal procurement cycles.
For Market Incumbents: Hedge against hydrogen fuel cell substitution in premium corridor applications by maintaining dual-platform engineering capabilities and securing PEM stack supply agreements with established fuel cell suppliers. Expand in-house cell-to-pack manufacturing capacity in Midwest assembly clusters to reduce tariff exposure on imported energy storage systems and shorten lead times for FTA grant-funded procurements. For New Entrants and Emerging Players: The EPA Clean School Bus Program in Texas border regions and California's San Joaquin Valley opens a window for specialized school bus configurations targeting air quality non-attainment zone districts with simplified depot charging architectures. Target unpenetrated Sun Belt transit districts in Dallas and Houston with lease-to-own financing structures that circumvent capital budget constraints, positioning battery-electric offerings against legacy diesel replacement cycles. For Investors and Strategic Acquirers: Utility rate design rulings establishing favorable time-of-use tariffs for depot charging infrastructure is the leading indicator that fleet electrification velocity will accelerate beyond vehicle supply constraints. Mid-cap specialists with integrated battery engineering capabilities and existing FTA Buy America certification represent the most defensible acquisition profile for long-term positioning across the transition horizon. Monitor state public utility commission docket filings for demand charge restructuring proposals as the primary signal of charging infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell procurement contracts with Korean suppliers secure cost position for CARB-mandated fleet conversions. |
| Backward Integration | In-house pack assembly in Midwest facilities satisfies FTA Buy America compliance and reduces lead times. |
| Platform Standardization | Modular architectures spanning battery-electric and hydrogen configurations defend against technology substitution. |
| Charging Infrastructure Partnership | Utility collaboration on depot interconnection queues removes deployment bottlenecks in dense urban territories. |
| Geographic Manufacturing Footprint | California and Great Lakes assembly plants anchor regional procurement relationships with transit authorities. |
Research Approach
Multi-period observation of transit authority procurement awards, battery pack shipment volumes, and utility interconnection queue depths anchored the trend analysis, supplemented by interviews with fleet electrification directors at municipal transportation agencies, procurement officers at school districts, battery pack engineering leads at Midwest assembly facilities, and utility demand-side management specialists. Secondary validation drew from FTA capital grant disbursement records, EPA Clean School Bus Program rebate allocations, CARB Innovative Clean Transit compliance filings, and NHTSA FMVSS certification databases. Bottom-up unit shipment modeling and top-down market value estimation were cross-referenced for triangulation.
Segment-weighting approaches applied differential growth assumptions across battery-electric and hydrogen fuel cell propulsion architectures, public transport authority and school district end-use categories, and depot versus fast charging infrastructure configurations over the projection horizon. CAGRs were derived from fitted trend lines applied to historical procurement data and policy-mandated fleet conversion timelines. Forecast inputs incorporated lithium carbonate price volatility scenarios and utility infrastructure approval timeline distributions.
Caveats apply where lithium carbonate supply disruptions, utility rate design reversals, or hydrogen fuel cell cost breakthroughs could materially shift the outlook for battery-electric deployment trajectories. Forecasts reflect assumptions about regulatory mandate continuity and federal rebate program funding levels. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
City Bus Low-Floor Axle Systems Market
Buses
United States School Bus Market
Buses
Europe Bus Market
Buses
Bus Rental Market
Buses
Luxury Coaches Market
Buses
Intercity Bus Travel Market
Buses
North America Bus Market
Buses
Europe Trolley Bus Market
Buses
Buses & Coaches Market
Buses
Global Luxury Shuttle Bus Market
Buses
Solar Bus Market
Buses
Electric Intercity Bus Market
Buses
School Bus Market
Buses
Bus Charter Services Market
Buses
Trolley Bus Market
Buses
Bus Seat Market