
 Bus Seat Market | 2026-2036
Bus Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Bus Seat Market Intelligence
The integration of lightweight composite materials and modular design principles is fragmenting the traditional, monolithic approach to bus seat manufacturing. GRAMMER AG leverages its expertise in commercial vehicle ergonomics to capture the premium coach segment. Faurecia, in contrast, competes on a global scale by offering standardized seating systems to large vehicle manufacturers. Freedman Seating Company specializes in the North American city transit and paratransit vehicle markets.
A bus seat is an engineered seating system designed for passenger vehicles, constructed from a core structure of metal or composites, foam padding, and durable upholstery. These systems must meet specific criteria for crashworthiness, fire retardancy, and ergonomic support. Within applications, intercity coaches command higher-margin reclining seats, while city transit vehicles primarily use fixed, vandal-resistant bench seats. The choice of material, from basic vinyl and polyester fabric to premium leatherette, directly influences both cost and perceived passenger comfort.
Safety and material standards are governed by a complex web of regional mandates, including the US National Highway Traffic Safety Administration (NHTSA) crash test requirements and Europe's ECE regulations for vehicle components. In China, compliance with specific GB standards for flammability and structural integrity is a prerequisite for market entry. Suppliers must navigate these divergent compliance pathways while balancing cost pressures with demands for enhanced passenger amenities.
Market Dynamics
The market's primary structural force is the bifurcation of design requirements. Intercity coaches demand high-comfort, feature-rich reclining seats, while urban transit vehicles prioritize durability, vandal resistance, and low lifecycle cost, creating divergent supply chains and R&D pathways.
Growth Catalysts
- Public Infrastructure Investment:China's national policy of expanding high-capacity bus rapid transit (BRT) systems in tier-2 and tier-3 cities requires massive volumes of standardized seating.
- Safety Mandates:The updated EU General Safety Regulation mandates features like advanced emergency braking support, which indirectly influences seat design for crashworthiness and passenger bracing.
- Passenger Experience:Intercity coach operators in North America and Europe compete on comfort, making reclining seats with USB ports and individual lighting a baseline expectation.
Market Restraints
- Input Cost Volatility:Fluctuating prices for petroleum-derived foams and specialized steel alloys for seat frames compress manufacturer margins, particularly on high-volume transit contracts.
- Regulatory Divergence:A single seat design rarely meets the distinct crashworthiness standards of NHTSA in the US, ECE regulations in Europe, and GB standards in China.
- Refurbishment Threat:Fleet operators often choose to reupholster and re-foam existing seats, a lower-cost alternative that defers new seat procurement cycles for budget-constrained municipalities.
Strategic Opportunities
- Electrification:The transition to electric buses in markets like India and Brazil creates demand for new, lightweight seating to offset battery weight and maximize vehicle range.
- Hygienic Materials:Integrating antimicrobial textiles and non-porous surfaces into seat construction addresses public health concerns, creating a new premium feature category.
- Modular Systems:Developing modular seat platforms allows for easier customization and repair, appealing to fleet managers focused on reducing vehicle downtime and total cost of ownership.
Industry Challenges
- Certification Delays:The extensive testing and documentation required to achieve compliance with ECE R118 (flammability) for new materials can significantly delay product launches in Europe.
- Skilled Labor Shortage:A lack of technicians skilled in composite material fabrication and repair affects the production and maintenance of advanced lightweight seating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bus Seat Market |
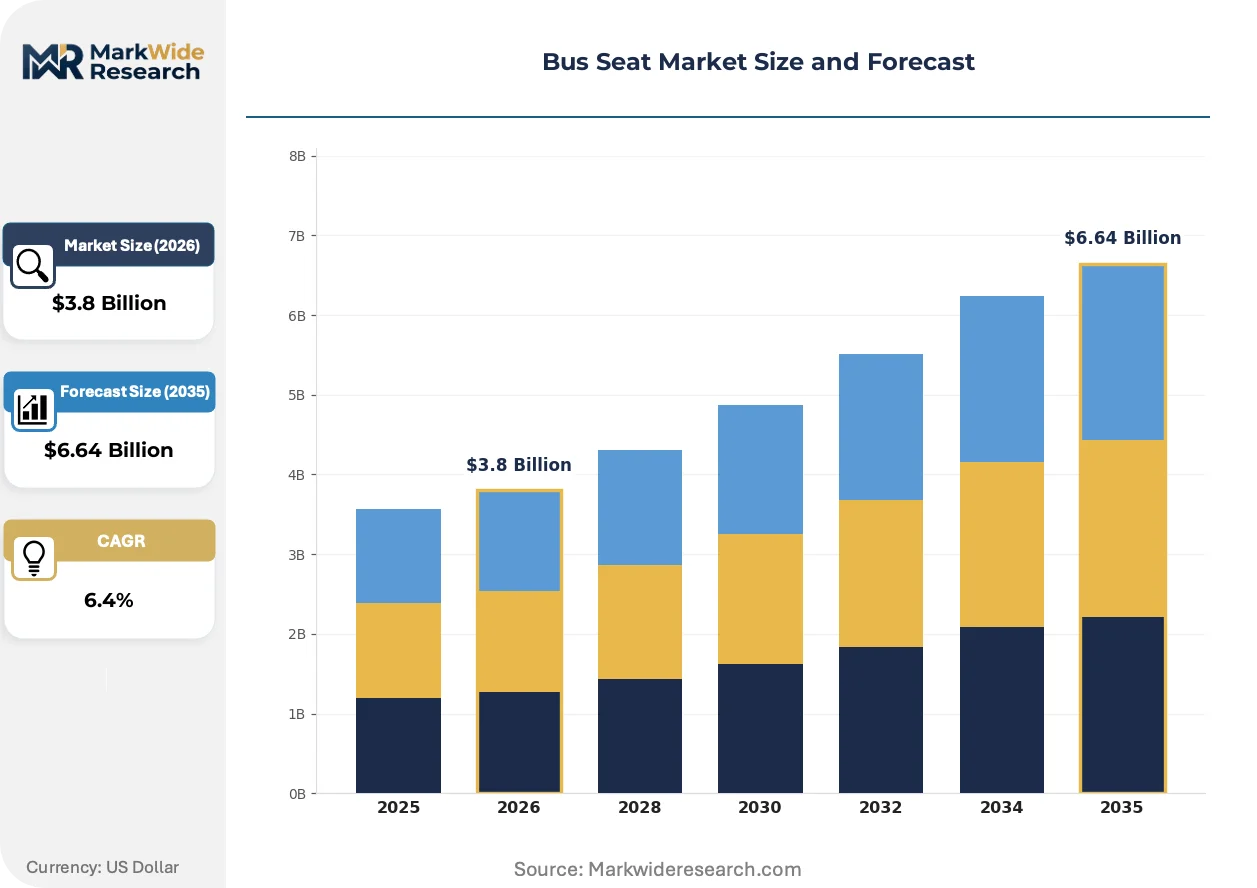
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench Seats, Individual Seats, Foldable Seats, Reclining Seats, Fixed Seats Material: Foam, Polyester Fabric, Leatherette, Vinyl, Mesh Application: City Transit Vehicles, School Transportation, Intercity Coaches, Tourist Buses, Shuttle Services End User: Bus Operators, Transportation Authorities, Tour Companies, Private Fleet Owners, Vehicle Manufacturers |
| Companies Covered | Freedman Seating Company, Adient, GRAMMER AG, Lear Corporation, ISRINGHAUSEN GmbH, Faurecia, Franz Kiel GmbH, Toyota Boshoku, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bus Seat Market Strategic Shifts & Innovations
The definition of a bus seat is expanding from a passive passenger accommodation to an active, intelligent system. This evolution integrates seating into the vehicle's broader electronic architecture, driven by demands for enhanced safety, operational efficiency, and data.
Occupancy sensor technology provides operators real-time data on passenger loads. Adoption is accelerating in metropolitan transit authorities for route planning and safety monitoring. Consequently, the bus seat is migrating from a simple mechanical component to an active data collection node within the vehicle's intelligent transportation system (ITS) network.
Europe's ECE Regulation R118, governing material flammability, imposes stricter burn-rate tests through ongoing revisions. This forces investment in R&D for new fire-retardant composites and textiles. The city transit segment, with its high-density seating, faces the most significant cost impact from this compliance burden.
A shift from transactional purchases to long-term life-cycle management contracts is altering procurement. Transit agencies now bundle multi-year maintenance and refurbishment services into the initial tender. This trend is most prominent in large municipal bus fleet renewals across North America.
Bus Seat Market Segmentation
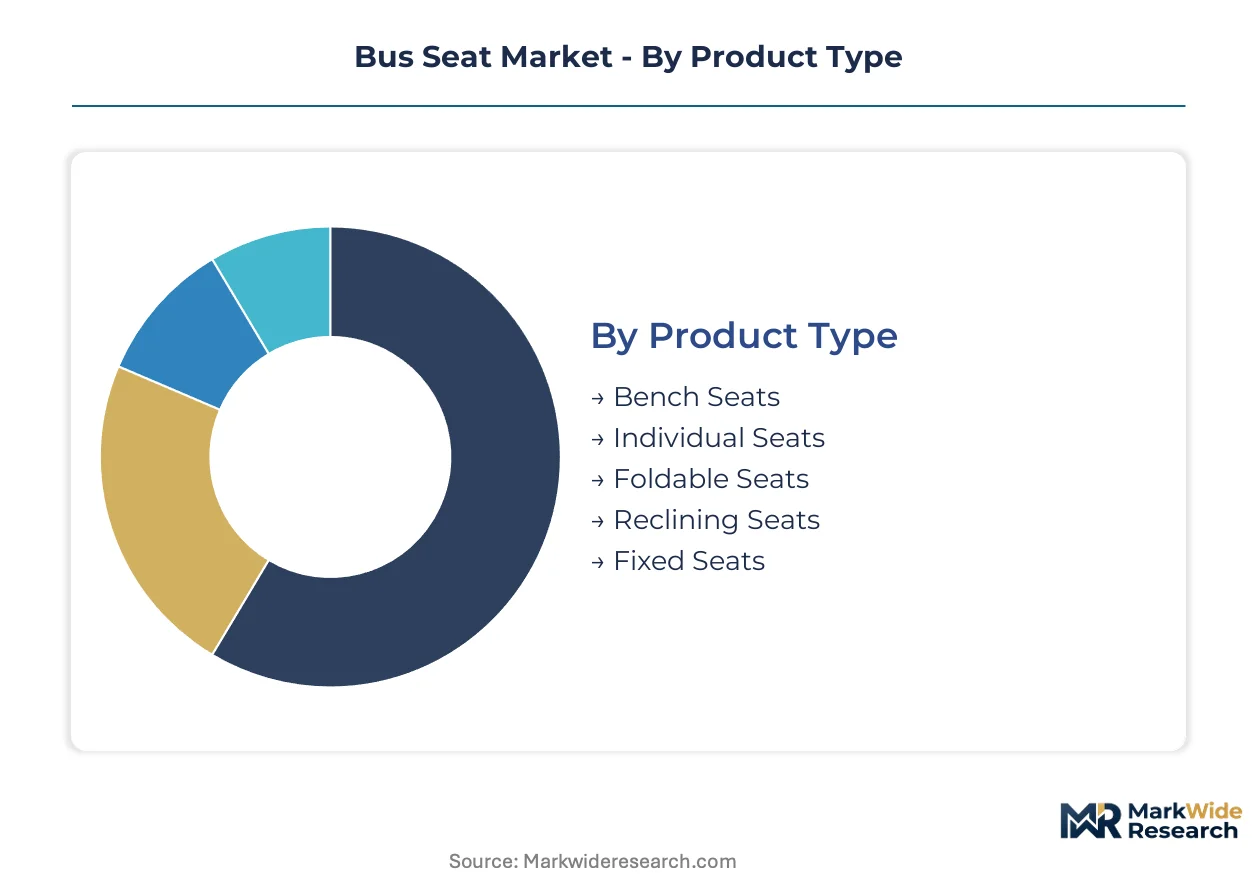
The bus seat market exhibits diverse requirements driven by varied vehicle types and operational demands. Understanding these distinctions through segmentation is crucial for manufacturers to tailor product offerings and sales strategies effectively. This analysis breaks down the market into key categories, highlighting the unique characteristics and commercial implications of each segment.
Product Type:
The product type segmentation illustrates a spectrum from mature, high-volume solutions to emerging, feature-rich innovations.
- Reclining Seats:Engineered systems allow passengers to adjust their backrest angle, often incorporating armrests and headrests. Demand concentrates in intercity coaches and tourist buses across Europe and North America, driven by passenger experience.
- Fixed Seats:Designed for maximum durability and vandal resistance, fixed seats provide a static seating position without adjustable features. City transit vehicles in China and India represent massive volume requirements for these robust solutions.
- Bench Seats:Simple, continuous seating arrangements prioritize high passenger capacity and ease of cleaning in urban transit environments.
- Individual Seats:Offering personal space and higher comfort, individual seats are common in premium shuttle services and smaller coaches.
- Foldable Seats:These flexible seating options allow for quick reconfiguration of vehicle interiors, primarily found in specialized paratransit or multi-purpose buses.
Fixed Seats handle the majority of throughput; Reclining Seats are the fastest mover on share.
Material:
Material selection for bus seats directly influences the overall cost structure and durability, ranging from economical options to more premium finishes.
- Foam:Polyurethane and other polymer foams form the core cushioning element, providing ergonomic support and impact absorption. Fluctuating petroleum prices directly impact manufacturing costs for high-density applications.
- Leatherette:This synthetic material provides a premium aesthetic and is easier to clean, offering a cost-effective alternative to genuine leather. Demand is expanding in luxury coach segments in Europe and North America.
- Polyester Fabric:Widely used for its durability and cost-effectiveness, polyester fabrics offer a balance of comfort and wear resistance.
- Vinyl:Known for extreme durability and ease of sanitation, vinyl is a preferred material for high-traffic city buses and school transportation.
- Mesh:Mesh materials offer breathability and a modern aesthetic, often incorporated into backrests for enhanced passenger ventilation.
The selection of Foam often dictates overall seating comfort; Leatherette offers a premium aesthetic and improved cleanability.
Application:
The application segment delineates distinct functional requirements, from high-volume urban transport to specialized long-distance travel.
- Intercity Coaches:These vehicles require comfortable, often reclining seats with amenities like USB ports and individual lighting for extended journeys. Operators in North America and Europe prioritize these features.
- City Transit Vehicles:Durability, vandal resistance, and ease of cleaning are paramount for seats in high-frequency, short-distance urban transport. Major metropolitan areas in China and India drive immense demand.
- School Transportation:Safety and basic comfort are key for school bus seating, which must withstand consistent use by children.
- Tourist Buses:Similar to intercity coaches, tourist buses demand comfortable, often reclining seats with features suitable for longer excursions.
- Shuttle Services:This segment covers airport transfers to corporate shuttles, requiring adaptable seating that balances comfort and capacity.
City Transit Vehicles represent a significant volume opportunity, whereas Intercity Coaches command premium feature integration.
End User:
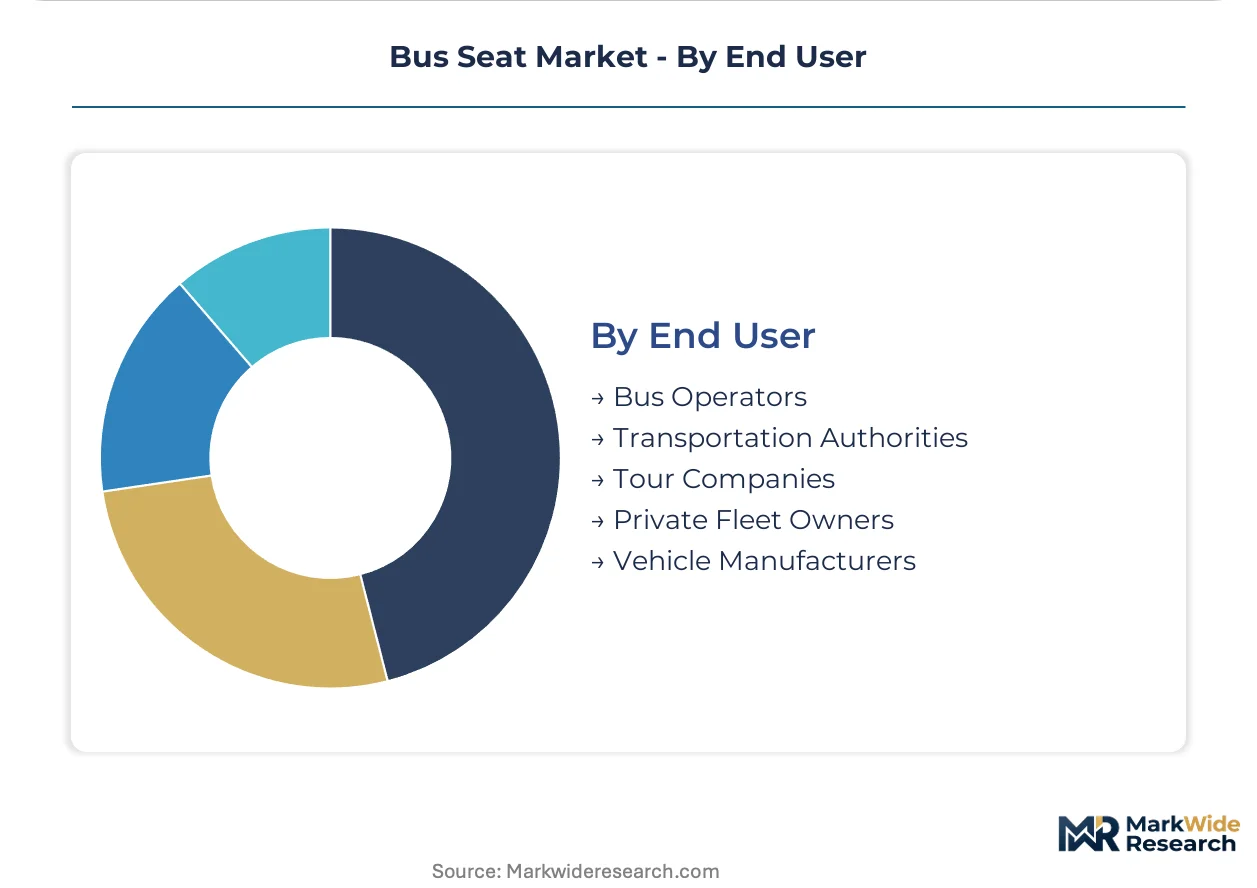
The end user segmentation highlights varying procurement priorities and purchasing power across different customer types.
- Bus Operators:These entities directly purchase seats for their fleets, focusing on lifecycle costs, maintenance ease, and passenger satisfaction. Large private bus companies in Europe and North America drive demand.
- Vehicle Manufacturers:OEMs integrate bus seats into their vehicle designs, prioritizing supply chain efficiency, standardization, and compliance with vehicle crashworthiness standards. Global manufacturers source high volumes.
- Transportation Authorities:Public transportation authorities procure seats for municipal fleets, emphasizing durability, public safety standards, and long-term value.
- Tour Companies:These companies prioritize passenger comfort and amenities for their tourist coaches, often seeking aesthetically pleasing and feature-rich seating.
- Private Fleet Owners:This diverse group includes corporate and specialized transport fleets, requiring seats balancing specific application needs with cost-effectiveness.
Direct procurement by Bus Operators focuses on total cost of ownership, while Vehicle Manufacturers emphasize initial vehicle integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bus seat procurement concentrates heavily among large public transportation authorities and vehicle manufacturers. These key buyer archetypes drive regional market dynamics through distinct demands. Their purchasing power shapes product development and supply chain investments across different geographies.
China
China's extensive public transportation infrastructure projects demand massive volumes of standardized seating. The country's GB standards for flammability and structural integrity are prerequisites for market entry. Cities like Shanghai and Beijing are rapidly expanding their BRT systems, requiring high-volume fixed seat procurement.
United States
United States demand for bus seats is shaped by school transportation and city transit vehicle renewals. The National Highway Traffic Safety Administration (NHTSA) sets stringent crash test requirements for all seating systems. Manufacturers in states like Illinois, home to Freedman Seating Company, focus on robust, compliant solutions for municipal fleets.
Germany
Germany's market for bus seats emphasizes ergonomic design and advanced materials for intercity coaches. Europe's ECE regulations, particularly ECE R118 for flammability, heavily influence product development. The automotive manufacturing cluster around Stuttgart and Munich drives innovation in premium seating solutions for commercial vehicles.
India
India's burgeoning urban centers necessitate durable and cost-effective seating for city transit vehicles. The government's push for electric buses creates demand for lightweight seating to maximize range. New Delhi and Mumbai are investing in modernizing their public bus fleets, driving significant volume for fixed and bench seats.
Brazil
Brazil's bus seat market is growing due to investments in public transport infrastructure and fleet modernization. National safety standards influence seat design, particularly for urban and intercity routes. The automotive manufacturing hubs in São Paulo and Minas Gerais are key centers for bus seat production and supply.
Bus Seat Market Key Industry Players
Channel-controlling players compete with product-specialist players across the bus seat market. The market structure exhibits a tiered consolidation, with large global suppliers addressing multiple segments alongside niche regional manufacturers. Strategic archetypes include diversified automotive suppliers, dedicated seating system providers, and regional specialists. Companies often engage in strategic partnerships and portfolio diversification to capture new opportunities and expand their geographic reach. This enables them to navigate diverse regulatory environments and cater to varying customer demands.
Among global manufacturers, Faurecia, a French-based automotive supplier, exemplifies the strategy of offering standardized seating systems to large vehicle manufacturers on a global scale. GRAMMER AG, a German company, represents expertise in commercial vehicle ergonomics, capturing the premium coach segment with high-comfort solutions. Freedman Seating Company, based in the United States, occupies a position as a specialist in the North American city transit and paratransit vehicle markets, prioritizing durability and compliance. These companies anchor different segments by leveraging their core strengths, technological capabilities, and regional focus.
| Leading Market Players |
|---|
| Freedman Seating Company |
| Adient |
| GRAMMER AG |
| Lear Corporation |
| ISRINGHAUSEN GmbH |
| Faurecia |
| Franz Kiel GmbH |
| Toyota Boshoku |
| Magna International Inc. |
| Others |
Cost & Logistics Intelligence
Fluctuating petroleum prices for foams and specialized steel alloys for frames impact manufacturer margins, especially in high-volume transit contracts. This upstream cost volatility squeezes profitability for downstream seat manufacturers.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate high-volume city transit tenders. Customization level for premium intercity coaches and certification level for crashworthiness standards (e.g., NHTSA, ECE) drive price differentiation. Pricing softness reflects intense competition for large municipal contracts, particularly for fixed seats. Transportation authorities and vehicle manufacturers are highly price-sensitive for standardized products, while intercity coach operators show less sensitivity for premium features.
Supply Chain Analysis
Regulatory divergence across US (NHTSA), Europe (ECE), and China (GB standards) creates complexity and cost for manufacturers. China and Germany concentrate bus seat manufacturing, with significant component sourcing from India and Brazil. Petroleum-derived foams and specialized steel alloys form critical material dependencies. Distribution runs through direct OEM integration for vehicle manufacturers and direct procurement for bus operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bus seat market presents a defensive-moat story, primarily due to regulatory entrenchment from stringent safety and flammability standards. Compliance with diverse regional mandates creates significant barriers to entry for new players.
For Market Incumbents: Pre-empt the refurbishment threat from fleet operators by offering long-term life-cycle management contracts. Invest in modular seat platforms for easier customization and repair, and expand R&D into hygienic materials. Leverage existing certification investments across ECE, NHTSA, and GB standards to maintain market position.
For New Entrants and Emerging Players: Pursue strategic partnerships with emerging electric bus manufacturers to integrate seating early in the design cycle. Target underserved regional city transit markets in India and Brazil, focusing on lightweight seating for electric buses. The electric bus segment offers a penetrable entry point due to evolving design requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional specialists possessing strong compliance expertise. The market offers stable, long-term returns driven by public infrastructure investment and fleet modernization over the next decade. Acquire specialized regional manufacturers with strong compliance expertise in specific geographies like North America or China. Monitor the accelerating adoption of electric buses and associated demand for lightweight seating as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Modular Seat Platforms | Allows for rapid customization and reduces vehicle downtime for fleet operators. |
| Invest in Antimicrobial Material R&D | Addresses public health concerns and creates a new premium feature category for operators. |
| Expand Certification Capabilities | Navigates diverse regional safety mandates like NHTSA and ECE regulations, enabling broader market access. |
| Form Partnerships with EV Bus OEMs | Captures demand for lightweight seating solutions in the rapidly growing electric vehicle segment. |
| Offer Life-Cycle Management Contracts | Shifts procurement from transactional purchases to long-term service agreements, securing recurring revenue. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings. This involved discussions with bus operators, vehicle manufacturers, material suppliers, and transportation authority procurement leads. Secondary validation drew from public transportation infrastructure reports, national safety regulation documents (NHTSA, ECE, GB standards), and automotive industry production data. Bottom-up and top-down triangulation ensured data consistency.
Calibration of historical growth rates against current market dynamics informed the forecast trajectory over the projection horizon. The analytical framework modeled segmentation dimensions including product type, material, application, and end-user, alongside regional adoption patterns. Compound annual growth rates were derived from a detailed analysis of new vehicle production schedules and fleet renewal cycles. Public infrastructure investment trends served as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or raw material prices would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Europe Trolley Bus Market
Buses
Luxury Bus Market
Buses
Buses & Coaches Market
Buses
United States School Bus Market
Buses
Bus Flooring Market
Buses
United States Electric Bus Market
Buses
Global Bus Market
Buses
Bus Rental Market
Buses
Fuel Cell Electric Bus Market
Buses
Hydrogen Buses Market
Buses
Intercity Bus Travel Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Luxury Coaches Market
Buses
Intelligent Bus Shelter Market
Buses
Solar Bus Market
Buses
Electric Intercity Bus Market