
 School Bus Market | 2026-2036
School Bus Market Size, Share, and Industry Trends Forecast 2026-2036
School Bus Market Outlook
Steel-intensive chassis construction is expanding as aluminum substitution gains ground in electric school bus architectures, reducing curb weight and extending battery range. Thomas Built Buses leverages its parent company's commercial truck scale to control powertrain sourcing costs. Blue Bird Corporation anchors its position through dedicated electric bus manufacturing capacity in Georgia. IC Bus competes with integrated Navistar drivetrain engineering for conventional and alternative-fuel platforms.
A school bus is a purpose-built passenger transport vehicle designed for student conveyance, typically featuring reinforced side-impact protection, flashing warning lamp systems, and stop-sign actuator arms with a gross vehicle weight rating spanning 10,000 to 36,000 pounds. Conventional bus configurations with hood-forward engine placement dominate North American procurement due to maintenance accessibility and driver familiarity. Electric bus adoption within the fuel type category attracts disproportionate capital allocation as utility rebate programs and EPA Clean School Bus funding reshape district purchasing timelines. Large bus variants in the size category sustain the highest unit margins, though mini bus demand accelerates in rural and special-needs routing applications.
EPA tailpipe emissions standards and NHTSA Federal Motor Vehicle Safety Standards govern powertrain certification and occupant protection design, respectively, while the Infrastructure Investment and Jobs Act channels dedicated funding toward zero-emission fleet conversion. State-level regulators in California augment federal requirements with Advanced Clean Trucks mandates that phase in electric procurement quotas for public fleets. Stakeholders must monitor utility interconnection timelines and rate structure negotiations, as charging infrastructure deployment speed will determine whether electric bus order backlogs convert to operational fleet additions.
Market Dynamics
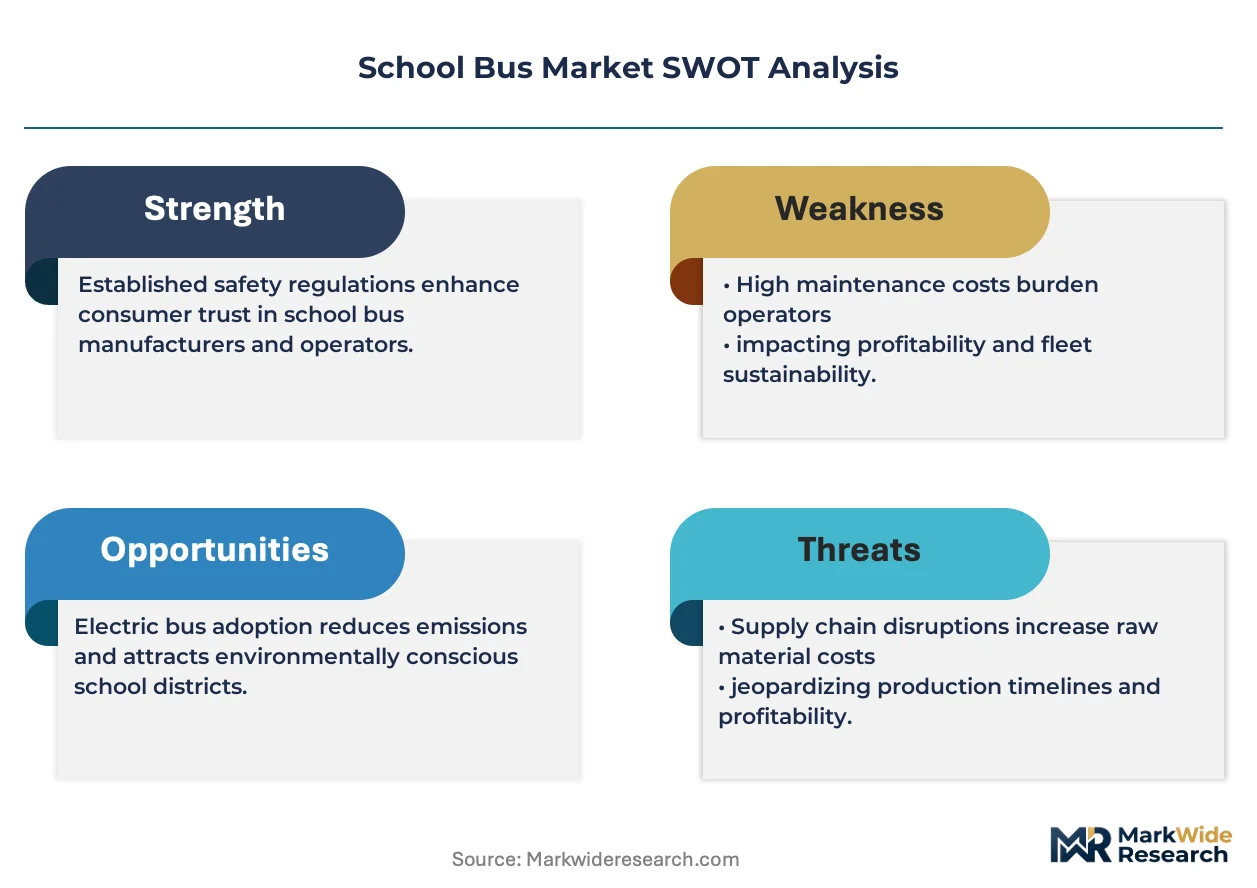
EPA Clean School Bus funding is compressing replacement cycles as districts accelerate zero-emission procurement timelines ahead of traditional diesel retirement schedules. Utility rebate programs and state-level clean fleet mandates are rewiring capital allocation patterns across public transportation authorities.
Growth Catalysts
- Battery cost curves:Lithium-ion cell prices are collapsing procurement economics for electric powertrains. School districts in California and New York are capturing total cost of ownership parity with diesel within eight-year fleet lifecycles.
- Utility rate structures:Demand-response tariffs and managed charging incentives from major municipal utilities are shaving operational costs for electric fleet operators. Pacific Gas & Electric and Consolidated Edison offer time-of-use rebates specifically for school bus depots.
- Advanced Clean Trucks:California Air Resources Board mandates are phasing in electric procurement quotas for public fleets. Districts must achieve 50% zero-emission purchases by 2035, creating regulatory pull-through.
Market Restraints
- Charging infrastructure capex:Depot electrical upgrades require transformer capacity expansions and switchgear installations. Rural districts face 18-month utility interconnection queues that delay fleet electrification.
- Steel and aluminum volatility:Chassis fabrication depends on hot-rolled coil and extruded aluminum pricing. Bus manufacturers lack pass-through mechanisms for raw material swings exceeding 15% annually.
- Range anxiety in cold climates:Battery thermal management losses in Minnesota and North Dakota reduce effective range by 30-40% during winter months. Diesel heating systems remain operationally superior for sub-zero routes.
Strategic Opportunities
- V2G grid services:Bidirectional charging infrastructure enables school buses to sell peak-shaving capacity back to utilities. Southern California Edison and Duke Energy are piloting frequency regulation programs with district fleets.
- Rural route consolidation:Mini bus configurations with 70-100 mile electric range are penetrating sparsely populated counties. Montana and Wyoming districts are testing 14-passenger electric units for low-density student transport.
- Federal tax credit stacking:The Inflation Reduction Act's commercial clean vehicle credit combines with state rebates. Districts in Texas and Florida are capturing $100,000+ per vehicle in stacked incentives.
Industry Challenges
- Technician certification gaps:High-voltage electrical systems require specialized training beyond traditional diesel mechanic credentials. Community college programs in Ohio and Pennsylvania are struggling to graduate sufficient EV-certified technicians.
- Software integration complexity:Telematics platforms from charging network providers must interface with legacy student information systems. Routing optimization algorithms require real-time state-of-charge data that existing dispatch software cannot process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | School Bus Market |
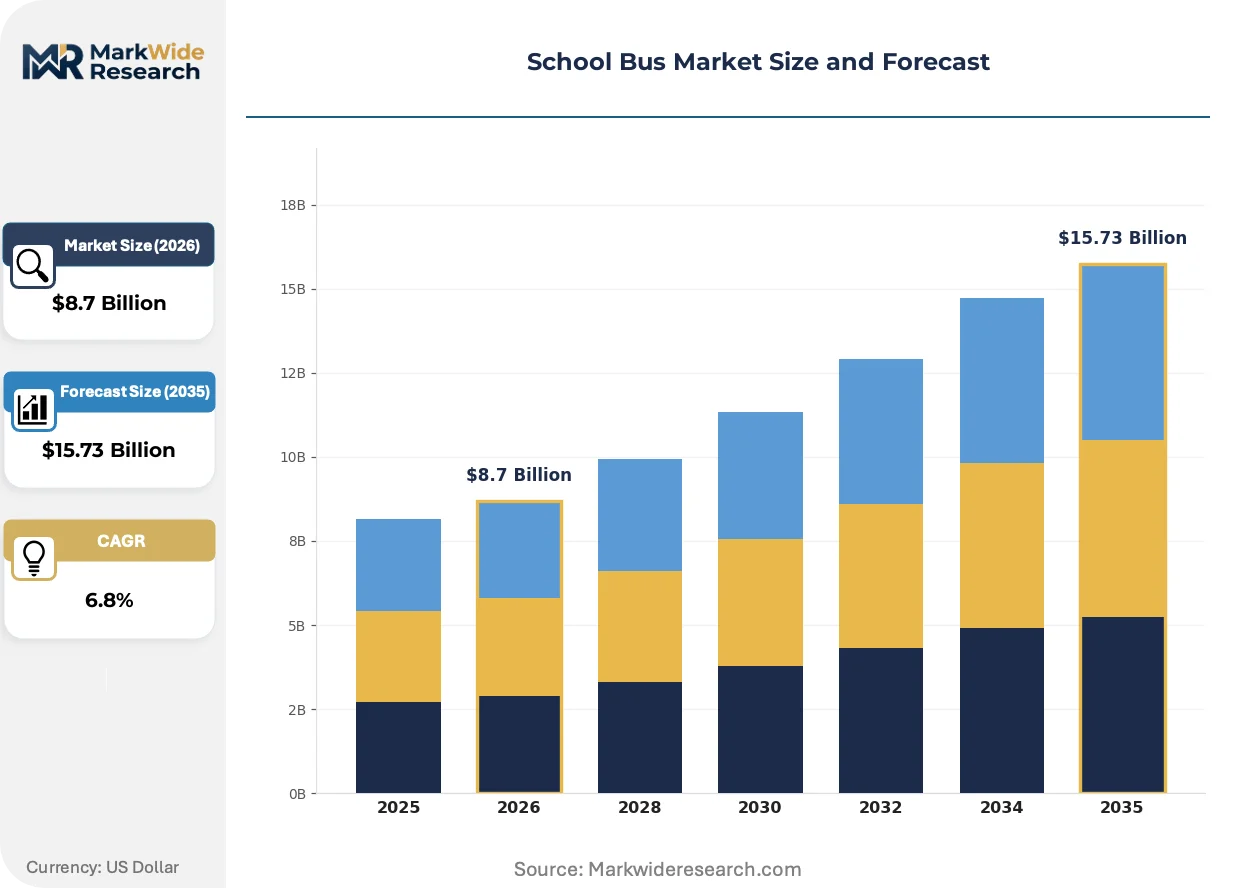
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Conventional Bus, Transit Bus, Electric Bus, CNG Bus Size: Mini Bus, Standard Bus, Large Bus, Over-Dimension Bus Fuel Type: Diesel, Gasoline, Electric, Hybrid End User: School Districts, Private Schools, Transportation Services, Government Entities |
| Companies Covered | New Flyer, Thomas Built Buses, Collins Bus Corporation, Trans Tech, GreenPower Motor Company, IC Bus, GILLIG LLC, Micro Bird, Blue Bird Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
School Bus Market Strategic Shifts
Powertrain electrification is forcing chassis redesign, battery thermal management advancement, and charging infrastructure co-development. Manufacturers and utilities are converging on integrated fleet solutions rather than discrete vehicle sales.
Lithium iron phosphate battery chemistry is rewriting range and safety parameters for electric school bus architectures. The chemistry's thermal stability eliminates cobalt supply chain exposure while delivering 150-200 mile daily range envelopes. Thomas Built Buses and Blue Bird Corporation are adopting LFP packs for their 2026-2027 model year offerings, compressing the premium versus diesel to sub-20% on upfront capital.
The Infrastructure Investment and Jobs Act is channeling dedicated funding toward zero-emission fleet conversion through 2026. Districts must obligate appropriated capital within compressed procurement windows or face clawback provisions. California and New York transportation authorities are front-loading orders to secure allocation, while Texas and Florida districts lag in application submission rates.
Leasing structures are displacing traditional municipal bond financing for electric bus acquisitions. Third-party fleet operators like Highland Electric Fleets and Zum Services are capturing route contracts with vehicle-and-charging bundled pricing. Massachusetts and Virginia school systems are piloting service-based models where operators retain residual value risk and handle utility rate negotiations.
School Bus Market Segmentation
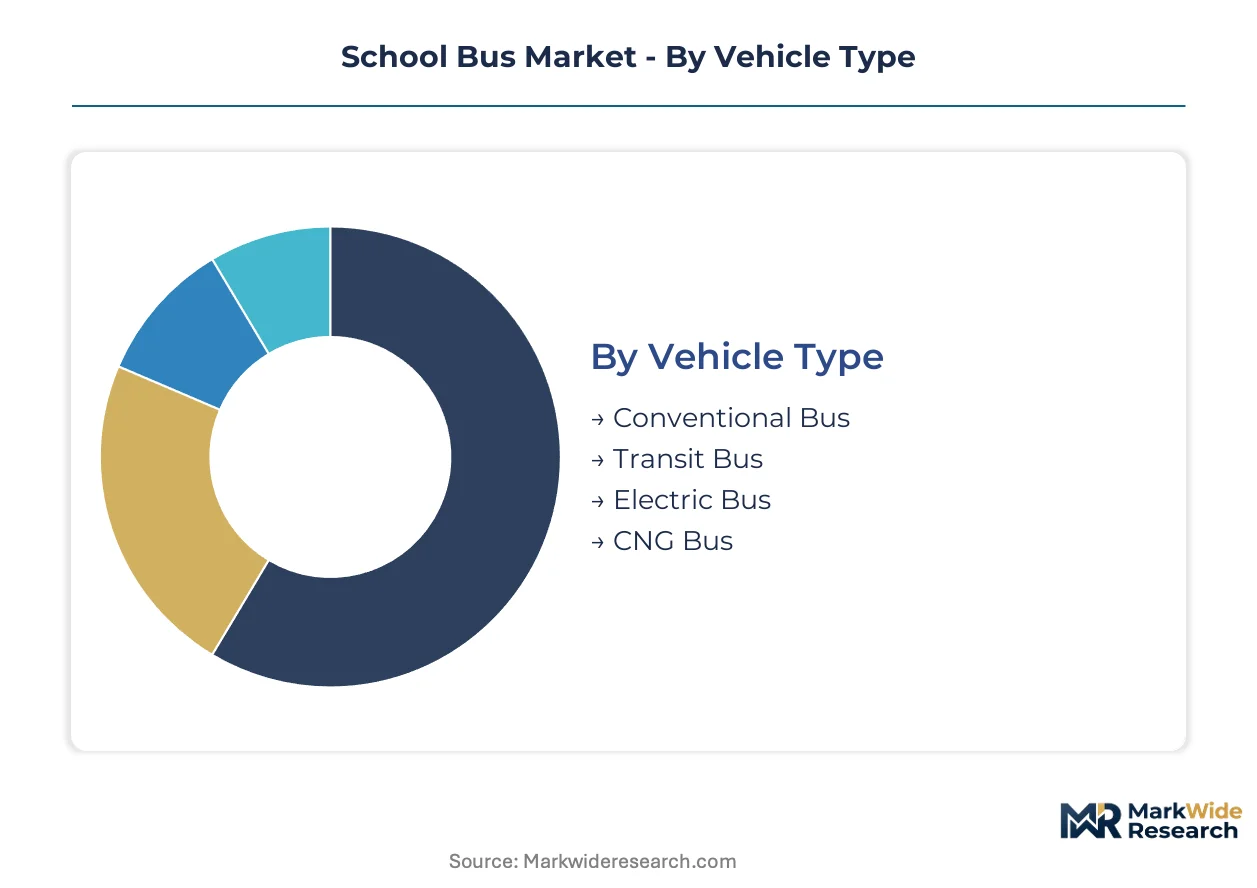
School bus procurement patterns diverge sharply across vehicle architecture, operational scale, and funding mechanisms. Districts weigh capital constraints against route requirements, while federal incentives reshape fuel-type preferences.
Vehicle Type:
Districts with established maintenance infrastructure favor hood-forward designs, while urban operators prioritize maneuverability and emissions compliance.
- Conventional Bus:Engine-forward chassis with separate hood compartment dominates rural and suburban fleets. Texas and Florida school districts maintain diesel-powered conventional units for 100+ mile daily routes where charging infrastructure remains sparse.
- Transit Bus:Flat-front, cab-over configuration maximizes passenger capacity within length restrictions. California urban districts deploy transit-style electric units for dense student populations in Los Angeles and San Francisco corridors.
- Electric Bus:Battery-electric powertrain with regenerative braking and depot charging dependency. Georgia manufacturing capacity is scaling to meet EPA Clean School Bus program obligations.
- CNG Bus:Compressed natural gas combustion with dedicated fueling infrastructure. Oklahoma and Utah districts leverage regional gas pipeline access for operational cost containment.
Conventional bus configurations lead volumes today; electric bus procurement is gaining share fastest.
Size:
Route density and student population concentration determine dimensional requirements, with margin profiles varying substantially across length categories.
- Mini Bus:14-20 passenger capacity with cutaway van chassis foundation. Montana rural districts are testing electric mini units for low-density student transport where full-size deployment is economically unjustified.
- Standard Bus:48-72 passenger capacity representing the procurement volume center. Midwestern states including Ohio and Illinois maintain standard-size diesel fleets with planned electrification transitions.
- Large Bus:72-90 passenger capacity with highest per-unit margins. High-growth suburban districts in Arizona and Nevada prioritize large-capacity units for consolidated routing efficiency.
- Over-Dimension Bus:Extended length variants exceeding standard regulatory thresholds requiring special permitting. Limited deployment in high-density northeastern corridors with waiver-granting state transportation authorities.
Standard bus dimensions anchor current fleet composition; mini bus configurations are expanding most quickly in specialized applications.
Fuel Type:
Total cost of ownership calculations now incorporate federal tax credit stacking and utility rate structures alongside traditional fuel price forecasting.
- Diesel:Compression-ignition powertrain with established supply chain and technician training infrastructure. Cold-climate districts in Minnesota and North Dakota retain diesel for thermal reliability during sub-zero operations.
- Gasoline:Spark-ignition engines in lighter-duty cutaway applications. Private school operators in southeastern states favor gasoline for lower upfront capital and simplified maintenance protocols.
- Electric:Battery-powered with zero tailpipe emissions and bidirectional charging capability. New York and California districts are capturing stacked incentives exceeding six figures per vehicle through IRA credits and state rebates.
- Hybrid:Dual powertrain combining internal combustion with electric assist. Early adoption in Pennsylvania and Massachusetts preceded full electrification transitions.
Diesel retains dominant installed base; electric powertrains show steepest expansion trajectory in new orders.
End User:
Capital access and procurement autonomy create divergent purchasing behaviors across institutional categories.
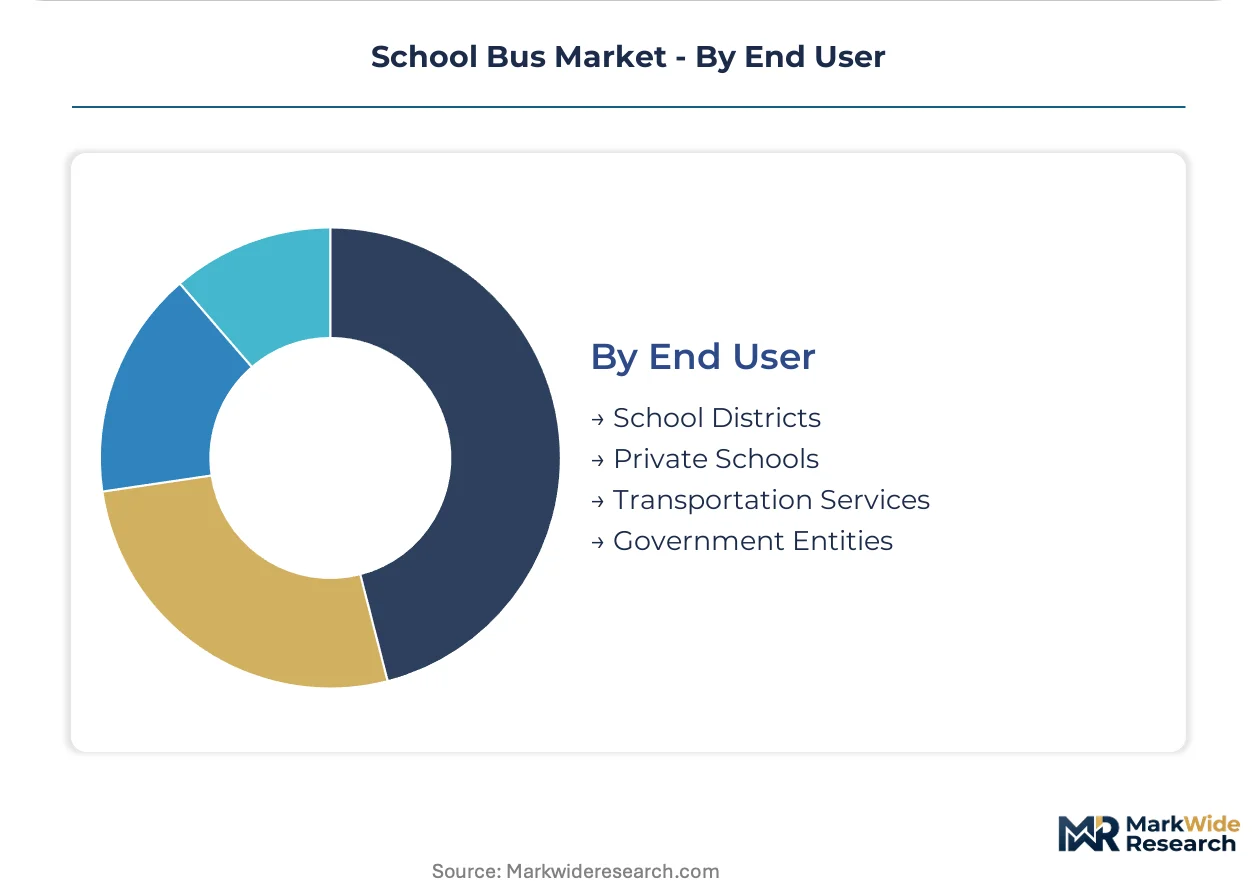
- School Districts:Public education authorities with municipal bond financing and federal grant eligibility. California's Los Angeles Unified and San Diego Unified are front-loading electric fleet commitments to secure IIJA funding windows.
- Private Schools:Independent institutions with tuition-driven capital budgets and faster procurement cycles. Texas religious academies are leasing electric units through third-party fleet operators to bypass infrastructure ownership.
- Transportation Services:Contract operators providing route service under district agreements. Massachusetts and Virginia systems are piloting service-based models where operators assume residual value risk.
- Government Entities:State and federal agencies including military base transport and tribal school systems. Department of Defense installations are electrifying student transport as component of installation energy resilience mandates.
School districts command procurement volumes; transportation services are climbing the fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Thomasville, Georgia manufacturing corridor anchors North American school bus production capacity. Federal funding mechanisms and state-level fleet mandates are redrawing procurement geography across distinct national markets. Regulatory divergence between jurisdictions is accelerating regional specialization in powertrain sourcing and charging infrastructure deployment.
United States
California Air Resources Board mandates are forcing 50% zero-emission procurement quotas by 2035 for public fleets. The EPA Clean School Bus program channels billions toward district fleet conversions with compressed obligation timelines. Georgia's manufacturing belt around Fort Valley anchors domestic electric bus assembly capacity for nationwide distribution.
Canada
Provincial climate action plans in British Columbia and Quebec are prioritizing electric school bus pilots with utility co-funding. Environment and Climate Change Canada regulations align with EPA tailpipe standards while adding cold-climate performance testing requirements. Ontario's Golden Horseshoe region concentrates fleet operator headquarters serving cross-border route contracts.
Germany
The KBA enforces EU-wide safety certifications while federal Klimaschutzgesetz mandates accelerate municipal fleet electrification timelines. Bavarian and Baden-Württemberg districts are testing bidirectional charging integration with grid stabilization services. Stuttgart's automotive engineering cluster supplies thermal management systems for electric bus architectures.
India
The Ministry of Road Transport and Highways mandates AIS-052 bus body standards while state electric vehicle policies in Delhi and Maharashtra subsidize school bus conversions. BIS certification requirements for high-voltage systems are creating compliance bottlenecks for imported powertrain components. Tamil Nadu's Chennai-Ambattur industrial corridor hosts emerging electric bus assembly joint ventures.
Brazil
ANFAVEA industry association guidelines shape procurement specifications for municipal education transport contracts. Proconve emission standards phase in gradually, preserving diesel dominance in rural routing applications. São Paulo state's industrial belt around São Bernardo do Campo concentrates chassis fabrication for Latin American export markets.
School Bus Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retool for electric powertrain assembly. The vendor base organizes around three strategic tiers: integrated commercial vehicle conglomerates with captive powertrain engineering, dedicated bus specialists with electric-first manufacturing footprints, and regional cutaway chassis assemblers serving niche capacity segments. Competitive moves concentrate on strategic partnerships with battery cell suppliers and geographic expansion through utility-aligned fleet service contracts.
Among North American specialists, Thomas Built Buses and Blue Bird Corporation exemplify the dedicated bus fabricator archetype with established electric production lines, while IC Bus occupies a position within the integrated vehicle group tier leveraging parent-company drivetrain engineering resources. GreenPower Motor Company represents the pure-play electric entrant segment focused exclusively on battery-electric architectures without legacy diesel exposure.
| Leading Market Players |
|---|
| New Flyer |
| Thomas Built Buses |
| Collins Bus Corporation |
| Trans Tech |
| GreenPower Motor Company |
| IC Bus |
| GILLIG LLC |
| Micro Bird |
| Blue Bird Corporation |
| Others |
Value Chain & Pricing Dynamics
Hot-rolled coil steel indices cascading through chassis fabrication tiers compress margin structures for conventional bus architectures while aluminum extrusion premiums in electric powertrain housings widen pricing spreads between diesel and zero-emission variants. District procurement officers face compressed total-cost-of-ownership windows where federal incentive stacking offsets upstream material volatility.
Pricing Analysis
Input-cost pass-through from battery cell suppliers and steel mills operates on quarterly adjustment clauses rather than fixed-price contracts. Three-tier pricing structure across premium electric, standard diesel, and economy gasoline configurations reflects certification grade and after-sales service bundling. Pricing pressure stems from lithium-ion cell oversupply and cobalt price deflation. Rural districts exhibit highest price sensitivity due to municipal bond financing constraints, while urban transportation authorities capture volume discounts through consolidated fleet orders.
Supply Chain Analysis
Regional distribution centers in Georgia, Indiana, and Ontario anchor hub-and-spoke delivery patterns for chassis components and fully assembled units. Manufacturing concentration rests on the United States, Canada, and Mexico under USMCA provisions. Raw material dependencies include hot-rolled steel coil, lithium iron phosphate cathode materials, and semiconductor power modules. Single-source vulnerability in battery management system chipsets from Taiwanese foundries creates procurement risk. Distribution runs through manufacturer-direct fleet sales and third-party leasing operators with bundled charging infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The school bus market functions as a stable compounder where regulatory mandates for zero-emission fleet conversion generate predictable replacement demand across extended procurement cycles.
For Market Incumbents: Hedge exposure to diesel powertrain obsolescence by accelerating in-house production of battery pack assemblies and thermal management systems. Secure long-term cathode material offtake agreements with North American lithium processors to defend margin position against supply chain volatility. Prioritize certification investment for bidirectional charging integration as utility revenue-sharing models mature. For New Entrants and Emerging Players: Enter via rural mini-bus electrification segments where incumbent coverage remains sparse and route consolidation creates white-space opportunity. Target Montana, Wyoming, and North Dakota districts with 14-passenger electric units purpose-built for low-density student transport. Pursue service-based leasing models that bundle vehicle, charging infrastructure, and utility rate negotiation to bypass district capital constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play electric bus manufacturers without legacy diesel service network overhead. Long-term viability favors asset-light fleet operators capturing route contracts with residual value retention. Monitor EPA Clean School Bus funding obligation timelines as inflection indicator for order backlog conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode material contracts with North American processors insulate against lithium price volatility. |
| Charging Infrastructure Partnership | Utility-aligned depot installations accelerate fleet electrification timelines for district customers. |
| Platform Standardization | Common battery architecture across bus sizes reduces component procurement complexity and service training costs. |
| Geographic Manufacturing Footprint | Georgia and Indiana production capacity positions suppliers for EPA funding program eligibility requirements. |
| Software-Defined Vehicle Investment | Telematics integration with student information systems enables route optimization and state-of-charge monitoring. |
Study Parameters
Bottom-up district fleet modeling reconciled against top-down manufacturer production tracking forms the analytical core of this study. Primary interviews with school district transportation directors, state procurement officers, utility fleet electrification specialists, and bus manufacturer product planners combined with secondary validation from EPA Clean School Bus program filings, NHTSA safety certification databases, state transportation authority budget documents, and utility rebate program disclosures. Triangulation across these sources ensures demand-side estimates align with supply-side capacity announcements.
Historical trendline analysis of replacement cycle compression and incentive program uptake patterns informed projection frameworks across the analysis window. Segmentation modeling incorporated vehicle architecture, passenger capacity tier, fuel type transition pathways, and regional regulatory cluster dimensions. CAGRs were derived from unit shipment trajectories and average selling price evolution. Forecast inputs included battery cost curve assumptions, utility interconnection queue durations, and technician training program graduation rates.
Inputs from EPA program administrators and state transportation authorities were available through the study window; gaps in rural district procurement intention surveys introduce uncertainty bands around mini-bus adoption forecasts. Forecasts reflect assumptions regarding federal funding continuity and battery chemistry cost reduction. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Buses & Coaches Market
Buses
Intercity Bus Travel Market
Buses
Bus Rental Market
Buses
Canada School Bus Market
Buses
Fuel Cell Electric Bus Market
Buses
Bus Chassis Market
Buses
Intelligent Bus Shelter Market
Buses
City Bus Low-Floor Axle Systems Market
Buses
Bus Flooring Market
Buses
Luxury Coaches Market
Buses
Bus Charter Services Market
Buses
Europe Bus Market
Buses
United States School Bus Market
Buses
Global Bus Market
Buses
Hydrogen CNG Bus Market
Buses
Global Luxury Shuttle Bus Market