
 Fuel Cell Electric Bus Market | 2026-2036
Fuel Cell Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Electric Bus Market Foresight
Solid-state power module integration is rewriting bus platform architecture, collapsing auxiliary component count while extending drivetrain service intervals. Ballard Power Systems anchors North American supply through its fuel cell stack manufacturing scale and transit authority partnerships. Yutong Bus Co., Ltd. dominates Chinese deployment volumes with integrated hydrogen storage and vehicle control systems. Solaris Bus & Coach competes across European tenders with modular platform designs that adapt to varying route duty cycles.
A fuel cell electric bus converts hydrogen into electricity through an electrochemical reaction, typically using proton exchange membrane stacks rated between 60 kW and 120 kW to power electric traction motors with water vapor as the sole emission. City bus configurations lead procurement volumes due to predictable depot return patterns that simplify refueling logistics and hydrogen supply contracting. Proton exchange membrane technology occupies the dominant share of installed capacity given its cold-start capability and power density suited to stop-and-go duty cycles. Public transit applications generate the largest revenue pool as municipal authorities bundle fleet conversions with long-term operating concessions.
The EPA tailpipe standards and California Air Resources Board zero-emission bus mandates shape North American product certification timelines and fleet replacement schedules. Europe's F-Gas Regulation and EU Green Deal hydrogen bank mechanisms alter total cost of ownership calculations for cross-border operators. China's MIIT new energy vehicle catalog and GB standards dictate domestic stack efficiency thresholds and safety testing protocols. Stakeholders must monitor hydrogen production source certification requirements, as carbon intensity thresholds for green hydrogen claims are tightening faster than refueling infrastructure deployment in several key corridors.
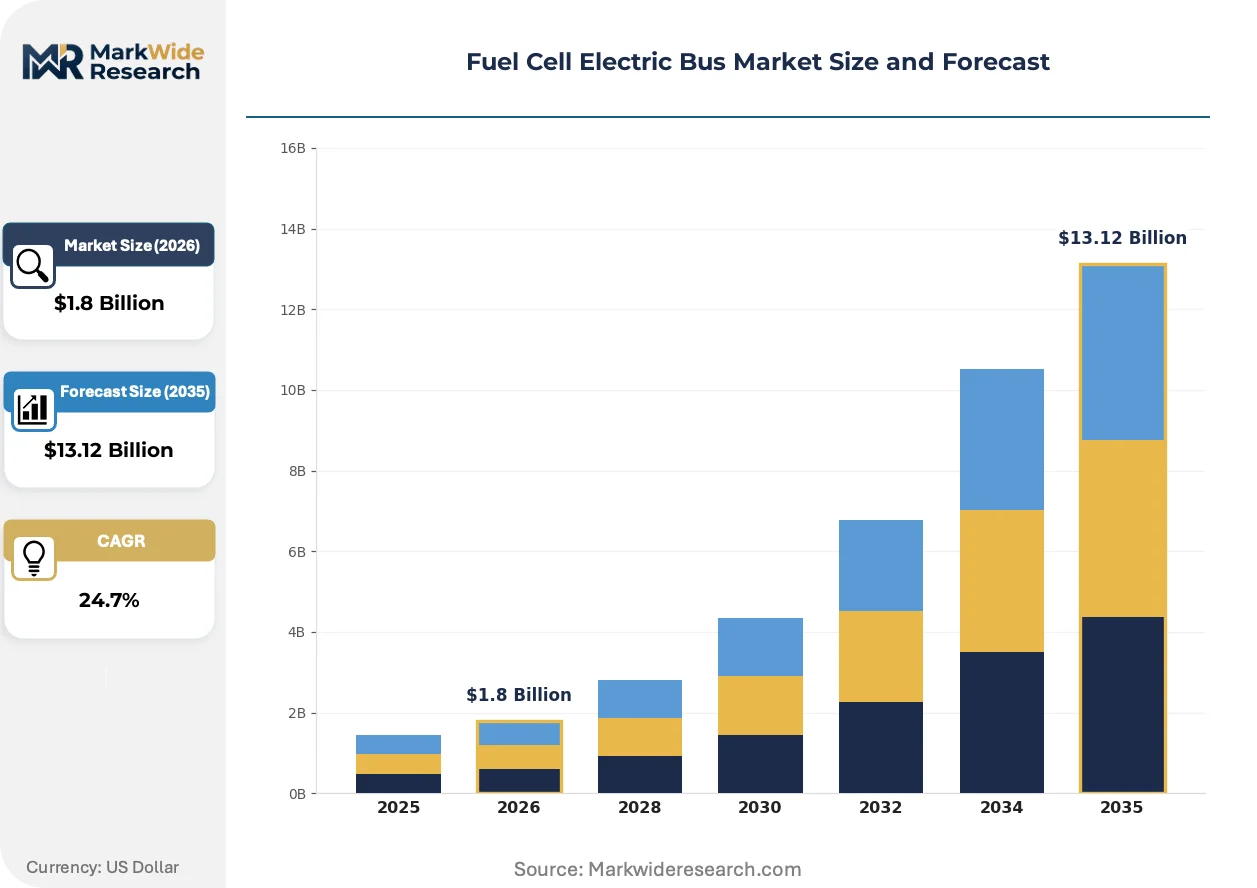
Market Dynamics
Solid-state power module integration is collapsing auxiliary component counts across bus platforms while proton exchange membrane stack efficiency gains compress total cost of ownership calculations for fleet operators.
Growth Catalysts
- California Air Resources Board zero-emission bus mandates:These binding fleet replacement schedules force municipal transit authorities to accelerate procurement timelines and lock in long-term hydrogen supply contracts.
- Depot-based electrolysis infrastructure:Urban corridor deployments with captive hydrogen production eliminate supply uncertainty and enable predictable refueling logistics for high-frequency route operations.
- EU Green Deal hydrogen bank mechanisms:Cross-border operators gain access to subsidized green hydrogen offtake agreements that reshape total cost of ownership models across European tender processes.
Market Restraints
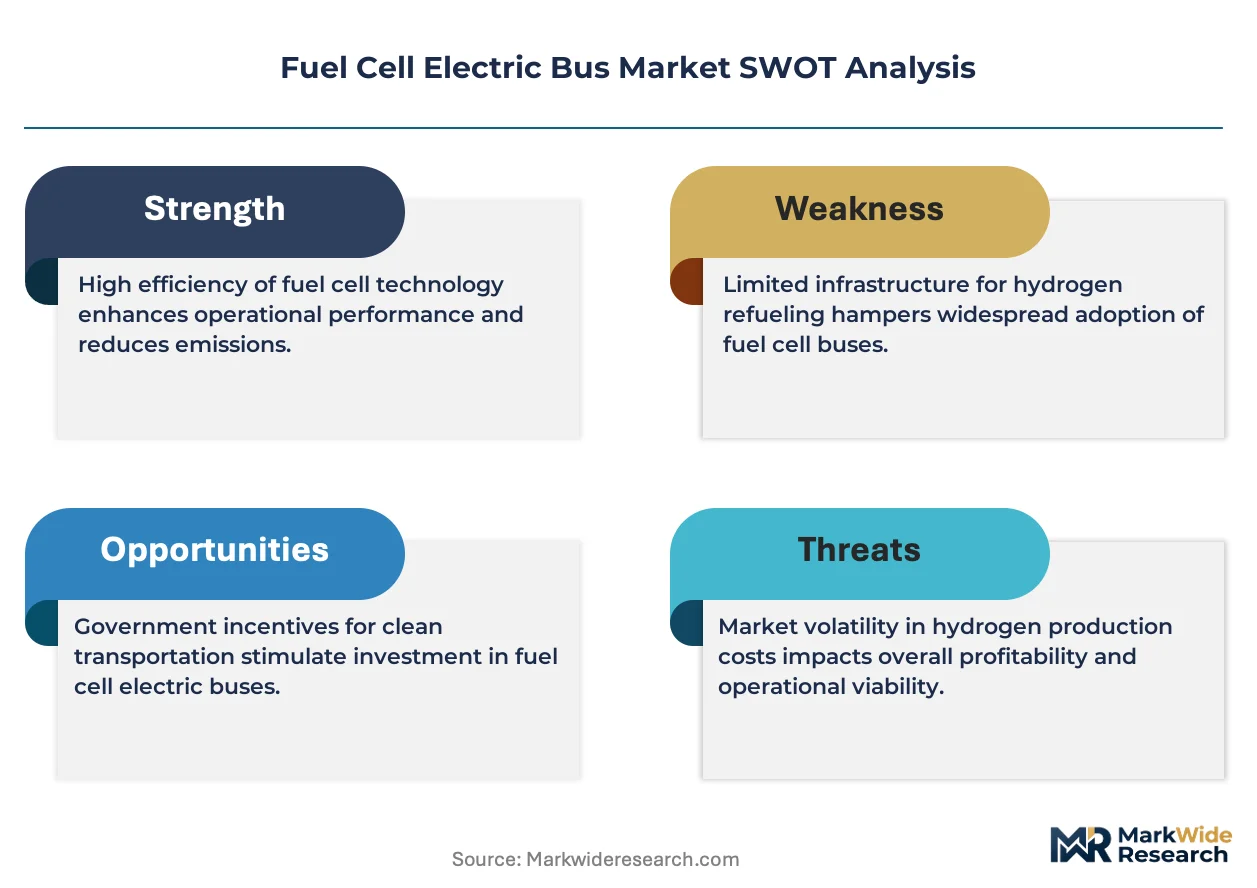
- Platinum group metal cost volatility:Fuel cell stack manufacturing remains exposed to palladium and platinum price swings that propagate directly into module pricing.
- Electrolyzer manufacturing concentration:Proton exchange membrane electrolyzer supply chains cluster in specific manufacturing regions, creating single-source vulnerability for depot-based hydrogen production.
- Cold-start performance limitations:Sub-zero temperature operation degrades stack efficiency and extends startup intervals, constraining deployment in high-latitude municipalities.
Strategic Opportunities
- Intercity coach electrification:Long-haul corridor applications with scheduled depot returns represent underpenetrated white space beyond urban duty cycles.
- MIIT new energy vehicle catalog expansion:China's domestic efficiency threshold adjustments create regulatory tailwinds for higher-power stack configurations in heavy-duty transit.
- Vehicle-to-grid integration:Bidirectional power electronics convergence with stationary fuel cell systems enables fleet operators to monetize grid services during idle periods.
Industry Challenges
- High-voltage safety certification timelines:GB standards compliance testing for integrated hydrogen storage systems extends product launch schedules by 12-18 months.
- Electrochemical engineering talent scarcity:Stack design and membrane electrode assembly process optimization require specialized expertise that outpaces vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Electric Bus Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.12 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: City Bus, Shuttle Bus, Double-Decker Bus, Coach Bus Fuel Cell Technology: Proton Exchange Membrane, Solid Oxide, Alkaline, Phosphoric Acid Application: Public Transit, Airport Transport, Campus Shuttle, Tourist Transport End User: Municipal Transport Authorities, Transit Operators, Private Fleet Owners, Leasing Companies |
| Companies Covered | Ballard Power Systems, New Flyer Industries, Hyundai Motor Company, Toyota Motor Corporation, Van Hool NV, Solaris Bus & Coach, Yutong Bus Co., Ltd., Wrightbus, CaetanoBus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Electric Bus Market Shifts & Advancements
Digital twin architectures and predictive maintenance algorithms are redefining fleet uptime guarantees while compressing service interval expectations across transit authority tender specifications.
Integrated vehicle control systems with real-time stack health monitoring is digitizing maintenance scheduling for municipal operators. Transit authorities in Germany and California are mandating these capabilities in new procurements. The technology is digitizing warranty structures and shifting risk allocation toward suppliers through uptime-based service contracts.
EPA tailpipe standards are tightening nitrogen oxide and particulate thresholds for heavy-duty vehicles, forcing stack manufacturers to optimize cathode air filtration systems. The industrial consequence is a surge in membrane electrode assembly redesign cycles. Urban bus configurations face the steepest compliance ramps and are responding with accelerated validation testing protocols.
Total cost of ownership contracting is displacing capital purchase models in European and North American fleet renewals. Municipal authorities now bundle vehicle supply with hydrogen fuel and maintenance under single-source agreements. This shift is most visible in German and Dutch tender processes where 10-15 year operating concessions dominate procurement structures.
Fuel Cell Electric Bus Market Segmentation
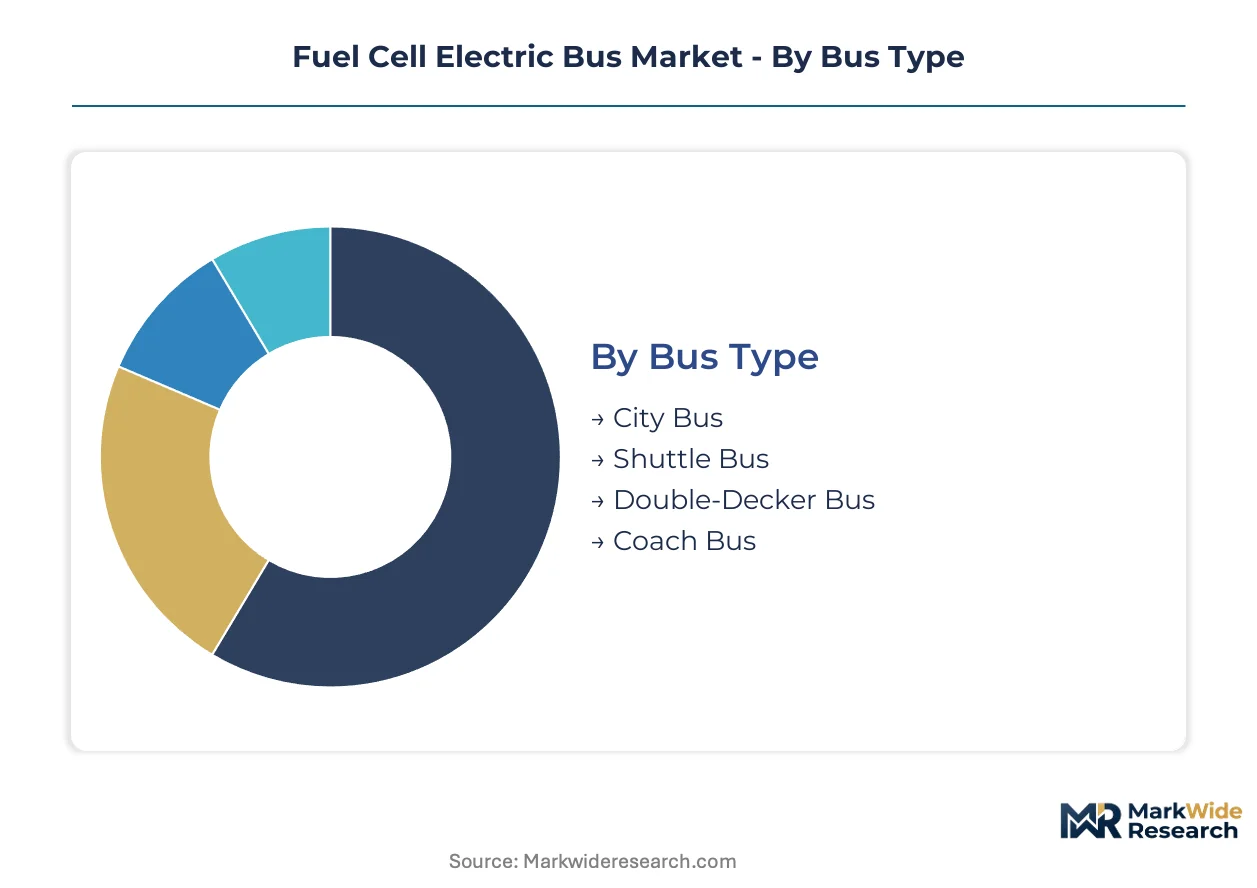
Bus configuration and fuel cell chemistry choices determine refueling infrastructure requirements, warranty structures, and total cost of ownership calculations for fleet operators. Procurement patterns diverge sharply between depot-return urban routes and extended corridor applications.
Bus Type:
Route duty cycle and passenger volume requirements shape chassis selection and hydrogen storage integration strategies.
- City Bus:Single-deck configurations with 60-120 kW proton exchange membrane stacks dominate procurement volumes. Municipal transport authorities in Germany and California favor these for predictable depot return patterns that simplify hydrogen supply contracting and overnight refueling logistics.
- Coach Bus:Long-haul intercity platforms with extended range hydrogen storage systems serve corridor routes between metropolitan clusters. European cross-border operators are piloting these for scheduled depot returns on 300-500 kilometer segments where battery electric range falls short.
- Shuttle Bus:Compact 8-12 meter platforms serve airport and campus circuits with reduced hydrogen capacity.
- Double-Decker Bus:High-capacity urban configurations face roof-mounted hydrogen tank packaging constraints that limit deployment to specific route profiles.
City bus configurations command the established base. The steepest expansion runs through coach bus deployments.
Fuel Cell Technology:
Stack chemistry selection trades off cold-start performance, power density, and platinum group metal loading against route-specific operational requirements.
- Proton Exchange Membrane:Low-temperature operation at 60-80°C enables rapid cold starts and high power density for stop-and-go duty cycles. California Air Resources Board zero-emission mandates and Chinese MIIT catalog requirements have cemented this technology's dominance across municipal procurement specifications.
- Solid Oxide:High-temperature ceramic electrolyte systems achieve superior electrical efficiency but require extended warm-up intervals. Japanese transit pilots are testing these for fixed-route applications where daily duty cycles allow thermal management optimization.
- Alkaline:Liquid electrolyte configurations reduce platinum loading but face system complexity barriers in mobile applications.
- Phosphoric Acid:Mature stationary technology with limited bus platform integration due to size and thermal management constraints.
Proton exchange membrane stacks anchor current deployment volumes. Solid oxide systems are climbing the fastest in pilot fleet evaluations.
Application:
Passenger flow predictability and route scheduling rigidity determine fleet conversion economics and hydrogen supply contract structures.
- Public Transit:High-frequency urban corridors with dedicated depot infrastructure generate the largest revenue pool. German municipal authorities bundle 10-15 year operating concessions with vehicle supply, shifting total cost of ownership risk to suppliers through uptime-based service contracts.
- Airport Transport:Captive fleet operations with centralized hydrogen production enable closed-loop supply economics. California airport authorities are mandating zero-emission conversions for ground transport fleets under EPA regional air quality commitments.
- Campus Shuttle:Controlled environments with limited route variability suit early deployment of emerging stack technologies.
- Tourist Transport:Seasonal demand patterns and scenic route requirements create niche specifications for extended range configurations.
Public transit commands the established base. Airport transport is gaining share fastest through regulatory mandates.
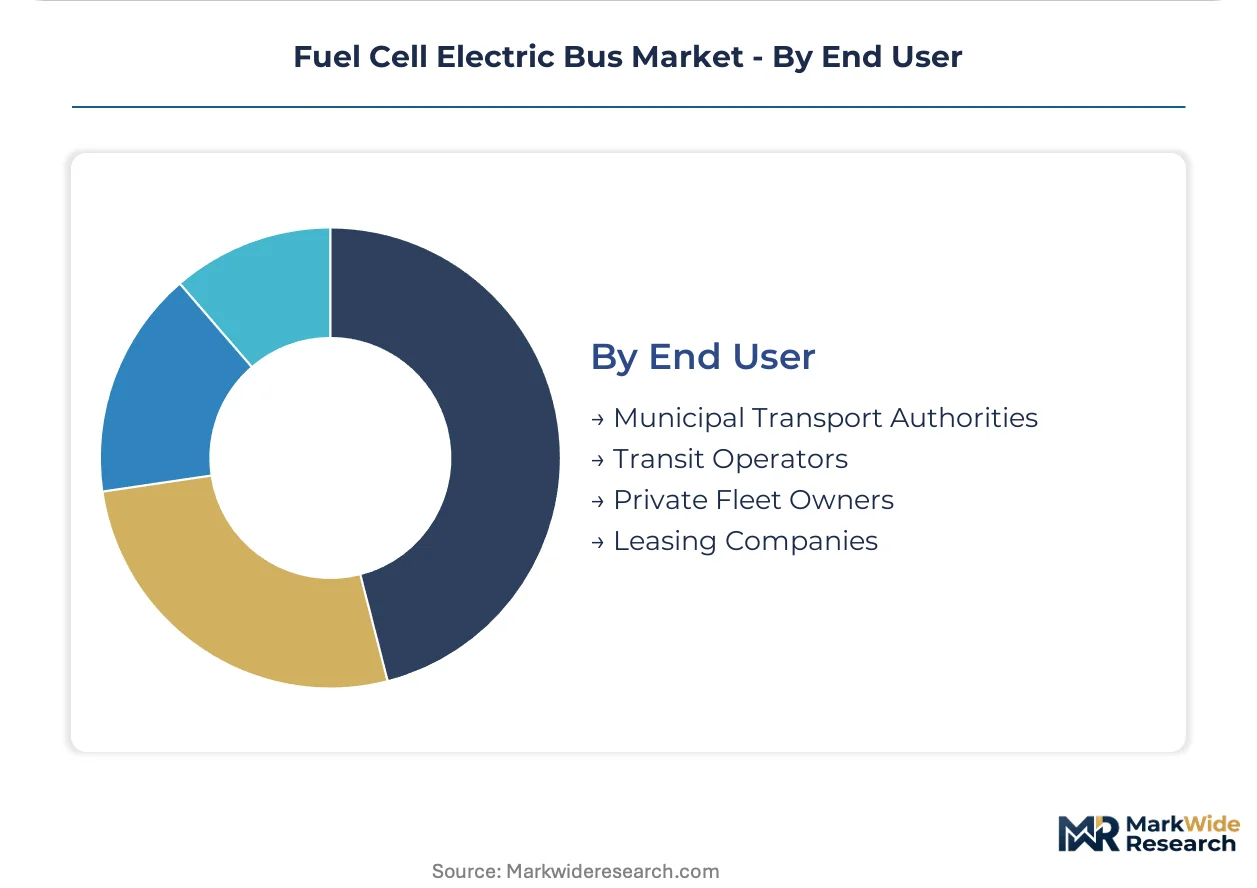
End User:
Procurement authority and balance sheet capacity determine contracting structures and technology risk allocation.
- Municipal Transport Authorities:Public sector entities with long-term capital planning horizons and regulatory compliance mandates drive volume procurement. These stakeholders in the Netherlands and California are standardizing total cost of ownership contracting that bundles vehicles, hydrogen fuel, and maintenance under single-source agreements.
- Transit Operators:Private concessionaires with operating contracts prioritize asset utilization and uptime guarantees. German and French operators are demanding real-time stack health monitoring and predictive maintenance capabilities in tender specifications.
- Private Fleet Owners:Corporate and institutional buyers with captive route requirements represent emerging demand outside traditional public transit structures.
- Leasing Companies:Financial intermediaries developing residual value models for hydrogen vehicle assets face technology obsolescence risk pricing challenges.
Municipal transport authorities command the established base. Transit operators are expanding most quickly through concession restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German stack manufacturers export proton exchange membrane systems to Dutch and Danish transit authorities under EU Green Deal hydrogen bank mechanisms. Chinese bus integrators ship complete vehicles to Southeast Asian municipal fleets through MIIT catalog certification pathways. California-based electrolyzer suppliers feed hydrogen production equipment into depot-based installations across the United States.
United States
California transit authorities drive procurement volumes through CARB zero-emission bus mandates with binding fleet replacement schedules. EPA tailpipe standards tighten nitrogen oxide thresholds for heavy-duty vehicles, forcing accelerated validation testing protocols. Los Angeles Metro and San Francisco MUNI anchor West Coast deployment clusters with 10-15 year operating concessions bundling vehicles and hydrogen supply.
Germany
Municipal transport authorities in North Rhine-Westphalia and Bavaria scale zero-emission commitments through F-Gas Regulation compliance frameworks. EU Green Deal hydrogen bank mechanisms subsidize green hydrogen offtake agreements that reshape tender economics. Cologne and Hamburg transit operators mandate real-time stack health monitoring and predictive maintenance capabilities in procurement specifications.
China
MIIT new energy vehicle catalog expansion creates regulatory tailwinds for higher-power stack configurations in heavy-duty transit applications. GB standards dictate domestic stack efficiency thresholds and safety testing protocols for integrated hydrogen storage systems. Zhengzhou and Beijing anchor manufacturing clusters where Yutong Bus Co., Ltd. dominates deployment volumes with integrated vehicle control systems.
Netherlands
Cross-border operators gain access to subsidized hydrogen infrastructure through EU Green Deal mechanisms that alter total cost of ownership calculations. Dutch tender processes standardize total cost of ownership contracting that bundles vehicles, fuel, and maintenance under single-source agreements. Rotterdam and Amsterdam municipal authorities lead procurement with 10-15 year operating concessions shifting risk to suppliers.
Japan
METI hydrogen roadmap commitments accelerate depot-based electrolysis infrastructure buildouts for fixed-route applications. Japanese transit pilots test solid oxide fuel cell systems where daily duty cycles allow thermal management optimization. Tokyo and Osaka metropolitan clusters concentrate demonstration fleets with scheduled depot returns enabling captive hydrogen production economics.
Fuel Cell Electric Bus Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement structures that favor bundled service contracts over discrete component sales. The vendor base organizes around three archetypes: integrated bus manufacturers with captive stack supply, independent fuel cell stack specialists, and hydrogen infrastructure operators securing vehicle offtake agreements. Tiered competitive dynamics separate premium-tier suppliers with full-system integration capabilities from mid-tier assemblers relying on outsourced membrane electrode assemblies. Dominant competitive moves include strategic partnerships between bus OEMs and electrolyzer suppliers, plus geographic expansion through joint venture manufacturing in target municipal markets.
Within the integrated manufacturer tier, Yutong Bus Co., Ltd. and Solaris Bus & Coach exemplify platform-scale competitors with modular designs adapting to varying route duty cycles. Ballard Power Systems anchors the independent stack specialist position. These three companies occupy distinct strategic positions: Chinese volume leadership, European tender adaptability, and North American supply chain anchoring respectively.
| Leading Market Players |
|---|
| Ballard Power Systems |
| New Flyer Industries |
| Hyundai Motor Company |
| Toyota Motor Corporation |
| Van Hool NV |
| Solaris Bus & Coach |
| Yutong Bus Co., Ltd. |
| Wrightbus |
| CaetanoBus |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese electrolyzer manufacturing is compressing module margins and forcing stack suppliers toward long-term offtake contracting to lock in volume commitments. This utilization dynamic simultaneously pressures pricing structures downstream and accelerates geographic diversification in procurement strategies.
Pricing Analysis
Next-generation solid-state power module configurations command substantial premiums over incumbent proton exchange membrane stacks, while prior-generation alkaline systems trade at distressed levels in secondary markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier differentiation under CARB and MIIT protocols, with volume scale discounts reshaping municipal tender economics. Cost compression in standard-tier stacks is intensifying because platinum group metal loading reductions are propagating through membrane electrode assembly redesigns. Private fleet owners exhibit the highest price sensitivity, whereas German municipal transport authorities prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for proton exchange membrane stack sourcing, forcing North American integrators toward Korean and Japanese alternative suppliers. Manufacturing gravity centers on China for electrolyzer production, South Korea for membrane electrode assemblies, and Germany for balance-of-plant components. Raw material dependencies rest on palladium and platinum catalysts, perfluorinated ionomer membranes, and carbon fiber hydrogen storage vessels. Single-source vulnerability concentrates in proton exchange membrane electrolyzer supply chains. Distribution runs through transit authority procurement consortia and OEM direct sales channels with embedded service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fuel cell electric bus market sits in early-cycle expansion, with California CARB mandates and EU Green Deal hydrogen bank mechanisms accelerating fleet conversion timelines beyond infrastructure deployment curves.
For Market Incumbents: Insulate stack manufacturing margins through backward integration into membrane electrode assembly production and captive platinum group metal recycling capabilities. Battery electric bus cost parity improvements in urban duty cycles represent a substitute technology threat requiring differentiated intercity range positioning. Certification investment in GB standards compliance testing extends product launch schedules but locks out mid-tier competitors from Chinese municipal tenders. For New Entrants and Emerging Players: Build out airport transport fleet conversions as the most penetrable white space, where captive hydrogen production economics and EPA regional air quality commitments compress procurement cycles. Campus shuttle applications with controlled route variability offer lower technical barriers for emerging solid oxide stack configurations. Partner with depot-based electrolyzer suppliers to bundle vehicle supply with hydrogen production infrastructure in single-source agreements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated vehicle control system development, as real-time stack health monitoring and predictive maintenance capabilities become tender requirements. Five-to-ten-year viability hinges on green hydrogen production cost trajectories and carbon intensity certification standardization. Acquisition target archetypes include independent fuel cell stack specialists with MIIT catalog positioning and electrolyzer OEMs with captive hydrogen offtake agreements. Monitor hydrogen production source certification threshold tightening as the critical inflection signal for asset valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Depot-Based Electrolyzer Partnership | Captive hydrogen production eliminates supply uncertainty for municipal operators in California and Germany. |
| Real-Time Stack Health Monitoring Integration | Digital twin architectures satisfy Cologne and Hamburg transit authority tender specifications for predictive maintenance. |
| MIIT Catalog Certification Investment | GB standards compliance testing locks in access to Chinese municipal procurement volumes dominated by Yutong. |
| Green Hydrogen Offtake Agreement Structuring | EU Green Deal hydrogen bank mechanisms reshape total cost of ownership calculations for Dutch and German operators. |
| Intercity Coach Platform Development | Extended range configurations address 300-500 kilometer corridor segments where battery electric range falls short. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with transit authority procurement directors, fuel cell stack engineering leads, hydrogen infrastructure project developers, and municipal fleet operations managers; and secondary validation through MIIT new energy vehicle catalog filings, CARB zero-emission bus mandate compliance reports, EU Green Deal hydrogen bank mechanism disclosures, and customs trade data on electrolyzer equipment flows. Bottom-up fleet deployment tracking and top-down regulatory mandate sizing were triangulated to constrain volume estimates.
Forecast inputs span bus configuration segmentation by route duty cycle, fuel cell technology chemistry selection, application type by passenger flow predictability, and end-user procurement authority structure across municipal transport authorities, transit operators, private fleet owners, and leasing companies. CAGRs were derived from regression analysis against regulatory mandate timelines and hydrogen infrastructure buildout schedules. Industry-specific forecast inputs include platinum group metal price trajectory assumptions and electrolyzer manufacturing capacity utilization rates.
Stress conditions across hydrogen production cost inflation, platinum group metal supply disruption, and cold-start performance degradation in sub-zero climates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and green hydrogen certification threshold evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Buses
Bus Chassis Market
Buses
School Bus Market
Buses
Bus Transmission System Market
Buses
Intercity Bus Travel Market
Buses
Global Luxury Shuttle Bus Market
Buses
Africa Electric Bus Market
Buses
Bus Rental Market
Buses
Buses & Coaches Market
Buses
Intelligent Bus Shelter Market
Buses
Airport Bus Market
Buses
United States Electric Bus Market
Buses
Airport Shuttle Bus Market
Buses
Luxury Coaches Market
Buses
Bus Rapid Transit System (BRT) Market
Buses
Hydrogen CNG Bus Market
Buses
Europe Bus Market