
 Pleurodynia Treatment Market | 2026-2036
Pleurodynia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pleurodynia Treatment Market Analysis
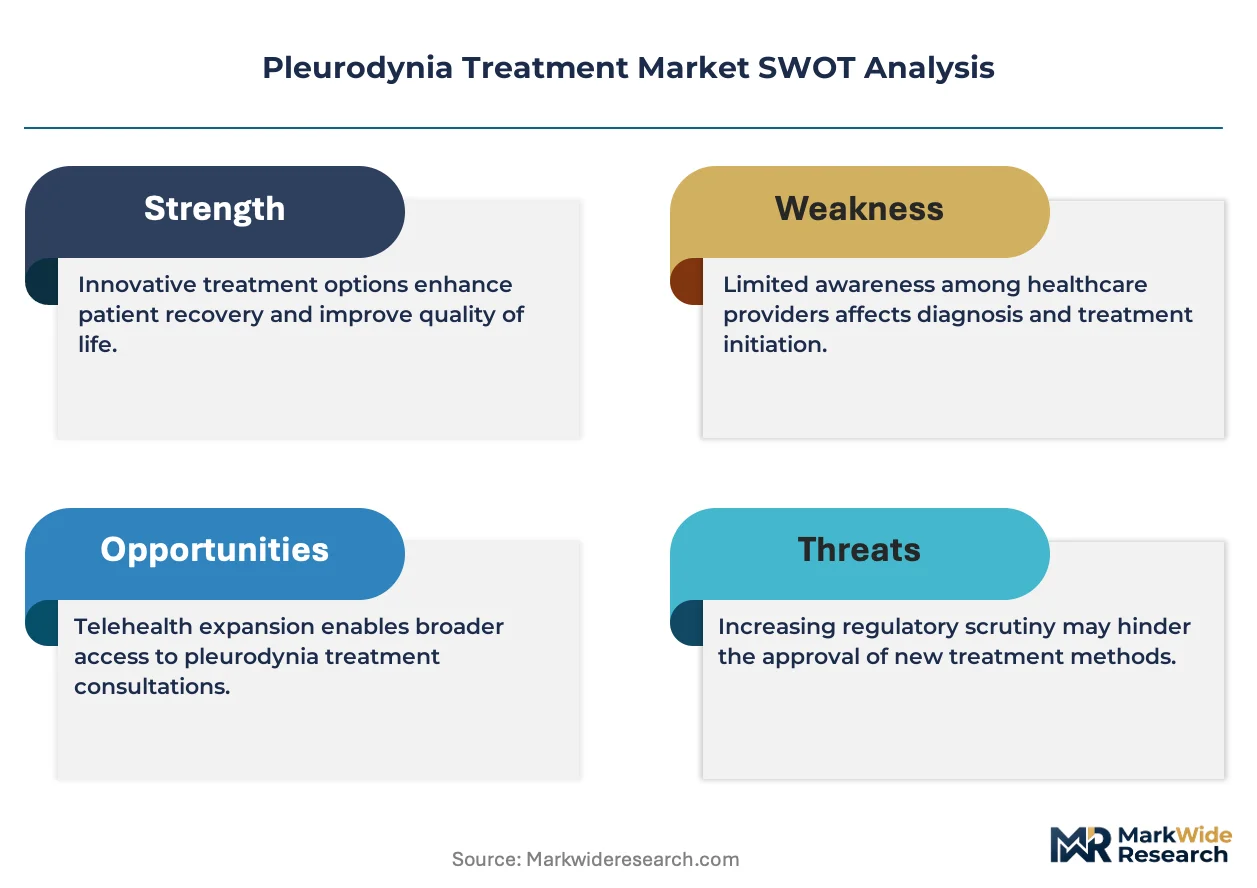
Acetaminophen is repositioning aspirin as the first-line analgesic for pediatric pleurodynia cases, reducing Reye syndrome risk and reshaping procurement economics across acute care networks. Pfizer Inc. leverages its antiviral manufacturing scale to supply ribavirin formulations for severe enterovirus presentations. Johnson & Johnson sustains broad retail distribution of analgesic portfolios that capture outpatient pleurodynia episodes. Roche Holding AG anchors its position through diagnostic-therapeutic bundling that links enterovirus PCR testing to treatment protocols.
Pleurodynia treatment encompasses pharmacological and supportive interventions targeting acute coxsackievirus B-induced intercostal myalgia, with therapy selection hinging on patient age, symptom severity, and comorbidity profile. The primary purpose centers on pain mitigation, fever reduction, and rare prevention of pericardial or myocardial complications in susceptible populations. Analgesics and antivirals command the largest revenue pools within product type segmentation, reflecting their frontline use in both hospital and homecare settings. Oral delivery dominates volume flows due to outpatient management preference, while intravenous routes capture premium positioning in pediatric intensive care. Combined therapy approaches are gaining fastest traction as clinicians integrate pharmacological pain control with non-pharmacological respiratory physiotherapy.
FDA orphan drug incentives and accelerated approval pathways shape antiviral development timelines for enterovirus-targeted therapies, while EMA pediatric investigation plans mandate age-appropriate formulation studies across European markets. WHO essential medicines criteria indirectly influence national reimbursement decisions for analgesic and antiviral access in lower-resource settings. Stakeholders must monitor evolving enterovirus surveillance data and regulatory exclusivity windows to calibrate pipeline investments against shifting epidemiological patterns.
Market Dynamics
FDA orphan drug incentives are compressing antiviral development timelines for enterovirus-targeted therapies while pediatric infectious disease networks concentrate acute care demand in coxsackievirus surveillance corridors.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy designation shortens clinical trial phases for severe enterovirus antivirals, pulling development investment toward pleurodynia indications.
- Pediatric Formulary Expansion:Hospital pharmacy committees are adding acetaminophen-ribavirin combination protocols to acute care order sets, standardizing multimodal pain management.
- Diagnostic-Therapeutic Bundling:PCR testing integration with treatment algorithms creates capture value for integrated health systems managing coxsackievirus outbreaks.
Market Restraints
- API Supply Concentration:Ribavirin active pharmaceutical ingredient production clusters in Chinese chemical manufacturing zones, exposing formulators to export license volatility.
- Reimbursement Compression:Medicaid pediatric fee schedules cap analgesic dispensing margins, constraining retail pharmacy participation in outpatient pleurodynia episodes.
- Clinical Trial Recruitment:Seasonal coxsackievirus epidemiology creates enrollment windows that extend antiviral development timelines beyond typical infectious disease programs.
Strategic Opportunities
- Homecare Infusion Services:Pediatric home health agencies are building intravenous analgesic administration capabilities, capturing step-down patients from PICU settings.
- WHO Essential Medicines Alignment:National procurement tenders in lower-resource settings reference WHO analgesic criteria, opening volume contracts for acetaminophen suppliers.
- Respiratory Physiotherapy Integration:Combined pharmacological-non-pharmacotherapy protocols create service line expansion potential for rehabilitation networks.
Industry Challenges
- Pediatric Pharmacokinetic Expertise:Formulation scientists with age-appropriate dosing specialization remain scarce relative to antiviral pipeline demands.
- Multi-Site Protocol Harmonization:Coxsackievirus surveillance networks span state health departments with incompatible data standards, complicating real-world evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pleurodynia Treatment Market |
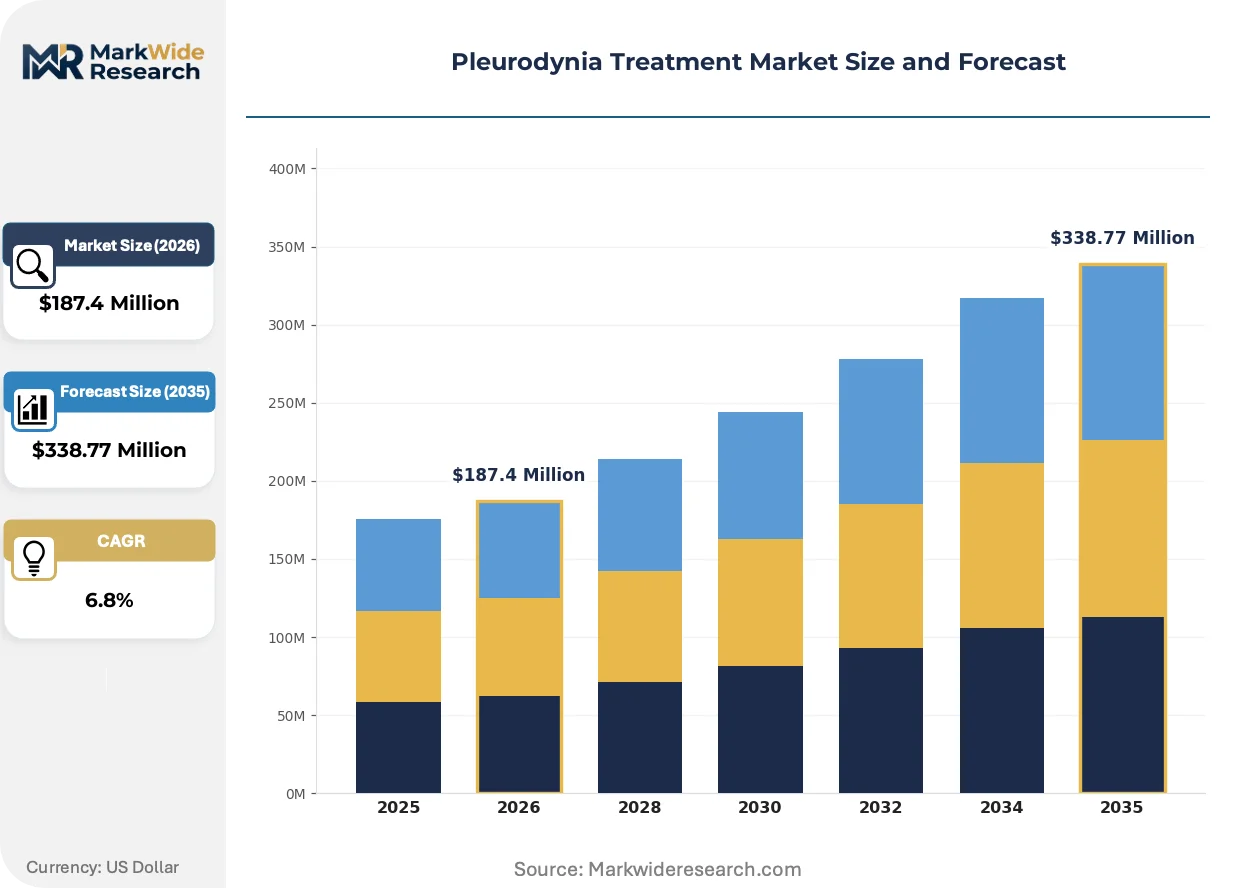
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antivirals, Corticosteroids, Muscle Relaxants Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Treatment Approach: Pharmacological, Non-Pharmacological, Alternative Medicine, Combined Therapy |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Roche Holding AG, Merck & Co., Novartis AG, GlaxoSmithKline, Sanofi SA, Abbott Laboratories, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pleurodynia Treatment Market Emerging Trajectories
Multimodal pain protocols are displacing single-agent analgesia in pediatric emergency departments, while regulatory data requirements for antiviral pediatric indications intensify formulation science investment.
Enterovirus PCR diagnostics is expanding into point-of-care platforms, compressing time-to-treatment initiation from days to hours. Pediatric emergency departments in coxsackievirus-endemic regions are adopting cartridge-based systems that integrate with electronic health record order sets. This velocity shift is expanding into triage protocols that trigger preemptive analgesic administration before laboratory confirmation.
EMA pediatric investigation plans mandate age-appropriate formulation studies for all novel antivirals with pleurodynia indications, extending development timelines by 18-24 months. European sponsors must submit pediatric study plans at end-of-phase II, forcing parallel rather than sequential adult-pediatric program design. This regulatory architecture most affects biotechnology developers without existing pediatric infrastructure, driving partnership demand with specialized contract research organizations.
Hospital procurement committees are consolidating analgesic contracts under system-wide pharmaceutical benefits managers, displacing individual facility formulary autonomy. Integrated delivery networks in the United States are negotiating multi-year acetaminophen and ibuprofen supply agreements that bundle pediatric and adult dosages. This concentration is most visible in states with dominant regional health systems, where three-to-five-year contracts lock out competing suppliers.
Pleurodynia Treatment Market Segmentation
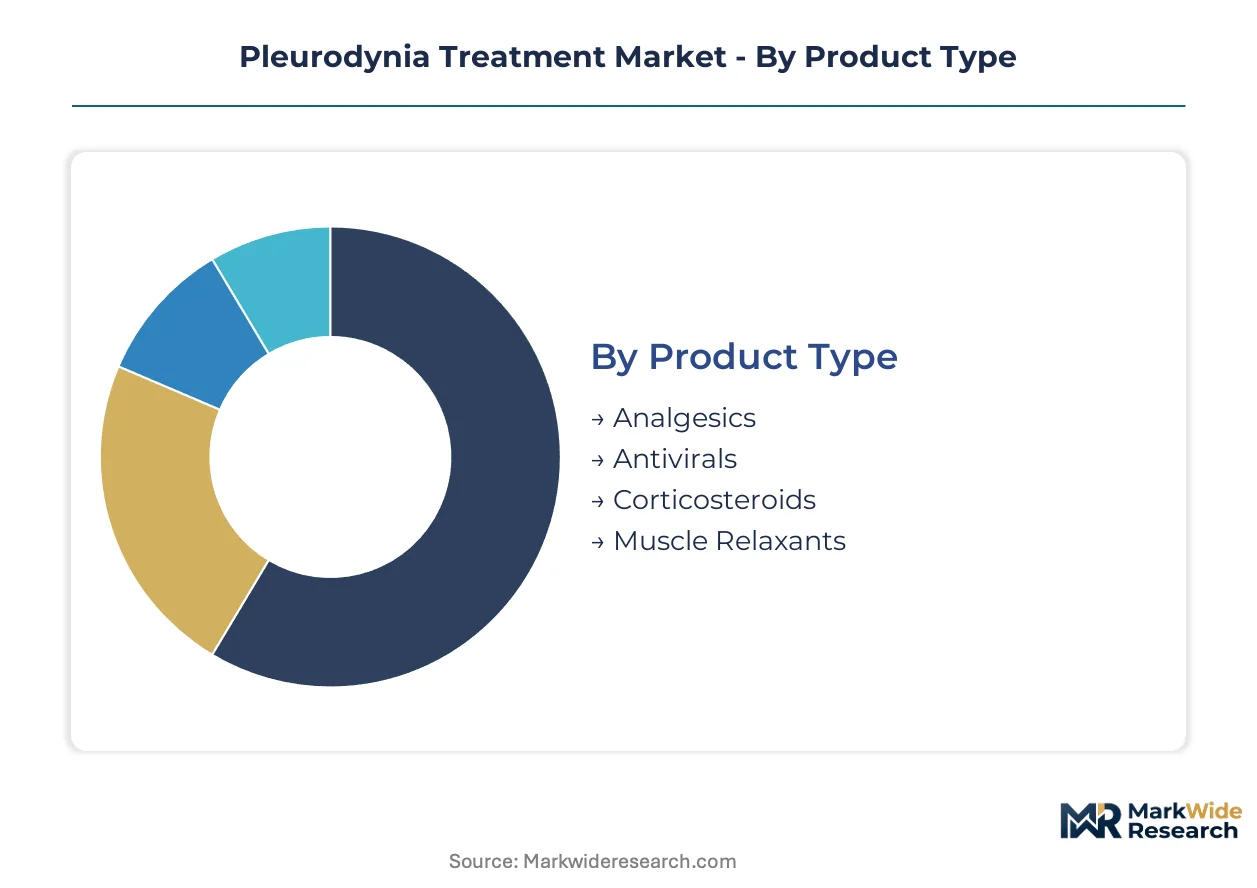
Pleurodynia treatment segmentation reveals divergent capital requirements across manufacturing and service delivery. Antiviral synthesis demands specialized containment infrastructure, while analgesic compounding operates at lower fixed-cost thresholds.
Product Type:
Antiviral manufacturing absorbs the heaviest upfront capital burden due to biocontainment specifications and fermentation capacity requirements.
- Analgesics:Acetaminophen and ibuprofen formulations dominate procurement volumes across acute care networks. Hospital pharmacy committees in the United States standardize these agents as first-line pediatric protocols, displacing aspirin from formulary preference.
- Antivirals:Ribavirin production requires dedicated viral containment suites and validated sterile filling lines. FDA accelerated approval pathways concentrate development investment toward severe enterovirus indications, though pediatric pharmacokinetic studies extend timelines.
- Corticosteroids:Dexamethasone and prednisolone suspensions address inflammatory complications in pericarditis-presenting cases.
- Muscle Relaxants:Cyclobenzaprine and methocarbamol target refractory intercostal spasm in adolescent populations.
Most installed capacity flows through Analgesics. Expansion is steepest in Antivirals.
Delivery Mode:
Route selection tracks severity stratification, with parenteral forms commanding premium positioning in critical care.
- Oral:Suspensions and chewable tablets capture outpatient volume through retail pharmacy networks. Medicaid pediatric fee schedules constrain dispensing margins, limiting pharmacy participation.
- Intravenous:Continuous infusion pumps in pediatric intensive care units deliver titrated analgesia for severe coxsackievirus presentations. Home health agencies are building step-down administration capabilities.
- Injectable:Intramuscular routes serve emergency department loading doses before oral transition.
- Topical:Lidocaine patches provide localized intercostal anesthesia with minimal systemic absorption.
Oral formulations generate highest prescription counts. Intravenous routes claim the steepest expansion trajectory as home infusion services proliferate.
End User:
Facility type determines reimbursement architecture and procurement centralization intensity.
- Hospitals:Integrated delivery networks consolidate pharmaceutical benefits manager contracts across three-to-five-year terms, locking in acetaminophen and antiviral supply agreements. Pediatric infectious disease infrastructure concentrates in surveillance corridor states.
- Homecare:Pediatric home health agencies capture PICU step-down patients through intravenous analgesic administration. Reimbursement compression under Medicaid pediatric fee schedules constrains service expansion.
- Clinics:Urgent care centers manage uncomplicated outpatient episodes with oral protocols.
- Rehabilitation Centers:Respiratory physiotherapy integration creates service line differentiation through combined pharmacological-non-pharmacotherapy approaches.
Hospitals anchor procurement volume concentration. Homecare is gaining share fastest as post-acute networks extend reach.
Treatment Approach:
Protocol selection reflects evolving evidence bases and payer preference for multimodal interventions.
- Pharmacological:Analgesic-antiviral combinations form the evidence standard for moderate-to-severe presentations. EMA pediatric investigation plans mandate age-appropriate formulation studies, forcing parallel adult-pediatric program design.
- Combined Therapy:Pain control integrated with respiratory physiotherapy protocols is displacing single-agent analgesia in pediatric emergency departments. WHO essential medicines criteria influence national procurement tenders in lower-resource settings.
- Non-Pharmacological:Chest wall physiotherapy and breathing exercises address functional recovery.
- Alternative Medicine:Acupuncture and herbal preparations occupy limited regulatory approval status.
Pharmacological protocols retain dominant utilization. Combined Therapy approaches are expanding most quickly as clinical evidence accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coxsackievirus surveillance corridors in the United States concentrate acute care demand and shape procurement patterns for pleurodynia therapeutics. Hospital networks across surveillance states standardize multimodal pain protocols that displace single-agent analgesia.
United States
FDA breakthrough therapy designation compresses antiviral development timelines for severe enterovirus indications. Medicaid pediatric fee schedules constrain retail pharmacy margins for outpatient analgesic dispensing. Texas Medical Center anchors pediatric infectious disease infrastructure that integrates PCR diagnostics with preemptive treatment protocols.
Germany
EMA pediatric investigation plans mandate parallel adult-pediatric program design for novel antiviral submissions. Hospital procurement committees consolidate pharmaceutical benefits manager contracts under multi-year supply agreements. Berlin-Brandenburg clusters contract research organizations specializing in age-appropriate formulation studies.
China
NMPA accelerated approval pathways attract development investment toward enterovirus-targeted therapies. National procurement tenders reference WHO essential medicines criteria for analgesic access. Yangtze River Delta chemical manufacturing zones concentrate ribavirin active pharmaceutical ingredient production.
India
CDSCO pediatric investigation requirements extend development timelines for age-appropriate antiviral formulations. National health mission programs expand essential medicines access in lower-resource settings. Maharashtra pharmaceutical corridors scale acetaminophen compounding capacity for domestic and export markets.
Japan
PMDA orphan drug incentives reshape pipeline priorities for rare infectious disease indications. Regional health systems integrate diagnostic-therapeutic bundling into coxsackievirus outbreak response protocols. Kanto metropolitan clusters concentrate pediatric intensive care units that drive intravenous analgesic procurement.
Pleurodynia Treatment Market Vendor Landscape
Global majors compete with regional champions across antiviral manufacturing scale and analgesic distribution reach. Market structure tiers between consolidated pharmaceutical conglomerates and specialized pediatric formulation developers. Three archetypes dominate: integrated health systems with diagnostic-therapeutic bundling capabilities, pure-play antiviral manufacturers with biocontainment infrastructure, and broad retail distributors capturing outpatient episodes. Competitive moves concentrate on strategic partnerships for pediatric pharmacokinetic expertise and capacity expansion in surveillance corridor states.
Within the integrated pharmaceutical tier, Pfizer Inc., Johnson & Johnson, and Roche Holding AG occupy positions that exemplify divergent strategic emphases. Pfizer represents antiviral manufacturing scale applied to severe enterovirus presentations. Johnson & Johnson anchors broad retail distribution networks that capture outpatient analgesic demand. Roche exemplifies diagnostic-therapeutic bundling that links PCR testing infrastructure to treatment protocol capture.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Roche Holding AG |
| Merck & Co. |
| Novartis AG |
| GlaxoSmithKline |
| Sanofi SA |
| Abbott Laboratories |
| Bristol-Myers Squibb |
| Others |
Supply Flow & Price Mechanics
Pediatric pharmacokinetic formulation scientists concentrated in Massachusetts and Basel command wage premiums that widen spreads between premium intravenous analgesic tiers and economy oral suspensions. Labor-cost differentials between specialized biocontainment facilities and standard compounding operations feed directly into hospital procurement committee tiering decisions.
Pricing Analysis
Input-cost pass-through from ribavirin active pharmaceutical ingredient volatility anchors contract-based long-term offtake structures between formulators and integrated delivery networks. Pricing stratifies across premium intravenous infusion protocols, standard oral combination therapies, and economy single-agent analgesics based on FDA certification tier and after-sales clinical support bundling. Cost compression in standard oral tiers is intensifying because Medicaid pediatric fee schedules cap dispensing margins. Retail pharmacy chains exhibit highest price sensitivity, while pediatric intensive care units demonstrate lowest sensitivity due to outcome-critical dosing precision requirements.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital pharmaceutical benefits managers force formulators to qualify secondary ribavirin API suppliers beyond Yangtze River Delta chemical manufacturing zones. Manufacturing draws from Chinese fermentation capacity, Indian acetaminophen compounding corridors, and German sterile filling infrastructure. Single-source vulnerability concentrates in pediatric-specific containment suites validated for enteroviral handling. Distribution runs through integrated health system central warehouses with direct-to-ward replenishment protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA breakthrough therapy designation for severe enterovirus antivirals accelerates development investment and concentrates acute care demand in surveillance corridor states.
For Market Incumbents: Anchor formulary position through multi-year pharmaceutical benefits manager contracts that lock acetaminophen-ribavirin combination protocols into pediatric emergency department order sets. Expand biocontainment capacity in Texas and California surveillance corridors to preempt API supply disruption from Chinese export license volatility. Certification investment in EMA pediatric investigation plans insulates against European market access erosion. For New Entrants and Emerging Players: Pediatric home health agencies represent the most accessible channel partner type for intravenous analgesic step-down services. White-space concentration sits in respiratory physiotherapy integration protocols and WHO essential medicines alignment for lower-resource national tenders. Penetrate Maharashtra and Yangtze River Delta manufacturing partnerships to capture acetaminophen export volume contracts. For Investors and Strategic Acquirers: Integrated health systems with diagnostic-therapeutic bundling capabilities are the most active acquirer in this space, seeking pediatric infectious disease infrastructure in coxsackievirus surveillance states. Long-term viability hinges on pipeline positioning against regulatory exclusivity windows rather than commodity analgesic manufacturing scale. Monitor enterovirus surveillance network data harmonization progress as inflection indicator for real-world evidence generation feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Submission | EMA mandates parallel adult-pediatric studies that force early partnership with specialized contract research organizations. |
| Diagnostic-Therapeutic Bundling | Roche's PCR-to-treatment protocol capture model demonstrates integrated health system value creation in outbreak response. |
| Home Infusion Service Buildout | Pediatric home health agencies in surveillance corridor states capture PICU step-down revenue previously lost to hospital readmission. |
| WHO Essential Medicines Alignment | National procurement tenders in India and lower-resource markets reference WHO analgesic criteria for volume contract eligibility. |
| API Supply Diversification | Ribavirin formulators dual-qualify Indian and European secondary sources to mitigate Chinese export license volatility exposure. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pediatric infectious disease specialists, hospital formulary directors, pharmaceutical benefits managers, and antiviral manufacturing executives with secondary validation through FDA accelerated approval filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov enterovirus protocol registries, and hospital procurement database extracts. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation anchored segment-level estimates.
Segment-weighting approaches distributed value across analgesic and antiviral product types, oral and intravenous delivery modes, hospital and homecare end users, and pharmacological versus combined therapy approaches throughout the projection horizon. CAGRs derived from epidemiological surveillance trend extrapolation, regulatory approval timeline probability weighting, and procurement contract renewal cycle analysis. Modeled inputs incorporated coxsackievirus outbreak seasonality patterns and Medicaid fee schedule revision trajectories.
Revisions become necessary when FDA breakthrough therapy designation timelines compress, EMA pediatric investigation plan requirements expand, or coxsackievirus surveillance network data standards harmonize across state health departments. Deviation in API export license volatility from Chinese chemical manufacturing zones would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Cancer Biological Therapy Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Botulism Treatment Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Pleurisy Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Treatment Market