
 Global Platform Screen Doors for Subway Lines Market | 2026-2036
Global Platform Screen Doors for Subway Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Platform Screen Doors for Subway Lines Market Outlook
Market Context
The platform screen door industry is recalibrating around a widening split between premium full-height systems with climate integration and commodity half-height barriers serving cost-constrained retrofits. Nabtesco leverages its precision motion control heritage to dominate high-reliability electric actuation modules for premium installations. Fangda anchors the Asia-Pacific supply base through deep manufacturing scale and captive component production. Alstom competes on system integration strength, bundling platform doors with rolling stock and signaling contracts across European and Middle Eastern projects.
Technical Definition and Segment Structure
Platform screen doors for subway lines are engineered barrier assemblies installed at platform edges, typically spanning 2.5 to 3.5 meters in height with opening widths of 1.8 to 2.4 meters, designed to separate passenger waiting zones from train tracks while synchronizing with door systems via programmable logic controllers. Their primary purpose is eliminating accidental falls, reducing ventilation loads, and enabling precision climate management in underground environments. Automatic product types now capture the dominant margin pool as transport authorities phase out manual configurations, while electric actuation technology leads volume due to superior energy efficiency and diagnostic transparency over pneumatic alternatives. Retrofit installation types are accelerating fastest in mature European networks where aging infrastructure demands barrier additions without full station reconstruction.
Regulatory Frame and Outlook
The European Union's F-Gas Regulation and Machinery Directive pressure manufacturers toward low-global-warming-potential sealing materials and redundant safety interlocks, while China's GB standards and MIIT rail safety protocols mandate fire resistance ratings and electromagnetic compatibility testing for all platform barrier systems. Japan's METI energy efficiency guidelines further shape product development by incentivizing regenerative drive mechanisms in high-cycle door operations. Stakeholders must monitor how divergent certification requirements across these jurisdictions fragment supply chain configurations and influence localization decisions for system integrators.
Market Dynamics
Electric actuation systems with integrated sensor networks are displacing pneumatic alternatives across new subway installations, driven by China's MIIT rail safety directives and the operational imperative for predictive maintenance capabilities in high-cycle environments.
Growth Catalysts
- Urban ridership density thresholds:Megacities in China, Japan, and South Korea now mandate full-platform enclosures where daily passenger volumes exceed 50,000 per station, creating automatic demand for climate-integrated barrier systems.
- MIIT electromagnetic compatibility mandates:China's Ministry of Industry and Information Technology now requires fire resistance ratings and EMC testing for all platform barrier systems, accelerating replacement cycles in legacy networks.
- Regenerative drive mechanisms:METI energy efficiency guidelines in Japan incentivize high-cycle door operations that capture and reuse braking energy, pulling adoption of advanced motor control systems.
Market Restraints
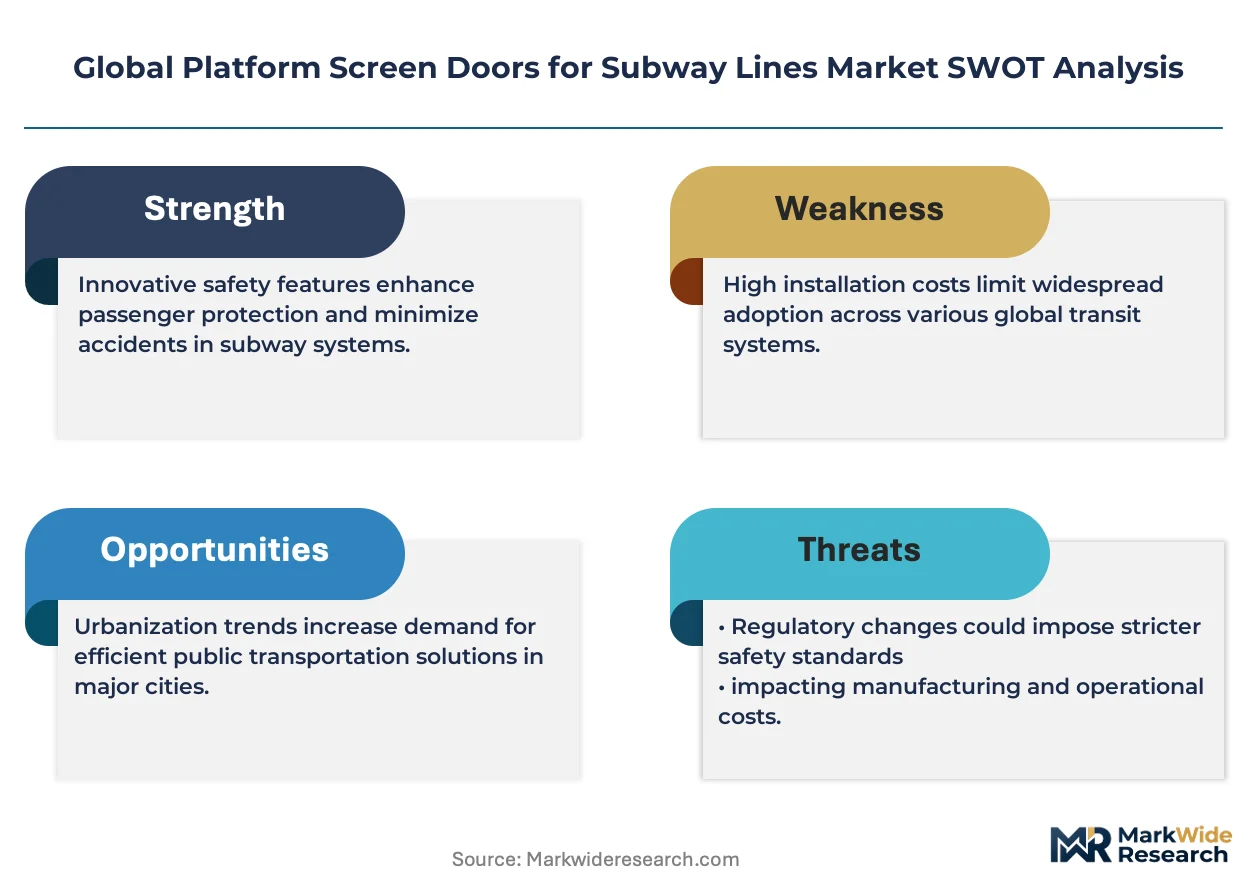
- Stainless steel and aluminum input volatility:Platform door frame fabrication depends on specialty alloy grades whose pricing fluctuates with energy-intensive smelting costs, compressing margins for system integrators locked into fixed-price contracts.
- Precision actuator supply concentration:High-reliability linear motion components for premium installations concentrate among Japanese and German component specialists, creating single-source vulnerability for projects requiring 99.97% availability ratings.
- Legacy station structural limitations:Mature subway networks in London, Paris, and New York face load-bearing constraints and narrow platform geometries that preclude full-height screen door retrofits without billion-dollar station reconstruction.
Strategic Opportunities
- Indian metro expansion corridors:Cities including Mumbai, Bangalore, and Chennai are greenfielding 200+ kilometers of new lines annually without legacy infrastructure constraints, enabling direct specification of full-climate-screen systems.
- EU F-Gas Regulation compliance services:The European Union's phasedown of high-global-warming-potential refrigerants creates aftermarket revenue streams for door seal refurbishment and low-GWP gasket replacement programs.
- Sensor-to-cloud diagnostics convergence:Vibration monitoring, thermal imaging, and edge computing are converging with door control systems to enable condition-based maintenance contracts that displace traditional break-fix service models.
Industry Challenges
- Systems integration engineering scarcity:Projects require specialists fluent in both IEC 61508 safety integrity levels and legacy train control communication protocols, with talent pools concentrated among a handful of European and Japanese engineering consultancies.
- Multi-jurisdiction certification timelines:A single platform screen door system may require sequential GB standard testing in China, CE marking in Europe, and FRA-equivalent validation in the US, stretching product launch cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Platform Screen Doors for Subway Lines Market |
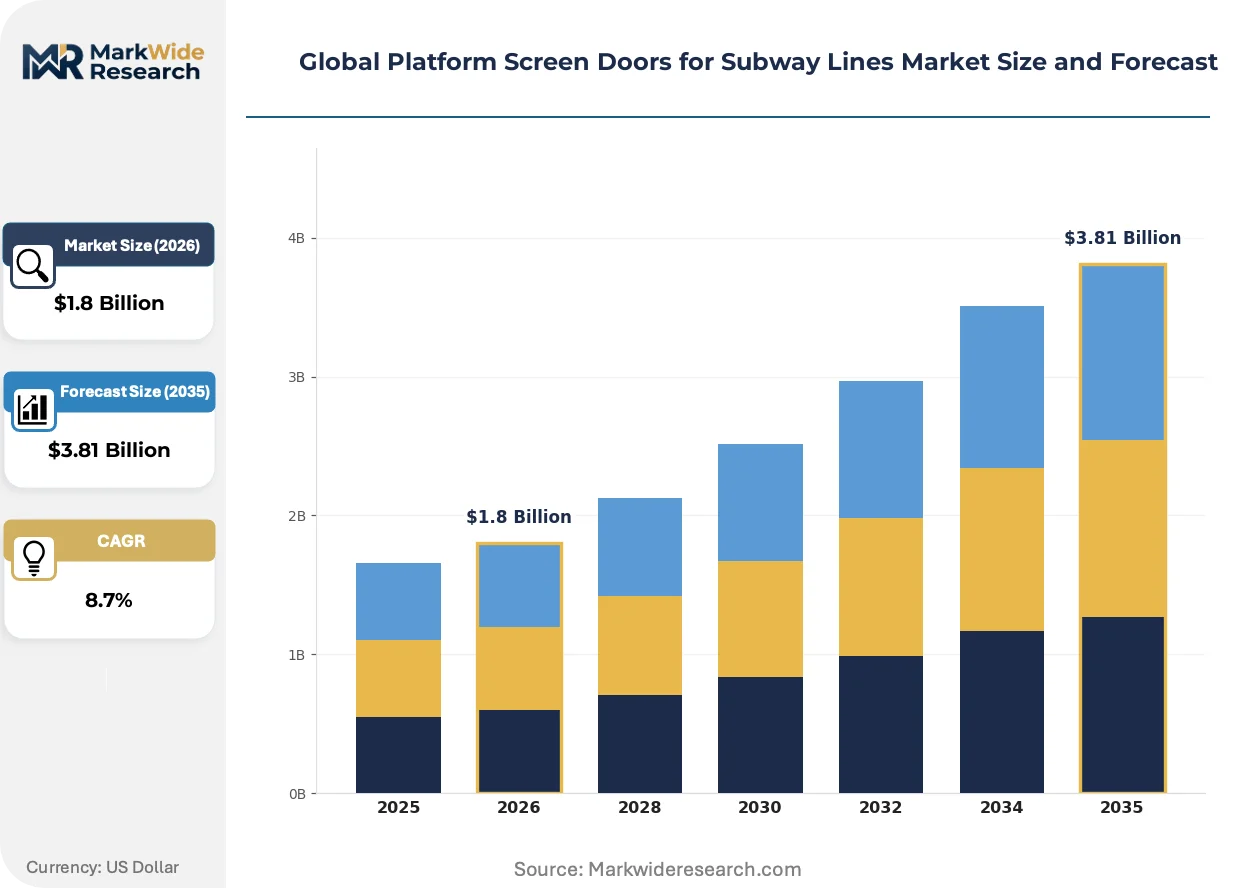
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Sliding, Folding Technology: Electric Actuation, Pneumatic Control, Hybrid Systems, Mechanical End User: Transport Authorities, Private Rail Operators, Urban Transit Systems, Infrastructure Developers Installation Type: New Construction, Retrofit, System Expansion, Upgrades |
| Companies Covered | Fangda, Stanley, Nabtesco, Horton Automatics, Panasonic, Westinghouse, Kangni, Alstom, Faiveley Transport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Platform Screen Doors for Subway Lines Market Strategic Shifts
Digital twin technology and edge-native diagnostics are reshaping how platform barrier systems are specified, commissioned, and maintained across their 25-30 year operational lifecycles.
Machine vision-based passenger detection is converging with door control logic to enable dynamic dwell time adjustment and intrusion prevention. Transport authorities in Singapore and Shenzhen are deploying these systems at platform chokepoints where crowd density peaks exceed design capacity. The technology is converging with predictive analytics platforms to compress incident response times from minutes to seconds.
The EU F-Gas Regulation is forcing manufacturers toward hydrofluoroolefin-based sealing materials and welded metal gasket alternatives in climate-integrated full-height systems. Industrial consequence includes accelerated R&D spending on material science and revised supplier qualification protocols. Premium segment producers serving Northern European underground networks are responding fastest, with some already achieving 90% reduction in GWP-weighted seal content.
Lifecycle service contracting is displacing capital-only procurement across mature networks. Transport for London and the Metropolitan Transportation Authority now bundle 15-year maintenance commitments with initial installation awards, transferring operational risk to OEMs. This pattern is most visible in Anglo-American procurement frameworks where public-sector budget constraints favor opex-over-capex accounting treatments.
Global Platform Screen Doors for Subway Lines Market Segmentation
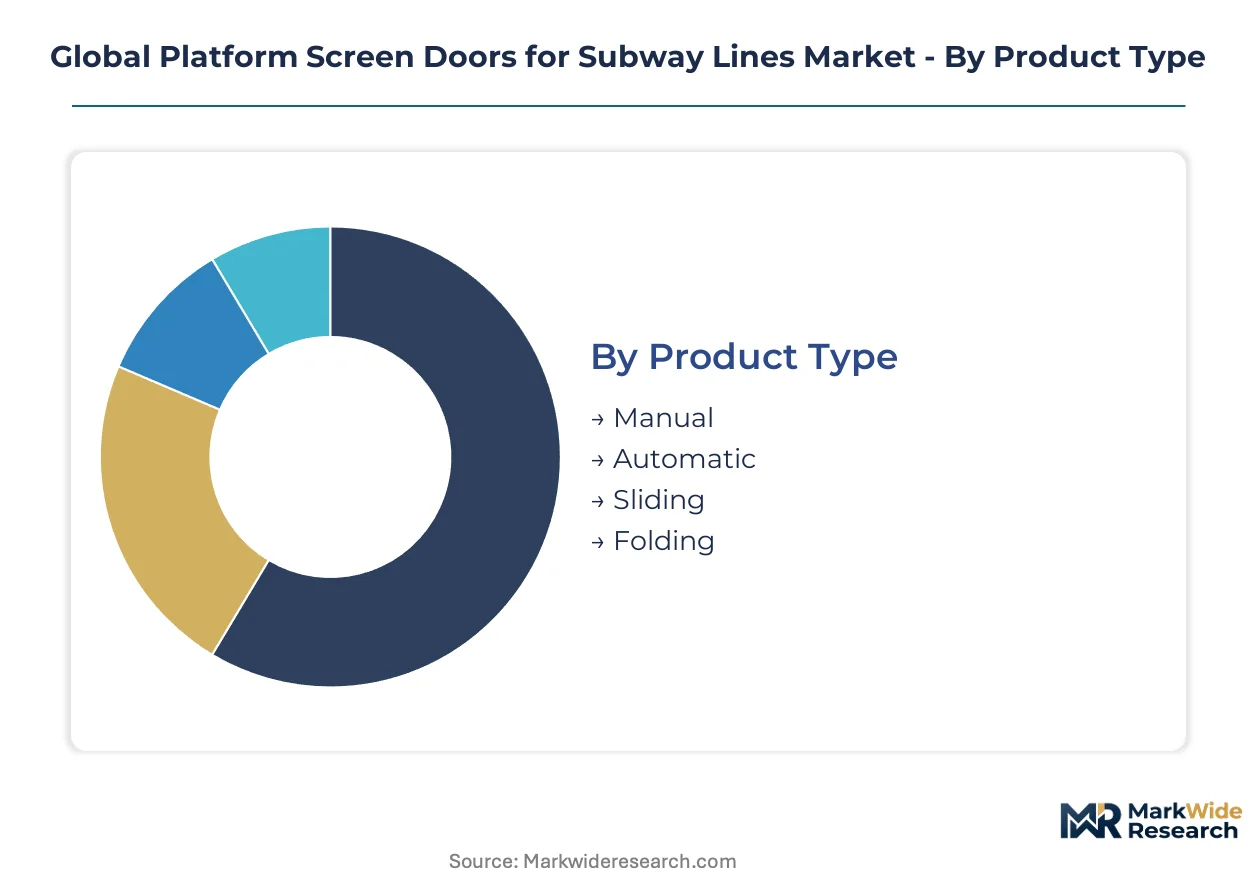
Platform screen door procurement splits sharply across automation level, actuation technology, and installation context. Transport authorities calibrate specifications to ridership density, climate control needs, and legacy station constraints.
Product Type:
Automation intensity defines the specification axis, with transport authorities weighing capital outlay against operational labor costs and safety performance.
- Automatic:Sensor-synchronized barrier systems integrate with train door controllers via programmable logic units, eliminating manual intervention. Chinese megacities including Beijing and Shenzhen mandate automatic configurations for all new underground stations exceeding 50,000 daily passengers under MIIT rail safety protocols.
- Manual:Operator-activated barriers persist in low-frequency suburban extensions and heritage rail preservation projects where capital budgets are constrained and ridership volumes remain below automation thresholds. Indian and Southeast Asian operators deploy these selectively on cost-sensitive corridor extensions.
- Sliding:Linear horizontal motion configurations dominate full-height climate-integrated installations across Northern European and East Asian underground networks where platform geometry accommodates lateral door pockets.
- Folding:Bi-fold or multi-panel accordion systems serve narrow platform retrofits in mature networks including London Underground and Paris Metro where structural constraints preclude sliding door envelopes.
Automatic leads on scale; Folding leads on momentum as retrofit demand accelerates in legacy European infrastructure.
Technology:
Actuation mechanism selection determines energy efficiency, diagnostic transparency, and lifecycle maintenance burden across 25-30 year operational horizons.
- Electric Actuation:Servo-motor driven linear motion systems deliver regenerative braking capability and real-time condition monitoring. METI energy efficiency guidelines in Japan explicitly incentivize electric configurations for high-cycle operations exceeding 500 daily door actuations.
- Pneumatic Control:Compressed air systems retain installed base in older Chinese and Russian networks but face replacement pressure under electromagnetic compatibility mandates requiring integrated sensor architectures that pneumatic infrastructure cannot support.
- Hybrid Systems:Dual-mode configurations combine electric precision with pneumatic backup for critical safety redundancy in high-availability installations serving airports and intermodal terminals.
- Mechanical:Spring-counterbalanced manual override systems persist as emergency fail-safes across all automated installations, with specifications governed by IEC 61508 safety integrity requirements.
Electric Actuation dominates new specification; Hybrid Systems are expanding most quickly in aviation-interfaced transit nodes.
End User:
Procurement authority structure shapes contract scale, financing mechanisms, and lifecycle service expectations.
- Transport Authorities:Municipal and regional government bodies including Transport for London and Metropolitan Transportation Authority bundle 15-year maintenance commitments with installation awards, transferring operational risk to OEMs.
- Private Rail Operators:Commercial concessionaires in Latin American and Asian markets prioritize capital efficiency and shorter payback periods, often selecting half-height barrier configurations over full climate-integrated systems.
- Urban Transit Systems:Integrated metro operators in Singapore, Hong Kong, and Dubai specify premium full-height systems with platform edge cooling and predictive maintenance diagnostics.
- Infrastructure Developers:Greenfield project sponsors in Indian cities including Mumbai and Bangalore specify platform barriers during initial station construction, avoiding retrofit cost premiums.
Transport Authorities lead on scale; Infrastructure Developers lead on specification clarity.
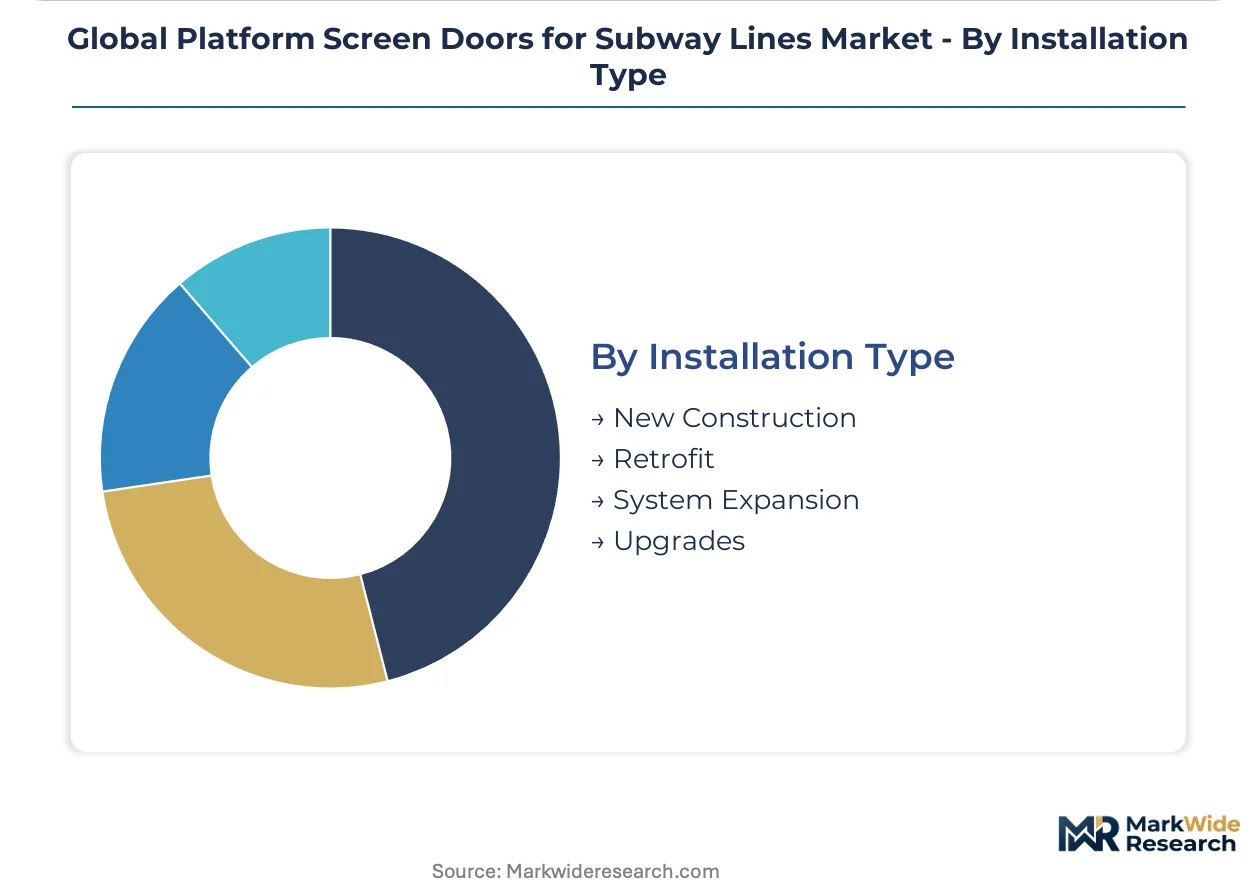
Installation Type:
Project context determines structural constraints, integration complexity, and revenue recognition timing for system integrators.
- New Construction:Greenfield station builds enable optimized platform barrier integration during architectural design phase, with full-height climate-integrated systems specified across Chinese, Indian, and Middle Eastern metro expansions.
- Retrofit:Barrier additions to operational stations in London, Paris, and New York face load-bearing limitations and narrow platform geometries that demand custom engineering and extended commissioning timelines.
- System Expansion:Corridor extensions to existing networks must achieve interoperability with legacy train control protocols and established maintenance workflows, constraining technology refresh options.
- Upgrades:Control system modernization and sensor retrofit programs extend functional life of installed barriers while preserving structural assets, concentrated in Japanese and Korean networks with aging first-generation automatic installations.
New Construction leads on volume; Retrofit leads on engineering margin intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT rail safety protocols are accelerating platform barrier deployments at triple the pace of European retrofit programs, while India's greenfield metro construction is bypassing legacy infrastructure constraints entirely.
China
Beijing and Shenzhen transit authorities mandate full-height automatic systems for stations exceeding 50,000 daily passengers under MIIT electromagnetic compatibility directives. GB standards enforcement now requires fire resistance ratings and integrated sensor architectures, forcing replacement of first-generation pneumatic installations in older networks. The Yangtze River Delta cluster around Shanghai anchors domestic manufacturing scale for electric actuation modules.
Japan
Tokyo Metro and Osaka Municipal Subway operate the world's densest platform door deployments, with METI energy efficiency guidelines incentivizing regenerative drive mechanisms. The Kanto region's high-cycle environments exceed 500 daily door actuations, pulling adoption of advanced motor control systems with predictive maintenance diagnostics. Nagoya's Chubu manufacturing belt supplies precision linear motion components to domestic and export markets.
India
Mumbai Metro, Bangalore Namma Metro, and Chennai Metro are greenfielding 200+ kilometers annually without structural constraints, enabling direct specification of full-climate-screen systems. The Ministry of Housing and Urban Affairs prioritizes platform safety barriers under metro expansion funding protocols. Maharashtra and Karnataka states concentrate domestic system integration capacity for these new-build corridors.
Germany
Berlin BVG and Munich MVG face platform geometry limitations that demand custom folding-door configurations for retrofit installations. The EU F-Gas Regulation pressures manufacturers toward hydrofluoroolefin-based sealing materials in climate-integrated systems. Bavaria and North Rhine-Westphalia host engineering consultancies specializing in IEC 61508 safety integrity certification for European projects.
United Kingdom
Transport for London bundles 15-year maintenance commitments with platform barrier installation awards, transferring operational risk to OEMs under opex-favored procurement frameworks. The Jubilee Line extension and Crossrail stations represent reference designs for full-height climate integration. London's engineering services cluster supports lifecycle contracting models now spreading to Manchester and Birmingham metro expansions.
Global Platform Screen Doors for Subway Lines Market Competitive Environment
Top-tier vendors anchor premium full-height system integration, while mid-tier fabricators compete on half-height retrofit solutions for cost-constrained networks. The vendor base stratifies across three archetypes: precision motion control specialists, integrated rail system bundlers, and captive manufacturing scale players. Consolidation pressure intensifies as lifecycle service contracts displace capital-only procurement. Dominant competitive moves include strategic partnerships for sensor-to-cloud diagnostics convergence and geographic expansion into Indian greenfield corridors.
Within the precision motion control tier, Nabtesco exemplifies Japanese engineering heritage in high-reliability electric actuation. Fangda occupies a position representing Chinese captive manufacturing scale and component integration. Alstom anchors the European system integration archetype, bundling platform barriers with rolling stock and signaling contracts. These three vendors represent distinct strategic positions: component specialization, manufacturing depth, and vertical project integration respectively.
| Leading Market Players |
|---|
| Fangda |
| Stanley |
| Nabtesco |
| Horton Automatics |
| Panasonic |
| Westinghouse |
| Kangni |
| Alstom |
| Faiveley Transport |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation gates both qualified supply and premium-tier pricing access by mandating hydrofluoroolefin-based sealing materials in climate-integrated full-height systems, forcing manufacturers to qualify new gasket suppliers while transport authorities absorb material cost premiums for compliant configurations.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for electric actuation modules as Fangda and domestic competitors expand servo-motor production. Three-tier pricing structure across premium, standard, and economy levels separates climate-integrated full-height installations from half-height retrofits and manual configurations. Cost compression in the economy tier is intensifying because Indian greenfield projects specify local content requirements. Private rail operators in Latin America exhibit highest price sensitivity; urban transit systems in Singapore and Dubai show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German precision linear motion component suppliers serving 99.97% availability installations. Manufacturing gravity centers on China, Japan, and Germany for electric actuation systems, with India emerging as assembly hub for greenfield metro corridors. Stainless steel specialty alloys and electromagnetic sensor arrays constitute critical input dependencies. Tariff exposure runs through EU-China component trade flows. Distribution runs through system integrators bundling installation with 15-year lifecycle service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder because subway ridership density thresholds in megacities create automatic replacement demand under safety mandates.
For Market Incumbents: Lock in long-term actuator supply agreements with Nagoya and Bavarian component specialists before capacity constraints tighten. Defend margin position by embedding predictive maintenance diagnostics into 15-year service contracts that transfer operational risk from transport authorities. Counter emerging sensor-to-cloud specialists by acquiring edge computing capabilities for condition-based monitoring platforms. For New Entrants and Emerging Players: Launch via direct specification partnerships with Indian infrastructure developers greenfielding Mumbai and Bangalore metro corridors. Target half-height retrofit opportunities in London and Paris where structural constraints preclude incumbent full-height systems. Penetrate through EU F-Gas Regulation compliance services for door seal refurbishment programs in Northern European networks. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators because lifecycle service contracts concentrate recurring revenue and create captive aftermarket lock-in. Five-to-ten year viability hinges on exposure to Chinese MIIT-mandated replacement cycles versus European retrofit complexity. Watch Indian metro construction velocity as inflection indicator for greenfield specification trends.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Cloud Diagnostics Convergence | Enables condition-based maintenance contracts displacing break-fix service models at Transport for London. |
| Backward Integration into Electric Actuation | Captures margin pool from Japanese and German precision component suppliers for high-availability installations. |
| EU F-Gas Compliance Service Launch | Creates aftermarket revenue streams for door seal refurbishment under phasedown of high-GWP refrigerants. |
| Indian Greenfield Corridor Expansion | Bypasses legacy infrastructure constraints enabling direct specification of full-climate-screen systems in Mumbai. |
| Lifecycle Service Contract Bundling | Transfers operational risk to OEMs under opex-favored procurement frameworks at Metropolitan Transportation Authority. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with metro procurement directors, rail system integrators, electric actuation engineers, and infrastructure development executives with secondary validation against MIIT rail safety protocols, EU F-Gas Regulation filings, GB standards documentation, and METI energy efficiency guidelines. Bottom-up project pipeline analysis triangulated with top-down transit authority budget forecasts.
Historical reference periods anchored the projection horizon to observed installation cycles and replacement timelines across mature networks. Segmentation dimensions modeled include automation intensity, actuation technology, installation context, and regional regulatory cluster. CAGRs derived from ridership density thresholds, MIIT mandate compliance timelines, and greenfield construction velocity in Indian corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity alloy price volatility and multi-jurisdiction certification delays. Forecasts reflect documented assumptions about electromagnetic compatibility mandate enforcement and regenerative drive mechanism adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Global Enterprise Building Solutions Market
Building Automation Systems
United States Smart Windows Market
Building Automation Systems
Asia-Pacific Building Automation System Market
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
Smart Garage Door Opener and Controller Market
Building Automation Systems
Global Solar Shading Systems Market
Building Automation Systems
Flushing Systems Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
United States Building Automation Controls Market
Building Automation Systems
Smart Building Solutions Market
Building Automation Systems
Europe HVAC Controls Market
Building Automation Systems
Signage Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Building Automation and Control System Market