
 Building and Construction Tapes Market | 2026-2036
Building and Construction Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Building and Construction Tapes Market Analysis
A capital-intensity divergence between integrated resin producers and specialty converters is reorganizing competitive tiers in the building and construction tapes sector. 3M leverages captive polymer science capabilities to command premium positioning in structural bonding applications. Saint-Gobain anchors its construction tape portfolio through vertical integration into glass fiber and mineral wool systems. tesa SE differentiates via precision coating assets that serve European automotive and building OEMs with exacting specification compliance.
Building and construction tapes are pressure-sensitive adhesive systems engineered with backing substrates such as polyethylene, paper, vinyl, or fabric, designed to bond, seal, protect, or insulate surfaces across residential, commercial, and infrastructure projects. These products typically achieve peel adhesion values ranging from 20 to 70 ounces per inch width depending on formulation chemistry and backing construction, enabling temporary masking or permanent structural sealing per application requirements. Duct tape and masking tape represent mature volume categories where polyethylene and paper backings dominate commodity construction workflows. Electrical tape formulated with vinyl backings captures specialized margin pools in building MEP installations where flame-retardant specifications apply. Surface protection and insulation applications are expanding fastest as building envelope performance standards tighten across developed markets.
FDA and EPA frameworks in the United States govern adhesive emissions and volatile organic compound thresholds in construction materials, while REACH and RoHS in Europe restrict hazardous substances in tape chemistries and mandate disclosure across supply chains. OSHA workplace exposure limits further shape product selection on commercial job sites where installer safety protocols influence specification decisions. Stakeholders must monitor evolving chemical compliance deadlines and building code harmonization efforts to anticipate specification lock-ins and raw material substitution requirements.
Market Dynamics
EU Green Deal building renovation mandates are compressing specification cycles and forcing raw material substitutions across the construction tapes value chain. Resin producers and specialty converters face divergent capital requirements as performance standards tighten.
Growth Catalysts
- EU Green Deal renovation targets:Mandatory energy-efficiency upgrades across Germany, France, and Italy are accelerating tape replacement cycles in existing residential stock.
- Building envelope performance standards:Tighter thermal bridging regulations in Western Europe are expanding demand for high-performance sealing and insulation tape systems.
- Residential retrofit concentration:Germany's building modernization subsidies are channeling procurement toward certified adhesive products with verified emission profiles.
Market Restraints
- Petrochemical input volatility:Acrylic and rubber-based adhesive formulations face margin pressure from fluctuating propylene and butadiene feedstock costs.
- Specialty resin supply concentration:High-performance polymer supply concentrates among integrated chemical producers in Germany and the Netherlands, creating procurement bottlenecks.
- REACH compliance friction:ECHA substance restriction updates force reformulation cycles that extend product development timelines by 12-18 months.
Strategic Opportunities
- Underpenetrated Eastern European markets:Poland and Romania present white space as EU cohesion funds flow toward building modernization programs.
- Smart building integration:Sensor-compatible adhesive systems that bond IoT devices to building surfaces without signal interference represent an emerging application category.
- Circular economy mandates:France's anti-waste law and extended producer responsibility frameworks create preferential procurement channels for recyclable tape constructions.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in low-VOC, high-adhesion polymer science remains concentrated among aging technical workforces in Germany and Switzerland.
- Coating asset intensity:Precision slot-die and gravure coating lines require capital deployment exceeding 15 million euros per production unit.
- Multi-jurisdiction certification lag:Harmonization delays between CE marking, German DIBt approvals, and French CSTB certifications extend time-to-market for new products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building and Construction Tapes Market |
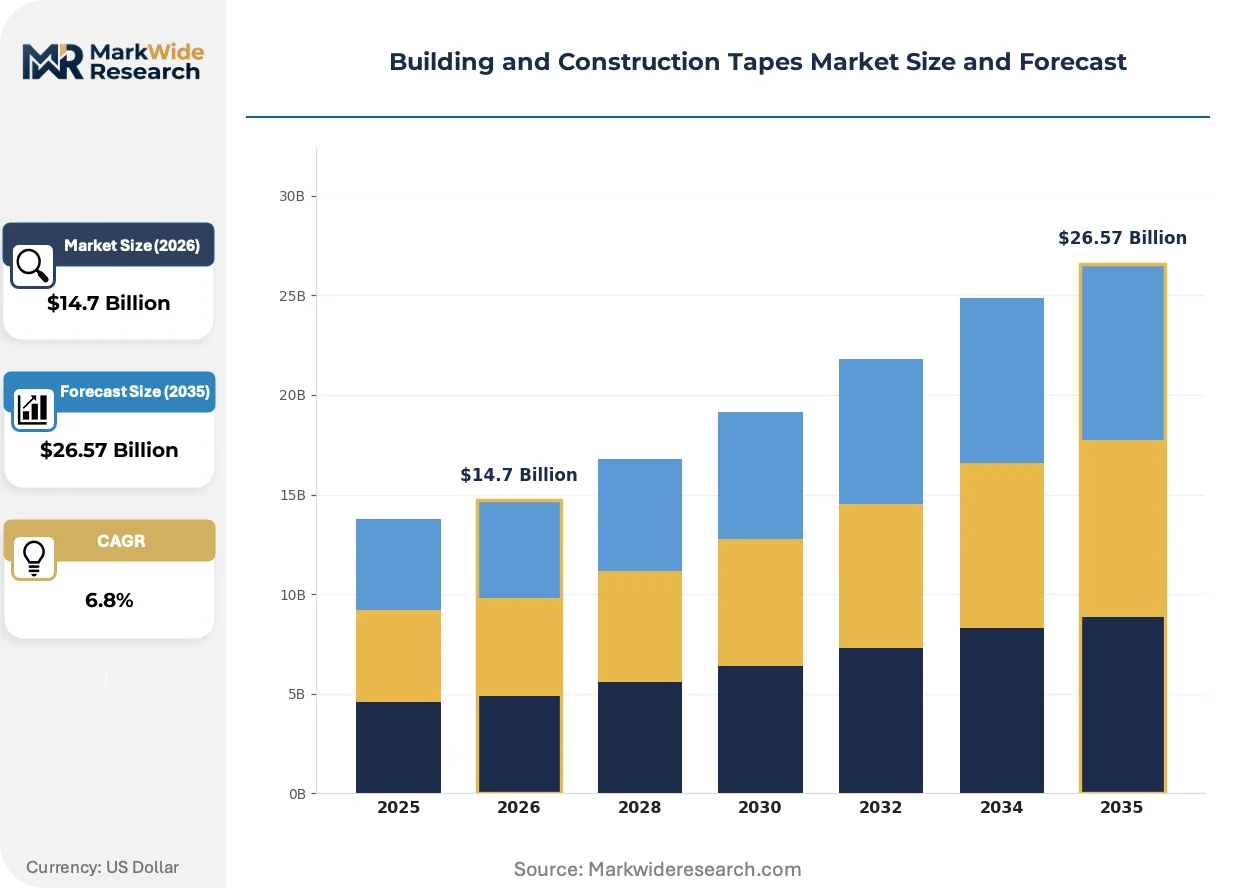
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Masking Tape, Duct Tape, Electrical Tape, Gaffer Tape Application: Surface Protection, Painting, Insulation, Sealing End User: Contractors, DIY Enthusiasts, Manufacturers, Resellers Material: Polyethylene, Paper, Vinyl, Fabric |
| Companies Covered | 3M, tesa SE, Nitto Denko Corporation, Avery Dennison Corporation, Intertape Polymer Group, DuPont de Nemours, Inc., Saint-Gobain, Scapa Group plc, Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building and Construction Tapes Market Emerging Trajectories
Active pressure-sensitive adhesive formulations are displacing passive bonding systems as building envelope performance requirements intensify. Material science advances and regulatory disclosure mandates are converging to reshape product development priorities.
Hybrid acrylic-silane adhesive chemistry is miniaturizing the functional thickness required for structural bonding applications. Commercial facade contractors in Germany and the Netherlands are specifying these systems for curtainwall installations where thermal cycling resistance is critical. The technology is compressing traditional mechanical fastening requirements while enabling thinner insulation assemblies.
REACH Article 33 disclosure obligations and SCIP database requirements are forcing supply chain transparency across the European construction sector. Tape manufacturers must now document substance composition down to 0.1% weight thresholds for articles containing SVHCs. German and French building material distributors are consolidating procurement around suppliers with pre-validated compliance documentation.
Specification authority is migrating from general contractors to building envelope consultants and energy auditors who control certification outcomes. France's RE2020 environmental regulation and Germany's GEG building energy code are elevating these technical advisors as gatekeepers for adhesive product selection. This shift is visible across large-scale residential developments in Paris and Munich where performance guarantees now hinge on tape system validation.
Building and Construction Tapes Market Segmentation
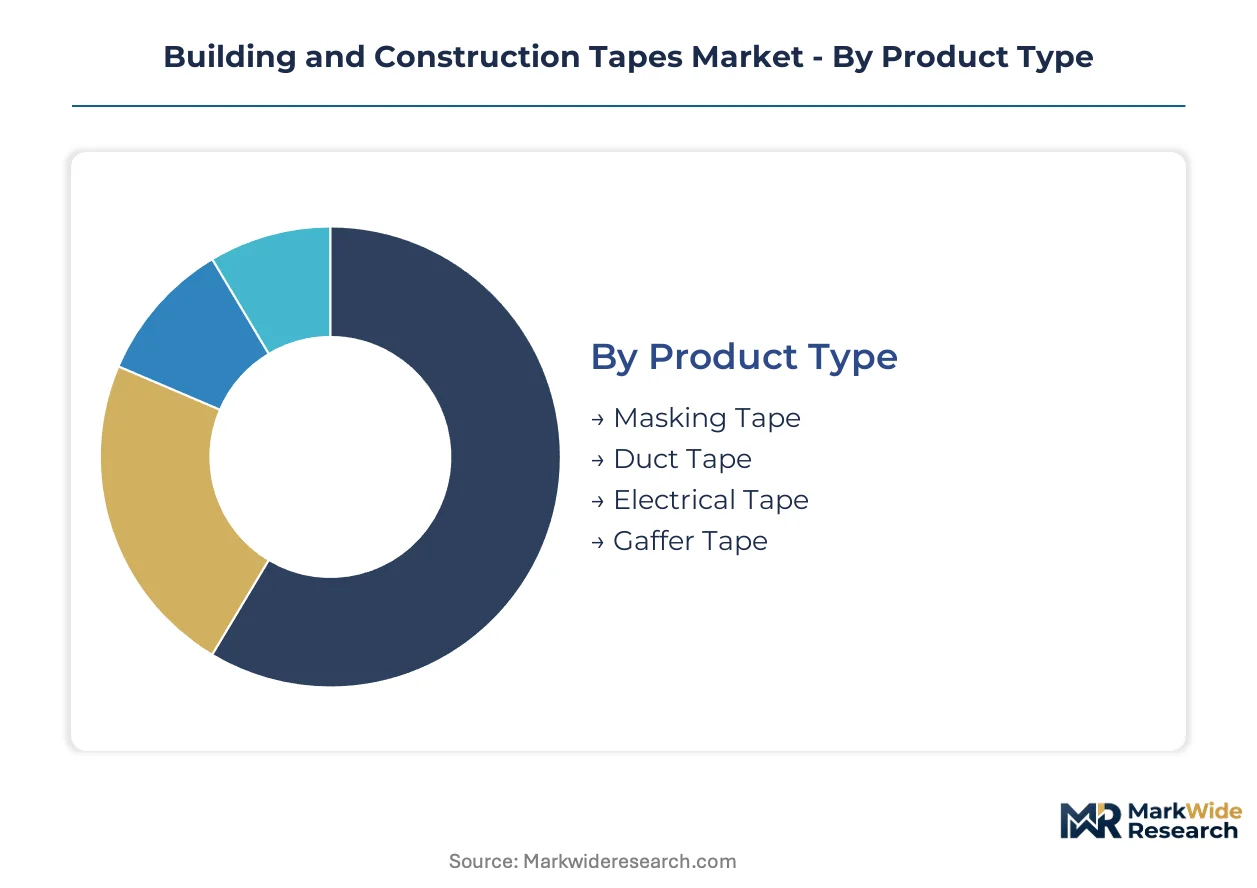
Segmentation in building and construction tapes reveals how substitution pressures and specification authority reshape procurement patterns. Each dimension exposes different vulnerability points to alternative bonding technologies and competing material formats.
Product Type:
Substitution pressure concentrates most intensely on commodity-grade formats where mechanical fastening and liquid adhesives compete aggressively on installed cost.
- Duct Tape:Polyethylene-backed cloth tapes with rubber-based adhesives deliver high tensile strength for temporary repairs and HVAC sealing. German facade contractors specify these for weatherproofing membrane overlaps where rapid application outweighs permanence.
- Masking Tape:Crepe paper backings with low-tack acrylic formulations enable clean removal after painting cycles. French residential renovators drive volume through RE2020-compliant renovation workflows requiring precision edge protection.
- Electrical Tape:PVC-backed pressure-sensitive systems with flame-retardant plasticizers insulate low-voltage building MEP runs.
- Gaffer Tape:Heavy-duty cloth backings with synthetic rubber adhesives serve stage construction and temporary event infrastructure.
Duct tape anchors the volume base while masking tape gains share at the steepest rate.
Application:
Application-based demand splits sharply between cost-driven temporary workflows and performance-specified permanent building envelope functions.
- Sealing:High-performance acrylic and butyl formulations create airtight, watertight bonds at structural joints. Netherlands curtainwall contractors specify these for thermal bridge elimination under stricter Dutch building codes.
- Insulation:Foil-faced and foam-backed tapes bond rigid insulation boards and seal vapor barriers. German Energieeffizienz standards accelerate replacement cycles in existing residential stock.
- Surface Protection:Low-tack polyethylene films shield finished surfaces during construction sequences.
- Painting:Washi paper and crepe formulations define crisp paint edges on interior and exterior substrates.
Sealing commands the premium tier while insulation expands most quickly.
End User:
End-user segmentation tracks specification authority migration from general procurement toward technical compliance gatekeepers.
- Contractors:Professional installation firms purchase certified tapes through building material distributors with pre-validated REACH documentation. French CSTB and German DIBt approvals increasingly determine specification eligibility.
- Manufacturers:Building component OEMs integrate tape systems into prefabricated envelope panels and window units. Polish and Romanian panel producers represent emerging demand concentration as EU cohesion funds flow eastward.
- DIY Enthusiasts:Retail-channel consumers prioritize price and immediate availability over certification depth.
- Resellers:Distributors consolidate procurement around suppliers with SCIP database compliance and transparent substance disclosure.
Contractors dominate current procurement value while manufacturers climb fastest.
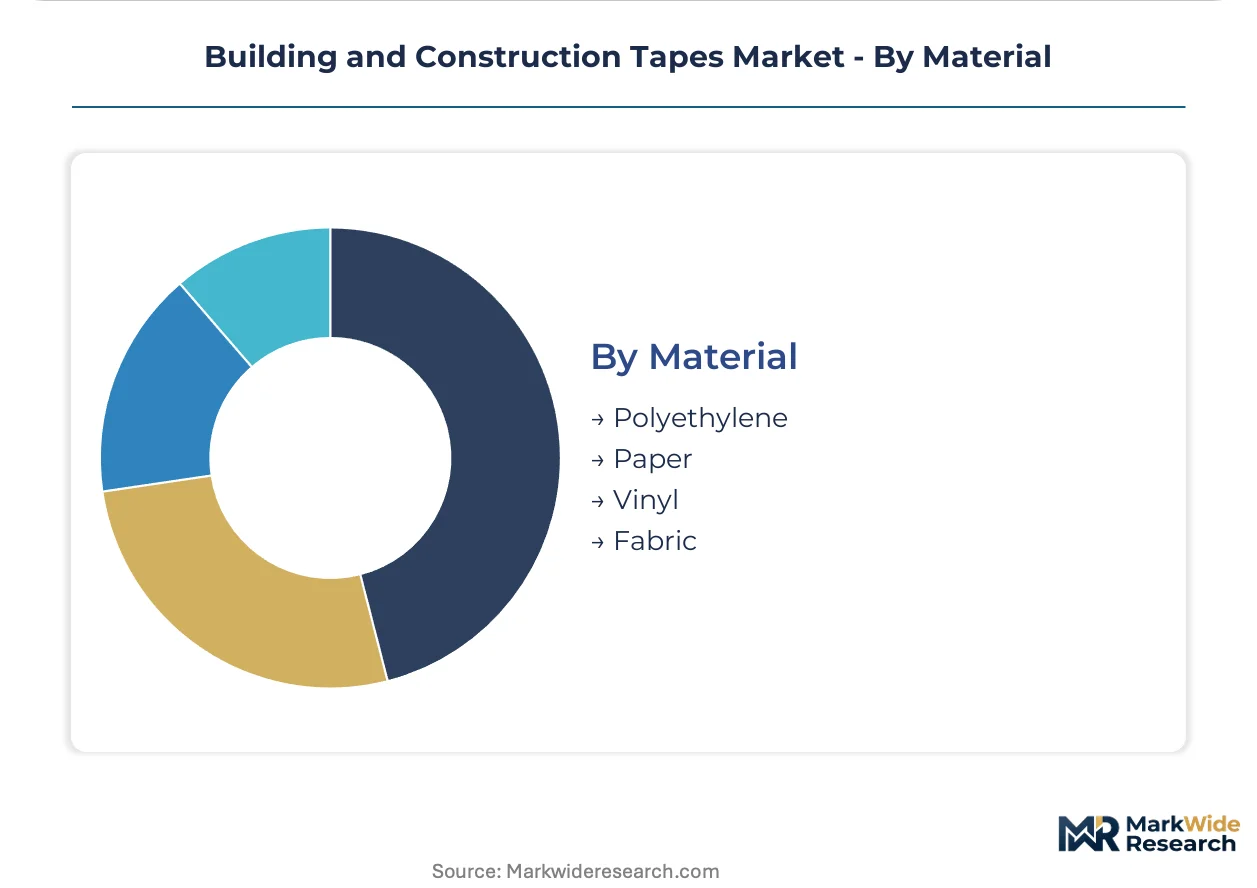
Material:
Material selection determines compatibility with building code performance tiers and recycling pathway feasibility.
- Polyethylene:Moisture-resistant backings with excellent conformability suit exterior sealing and temporary protection. Dutch and Belgian contractors favor these for below-grade waterproofing where chemical resistance matters.
- Paper:Crepe and flatback kraft backings enable clean removal and sustainable disposal. France's anti-waste law creates preferential procurement channels for recyclable paper-based constructions.
- Vinyl:PVC formulations deliver electrical insulation and flame retardancy for MEP installations.
- Fabric:Woven cotton and synthetic cloth backings provide tear resistance for heavy-duty duct and gaffer applications.
Polyethylene holds the installed base while paper-based alternatives expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French markets command pricing premiums through certified product mandates, while Eastern European procurement remains cost-sensitive despite accelerating renovation volumes. This asymmetry concentrates margin capture in Western European markets while volume expansion shifts eastward.
Germany
Residential retrofit subsidies under the GEG building energy code are accelerating tape replacement cycles in existing housing stock. ECHA substance disclosure requirements through the SCIP database force supply chain transparency that favors pre-certified suppliers. The Rhine-Ruhr industrial corridor hosts precision coating operations serving curtainwall contractors in Cologne and Düsseldorf with thermal-cycling-resistant formulations.
France
RE2020 environmental regulations elevate building envelope consultants as specification gatekeepers for adhesive selection. The anti-waste law creates preferential procurement channels for recyclable tape constructions with verified end-of-life pathways. The Paris metropolitan area concentrates demand from large-scale residential developments requiring performance-guaranteed sealing systems.
Netherlands
Stricter Dutch building codes on thermal bridging elimination expand demand for high-performance butyl and acrylic sealing tapes. CE marking harmonization with German DIBt approvals streamlines cross-border procurement for facade contractors. The Randstad region anchors curtainwall installation activity where hybrid adhesive-silane chemistry displaces mechanical fastening.
Poland
EU cohesion fund inflows toward building modernization programs create white-space opportunity for certified adhesive suppliers. REACH compliance documentation remains uneven among local distributors, creating procurement friction for Western European exporters. The Warsaw and Kraków metropolitan areas concentrate panel manufacturing operations integrating tape systems into prefabricated envelope components.
Italy
Energy-efficiency upgrade mandates in northern industrial cities accelerate demand for insulation bonding and vapor barrier sealing applications. CSTB certification recognition delays extend time-to-market for new product introductions from French and German suppliers. The Milan-Turin corridor hosts building component OEMs specifying tape-integrated facade systems for commercial developments.
Building and Construction Tapes Market Vendor Landscape
Concentration sits with integrated chemical producers and precision coating specialists who control captive polymer supply and specification-compliant production assets. The vendor base splits between commodity converters serving temporary construction workflows and performance-tier suppliers capturing permanent building envelope applications. Three archetypes dominate: integrated resin producers with backward polymer control, specialty converters with precision coating assets, and regional distributors with compliance documentation capabilities. Competitive moves center on M&A for coating asset acquisition and strategic partnerships with building envelope consultants who control certification outcomes.
Among integrated producers with captive material science, 3M and Saint-Gobain occupy positions that exemplify premium-tier positioning through upstream control over substrate and adhesive formulation. tesa SE represents the precision-converter archetype, serving European OEMs with exacting specification compliance. These three anchors illustrate how competitive advantage derives from either material science integration or coating precision rather than scale alone.
| Leading Market Players |
|---|
| 3M |
| tesa SE |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Intertape Polymer Group |
| DuPont de Nemours, Inc. |
| Saint-Gobain |
| Scapa Group plc |
| Berry Global Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day resin lead times concentrate procurement leverage among German and Dutch integrated producers, compressing margin capture for downstream converters while elevating pricing power at the polymer origin. This temporal asymmetry between raw material availability and finished tape delivery reshapes contract negotiations across the European building envelope value chain.
Pricing Analysis
Configured-to-order premiums for REACH-certified formulations with validated SCIP documentation command spreads exceeding standard commodity tape pricing by substantial multiples. Pricing stratifies across premium, standard, and economy tiers where German DIBt and French CSTB certifications determine eligibility for high-performance sealing applications. Cost compression in commodity polyethylene-backed formats intensifies as Asian imports penetrate Southern European distribution channels. DIY retail consumers exhibit highest price sensitivity while building envelope consultants controlling RE2020 and GEG compliance outcomes prioritize performance guarantees over unit economics.
Supply Chain Analysis
Just-in-time resin procurement dominates among specialty converters lacking captive polymer supply, forcing exposure to propylene and butadiene spot volatility. Strategic stockpiling of acrylic adhesive precursors concentrates among integrated producers in Germany, the Netherlands, and Belgium. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks, Russian butadiene streams, and regional European propylene crackers. Single-source vulnerability concentrates in high-performance silane-modified polymers produced at limited German chemical sites. Distribution runs through building material wholesalers with pre-validated compliance documentation serving facade contractors and panel manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise remains anchored among aging technical workforces in Basel and Frankfurt, constraining new product development velocity and amplifying acquisition premiums for capable R&D teams. This human capital scarcity reshapes competitive entry economics across the construction tapes sector.
For Market Incumbents: Secure backward integration into acrylic and butyl polymer production to defend margin structures against petrochemical feedstock volatility. Acquire precision coating assets in the Rhine-Ruhr corridor to capture specification authority migrating toward building envelope consultants. Channel control through distributors with pre-validated REACH documentation represents the critical defensive lever against emerging Polish and Romanian competitors. For New Entrants and Emerging Players: Anchor in Eastern European panel manufacturing clusters where EU cohesion fund inflows create white-space demand for certified tape-integrated envelope systems. Target Polish and Romanian building component OEMs with SCIP-compliant product offerings and streamlined certification pathways. A go-to-market partnership with Western European distributors seeking geographic diversification accelerates market access without direct coating asset investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized construction tape divisions lacking specification-grade coating capabilities. Five-to-ten-year viability hinges on exposure to EU Green Deal renovation mandates and building energy code tightening rather than new construction cyclicality. Precision coating specialists with validated German DIBt and French CSTB approval portfolios represent the priority acquisition archetype. The signal to watch is ECHA substance restriction announcements forcing reformulation cycles that extend incumbent product development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive acrylic supply insulates German converters from propylene spot volatility and secures formulation control. |
| Precision Coating Asset Acquisition | Slot-die and gravure lines exceeding 15 million euros per unit enable specification compliance for curtainwall contractors. |
| REACH Certification Investment | Pre-validated SCIP database documentation accelerates procurement consolidation by French and German distributors. |
| Eastern European Distribution Partnership | Polish and Romanian channel access captures EU cohesion fund flows without direct production footprint expansion. |
| Building Envelope Consultant Engagement | Technical advisor relationships secure specification authority under RE2020 and GEG compliance frameworks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of ECHA substance restriction updates, EU customs trade data, and building code harmonization documentation across member states. Plant managers at German and Dutch coating facilities, procurement leads at French facade contractors, distribution channel partners in Poland and Romania, and technical R&D directors at adhesive formulators provided structured input. Bottom-up demand modeling from construction permit data and top-down value chain analysis triangulate volume estimates.
Segmentation dimensions modeled include product type, application function, end-user archetype, backing material, and regional regulatory cluster across the analysis window. CAGRs derive from regression against historical replacement cycle data and policy-mandated renovation targets. Industry-specific forecast inputs incorporate thermal bridging regulation stringency indices and SCIP database compliance penetration rates by country.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and REACH enforcement continuity; material deviation would warrant model refresh. Forecasts reflect base-case policy trajectories without contingency for regulatory rollback or accelerated substance restriction timelines. Revision becomes warranted when ECHA SVHC candidate list expansion crosses thresholds that trigger mandatory reformulation across core adhesive chemistries.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Water Activated Tape Dispensers Market
Tapes
Wire Harness Tape Market
Tapes
Tape Applicator Machines Market
Tapes
Paper Packaging Tapes Market
Tapes
Carry Handle Tape Market
Tapes
Tissue Tapes Market
Tapes
Differential Tapes Market
Tapes
Replica Tapes Market
Tapes
North America Packaging Tapes Market
Tapes
Tape Banding Machine Market
Tapes
Foam Tape Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Paper Masking Tapes Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Release Tape Market
Tapes
Edge Band Tapes Market