
 Wire Harness Tape Market | 2026-2036
Wire Harness Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Harness Tape Market Outlook
China's expanding automotive wiring capacity is reshaping regional supply dynamics for harness tape producers. tesa SE leverages its European R&D base to sustain technical leadership in acrylic adhesive formulations. 3M Company anchors North American demand through deep vertical integration into fluoropolymer substrates. Nitto Denko Corp. competes aggressively in Asian electronics channels with thin-film precision products.
Wire harness tape denotes a flexible adhesive-backed substrate engineered to wrap, insulate, and mechanically protect bundled electrical conductors, typically rated for continuous operating temperatures from 105°C to 180°C depending on base polymer chemistry. The primary purpose centers on preventing abrasion-induced short circuits while maintaining dielectric integrity across engine compartments and cabin harnesses. Electrical tape and insulation tape categories dominate current revenue pools given their ubiquity in automotive OEM assembly lines. Polyester and PVC material grades represent mature, high-volume segments where margin compression is acute, while PTFE-based products command premium positioning in aerospace and high-voltage EV architectures.
REACH compliance in Europe and GB standard certification in China directly dictate permissible halogen content and smoke density thresholds for harness tapes installed in passenger vehicles. EPA and NHTSA requirements in the United States further constrain material selection through flame-spread and toxicity emission protocols. Stakeholders must monitor evolving battery-electric vehicle platform voltages, as 800V architectures will redefine insulation thickness specifications and thermal class ratings across all major supply contracts.
Market Dynamics
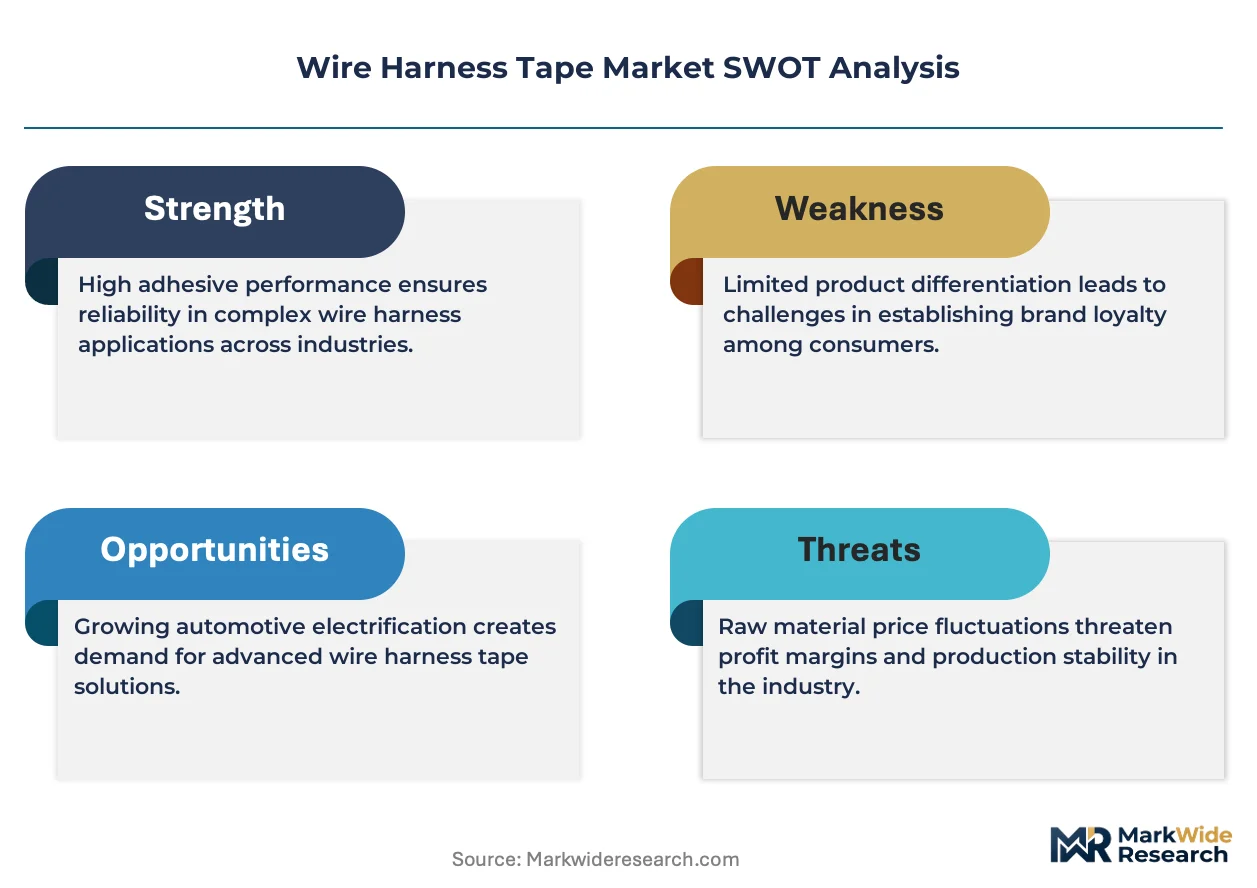
800V battery-electric vehicle architectures are forcing wholesale recalibration of thermal class ratings and insulation thickness specifications across automotive supply contracts, compressing qualification timelines for incumbent substrate suppliers.
Growth Catalysts
- EU REACH flame-retardancy mandates:Passenger vehicle OEMs in Germany and France must now specify halogen-free harness tapes, creating certified-product pull-through across assembly lines.
- China's GB standard certification:Domestic EV manufacturers in Shenzhen and Shanghai face compulsory smoke-density thresholds, accelerating tape replacement cycles in high-voltage battery compartments.
- Acrylic adhesive chemistry advances:Next-generation solvent-free formulations bond reliably to polyimide substrates at 180°C continuous operation, opening aerospace and defense channels previously closed to tape-based solutions.
Market Restraints
- Fluoropolymer resin supply concentration:PTFE substrate production clusters in the US and Japan, exposing converters to feedstock allocation risk during semiconductor-industry demand spikes.
- Polyester film margin compression:Mature PVC and PET grades face commodity pricing pressure as Chinese integrated producers expand captive tape extrusion capacity.
- Silicone adhesive substitution threat:Liquid injection-molded grommets and overmolded cable assemblies eliminate tape wrapping steps in premium EV platforms above 400V.
Strategic Opportunities
- India's PLI scheme for automotive components:Chennai and Pune manufacturing corridors offer tariff-advantaged tape conversion capacity for export to ASEAN EV assembly plants.
- Wireless charging coil integration:Shielding-grade harness tapes with integrated ferrite particle loading address electromagnetic interference in 11kW inductive charging architectures.
- EU Green Deal circularity requirements:Design-for-recycling mandates favor mono-material tape constructions over multi-layer laminates, rewarding substrate suppliers with in-house polymerization capabilities.
Industry Challenges
- High-voltage safety engineer scarcity:OEM technical centers in Stuttgart and Wolfsburg compete for limited talent pools capable of validating 800V insulation systems against partial discharge failure modes.
- Multi-standard certification timelines:Simultaneous UL, VDE, and CQC qualification for a single tape SKU extends product launch windows by 14-18 months.
- Legacy harness design integration:12V auxiliary circuits in hybrid platforms require thermal class de-rating that conflicts with 800V primary harness specifications on shared production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Harness Tape Market |
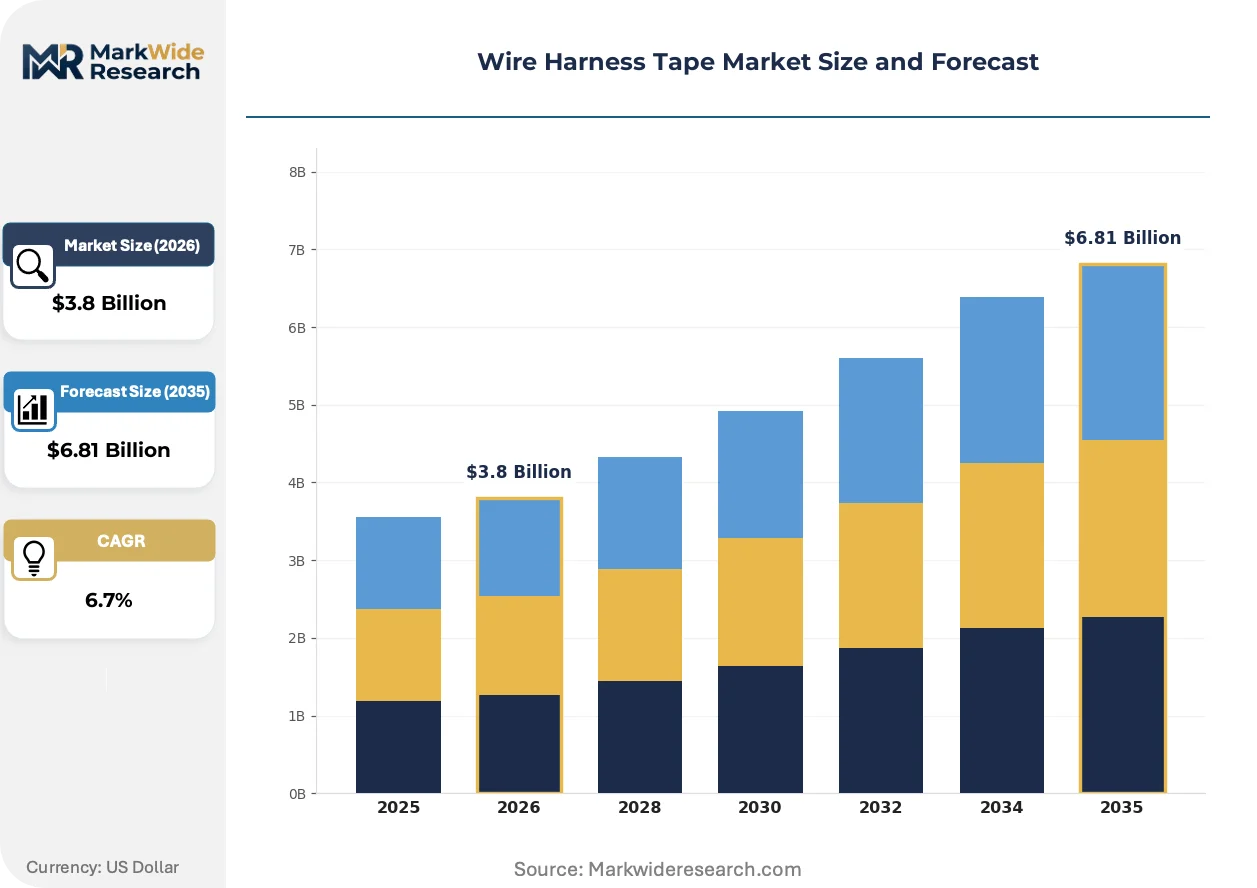
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Tape, Insulation Tape, PTFE Tape, Adhesive Tape Material: Polyester, PVC, Polypropylene, Cotton End User: Automotive, Aerospace, Electronics, Industrial Application: Wire Management, Surface Protection, Insulation, Bundling |
| Companies Covered | Saint-Gobain S.A., tesa SE, 3M Company, Berry Global, Intertape Polymer Group, Nitto Denko Corp., Beiersdorf AG, Scapa Group, Avery Dennison Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Harness Tape Market Strategic Shifts
Material science breakthroughs and regulatory pressure on halogen content are converging to redefine substrate-adhesive combinations across voltage classes. Technical differentiation now hinges on thermal endurance rather than mechanical bundling performance.
Polyimide film substrates with vapor-deposited aluminum oxide barrier layers are rendering obsolete traditional three-layer PET-PVC laminates in engine-compartment applications. BMW and Mercedes-Benz powertrain engineers specify these metallized tapes for 150°C continuous zones. The shift compresses addressable volume for commodity-grade converters while expanding margin pools for chemical vapor deposition equipment suppliers.
REACH Annex XVII restrictions on short-chain chlorinated paraffins entered full enforcement in January 2024, forcing reformulation of legacy PVC-based harness tapes across EU assembly plants. Compounders in Belgium and the Netherlands scrambled to certify calcium-zinc stabilizer alternatives. The regulatory friction most acutely affects aftermarket distributors holding pre-2023 inventory now unsalable in member states.
Automotive tier-one suppliers now mandate lot-level thermal aging traceability from tape vendors, replacing certificate-of-analysis documentation with blockchain-anchored test records. Yazaki and Aptiv procurement teams in Japan and Detroit pilot this verification layer. The behavioral shift concentrates contract awards toward integrated manufacturers with captive laboratory infrastructure rather than merchant converters.
Wire Harness Tape Market Segmentation
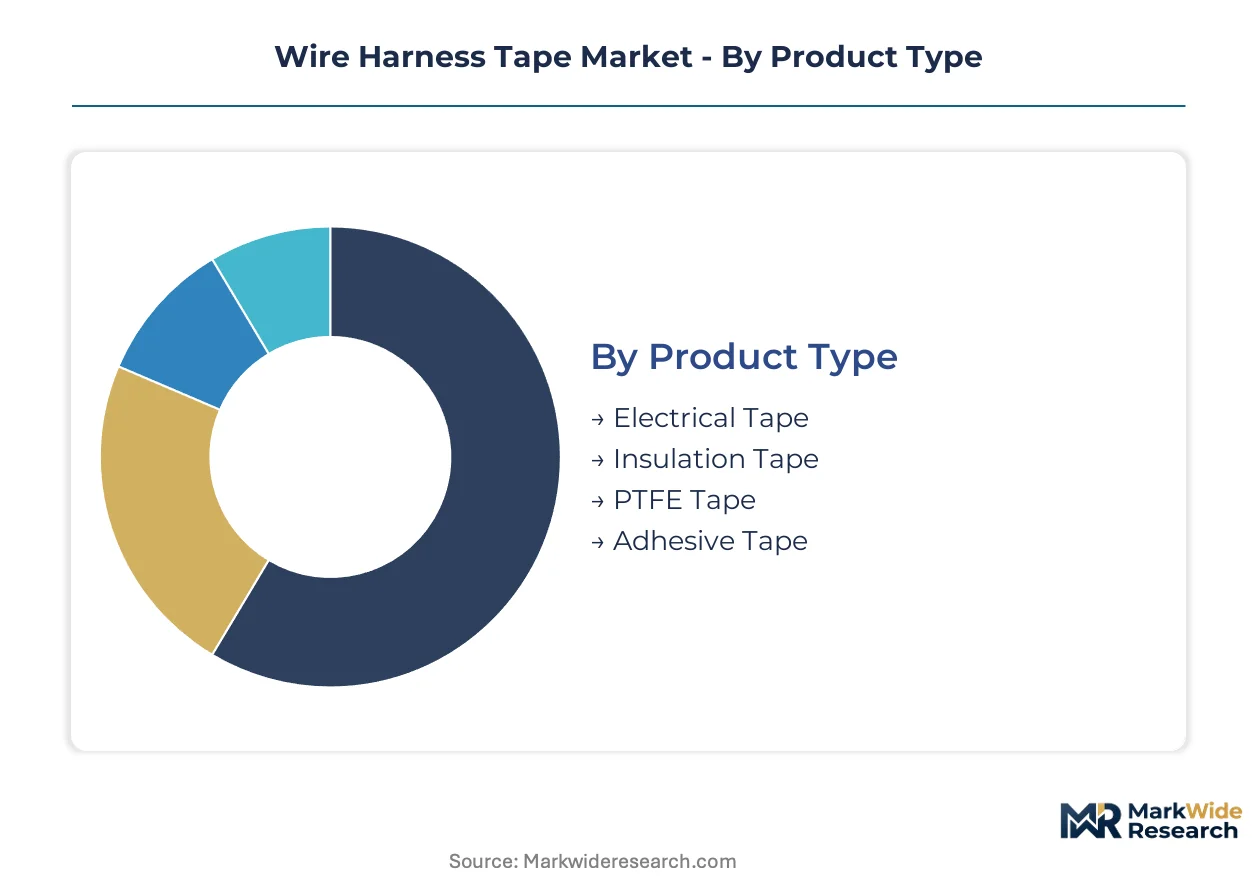
Wire harness tape segmentation reflects divergent thermal performance requirements across voltage classes and regulatory jurisdictions. Material chemistry and adhesive formulation choices directly determine qualification eligibility for specific OEM platforms.
Product Type:
End-use applications span from 12V auxiliary circuits to 800V battery-electric architectures, with each voltage tier demanding distinct dielectric ratings and flame-retardancy certifications.
- Electrical Tape:PVC or rubber-based substrates with pressure-sensitive adhesives dominate 12V automotive harness bundling. German OEM assembly lines in Stuttgart and Wolfsburg specify halogen-free formulations under EU REACH Annex XVII constraints.
- Insulation Tape:Polyester and polyimide backings rated for 130°C to 180°C continuous operation serve engine-compartment and high-voltage battery zones. Chinese EV manufacturers in Shenzhen prioritize smoke-density compliance under GB standards for these products.
- PTFE Tape:Fluoropolymer substrates withstand 260°C intermittent exposure in aerospace wire harnesses.
- Adhesive Tape:Acrylic and silicone pressure-sensitive systems bond to diverse cable jacket chemistries.
The dominant share belongs to electrical tape, while insulation tape is closing the gap fastest.
Material:
Substrate selection balances cost position against thermal class requirements, with commodity grades facing margin pressure from integrated Chinese producers.
- Polyester:PET film offers dimensional stability and moisture resistance at moderate cost, serving interior cabin harnesses where 105°C ratings suffice. Volume concentration in East Asian manufacturing corridors exposes converters to pricing pressure from captive extrusion capacity.
- PVC:Flexible vinyl compounds with plasticizer systems dominate aftermarket replacement demand. REACH restrictions on short-chain chlorinated paraffins forced Belgian and Dutch compounders to reformulate stabilizer packages.
- Polypropylene:Lower density and chemical resistance suit industrial cable management applications.
- Cotton:Woven fabric backings with rubber adhesives persist in legacy aerospace specifications.
Polyester film commands the largest volume position, though PVC retains aftermarket relevance despite regulatory headwinds.
End User:
Customer segments exhibit sharply diverging procurement patterns, from high-volume automotive contracts to low-volume aerospace qualification cycles.
- Automotive:Wire harness tape consumption concentrates in EV platform ramp-ups across Germany and China. OEM technical centers mandate lot-level thermal aging traceability, favoring suppliers with captive laboratory infrastructure.
- Aerospace:Polyimide and PTFE substrates with vapor-deposited barrier layers serve 150°C continuous zones in engine compartments. Boeing and Airbus qualification timelines extend 14-18 months for new tape SKUs.
- Electronics:Thin-film precision products address consumer device cable management.
- Industrial:Heavy-duty fabric and rubber tapes protect machinery wiring in harsh environments.
Automotive applications generate the dominant revenue pool, with aerospace representing the highest-margin segment per meter sold.
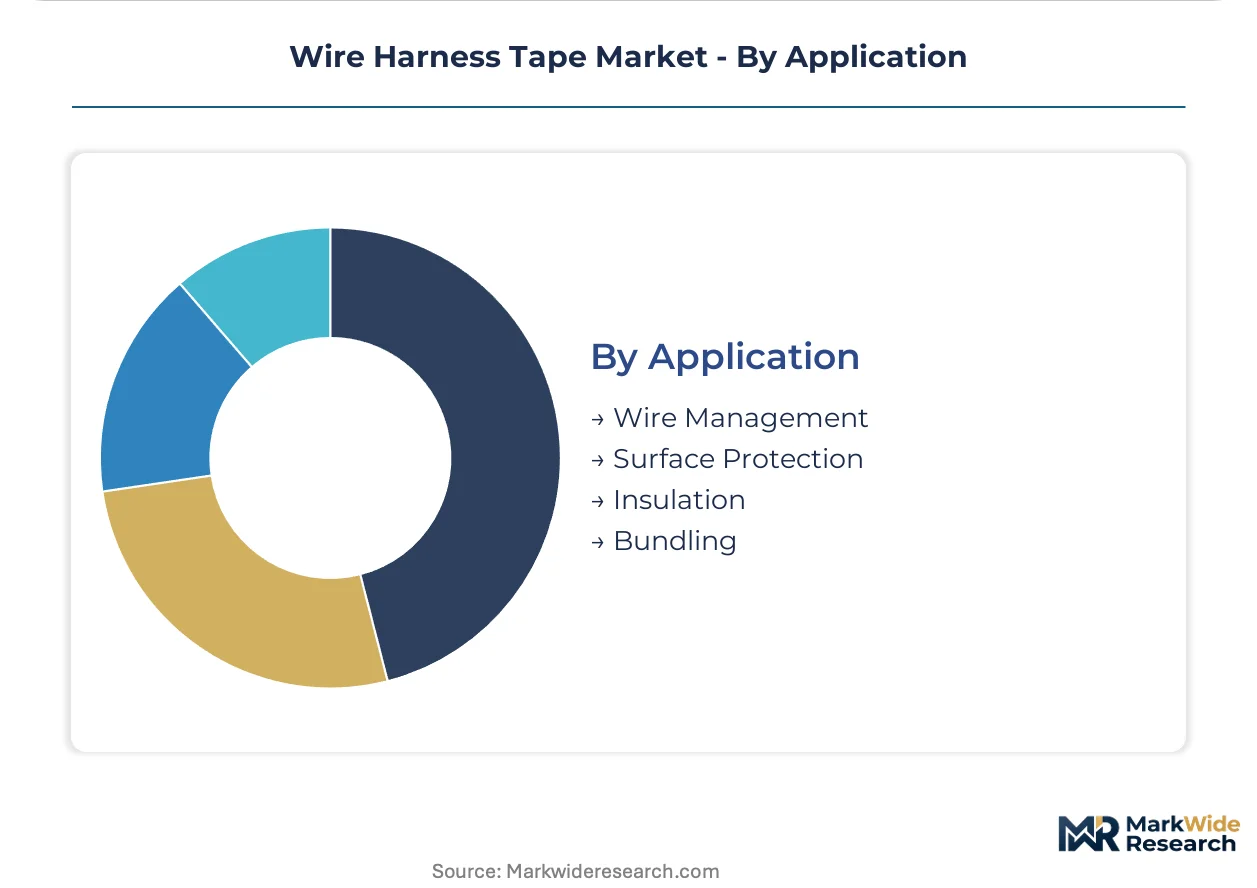
Application:
Functional requirements range from mechanical bundling to electromagnetic shielding, with specification complexity escalating alongside operating voltage.
- Wire Management:Routing and securing conductor bundles in confined engine compartments demands abrasion-resistant backings. BMW powertrain engineers specify metallized polyimide tapes for 150°C zones, displacing traditional PET-PVC laminates.
- Surface Protection:Temporary masking during assembly and transport prevents connector contamination. India's PLI scheme for automotive components attracts tape conversion investment in Chennai and Pune corridors for ASEAN export.
- Insulation:Dielectric integrity maintenance across temperature cycling.
- Bundling:Mechanical consolidation of multi-conductor harnesses.
Wire management captures the largest application share, while surface protection is expanding most quickly on EV platform assembly lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH Annex XVII restrictions on halogenated compounds anchor European demand dynamics, while China's GB standards and India's PLI scheme reshape supply chain geography across three continents.
China
Shenzhen and Shanghai EV manufacturers drive high-temperature insulation tape procurement for 800V battery compartments. GB standard certification mandates smoke-density thresholds that disqualify legacy PVC formulations. The Yangtze River Delta manufacturing corridor concentrates tape conversion capacity serving domestic OEMs and ASEAN export markets.
Germany
Stuttgart and Wolfsburg technical centers specify halogen-free harness tapes under EU REACH Annex XVII constraints for passenger vehicle platforms. The KBA enforces flame-retardancy compliance through type-approval protocols. Bavaria's automotive supplier ecosystem hosts captive laboratory infrastructure for lot-level thermal aging traceability.
United States
EPA and NHTSA flame-spread protocols constrain material selection for Detroit Three OEM assembly lines. The NHTSA administers toxicity emission standards through Federal Motor Vehicle Safety Standards. Michigan and Ohio manufacturing corridors anchor North American demand for fluoropolymer substrate integration.
India
Chennai and Pune production hubs attract tape conversion investment under the PLI scheme for automotive components. The BIS administers certification requirements for harness materials in domestic vehicle production. Maharashtra and Tamil Nadu corridors supply ASEAN EV assembly plants with tariff-advantaged capacity.
Japan
METI industrial policy supports polyimide substrate development for aerospace and high-voltage applications. The JIS standards framework governs thermal class ratings for domestic OEM supply contracts. The Chubu region around Nagoya concentrates precision film manufacturing for thin-film electronics channels.
Wire Harness Tape Market Competitive Environment
Capability concentration sits with integrated chemical producers possessing captive polymerization infrastructure; scale advantage sits with diversified adhesive converters serving multi-industry demand. The vendor base stratifies across three tiers: multinational diversified materials groups, regional specialty adhesive manufacturers, and commodity-grade merchant converters. Strategic moves center on backward integration into fluoropolymer resin supply and geographic expansion into India's PLI-advantaged manufacturing corridors.
Within the diversified multinational tier, 3M Company and Saint-Gobain S.A. exemplify integrated materials positioning spanning substrate chemistry through adhesive formulation. tesa SE and Nitto Denko Corp. represent regional specialists with deep vertical integration into precision coating capabilities. These four anchors demonstrate how competitive positioning depends on control over raw material supply chains and qualification relationships with automotive tier-one suppliers.
| Leading Market Players |
|---|
| Saint-Gobain S.A. |
| tesa SE |
| 3M Company |
| Berry Global |
| Intertape Polymer Group |
| Nitto Denko Corp. |
| Beiersdorf AG |
| Scapa Group |
| Avery Dennison Corp. |
| Others |
Value Chain & Pricing Dynamics
Fluoropolymer resin supply concentration in the US and Japan determines both the premium-mid-economy pricing differentiation across voltage tiers and the geographic shape of tape converter networks. This single-source dependency for PTFE substrates compresses margin pools for European and Chinese converters while amplifying pricing power for integrated resin producers.
Pricing Analysis
Price spreads between German and Chinese tape markets exceed 40 percent for equivalent thermal class ratings, driven by REACH certification overhead and logistics premiums. Pricing stratifies across premium, standard, and economy tiers based on halogen-free certification status and captive laboratory infrastructure. Cost compression in polyester and PVC grades is intensifying because Chinese integrated producers are expanding captive extrusion capacity. Aftermarket distributors exhibit highest price sensitivity, while aerospace OEMs prioritize thermal traceability over unit cost.
Supply Chain Analysis
Extended payment terms from automotive tier-one suppliers in Stuttgart and Wolfsburg strain working capital for merchant converters without supply-chain finance facilities. Raw material sourcing draws from fluoropolymer resin clusters in the US and Japan, polyimide film production in the Chubu region, and acrylic adhesive compounders in Belgium and the Netherlands. Single-source vulnerability for PTFE substrates exposes converters to semiconductor-industry demand spikes. Distribution runs through direct OEM contracts for automotive volumes and specialized distributors for aerospace qualification batches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against liquid injection-molded grommets and overmolded cable assemblies that eliminate tape wrapping steps in premium EV platforms above 400V.
For Market Incumbents: Pre-empt silicone adhesive substitution by accelerating solvent-free acrylic formulation certification for 180°C continuous operation. Secure backward integration into polyimide substrate supply through joint development agreements with Japanese film producers. Prioritize lot-level thermal aging traceability infrastructure to meet Yazaki and Aptiv procurement mandates. For New Entrants and Emerging Players: Pursue India's PLI-advantaged manufacturing corridors in Chennai and Pune to serve ASEAN EV assembly plants with tariff-competitive conversion capacity. Target wireless charging coil shielding applications with ferrite-loaded tape formulations where specification standards remain unsettled. Lead with design-for-recycling mono-material constructions to capture EU Green Deal circularity mandates ahead of integrated competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive polymerization capabilities and multi-standard certification infrastructure. Five-to-ten year viability hinges on 800V platform penetration rates and the pace of adhesive chemistry substitution. Watch for inflection in high-voltage safety engineer hiring velocity at Stuttgart and Wolfsburg technical centers as early demand signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyimide Substrates | Captive film supply secures margin pools as metallized tapes displace PET-PVC laminates at BMW. |
| Multi-Standard Certification Investment | Simultaneous UL, VDE, and CQC qualification compresses 14-18 month launch windows for new SKUs. |
| India PLI Corridor Capacity Buildout | Chennai and Pune conversion assets capture tariff advantages for ASEAN EV assembly plant supply. |
| Solvent-Free Acrylic Formulation Development | 180°C continuous operation ratings open aerospace and defense channels previously closed to tape solutions. |
| Blockchain-Anchored Thermal Traceability | Lot-level test records replace certificate-of-analysis documentation for Yazaki and Aptiv procurement teams. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and automotive production databases. Primary interviews engaged Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and adhesive formulation R&D directors. Secondary validation drew from IHS Markit vehicle registration data, ECHA REACH enforcement notices, and GB standard certification records. Bottom-up tape consumption modeling triangulated against top-down automotive wiring harness value chain estimates.
Forecast inputs include vehicle production volumes by propulsion architecture, content-per-vehicle assumptions for 12V auxiliary versus 800V primary harnesses, and thermal class rating migration curves. Segmentation dimensions span material chemistry, adhesive formulation, voltage class, and regional regulatory cluster. CAGRs derive from regression against historical tape consumption intensity and projected EV platform ramp schedules. Partial discharge failure mode prevalence in 800V architectures and high-voltage safety engineer scarcity at German technical centers inform scenario boundaries.
Macroeconomic conditions sit as an overlay; deviation in automotive capital expenditure cycles, battery-electric vehicle subsidy regimes, or fluoropolymer resin allocation priorities would shift the trajectory. Forecasts reflect documented assumptions regarding REACH Annex XVII enforcement continuity and GB standard smoke-density threshold stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Removal Strips Market
Tapes
Tape Applicator Machines Market
Tapes
Raffia Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Gaffers Tape Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Tape Unwinder Market
Tapes
Replica Tapes Market
Tapes
Thread Seal Tape Market
Tapes
Mastic Tapes Market
Tapes
Double Sided Tape Market
Tapes
Aluminum Foil Tape Market
Tapes
Pre-Printed Tape Market
Tapes
Thermal Release Tapes Market
Tapes
Nylon Cable Ties Market