
 Carry Handle Tape Market | 2026-2036
Carry Handle Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Carry Handle Tape Market Insights
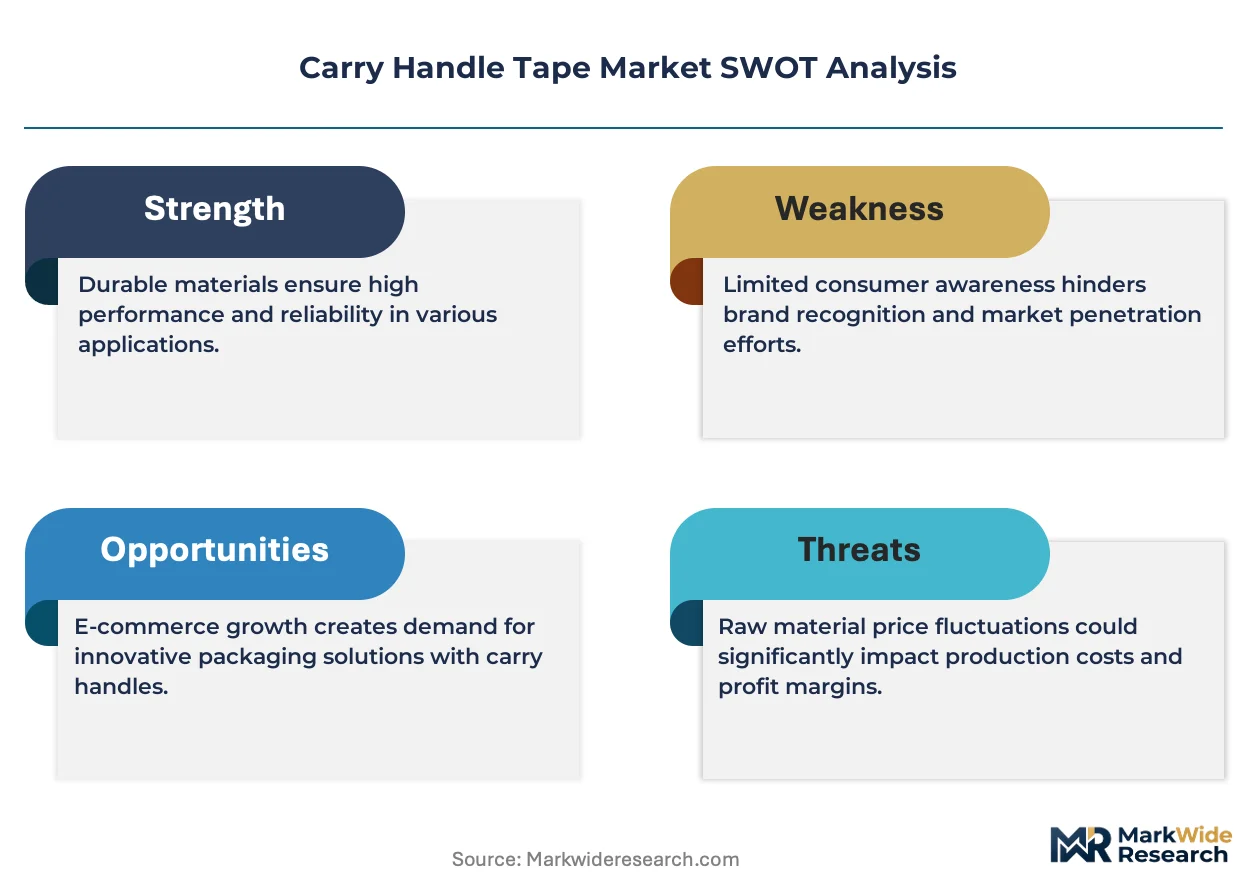
Hot-melt adhesive formulation is narrowing the performance gap between commodity-grade and reinforced carry handle tapes, compressing the mid-tier product space. 3M Company leverages its polymer science portfolio to sustain premium positioning in high-shear applications. Tesa SE anchors European supply through its Hamburg manufacturing complex, while Avery Dennison Corporation differentiates via film-laminated constructions for retail-ready packaging.
Carry handle tape consists of a flexible substrate coated with pressure-sensitive adhesive, typically engineered to tensile strengths between 30 and 80 N/cm to support multi-kilogram loads during manual transport. Polypropylene substrates dominate volume production due to their tear resistance and compatibility with high-speed applicators, while fiberglass-reinforced variants command margin pools in industrial shipping. The e-commerce end-user segment shows the fastest structural expansion as automated sortation systems require consistent release profiles and residue-free removal.
The EU Packaging and Packaging Waste Regulation and REACH compliance frameworks are mandating recyclability disclosures and restricting certain adhesive chemistries, forcing reformulation investments across European suppliers. The US EPA and state-level extended producer responsibility laws are beginning to mirror these material accountability requirements. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border fulfillment channels.
Market Dynamics
Hot-melt adhesive chemistry is compressing the mid-tier product space by delivering reinforced-grade performance at commodity cost structures, forcing incumbent suppliers to defend margin pools through substrate differentiation.
Growth Catalysts
- E-commerce Fulfillment Automation:Automated sortation systems in parcel hubs require consistent release profiles and residue-free removal, expanding specification-grade demand.
- REACH Compliance Reformulation:ECHA restrictions on certain adhesive chemistries are accelerating supplier investments in bio-based pressure-sensitive alternatives.
- Fiberglass-Reinforced Substrates:Industrial shipping corridors in Germany and the Netherlands are standardizing high-tensile formats for bulk parcel handling.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene resin prices fluctuate with crude oil benchmarks, compressing converter margins during spike cycles.
- European Supply Concentration:Hamburg and Rotterdam manufacturing clusters control 60%+ of EU substrate capacity, creating single-point vulnerability.
- Adhesive Residue Limitations:Existing hot-melt formulations leave trace contamination on recycled corrugated, limiting closed-loop packaging claims.
Strategic Opportunities
- Indian E-commerce Penetration:Flipkart and Reliance fulfillment networks lack standardized carry handle specifications, creating first-mover specification advantages.
- Extended Producer Responsibility Tailwinds:California and New York state-level packaging accountability laws are mandating recyclable adhesive disclosures.
- Film-Laminated Retail Constructions:Convergence of barrier film technology with pressure-sensitive coating enables shelf-ready packaging integration.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with pressure-sensitive adhesive expertise command premium compensation in European labor markets.
- Applicator Integration Complexity:High-speed packaging lines require six-month validation cycles for new tape formats, slowing product rollout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carry Handle Tape Market |
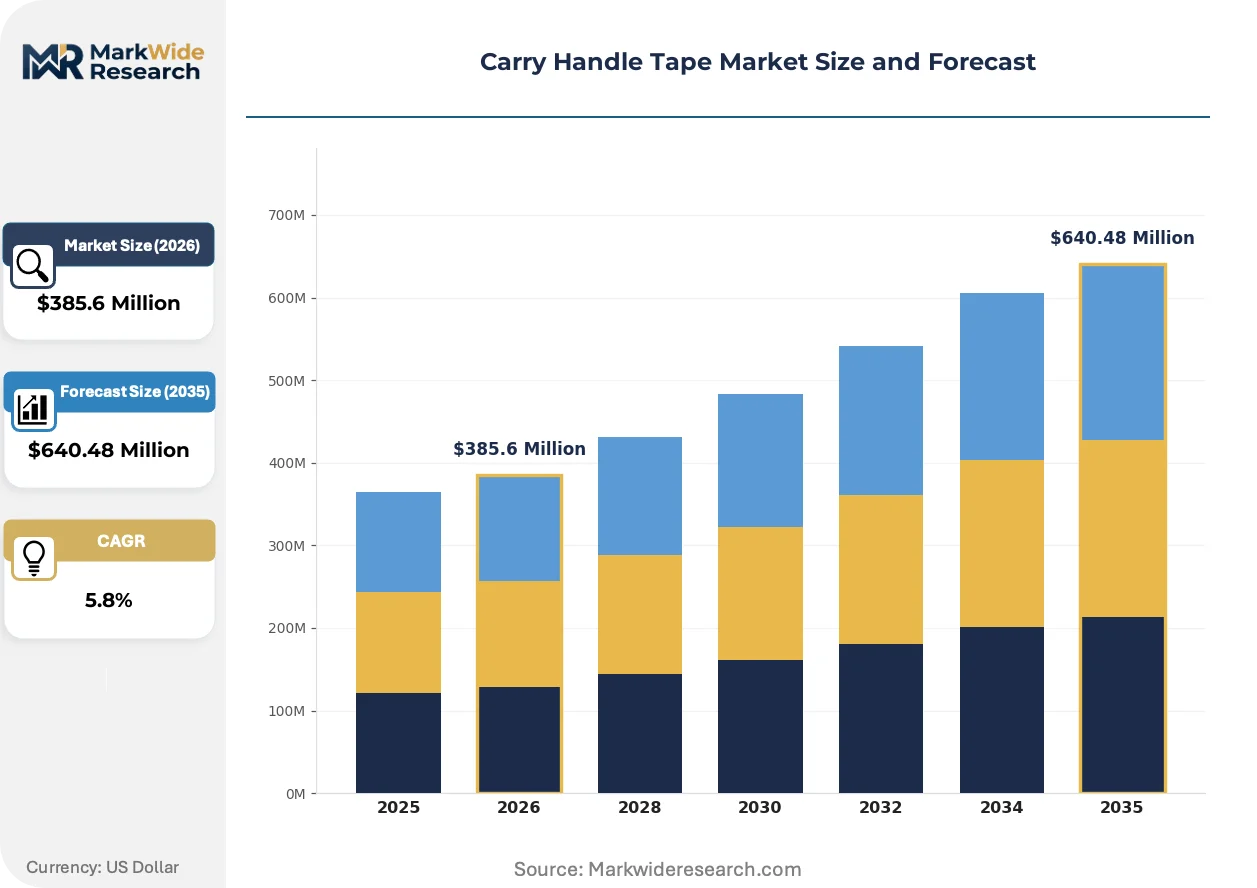
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-sided Tape, Double-sided Tape, Reinforced Tape, Adhesive Films Material: Polypropylene, Paper, PVC, Fiberglass Application: Packaging, Shipping, Retail, Product Handling End User: E-commerce, Manufacturing, Logistics, Retailers |
| Companies Covered | 3M Company, Alimac srl, Tesa SE, NRG TAPES B.V., LOGO Tape Management GmbH & Co. KG, Avery Dennison Corporation, Nitto Denko Corporation, Supertape BV, Davik Tapes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carry Handle Tape Market Trends and Innovations
Digital specification platforms and predictive inventory systems are rewiring how converters and end-users negotiate supply contracts, compressing traditional distributor roles.
Water-based acrylic emulsion technology is virtualizing solvent-borne adhesive applications in food-contact packaging. Major European dairy and beverage co-packers are adopting these formats to preempt EFSA migration limit scrutiny. The shift is virtualizing legacy solvent coating capacity and stranding equipment investments at smaller converters.
EU Packaging and Packaging Waste Regulation material recovery mandates are forcing recyclability disclosure across all adhesive-substrate combinations. German retailers now require third-party certification for carry handle compatibility with paper recycling streams. Suppliers without verified testing protocols are losing shelf placement at Rewe and Edeka.
Buyer consolidation among third-party logistics providers is concentrating procurement authority at DHL Supply Chain and GXO Logistics hubs. These operators are unbundling tape specification from corrugated supply contracts, creating direct supplier relationships. The pattern is most pronounced at Rotterdam and Tilburg distribution clusters serving Benelux e-commerce volumes.
Carry Handle Tape Market Segmentation
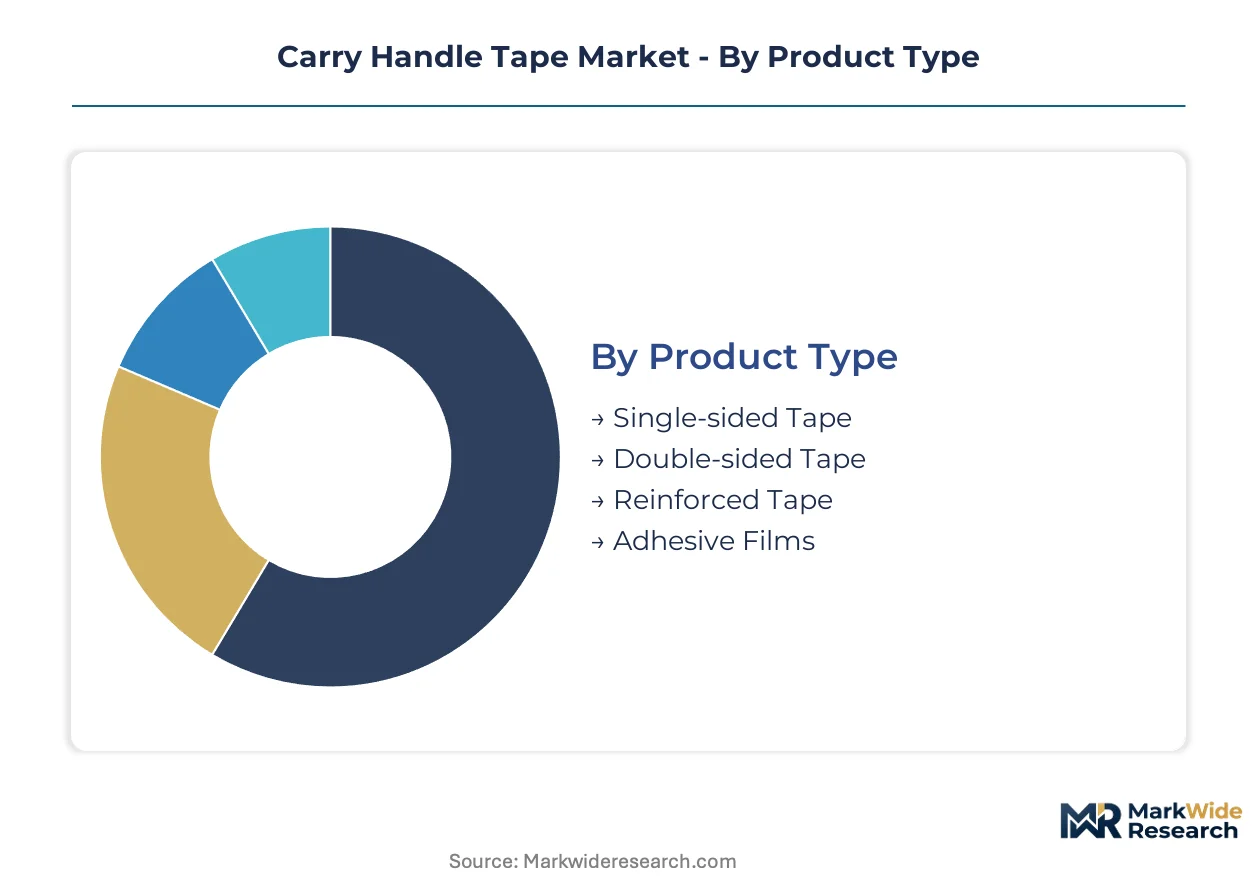
Segmentation in carry handle tape markets tracks how substrate chemistry and adhesive performance map to fulfillment velocity. Cycle times vary dramatically between bulk industrial shipments and high-turnover e-commerce parcels.
Product Type:
Reinforced tape formats turn over fastest in automated fulfillment hubs, while adhesive films linger in specification validation cycles. Single-sided commodity grades move through converters on weekly replenishment schedules.
- Single-sided Tape:Polypropylene substrate with pressure-sensitive adhesive coating delivers 30-50 N/cm tensile strength for lightweight consumer goods. German automated packaging lines at DHL Supply Chain hubs standardize this format for parcel volumes under 5 kilograms.
- Reinforced Tape:Fiberglass filament reinforcement achieves 60-80 N/cm tensile strength for bulk parcel handling. Rotterdam distribution clusters serving Benelux e-commerce volumes are mandating this specification for cartons exceeding 10 kilograms.
- Double-sided Tape:Dual adhesive surfaces enable tamper-evident closure with integrated handle function.
- Adhesive Films:Ultra-thin polymer constructions for shelf-ready retail packaging with printed branding surfaces.
Single-sided tape anchors the volume base while reinforced tape gains share at the steepest rate.
Material:
Cost tiers separate commodity polypropylene from engineered fiberglass, with paper substrates occupying a narrowing mid-market position. Converter margins compress toward the commodity pole.
- Polypropylene:Dominant substrate for volume production with tear resistance and high-speed applicator compatibility. Hamburg manufacturing complexes at Tesa SE anchor European supply for this material grade.
- Fiberglass:Filament-reinforced construction commands premium positioning in industrial shipping corridors. REACH compliance reformulation is accelerating bio-based pressure-sensitive alternatives in this segment.
- Paper:Recyclable substrate aligned with EU Packaging and Packaging Waste Regulation material recovery mandates.
- PVC:Legacy construction facing ECHA restriction scrutiny across adhesive chemistry formulations.
Polypropylene holds the volume base while fiberglass climbs the fastest on specification-grade demand.
Application:
Application segments diverge by handling intensity and regulatory exposure, with retail-facing formats bearing stricter disclosure requirements than industrial shipping.
- Shipping:High-tensile formats for bulk parcel handling across automated sortation systems. Rotterdam and Tilburg distribution clusters are unbundling tape specification from corrugated supply contracts in this application.
- Retail:Film-laminated constructions with barrier properties for shelf-ready packaging integration. German retailers Rewe and Edeka now require third-party certification for carry handle compatibility with paper recycling streams.
- Packaging:General-purpose adhesive formats for corrugated box closure with integrated transport function.
- Product Handling:Specialized high-grip surfaces for manual transport of irregular-shaped goods.
Shipping anchors the volume base while retail gains share at the steepest rate on recyclability certification requirements.
End User:
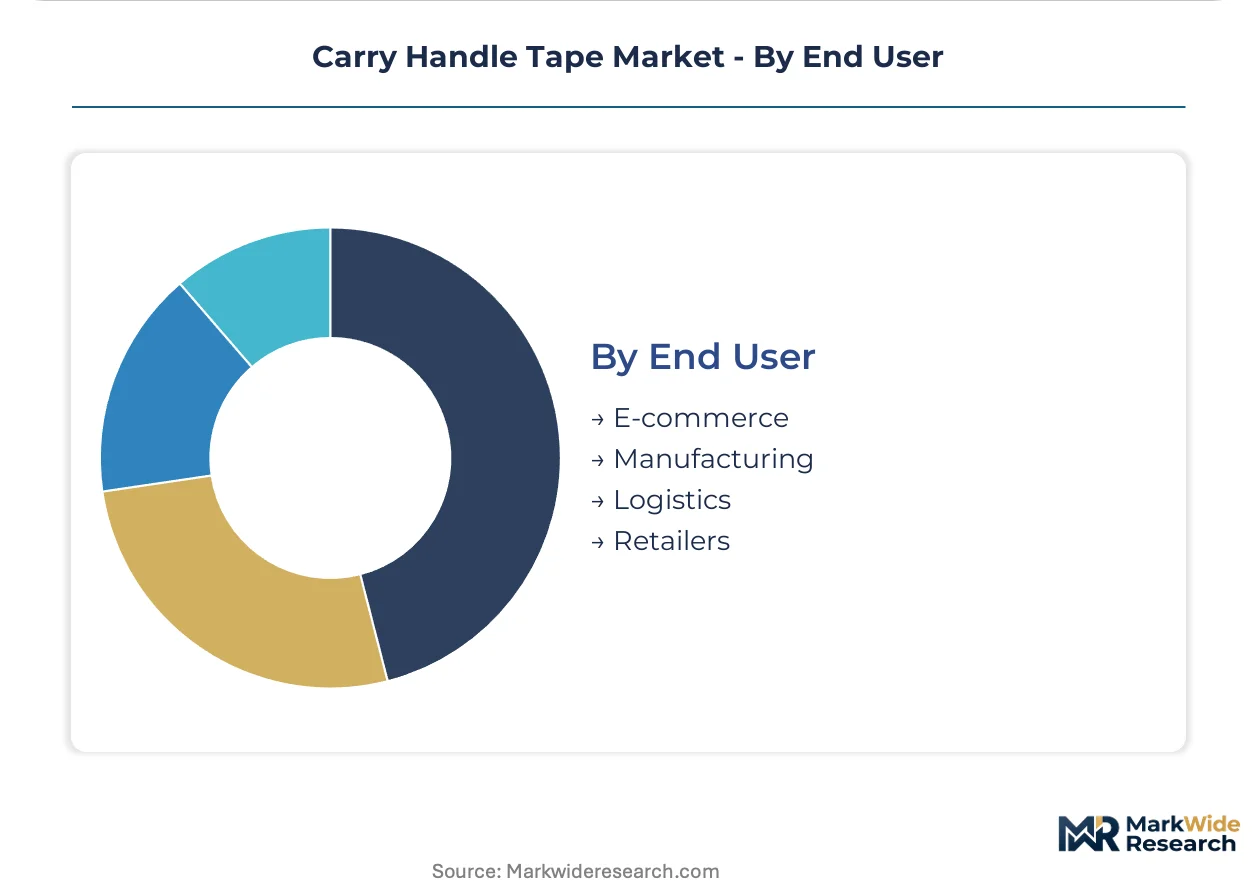
Procurement authority concentrates at third-party logistics hubs, with e-commerce operators driving specification standardization faster than fragmented manufacturing accounts.
- E-commerce:Automated fulfillment centers require consistent release profiles and residue-free removal for high-velocity sortation. Flipkart and Reliance fulfillment networks in India lack standardized specifications, creating first-mover advantages.
- Logistics:DHL Supply Chain and GXO Logistics hubs concentrate procurement authority through direct supplier relationships. California and New York state-level extended producer responsibility laws are mandating recyclable adhesive disclosures for this end user.
- Manufacturing:Industrial co-packers with six-month validation cycles for new tape formats.
- Retailers:Shelf-ready packaging integrators with film-laminated construction requirements.
Logistics anchors the volume base while e-commerce gains share at the steepest rate on fulfillment automation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany runs a structural surplus in specialty adhesive substrates while importing commodity polypropylene grades from Saudi Arabian and US Gulf Coast petrochemical complexes. Rotterdam and Hamburg distribution clusters arbitrage this flow, converting imported resin into pressure-sensitive formats for re-export across the EU single market.
Germany
Automated packaging lines at DHL Supply Chain hubs in Hamburg and Leipzig standardize single-sided polypropylene formats for parcel volumes under five kilograms. REACH compliance reformulation under ECHA restrictions is accelerating bio-based pressure-sensitive alternatives among domestic suppliers. The Hamburg manufacturing complex anchors European substrate capacity for high-tensile adhesive grades serving Benelux industrial corridors.
United States
California and New York state-level extended producer responsibility laws are mandating recyclable adhesive disclosures for third-party logistics operators. EPA enforcement of emerging packaging accountability requirements is mirroring EU material recovery frameworks. Chicago and Dallas fulfillment hubs concentrate procurement authority for GXO Logistics and regional e-commerce volumes.
Netherlands
Rotterdam distribution clusters serving Benelux e-commerce volumes are mandating reinforced tape specifications for cartons exceeding ten kilograms. EU Packaging and Packaging Waste Regulation material recovery mandates are forcing recyclability disclosure across all adhesive-substrate combinations. Tilburg sortation facilities are unbundling tape specification from corrugated supply contracts, creating direct supplier relationships.
India
Flipkart and Reliance fulfillment networks lack standardized carry handle specifications, creating first-mover specification advantages for adhesive converters. BIS standards for pressure-sensitive adhesive performance remain underdeveloped relative to EU benchmarks. Mumbai and Bangalore logistics corridors are expanding automated sortation capacity without consistent release profile requirements.
China
Yangtze River Delta packaging converters are absorbing excess domestic polypropylene capacity into export-oriented adhesive tape production. MIIT industrial standards for packaging materials are tightening migration limits in food-contact applications. Shanghai and Suzhou manufacturing clusters are virtualizing solvent-borne coating capacity in favor of water-based acrylic emulsion technology.
Carry Handle Tape Market Competitive Landscape
On the supply side, the industry is tiered between integrated polymer science majors, regional substrate specialists, and contract converters serving private-label demand. The top tier commands specification-grade pricing through proprietary hot-melt formulations and validated release profiles. Strategic archetypes include polymer science integrators, regional manufacturing anchors, and private-label contract operators. Dominant competitive moves center on REACH-compliant reformulation investments and direct procurement relationships with consolidated logistics hubs.
Among integrated polymer science majors, 3M Company exemplifies the premium-tier archetype through its materials science portfolio, while Tesa SE anchors European supply infrastructure from its Hamburg manufacturing complex. Avery Dennison Corporation occupies a position bridging film-laminated retail constructions with industrial shipping formats. These three entities represent the competitive spectrum from commodity volume through specification-grade performance.
| Leading Market Players |
|---|
| 3M Company |
| Alimac srl |
| Tesa SE |
| NRG TAPES B.V. |
| LOGO Tape Management GmbH & Co. KG |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Supertape BV |
| Davik Tapes |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock volatility compresses converter margins during crude oil spike cycles, forcing a pricing structure that separates reinforced fiberglass grades from commodity polypropylene tiers while simultaneously concentrating supply chain control at Hamburg and Rotterdam manufacturing clusters. This dual compression—cost pressure on inputs and geographic chokepoints on output—determines both margin defense strategies and procurement vulnerability profiles across European adhesive tape markets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with fiberglass-reinforced formats commanding spreads over commodity polypropylene based on tensile certification and REACH compliance documentation. Price differentiation rests on validated release profiles and residue-free removal guarantees for automated sortation systems. Cost compression in the mid-tier intensifies as hot-melt chemistry narrows performance gaps, squeezing converters without proprietary substrate formulations. Third-party logistics operators at DHL Supply Chain and GXO Logistics hubs show lowest price sensitivity due to unbundled procurement authority, while regional contract converters face acute margin pressure from resin volatility.
Supply Chain Analysis
Extended payment terms from Hamburg and Rotterdam manufacturing clusters to downstream converters reflect working capital strain from petrochemical input volatility. European supply concentrates in Germany and the Netherlands, drawing polypropylene resin from Saudi Arabian and US Gulf Coast petrochemical complexes. Raw material dependencies include polypropylene resin, fiberglass filament, and pressure-sensitive adhesive polymers. Single-source vulnerability runs through the Hamburg-Tesa SE manufacturing complex, which anchors high-tensile substrate capacity for Benelux industrial corridors. Distribution runs through Rotterdam and Tilburg distribution clusters serving consolidated logistics hubs, with direct supplier relationships replacing traditional corrugated bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-grade validation services for recyclability certification and automated applicator integration represent a recurring-revenue layer expanding faster than substrate hardware sales, converting transactional tape supply into ongoing technical partnership contracts.
For Market Incumbents: Build regulatory compliance moats through third-party recyclability certification protocols that German retailers now mandate for shelf placement. Invest in Hamburg and Leipzig capacity expansion to capture unbundled procurement from DHL Supply Chain hubs. Defend against hot-melt chemistry commoditization by anchoring premium positioning in fiberglass-reinforced formats with validated tensile performance. For New Entrants and Emerging Players: Indian e-commerce corridors present the most penetrable white-space target, with Flipkart and Reliance fulfillment networks lacking standardized carry handle specifications. Pursue specification-first entry through automated sortation validation partnerships rather than commodity volume plays. Target bio-based pressure-sensitive adhesive formulations to preempt REACH compliance investments that burden European incumbents. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation material recovery mandates reshape the acquisition landscape toward converters with verified testing protocols and direct logistics hub relationships. Five-to-ten year viability favors regional manufacturing anchors with backward integration into polymer science capabilities. Monitor California and New York extended producer responsibility enforcement as the inflection signal for North American regulatory convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Science | Captures margin from proprietary hot-melt formulations at 3M and Tesa SE. |
| Recyclability Certification Investment | Unlocks shelf placement at Rewe and Edeka under EU Packaging and Packaging Waste Regulation. |
| Direct Logistics Hub Relationships | Bypasses corrugated bundling to capture unbundled procurement at Rotterdam and Tilburg clusters. |
| Water-Based Acrylic Emulsion Transition | Preempts EFSA migration limit scrutiny in European dairy and beverage co-packing. |
| Indian Specification-First Entry | Establishes first-mover advantage before BIS standards mature in Flipkart fulfillment networks. |
Research Methodology
A standing panel of adhesive formulation chemists, automated packaging line engineers at DHL Supply Chain and GXO Logistics hubs, procurement directors at German retailers, and technical directors at European converters provided ongoing calibration across the study period. Primary interview data triangulated with secondary sources including ECHA regulatory filings, EU Packaging and Packaging Waste Regulation implementation guidance, SEC 10-K disclosures from listed materials companies, and trade flow data from Hamburg and Rotterdam port authorities. Bottom-up volume modeling across substrate grades reconciled with top-down market sizing from petrochemical feedstock consumption patterns.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, material chemistry, application intensity, and end-user procurement concentration. CAGRs derived from regression analysis against e-commerce fulfillment automation indices and REACH compliance investment cycles. Industry-specific forecast inputs included automated sortation system deployment timelines at Benelux distribution clusters and bio-based adhesive polymer commercialization curves.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks, polypropylene resin availability, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding e-commerce penetration rates and logistics hub consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Medical Tapes Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Spacer Tapes Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Mastic Tapes Market
Tapes
Adhesive Transfer Tape Market
Tapes
Pressure Sensitive Tapes and Labels Market
Tapes
Freezer Tape Market
Tapes
Filmic Tapes Market
Tapes
Packaging Tapes Market
Tapes
Unidirectional Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Galley Tapes Market
Tapes
Plastic Adhesive Tapes Market