
 Tissue Tapes Market | 2026-2036
Tissue Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Tapes Market Outlook
Modular tape configurations are restructuring how industrial buyers specify adhesive systems, shifting from single-product orders to bundled substrate-adhesive-liner combinations that reduce sourcing complexity. 3M leverages its polymer science portfolio to sustain leadership in medical-grade laminates, while Nitto Denko Corporation anchors Asian electronics assembly demand through high-precision die-cut formats. Tesa SE competes aggressively in European automotive interior bonding, where OEMs prioritize consistent peel-strength performance across temperature cycles.
Tissue tapes are non-woven fabric carriers impregnated with pressure-sensitive adhesives, typically manufactured through hot-melt coating or solvent-based saturation processes to achieve controlled thickness between 0.05 mm and 0.25 mm; they serve primarily as conformable bonding and cushioning interfaces in medical, electronics, and packaging applications. Medical Grade tapes command premium positioning due to ISO 10993 biocompatibility certification requirements and single-use sterility protocols, while Industrial Grade volumes dominate absolute consumption through corrugated box sealing and temporary surface protection in manufacturing facilities. Pressure Sensitive adhesives lead technology selection for room-temperature tack applications, though Water-Based formulations are gaining converter preference as volatile organic compound regulations tighten across multiple jurisdictions.
FDA enforces biocompatibility and sterility standards for medical tape applications in the United States, while REACH restricts hazardous substance content in European adhesive imports, and China's GB standards govern solvent residue limits in domestic tape production. These frameworks elevate compliance costs for smaller converters but create structural advantages for integrated manufacturers with in-house analytical laboratories and regulatory affairs capacity. Stakeholders must monitor evolving extended producer responsibility mandates in the European Union and potential adhesive chemistry restrictions under the EU Green Deal's chemicals strategy for sustainability.
Market Dynamics
Medical-grade tape procurement from German and Japanese automotive OEMs is compressing supplier qualification timelines while tightening substrate purity specifications beyond legacy industrial grades.
Growth Catalysts
- REACH substrate mandates:ECHA restrictions on hazardous adhesive components are accelerating converter investment in analytical laboratory capacity across European manufacturing corridors.
- Wearable device assembly:Medical electronics manufacturers in Japan are expanding die-cut tape specifications for skin-contact sensor mounting.
- Hot-melt coating advances:Solvent-free saturation processes are displacing legacy solvent-based methods in China's eastern converter clusters.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and synthetic rubber input costs swing with crude oil indices, compressing margin predictability for mid-tier converters.
- Single-source liner supply:Silicone-coated release liner production concentrates among three European suppliers, creating bottleneck risk for just-in-time medical tape orders.
- ISO 10993 certification timelines:Cytotoxicity and sensitization testing protocols extend product launch cycles by 14-18 months for new medical-grade formulations.
Strategic Opportunities
- Water-based adhesive convergence:Volatile organic compound regulations in California and EU member states are unifying converter R&D priorities around aqueous polymer systems.
- Extended producer responsibility:EU Green Deal packaging mandates are creating service-revenue streams for tape manufacturers offering take-back logistics.
- India medical device assembly:CDSCO regulatory harmonization with ISO 13485 is opening import substitution opportunities for domestic tape converters.
Industry Challenges
- Polymer science talent scarcity:Pressure-sensitive adhesive formulation expertise concentrates among retiring specialists in German and Japanese chemical conglomerates.
- Cleanroom capacity expansion:ISO Class 8 manufacturing environments for medical-grade tapes demand capital commitments exceeding mid-tier converter balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Tapes Market |
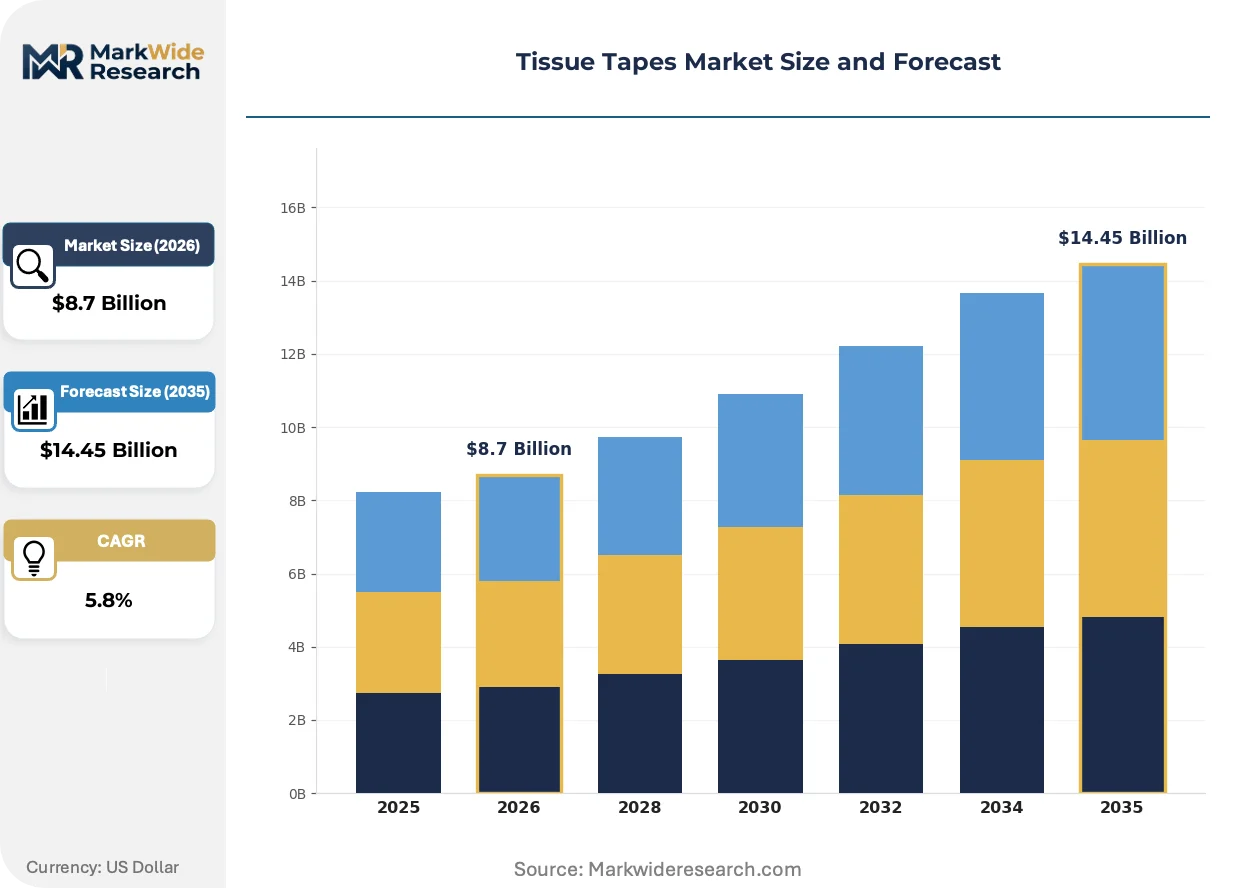
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Grade, Industrial Grade, Craft Grade, Specialty Tapes Application: Wound Care, Packaging, Crafting, Insulation End User: Hospitals, Clinics, Manufacturing, Retail Adhesive Type: Pressure Sensitive, Water-Based, Solvent-Based, Hot Melt |
| Companies Covered | 3M, Tesa SE, Nitto Denko Corporation, Lohmann, LINTEC, Avery Dennison Corporation, Scapa Group Plc, Saint-Gobain, Ritu Raj Tapes Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Tapes Market Strategic Shifts
Adhesive system specification is migrating from component sourcing to bundled substrate-adhesive-liner configurations, compressing supplier relationship structures and elevating technical service expectations.
Hot-melt coating technology is unifying medical and electronics-grade production lines through precise temperature-controlled saturation that maintains thickness tolerances within 0.01 mm. German automotive OEMs are qualifying these unified-process tapes for interior bonding applications previously reserved for solvent-coated alternatives. The structural consequence is compressing capital equipment requirements for converters serving multiple end-use verticals.
REACH Annex XVII restrictions on phthalate plasticizers are forcing adhesive reformulation across European medical device supply chains. Industrial consequence includes accelerated migration to bio-based tackifier resins derived from rosin esters and hydrogenated hydrocarbons. Medical-grade laminates face the steepest compliance cost escalation, with smaller converters outsourcing analytical testing to certified laboratories.
Buyer specification behavior is consolidating around performance-based qualification protocols that compress multi-year supplier contracts into annual technical reviews. Electronics assemblers in South Korea and Taiwan are displacing traditional distributor relationships with direct converter partnerships supported by localized die-cutting operations. This pattern is most visible in semiconductor packaging facilities where tape-to-tape bonding precision requirements exceed standard distribution channel technical capabilities.
Tissue Tapes Market Segmentation
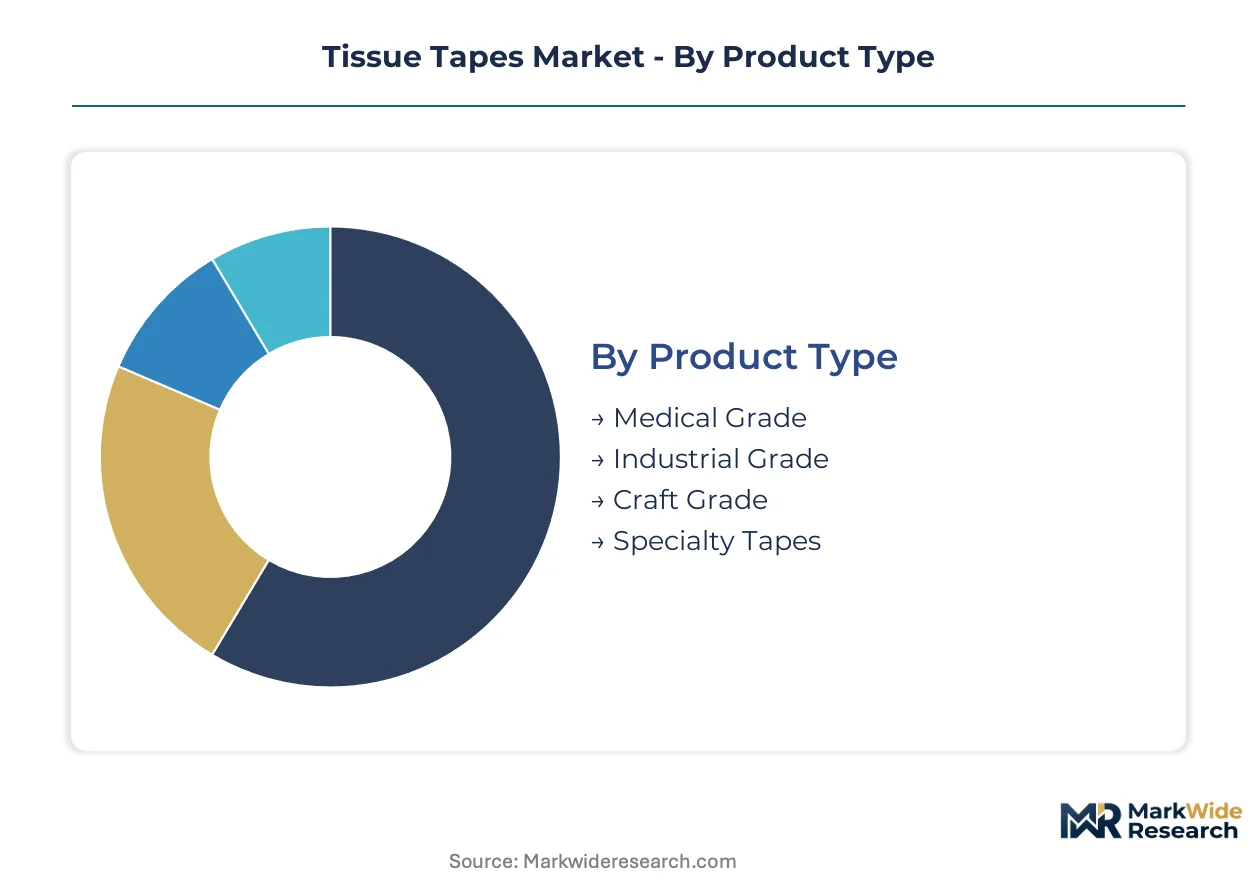
Tissue tape buyers specify products through layered qualification protocols where adhesive chemistry, carrier construction, and end-use certification requirements intersect. Segmentation clarity determines converter capital allocation and regulatory compliance pathways across medical, industrial, and consumer verticals.
Product Type:
ISO 10993 biocompatibility certification separates medical-grade specifications from industrial alternatives, with FDA and EMA submission requirements driving formulation purity thresholds.
- Medical Grade:Non-woven carriers saturated with hypoallergenic acrylic or silicone adhesives meeting cytotoxicity and sensitization protocols. German and Japanese automotive OEMs are expanding procurement for wearable device assembly, compressing supplier qualification timelines while tightening substrate purity beyond legacy industrial grades.
- Industrial Grade:Corrugated box sealing and temporary surface protection dominate volume consumption through hot-melt or solvent-based saturation processes. China's eastern manufacturing corridor anchors converter capacity expansion for pressure-sensitive laminates serving packaging and assembly operations.
- Craft Grade:Lower-tack formulations prioritize repositionability and clean removal for consumer applications.
- Specialty Tapes:Die-cut configurations for electronics bonding and semiconductor packaging with thickness tolerances within 0.01 mm.
Leading the category by volume: Industrial Grade. Growing fastest: Medical Grade.
Application:
End-use performance requirements dictate substrate weight, adhesive coat weight, and release liner specification across divergent operating environments.
- Wound Care:Breathable non-woven carriers with porous adhesive patterns enable moisture vapor transmission rates critical for skin-contact applications. Japanese medical electronics manufacturers specify die-cut formats for sensor mounting, expanding precision die-cutting demand.
- Packaging:High-tack hot-melt adhesives on crepe paper carriers secure corrugated closure in high-speed fulfillment operations. REACH compliance costs elevate substrate and adhesive purity requirements for European converter operations.
- Crafting:Repositionable adhesives on lightweight tissue carriers serve hobby and educational markets.
- Insulation:Multi-layer laminates combining tissue carriers with foil or film substrates for thermal and electrical barrier applications.
Dominant by volume: Packaging. Steepest expansion trajectory: Wound Care.
End User:
Procurement scale and technical service intensity vary sharply between institutional healthcare buyers and distributed retail channels.
- Hospitals:Centralized purchasing departments enforce ISO 13485 supplier certification and lot-level traceability for surgical and wound care applications. FDA biocompatibility standards in the United States and MDR requirements in Europe elevate compliance documentation burdens.
- Clinics:Smaller order quantities with accelerated delivery requirements favor distributors over direct converter relationships.
- Manufacturing:Automotive and electronics assemblers specify performance-based qualification protocols with annual technical reviews replacing multi-year contracts.
- Retail:Price-sensitive consumer channels drive volume through private-label and branded craft tape offerings.
Largest procurement scale: Manufacturing. Fastest qualification compression: Hospitals.
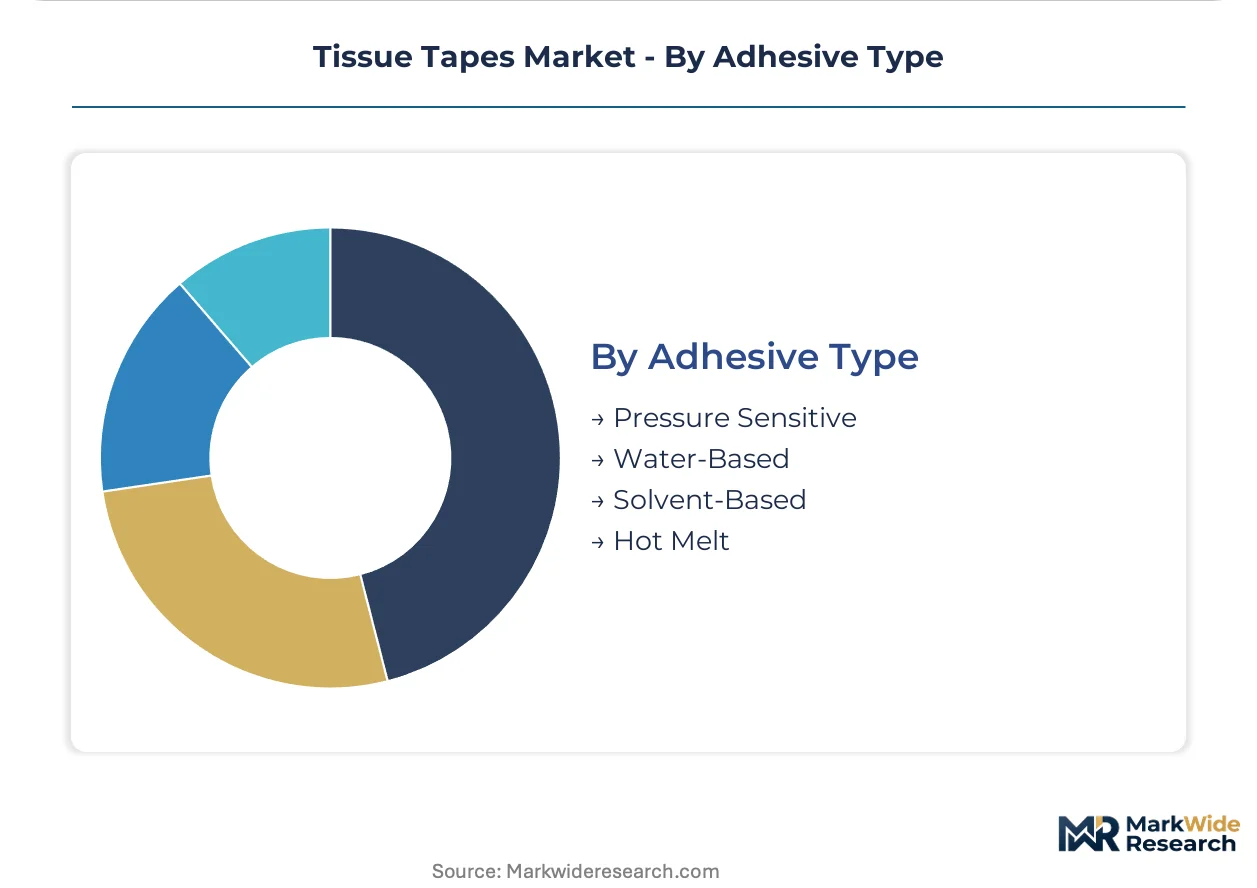
Adhesive Type:
Environmental regulatory pressure is restructuring technology selection priorities across converter R&D programs.
- Pressure Sensitive:Room-temperature tack without activation dominates medical and electronics bonding applications. Acrylic emulsion and solvent-borne systems compete on adhesion-to-substrate specificity and aging performance.
- Water-Based:Aqueous polymer systems gain converter preference as California Air Resources Board and EU VOC regulations tighten. Volatile organic compound restrictions unify R&D priorities across North American and European manufacturing corridors.
- Solvent-Based:Legacy saturation methods face displacement in China's eastern converter clusters where hot-melt coating advances reduce solvent residue compliance burdens.
- Hot Melt:Solvent-free saturation processes maintain thickness tolerances within 0.01 mm while unifying medical and electronics-grade production lines.
Technology leadership: Pressure Sensitive. Gaining share fastest: Water-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor concentrates converter capacity expansion, where Yangtze River Delta special economic zones accelerate pressure-sensitive laminate production for export-oriented electronics assembly.
China
Hot-melt coating advances displace solvent-based saturation in Suzhou and Shanghai converter clusters, reducing GB standards compliance burdens for solvent residue limits. NMPA-aligned medical device assembly lines expand procurement of die-cut tissue formats for wearable sensor mounting. The Pearl River Delta anchors packaging-grade volume production serving Southeast Asian fulfillment networks.
Germany
Automotive OEMs in Stuttgart and Munich compress supplier qualification timelines for medical-grade tape procurement in wearable device assembly. REACH Annex XVII phthalate restrictions force adhesive reformulation across Baden-Württemberg medical device supply chains. The KBA's materials certification protocols elevate substrate purity specifications beyond legacy industrial grades for interior bonding applications.
United States
FDA biocompatibility standards tighten substrate and adhesive purity requirements for wound care and surgical applications in Minnesota and Massachusetts medical device corridors. California Air Resources Board VOC regulations accelerate water-based adhesive R&D priorities among domestic converters. The Pacific Northwest semiconductor packaging facilities specify precision die-cut formats with thickness tolerances exceeding standard distribution capabilities.
Japan
METI-industrial policy supports medical electronics manufacturers in Tokyo and Osaka expanding die-cut tape specifications for skin-contact sensor mounting. PMDA submission requirements extend ISO 10993 certification timelines, compressing product launch cycles for new formulations. The Chubu region's automotive electronics assemblers qualify unified-process hot-melt tapes for interior bonding previously reserved for solvent-coated alternatives.
India
CDSCO regulatory harmonization with ISO 13485 opens import substitution opportunities for domestic tape converters in Maharashtra and Gujarat medical device clusters. PLI scheme incentives for electronics manufacturing expand precision die-cutting demand in Tamil Nadu semiconductor assembly facilities. The Delhi-NCR corridor concentrates distributor networks serving clinic procurement with accelerated delivery requirements.
Tissue Tapes Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across medical, automotive, and electronics verticals, creating a tiered structure where polymer science capabilities determine premium positioning. Three archetypes dominate: integrated chemical conglomerates with in-house analytical laboratories, precision die-cut converters with localized technical service, and regional packaging-grade volume suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, particularly around cleanroom manufacturing investments and direct OEM qualification pathways.
Among diversified chemical conglomerates, 3M and Nitto Denko Corporation exemplify integrated manufacturers sustaining structural advantages through regulatory affairs capacity and polymer formulation expertise. Tesa SE occupies a position within the European automotive-focused tier, competing through consistent peel-strength performance validation across temperature cycles. Lohmann and LINTEC represent precision die-cut specialists serving electronics assembly demand with localized technical service operations.
| Leading Market Players |
|---|
| 3M |
| Tesa SE |
| Nitto Denko Corporation |
| Lohmann |
| LINTEC |
| Avery Dennison Corporation |
| Scapa Group Plc |
| Saint-Gobain |
| Ritu Raj Tapes Pvt. Ltd. |
| Others |
Value Chain & Pricing Dynamics
ISO 10993 certification tiers bifurcate medical-grade tissue tapes from industrial alternatives, compressing pricing power into integrated manufacturers with in-house analytical laboratories while dispersing commodity-grade margins across fragmented converter clusters in China's eastern corridor. This certification-driven divergence manifests in supply chain configurations where premium medical laminates draw from single-source silicone-coated liner suppliers in Europe, while packaging-grade volumes feed from distributed hot-melt coating facilities.
Pricing Analysis
Short lead-time premiums compress pricing differentiation across the tissue tape market, with just-in-time medical tape orders commanding substantial markups over spot inventory positions. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical laminates from industrial hot-melt grades and repositionable craft formulations. Cost compression in industrial-grade segments intensifies because acrylic monomer feedstock volatility erodes converter margin predictability. Hospital procurement departments exhibit lowest price sensitivity due to sterility protocol requirements, while retail craft channels demonstrate highest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, China, and Japan anchor hub-and-spoke patterns for medical-grade tissue tape fulfillment, with Suzhou and Stuttgart facilities maintaining strategic buffer stocks. Raw material dependencies center on silicone-coated release liners from European suppliers, acrylic emulsion polymers from petrochemical feedstocks, and hydrogenated hydrocarbon tackifiers. Single-source liner vulnerability concentrates bottleneck risk for medical tape orders. Distribution runs through direct converter partnerships for electronics assemblers and distributor networks for clinic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue tape market sits in a solvent-to-hot-melt technology transition, with water-based adhesive systems displacing legacy saturation methods across European and North American converter operations.
For Market Incumbents: Deploy cleanroom capacity expansion as the primary defensive lever against emerging Asian precision die-cut specialists. Integrated manufacturers should deepen backward integration into silicone-coated liner production to neutralize single-source supply risk. Incumbents must accelerate ISO 10993 certification pipelines to compress 14-18 month launch cycles before regulatory timelines tighten further.
For New Entrants and Emerging Players: Capture import substitution opportunities in India's Maharashtra and Gujarat medical device clusters where CDSCO harmonization with ISO 13485 opens domestic converter gaps. New entrants should target water-based adhesive R&D partnerships with California and EU converters facing VOC compliance deadlines. A precision die-cutting technical service model offers the most penetrable go-to-market angle for semiconductor packaging facilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision die-cut specialists with localized technical service operations and direct OEM qualification relationships. Long-term viability favors integrated manufacturers with regulatory affairs capacity and polymer formulation expertise over pure-play packaging-grade volume suppliers. Investors should watch extended producer responsibility mandate implementation across EU member states as the inflection signal for service-revenue model adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 8 manufacturing investments exceed mid-tier converter balance sheets, consolidating medical-grade supply among integrated conglomerates. |
| Backward Integration into Liner Production | In-house silicone-coated release liner capacity neutralizes European single-source bottleneck risk for just-in-time medical orders. |
| Water-Based Adhesive R&D Partnership | California Air Resources Board and EU VOC regulations unify converter priorities around aqueous polymer system development. |
| Precision Die-Cutting Technical Service | Localized die-cutting operations in South Korea and Taiwan displace traditional distributor relationships for semiconductor packaging. |
| Extended Producer Responsibility Logistics | EU Green Deal packaging mandates create service-revenue streams for manufacturers offering tape take-back programs. |
Study Parameters
Document review covered regulatory filings with FDA and ECHA, trade association publications from adhesive and medical device sectors, and customs data on pressure-sensitive laminate imports, complemented by interviews with converter plant managers, medical device procurement leads, automotive OEM materials engineers, and distribution channel partners. Secondary validation drew from SEC 10-K disclosures of diversified chemical conglomerates, ISO 10993 certification databases, and REACH Annex XVII restriction updates. Bottom-up demand modeling across end-use verticals triangulated against top-down market sizing from production capacity assessments.
Segmentation outputs reflect product type, adhesive chemistry, application vertical, and geographic regulatory cluster variations across the projection horizon. CAGRs were derived from production volume trajectories, capacity expansion announcements, and end-use demand elasticity parameters specific to medical electronics assembly and automotive interior bonding applications. The analytical framework incorporated hot-melt coating technology diffusion rates and water-based adhesive formulation adoption curves as industry-specific forecast inputs.
The model holds under stable petrochemical feedstock pricing and continued REACH enforcement intensity; deviation in crude oil volatility or accelerated EU Green Deal chemical restrictions would shift converter margin structures and technology migration timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Splicing Tapes Market
Tapes
Shipping Tapes Market
Tapes
Carry Handle Tape Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Medical Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Hydrocolloid Tapes Market
Tapes
Cable Wrapping Tapes Market
Tapes
Tape Unwinder Market
Tapes
Europe Packaging Tapes Market
Tapes
Aluminum Foil Tape Market
Tapes
Kraft Paper Tapes Market
Tapes
Nano Tapes Market
Tapes
Security Tape Market
Tapes
Seam Tapes Market
Tapes
ESD Tapes and Labels Market