
 Foam Tape Market | 2026-2036
Foam Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Tape Market Intelligence
The high capital expenditure required for integrated polymer foam production and adhesive coating lines is reshaping competitive positioning. This dynamic favors large, diversified players like 3M Company, which leverages its extensive material science R&D across multiple end-markets. Nitto Denko Corporation specializes in high-performance tapes for the electronics sector, particularly in Japan and South Korea, while tesa SE focuses on the European automotive and construction industries.
Foam tape is a composite material consisting of a foam carrier, such as polyethylene or acrylic, coated with a pressure-sensitive adhesive. Its compressible and conformable nature allows it to bond to irregular surfaces, providing sealing, cushioning, and vibration dampening. Acrylic foam tapes command a premium due to their high strength and durability, especially in automotive and construction applications. Mounting and bonding applications are expanding rapidly, driven by demand from electronics manufacturers for assembling compact devices.
Regulatory frameworks, including the EU's REACH and volatile organic compound (VOC) limits from the US EPA, directly influence adhesive chemistry and manufacturing processes. Compliance with national standards, such as China's GB standards, is mandatory for market access in key sectors like automotive. Future profitability hinges on developing formulations that meet diverging regional environmental and safety mandates while maintaining performance.
Market Dynamics
The market's central tension exists between escalating performance demands from electronics and automotive sectors and the tightening web of global chemical regulations. This dynamic forces continuous investment in adhesive reformulation to meet divergent standards like the EU's REACH and RoHS directive.
Growth Catalysts
- Electronics Miniaturization:Demand from consumer electronics for bonding components in compact devices like smartphones.
- Automotive Lightweighting:Use of tapes to bond dissimilar materials, reducing vehicle weight and dampening vibration.
- Building Energy Codes:Stricter codes in Europe and North America drive demand for tapes as air and moisture barriers.
Market Restraints
- Raw Material Volatility:Price fluctuations in petrochemical feedstocks like polyethylene and acrylic monomers create margin pressure.
- Regulatory Compliance Costs:Adhering to the EU's REACH and US EPA's VOC limits requires costly reformulation.
- Substitution Threat:Liquid structural adhesives offer superior load-bearing capabilities in some high-stress structural applications.
Strategic Opportunities
- Bio-based Formulations:Developing tapes with bio-based polymers and solvent-free adhesives to meet corporate sustainability goals.
- Electric Vehicle Batteries:Specialized tapes for thermal management and sealing within EV battery pack assemblies.
- Medical Device Adhesion:Expansion into skin-contact applications requiring tapes that meet ISO 10993 biocompatibility standards.
Industry Challenges
- Application-Specific Testing:Validating tape performance for long-term UV resistance or electronics outgassing requires extensive testing protocols.
- High Capital Investment:Foam extrusion and adhesive coating lines require significant capital, creating high barriers to entry.
- End-of-Life Recycling:The composite nature of foam tape complicates recycling efforts for circular economy initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Tape Market |
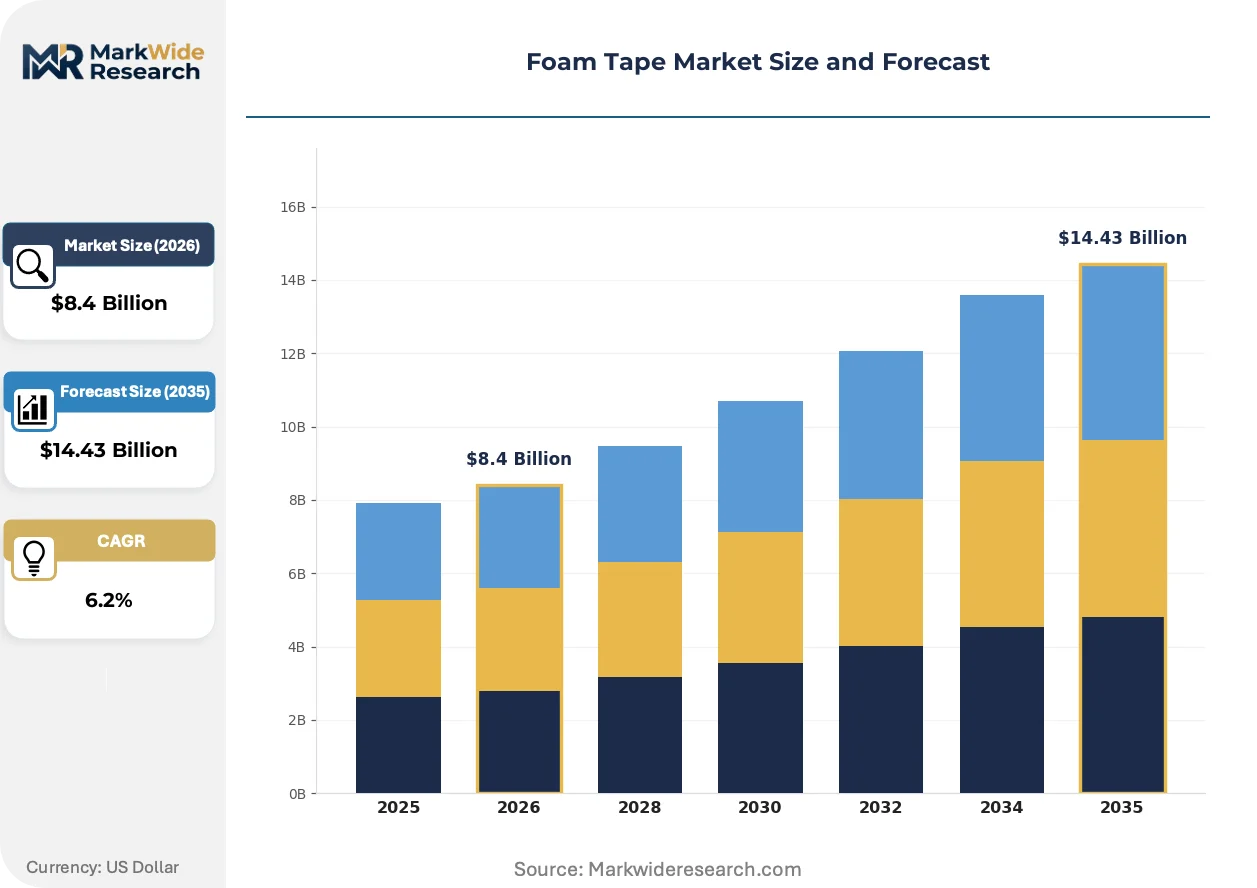
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Foam Tape, Polyurethane Foam Tape, Acrylic Foam Tape, Silicone Foam Tape, Rubber Foam Tape Application: Sealing & Weatherproofing, Cushioning & Padding, Insulation & Soundproofing, Mounting & Bonding, Vibration Dampening End User Industry: Electronics Manufacturers, Construction Contractors, HVAC Specialists, Furniture Makers, Packaging Companies Distribution Channel: Direct Sales, Industrial Distributors, E-commerce Platforms, Retail Hardware Stores, Wholesalers |
| Companies Covered | Avery Dennison Corporation, LINTEC Corporation, 3M Company, Saint-Gobain Performance Plastics, HALCO, Nitto Denko Corporation, Intertape Polymer Group, Lohmann, tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Tape Market Strategic Shifts & Innovations
The evolution of foam tape is moving beyond simple adhesion toward multifunctional materials. These advanced composites are engineered to provide thermal management or EMI shielding in addition to bonding, transforming their role in product design.
Thermally conductive foam tapes function to dissipate heat from electronic components while also providing bonding and cushioning. Electronics manufacturers adopt these materials for servers and high-power devices to improve thermal management. This integrated functionality is rendering obsolete the need for separate mechanical fasteners, thermal pads, and adhesive layers.
China's dual carbon goals and stricter GB standards for VOCs in industrial products create new compliance hurdles. This is compelling manufacturers selling into the country to accelerate the transition to water-based and solventless adhesive technologies. Automotive and electronics supply chains within China prioritize suppliers who can document compliance with these national standards.
A behavioral shift involves specifying custom die-cut components for automated assembly lines instead of buying discrete tape rolls. This model bypasses traditional distributors, requiring converters to develop engineering and just-in-time logistics capabilities. The trend is most prominent within high-volume electronics assembly in South Korea and Taiwan.
Foam Tape Market Segmentation
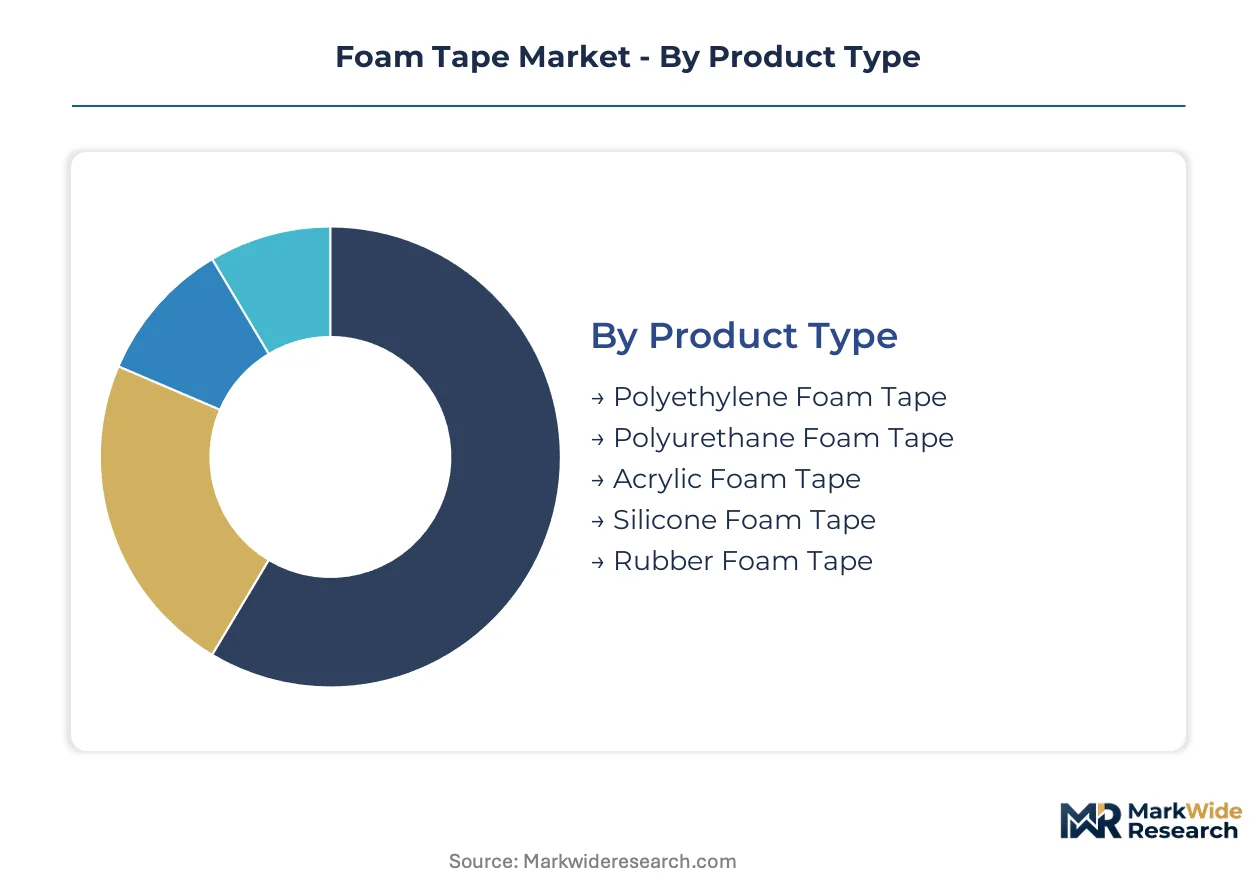
Market segmentation provides a granular view of the Foam Tape Market, dissecting demand drivers and supplier strategies across diverse product types, applications, end-user industries, and distribution channels. Understanding these distinct segments is critical for identifying specific growth opportunities and navigating specialized regulatory landscapes.
Product Type:
The product type segmentation reveals a spectrum from mature, cost-effective options to high-performance, specialized formulations catering to demanding industrial requirements.
- Acrylic Foam Tape:This premium tape consists of a viscoelastic acrylic polymer, offering high strength, durability, and excellent resistance to UV, temperature, and solvents. Demand concentrates within automotive and construction sectors for bonding dissimilar materials and providing long-term structural integrity.
- Polyethylene Foam Tape:Characterized by its closed-cell structure and flexibility, polyethylene foam tape provides good sealing, cushioning, and vibration dampening properties at a competitive price point. General industrial applications and packaging companies represent significant demand centers for this versatile product type.
- Polyurethane Foam Tape:Known for its open-cell structure, polyurethane foam tape excels in sound absorption and cushioning applications.
- Silicone Foam Tape:Offering superior high-temperature resistance and environmental sealing capabilities, silicone foam tape serves specialized industrial applications.
- Rubber Foam Tape:This tape provides effective sealing, weatherproofing, and vibration dampening across various industrial and consumer goods applications.
Polyethylene Foam Tape retains volume leadership; Acrylic Foam Tape holds the steepest expansion curve.
Application:
The diverse application landscape highlights the multifunctional utility of foam tapes across various industries, driven by specific functional requirements.
- Mounting & Bonding:These applications involve using foam tapes for structural adhesion and component assembly, often replacing mechanical fasteners. Demand is particularly strong from electronics manufacturers for assembling compact devices and from automotive companies for lightweighting initiatives.
- Sealing & Weatherproofing:Foam tapes create effective air and moisture barriers, protecting against environmental ingress and improving energy efficiency. Construction contractors and HVAC specialists in Europe and North America utilize these tapes to meet stricter building energy codes.
- Cushioning & Padding:Foam tapes provide shock absorption and protective layers, safeguarding delicate components during transport or operation.
- Insulation & Soundproofing:These tapes contribute to thermal management and noise reduction, particularly in automotive interiors and building envelopes.
- Vibration Dampening:Foam tapes reduce unwanted vibrations and noise, extending the lifespan of components in machinery and vehicles.
Mounting & Bonding applications are expanding most quickly, driven by electronics miniaturization and automotive assembly demands.
End User Industry:
End-user industries demonstrate distinct procurement patterns and performance requirements for foam tape solutions, influencing product development priorities.
- Electronics Manufacturers:This segment demands high-performance tapes for component bonding, thermal management, and EMI shielding in compact devices. Major manufacturing hubs in China, South Korea, and Taiwan represent significant demand concentrations, often requiring custom die-cut components for automated assembly lines.
- Construction Contractors:Construction applications require durable tapes for air sealing, moisture barriers, and insulation in residential and commercial buildings. Regulatory frameworks in Europe and North America, such as stricter building energy codes, drive specific material selection.
- HVAC Specialists:These professionals utilize foam tapes for duct sealing, thermal insulation, and vibration control within heating, ventilation, and air conditioning systems.
- Furniture Makers:Foam tapes find use in furniture assembly, cushioning, and surface protection, offering efficient bonding solutions.
- Packaging Companies:This industry employs foam tapes for protective packaging, void fill, and sealing applications to secure goods during transit.
Electronics Manufacturers are driving significant innovation, while Construction Contractors represent a stable, high-volume segment.
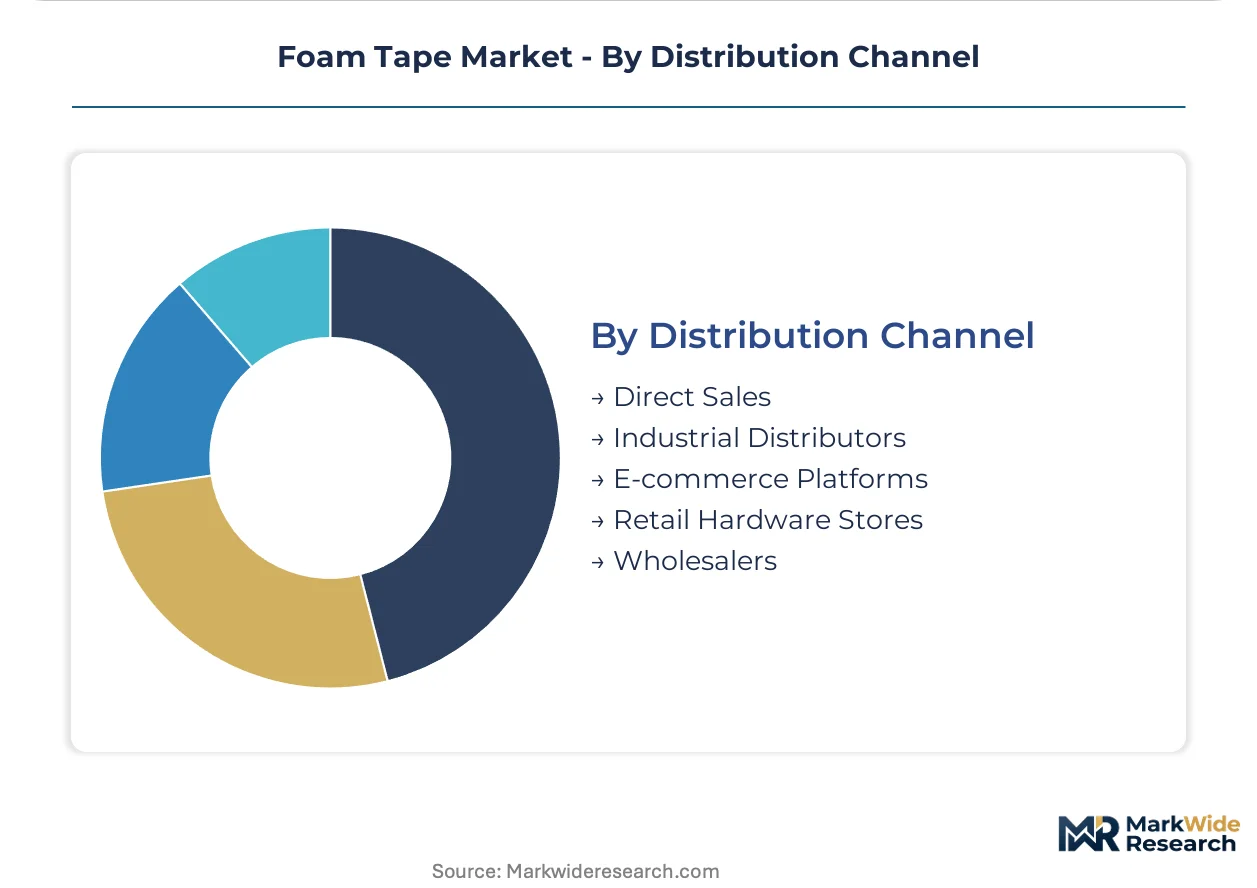
Distribution Channel:
The distribution channel structure reflects varying market access strategies and customer service models, ranging from direct sales to broad industrial networks.
- Industrial Distributors:These channels offer broad product portfolios, technical support, and regional warehousing, serving diverse industrial sectors with efficiency. Industrial distributors play a crucial role in providing localized service and maintaining supply chain stability for numerous small and medium-sized enterprises.
- Direct Sales:Manufacturers engage in direct sales for large OEM accounts and specialized applications, providing custom formulations and in-depth technical consultation. This channel facilitates strong partnerships and addresses complex engineering requirements, particularly in automotive and high-end electronics.
- E-commerce Platforms:Online platforms provide convenient access and price transparency, catering to smaller businesses and specialized niche markets.
- Retail Hardware Stores:This channel serves the DIY market and small-scale construction projects, offering general-purpose foam tapes for consumer use.
- Wholesalers:Wholesalers facilitate bulk purchasing and regional supply to a network of smaller retailers and contractors, ensuring broad market availability.
Industrial Distributors maintain extensive reach, while Direct Sales channels cater to high-volume, custom-engineered solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global foam tape market exhibits a complex trade balance, with significant production concentrated in Asian manufacturing hubs supporting worldwide consumption. China leads in both domestic demand and export volume for various foam tape grades, influencing material flow across continents. Other regions, particularly Europe and North America, focus on high-value, specialized foam tape formulations, often driven by stringent regulatory frameworks and advanced industrial applications.
China
China's advanced manufacturing and automotive assembly clusters drive substantial demand for foam tapes in electronics and vehicle production. The nation's dual carbon goals and stricter GB standards for industrial VOCs compel manufacturers to adopt water-based and solventless adhesive technologies. The Yangtze River Delta region, including Shanghai and Suzhou, represents a major hub for electronics and automotive component manufacturing, integrating foam tape into high-volume assembly lines.
Germany
Germany's automotive sector and high-performance construction industry generate strong demand for durable acrylic foam tapes. The EU's REACH and RoHS directives significantly influence adhesive chemistry and material selection, favoring compliant and sustainable formulations. Bavaria, with its prominent automotive manufacturers, and the Rhine-Ruhr region, a center for industrial production, demonstrate significant foam tape consumption for sealing and bonding applications.
United States
United States demand for foam tapes stems from robust construction activity, electronics manufacturing, and a growing electric vehicle market. US EPA's VOC limits necessitate continuous reformulation of adhesive products to ensure environmental compliance. Silicon Valley's electronics industry and the Detroit automotive cluster utilize specialized foam tapes for component assembly and vibration dampening, alongside widespread use in commercial and residential building projects.
Japan
Japan emphasizes precision engineering in electronics and automotive applications, requiring high-performance foam tapes for bonding and thermal management. Compliance with JIS standards is critical for market access and product acceptance in various industrial sectors. The Tokyo metropolitan area, a hub for electronics R&D and manufacturing, and Aichi Prefecture, home to major automotive production, are key consumption centers for advanced foam tape solutions.
South Korea
South Korea's robust electronics manufacturing sector, particularly for smartphones and displays, drives significant demand for custom die-cut foam tape components. The country's strict quality controls and fast-paced innovation cycles influence material specifications for compact devices. The Seoul Capital Area, a global electronics manufacturing powerhouse, and Ulsan, a major automotive production base, represent primary consumption zones for specialized foam tape applications.
Foam Tape Market Key Industry Players
On the supply side, the industry is tiered, featuring large, diversified conglomerates alongside specialized manufacturers focusing on niche applications. Large material science companies leverage extensive R&D capabilities and broad product portfolios across multiple end-markets. Strategic archetypes include global diversified players, regional specialists, and application-specific innovators. Dominant competitive moves involve continuous investment in advanced material science and strategic partnerships to expand market reach.
At the scale-driven end, 3M Company, a Minnesota-based conglomerate, exemplifies a diversified approach, leveraging its extensive material science expertise across numerous end-markets. Japan's Nitto Denko Corporation occupies a strong position in high-performance tapes, particularly for the electronics sector in Asia. Germany's tesa SE anchors the European automotive and construction industries, focusing on specialized foam tape solutions that meet regional regulatory requirements and demanding performance criteria.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| LINTEC Corporation |
| 3M Company |
| Saint-Gobain Performance Plastics |
| HALCO |
| Nitto Denko Corporation |
| Intertape Polymer Group |
| Lohmann |
| tesa SE |
| Others |
Cost & Logistics Intelligence
Commodity volatility in petrochemical feedstocks, such as polyethylene and acrylic monomers, represents a significant risk vector determining both pricing tier spreads and the broader foam tape supply chain shape. This instability directly impacts manufacturing costs for all product types, influencing market competitiveness across regions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for foam tapes. Pricing stratifies across premium, standard, and economy tiers based on quality grade, customization level for die-cut components, and specific certification levels like RoHS or GB standards. Pricing pressure stems from raw material volatility, particularly for general-purpose polyethylene foam tapes. Electronics manufacturers and automotive OEMs demonstrate lower price sensitivity for high-performance acrylic and silicone tapes due to critical application requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive foam tape manufacturing ecosystem. Geographic supply concentrates in China for raw material processing and volume production, with Japan and Germany specializing in high-performance formulations. Raw material dependencies include petrochemical feedstocks like polyethylene and acrylic monomers, alongside various pressure-sensitive adhesives. Raw material volatility poses a structural risk across the entire supply chain. Distribution runs through industrial distributors for broad market access and direct sales channels for large OEM accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foam tape market presents an early-cycle expansion story, driven by persistent adoption of advanced bonding solutions in electronics miniaturization and automotive lightweighting initiatives.
For Market Incumbents:Insulate core markets by investing in advanced material science R&D, particularly for bio-based and solvent-free adhesive formulations. Deepen partnerships with key electronics and automotive OEMs to secure long-term contracts for specialized applications. This strategy mitigates the substitution threat from liquid structural adhesives. Continuous certification investment for regional standards like EU REACH and China GB standards reinforces market access and compliance leadership.
For New Entrants and Emerging Players:Pursue niche high-performance applications where existing solutions fall short or where specific regulatory compliance creates barriers. Target specialized tapes for electric vehicle battery thermal management and sealing. The medical device adhesion segment, requiring ISO 10993 biocompatibility, offers a penetrable white space. A focused go-to-market angle involves offering custom die-cut components for automated assembly lines, bypassing traditional distribution for high-volume customers.
For Investors and Strategic Acquirers:The EU's RoHS directive and China's dual carbon goals reshape the acquisition landscape, favoring compliant and sustainable material providers. Long-term viability rests on sustained demand from high-growth, regulation-driven sectors like electronics, electric vehicles, and medical devices. Target mid-sized specialists with proprietary adhesive formulations or advanced manufacturing capabilities in thermal management or biocompatibility. Adoption rates of bio-based formulations serve as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-based Adhesive Formulations | Addresses corporate sustainability goals and complies with tightening environmental regulations like EU REACH. |
| Invest in Die-Cut Component Manufacturing | Supports automated assembly lines in electronics and automotive, improving efficiency for OEMs. |
| Expand into EV Battery Thermal Management | Captures demand from the rapidly growing electric vehicle sector for specialized sealing and cooling. |
| Secure ISO 10993 Certification for Medical Tapes | Unlocks high-value, regulated applications in the medical device adhesion market. |
| Establish Regional Compliance Centers | Ensures adherence to diverse national standards, including US EPA VOC limits and China GB standards, for market access. |
Research Approach
Initial hypotheses were tested against primary input from electronics R&D engineers, automotive procurement leads, construction materials specifiers, adhesive chemists, and industrial distributors, then refined. This involved combining qualitative insights from interviews with quantitative validation from secondary sources. Secondary data included EU RoHS/REACH directives, US EPA VOC limits, China GB standards, company annual reports, and trade association publications, ensuring bottom-up and top-down triangulation.
Demand-supply-balance framing guided the analytical framework applied over the projection horizon. Segmentation dimensions modeled included product type (acrylic, polyethylene), application (mounting & bonding, sealing), end-user industry (electronics, automotive), and geographic region (China, Germany, US). Compound annual growth rates were derived from historical performance and anticipated market shifts. Key industry-specific forecast inputs included electronics miniaturization rates and electric vehicle production forecasts.
Sensitivities concentrate around volatility in petrochemical feedstock prices, unexpected shifts in global trade policies, and rapid advancements in alternative bonding technologies. Forecasts reflect assumptions regarding these factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Adhesive Transfer Tape Market
Tapes
Pouch Tapes Market
Tapes
Tape Unwinder Market
Tapes
Filament Tapes Market
Tapes
Strapping Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Splicing Tapes Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Dicing Tapes Market
Tapes
Security Tape Market
Tapes
Breathable Tape Market
Tapes
Electrical Shielding Tape Market
Tapes
Global Non Woven Tape Market
Tapes
Sterilization Indicator Tape Market
Tapes
UV Tapes Market
Tapes
Europe Packaging Tapes Market