
 Release Tape Market | 2026-2036
Release Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Release Tape Market Insights
ISO 9001 quality certification cycles for adhesive tape suppliers is collapsing from eighteen-month intervals to continuous audit regimes. Sekisui Chemical Co., Ltd. leverages captive polymer synthesis to secure raw material consistency across Asian manufacturing nodes. Nitto Denko Corporation anchors its position through R&D intensity in ultra-thin silicone coatings for flexible electronics. 3M Company competes via global distribution infrastructure that reaches automotive OEMs across multiple continents.
Release tape denotes a pressure-sensitive adhesive substrate engineered with controlled peel-force characteristics, typically incorporating silicone or rubber-based release coatings on polyester or polypropylene backings to enable clean separation from bonded surfaces. Manufacturing employs precision coating lines with thickness tolerances below five micrometers to ensure repeatable release values critical for automated assembly lines. Silicone formulations dominate medical and electronics applications where thermal stability and chemical inertness command premium positioning, while rubber-based alternatives occupy cost-sensitive packaging segments. Polypropylene substrates sustain growth in automotive interior applications where dimensional stability under temperature cycling proves essential.
FDA regulates medical-grade release tapes through biocompatibility testing under ISO 10993 frameworks, while EPA oversight of solvent-based coating emissions pushes manufacturers toward waterborne and UV-curable alternatives. REACH restrictions on organotin catalysts in silicone curing systems force reformulation investments across European supply chains. Stakeholders must monitor evolving PFAS regulations and assess adhesive platform transitions before compliance deadlines tighten material specifications.
Market Dynamics
Silicone migration constraints from REACH compliance are forcing wholesale adhesive platform transitions across European supply chains, compressing reformulation timelines and elevating technical qualification costs for tape manufacturers serving medical and electronics end-uses.
Growth Catalysts
- Display fabrication scaling:Semiconductor and OLED panel production clusters in China, Japan, and South Korea require precision release solutions for automated handling of ultra-thin substrates during lamination and dicing operations.
- ISO 10993 biocompatibility frameworks:FDA-mandated testing protocols for medical-grade tapes expand addressable markets in wound care and transdermal drug delivery applications where skin-contact safety is non-negotiable.
- Miniaturization imperatives:Electronics manufacturers demand five-micrometer thickness tolerances in coating lines to enable clean separation of bonded micro-components without residue transfer.
Market Restraints
- Organotin catalyst restrictions:REACH limitations on platinum-catalyzed silicone curing systems force European manufacturers into unproven alternative chemistries with uncertain performance parity.
- Petrochemical feedstock volatility:Polypropylene and polyester substrate costs fluctuate with crude oil derivatives, compressing margin stability for cost-sensitive packaging segment suppliers.
- Regional supply concentration:Captive polymer synthesis capabilities concentrate among Japanese and South Korean chemical conglomerates, creating procurement bottlenecks for independent tape converters.
Strategic Opportunities
- Waterborne coating transitions:EPA emissions oversight of solvent-based processes creates first-mover advantage for manufacturers investing in UV-curable and aqueous adhesive platforms ahead of compliance deadlines.
- Flexible electronics integration:Ultra-thin silicone coating R&D for foldable display manufacturing opens premium positioning in next-generation consumer device supply chains.
- Automotive interior thermal cycling:Polypropylene substrates with dimensional stability under temperature extremes address unmet needs in electric vehicle battery module assembly and cabin trim applications.
Industry Challenges
- Continuous audit regime complexity:ISO 9001 certification cycles collapsing from eighteen-month intervals to real-time quality verification strains documentation and personnel training systems.
- PFAS regulatory uncertainty:Evolving restrictions on fluorinated compounds in adhesive formulations require speculative R&D investment before material specifications crystallize into enforceable mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Release Tape Market |
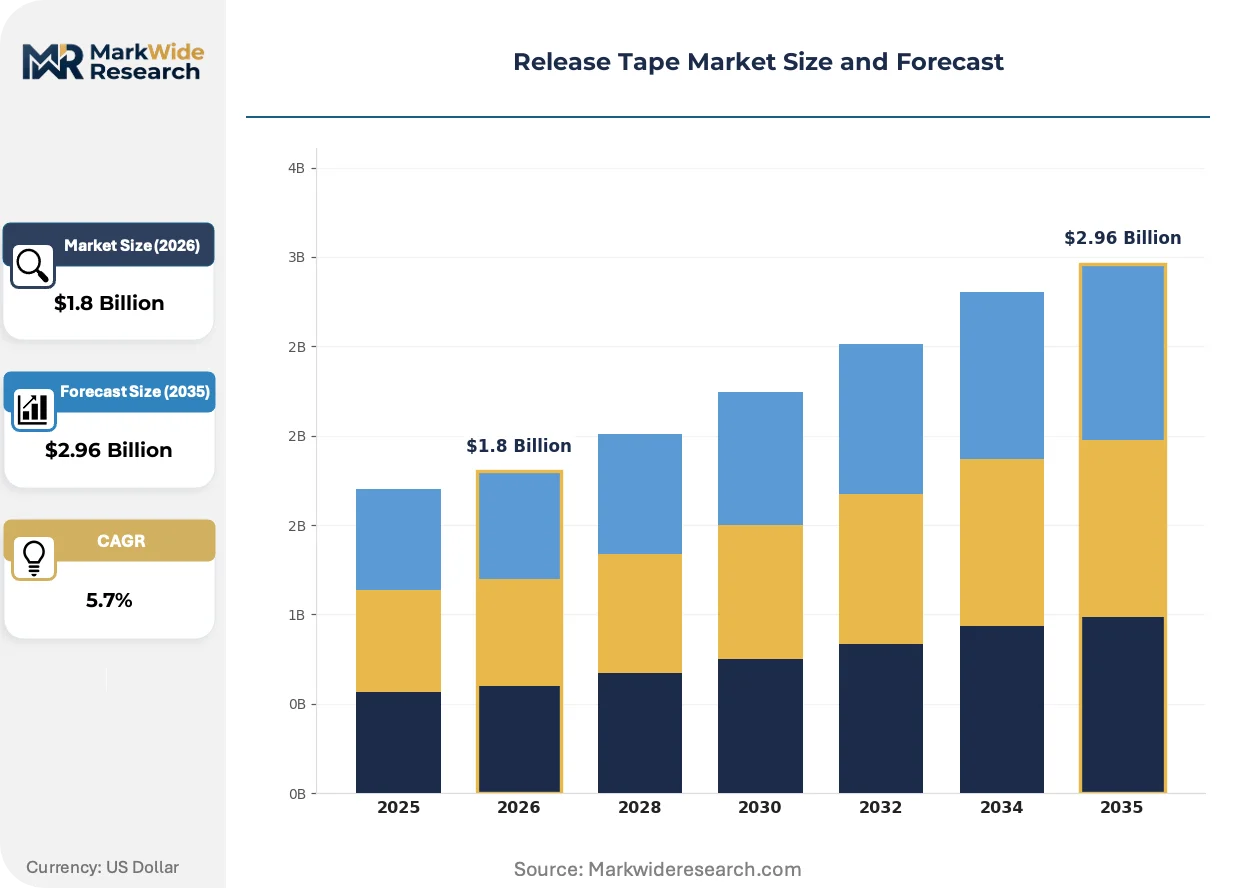
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Rubber, Polypropylene, Polyethylene Application: Automotive, Electronics, Packaging, Medical End User: Manufacturers, Distributors, Retailers, Contractors Technology: Coating, Laminating, Adhesive, Cutting |
| Companies Covered | Sekisui Chemical Co., Ltd., Nitto Denko Corporation, 3M Company, Avery Dennison Corporation, Lintec Corporation, tesa SE, Scapa Group plc, Shurtape Technologies, LLC, Intertape Polymer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Release Tape Market Trends and Innovations
Coating technology and regulatory chemistry are diverging simultaneously, splitting the release tape market into distinct performance tiers while environmental compliance accelerates material substitution timelines.
Silicone release coatings are bifurcating into high-purity medical grades and industrial commodity variants as end-use specifications diverge. Medical device manufacturers in Germany and Switzerland now demand sub-ppm silicone migration thresholds for implantable applications, while packaging converters in Southeast Asia prioritize cost-optimized rubber-based alternatives. This split is compressing mid-tier product viability and forcing manufacturers to commit to single-strategy specialization rather than portfolio breadth.
ECHA's evolving restrictions on organotin catalysts under REACH Article 57 are eliminating conventional platinum-cured silicone systems from European medical tape formulations. Manufacturers serving wound care and transdermal patch markets must validate tin-free curing chemistries through extended biocompatibility testing under ISO 10993-5 and ISO 10993-10 frameworks. German and French medical device assemblers are absorbing eighteen-month qualification delays as they await regulatory clarity on acceptable catalyst alternatives.
Specification-driven purchasing is displacing price-primary procurement in electronics supply chains as miniaturization failures carry catastrophic yield penalties. Display panel manufacturers in South Korea and semiconductor fabricators in Taiwan now mandate continuous thickness certification from tape suppliers rather than batch sampling. This behavioral shift concentrates procurement among vertically integrated chemical conglomerates with captive metrology capabilities, marginalizing independent converters lacking in-house coating line instrumentation.
Release Tape Market Segmentation
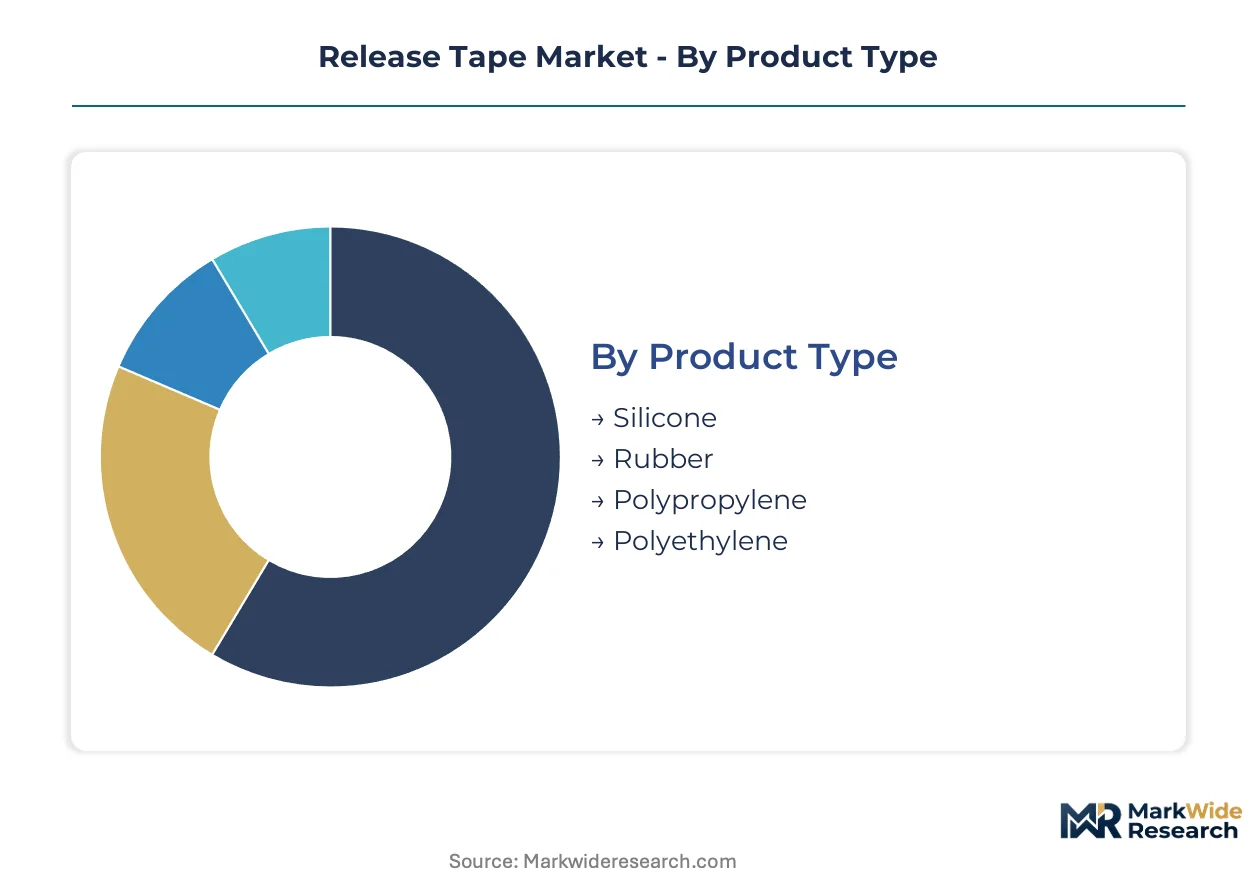
Release tape segmentation reflects divergent compliance burdens and performance thresholds across end-use ecosystems. Material chemistry, substrate construction, and coating technology each carry distinct regulatory fingerprints that reshape supplier economics and customer procurement criteria.
Product Type:
REACH Article 57 restrictions on organotin catalysts split silicone formulations into medical-grade purity tiers versus industrial commodity grades, while substrate selection hinges on thermal cycling demands in target applications.
- Silicone:Platinum-catalyzed systems deliver sub-ppm migration thresholds for implantable medical devices under ISO 10993 frameworks. South Korean display manufacturers specify these for OLED lamination where residue-free separation protects microcircuit yield.
- Rubber:Cost-optimized formulations dominate Southeast Asian packaging converters serving high-volume logistics operations. Natural and synthetic rubber alternatives sacrifice thermal stability for unit economics in non-critical peel applications.
- Polypropylene:Dimensional stability under temperature extremes addresses electric vehicle battery module assembly requirements.
- Polyethylene:Lower-cost substrate for disposable medical and general industrial applications where extended thermal performance is unnecessary.
Established volume favors rubber formulations in cost-sensitive packaging; emerging adoption favors silicone grades in medical and electronics precision handling.
Application:
End-use specifications cascade backward through coating line investments, with medical and electronics segments demanding continuous metrology certification that packaging and automotive segments rarely require.
- Electronics:Five-micrometer thickness tolerances enable clean separation of bonded micro-components during semiconductor dicing and display panel lamination. Taiwan and South Korea fabrication clusters specify continuous thickness certification rather than batch sampling.
- Medical:FDA biocompatibility testing under ISO 10993-5 and ISO 10993-10 mandates eighteen-month qualification cycles for wound care and transdermal drug delivery applications.
- Automotive:Interior trim and battery module applications prioritize polypropylene substrates with stability across temperature cycling profiles.
- Packaging:High-volume logistics operations in Southeast Asia absorb commodity-grade rubber formulations where peel consistency matters more than thermal performance.
Electronics and medical segments command premium positioning through specification intensity; packaging and automotive segments compete on scale economics and supply security.
End User:
Procurement authority concentrates differently across value chain tiers, with manufacturers capturing specification-setting power while distributors and retailers optimize for inventory velocity.
- Manufacturers:Electronics OEMs and medical device assemblers in Germany, Switzerland, and South Korea dictate material specifications through captive metrology requirements and extended qualification protocols.
- Distributors:Independent tape converters without in-house coating line instrumentation face procurement bottlenecks as specification-driven purchasing displaces price-primary procurement.
- Retailers:General industrial supply channels serve maintenance and repair operations with standardized product grades.
- Contractors:Installation and assembly service providers source through distributor networks for project-specific material requirements.
Direct manufacturer relationships secure specification influence; distributor and contractor channels compete on logistics responsiveness and technical support depth.
Technology:
Coating precision and curing chemistry differentiation separate premium positioning from commodity competition, with environmental compliance accelerating platform transitions.
- Coating:Precision lines with sub-five-micrometer thickness control enable repeatable release values critical for automated electronics assembly. EPA emissions oversight pushes investment toward waterborne and UV-curable alternatives.
- Adhesive:Formulation chemistry determines migration profiles and biocompatibility certification scope under FDA and REACH frameworks.
- Laminating:Multi-layer construction for complex substrate-adhesive-release coating combinations serving flexible electronics integration.
- Cutting:Die-cutting and slitting operations for customized width and length specifications serving contract assembly operations.
Coating technology anchors premium tier differentiation; laminating and cutting operations scale through operational efficiency in downstream conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Article 57 restrictions on organotin catalysts are accelerating adhesive platform transitions across European medical tape supply chains, while EPA emissions oversight pushes North American manufacturers toward waterborne coating investments. Asian fabrication clusters in display and semiconductor manufacturing drive precision release tape demand through specification-intensive procurement.
China
OLED panel production expansion in the Yangtze River Delta and semiconductor fabrication scaling in Jiangsu Province absorb precision silicone release tapes for automated substrate handling. MIIT industrial upgrading guidelines prioritize domestic supply chain security for electronic materials. Display manufacturing clusters in Hefei and Chengdu operate automated lamination lines demanding five-micrometer coating tolerances.
Germany
Medical device assemblers in Baden-Württemberg and North Rhine-Westphalia specify sub-ppm silicone migration thresholds for wound care and transdermal patch applications. ECHA restrictions on platinum-catalyzed curing systems force eighteen-month requalification cycles for tin-free alternative chemistries. Stuttgart and Munich medical technology corridors absorb premium-grade release tapes through ISO 10993-certified supply chains.
South Korea
Flexible OLED manufacturing in Gyeonggi Province and semiconductor dicing operations in Gwangju drive ultra-thin silicone coating specifications for residue-free substrate separation. MFDS biocompatibility frameworks align with ISO 10993 standards for medical-grade tape qualification. Display panel fabrication clusters in Asan and Cheonan mandate continuous thickness certification from adhesive suppliers.
United States
Automotive battery module assembly in Michigan and Ohio absorbs polypropylene release tapes with thermal cycling stability for electric vehicle production. EPA oversight of solvent-based coating emissions accelerates UV-curable platform investments among domestic manufacturers. Electronics contract manufacturers in Texas and Arizona specify precision release solutions for semiconductor packaging operations.
Japan
Captive polymer synthesis capabilities among chemical conglomerates concentrate procurement power for independent tape converters serving domestic electronics OEMs. METI carbon neutrality roadmaps pressure coating line energy efficiency improvements. Precision manufacturing clusters in Nagoya and Osaka demand sub-five-micrometer thickness control for automated micro-component assembly.
Release Tape Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and R&D commitment dimensions, creating a tiered structure where scale advantages concentrate among integrated chemical conglomerates while niche positioning sustains mid-tier specialists. Three archetypes dominate: vertically integrated polymer producers with captive raw material supply, precision coating specialists with metrology-intensive quality systems, and regional converters leveraging distribution proximity for cost-sensitive segments. Competitive moves center on backward integration into polymer synthesis and strategic partnerships with fabrication equipment OEMs to secure specification-setting influence.
Within the integrated chemical conglomerate tier, Sekisui Chemical Co., Ltd., Nitto Denko Corporation, and 3M Company exemplify divergent strategic anchors. Sekisui Chemical represents Japanese chemical conglomerate positioning through captive polymer synthesis capabilities securing raw material consistency. Nitto Denko occupies the precision coating specialist archetype with R&D intensity in ultra-thin silicone formulations. 3M exemplifies global distribution infrastructure scale reaching automotive OEMs across multiple continents. Each occupies a distinct competitive position without direct overlap in core capability emphasis.
| Leading Market Players |
|---|
| Sekisui Chemical Co., Ltd. |
| Nitto Denko Corporation |
| 3M Company |
| Avery Dennison Corporation |
| Lintec Corporation |
| tesa SE |
| Scapa Group plc |
| Shurtape Technologies, LLC |
| Intertape Polymer Group |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month qualification cycles for ISO 10993-certified medical grades compress inventory turns to ninety-day windows, concentrating pricing power among Japanese and South Korean chemical conglomerates with captive polymer synthesis while independent converters absorb margin erosion from feedstock volatility.
Pricing Analysis
Certification level under FDA and ISO 10993 frameworks creates the primary spread between medical-grade silicone formulations and commodity rubber alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects biocompatibility testing burden, coating precision tolerances, and volume scale. Price differentiation intensifies as REACH Article 57 compliance costs elevate European medical tape production above Asian commodity supply. Electronics OEMs in Taiwan and South Korea exhibit lowest price sensitivity due to catastrophic yield penalties from release value inconsistency, while Southeast Asian packaging converters prioritize unit economics over thermal performance specifications.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European medical device assemblers sourcing precision-coated substrates. Manufacturing gravity centers on Japan, South Korea, and China where display fabrication clusters and captive polymer synthesis capabilities concentrate. Raw material flows draw from petrochemical derivatives for polypropylene and polyester substrates, platinum-group metals for silicone curing catalysts, and specialty silicone polymers for high-purity grades. Single-source vulnerability runs through Japanese chemical conglomerates controlling metrology-intensive coating line instrumentation. Distribution runs through direct manufacturer relationships for specification-intensive electronics and medical segments, with independent converters serving cost-sensitive packaging through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through eighteen-month biocompatibility qualification cycles protects incumbent positioning against price-based disruption.
For Market Incumbents: Shield market share through backward integration into silicone polymer synthesis and continuous metrology certification investments that exceed independent converter capabilities. The threat of REACH-compliant tin-free curing chemistry failures demands accelerated R&D commitment. Channel control through direct specification-setting relationships with South Korean display manufacturers and German medical device assemblers anchors premium positioning against commodity encroachment. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for wound care applications offer the most penetrable entry vector for qualification-light market penetration. White-space targets concentrate in waterborne coating platforms ahead of EPA compliance deadlines and UV-curable alternatives for automotive interior applications. A go-to-market angle emphasizing eighteen-month qualification cost absorption for European medical device assemblers stranded by organotin catalyst restrictions creates differentiation against established silicone suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-driven purchasing concentrates procurement among vertically integrated chemical conglomerates while marginalizing independent converters lacking captive metrology. Acquisition target archetypes include precision coating specialists with ISO 10993-certified quality systems and waterborne platform investments ahead of environmental compliance deadlines. The signal to watch is ECHA guidance clarity on acceptable platinum-catalyzed silicone alternatives, which would trigger requalification spending waves and distressed asset opportunities among European medical tape manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Polymer Synthesis | Sekisui Chemical's captive raw material supply secures batch consistency across Asian manufacturing nodes. |
| Waterborne Coating Platform Investment | EPA emissions oversight accelerates UV-curable and aqueous adhesive transitions ahead of compliance deadlines. |
| ISO 10993-5 Biocompatibility Certification | German medical device assemblers demand sub-ppm migration thresholds for implantable wound care applications. |
| Continuous Thickness Metrology Deployment | South Korean display manufacturers mandate real-time certification rather than batch sampling for OLED lamination. |
| Strategic Partnership with Fabrication Equipment OEMs | Specification-setting influence secures embedded release tape requirements in automated semiconductor dicing lines. |
Research Methodology
Operator-level perspectives from coating line engineers, medical device procurement managers, electronics OEM supply chain directors, and adhesive formulation chemists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings of listed chemical conglomerates, and ECHA regulatory guidance documents. Bottom-up segment sizing triangulated against top-down market value estimates derived from production capacity announcements across Japanese and South Korean manufacturing clusters.
Sensitivity analysis around petrochemical feedstock volatility and regulatory compliance timeline scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, substrate construction type, end-use application intensity, coating technology platform, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating miniaturization imperatives in electronics and biocompatibility expansion in medical applications. Industry-specific forecast inputs encompassed OLED panel production scaling in China and electric vehicle battery module assembly growth in the United States.
Decision-makers should treat outputs as directional under assumptions of sustained REACH Article 57 enforcement and continued EPA emissions oversight trajectory; material deviation would warrant model refresh. Forecasts incorporate assumptions regarding organotin catalyst substitution timelines and waterborne coating adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Removal Strips Market
Tapes
Gaffers Tape Market
Tapes
Carbon Tapes Market
Tapes
Plastic Adhesive Tapes Market
Tapes
Global Non Woven Tape Market
Tapes
Splicing Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Paper Packaging Tapes Market
Tapes
Thermoplastic Tape Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Pre-Printed Tape Market
Tapes
Ultra High Bond (UHB) Tape Market