
 Paper Packaging Tapes Market | 2026-2036
Paper Packaging Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Packaging Tapes Market Analytics
The EU Green Deal is decoupling paper packaging tapes from conventional plastic tape demand across European supply chains. 3M Company leverages its adhesive R&D infrastructure to sustain water-activated formulations for high-strength industrial sealing. Avery Dennison Corporation anchors its position through specialized linerless tape systems that reduce material waste in automated packaging lines.
Paper packaging tapes are pressure-sensitive or water-activated adhesive strips constructed from kraft paper backings with starch, dextrin, or synthetic polymer coatings, designed for carton sealing, bundle reinforcement, and label protection in distribution environments. Single-sided tapes dominate unit volume in retail and logistics applications where cost-efficient carton closure remains the primary function, while gummed tapes capture premium positioning in e-commerce channels demanding tamper-evident and fully recyclable sealing. Water-based adhesives lead the adhesive type category due to compatibility with paper recycling streams and reduced volatile organic compound emissions during manufacturing.
The EPA regulates adhesive emissions under Clean Air Act standards, while the EU F-Gas Regulation and REACH framework restrict solvent-based chemistries that compromise circular packaging goals. FDA indirect food contact rules shape tape selection for food and beverage end users requiring migration-safe adhesive systems. Stakeholders must monitor evolving extended producer responsibility schemes that will penalize non-recyclable packaging components.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing a structural substitution wave as corrugated box producers abandon plastic sealing tapes for paper-based alternatives that satisfy extended producer responsibility schemes.
Growth Catalysts
- E-commerce fulfillment expansion:Automated packaging lines in third-party logistics warehouses are consuming water-activated kraft tapes at accelerating rates for tamper-evident carton sealing.
- REACH solvent restrictions:The EU chemical framework's tightening volatile organic compound limits are eliminating solvent-based adhesive competition from plastic tape alternatives.
- Automotive parts export standardization:German automotive suppliers are mandating fully recyclable sealing systems for outbound component shipments to meet OEM circularity requirements.
Market Restraints
- Pulp input cost volatility:Kraft paper backing prices fluctuate with Nordic softwood pulp contract settlements, compressing converter margins during supply tightness.
- Adhesive supply concentration:Specialty dextrin and modified starch chemistries rely on a narrow base of European adhesive compounders, creating single-source vulnerability.
- Moisture sensitivity limitations:Paper tape structural integrity degrades in high-humidity cold chain environments, restricting penetration in pharmaceutical distribution.
Strategic Opportunities
- India's packaging modernization:The country's Bureau of Indian Standards is drafting recyclable packaging mandates that will open demand for gummed paper tapes in domestic e-commerce.
- Linerless system adoption:Eliminating silicone release liners reduces material waste by 15-20% and aligns with CSRD reporting requirements for packaging material intensity.
- Food contact certification expansion:FDA migration-safe adhesive approvals are unlocking specialty tape demand in organic and natural food segments previously served by plastic alternatives.
Industry Challenges
- Adhesive formulation talent scarcity:Water-based polymer chemistry expertise is concentrating at legacy tape manufacturers, constraining new entrant R&D velocity.
- Automated line integration complexity:Retrofitting existing case sealers for water-activated tape dispensing requires mechanical rework and operator retraining cycles.
- Multi-jurisdiction certification timelines:Simultaneous EU F-Gas, REACH, and FDA compliance pathways extend product launch schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Packaging Tapes Market |
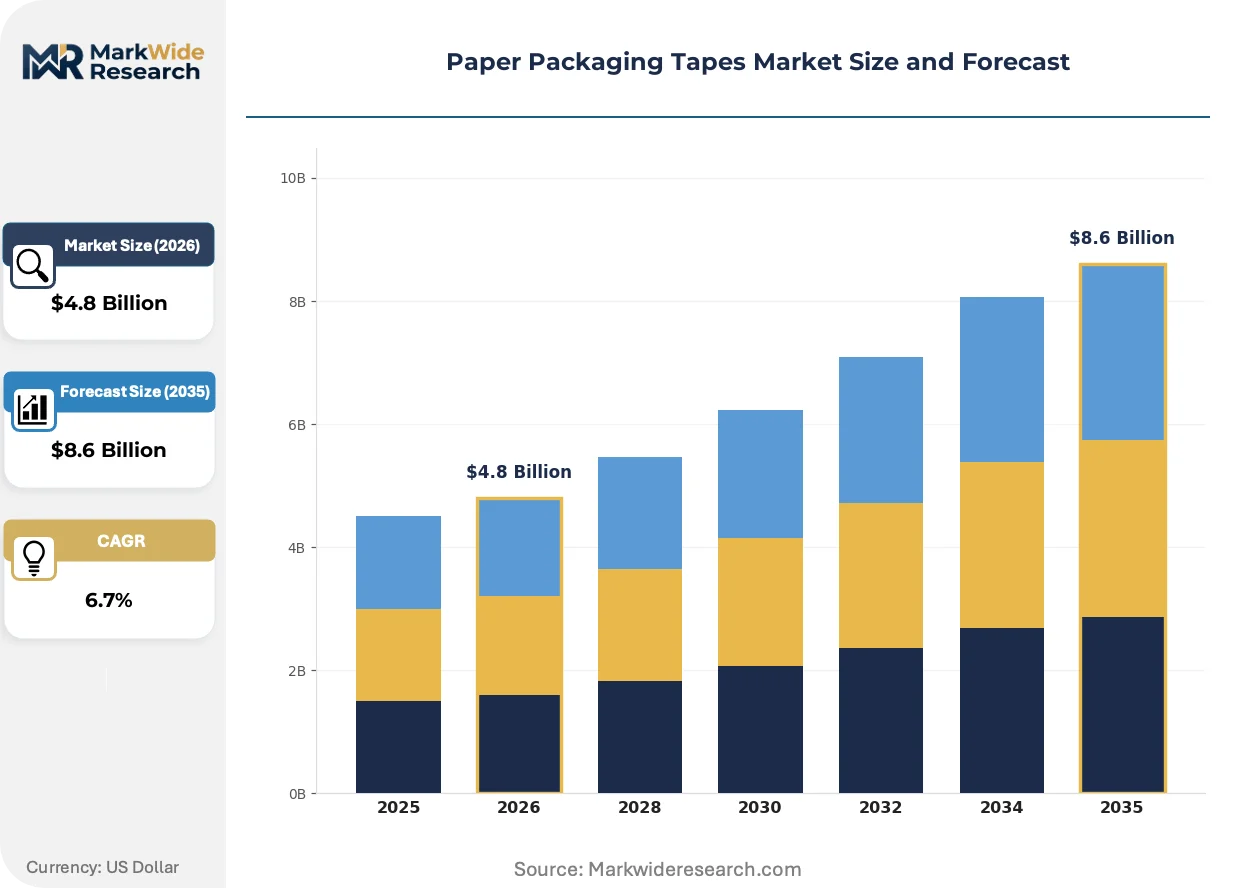
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Gummed Tape, Reinforced Tape Application: Retail Packaging, Industrial Packaging, Crafting, Shipping Adhesive Type: Water-Based, Hot Melt, Solvent-Based, Natural Rubber End User: E-Commerce, Manufacturing, Logistics, Food & Beverage |
| Companies Covered | 3M Company, Intertape Polymer Group Inc., Avery Dennison Corporation, Nitto Denko Corporation, tesa SE, Berry Global Inc., Scapa Group plc, Shurtape Technologies LLC, Saint-Gobain Performance Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Packaging Tapes Market Evolving Landscape
Adhesive chemistry evolution and regulatory compliance automation are compressing product development cycles while reshaping how converters compete on sustainability credentials.
Reinforced filament tape constructions with fiberglass or synthetic yarn inserts are consolidating strength performance previously requiring plastic strapping or heavy-duty plastic tapes. Food and beverage distributors with high-value palletized loads are adopting these systems for bundle stabilization. The technology is consolidating demand from dual-source sealing strategies into single-material recyclable workflows.
REACH Annex XVII restrictions on persistent organic pollutants are accelerating reformulation investments across European adhesive compounders. The regulatory pressure is eliminating legacy solvent-based tape chemistries from automotive and electronics export packaging. German industrial packaging buyers are now requiring full material disclosure documentation as a procurement gate.
Direct contracting between e-commerce platforms and tape converters is displacing traditional distribution intermediaries in high-volume fulfillment corridors. Amazon, Zalando, and regional logistics aggregators are negotiating specification-controlled supply agreements with adhesive R&D support clauses. This pattern is most visible in the Rhine-Ruhr and Randstad warehouse clusters where automated packaging density concentrates.
Paper Packaging Tapes Market Segmentation
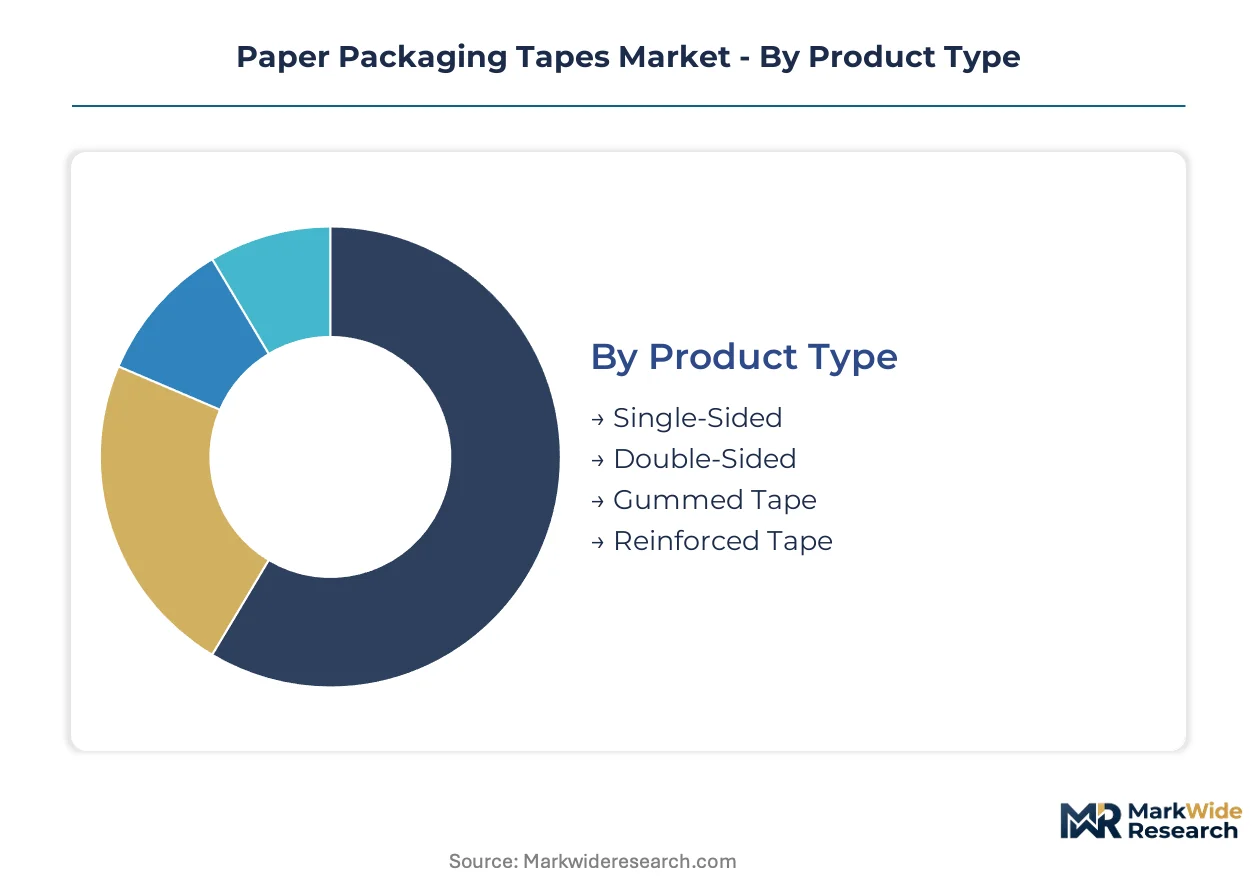
Paper packaging tape segmentation reveals how adhesive chemistry and backing construction determine recyclability credentials and automated line compatibility. Supply chain managers select segments based on extended producer responsibility compliance and case sealer integration requirements.
Product Type:
Supply concentration in kraft paper backing mills favors segments with standardized widths and tensile specifications that align with high-volume converter operations.
- Single-Sided:Pressure-sensitive adhesive coats one side of kraft paper backing in widths from 24mm to 72mm. E-commerce fulfillment centers in Germany's Rhine-Ruhr corridor consume this format for cost-efficient carton closure on high-speed automated lines.
- Gummed Tape:Water-activated starch or dextrin adhesive requires moisture activation to form permanent fiber-to-fiber bonds. Amazon and Zalando distribution hubs specify this segment for tamper-evident sealing that survives the entire returns cycle.
- Double-Sided:Adhesive layers on both backing surfaces enable splicing and temporary bonding applications. Narrow demand concentration appears in label manufacturing and print finishing operations.
- Reinforced Tape:Fiberglass or synthetic yarn filaments embedded in kraft backing deliver tensile strength exceeding 100 N/cm. Automotive parts pallet stabilization in Stuttgart supplier parks drives specialized procurement.
Today's leader: Single-Sided. Tomorrow's challenger: Gummed Tape.
Application:
Cost tier stratification separates commodity carton sealing from premium bundle reinforcement requiring certified recyclability documentation.
- Industrial Packaging:Heavy-duty kraft constructions with reinforced filaments secure palletized loads for export shipment. German automotive suppliers mandate this application for OEM circularity compliance.
- Shipping:Standard kraft tapes seal corrugated containers for parcel distribution. Third-party logistics warehouses in the Randstad cluster specify water-activated formats for automated dispensing compatibility.
- Retail Packaging:Decorative printed kraft tapes serve boutique e-commerce unboxing experiences. Limited volume concentration in premium cosmetics and organic food segments.
- Crafting:Low-tack decorative tapes address hobbyist and educational supply channels. Fragmented demand across specialty retailers and online marketplaces.
Industrial Packaging commands margin premiums. Shipping delivers volume scale.
Adhesive Type:
REACH solvent restrictions and FDA migration standards are eliminating formulation categories that conflict with circular packaging mandates.
- Water-Based:Acrylic or starch-dextrin emulsions cure through moisture evaporation without volatile organic compound release. EU F-Gas Regulation alignment makes this the default specification for European corrugated box producers.
- Hot Melt:Thermoplastic synthetic rubber adhesives activate at 150-180°C for instant bond formation. High-speed case sealing lines in Dutch fulfillment centers favor this chemistry for throughput maximization.
- Solvent-Based:Organic solvent carriers deliver aggressive tack for difficult substrates. REACH Annex XVII restrictions on persistent organic pollutants are phasing this category from automotive and electronics export packaging.
- Natural Rubber:Hevea brasiliensis latex formulations provide cold-temperature flexibility. Niche demand in refrigerated pharmaceutical distribution where synthetic alternatives stiffen.
Water-Based dominates regulatory compliance. Hot Melt gains share fastest in automation-heavy segments.
End User:
Customer procurement sophistication varies from specification-controlled supply agreements to spot-market commodity purchasing.
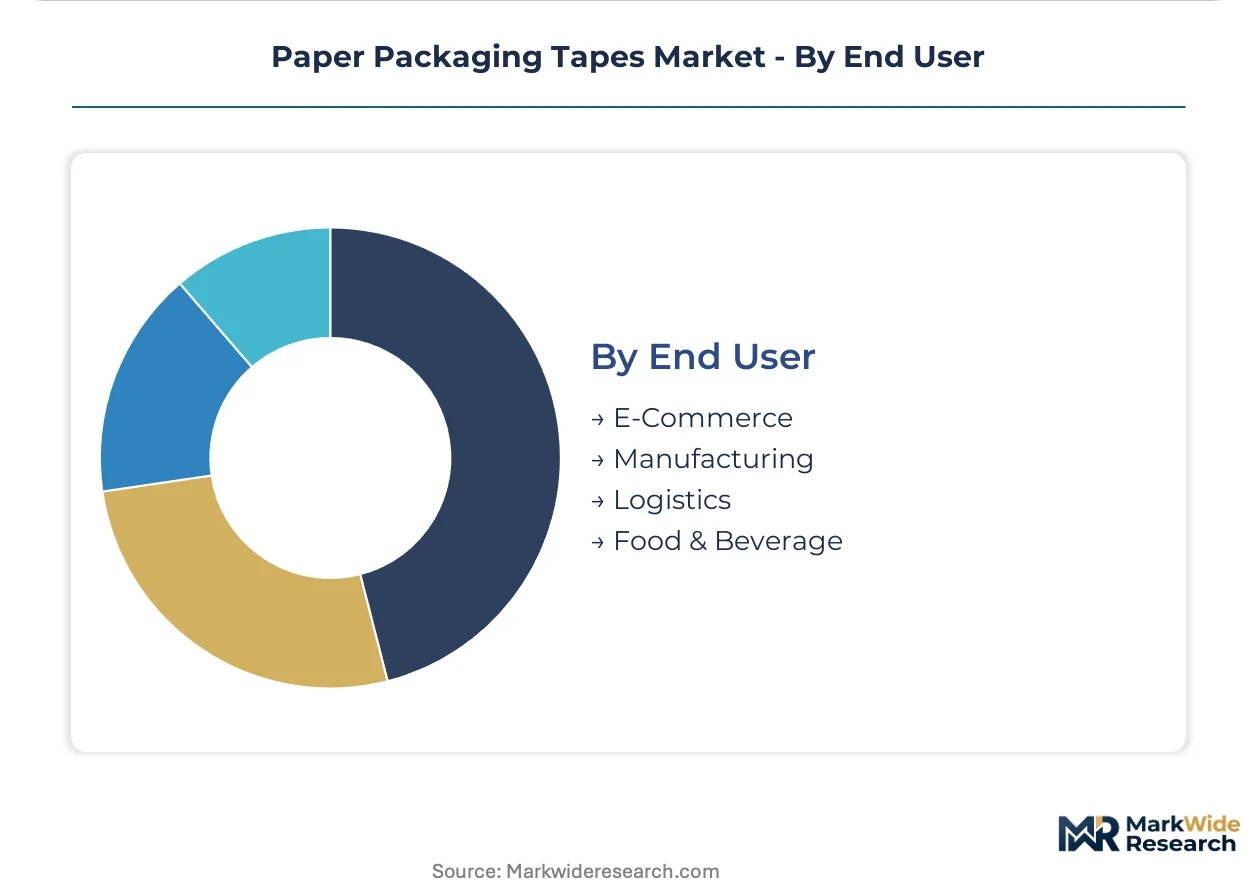
- E-Commerce:Direct platform-to-converter contracting displaces distribution intermediaries. Amazon and regional aggregators negotiate adhesive R&D support clauses for high-volume fulfillment corridors.
- Logistics:Third-party providers standardize tape specifications across multi-client warehouse operations. German DHL and Kuehne+Nagel facilities drive recyclable sealing mandate adoption.
- Manufacturing:Industrial packaging engineers specify tape performance for outbound component protection. Automotive and electronics exporters require full material disclosure documentation.
- Food & Beverage:FDA indirect food contact rules govern adhesive selection for migration safety. Organic and natural food segments previously served by plastic alternatives are converting to paper-based systems.
E-Commerce sets specification standards. Food & Beverage offers the steepest expansion trajectory as migration-safe approvals accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers pioneered recyclable sealing mandates for outbound component shipments, establishing the regulatory and procurement template that now diffuses across European supply chains and into Asian e-commerce corridors.
Germany
Automotive parts exporters in Stuttgart and Wolfsburg supplier parks mandate fully recyclable sealing systems to satisfy OEM circularity requirements. The EU F-Gas Regulation eliminates solvent-based adhesive competition from plastic tape alternatives. Rhine-Ruhr logistics clusters standardize water-activated kraft tape specifications across DHL and Kuehne+Nagel fulfillment operations.
United States
Amazon fulfillment centers drive specification-controlled supply agreements with adhesive R&D support clauses for automated packaging lines. EPA Clean Air Act standards regulate adhesive emissions in domestic manufacturing. Chicago and Dallas warehouse corridors concentrate demand for pressure-sensitive single-sided formats in high-speed case sealing environments.
India
The Bureau of Indian Standards drafts recyclable packaging mandates that will open demand for gummed paper tapes in domestic e-commerce. Mumbai and Bangalore logistics aggregators pilot water-activated tape dispensing systems for automated packaging modernization. BIS certification timelines extend product launch schedules for multinational tape converters entering the market.
Netherlands
Randstad third-party logistics warehouses specify water-activated formats for automated dispensing compatibility in high-volume fulfillment corridors. REACH solvent restrictions accelerate substitution of plastic sealing tapes with paper-based alternatives. Rotterdam distribution hubs standardize linerless tape systems to reduce material waste intensity for CSRD reporting compliance.
China
Yangtze River Delta e-commerce platforms negotiate direct converter contracts for high-volume carton sealing specifications. MEE environmental standards tighten volatile organic compound limits in adhesive manufacturing. Shanghai and Suzhou fulfillment clusters adopt reinforced filament tape constructions for palletized load stabilization in export packaging.
Paper Packaging Tapes Market Competitive Landscape
Capital-heavy adhesive compounders compete with asset-light tape converters across a market structure that concentrates formulation expertise at legacy manufacturers while fragmentating downstream converting operations. Tier-one players command procurement relationships with e-commerce platforms and automotive OEMs through specification-controlled supply agreements. Three strategic archetypes dominate: integrated adhesive-to-tape manufacturers, specialized linerless system developers, and regional kraft paper converters. Capacity expansion in Nordic softwood pulp backings and strategic partnerships for automated line integration represent the dominant competitive vectors.
Within the integrated adhesive formulation tier, 3M Company and Avery Dennison Corporation exemplify capital-intensive players that anchor premium positioning through in-house R&D infrastructure. Tesa SE occupies a position bridging European regulatory compliance expertise with automated packaging line integration capabilities. These three players represent the archetype that now controls specification-setting relationships with Amazon, Zalando, and German automotive supplier parks.
| Leading Market Players |
|---|
| 3M Company |
| Intertape Polymer Group Inc. |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| tesa SE |
| Berry Global Inc. |
| Scapa Group plc |
| Shurtape Technologies LLC |
| Saint-Gobain Performance Plastics Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned Nordic softwood pulp mills anchor upstream supply, transmitting cost volatility through kraft paper backing contracts while limiting converter margin flexibility during supply tightness. This ownership structure concentrates pricing power at the raw material tier and forces downstream tape converters into long-term offtake commitments to secure volume allocation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by adhesive chemistry sophistication and certification documentation depth. Premium tiers capture water-activated gummed tapes with full EU F-Gas and REACH compliance documentation, while economy segments serve commodity pressure-sensitive formats for undifferentiated carton sealing. Cost compression in standard tiers is intensifying because Nordic pulp contract settlements have tightened converter margins. E-commerce fulfillment centers exhibit lowest price sensitivity due to specification-controlled supply agreements, whereas fragmented retail packaging buyers drive spot-market commodity competition.
Supply Chain Analysis
Kraft paper backing supply rests on Nordic softwood pulp producers in Sweden, Finland, and Norway, with secondary concentration in German and Austrian specialty paper mills. Specialty dextrin and modified starch adhesive chemistries draw from a narrow base of European compounders in Germany and the Netherlands. Single-source vulnerability in adhesive formulation creates structural risk if REACH Annex XVII restrictions eliminate additional chemistries. Distribution runs through converter-direct relationships with e-commerce platforms and third-party logistics warehouses, displacing traditional wholesale intermediaries in high-volume corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EU extended producer responsibility schemes and India's emerging BIS mandates creates geographic-arbitrage opportunities for converters with multi-jurisdiction certification capabilities. Cost differentials in adhesive formulation compliance timelines favor early movers in South Asian packaging modernization.
For Market Incumbents: Acquire water-based adhesive formulation expertise through specialist compounder transactions to defend against REACH-driven chemistry obsolescence. Secure captive supply of Nordic kraft paper backing through equity stakes in family-owned pulp mills. Build automated line integration service capabilities to lock in e-platform procurement relationships. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for solvent-free adhesive specialists to capture automotive and electronics export packaging share vacated by legacy chemistries. India's BIS recyclable packaging mandates represent the most penetrable geography for gummed tape system adoption. Lead with linerless tape offerings that reduce material intensity for CSRD-reporting corporate buyers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional kraft paper converters lacking in-house adhesive R&D capabilities. Long-term viability hinges on backward integration into formulation chemistry or forward integration into automated dispensing system partnerships. Watch for BIS certification completion timelines as the signal for Indian market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Chemistry | Captures REACH compliance margin previously extracted by European compounders in Stuttgart supplier parks. |
| Linerless System Capacity Expansion | Aligns tape converters with CSRD material intensity reporting requirements for Randstad logistics clusters. |
| Automated Line Integration Partnership | Locks in specification control with Amazon and Zalando distribution hubs in Rhine-Ruhr corridors. |
| BIS Certification Pathway Investment | Opens access to Mumbai and Bangalore e-commerce fulfillment modernization programs. |
| Nordic Pulp Mill Equity Stake | Secures kraft backing supply priority during softwood pulp contract tightness in Scandinavian markets. |
Research Methodology
Coverage spans Germany, the United States, India, the Netherlands, and China, with primary inputs from each market cluster combining tape converter executives, automotive packaging engineers, e-commerce fulfillment procurement leads, and adhesive R&D directors. Secondary validation draws from EU F-Gas regulatory filings, BIS draft standard publications, EPA Clean Air Act enforcement data, and Nordic pulp industry trade statistics. Bottom-up demand modeling triangulates against top-down corrugated box production forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across adhesive type, product format, and end-use application dimensions over the projection horizon. CAGRs derive from segment-level demand build-ups incorporating e-commerce fulfillment center expansion pipelines, automotive export packaging specification shifts, and regulatory compliance timeline accelerations. Modeled inputs include pulp contract price settlement patterns and automated packaging line retrofit adoption curves.
Revisions become necessary when REACH Annex XVII restrictions expand to additional adhesive chemistries, BIS mandates accelerate implementation timelines, or Nordic pulp supply disruptions extend beyond contract adjustment mechanisms. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Flatback Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Kraft Paper Tapes Market
Tapes
Strapping Supplies Market
Tapes
Thread Seal Tape Market
Tapes
Automotive Tapes Market
Tapes
Global Construction Tape Market
Tapes
Splicing Tapes Market
Tapes
ESD Tapes and Labels Market
Tapes
Tape Banding Machine Market
Tapes
Global Non-Conductive Water Blocking Tape Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
India Reflective Tapes Market