
 Glucose, Dextrose, and Maltodextrin Market | 2026-2036
Glucose, Dextrose, and Maltodextrin Market Size, Share, and Industry Trends Forecast 2026-2036
Glucose, Dextrose, and Maltodextrin Market Intelligence
The consolidation of purchasing power among large multinational food and beverage conglomerates is repositioning supplier relationships in the carbohydrate ingredients space. Cargill, Incorporated leverages its vast corn wet-milling capacity to achieve significant economies of scale. Archer Daniels Midland Company competes by offering a diversified portfolio of sweeteners and starches for various applications. Tate & Lyle PLC differentiates through its focus on value-added specialty ingredients and clean-label texturants.
Glucose, dextrose, and maltodextrin are carbohydrate ingredients derived from starch hydrolysis, primarily from corn or wheat. They function as sweeteners, bulking agents, and texturizers in processed foods, beverages, and pharmaceutical products. Maltodextrin powder leads in versatility for applications in the food & beverages sector, particularly for nutraceuticals. The syrup form is essential for beverage production, while the pharmaceuticals industry requires high-purity glucose monohydrate for critical formulations.
Food safety and labeling regulations from the US Food and Drug Administration (FDA) and European Food Safety Authority (EFSA) govern ingredient declarations. In China, compliance with national GB standards for food additives is mandatory for market access, influencing formulation. Navigating the divergent regional definitions of "natural" and "clean label" will be a central strategic challenge for ingredient manufacturers.
Market Dynamics
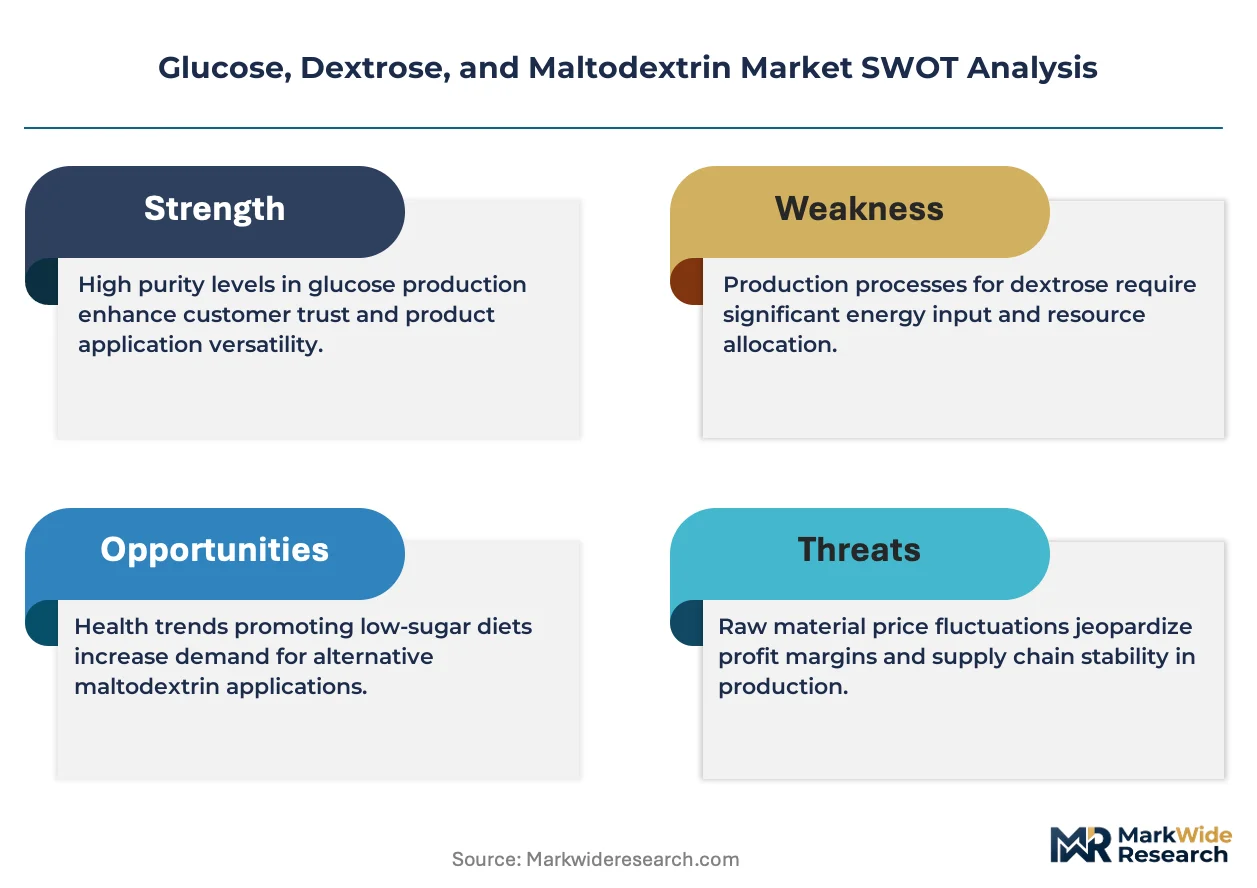
The central tension shaping the market is the demand from nutraceutical and clean-label food sectors for functional, traceable ingredients, which challenges the traditional, scale-driven commodity model of corn and wheat-based starch derivatives.
Growth Catalysts
- Nutraceutical Demand:Expansion in the sports nutrition sector drives consumption of maltodextrin as a readily digestible carbohydrate source in energy gels and recovery powders.
- Clean Label Formulation:Stricter food labeling guidelines from the FDA and EFSA encourage the use of non-GMO corn or alternative starches like tapioca to meet consumer demand for transparent ingredient lists.
- Pharmaceutical Applications:The growing need for high-purity glucose monohydrate in intravenous solutions, dialysis, and oral rehydration therapies supports stable demand from the global healthcare industry.
Market Restraints
- Input Cost Volatility:The market is directly exposed to price fluctuations in agricultural commodities, primarily corn and wheat, which can compress manufacturer margins and create price instability for buyers.
- Substitution Threat:The rise of alternative sweeteners and texturizers, such as stevia, erythritol, and soluble dietary fibers, presents a significant challenge in health-focused food and beverage applications.
- Negative Health Perception:Consumer concerns regarding high-glycemic ingredients and the association of corn syrups with highly processed foods limit the application of glucose and dextrose in products marketed for wellness.
Strategic Opportunities
- Alternative Starch Sources:Developing ingredients from non-corn and non-wheat sources like tapioca, potato, and rice creates opportunities to serve the allergen-free and non-GMO product markets.
- Specialty Maltodextrins:Manufacturing maltodextrins with specific dextrose equivalent (DE) values offers tailored functionality for texture, solubility, and browning in applications like infant formula and bakery.
- Animal Nutrition Expansion:Dextrose and maltodextrin can be further utilized as highly digestible energy sources in starter feeds for poultry, swine, and aquaculture, representing an underpenetrated market segment.
Industry Challenges
- Regulatory Divergence:Manufacturers face complexity in creating globally harmonized products due to differing definitions of "natural" and "clean label" between key regulatory bodies like the US FDA and the EFSA in Europe.
- Energy and Water Consumption:The corn wet-milling process is resource-intensive, posing operational cost and sustainability challenges, particularly in regions with strict environmental regulations or water scarcity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucose, Dextrose, and Maltodextrin Market |
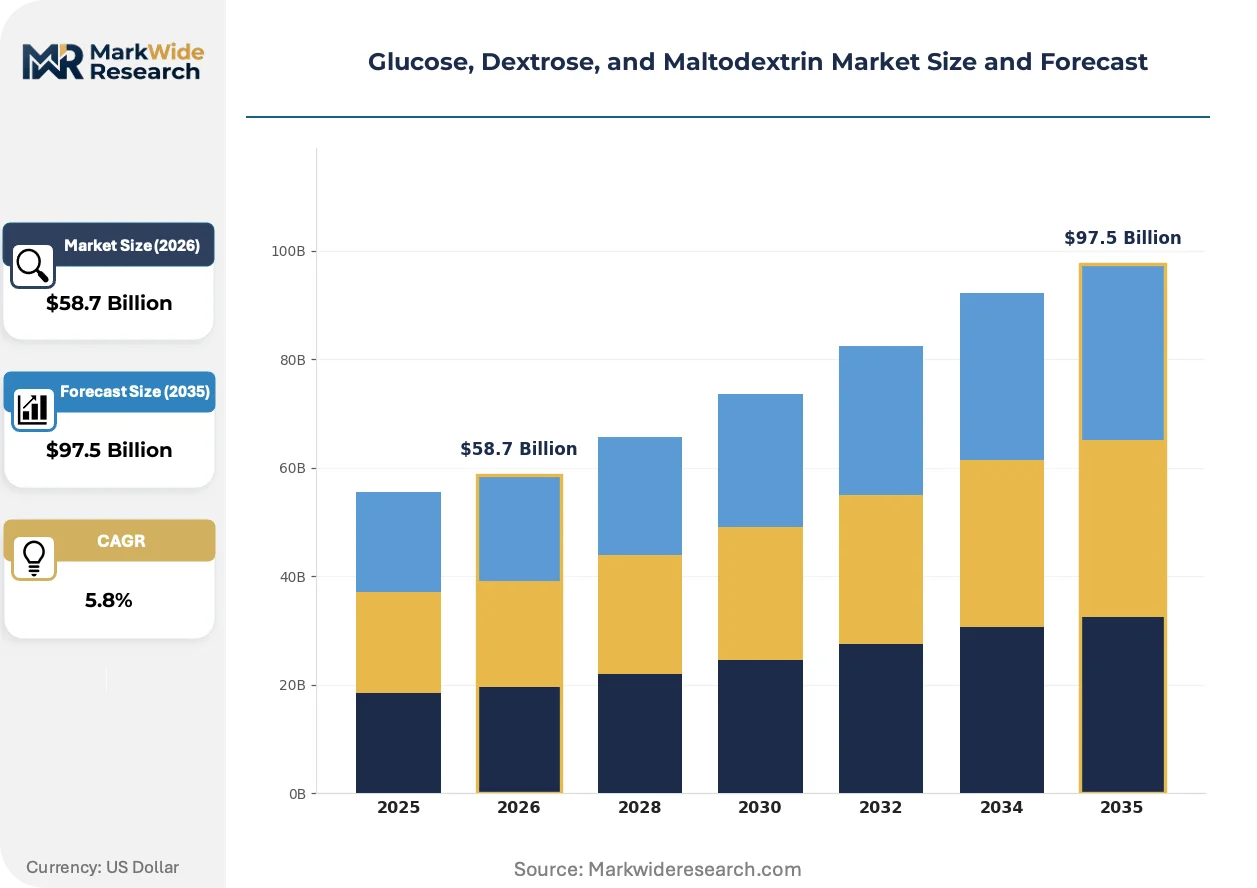
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Monohydrate, Dextrose Anhydrous, Maltodextrin Powder, High Maltose Syrup Application: Food & Beverages, Pharmaceuticals, Animal Nutrition, Personal Care Form: Powder, Syrup, Granules, Crystals End User Industry: Confectionery, Bakery, Nutraceuticals, Cosmetics |
| Companies Covered | Tate & Lyle PLC, Tereos S.A., Cargill, Incorporated, Südzucker AG, Grain Processing Corporation, Archer Daniels Midland Company, Roquette Frères, Beneo GmbH, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucose, Dextrose, and Maltodextrin Market Strategic Shifts & Innovations
Ingredient functionality is displacing price as the primary competitive axis in the carbohydrate ingredients space. This shift is compelling producers to invest in process technology and application-specific product development to meet new buyer requirements.
Enzymatic hydrolysis and advanced chromatographic separation are technologies enabling the production of highly purified glucose fractions and specialty maltodextrins. Nutraceutical and pharmaceutical formulators are rapidly adopting these ingredients for their precise functional properties. This precision at the molecular level is decentralizing product development, allowing for tailored ingredients outside the control of large-scale, one-size-fits-all corn refining.
The US FDA's updated Nutrition Facts label mandates the declaration of "Added Sugars," directly impacting how glucose and dextrose are perceived by consumers. This forces food and beverage manufacturers to re-evaluate sweetener content to avoid high "Added Sugars" values on their packaging. The beverage and confectionery segments are most affected, accelerating the search for alternative bulking agents or lower-DE maltodextrins that contribute less to this metric.
Sourcing decisions are increasingly guided by non-GMO, organic, and allergen-free certifications rather than solely by price and availability. This disrupts traditional procurement from large-scale commodity suppliers, creating openings for specialized producers of ingredients from alternative starches like tapioca or potato. This trend is most pronounced in the infant nutrition and plant-based food sectors in Europe and North America.
Glucose, Dextrose, and Maltodextrin Market Segmentation
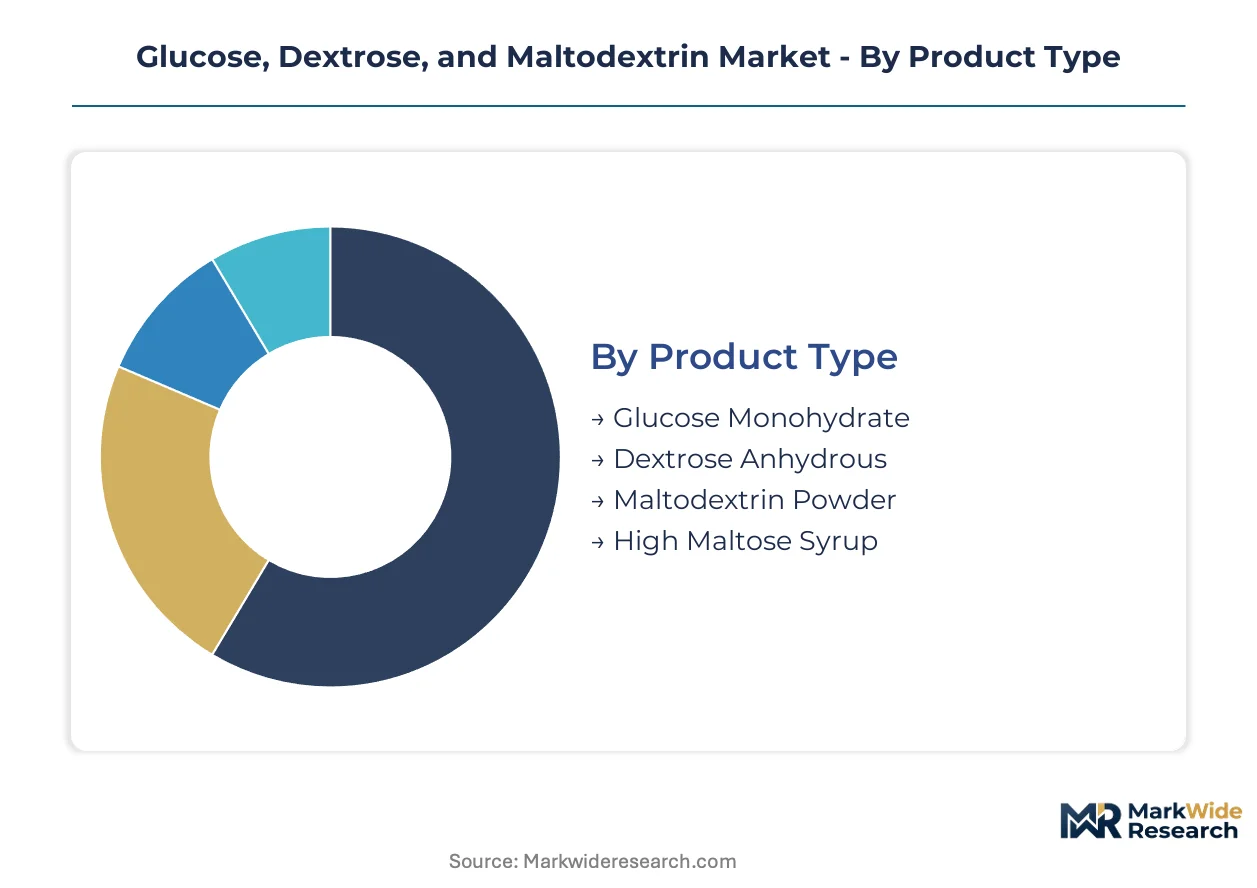
The Glucose, Dextrose, and Maltodextrin market exhibits diverse segmentation, reflecting varied product characteristics and application requirements. Understanding these segments helps manufacturers tailor offerings to specific end-user needs and navigate evolving regulatory landscapes. Each segment plays a distinct role in the overall market structure.
Product Type:
Product type segmentation highlights the differing functional properties and purity levels required by various industries for carbohydrate ingredients.
- Maltodextrin Powder:This product type is a white, hygroscopic powder, typically derived from corn, potato, or tapioca starch, with a dextrose equivalent (DE) below 20. Demand concentrates in the nutraceuticals sector, where it functions as a bulking agent and readily digestible carbohydrate source for energy gels.
- Glucose Monohydrate:This highly purified crystalline form of glucose contains one molecule of water, offering high solubility and specific functional properties for critical applications. The pharmaceuticals industry drives demand for its use in intravenous solutions and oral rehydration therapies, requiring stringent purity standards.
- Dextrose Anhydrous:This is a pure, crystalline glucose without water, used as a sweetener and bulking agent in various food applications. Its direct fermentability makes it useful in brewing and baking.
- High Maltose Syrup:This liquid sweetener contains a high concentration of maltose, providing controlled sweetness and improved texture in confectionery products. It offers specific functionalities for candy and baked goods.
Volume placements concentrate in Maltodextrin Powder; the faster expansion belongs to Glucose Monohydrate.
Application:
Application-based segmentation reveals the primary industries leveraging these carbohydrate ingredients for their functional attributes.
End-use applications delineate where the greatest value is extracted, influencing product development and ingredient specialization.
- Food & Beverages:This segment encompasses the largest volume usage, with ingredients serving as sweeteners, bulking agents, and texturizers across a vast array of processed foods and drinks. The increasing consumer demand for functional foods and beverages drives innovation in this sector.
- Pharmaceuticals:High-purity glucose and dextrose forms are essential excipients and active ingredients in pharmaceutical formulations, including intravenous fluids, tablets, and medical nutrition products. Stringent regulatory requirements from the FDA and EFSA govern ingredient quality for this critical application.
- Animal Nutrition:Dextrose and maltodextrin provide highly digestible energy sources for livestock and aquaculture, supporting growth and health in animal feed formulations. This application represents a significant, yet underpenetrated, market segment.
- Personal Care:These carbohydrates act as humectants, binders, and emollients in cosmetic and personal care products, enhancing texture and moisture retention. They contribute to the formulation stability of various skin and hair care items.
Demand for Food & Beverages drives consistent volume, while Pharmaceuticals provides stable, high-value growth.
Form:
Segmentation by form highlights the physical state in which these ingredients are supplied, catering to diverse manufacturing processes.
The physical presentation of these ingredients dictates their ease of integration into different industrial processes and end-product matrices.
- Powder:The most versatile form, easily blended into dry mixes, nutritional supplements, and powdered beverages, offering excellent solubility and stability. Maltodextrin powder dominates this form due to its widespread use in nutraceuticals.
- Syrup:A liquid form primarily used in beverage production, confectionery, and baked goods, providing sweetness, moisture retention, and texture modification. High maltose syrup is a key component in many liquid food applications.
- Granules:These larger particles offer improved flowability and reduced dust, making them suitable for specific tablet compression and blending applications in the pharmaceutical industry. Granular forms aid in consistent dosing.
- Crystals:Highly purified crystalline forms, such as dextrose monohydrate, are used in applications requiring precise sweetness, rapid dissolution, and specific textural properties. This form is often preferred for direct consumption products.
The Powder form offers broad versatility; specialized needs drive the demand for Syrup.
End User Industry:
End user industry segmentation identifies the specific sectors that incorporate glucose, dextrose, and maltodextrin into their final products.
This classification reveals the diverse industrial ecosystems where these carbohydrate ingredients are integrated into consumer-facing goods.
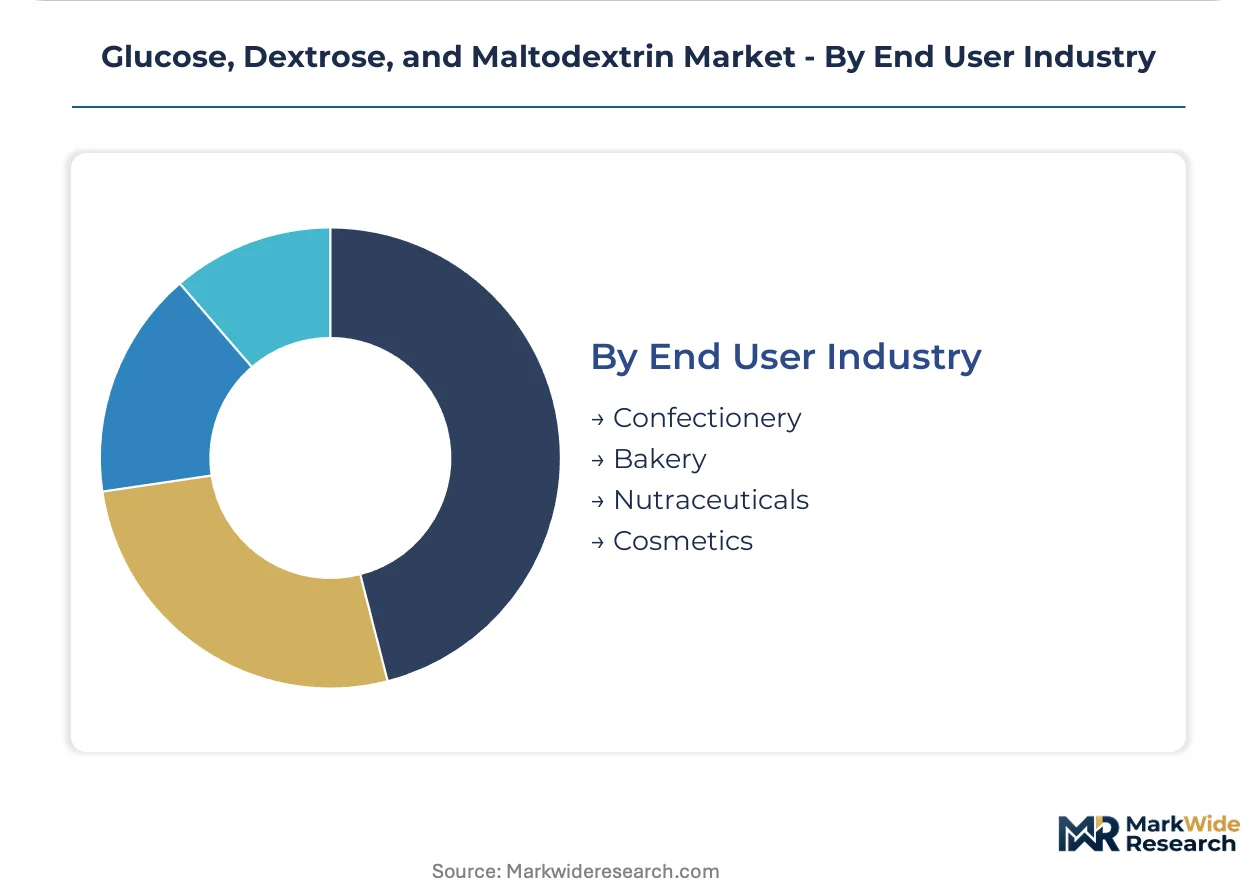
- Nutraceuticals:This sector utilizes maltodextrin as a carbohydrate source in sports nutrition products, energy bars, and dietary supplements, supporting athletic performance and recovery. The clean label trend influences ingredient sourcing within this segment.
- Confectionery:Glucose, dextrose, and maltodextrin are vital for controlling sweetness, texture, and crystallization in candies, chocolates, and chewing gums. Updated food labeling guidelines from the FDA impact formulation choices in this industry.
- Bakery:These ingredients contribute to browning, moisture retention, and fermentation in bread, cakes, and pastries, enhancing product quality and shelf life. They provide essential functional properties for dough development.
- Cosmetics:Maltodextrin and glucose derivatives function as binding agents, film formers, and humectants in personal care products, including creams, lotions, and makeup. They contribute to product stability and skin feel.
Established applications in Confectionery anchor stable demand, with Nutraceuticals showing dynamic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Glucose, Dextrose, and Maltodextrin market exhibits significant demand concentration in key regions globally. China's expansive food and beverage processing industry anchors a substantial portion of this demand. Other major markets include North America and Europe, driven by diverse application requirements.
China
China's vast food and beverage processing industry fuels immense demand for carbohydrate ingredients. Compliance with national GB standards for food additives is mandatory for market access. The Yangtze River Delta region, a hub for food ingredient manufacturing, experiences substantial growth in maltodextrin production.
United States
The United States market is characterized by strong demand from the nutraceuticals and sports nutrition sectors. FDA's updated Nutrition Facts label mandates "Added Sugars" declarations, impacting formulation choices. The Midwest corn belt, with its extensive corn wet-milling capacity, remains central to ingredient supply.
Germany
Germany drives demand for high-purity glucose monohydrate in its pharmaceutical sector and specialty food applications. EFSA regulations and clean label initiatives strongly influence ingredient formulation choices across the country. Bavaria, a region with robust pharmaceutical and food processing industries, sees consistent ingredient procurement.
India
India's rapidly expanding processed food sector and animal nutrition industry require significant volumes of glucose and maltodextrin. FSSAI food safety standards govern ingredient quality and labeling for domestic consumption. Maharashtra, a key industrial state, is witnessing increased investment in food and pharmaceutical ingredient production.
Brazil
Brazil presents substantial demand from its large food and beverage industry and growing animal feed segment. ANVISA regulations for food additives ensure product safety and compliance for manufacturers. São Paulo state, a significant agricultural and industrial hub, concentrates much of the country's carbohydrate ingredient processing.
Glucose, Dextrose, and Maltodextrin Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty ingredient niches, particularly in clean label and nutraceuticals. The carbohydrate ingredients market exhibits a tiered structure, with large commodity players coexisting with specialized value-added manufacturers. Strategic archetypes include integrated starch processors, specialty ingredient innovators, and regional suppliers. Companies are primarily focused on capacity expansion and portfolio diversification, alongside strategic partnerships, to meet evolving demand for functional ingredients.
At the scale-driven end, Cargill, Incorporated and Archer Daniels Midland Company exemplify integrated agricultural processors. These U.S.-based entities leverage extensive corn and wheat wet-milling capacities to produce a broad range of commodity carbohydrate ingredients. Tate & Lyle PLC, a U.K.-based company, occupies a position as a specialty ingredient innovator. It differentiates through its focus on value-added functional ingredients and clean-label texturants, serving the evolving needs of the food and beverage industry.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Tereos S.A. |
| Cargill, Incorporated |
| Südzucker AG |
| Grain Processing Corporation |
| Archer Daniels Midland Company |
| Roquette Frères |
| Beneo GmbH |
| Ingredion Incorporated |
Cost & Logistics Intelligence
Large multinational food and beverage conglomerates often dictate the dominant contract-based pricing model in the carbohydrate ingredients market.
Pricing Analysis
Volume-driven segments operate under commodity spot pricing, while specialty applications command premium pricing. Price differentiation stems from quality grade, such as high-purity glucose monohydrate for pharmaceuticals, and specific certifications like non-GMO status for infant nutrition. Pricing pressure stems from volatility in agricultural commodity inputs like corn and wheat, alongside the substitution threat from alternative sweeteners. Pharmaceutical buyers exhibit low price sensitivity due to stringent purity requirements, contrasting with the high price sensitivity of bulk food and beverage manufacturers.
Supply Chain Analysis
Logistics and freight costs significantly influence regional pricing, particularly for bulk carbohydrate shipments from major production hubs. Geographic supply concentrates in the United States Midwest corn belt, China's Yangtze River Delta, and European starch processing regions. Raw material dependencies center on corn, wheat, and increasingly, tapioca and potato starches. Commodity price volatility in corn and wheat represents a structural supply chain risk. Distribution runs through direct sales to large industrial buyers, with specialized distributors serving niche markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Glucose, Dextrose, and Maltodextrin market is undergoing a consolidation play, with stringent clean label regulations pressuring smaller, less adaptable producers.
For Market Incumbents: Anticipate continued investment in enzymatic hydrolysis to develop highly purified glucose fractions for pharmaceutical applications. Integrate alternative starch sourcing, such as tapioca or potato, to meet growing allergen-free and non-GMO demand, mitigating input commodity price volatility. Enhance research and development into specialty maltodextrins with tailored functional properties for infant formula, addressing the threat of substitute ingredients. Pursue strategic partnerships with nutraceutical brands to secure long-term supply agreements for specialized ingredients.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce platforms offer a viable digital-channel route for new entrants targeting niche sports nutrition consumers. Focus on developing specialty maltodextrins from non-corn sources like tapioca for allergen-free products, a white-space opportunity in European and North American markets. Target the underpenetrated animal nutrition segment, particularly starter feeds for aquaculture, with highly digestible dextrose and maltodextrin. Leverage certifications like organic and non-GMO to differentiate offerings in crowded segments.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists in Europe, particularly those with established alternative starch processing capabilities. Long-term viability rests on companies capable of navigating divergent regulatory landscapes and adapting to evolving clean label demands in a 5-10 year window. Target ingredient innovators with robust R&D pipelines in specialty carbohydrates and a strong presence in the nutraceutical sector. Increased M&A activity among mid-sized alternative starch processors is a signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Alternative Starches | This move diversifies raw material sourcing and caters to allergen-free product demand. |
| Investment in Enzymatic Hydrolysis Technologies | This enhances production of high-purity glucose and specialty maltodextrins for pharmaceuticals. |
| Strategic Partnerships with Nutraceutical Brands | This secures long-term demand for functional carbohydrate ingredients in a growth sector. |
| Development of Tailored Maltodextrin DE Values | This offers precise functionality for specific applications like infant formula and bakery products. |
| Expansion into Animal Nutrition Applications | This taps into an underpenetrated market segment with stable demand for digestible energy sources. |
Research Approach
Multi-period observation of ingredient pricing trends and import/export volumes anchored the trend analysis, supplemented by interviews with R&D directors at food and beverage companies, procurement managers in pharmaceutical firms, and food safety regulators. Secondary validation drew from FDA guidelines, EFSA reports, national GB standards in China, and agricultural commodity market data. This approach facilitated bottom-up and top-down triangulation of market size and growth drivers.
An input-output matrix framework analyzed market dynamics, segmenting by product type, application, form, end-user industry, and starch source across the analysis window. Forecasts for compound annual growth rates were derived from historical data, macroeconomic indicators, and projected shifts in consumer preferences. Key industry-specific forecast inputs included agricultural commodity price forecasts and anticipated changes in global food labeling regulations.
Inputs from national GB standards and EFSA reports were available through the study window; gaps in real-time agricultural commodity pricing data introduce uncertainty bands into short-term forecasts. Forecasts reflect assumptions regarding regulatory stability and sustained investment in functional food innovation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Stevia Mints Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Citrus Molasses Market
Sweeteners
Galactose Market
Sweeteners
North America Low-Calorie Sweeteners Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Low-Fat Sugar Market
Sweeteners
Liquid Sugar Market
Sweeteners
Sugar Market
Sweeteners
Cassava Syrup Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Australia Allulose Market
Sweeteners
China Allulose Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
China Saccharin Market